
 Global High Abuse Shrink Bags Market | 2026-2036
Global High Abuse Shrink Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Global High Abuse Shrink Bags Market Intelligence
The capital investment required for advanced multi-layer co-extrusion lines is bifurcating the market. Large-scale producers like Amcor leverage their global manufacturing footprint and R&D capabilities to serve multinational food processors. Sealed Air sustains its market position through proprietary polymer formulations and integrated packaging systems. In contrast, regional players such as Flexopack compete by offering customized solutions and faster turnaround times for specific end-use applications.
High abuse shrink bags are multi-layer plastic films designed to provide exceptional puncture and tear resistance for packaging irregularly shaped or sharp-edged products. These bags, often made from co-extruded polymers, shrink tightly around items like bone-in meats or hardware during heat application. Within material types, advanced Polyethylene and Ethylene Vinyl Acetate (EVA) formulations dominate due to their flexibility and strength. The food packaging segment, specifically for fresh and frozen protein, constitutes the largest end-use industry by volume and value.
Compliance with food contact material regulations, such as those from the FDA in the United States and the EFSA in Europe, is non-negotiable for market participants. In China, GB standards for plastic packaging materials dictate specific polymer and additive usage, influencing material selection. These regulatory frameworks directly shape product development and market access strategies. The key decision for manufacturers will be balancing the demand for higher performance and recyclability with material cost pressures.
Market Dynamics
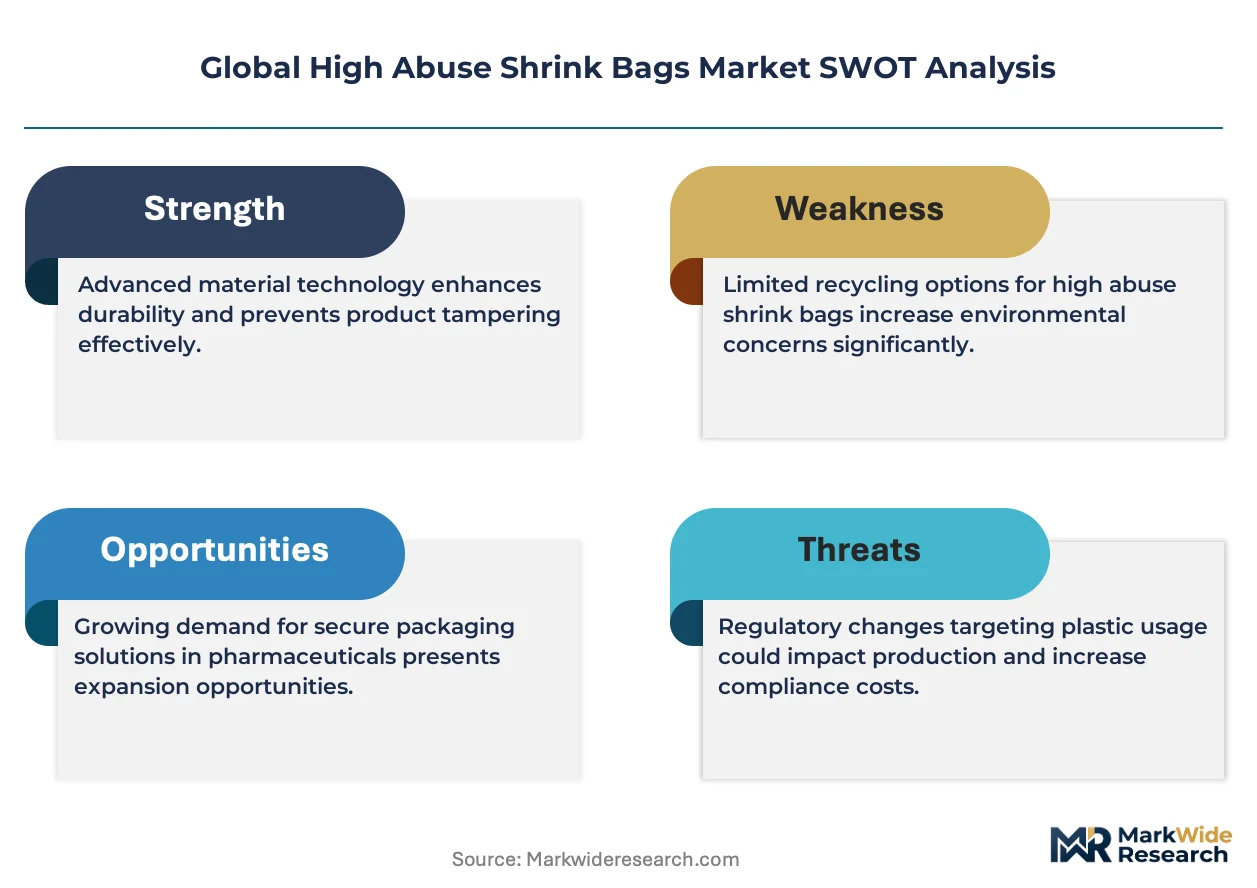
The central tension shaping the high abuse shrink bag market is the conflict between the need for higher-performance, puncture-resistant multi-layer films for food safety and the escalating regulatory and consumer pressure for simplified, recyclable packaging structures.
Growth Catalysts
- Food Sector Demand:The expansion of centralized meat processing, particularly for bone-in beef and pork in Brazil and the Midwestern United States, requires packaging with superior puncture resistance to ensure product integrity and extend shelf life.
- Material Science Advances:Innovations in multi-layer co-extrusion technology and advanced polymer formulations, including specific grades of EVA, enable the production of thinner yet stronger films, reducing material usage without compromising performance.
- Regulatory Mandates:Stringent food contact safety standards from bodies like the United States FDA and Europe's EFSA compel food processors to use certified, high-barrier packaging, directly benefiting suppliers of compliant high abuse shrink bags.
Market Restraints
- Raw Material Price Volatility:Market pricing is highly sensitive to fluctuations in the cost of key polymer resins, such as polyethylene and ethylene vinyl acetate (EVA), which can compress manufacturer margins and create price instability for end-users.
- Recycling Complexity:The multi-material, co-extruded structure of most high abuse bags makes them difficult to recycle through conventional mechanical recycling streams, creating a conflict with corporate and national sustainability goals.
- Alternative Packaging Competition:The market faces competition from other packaging formats, such as vacuum skin packaging (VSP) and modified atmosphere packaging (MAP), which offer different aesthetic and functional benefits for protein products.
Strategic Opportunities
- Non-Food Applications:There is significant potential for expansion into industrial sectors for packaging sharp-edged items like tools, hardware, or automotive parts, where puncture and tear resistance are critical functional requirements.
- Bio-Based Formulations:Developing high-performance shrink bags from bio-based or certified circular polymers that meet food contact regulations presents a major opportunity to address sustainability concerns and capture premium value.
- Emerging Market Penetration:Modernizing food supply chains in Southeast Asian and Latin American countries offer new growth avenues as local processors adopt more sophisticated packaging to reduce food waste and access export markets.
Industry Challenges
- Capital Investment Hurdles:The significant capital expenditure needed for state-of-the-art multi-layer co-extrusion lines creates a high barrier to entry and limits the ability of smaller players to compete on technology.
- Navigating Global Regulations:Managing compliance across divergent international food contact material standards, such as the FDA in the US, EFSA in Europe, and China's GB standards, requires extensive testing and administrative resources.
- Specialized Labor Scarcity:A shortage of skilled polymer engineers and machine operators capable of running and maintaining complex co-extrusion equipment can constrain production efficiency and innovation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global High Abuse Shrink Bags Market |
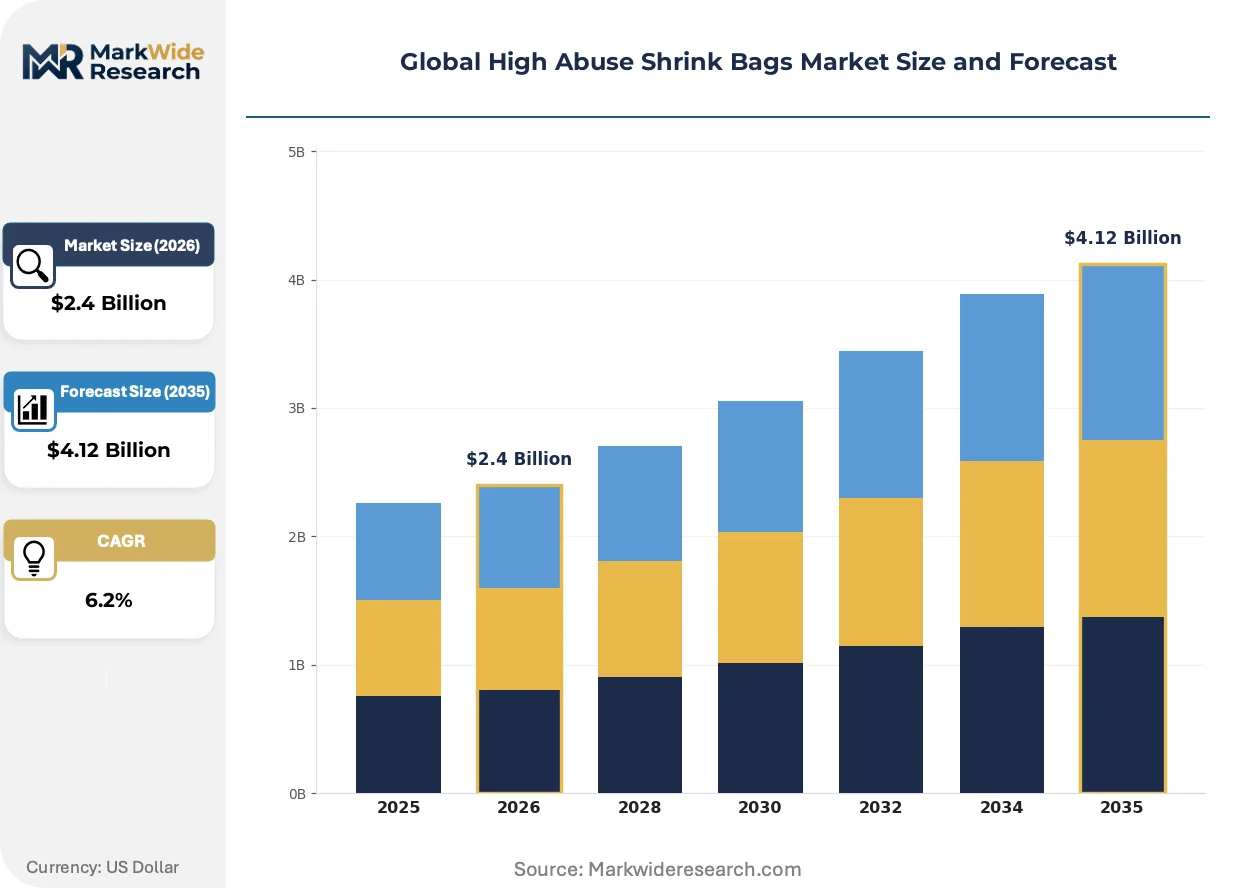
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.12 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polyethylene, Polypropylene, PVC, PVDC, EVA End Use Industry: Food Packaging, Pharmaceuticals, Electronics, Consumer Goods, Chemical Products Packaging Format: Single Pack, Multipack, Bundled Packs, Display Packs, Bulk Packs Application Type: Protection & Preservation, Tamper Evidence, Branding, Logistics Handling, Anti-Theft |
| Companies Covered | Amcor, Sealed Air, Berry Plastics Group Incorporated, Bemis Krehalon UK Ltd., Krehalon Industries B.V., Flexopack, Printpack, Novolex, Apex Packaging Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global High Abuse Shrink Bags Market Strategic Shifts & Innovations
Material science is at the core of market evolution, driven by a dual mandate to enhance film performance while simultaneously improving the sustainability profile of multi-layer structures. This dynamic forces a continuous cycle of reformulation and process optimization for manufacturers.
Advanced co-extrusion technology, which enables the creation of films with nine, eleven, or more distinct layers, provides unprecedented control over barrier and mechanical properties. Food processors handling high-value protein products are the primary adopters, seeking tailored solutions. This capability is fragmenting the market away from generic, all-purpose bags toward application-specific film structures optimized for products like bone-in lamb versus hard cheeses.
The European Union's Circular Economy Action Plan is forcing a re-evaluation of packaging design. This policy directly challenges the viability of traditional multi-polymer high abuse bags due to their poor recyclability. The fresh meat packaging segment in Europe is most affected, with material suppliers now prioritizing R&D on mono-material polyethylene-based solutions that offer sufficient puncture resistance while being compatible with existing recycling streams.
Retailer preference for case-ready packaged meat products is altering supply chain dynamics. This model transfers packaging responsibility from individual stores to large, centralized processing facilities, which then ship shelf-ready items. This shift, most visible in North American and Western European grocery channels, increases the demand for high abuse shrink bags that can endure longer, more complex distribution routes without failure.
Global High Abuse Shrink Bags Market Segmentation
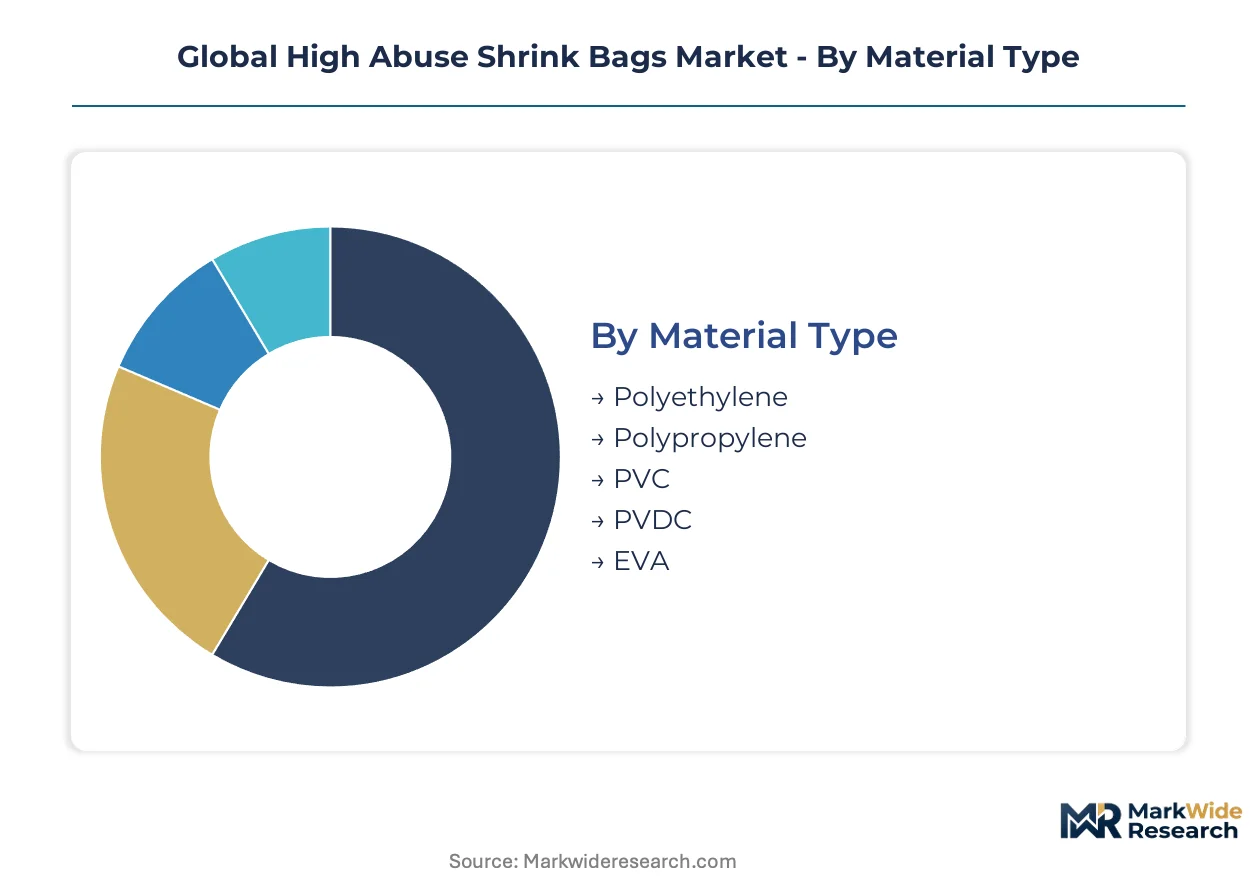
The market for high abuse shrink bags differentiates across material compositions, end-use applications, and packaging formats. Understanding these distinct segments allows manufacturers to align product development with specific performance requirements. This segmentation highlights where specialized solutions are most critical for product integrity and supply chain efficiency.
Material Type:
Distribution channels for high abuse shrink bags often dictate material choice, with specialized polymer formulations flowing to large processors.
- Polyethylene:Advanced multi-layer polyethylene bags offer excellent puncture resistance and flexibility for bone-in meat packaging. Demand concentrates in meat processing hubs across the Midwestern United States and Brazil, driven by superior product integrity in cold chain logistics.
- EVA:Ethylene Vinyl Acetate formulations provide enhanced elasticity and barrier properties for demanding applications requiring strength and sealability. Food processors for high-value protein in Europe seek EVA-based solutions to meet stringent EFSA food contact regulations.
- Polypropylene:Polypropylene-based films offer good clarity and stiffness, finding applications in specific non-food packaging where optical properties are prioritized over extreme puncture resistance.
- PVC:Polyvinyl Chloride shrink films provide high clarity and gloss, often used for display packaging in retail environments where visual appeal is a primary concern.
- PVDC:Polyvinylidene Chloride films deliver exceptional oxygen and moisture barrier properties, important for extending shelf life in specialized food applications.
Polyethylene dominates the installed base. EVA is where expansion concentrates.
End Use Industry:
Specific functional requirements of each end-use industry determine the necessary performance characteristics for high abuse shrink bags.
- Food Packaging:This segment requires superior puncture resistance and barrier properties to protect perishable items, especially bone-in meats and poultry. Demand is highest in centralized protein processing facilities in Brazil and the United States, focused on maintaining freshness.
- Pharmaceuticals:High abuse shrink bags in pharmaceutical applications protect sensitive medical devices and sterile products from contamination and physical damage. Compliance with stringent regulatory standards from the FDA in the United States and EMA in Europe is paramount.
- Electronics:Electronic components and devices utilize these bags for protection against static discharge and physical impacts during transit and storage.
- Consumer Goods:Diverse consumer products, including hardware and household items, use shrink bags for tamper evidence and bundling multiple units.
- Chemical Products:Industrial chemicals and hazardous materials employ high abuse bags for secure containment and protection against leaks or external contamination.
Food Packaging commands the largest share of demand. Pharmaceutical applications exhibit a rapidly climbing share.
Packaging Format:
Product volume directly influences the choice of high abuse shrink bag format, optimizing for efficiency and cost.
- Bulk Packs:Large format bags are designed for high-volume industrial and food processing applications, often containing multiple units or large meat cuts. Centralized meat processors in North America and Europe rely on bulk packaging for efficient retail and foodservice distribution.
- Multipack:Multipack formats bundle several individual items, enhancing retail presentation and consumer convenience for products like sausages or smaller meat cuts. Retailer preferences in Western European grocery channels drive demand for appealing, functional multipack solutions.
- Single Pack:Individual items, particularly high-value or specialty products, utilize single-pack shrink bags for precise protection and branding.
- Bundled Packs:Bundled configurations combine related products for promotional purposes or to create a more substantial retail offering.
- Display Packs:These formats are engineered for retail shelf presence, often featuring enhanced clarity and printability for product visibility.
Bulk Packs represent the foundational volume. Multipack solutions are currently gaining share most quickly.
Application Type:
Packaging technology maturity in a given application dictates the sophistication required in high abuse shrink bag design.
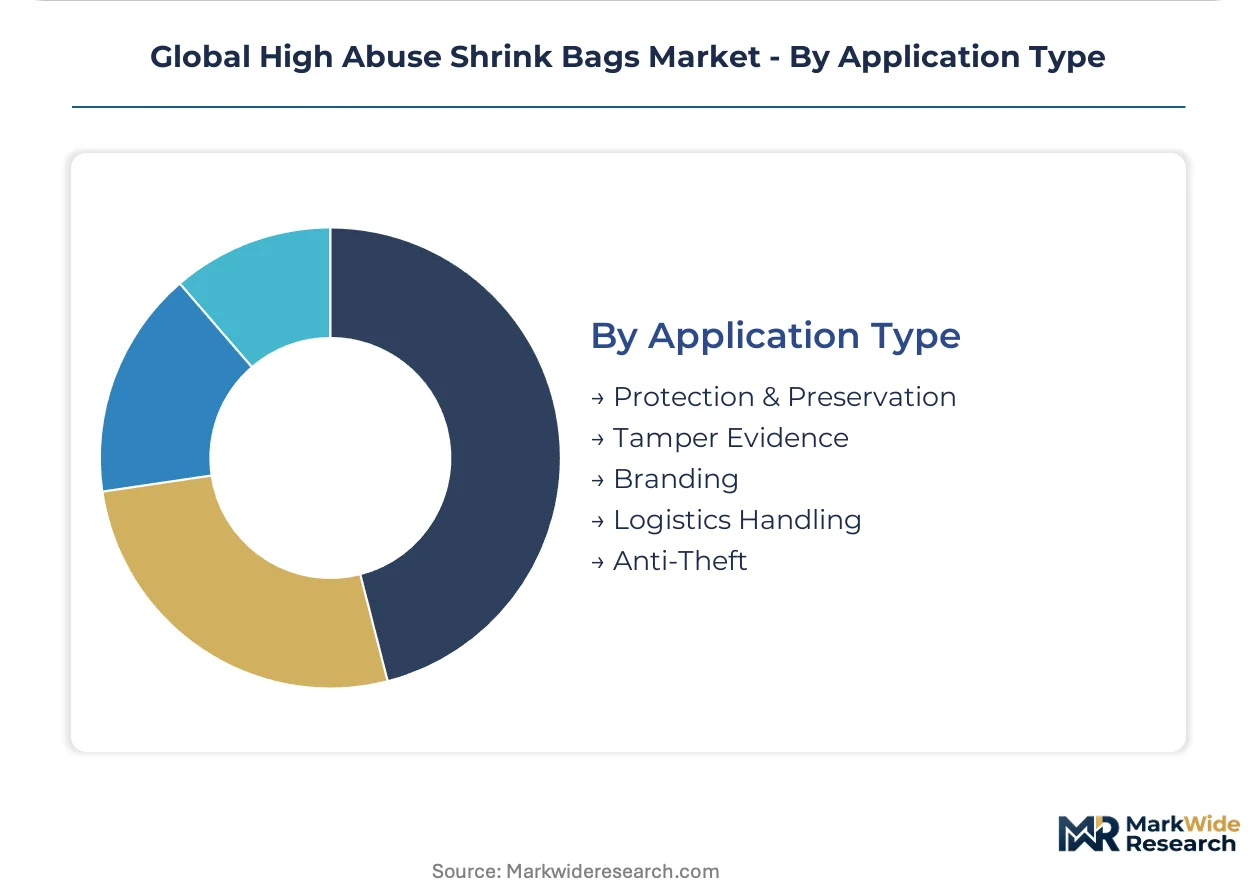
- Protection & Preservation:This core application focuses on shielding products from physical damage, moisture, and oxygen, extending shelf life and quality. Fresh protein products in global supply chains, particularly those from Brazil, depend on robust protection for market access.
- Branding:Shrink bags contribute to product branding through high-quality graphics, transparent windows, and unique shapes that enhance shelf appeal. Consumer-facing products in competitive retail environments, especially North America, leverage branding for differentiation.
- Tamper Evidence:These applications utilize shrink films to provide visible proof of tampering, ensuring product integrity and consumer safety.
- Logistics Handling:Shrink bags facilitate easier handling, stacking, and palletization of products throughout the complex distribution network.
- Anti-Theft:Certain shrink packaging designs incorporate features that deter theft, particularly for high-value smaller consumer items in retail.
Protection & Preservation remains the primary functional driver. Branding applications show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for high abuse shrink bags varies significantly across end-use sectors. Buyers in premium food packaging, especially for bone-in meats, exhibit lower price sensitivity due to critical safety and shelf-life requirements. Conversely, non-food applications or commodity segments often demonstrate greater price sensitivity, seeking cost-effective solutions.
United States
United States demand for high abuse shrink bags centers on its vast centralized meat processing industry, particularly for bone-in beef and pork. FDA food contact regulations mandate stringent packaging standards for food safety and consumer protection. The Midwestern United States, including major hubs like Omaha and Chicago, drives significant volume for protein packaging.
Brazil
Brazilian demand is propelled by its massive beef export market and growing domestic protein consumption. ANVISA food safety standards are crucial for ensuring product integrity and market access for Brazilian meat products. Large-scale processing facilities in São Paulo and Mato Grosso utilize these bags extensively for fresh and frozen meat.
Germany
German demand emphasizes high-performance packaging for premium fresh and processed protein products within the European market. EFSA regulations for food contact materials dictate specific polymer and additive usage for compliance. Advanced food processing clusters in regions like North Rhine-Westphalia lead innovation in sustainable shrink bag solutions.
China
China's expanding cold chain logistics and increasing consumption of packaged meats drive significant demand for high abuse shrink bags. GB standards for plastic packaging materials influence material selection and product development for domestic manufacturers. Major food processing and packaging hubs in the Yangtze River Delta region represent key consumption areas.
Global High Abuse Shrink Bags Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the high abuse shrink bags market. Large-scale global manufacturers, often vertically integrated, invest heavily in advanced multi-layer co-extrusion technologies and proprietary polymer formulations. In contrast, regional specialists focus on customized solutions and faster turnaround times for niche applications. Strategic moves include continuous R&D into sustainable materials and geographic expansion into emerging processing hubs.
Within the global scale and innovation tier, Amcor and Sealed Air exemplify market leadership through extensive R&D capabilities and integrated packaging systems. Amcor, with its global manufacturing footprint, serves multinational food processors across continents. Sealed Air sustains its market position by leveraging proprietary polymer formulations for specialized applications. Flexopack, a European-based company, represents regional players offering customized solutions and quicker delivery for specific end-use applications in its local markets.
| Leading Market Players |
|---|
| Amcor |
| Sealed Air |
| Berry Plastics Group Incorporated |
| Bemis Krehalon UK Ltd. |
| Krehalon Industries B.V. |
| Flexopack |
| Printpack |
| Novolex |
| Apex Packaging Corporation |
| Others |
Cost & Logistics Intelligence
Long-term offtake agreements for specialized polymer resins lock in both supply access and price visibility for large-scale manufacturers in the high abuse shrink bags market. These contracts mitigate the impact of volatile raw material costs, providing stability for key producers.
Pricing Analysis
After-sales service and technical support drive lifetime value for high abuse shrink bag solutions, particularly for complex co-extrusion lines. Per-unit transactional pricing dominates, but value-based models emerge for custom-engineered films. Price differentiation stems from quality grade, with FDA and EFSA certifications commanding premiums, and volume scale discounts influencing large processors. Pricing pressure originates from raw material cost fluctuations, compressing manufacturer margins. Buyers in premium food packaging for bone-in meats exhibit lower price sensitivity, while non-food applications seek more cost-effective solutions.
Supply Chain Analysis
Inbound logistics costs, particularly container availability for polymer shipments from major production hubs, impact manufacturing expenses for high abuse shrink bags. Geographic supply concentration centers on resin producers in the United States, Europe, and Asia. Raw material dependencies include polyethylene and Ethylene Vinyl Acetate (EVA) formulations. Commodity price volatility presents a structural supply chain risk for film manufacturers. Distribution runs through centralized processing facilities, which then supply retail and foodservice channels globally.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a platform-economics inflection, driven by the increasing interoperability between advanced material science and sustainable packaging solutions.
For Market Incumbents: Consolidate R&D efforts on mono-material polyethylene-based solutions to address regulatory pressure for recyclability. Expand global manufacturing footprint in emerging markets like Southeast Asia to capture new demand. Invest in certification for bio-based polymers to maintain market leadership against sustainability mandates. Leverage existing channel control to introduce advanced film technologies to multinational food processors.
For New Entrants and Emerging Players: Lead with customized solutions for specific end-use applications in non-food sectors, such as hardware or automotive parts. Target underpenetrated emerging markets in Latin America with cost-effective, high-performance offerings. Focus go-to-market strategies on faster turnaround times and specialized technical support for regional clients. Develop niche expertise in unique polymer blends for challenging packaging requirements.
For Investors and Strategic Acquirers: Capital is best deployed toward specialized material science firms with proprietary polymer formulations and advanced co-extrusion capabilities. Long-term viability hinges on sustainability-aligned growth over the next decade, favoring companies with circular economy solutions. Acquisition targets should demonstrate strong intellectual property in bio-based or recyclable high abuse films. The signal to watch is the adoption rate of certified circular polymers by major food brands.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Mono-Material R&D | This initiative directly addresses European Union Circular Economy mandates for packaging recyclability. |
| Expand Co-extrusion Capacity | Increased capacity supports the rising demand for multi-layer, high-performance films in protein packaging. |
| Secure Bio-Based Polymer Supply | Ensuring access to sustainable raw materials mitigates environmental impact and meets consumer preferences. |
| Strengthen Regulatory Compliance Teams | Robust compliance ensures market access across diverse regions like the US, Europe, and China. |
| Target Non-Food Industrial Applications | Diversifying into sectors like hardware and automotive parts reduces reliance on the cyclical food industry. |
Research Approach
A standing panel of food processing executives, polymer engineers, packaging procurement leads, and regulatory compliance officers provided ongoing calibration throughout the analysis. This approach combined primary interviews with extensive secondary validation from sources like FDA filings, EFSA reports, GB standards, and trade association publications. The methodology employed both bottom-up market sizing and top-down market validation to ensure data accuracy and comprehensive coverage.
Consistency checks validated outputs against external benchmarks and established market intelligence across the analysis window. The analytical framework modeled segmentation dimensions including material compositions, end-use applications, packaging formats, application types, and regional consumption patterns. Compound Annual Growth Rates (CAGRs) were derived from historical trends and projected market dynamics, incorporating key industry-specific forecast inputs such as protein consumption growth and multi-layer co-extrusion technology adoption.
The analysis sits within stated boundaries; outcomes outside significant raw material price shocks or major shifts in global trade policies would require recalibration. Forecasts reflect assumptions regarding technological advancements and regulatory stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Pasted Valve Bags Market
Bags and Containers
Cross Bottom Bags Market
Bags and Containers
Insulated Delivery Bag Market
Bags and Containers
Crates Market
Bags and Containers
Bag-In-Box Market
Bags and Containers
Big Bag Discharge Station Market
Bags and Containers
Ventilated FIBC Market
Bags and Containers
Bulk Bags Market
Bags and Containers
Flip Lip Bags Market
Bags and Containers
Compression Baggers Market
Bags and Containers
Liquid Packaging Bag Market
Bags and Containers
Counter Bags Market
Bags and Containers
Silicone Storage Bags Market
Bags and Containers
On the Go Packaging Market
Bags and Containers
Hanging Bags Market
Bags and Containers
Self-Sealing Ziplock Bags Market