
 Twin Seal Bags Market | 2026-2036
Twin Seal Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Twin Seal Bags Market Analytics
REACH compliance in Europe is consolidating the cost-of-entry calculus for twin seal bag converters targeting pharmaceutical and food-grade applications. Amcor plc leverages its integrated film extrusion and converting footprint to sustain compliance leadership across EU member states. Sealed Air Corporation anchors North American demand through controlled-atmosphere packaging systems that incorporate proprietary heat-seal technologies. Berry Global, Inc. competes on polyethylene resin scale and regional manufacturing density.
Twin seal bags are flexible packaging structures featuring two independent closure mechanisms—typically a primary heat-seal layer paired with a secondary zip or adhesive seal—manufactured through coextrusion or lamination processes with total gauge ranges from 50 to 120 micron. These constructions provide redundant barrier protection against moisture and oxygen ingress, serving critical functions in perishable food preservation and moisture-sensitive pharmaceutical storage. Polyethylene formulations dominate volume production due to cost efficiency and seal reliability, while foil laminations command premium positioning in pharmaceutical end uses where light and oxygen exclusion are paramount. Heat seal technology leads across industrial and food applications, though cold seal systems are gaining traction in temperature-sensitive pharmaceutical packaging where thermal degradation of active ingredients must be avoided.
FDA food contact substance regulations and EU REACH chemical authorization requirements shape material selection and migration testing protocols for all suppliers accessing regulated end uses. BIS certification in India and GB standards compliance in China create additional testing burdens for exporters seeking qualification in those markets. Stakeholders must monitor evolving extended producer responsibility frameworks and substrate recyclability mandates, as these will determine which material-seal combinations retain market access over the forecast horizon.
Market Dynamics
REACH chemical authorization and EU Packaging Waste Directive mandates are forcing converters toward mono-material polyethylene formulations, eliminating multi-layer laminations that previously dominated barrier packaging for perishables and pharmaceuticals.
Growth Catalysts
- EU regulatory consolidation:The EU Packaging Waste Directive's recyclability targets are accelerating demand for mono-material twin seal constructions in German food processing and pharmaceutical contract packing operations.
- Cold seal technology:Temperature-sensitive pharmaceutical packaging is pulling cold seal systems into mainstream adoption where thermal degradation of active ingredients must be avoided entirely.
- Barrier specification upgrades:Food processors across refrigerated and shelf-stable segments are demanding redundant moisture-oxygen protection that twin seal architectures uniquely provide.
Market Restraints
- Resin cost volatility:Polyethylene feedstock exposure creates margin compression for converters lacking backward integration into polymer production.
- Multi-layer technical lock-in:Existing foil lamination infrastructure cannot be retrofitted for mono-material output without substantial capital redeployment.
- Substitution by rigid formats:Glass and pharmaceutical-grade rigid containers retain preference in ultra-high-barrier applications where oxygen exclusion exceeds flexible packaging limits.
Strategic Opportunities
- Indian export qualification:BIS certification requirements create a protected supplier tier for converters willing to absorb testing burdens for pharmaceutical-grade exports.
- Controlled-atmosphere integration:Twin seal bags paired with modified atmosphere packaging systems are expanding into fresh produce distribution channels.
- Extended producer responsibility tailwinds:EU member state implementations of EPR frameworks favor recyclable mono-material formats over complex multi-substrate alternatives.
Industry Challenges
- Migration testing capacity:FDA food contact substance protocols and EU REACH authorization timelines strain analytical laboratory throughput for new material qualification.
- Heat seal-cold seal integration:Manufacturing lines must accommodate both thermal and adhesive bonding methods without changeover penalties.
- Recyclability certification complexity:Third-party recyclability claims require harmonized testing across multiple national packaging registries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Twin Seal Bags Market |
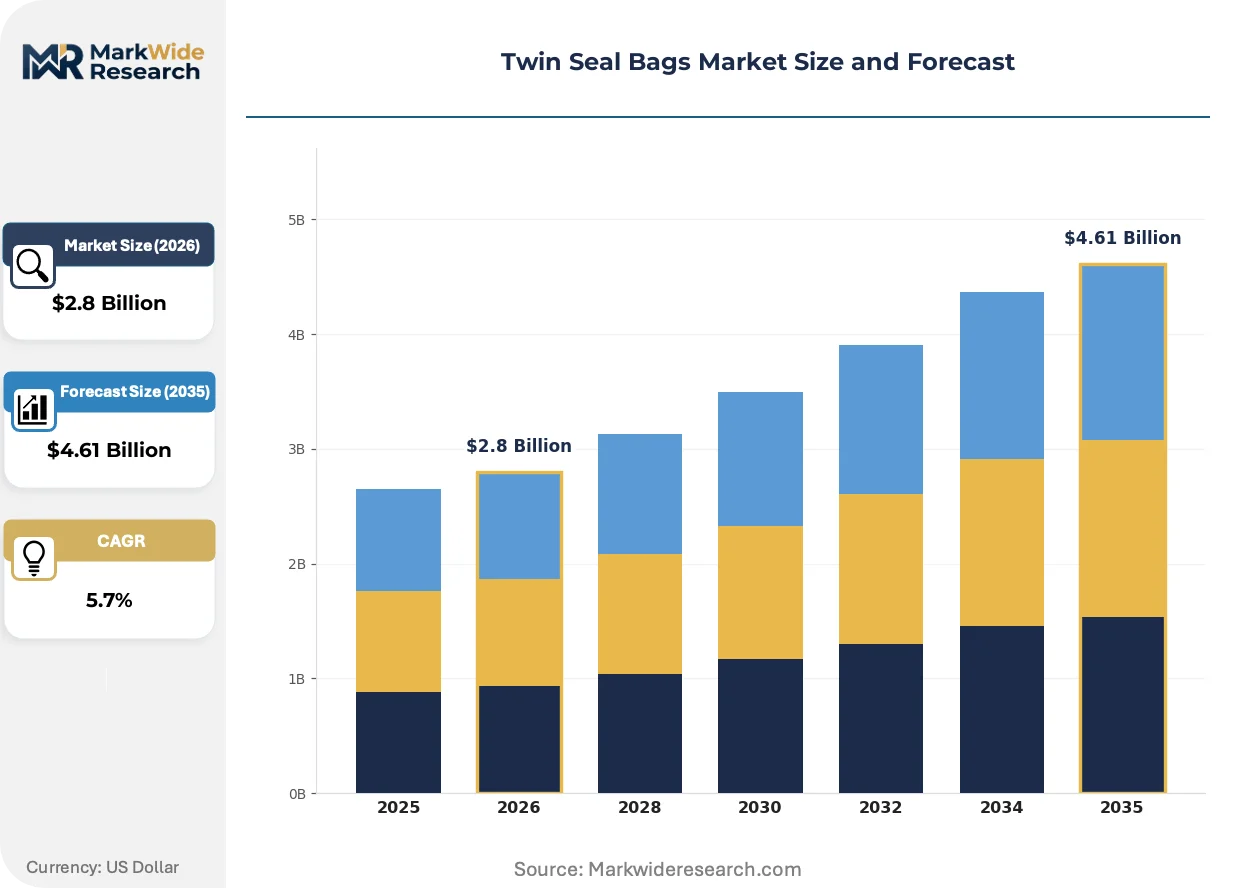
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polyethylene, Polypropylene, Nylon, Foil Seal Type: Heat Seal, Cold Seal, Pressure Seal, Adhesive Seal End Use: Food Packaging, Pharmaceutical Packaging, Industrial Packaging, Consumer Goods Packaging Thickness: 50 Micron, 70 Micron, 100 Micron, 120 Micron |
| Companies Covered | Aropak Sdn Bhd, Bagpack Inc., Emerald Packaging, Inc., Safepak, Rayna Enterprises, Wuxi Benno, Amcor plc, Sealed Air Corporation, Berry Global, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Twin Seal Bags Market Evolving Landscape
Material science advances and regulatory pressure on substrate complexity are converging to redefine competitive advantage around seal reliability and end-of-life recyclability rather than barrier performance alone.
Mono-material polyethylene twin seal constructions are expanding into pharmaceutical applications previously reserved for foil laminations. German and Swiss pharmaceutical contract packers are qualifying all-polyethylene formats for moisture-sensitive solid dose products. This migration is compressing demand for aluminum-containing laminations and forcing foil suppliers to defend position through oxygen barrier guarantees that polyethylene cannot match.
REACH authorization requirements for chemical substances used in adhesive seal layers are tightening migration testing protocols across EU member states. Converters must now document substance safety across the full product lifecycle, not just finished article compliance. Food-grade and pharmaceutical-grade applications face the steepest documentation burdens, with German regulators leading enforcement stringency.
Buyer consolidation among European retail chains is compressing supplier qualification timelines and unbundling technical service from unit pricing. Large German and French food retailers now demand twin seal specifications that balance shelf-life extension with store-drop recyclability claims. This specification tightening favors converters with integrated film extrusion and in-house seal technology development capabilities.
Twin Seal Bags Market Segmentation
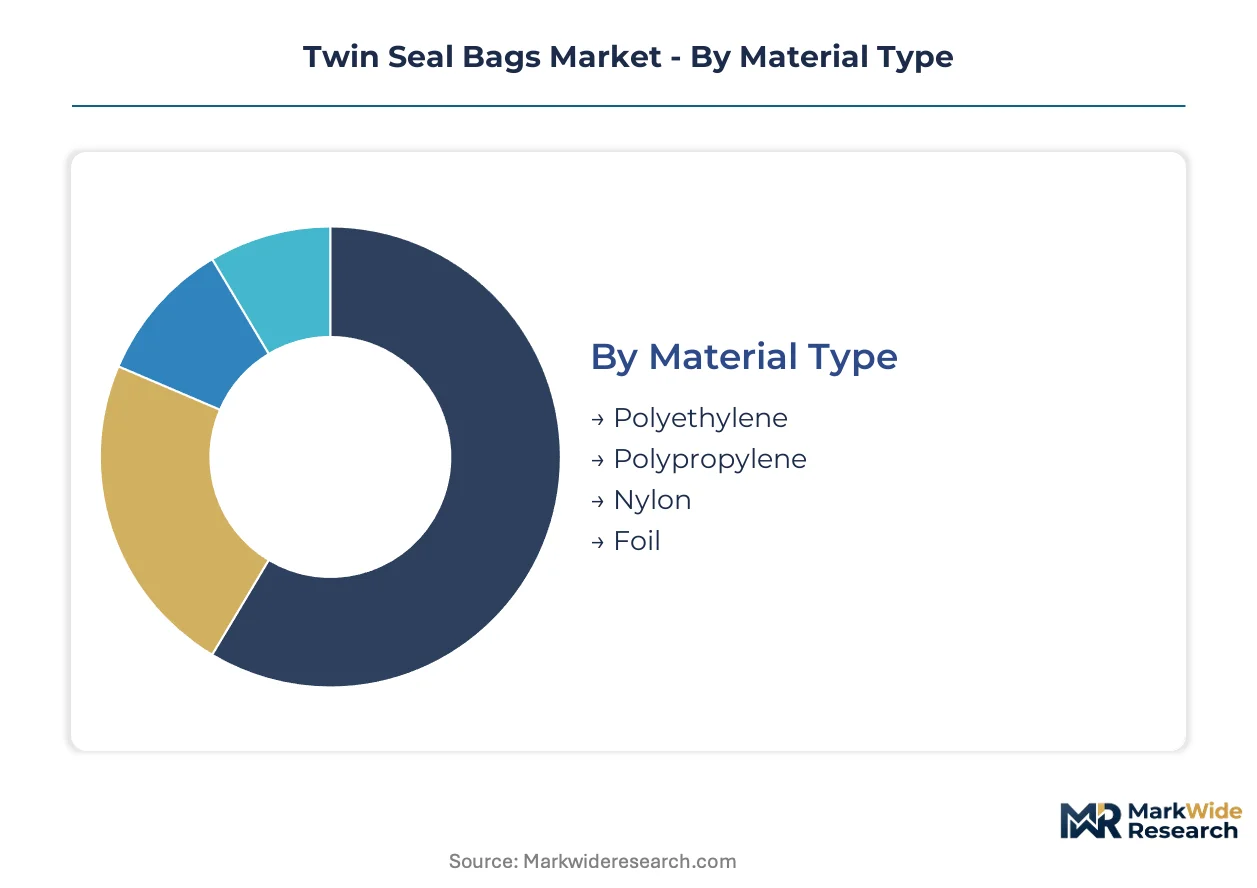
Twin seal bag specifications diverge sharply across material chemistry and seal architecture, with regulatory compliance and end-use barrier requirements driving selection. Converters must match substrate-seal combinations to specific migration testing protocols and recyclability mandates. Each segmentation axis presents distinct trade-offs between unit economics, performance certification, and supply chain qualification burdens.
Material Type:
Standardization dominates commodity polyethylene grades, while pharmaceutical and high-barrier food applications demand customized multi-layer or foil-reinforced constructions tailored to specific oxygen and moisture transmission specifications.
- Polyethylene:Linear low-density and metallocene polyethylene formulations provide cost-efficient heat seal reliability and mono-material recyclability. German food processors and pharmaceutical contract packers are consolidating procurement around all-polyethylene formats to satisfy EU Packaging Waste Directive recyclability targets and REACH authorization documentation requirements.
- Foil:Aluminum-containing laminations deliver oxygen transmission rates below 0.1 cc/m²/day for moisture-sensitive pharmaceuticals and oxygen-critical food applications. Demand concentrates in Swiss and German pharmaceutical packaging where oxygen exclusion guarantees override recyclability concerns and justify premium positioning.
- Polypropylene:Cast and oriented polypropylene films offer elevated temperature resistance and clarity for retort and hot-fill food applications requiring sterilization compatibility.
- Nylon:Polyamide layers provide puncture resistance and mechanical strength for industrial and bone-in meat packaging with abrasive handling requirements.
Leading the category by volume: Polyethylene. Growing fastest: Foil laminations in pharmaceutical barrier applications.
Seal Type:
Application temperature sensitivity and active ingredient stability determine seal architecture selection, with pharmaceutical cold seal demand pulling investment away from conventional thermal bonding systems.
- Heat Seal:Thermal bonding of polyethylene or polypropylene layers through controlled temperature, pressure, and dwell time parameters produces hermetic closures with validated seal strength consistency. Food packaging across refrigerated and shelf-stable segments anchors volume demand, though REACH chemical authorization for seal layer additives is extending qualification timelines.
- Cold Seal:Pressure-activated cohesive coatings bond at ambient temperatures, eliminating thermal exposure for temperature-sensitive pharmaceutical actives. German and Swiss contract packers are qualifying cold seal twin seal bags for biologic and probiotic solid dose products where thermal degradation risks exclude heat seal processing.
- Pressure Seal:Mechanical interlock or cohesive closure systems activated by finger pressure serve consumer convenience applications with moderate barrier requirements.
- Adhesive Seal:Permanent or resealable pressure-sensitive adhesive layers provide secondary closure redundancy in multi-meal food portions and medical kit packaging.
Dominating production scale: Heat Seal. Expanding most quickly: Cold Seal for pharmaceutical temperature sensitivity.
End Use:
Regulatory stringency and barrier specification complexity create tiered margin structures, with pharmaceutical applications commanding qualification premiums and food packaging driving volume scale.
- Food Packaging:Modified atmosphere and vacuum-compatible twin seal constructions extend shelf life for fresh produce, processed meats, and ready-to-eat meals. German retail chains are unbundling technical service from unit pricing, demanding specifications that balance shelf-life extension with store-drop recyclability claims.
- Pharmaceutical Packaging:FDA food contact substance regulations and EU REACH chemical authorization requirements impose migration testing and documentation burdens that exclude commodity converters. Moisture-sensitive solid dose and probiotic applications are migrating toward all-polyethylene formats previously reserved for foil laminations.
- Industrial Packaging:Heavy-duty polyethylene constructions with reinforced seals serve chemical, automotive, and electronics components requiring particulate and moisture protection during distribution.
- Consumer Goods Packaging:Convenience-oriented resealable formats for personal care, household products, and apparel prioritize tactile seal quality and repeated open-close durability.
Highest volume concentration: Food Packaging. Steepest specification escalation: Pharmaceutical Packaging.
Thickness:
Mechanical durability and barrier performance trade against material cost and flexural fatigue, with gauge selection calibrated to handling severity and shelf-life requirements.
- 70 Micron:Mid-range gauge balances puncture resistance and seal integrity for mainstream food and consumer applications without excessive material consumption.
- 100 Micron:Elevated thickness provides structural rigidity for standing pouch formats and industrial applications with rough handling exposure.
- 50 Micron:Minimum viable gauge for lightweight, cost-sensitive applications with limited barrier demands and gentle distribution environments.
- 120 Micron:Maximum specified thickness for heavy industrial and export packaging requiring extreme puncture resistance and seal robustness under load.
Standard specification anchor: 70 Micron. Gaining specification share: 100 Micron for standing format expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Vietnam and industrial parks across Malaysia are concentrating flexible packaging investment. These zones offer tax holidays and duty exemptions that offset REACH compliance costs for exporters serving European pharmaceutical and food processing clients.
Germany
Pharmaceutical contract packers in Baden-Württemberg and Bavaria are upgrading to mono-material twin seal formats. ECHA enforcement of REACH chemical authorization for adhesive seal layers extends qualification timelines for converters. The Stuttgart industrial corridor hosts qualification programs where food processors test all-polyethylene constructions against foil lamination benchmarks.
United States
Controlled-atmosphere packaging demand from California fresh produce distributors and Midwest meat processors anchors heat seal volume. FDA food contact substance regulations shape migration testing protocols for suppliers accessing regulated end uses. The Chicago packaging cluster integrates twin seal bags with modified atmosphere systems for refrigerated distribution networks.
China
GB standards compliance requirements create testing burdens for exporters seeking pharmaceutical-grade qualification in domestic and overseas markets. The Yangtze River Delta concentration of flexible converters serves both export pharmaceutical packaging and domestic food retail chains. Shanghai-based laboratories handle migration testing for REACH and FDA parallel submissions.
India
BIS certification requirements for pharmaceutical-grade exports are consolidating supplier tiers around converters with analytical laboratory partnerships. Maharashtra and Gujarat host the primary flexible packaging clusters serving contract pharmaceutical packers. Mumbai-based converters are absorbing testing costs to qualify for European and North American pharmaceutical supply chains.
Switzerland
Swissmedic pharmaceutical packaging regulations and proximity to German pharmaceutical manufacturing sustain demand for ultra-high-barrier foil laminations. The Basel-Lucerne corridor concentrates pharmaceutical packaging innovation where oxygen exclusion guarantees override recyclability concerns. Contract packers here qualify cold seal twin seal formats for temperature-sensitive biologic products.
Twin Seal Bags Market Competitive Landscape
European producers anchor one tier; Asia-Pacific specialists hold cost-competitive positions in commodity polyethylene formats. The market structure reflects consolidation among integrated film extruders and fragmentation among regional converters serving single end-use segments. Three archetypes dominate: integrated multinational suppliers with captive resin supply, regional specialists with pharmaceutical qualification capabilities, and commodity converters competing on unit economics. Capacity expansion and strategic partnerships represent the dominant competitive moves as players address mono-material transition requirements.
Within the integrated multinational tier, Amcor plc and Sealed Air Corporation exemplify converters with film extrusion and seal technology development capabilities. Among regional specialists, Emerald Packaging, Inc. occupies a position representing pharmaceutical-grade qualification expertise. These named entities anchor industry-level commentary without specific factual claims about individual strategic actions or market positions.
| Leading Market Players |
|---|
| Aropak Sdn Bhd |
| Bagpack Inc. |
| Emerald Packaging, Inc. |
| Safepak |
| Rayna Enterprises |
| Wuxi Benno |
| Amcor plc |
| Sealed Air Corporation |
| Berry Global, Inc. |
| Others |
Value Network & Pricing Analysis
Captive resin supply from integrated polyethylene producers anchors both procurement security and margin stability for twin seal bag converters serving REACH-regulated European markets. German food processors and pharmaceutical contract packers absorb premium positioning for mono-material formats that satisfy ECHA chemical authorization documentation.
Pricing Analysis
Short lead-time premiums separate urgent pharmaceutical qualification orders from standard food-packaging procurement cycles. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume scale, with FDA food contact substance tiering commanding substantial premiums over industrial-grade polyethylene. Price erosion runs through commodity converters lacking backward integration, as resin cost volatility compresses margins. Food retail chains exhibit highest price sensitivity, while Swiss pharmaceutical contract packers prioritize oxygen barrier guarantees over unit economics.
Supply Chain Analysis
Regional distribution centers in Germany, China, and India organize hub-and-spoke patterns for pharmaceutical-grade twin seal bags. Manufacturing concentration in the Yangtze River Delta, Maharashtra-Gujarat corridor, and Baden-Württemberg feeds from metallocene polyethylene, adhesive cohesive coatings, and aluminum foil laminations. Single-source vulnerability in European specialty resin supply creates structural exposure. Distribution runs through converter-direct models for large pharmaceutical contract packers and packaging distributors for mid-tier food processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Migration testing laboratory capacity constrains new material qualification throughput, propping pricing for converters with established FDA and REACH documentation archives.
For Market Incumbents: Acquire analytical testing partnerships to compress REACH authorization timelines for adhesive seal layer formulations. Expand cold seal manufacturing lines in the Stuttgart industrial corridor to capture Swiss pharmaceutical biologic packaging demand. Consolidation pressure from buyer-unbundled technical service threatens standalone converters lacking integrated film extrusion. For New Entrants and Emerging Players: Indian pharmaceutical contract packers seeking BIS-certified export qualification represent the most penetrable buyer archetype. Cold seal twin seal formats for temperature-sensitive probiotics offer white-space positioning against heat seal incumbents. Lead with analytical laboratory co-investment to absorb migration testing burdens that exclude commodity competitors. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated multinational suppliers seeking mono-material formulation capabilities. Long-term viability favors converters with captive polyethylene supply and in-house seal technology development. Watch for EPR framework implementation acceleration across EU member states as inflection indicator for recyclable format demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Metallocene Polyethylene | Captive resin supply insulates margin compression from feedstock volatility for REACH-compliant converters. |
| Cold Seal Manufacturing Line Expansion | Temperature-sensitive pharmaceutical qualification opens Swiss and German biologic packaging contracts. |
| Migration Testing Laboratory Partnership | Parallel FDA and REACH submission capability compresses qualification timelines for adhesive seal layers. |
| Mono-Material Format Certification Investment | EU Packaging Waste Directive recyclability claims secure access to German retail chain procurement. |
| Regional Distribution Hub Establishment | Hub-and-spoke logistics in Maharashtra-Gujarat corridor reduce lead times for Indian pharmaceutical exports. |
Research Methodology
Independent corroboration across converter operations managers, pharmaceutical packaging engineers, and food retail procurement directors underwrites the qualitative findings. Secondary validation draws from ECHA substance authorization databases, FDA food contact substance notifications, BIS certification registries, and flexible packaging trade association capacity surveys. Bottom-up volume modeling triangulates against top-down spending pattern analysis across the projection horizon.
Comparable historical periods anchored the forecast window to pre-pandemic baseline demand and post-regulatory-shift adjustment phases. Segmentation dimensions span material chemistry, seal architecture, end-use application, thickness specification, and regional regulatory cluster. CAGRs derive from fitted trend extrapolation moderated by capacity constraint assumptions and substitution elasticity estimates for rigid container formats.
Revisions become necessary when REACH authorization timelines extend beyond modeled laboratory throughput capacity or when EPR implementation accelerates recyclability mandate enforcement. Forecasts reflect documented assumptions around resin price stability and regulatory enforcement stringency. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Bag-On-Valve Laminates Market
Bags and Containers
Hermetic Storage Bags Market
Bags and Containers
Octabin Market
Bags and Containers
Woven Sacks Market
Bags and Containers
Wooden Boxes Market
Bags and Containers
Crates Market
Bags and Containers
Net Bags Market
Bags and Containers
Portion Bags Market
Bags and Containers
Block Sack Market
Bags and Containers
Global High Abuse Shrink Bags Market
Bags and Containers
Archive Boxes Market
Bags and Containers
Freezer Bags Market
Bags and Containers
Water Soluble Bags Market
Bags and Containers
Multiwall Bags Market
Bags and Containers
Cooler Bags Market
Bags and Containers
Bag Dump Stations Market