
 Mylar Bags Market | 2026-2036
Mylar Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Mylar Bags Market Analytics
Custom-printed subscription packaging with integrated reseal features is repositioning Mylar bags from commodity liners to branded consumer touchpoints. CarePac leverages digital printing capabilities to serve short-run artisan food brands with rapid turnaround. Constantia Flexibles sustains European pharmaceutical barrier film leadership through cleanroom-certified production networks. ePac Flexible Packaging anchors North American distributed manufacturing with networked digital presses near regional food clusters.
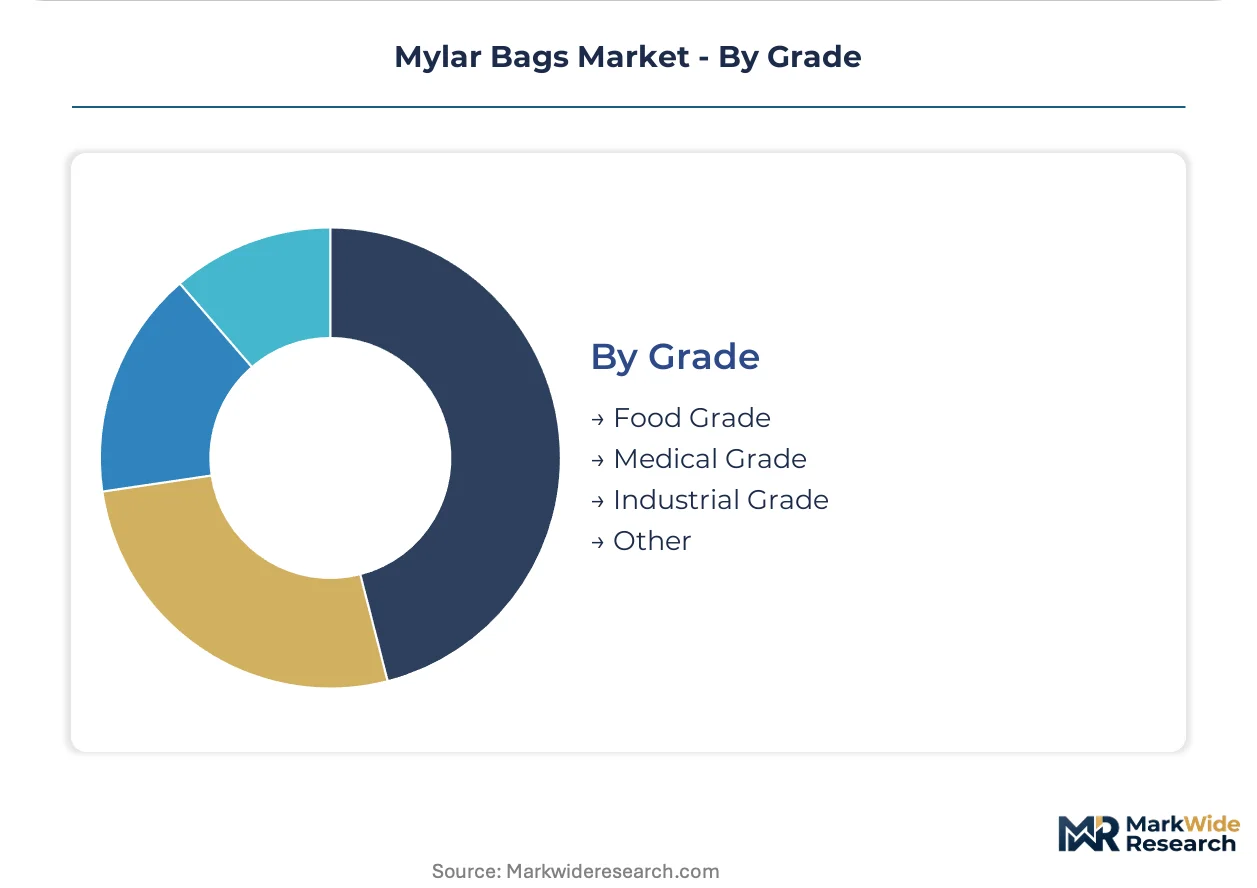
Mylar bags consist of polyethylene terephthalate film laminated with aluminum foil or metallized coatings, typically measuring 3.5 to 7.0 mils in total thickness, engineered to provide oxygen transmission rates below 0.01 cc per square inch per day for moisture-sensitive goods. Stand-up pouches command the largest volume share among product types due to shelf presence and filling-line compatibility across food and beverage lines. Food grade certification dominates grade-level demand, though medical grade specifications are gaining traction as pharmaceutical blister alternatives face aluminum supply constraints. Small and medium sizes lead unit volume while extra large formats capture industrial chemical and bulk ingredient applications.
The FDA regulates direct food contact layers under 21 CFR 177.1630 for polyester resins, while EPA guidelines on per- and polyfluoroalkyl substances are pressuring converters to eliminate fluorinated treatments from high-barrier laminations. The EU Packaging and Packaging Waste Regulation is mandating recyclability-by-design criteria that challenge multi-layer Mylar constructions across export-bound production. California's SB 54 extended producer responsibility framework imposes material recovery targets affecting flexible packaging sold into the state. Stakeholders must monitor chemical compliance deadlines and recyclability mandates to avoid stranded inventory in regulated channels.
Market Dynamics
California's SB 54 extended producer responsibility law is forcing flexible packaging converters to redesign multi-layer Mylar laminations for material recovery compliance, compressing legacy production runs and accelerating recyclable mono-material development timelines.
Growth Catalysts
- E-commerce fulfillment surge:China's cross-border shipping corridors are vacuum-sealing electronics with high-barrier Mylar liners, expanding unit demand for moisture-proof protective packaging.
- Long-term food storage preparedness:North American consumers are stockpiling multi-layer barrier pouches for emergency reserves, lifting order volumes for oxygen-scavenging formats.
- REACH chemical compliance:EU fluorinated substance restrictions are redirecting converter R&D toward PFAS-free high-barrier coatings, creating first-mover advantages for compliant suppliers.
Market Restraints
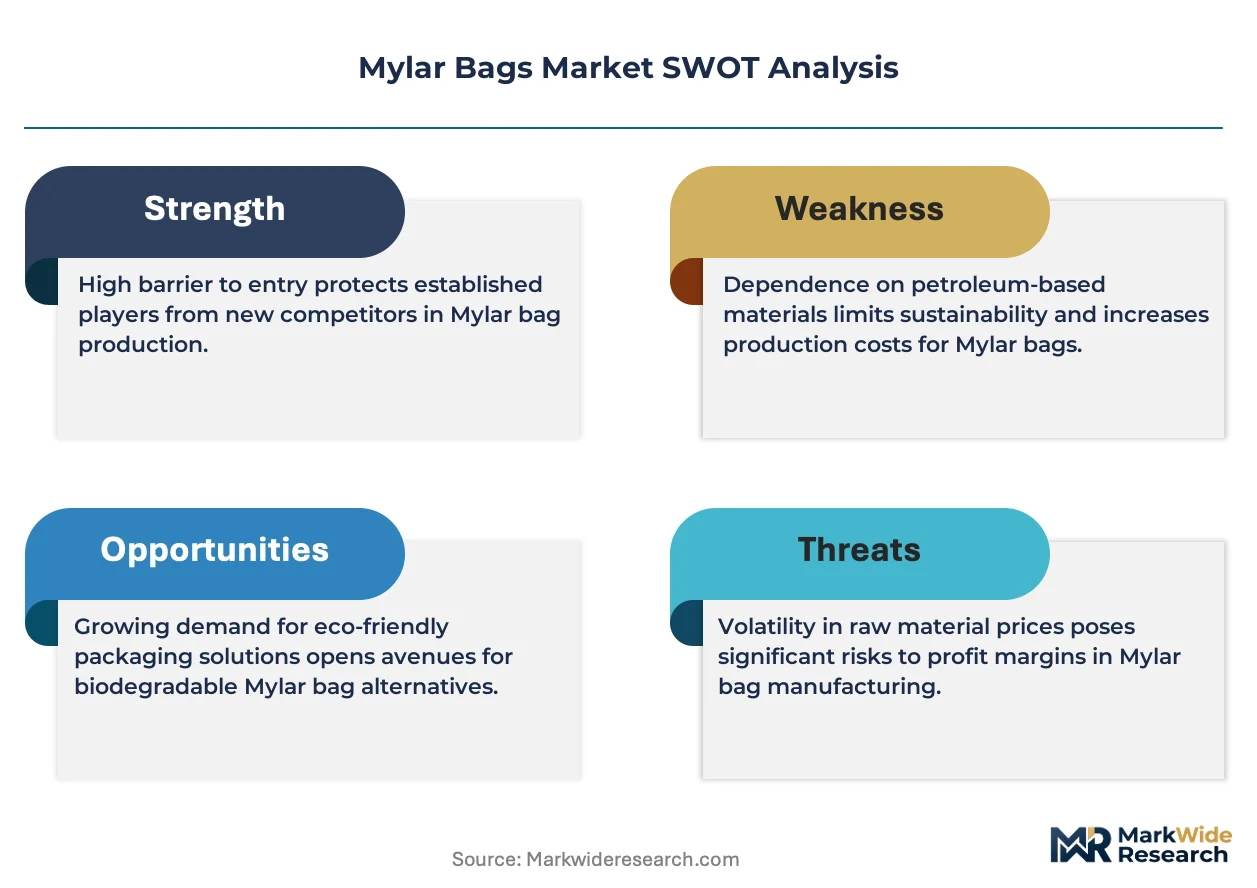
- Aluminum foil supply concentration:Metallized film converters depend on concentrated primary aluminum smelting in China and Russia, exposing laminate producers to input volatility and trade policy disruptions.
- Multi-layer recyclability deadlock:PET-aluminum-PE laminations lack mechanical recycling infrastructure, stranding post-consumer material under EU Packaging and Packaging Waste Regulation targets.
- Fluorinated barrier substitution lag:Non-fluorinated alternatives currently deliver 15-30% lower oxygen barrier performance, limiting immediate compliance pathways for pharmaceutical-grade specifications.
Strategic Opportunities
- Mono-material recyclable platforms:All-polyester barrier films with vapor-deposited silicon oxide coatings are qualifying for European recycling streams, opening premium positioning against legacy laminates.
- Pharmaceutical blister displacement:Aluminum supply constraints for cold-form foil are pushing drug packagers toward thermoformable Mylar alternatives with comparable moisture barrier.
- Digital printing integration:Short-run custom branding for artisan food subscription boxes is converting commodity liner demand into value-added printed pouch revenue.
Industry Challenges
- Cleanroom certification bottlenecks:Medical-grade Mylar production requires ISO 14644 Class 7 environments, limiting qualified converter capacity and extending qualification timelines for new entrants.
- Legacy equipment retrofit costs:Converting lines built for three-ply laminations require substantial capital expenditure to handle mono-material structures with different sealing profiles and web tensions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mylar Bags Market |
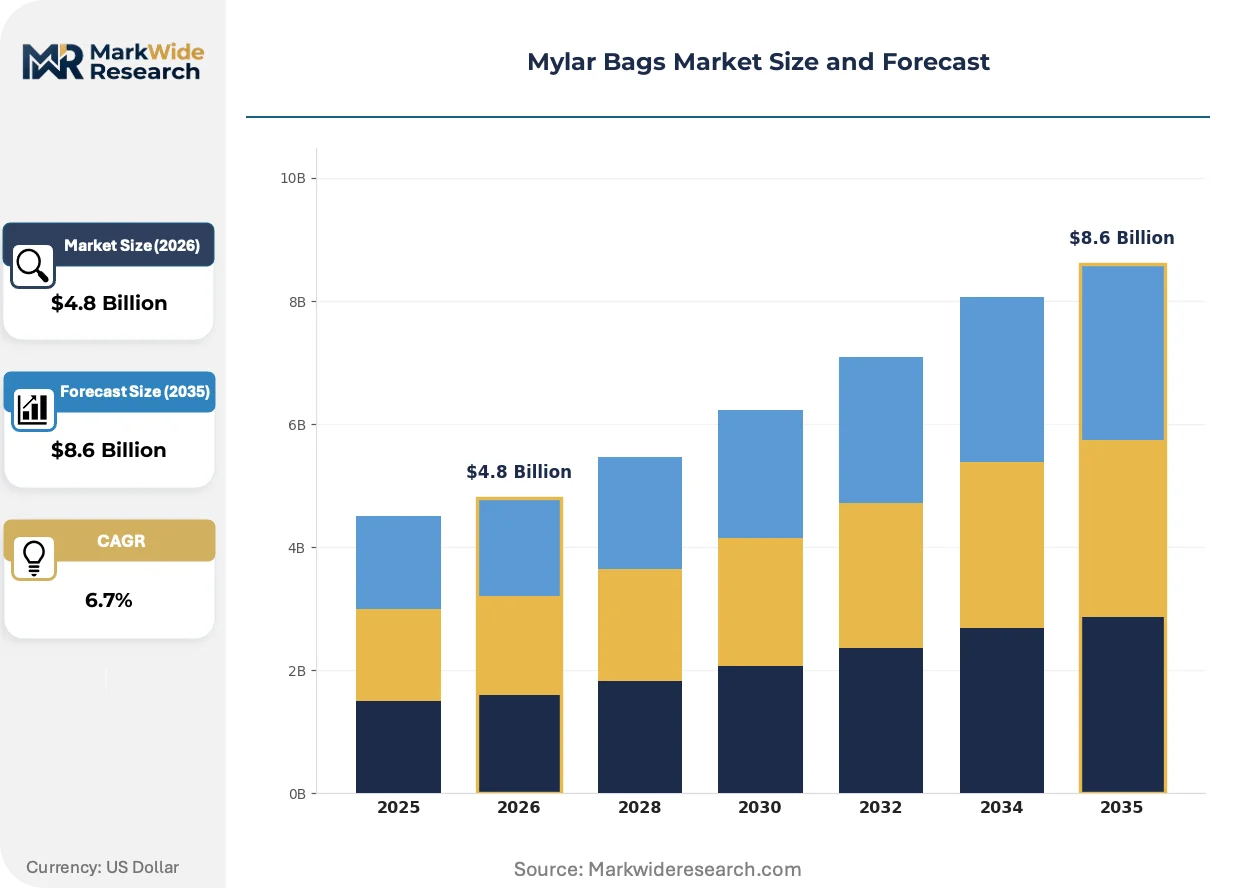
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Up Pouches, Flat Bags, Zip Lock Bags, Gusseted Bags End Use Industry: Food & Beverage, Pharmaceuticals, Electronics, Industrial Size: Small, Medium, Large, Extra Large Grade: Food Grade, Medical Grade, Industrial Grade, Other |
| Companies Covered | CarePac, ePac Flexible Packaging, Constantia Flexibles, Scientex, IMH Packaging, Printpack, Baishen Pack, YLTPACK, ShieldPro Flexible, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mylar Bags Market Evolving Landscape
Digital manufacturing networks and barrier coating chemistry are converging to compress lead times and eliminate fluorinated compounds from high-performance flexible packaging.
Silicon oxide vapor deposition is integrating into Mylar production lines as a transparent barrier alternative to aluminum foil. Specialty coffee roasters and dried fruit packagers are adopting these clear high-barrier films for retail visibility. The technology is integrating product presentation with shelf-life extension, collapsing the trade-off between barrier performance and package clarity that previously forced brand owners to choose.
EPA per- and polyfluoroalkyl substance enforcement is accelerating fluorinated treatment phaseouts across US converter operations. The agency's testing and disclosure mandates are compelling laminate suppliers to certify PFAS-free status for food-contact applications. California's Department of Toxic Substances Control is extending these requirements to imported flexible packaging, pressuring Asian contract manufacturers to reformulate or lose access.
Direct-to-consumer subscription models are compressing order cycles from annual blanket contracts to weekly replenishment schedules. Small-batch food brands are bypassing traditional distributor networks to source digitally printed pouches with two-week turnaround. This pattern concentrates in North American urban food clusters where micro-roasters and specialty processors lack warehouse space for bulk packaging inventory.
Mylar Bags Market Segmentation
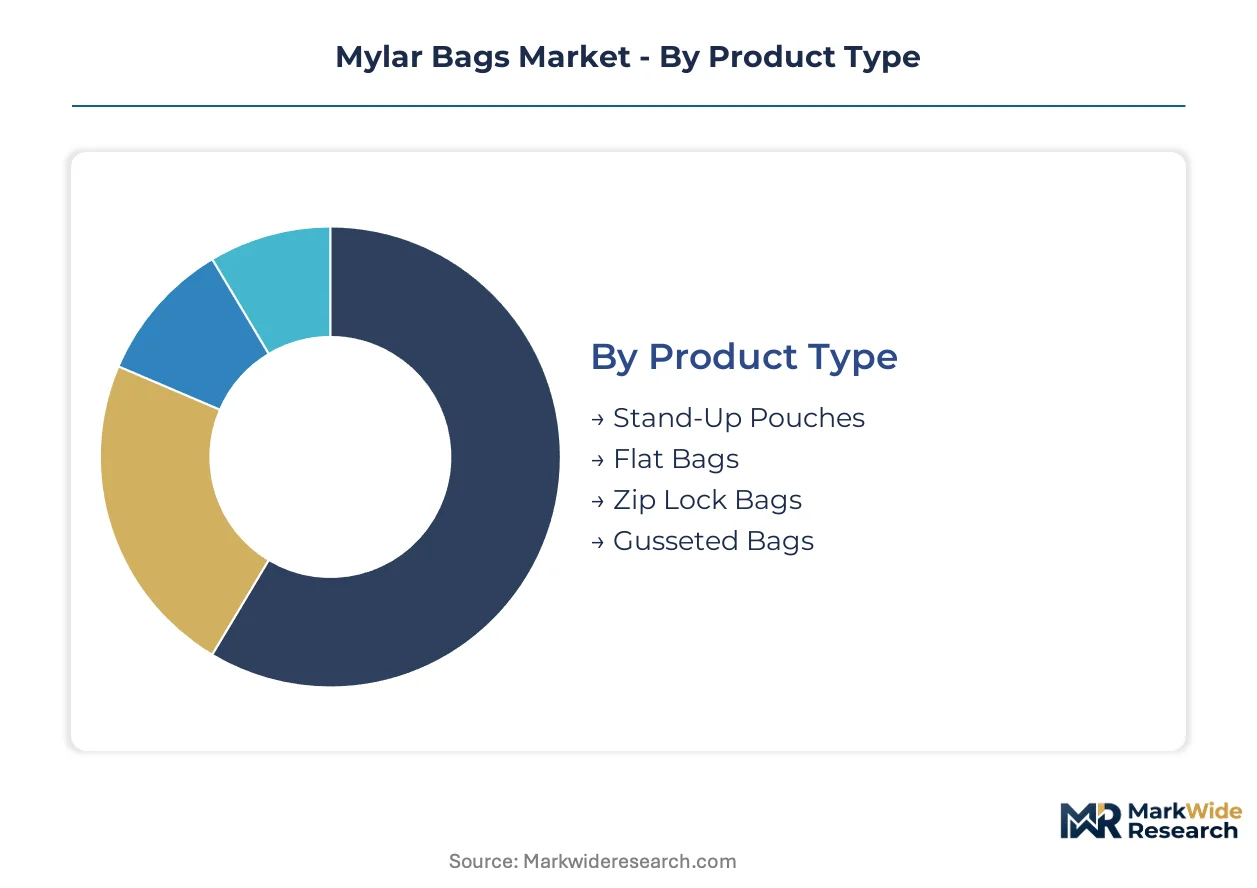
Segmentation in Mylar bags reveals divergent performance requirements across barrier specifications, filling equipment, and regulatory exposure. Understanding these splits enables converters to align laminate engineering with specific compliance and shelf-life demands.
Product Type:
Volume concentration favors formats compatible with high-speed vertical form-fill-seal lines, while premium positioning attaches to resealable and display-ready constructions.
- Stand-Up Pouches:These formats incorporate bottom gusset structures enabling self-supporting shelf presentation, typically specified at 4.5-6.0 mils total thickness with oxygen transmission rates below 0.01 cc/sq in/day. Coffee roasters and dried fruit packagers in California and Texas are driving specification tightening as direct-to-consumer subscription volumes expand.
- Zip Lock Bags:Integrated interlocking closure systems transform single-use liners into multi-access storage solutions, adding 0.3-0.5 mils to base film gauges. Specialty pet food brands and emergency preparedness suppliers in Colorado and Utah are specifying these for repeat-access protein storage without oxygen scavenger replenishment.
- Flat Bags:Two-seam constructions minimize material usage for vacuum-sealed applications where rigidity is unnecessary.
- Gusseted Bags:Side-fold geometries expand cubic capacity for bulk dry goods and industrial chemical handling.
Mature deployment sits with Flat Bags in commodity liner applications. Newer deployment is concentrated in Stand-Up Pouches as brand owners prioritize retail differentiation.
End Use Industry:
Application-driven segmentation separates consumer-facing compliance burdens from industrial performance specifications.
- Food & Beverage:Direct contact layers require FDA 21 CFR 177.1630 certification for polyester resins, with additional state-level scrutiny under California's SB 54 extended producer responsibility framework. Snack food manufacturers and specialty coffee processors are demanding PFAS-free barrier alternatives as EPA enforcement accelerates.
- Pharmaceuticals:Blister and sachet applications require moisture vapor transmission rates below 0.1 g/sq in/day, driving qualification of thermoformable Mylar alternatives to cold-form aluminum foil. ISO 14644 Class 7 cleanroom production constraints limit qualified converter capacity.
- Electronics:Vacuum-sealed moisture barrier protection for semiconductors and PCBs during cross-border shipping.
- Industrial:Chemical resistance and puncture tolerance for agricultural inputs and bulk ingredients.
Food & Beverage commands the broadest converter participation. Pharmaceuticals maintains the steepest expansion trajectory as aluminum supply constraints deepen.
Size:
Unit economics and handling automation create distinct specification bands across the dimensional range.
- Small:Single-serve and sample formats under 4 oz capacity dominate pharmaceutical unit-dose and cosmetic sachet applications. European contract manufacturers are migrating these specifications to mono-material recyclable platforms ahead of EU Packaging and Packaging Waste Regulation deadlines.
- Medium:8-16 oz capacities balance retail shelf presence with distribution efficiency for specialty food brands.
- Large:Bulk ingredient and foodservice formats requiring reinforced seals and extended shelf-life engineering.
- Extra Large:Industrial chemical and agricultural input containment with specialized venting and UN certification requirements.
Medium sizes anchor current production volume. Extra Large formats are gaining share fastest as industrial buyers consolidate packaging specifications.
Grade:
Certification tiering determines allowable end-use applications and corresponding margin structures.
- Food Grade:Migration-tested laminates meeting FDA and state-level food contact requirements constitute the baseline specification. California's Department of Toxic Substances Control is extending PFAS disclosure mandates to imported flexible packaging, pressuring Asian contract manufacturers to reformulate or exit the state's supply chain.
- Medical Grade:ISO 10993 biocompatibility testing and cleanroom production protocols support sterile barrier applications. Aluminum supply constraints for cold-form foil are accelerating qualification of Mylar alternatives for drug-device combination products.
- Industrial Grade:Performance specifications prioritize puncture resistance and chemical compatibility over migration testing.
- Other:Emerging grades including compostable-certified and ocean-bound plastic content variants.
Food Grade maintains the deepest converter infrastructure. Medical Grade represents the fastest-climbing specification tier as pharmaceutical packaging alternatives multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of metallized PET film feedstock while the United States and Germany consume the highest per-capita volumes of finished barrier pouches. This production-consumption divide shapes trade flows, regulatory compliance burdens, and converter location strategies across major economies.
United States
California's SB 54 extended producer responsibility law is forcing flexible packaging converters to redesign multi-layer Mylar laminations for material recovery compliance. The EPA is accelerating PFAS enforcement timelines for food-contact applications. Los Angeles and Dallas-Fort Worth food processing clusters are driving demand for digitally printed stand-up pouches with rapid turnaround requirements.
China
Cross-border e-commerce fulfillment corridors are vacuum-sealing electronics with high-barrier Mylar liners, expanding unit demand for moisture-proof protective packaging. The Ministry of Ecology and Environment is tightening emissions standards for metallized film vapor deposition processes. Shenzhen and Dongguan converter networks are consolidating around integrated PET film extrusion and lamination capabilities.
Germany
REACH fluorinated substance restrictions are redirecting converter R&D toward PFAS-free high-barrier coatings, creating first-mover advantages for compliant suppliers. The EU Packaging and Packaging Waste Regulation is mandating recyclability-by-design criteria that challenge multi-layer Mylar constructions. Bavarian pharmaceutical packaging specialists are qualifying thermoformable Mylar alternatives to cold-form aluminum foil.
India
Specialty coffee roasters and dried fruit packagers are migrating to barrier pouches as direct-to-consumer subscription channels expand. The Food Safety and Standards Authority of India is tightening migration testing protocols for imported flexible packaging materials. Maharashtra and Karnataka food processing hubs are attracting digital printing investments from regional flexible packaging converters.
Japan
Semiconductor and electronics manufacturers are specifying vacuum-sealed moisture barrier protection for cross-border component shipments. The Ministry of Economy, Trade and Industry is promoting mono-material recyclable packaging platforms through supply chain decarbonization incentives. Osaka-Kobe industrial corridors are hosting qualification programs for silicon oxide vapor deposition barrier films.
Mylar Bags Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the Mylar bags market. Integrated film extruders and metallizers control upstream feedstock economics while specialized converters focus on digital printing and rapid-turnaround customization. Three archetypes dominate: vertically integrated material suppliers, distributed digital manufacturing networks, and cleanroom-certified pharmaceutical specialists. Capacity expansion and strategic technology licensing represent the dominant competitive moves as players position for PFAS-free barrier transitions.
Among North American distributed manufacturing specialists, ePac Flexible Packaging exemplifies the networked digital press model anchored near regional food clusters. CarePac occupies a position within the short-run custom branding tier serving artisan food subscription boxes. Constantia Flexibles represents the pharmaceutical barrier film archetype through European cleanroom-certified production networks. These three anchors illustrate how geographic proximity, regulatory compliance depth, and end-use specialization segment competitive positioning across the value chain.
| Leading Market Players |
|---|
| CarePac |
| ePac Flexible Packaging |
| Constantia Flexibles |
| Scientex |
| IMH Packaging |
| Printpack |
| Baishen Pack |
| YLTPACK |
| ShieldPro Flexible |
| Others |
Value Network & Pricing Analysis
California's SB 54 extended producer responsibility mandates are forcing brand owners to absorb redesign costs for recyclable mono-material laminations, compelling converters to restructure procurement around qualified film suppliers and pass compliance premiums through contract tiers.
Pricing Analysis
Margin tightening in medical-grade specifications reflects ISO 14644 Class 7 cleanroom capacity scarcity and aluminum foil substitution R&D overhead. Three-tier pricing structure across premium, standard, and economy levels separates FDA-certified food contact from industrial-grade commodity liners. Cost-down pressure on standard grades accelerates because Asian contract manufacturers face PFAS disclosure mandates for California-bound shipments. Artisan food subscription brands show least price sensitivity for two-week turnaround digital printing; bulk industrial chemical buyers negotiate hardest on per-unit liner costs.
Supply Chain Analysis
Single-source vulnerability sits with Chinese metallized PET film extrusion and Russian primary aluminum smelting feedstock. Raw material dependencies encompass biaxially oriented polyester resin, vapor-deposited aluminum coatings, and silicon oxide barrier precursors. Tariff exposure on metallized film imports from China threatens laminate cost stability for North American converters. Distribution runs through regional flexible packaging distributors serving food processing clusters, with direct-to-brand digital manufacturing bypassing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cleanroom-certified production capacity scarcity props pricing power for medical-grade Mylar suppliers, creating durable margin pools as pharmaceutical blister displacement accelerates.
For Market Incumbents: Anticipate PFAS-free barrier coating qualification timelines by securing silicon oxide vapor deposition partnerships ahead of EPA enforcement deadlines. Defend position by adding mono-material recyclable capacity in Texas and California food processing corridors, locking in SB 54-compliant supply relationships before Asian competitors reformulate. For New Entrants and Emerging Players: Enter via short-run digital printing for specialty coffee and dried fruit subscription channels, where two-week turnaround requirements exclude legacy converters. Target medium-format stand-up pouches for North American urban food clusters lacking warehouse space for bulk packaging inventory. Lead with rapid-turnaround customization as the primary go-to-market angle. For Investors and Strategic Acquirers: The window for entry favors cleanroom-certified pharmaceutical specialists with thermoformable Mylar qualifications. Long-term viability hinges on aluminum supply constraint duration and cold-form foil displacement velocity. Watch FDA PFAS enforcement acceleration as the decisive inflection signal for first-mover advantage in fluorinated-free barrier films.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Platform Development | Qualifies laminates for EU Packaging and Packaging Waste Regulation recycling streams, unlocking premium positioning. |
| Silicon Oxide Vapor Deposition Integration | Replaces aluminum foil with transparent barrier films for specialty coffee roasters demanding retail visibility. |
| Cleanroom Capacity Expansion | Adds ISO 14644 Class 7 production lines to capture pharmaceutical blister displacement opportunities. |
| Digital Manufacturing Network Deployment | Positions regional presses near Los Angeles and Dallas-Fort Worth food clusters for rapid-turnaround subscription packaging. |
| PFAS-Free Coating Qualification | Secures California Department of Toxic Substances Control compliance ahead of imported packaging disclosure mandates. |
Research Methodology
Independent corroboration across converter operations directors, food brand procurement leads, and pharmaceutical packaging engineers underwrites the qualitative findings. Primary interviews with flexible packaging R&D heads, metallized film plant managers, and subscription box fulfillment operators combined with secondary validation from FDA 21 CFR filings, EPA PFAS enforcement dockets, and EU Packaging and Packaging Waste Regulation drafts. Bottom-up shipment data from regional converter networks triangulates against top-down material consumption estimates from PET resin trade associations.
Comparable-period anchoring to historical laminate pricing and volume trajectories structured the projection horizon. Segmentation dimensions modeled span product type, grade certification tier, end-use industry, and geographic regulatory cluster. CAGRs derived from fitted growth curves applied to segment-level baselines, with cross-border e-commerce fulfillment volumes and pharmaceutical aluminum substitution rates as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt EPA PFAS enforcement acceleration or Chinese metallized film export restriction scenarios. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Pasted Valve Bags Market
Bags and Containers
Jumbo Bags Market
Bags and Containers
Middle East & Africa Paper Bags Market
Bags and Containers
Freezing Bags Market
Bags and Containers
Padding Bags Market
Bags and Containers
Household and Cleaning Container Market
Bags and Containers
FIBC Market
Bags and Containers
Vertical Form Fill Seal Baggers Market
Bags and Containers
Multiwall Bags Market
Bags and Containers
Baffle Bags Market
Bags and Containers
Bulk Tote Dumpers Market
Bags and Containers
Commodity Liners Market
Bags and Containers
Global High Abuse Shrink Bags Market
Bags and Containers
Flat Bottom Bags Market
Bags and Containers
Loop Handle Bags Market
Bags and Containers
Conductive Bags Market