
 Bulk Bags Market | 2026-2036
Bulk Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Bulk Bags Market Analysis
Polypropylene woven fabric automation is tilting cost structures toward high-volume continuous production. Greif sustains North American leadership through captive resin sourcing and vertical mill networks. Mondi Group differentiates via integrated kraft-paper and woven PP hybrid solutions for chemical clients. Conitex Sonoco anchors Latin American supply through regional weaving and conversion facilities.
Bulk bags are large-capacity flexible containers typically constructed from woven polypropylene fabric with load ratings from 500 kg to 2,000 kg, designed for single-trip or multi-trip handling of dry flowable materials via forklift loops or stevedore straps. Their primary purpose is to replace smaller sacks and rigid intermediate bulk containers in granular and powder logistics. Flexible Intermediate Bulk Containers dominate volume owing to established ISO 21898 testing protocols and universal forklift compatibility across agriculture and chemicals. Food-grade polyethylene liners within FIBC systems command premium positioning as end users enforce HACCP-aligned contamination barriers. Rigid containers retain defensive share in construction aggregates where puncture resistance overrides freight efficiency.
REACH in Europe mandates full substance registration for chemical-contact packaging, while FDA Title 21 CFR 177.1520 governs olefin polymer suitability for food applications in the United States. BIS certification under IS 16008 in India enforces safe working load and UV-stability testing for domestic and export-bound FIBCs. Stakeholders must weigh multi-jurisdictional compliance costs against regional manufacturing localization to preserve margin structures.
Market Dynamics
Polypropylene resin supply concentration and REACH substance registration requirements are compressing margins for non-integrated converters while favoring producers with captive polymer streams.
Growth Catalysts
- REACH substance registration:European chemical processors now require full traceability documentation for FIBCs handling hazardous powders, pulling demand toward certified converters with testing infrastructure.
- Agricultural export formalization:India's BIS IS 16008 certification mandate for grain-handling FIBCs is standardizing quality tiers and displacing unorganized weaving capacity.
- Food-grade liner integration:HACCP-aligned polyethylene barrier systems are penetrating dairy and spice supply chains where contamination risk previously limited FIBC adoption.
Market Restraints
- Propylene feedstock volatility:Naphtha-cracking economics and refinery output shifts transmit directly to woven fabric input costs, squeezing converter margins.
- Weaving concentration in South Asia:Circular loom capacity clusters in Gujarat and Tamil Nadu create geographic single-point vulnerability for global supply.
- Rigid IBC substitution in aggregates:Construction material handlers prefer steel or plastic caged tanks where puncture resistance outweighs freight cube efficiency.
Strategic Opportunities
- Latin American chemical logistics:Brazilian petrochemical expansion and ANVISA packaging rules are opening demand for locally converted FIBCs with Portuguese documentation.
- RFID-embedded traceability:Converging woven fabric manufacturing with IoT sensor integration enables real-time location and condition monitoring for pharmaceutical shipments.
- EU Green Deal packaging targets:Recycled-content mandates and extended producer responsibility schemes favor producers with post-industrial polypropylene collection systems.
Industry Challenges
- Multi-jurisdictional certification lag:Simultaneous FDA, REACH, and BIS testing protocols extend product qualification timelines by 8-14 months.
- Skilled loom technician scarcity:Circular weaving expertise is aging out in traditional manufacturing clusters without structured apprenticeship pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bulk Bags Market |
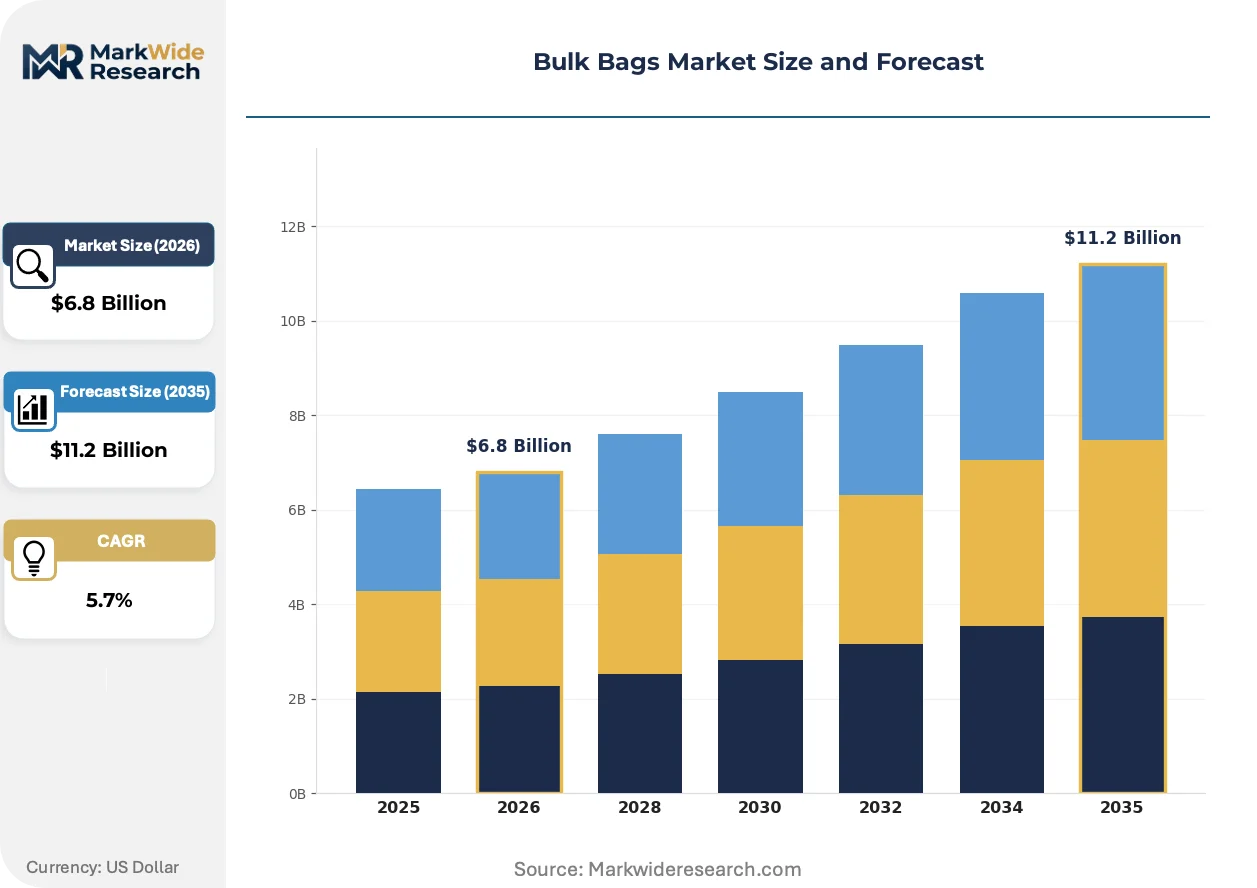
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Intermediate Bulk Containers, Rigid Containers, Pillow Bags, FIBC Liners End User: Agriculture, Chemicals, Food & Beverage, Construction Material: Polypropylene, polyethylene, Cotton, Jute Distribution Channel: Online, Direct Sales, Retail Stores, Distributors |
| Companies Covered | Berry Global, Greif, Conitex Sonoco, Mondi Group, LC Packaging, BAG Corp, Global-Pak, International Bulk Containers, Bulk Lift International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bulk Bags Market Emerging Trajectories
Automation in fabric finishing and liner insertion is compressing unit economics while regulatory digitization is redefining what constitutes compliant packaging documentation.
Anti-static and conductive FIBC fabric technology is migrating from niche chemical handling toward mainstream pharmaceutical and food applications. European API manufacturers now specify Type C or D grounding systems for solvent-laden powders. This shift is compressing the premium gap between standard and hazard-rated containers.
REACH Article 33 extended supply chain communication obligations now require downstream packaging converters to document SVHC content above 0.1% w/w. German chemical distributors are rejecting FIBC lots without SCIP database registration. Specialty chemical segments in the Rhine-Ruhr corridor are consolidating supplier lists to those with full substance dossiers.
Consolidated procurement desks at multinational agribusinesses are unbundling liner supply from bag fabrication. Cargill and ADM-style operators now source polyethylene inserts separately through polymer traders, forcing FIBC converters to compete on sewing and testing alone. This pattern is most visible in North American grain export corridors where volume concentration enables direct liner import.
Bulk Bags Market Segmentation
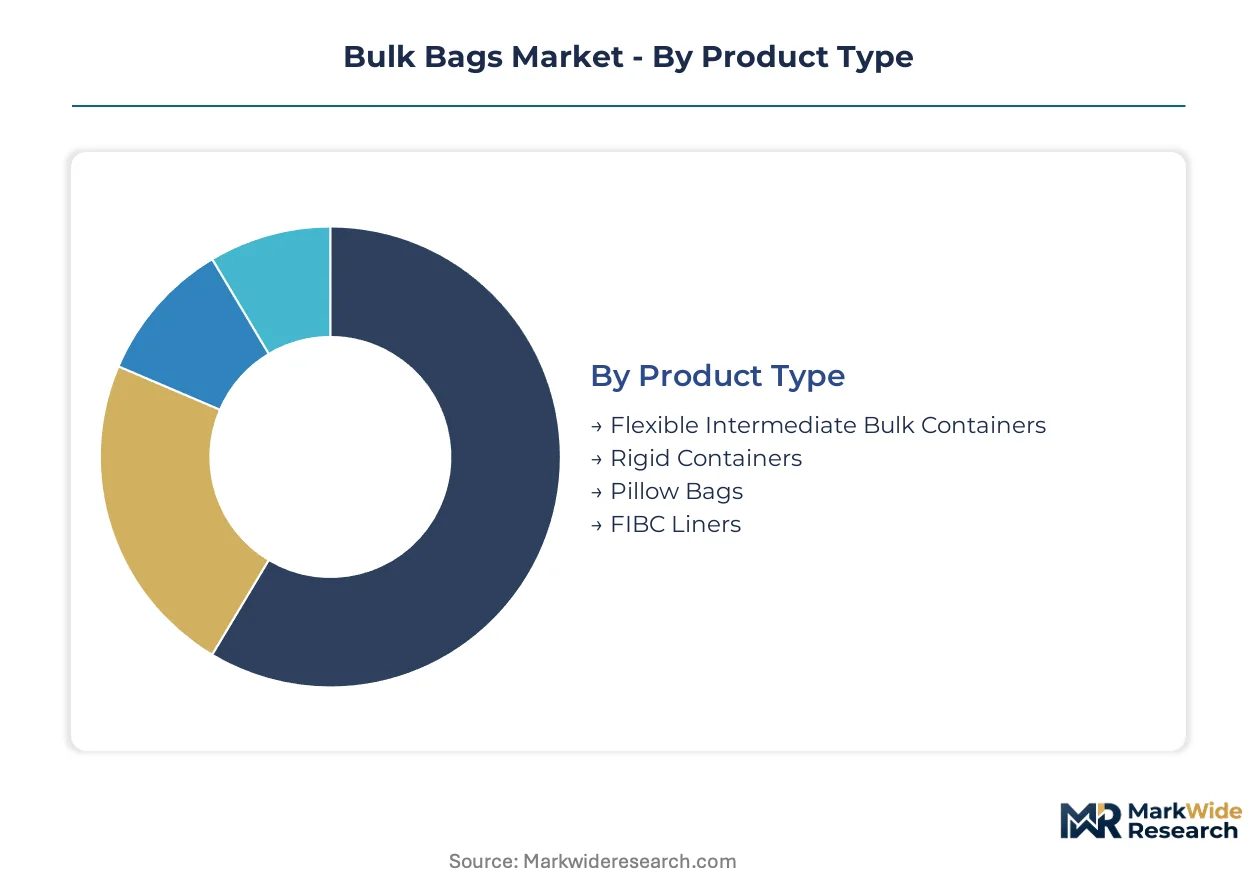
Segmentation in the Bulk Bags Market reveals how material specifications, regulatory compliance tiers, and handling protocols split demand across incompatible use cases. Understanding these divides explains why converters specialize rather than generalize.
Product Type:
Mature formats with established ISO testing protocols dominate volume, while emerging variants capture premium niches through specialized safety ratings.
- Flexible Intermediate Bulk Containers:Woven polypropylene containers rated 500–2,000 kg with forklift loops and stevedore straps, governed by ISO 21898 testing protocols. Chemical processors in Germany's Rhine-Ruhr corridor now mandate Type C or D grounding systems for solvent-laden powders, compressing the premium gap between standard and hazard-rated containers.
- FIBC Liners:Food-grade polyethylene barrier systems inserted within woven shells to satisfy HACCP-aligned contamination protocols. Dairy and spice supply chains in India are standardizing liner integration as BIS IS 16008 certification tightens traceability requirements for agricultural exports.
- Rigid Containers:Steel or plastic caged tanks preferred where puncture resistance outweighs freight cube efficiency. Construction material handlers specify these for aggregates handling despite higher empty-return costs.
- Pillow Bags:Flat-bottomed flexible containers for low-density, high-volume materials. Limited adoption outside specialty chemical and mineral applications where stacking stability is secondary to fill volume.
Flexible Intermediate Bulk Containers handle the majority of throughput; FIBC Liners are expanding most quickly as food-grade certification becomes mandatory across export corridors.
End User:
Application intensity varies by sector, with chemical and agricultural buyers driving specification complexity while construction favors durability over compliance documentation.
- Chemicals:European processors require full REACH substance registration for hazardous powder handling, pulling demand toward certified converters with SCIP database capabilities. German distributors now reject lots without documented SVHC content below 0.1% w/w thresholds.
- Agriculture:India's grain export formalization under BIS IS 16008 is displacing unorganized weaving capacity in Gujarat and Tamil Nadu. Cargill-style procurement desks are unbundling liner supply from bag fabrication, forcing converters to compete on sewing and testing alone.
- Food & Beverage:HACCP-aligned barrier systems are penetrating dairy and spice logistics where contamination risk previously limited FIBC adoption. FDA Title 21 CFR 177.1520 governs olefin polymer suitability for US-bound shipments.
- Construction:Aggregate handlers prefer rigid containers or heavy-duty woven formats where puncture resistance overrides freight efficiency. This segment resists liner integration due to cost sensitivity and single-trip disposal patterns.
Chemicals generates the most stringent specification requirements; Agriculture is climbing the fastest as Indian export formalization accelerates.
Material:
Cost tiers separate commodity feedstocks from specialty fibers, with synthetic dominance challenged only in niche sustainability positioning.
- Polypropylene:Dominant woven fabric substrate derived from naphtha-cracking economics. Propylene feedstock volatility transmits directly to converter margins, favoring producers with captive resin streams or backward integration into polymer supply.
- Polyethylene:Primary liner material for food-grade and chemical barrier applications. FDA-regulated grades command premium positioning in dairy and pharmaceutical supply chains.
- Cotton:Natural fiber alternative for specialty agricultural and food applications requiring breathable storage. Limited volume due to moisture absorption and UV degradation relative to synthetics.
- Jute:Biodegradable option for single-trip agricultural exports from South Asia. BIS certification mandates are gradually displacing traditional jute in favor of standardized woven PP.
Polypropylene accounts for the dominant share of woven fabric consumption; Polyethylene in liner applications is gaining share fastest through food-grade certification expansion.
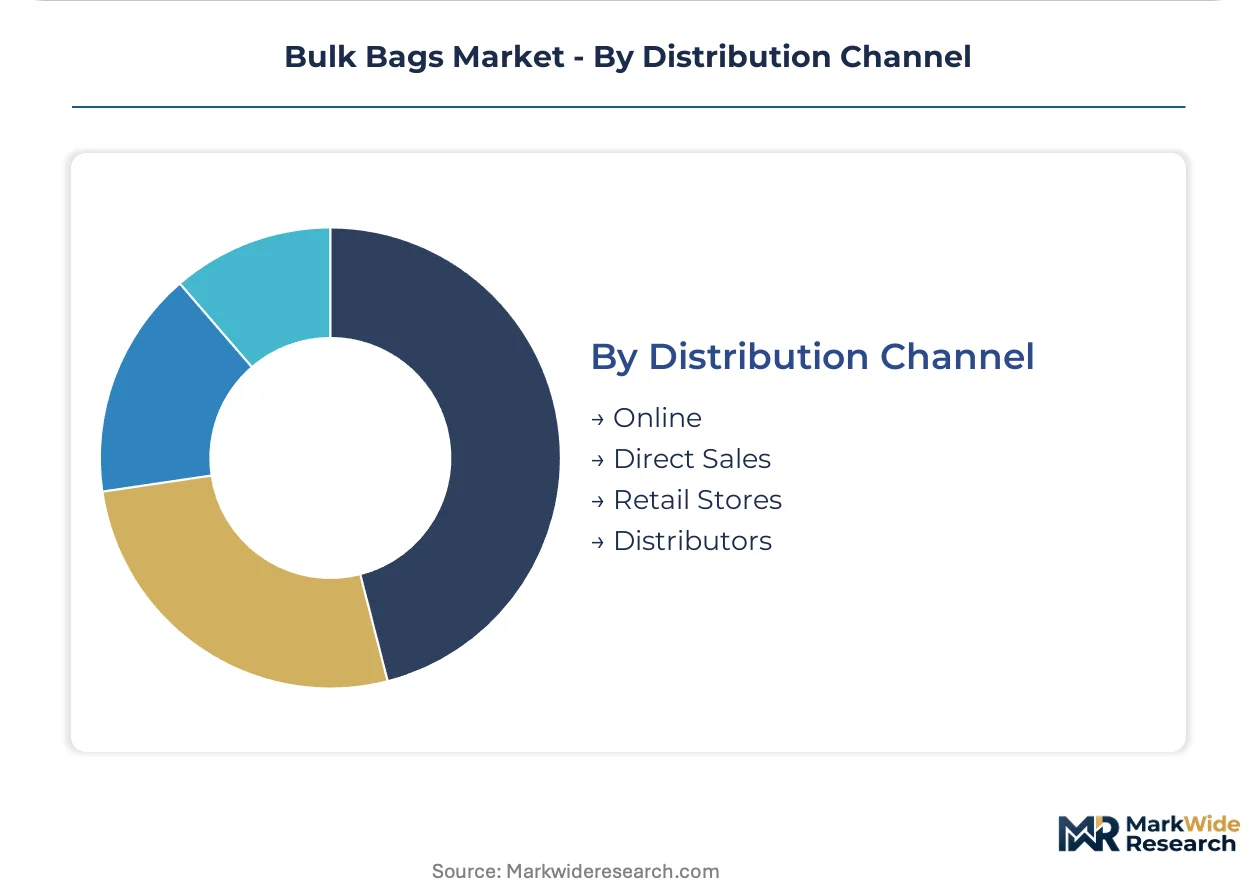
Distribution Channel:
Channel selection reflects order scale, specification complexity, and the buyer's internal technical capability to self-specify.
- Direct Sales:Preferred by multinational agribusinesses and chemical processors requiring customized certification packages. Consolidated procurement desks negotiate sewing and testing services separately from liner supply.
- Distributors:Channel for mid-volume buyers needing technical support with REACH, FDA, or BIS compliance documentation. German chemical distributors now filter suppliers by SCIP registration status.
- Online:Emerging channel for standardized FIBC formats with published load ratings and pre-certified testing protocols. Limited to buyers with internal specification expertise.
- Retail Stores:Minimal relevance for industrial bulk packaging; confined to small-scale agricultural and construction users with immediate, low-volume needs.
Direct Sales captures the largest contract value; Distributors are expanding most quickly as mid-market chemical processors seek compliance support.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Multinational chemical processors and agribusiness procurement desks concentrate demand in jurisdictions with harmonized certification infrastructure, pulling capacity toward Germany, India, Brazil, and the United States where regulatory clarity reduces supplier qualification friction.
Germany
Rhine-Ruhr chemical distributors now mandate SCIP database registration for all FIBC lots handling solvent-laden powders. REACH Article 33 extended supply chain communication obligations force converters to document SVHC content below 0.1% w/w thresholds. Specialty chemical clusters around Leverkusen and Ludwigshafen are consolidating supplier lists to certified producers with full substance dossiers.
India
BIS IS 16008 certification mandates for grain-handling FIBCs are displacing unorganized weaving capacity as agricultural export formalization accelerates. The Food Safety and Standards Authority of India aligns with DGFT traceability requirements for spice and dairy logistics. Circular loom clusters in Gujarat and Tamil Nadu are expanding food-grade liner insertion capacity to capture premium export contracts.
Brazil
Petrochemical expansion in Camacari and Triunfo is reducing propylene feedstock import dependence for woven fabric producers. ANVISA packaging rules for pharmaceutical and food-contact applications require Portuguese-language documentation that favors locally converted FIBCs. São Paulo-state chemical distributors are building regional testing infrastructure to avoid cross-border certification delays.
United States
FDA Title 21 CFR 177.1520 governs olefin polymer suitability for food-grade FIBC applications across dairy and spice supply chains. Consolidated procurement desks at agribusinesses in the Midwest grain belt are unbundling liner supply from bag fabrication. Houston-area chemical processors are demanding Type C and D anti-static grounding systems for hazardous powder handling.
China
GB standards for woven polypropylene containers are converging with ISO 21898 testing protocols to facilitate export clearance at Ningbo and Shanghai ports. The Ministry of Ecology and Environment is tightening post-industrial polypropylene collection requirements under dual carbon goals. Yangtze River Delta fabricators are automating liner insertion to offset wage pressure in Zhejiang and Jiangsu provinces.
Bulk Bags Market Vendor Landscape
Channel-controlling players compete with product-specialist players across three distinct tiers. Integrated resin-to-bag producers with captive polymer streams command margin advantage during propylene volatility cycles. Regional weaving specialists defend position through certification depth rather than scale. Technology-forward converters embed RFID traceability and conductive fabric systems to capture pharmaceutical and chemical premium segments. Dominant competitive moves include backward integration into resin supply and geographic expansion through regional mill networks.
Among North American packaging conglomerates, Berry Global and Greif exemplify the integrated archetype with captive sourcing infrastructure. Mondi Group represents the European hybrid model combining kraft-paper and woven PP capabilities. Conitex Sonoco anchors Latin American supply through regional conversion presence. LC Packaging and BAG Corp occupy mid-market positions emphasizing certification agility over vertical integration.
| Leading Market Players |
|---|
| Berry Global |
| Greif |
| Conitex Sonoco |
| Mondi Group |
| LC Packaging |
| BAG Corp |
| Global-Pak |
| International Bulk Containers |
| Bulk Lift International |
| Others |
Supply Flow & Price Mechanics
Propylene feedstock volatility from naphtha-cracking economics determines both the spread between premium and economy-tier FIBC pricing and the geographic clustering of weaving capacity around South Asian petrochemical corridors. This input-cost instability compresses margins for non-integrated converters while rewarding producers with captive resin streams and regional mill networks.
Pricing Analysis
Cost-plus contracts indexed to propylene monomer spot benchmarks dominate the woven fabric segment, with three-tier pricing structure across premium, standard, and economy levels separating food-grade certified FIBCs with HACCP-aligned liners from basic agricultural formats. Price differentiation hinges on certification depth—REACH substance dossiers and FDA Title 21 CFR 177.1520 compliance command premiums—and volume scale, where consolidated procurement desks at multinational agribusinesses extract sewing-only rates. Cost compression in the standard tier is intensifying because Cargill-style operators now source polyethylene liners separately through polymer traders. Construction material handlers exhibit the highest price sensitivity, accepting single-trip disposal economics, while European chemical processors in the Rhine-Ruhr corridor show minimal elasticity for documented SVHC traceability.
Supply Chain Analysis
Tariff exposure between India and key export destinations for grain-handling FIBCs dominates supply chain risk planning for converters serving agricultural formalization demand. Geographic supply concentration centers on India, China, and Turkey, where circular loom clusters in Gujarat, Zhejiang, and Gaziantep feed global demand. Raw material dependencies rest on polypropylene resin from naphtha crackers, polyethylene for food-grade liners, and conductive masterbatch for Type C/D anti-static fabrics. Single-source vulnerability looms where South Asian weaving capacity faces monsoon logistics disruptions. Distribution runs through direct sales channels for multinational chemical processors requiring customized certification packages, with distributors capturing mid-volume buyers seeking REACH, FDA, or BIS compliance support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Bulk Bags Market sits in a cyclical recovery phase as propylene feedstock economics stabilize and agricultural export formalization in India accelerates replacement demand for certified FIBCs.
For Market Incumbents: Insulate margin structures by deepening backward integration into captive resin supply or acquiring regional weaving capacity in Brazil to offset South Asian geographic concentration risk. Invest in SCIP database registration infrastructure to defend position against REACH Article 33 compliance rejections from German chemical distributors. Certification depth, not scale, is the sustainable lever. For New Entrants and Emerging Players: Pursue white-space opportunities in Latin American chemical logistics, where Brazilian petrochemical expansion and ANVISA packaging rules create demand for locally converted FIBCs with Portuguese documentation. Target São Paulo-state pharmaceutical distributors seeking to avoid cross-border certification delays. A go-to-market angle anchored in RFID-embedded traceability for solvent-laden powders captures premium pricing. For Investors and Strategic Acquirers: Regional weaving specialists with multi-jurisdictional certification agility represent the most defensible acquisition archetype in a market where simultaneous FDA, REACH, and BIS testing protocols extend qualification timelines. Long-term viability favors converters with post-industrial polypropylene collection systems aligned to EU Green Deal packaging targets. Watch for inflection in German chemical distributor rejection rates for non-SCIP-registered lots as the signal of compliance-driven consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Supply | Captive polypropylene sourcing from naphtha crackers insulates margin compression during feedstock volatility cycles. |
| Multi-Jurisdictional Certification Investment | Simultaneous FDA, REACH, and BIS testing infrastructure captures premium chemical and agricultural export contracts. |
| RFID-Embedded Traceability Deployment | IoT sensor integration in woven fabric enables real-time condition monitoring for pharmaceutical solvent-laden powders. |
| Regional Mill Network Expansion | Local conversion presence in Brazil satisfies ANVISA Portuguese-documentation requirements for petrochemical logistics. |
| Post-Industrial Collection System Buildout | Recycled-content polypropylene pipelines align with EU Green Deal extended producer responsibility mandates. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with plant managers at woven fabric converters, procurement leads at downstream chemical processors, distribution channel partners, and technical R&D directors; and secondary validation against customs/trade data, BIS certification registries, SEC filings from packaging conglomerates, and ECHA SCIP database disclosures. Bottom-up demand modeling across end-use segments triangulated with top-down capacity assessments from regional loom cluster surveys.
Forecast inputs considered propylene feedstock trajectory, agricultural export formalization velocity, and regulatory digitization timelines across the analysis window. Segmentation dimensions modeled include product type tier, material grade, certification level, end-use industry intensity, and regional production hub. CAGRs were derived from slope analysis of normalized demand curves against capacity expansion announcements. Industry-specific forecast inputs incorporated REACH substance registration lag effects and BIS IS 16008 displacement rates for unorganized weaving capacity.
Macroeconomic conditions sit as an overlay; deviation in propylene pricing spreads, agricultural commodity export volumes, or EU packaging regulation enforcement intensity would shift the trajectory. Forecasts reflect assumptions on certification harmonization timelines and loom automation adoption curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Americas Plastic Bags and Sacks Market
Bags and Containers
Inner Bulk Liners Market
Bags and Containers
Octabin Market
Bags and Containers
Insulated Delivery Bag Market
Bags and Containers
Anti-Static Collapsible Tote Bins Market
Bags and Containers
Wicketed Bags Market
Bags and Containers
Global High Abuse Shrink Bags Market
Bags and Containers
Global PP Jumbo Bags Market
Bags and Containers
Cross Bottom Bags Market
Bags and Containers
Nonwoven Containers Market
Bags and Containers
PE Jumbo Bags Market
Bags and Containers
4-Loop FIBC Market
Bags and Containers
Inflatable Bags Packaging Market
Bags and Containers
Europe Bulk Bags Market
Bags and Containers
Global Bubble Lined Courier Bag Market
Bags and Containers
Zipper Bags Market