
 Lawn and Leaf Bags Market | 2026-2036
Lawn and Leaf Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Lawn and Leaf Bags Market Foresight
Multi-count modular bundling is repositioning how households and landscapers select lawn and leaf bags, shifting unit economics toward volume-based value packs over single-item purchases. Mondi Group plc leverages its European pulp and paper infrastructure to anchor supply of kraft-based yard waste solutions across retail garden centers. Sigma Plastics Group competes through vertical integration into blown film extrusion, sustaining cost discipline in high-density polyethylene production for contractor-grade bags.
Lawn and leaf bags are flexible containment vessels engineered from polyethylene film, kraft paper, woven polypropylene, or compostable polymers such as PLA and PBAT, designed to collect, transport, and store organic yard debris for municipal composting or landfill disposal. Biodegradable and paper product types are capturing margin pools as municipalities restrict conventional plastic film from organic waste streams, while plastic variants retain volume leadership in landscaping and construction-adjacent debris removal. Large and extra large sizes dominate commercial procurement by municipalities and golf courses, whereas household demand clusters in medium formats sold through home improvement stores and supermarkets.
The US EPA and state environmental agencies shape product standards through yard waste diversion mandates and landfill tipping fee structures that incentivize compostable collection methods. The EU F-Gas Regulation and REACH framework indirectly pressure film suppliers to certify additive chemistries, while California's SB 1383 organic waste recycling requirements directly dictate bag material specifications for compliance. Stakeholders must monitor how fragmented municipal procurement standards evolve and whether biodegradable certification costs erode price competitiveness against incumbent polyethylene alternatives.
Market Dynamics
Municipal composting mandates across North America and Europe are forcing rapid material transitions from polyethylene to certified compostable films, compressing replacement cycles and rewiring procurement specifications for yard waste containment.
Growth Catalysts
- California SB 1383:This organic waste recycling mandate requires jurisdictions to provide compostable collection infrastructure, directly expanding addressable demand for biodegradable bag variants in the United States.
- Curbside program expansion:Municipalities in Ontario and British Columbia are scaling residential organics pickup, creating institutional procurement pipelines for high-volume kraft and biopolymer bag supply.
- Film lamination advances:Multi-layer extrusion techniques now bond moisture-resistant barriers to paper substrates, extending performance parity between compostable and conventional plastic options.
Market Restraints
- Resin price volatility:PBAT and PLA feedstock costs fluctuate with agricultural commodity markets, squeezing margin stability for biodegradable product lines against petroleum-based polyethylene.
- Certification bottleneck:BPI and TUV OK compost certifications require 90-180 day testing cycles, delaying product launches and freezing inventory commitments during approval windows.
- Collection infrastructure gaps:Many United States municipalities lack industrial composting facilities capable of processing certified bags, creating compliance friction where regulations outpace physical capacity.
Strategic Opportunities
- Contractor channel penetration:Landscaping services in Florida and Texas represent underdeveloped volume accounts, with crews currently reusing construction debris bags for organic material.
- Retail private label conversion:Home improvement chains are consolidating supplier bases around dual-certified paper-plastic hybrid lines, rewarding manufacturers with integrated extrusion and converting assets.
- EU Green Deal alignment:The EU Single-Use Plastics Directive's extended producer responsibility frameworks create premium positioning for kraft-based alternatives in German and French garden center networks.
Industry Challenges
- Composting facility compatibility:Bag manufacturers must maintain dual certification portfolios across ASTM D6400 and EN 13432 standards, multiplying testing expenditure and SKU complexity.
- Seasonal demand spikes:Autumn leaf collection concentrates 60-70 percent of annual volume into eight-week windows, straining extrusion and converting capacity while forcing inventory carry costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lawn and Leaf Bags Market |
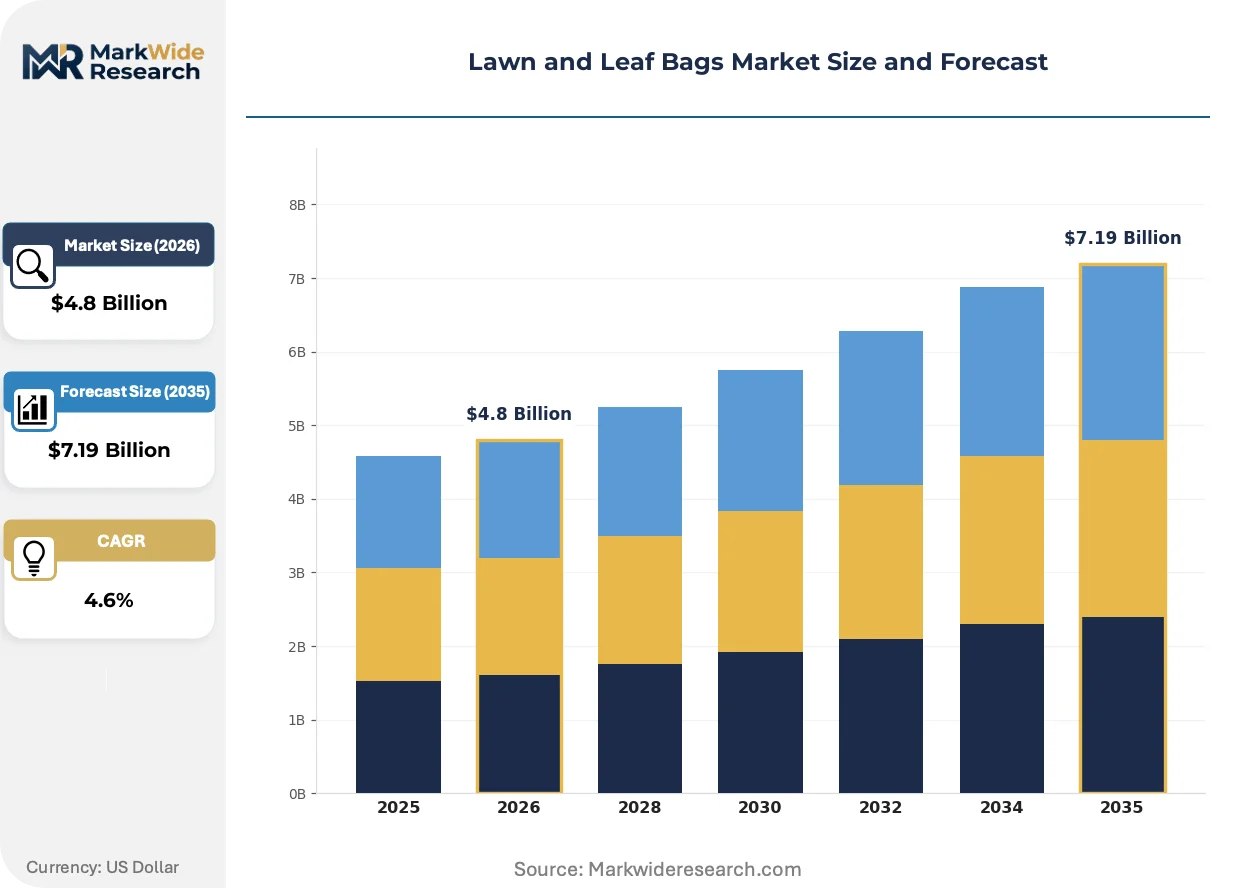
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Biodegradable, Paper, Cloth Size: Small, Medium, Large, Extra Large End User: Households, Landscapers, Municipalities, Golf Courses Distribution Channel: Online Retail, Home Improvement Stores, Garden Centers, Supermarkets |
| Companies Covered | Mondi Group plc, PEI Bag Co., Dano Group, Custom Faberkin, Inc., USA Poly Pack, Go-GreenGardening, Bundaberg Bag Company, Brisbane Bag Company, Sigma Plastics Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lawn and Leaf Bags Market Shifts & Advancements
Material science breakthroughs and regulatory sequencing are compressing the performance gap between conventional and sustainable yard waste containment, reshaping how municipalities specify procurement and how retailers merchandise seasonal categories.
PBAT-starch alloy formulations are unifying tear resistance and soil biodegradation timelines previously considered mutually exclusive. Municipal procurement officers in Washington and Oregon are specifying these alloys for fall collection programs. The technology is unifying formerly separate premium and standard product tiers into single certified SKUs.
REACH framework amendments targeting polymer additive disclosure are compelling film suppliers to reformulate colorants and slip agents. Compounders serving the European market are investing in non-phthalate plasticizer alternatives. Kraft paper suppliers with integrated pulping operations are capturing specification share as REACH compliance costs erode polyethylene cost advantages.
Homeowner associations and property management firms are consolidating seasonal purchases through cooperative buying platforms. Bulk procurement consortia in suburban Chicago and Atlanta markets are displacing individual household purchases at retail. Landscapers serving these associations are shifting toward 100-count contractor packs over single-item retail formats.
Lawn and Leaf Bags Market Segmentation
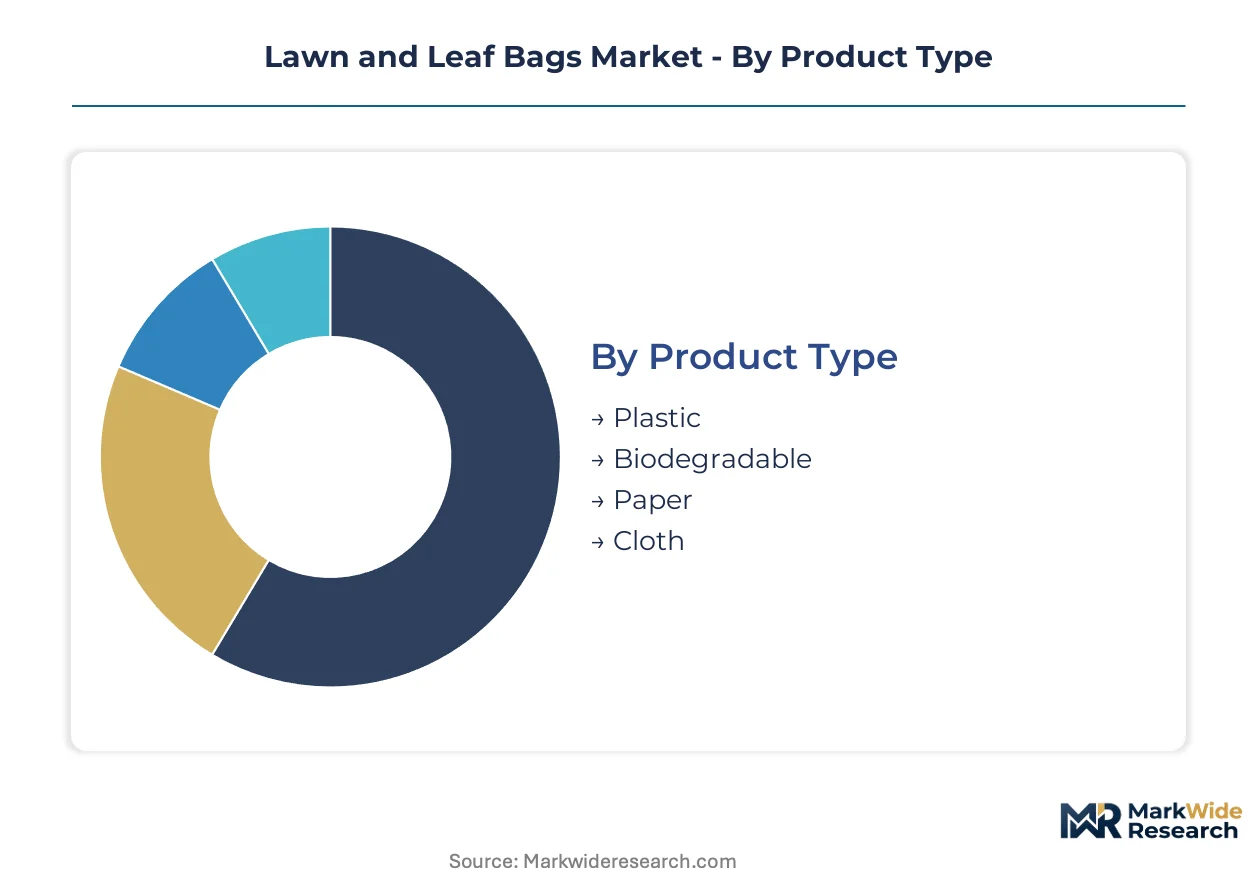
Material specifications, volume requirements, and regulatory compliance needs fragment demand across distinct buyer profiles in the lawn and leaf bags market. Procurement patterns diverge sharply between municipal composting programs and residential seasonal purchases, rewiring how manufacturers configure product portfolios and channel strategies.
Product Type:
Buyers differentiate primarily by disposal pathway compatibility and certification requirements rather than unit cost alone.
- Plastic:High-density polyethylene film dominates contractor-grade applications through moisture resistance and puncture strength. Landscapers in Florida and Texas specify these for construction-adjacent debris removal where composting certification is irrelevant. Plastic leads volumes today; biodegradable variants are gaining share fastest.
- Biodegradable:PBAT-starch alloys and PLA formulations carry BPI or TUV OK compost certifications required by California SB 1383 and Ontario curbside programs. Washington and Oregon municipalities specify these alloys for fall collection programs where industrial composting infrastructure exists. Feedstock volatility from agricultural commodity markets compresses margin stability against polyethylene alternatives.
- Paper:Kraft-based yard waste solutions leverage integrated pulping operations for REACH-compliant European supply. German and French garden center networks prioritize these under EU Single-Use Plastics Directive extended producer responsibility frameworks.
- Cloth:Woven polypropylene reusable containers target landscaping crews with repeated collection cycles. Suburban Chicago homeowner associations specify these for cooperative buying platforms displacing single-use retail formats.
Biodegradable alloys unify formerly separate premium and standard tiers; paper captures specification share as regulatory compliance costs erode plastic advantages.
Size:
Volume per collection event and storage constraints determine format selection across residential and institutional buyers.
- Small:Compact formats suit balcony composting and limited-storage urban households. Tokyo and Singapore high-rise residents specify these for municipal organics diversion programs with space-constrained collection infrastructure.
- Medium:Standard 30-gallon equivalents cluster in household demand through home improvement stores and supermarkets. Atlanta and Chicago suburban markets concentrate replacement cycles around autumn leaf collection windows.
- Large:45-50 gallon formats dominate commercial procurement by municipalities and golf courses with mechanized collection systems. British Columbia residential organics pickup programs specify these for high-volume kraft and biopolymer supply.
- Extra Large:Contractor-grade capacities serve landscaping crews handling estate-scale debris removal. Florida and Texas landscaping services currently reuse construction debris bags for organic material, representing underdeveloped volume accounts for purpose-designed alternatives.
Large and extra large formats concentrate institutional procurement; medium formats anchor retail velocity through seasonal replacement cycles.
End User:
Compliance mandates and procurement centralization separate institutional buyers from fragmented residential demand.
- Households:Individual purchasers respond to homeowner association landscaping standards and municipal composting education campaigns. Seasonal demand spikes concentrate 60-70 percent of annual volume into eight-week autumn windows.
- Landscapers:Crews require puncture-resistant containment for mixed debris including branches and soil. Cooperative buying platforms in suburban Atlanta and Chicago markets are displacing individual retail purchases with 100-count contractor packs.
- Municipalities:Jurisdictions specify certified compostable films under SB 1383 and Ontario organics mandates. Procurement officers in Washington and Oregon specify PBAT-starch alloys for fall collection programs.
- Golf Courses:Superintendents prioritize tear resistance for grass clippings and aeration debris with consistent weekly volume. Large-format kraft solutions capture specification share where municipal composting partnerships exist.
Municipalities drive material transition mandates; landscapers represent the most underpenetrated volume expansion opportunity.
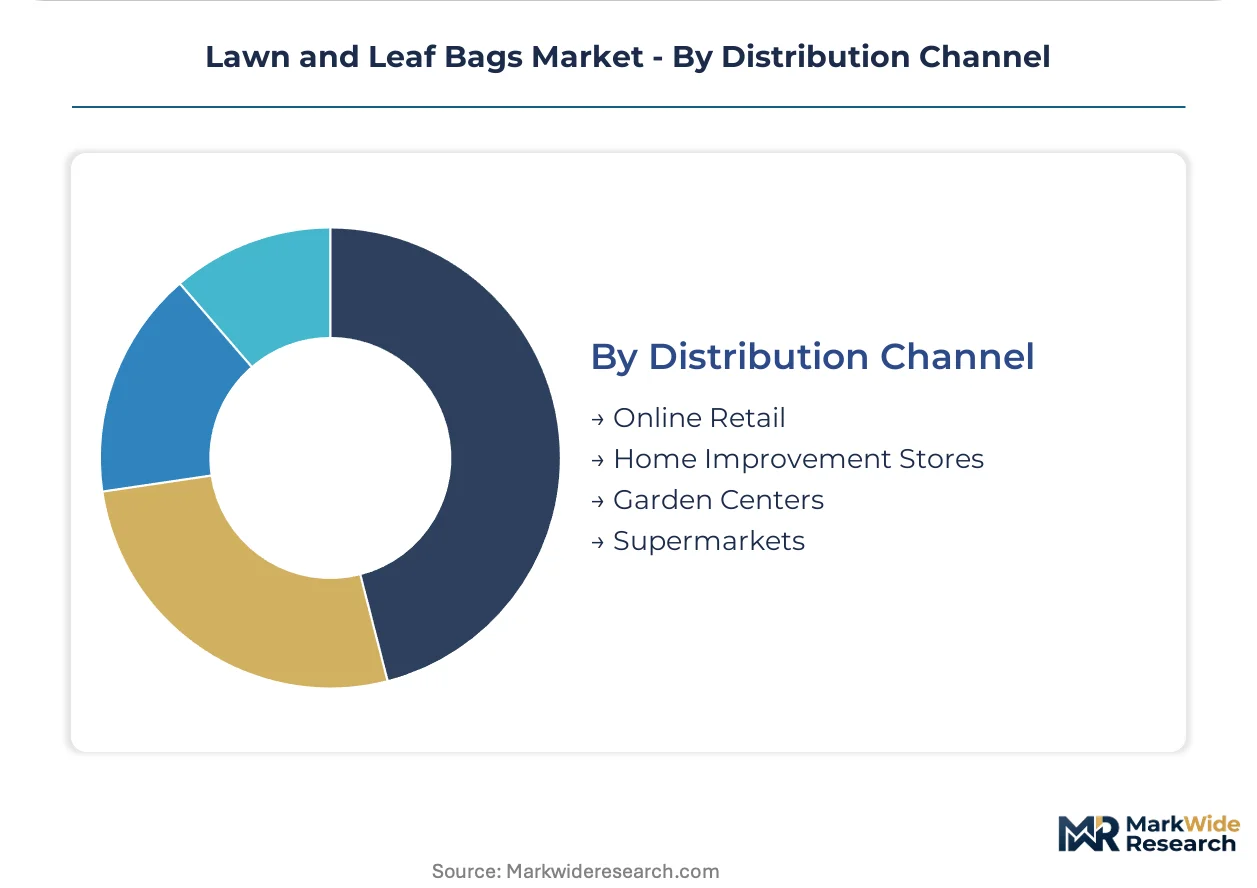
Distribution Channel:
Channel selection reflects purchase frequency, certification verification needs, and volume consolidation trends.
- Online Retail:E-commerce platforms serve cooperative buying consortia and bulk procurement with direct-to-crew delivery. Landscapers in fragmented markets access certified compostable variants unavailable through local retail.
- Home Improvement Stores:Big-box retailers consolidate supplier bases around dual-certified paper-plastic hybrid lines. Integrated extrusion and converting assets determine vendor selection for seasonal category resets.
- Garden Centers:Specialty retail networks in Germany and France prioritize kraft-based alternatives under EU Green Deal alignment. Premium positioning rewards REACH-compliant additive disclosure and non-phthalate plasticizer alternatives.
- Supermarkets:Mass-market grocery channels cluster medium-format household demand with impulse-category placement. Autumn promotional cycles synchronize with leaf collection timing in temperate climate zones.
Home improvement stores anchor household volume; garden centers capture premium positioning for regulatory-compliant alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The lawn and leaf bags industry traces its commercial origins to mid-20th century North American municipal waste management programs, where polyethylene film first displaced paper sacks for curbside yard debris collection. Material innovation hubs subsequently emerged across Western Europe and East Asia as composting infrastructure matured.
United States
California's SB 1383 organic waste mandate and homeowner association landscaping standards drive certified compostable bag procurement. The EPA and state environmental agencies coordinate yard waste diversion targets through landfill tipping fee structures. Procurement officers in Washington and Oregon specify PBAT-starch alloys for municipal fall collection programs.
Germany
German garden center networks prioritize kraft-based alternatives under EU Single-Use Plastics Directive extended producer responsibility frameworks. The ECHA REACH framework pressures film suppliers to certify additive chemistries for polymer disclosure compliance. Bavarian pulping operations supply specification-grade paper substrates to retail channels across Central Europe.
Canada
Ontario and British Columbia scale residential organics pickup, creating institutional procurement pipelines for high-volume kraft and biopolymer bag supply. Municipal composting mandates in Toronto and Vancouver accelerate material transitions from polyethylene to certified compostable films. British Columbia's industrial composting infrastructure processes certified bags at scale.
France
French garden center networks capture premium positioning for regulatory-compliant alternatives under EU Green Deal alignment. The ECHA REACH framework compels reformulation of colorants and slip agents in film production. Auvergne-Rhône-Alpes specialty retail clusters displace conventional plastic variants through cooperative buying platforms.
Japan
Tokyo high-rise residents specify compact formats for municipal organics diversion programs with space-constrained collection infrastructure. METI coordinates standardization of biodegradable certification requirements across prefectural jurisdictions. Kanto region waste management authorities pilot multi-layer extrusion technologies for moisture-resistant paper substrates.
Lawn and Leaf Bags Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification tier and material specialization, with integrated pulp-to-converting operations commanding pricing power over resin-dependent film extruders. The vendor base organizes into three strategic archetypes: European kraft paper specialists with captive forestry assets, North American polyethylene compounders with blown film capacity, and Asian biopolymer formulators scaling PBAT-starch alloys. Dominant competitive moves include backward integration into raw material supply and geographic expansion through municipal procurement consortia.
Within the integrated paper specialist tier, Mondi Group plc exemplifies European infrastructure deployment across retail garden center networks. Sigma Plastics Group occupies a position among North American resin compounders with in-house production of high-density polyethylene film. Among diversified packaging conglomerates, Dano Group represents scale-driven consolidation targeting contractor-grade volume accounts. These three anchors illustrate how competitive positioning stratifies across material technology and channel access rather than geographic coverage alone.
| Leading Market Players |
|---|
| Mondi Group plc |
| PEI Bag Co. |
| Dano Group |
| Custom Faberkin, Inc. |
| USA Poly Pack |
| Go-GreenGardening |
| Bundaberg Bag Company |
| Brisbane Bag Company |
| Sigma Plastics Group |
| Others |
Supply & Pricing Matrix
Blown film extrusion technician pools in the US Gulf Coast and Central European converting hubs create labor-cost differentials that widen spreads between contractor-grade polyethylene bags and certified compostable alternatives. These workforce concentrations anchor pricing power for integrated resin compounders while squeezing margin structures for biopolymer specialists facing agricultural feedstock volatility.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates BPI-certified compostable films from conventional polyethylene and unbranded commodity grades. Price differentiation hinges on certification tier and volume scale, with municipal procurement consortia capturing lowest unit costs through 100-count contractor packs. Cost compression in biodegradable lines is intensifying because PBAT resin prices fluctuate with corn starch markets. Household purchasers through supermarkets exhibit highest price sensitivity, while municipalities with SB 1383 mandates absorb premium tiers without volume elasticity.
Supply Chain Analysis
Workforce availability for blown film extrusion and kraft converting concentrates in the United States, Germany, and China, with each geography specializing in distinct material outputs. Raw material sourcing draws from petroleum resin complexes along the US Gulf Coast, Scandinavian pulp operations for European paper grades, and agricultural starch processing in the American Midwest. Single-source vulnerability runs through PBAT polymerization capacity concentrated with limited Asian compounders. Distribution runs through home improvement store networks and municipal procurement consortia rather than traditional wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where municipal procurement officers now specify certified compostable films as baseline requirement rather than premium upgrade, compressing margin pools for conventional polyethylene specialists.
For Market Incumbents: Deepen backward integration into captive pulp supply or resin compounding to defend margin structures against biopolymer feedstock volatility. Sigma Plastics Group's blown film infrastructure provides template for polyethylene compounders facing California SB 1383 compliance erosion. Certification investment in dual ASTM D6400 and EN 13432 portfolios preserves specification access across fragmented municipal standards. For New Entrants and Emerging Players: Begin with contractor channel penetration in Florida and Texas landscaping services currently reusing construction debris bags for organic material. These underdeveloped volume accounts lack purpose-designed alternatives and respond to puncture-resistant PBAT-starch formulations. Direct-to-crew online retail bypasses entrenched home improvement store supplier bases. For Investors and Strategic Acquirers: European kraft paper specialists with captive forestry assets are the most active acquirer in this space, consolidating REACH-compliant converting capacity ahead of EU Single-Use Plastics Directive enforcement. Five-to-ten year viability favors integrated pulp-to-bag operations over resin-dependent film extruders facing regulatory displacement. The signal to watch is industrial composting facility buildout rates in US states without SB 1383 analogues.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Raw Material Supply | Captive pulp or resin production insulates margin from agricultural commodity volatility and REACH compliance costs. |
| Dual Certification Portfolio Investment | Simultaneous ASTM D6400 and EN 13432 approval unlocks municipal procurement across North American and European jurisdictions. |
| Contractor Channel Direct Distribution | Bypassing retail intermediaries captures volume accounts in Florida and Texas landscaping services with 100-count pack formats. |
| PBAT-Starch Alloy Formulation Scale-Up | Multi-layer extrusion advances unify tear resistance and soil biodegradation timelines for fall collection program specifications. |
| Municipal Procurement Consortia Partnership | Cooperative buying platforms in suburban Chicago and Atlanta markets displace individual household retail purchases. |
Research Methodology
Multiple input streams — municipal procurement officer interviews, blown film extrusion plant manager discussions, and home improvement store category buyer consultations — were reconciled against customs trade data, EPA yard waste diversion statistics, and SEC filings from integrated paper and packaging conglomerates. Bottom-up volume estimates from county-level composting program rollouts were cross-checked with top-down resin consumption figures from industry associations.
Historical shipment data from kraft paper and polyethylene film trade associations were cross-referenced against panel inputs from procurement officers in Washington, Oregon, and California to construct demand trajectories across the analysis window. Segmentation modeling incorporated material type, size format, end-user category, and distribution channel dimensions with regional regulatory cluster overlays. CAGRs were derived from curve-fitting approaches applied to certified compostable film adoption rates and seasonal demand spike patterns.
Several conditions sit outside the modeled scope, including unannounced municipal composting mandate expansions, breakthroughs in non-starch biopolymer feedstocks, and industrial composting facility permitting delays. Forecasts reflect assumptions regarding SB 1383 compliance timelines and EU Single-Use Plastics Directive enforcement consistency. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Jumbo Bags Market
Bags and Containers
Portion Bags Market
Bags and Containers
Tote and Ingredient Bags Packaging Market
Bags and Containers
Net Bags Market
Bags and Containers
Mylar Bags Market
Bags and Containers
Lay Flat Bags Market
Bags and Containers
Clay Desiccant Bag Market
Bags and Containers
Woven Sacks Market
Bags and Containers
PVDC Shrink Bags Market
Bags and Containers
Bag-In-Box Container Market
Bags and Containers
4-Loop FIBC Market
Bags and Containers
Flip Lip Bags Market
Bags and Containers
MSW Bag Opener Market
Bags and Containers
Bagster Bag Market
Bags and Containers
Nonwoven Containers Market
Bags and Containers
Octabin Market