
 Non-Barrier Bag Market | 2026-2036
Non-Barrier Bag Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Barrier Bag Market Analytics
The capital-intensity divergence between integrated resin producers and regional converters is unwinding competitive stability in non-barrier bag supply. Berry Global Group leverages vertical integration through captive resin and film extrusion to sustain margin control across North American food packaging. Mondi Group anchors its position through kraft paper specialization and recycled fiber sourcing in European retail applications. Sealed Air Corporation differentiates via automated bagging systems integration, competing less on commodity resin economics than on throughput efficiency for e-commerce clients.
Non-barrier bags are single-ply or multi-ply flexible containers manufactured from polyethylene, polypropylene, paper, or woven polypropylene without metallized, coextruded, or coated layers that impede gas or moisture transmission, typically specified at thicknesses below 3 mil for lightweight shipping and 3-6 mil for industrial dunnage. These bags serve primary functions of containment, identification, and basic protection where extended shelf life or oxygen exclusion is unnecessary. Plastic bags dominate volume in food packaging applications where cost-per-unit and heat-seal compatibility govern procurement decisions, while paper bags capture premium positioning in retail branding where printability and curbside recyclability align with corporate sustainability commitments. Compostable bags represent the fastest-growing product type as certification requirements under BPI and TÜV OK Compost standards create qualification barriers that concentrate margin pools with resin compounders possessing certified formulation expertise.
EPA guidelines on recycled content thresholds and state-level extended producer responsibility frameworks in California and New York are reshaping material specifications and compliance documentation burdens for bag converters. REACH restrictions on intentionally added microplastics and the EU Single-Use Plastics Directive are forcing export-oriented manufacturers to maintain dual product lines or absorb reformulation costs. Stakeholders must monitor polymer price volatility against recycled feedstock availability and pre-qualify alternative resin streams before regulatory deadlines eliminate incumbent material options.
Market Dynamics
E-commerce fulfillment centers are compressing order-to-delivery windows, forcing bag converters to engineer lighter-weight shipping sacks that cut dimensional weight charges while maintaining burst strength for automated sortation systems. This operational pressure is reshaping resin specifications and extrusion investments across the value chain.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:The mandate for mono-material designs is accelerating converter R&D into recyclable polyethylene structures that simplify post-consumer sorting and reprocessing streams.
- Quick-commerce logistics:Ten-minute delivery platforms in Indian metropolitan clusters are generating surging order volumes requiring lightweight, printed non-barrier bags for rapid picking and thermal insulation.
- Compostable resin certification:BPI and TÜV OK Compost standards are creating qualified supplier scarcity that concentrates margin pools with compounders possessing certified formulation expertise.
Market Restraints
- Polyethylene price volatility:Naphtha-linked resin costs swing with crude oil benchmarks, compressing converter margins when long-term supply contracts lock in fixed pricing to retail clients.
- Recycled feedstock concentration:Post-consumer polyethylene flake supply clusters in German and Dutch reprocessing facilities, creating geographic dependency for converters seeking 30% recycled content compliance.
- Permeability limitation:Non-barrier constructions cannot exclude oxygen or moisture, disqualifying them from fresh protein and pharmaceutical applications where modified atmosphere packaging is mandatory.
Strategic Opportunities
- Organized retail expansion in Tier-2 Indian cities:Modern grocery chains penetrating secondary urban centers are establishing centralized distribution hubs that standardize bag specifications and consolidate procurement volumes.
- Automated bagging system integration:Convergence of vision-guided robotics with pre-opened bag dispensers is creating service-revenue streams for film suppliers who bundle equipment with consumables contracts.
- California SB 54 implementation:Extended producer responsibility frameworks are mandating recycled content thresholds that favor domestic converters with verified post-consumer supply chains over import-dependent competitors.
Industry Challenges
- Compostable processing skill scarcity:Extrusion technicians trained in polyethylene rheology require retraining to manage PLA and PBAT melt instability during high-speed converting operations.
- Dual product line complexity:Export-oriented manufacturers must maintain separate resin inventories and quality systems to serve REACH-compliant European orders alongside conventional formulations for other destinations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Barrier Bag Market |
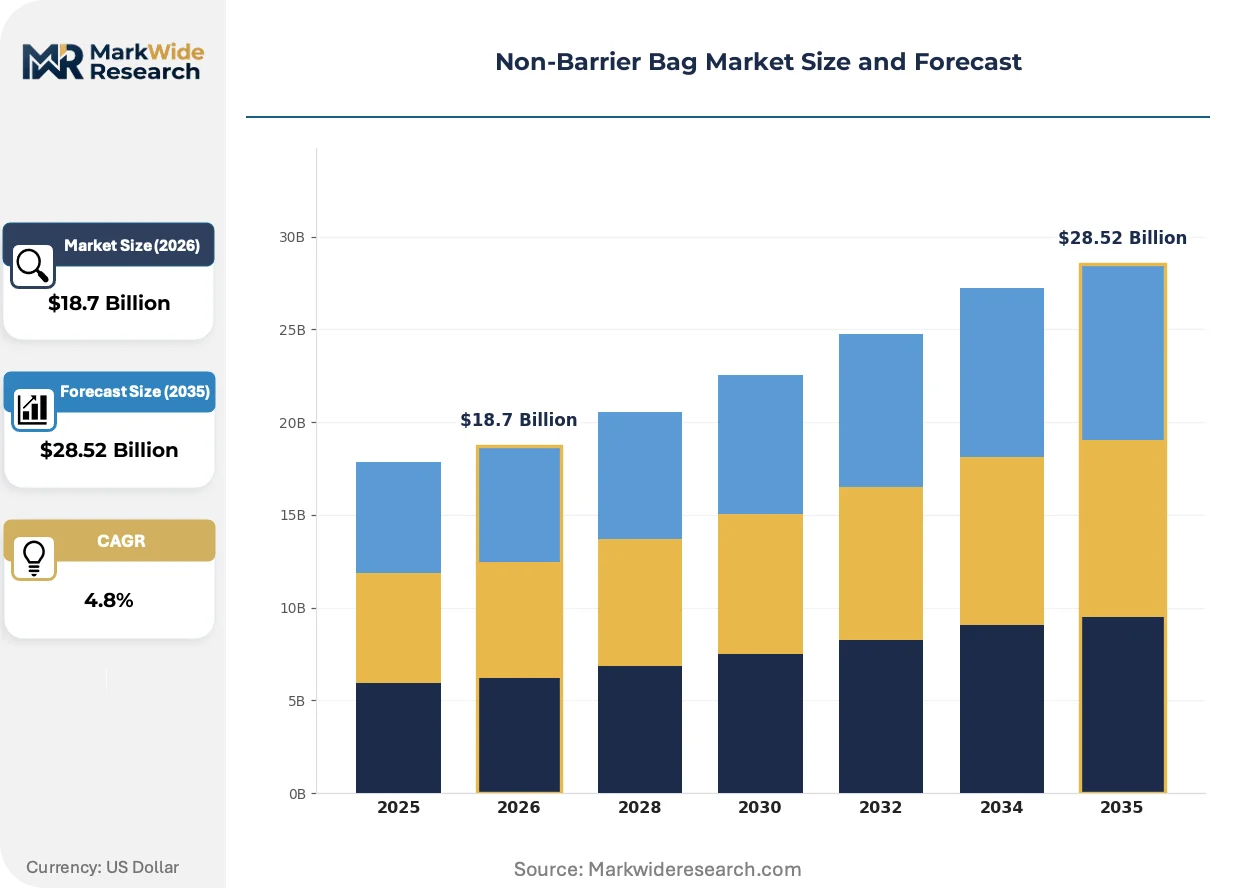
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Bags, Paper Bags, Fabric Bags, Compostable Bags Application: Food Packaging, Retail Packaging, Industrial Packaging, Household Use End User: Food Service, Retailers, E-Commerce, Manufacturing Distribution Channel: Online Sales, Supermarkets, Convenience Stores, Wholesale |
| Companies Covered | Berry Global Group, Mondi Group, Amcor, Sealed Air Corporation, Huhtamaki, Coveris, Novolex, Sonoco Products, Winpak, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Barrier Bag Market Evolving Landscape
Material science advances and regulatory compliance architectures are converging to redefine performance specifications and sourcing protocols across non-barrier bag applications. Three developments are commanding strategic attention from converters and brand owners.
Downgauging technology is miniaturizing film thickness without sacrificing tensile properties through biaxial orientation and metallocene catalysis. E-commerce fulfillment operators are adopting 1.5-mil shipping sacks at accelerating pace to minimize dimensional weight charges. The structural consequence is compressing resin consumption per thousand bags while demanding capital-intensive extrusion equipment upgrades.
REACH restrictions on intentionally added microplastics are forcing reformulation of slip agents and anti-block additives in European-bound production lines. The industrial consequence is accelerated qualification of mineral-based alternatives that maintain machinability without polymer contamination. Food packaging exports to the EU are most affected, with converters absorbing testing costs to maintain market access.
Buyer consolidation among quick-commerce platforms is compressing supplier qualification cycles and unbundling after-sales technical service from unit pricing. Aggregated procurement desks in Mumbai and Bangalore are replacing fragmented distributor networks, demanding direct mill relationships with documented carbon footprints. This pattern is most visible in Indian metropolitan clusters where platform economics favor national supply contracts over regional sourcing diversity.
Non-Barrier Bag Market Segmentation
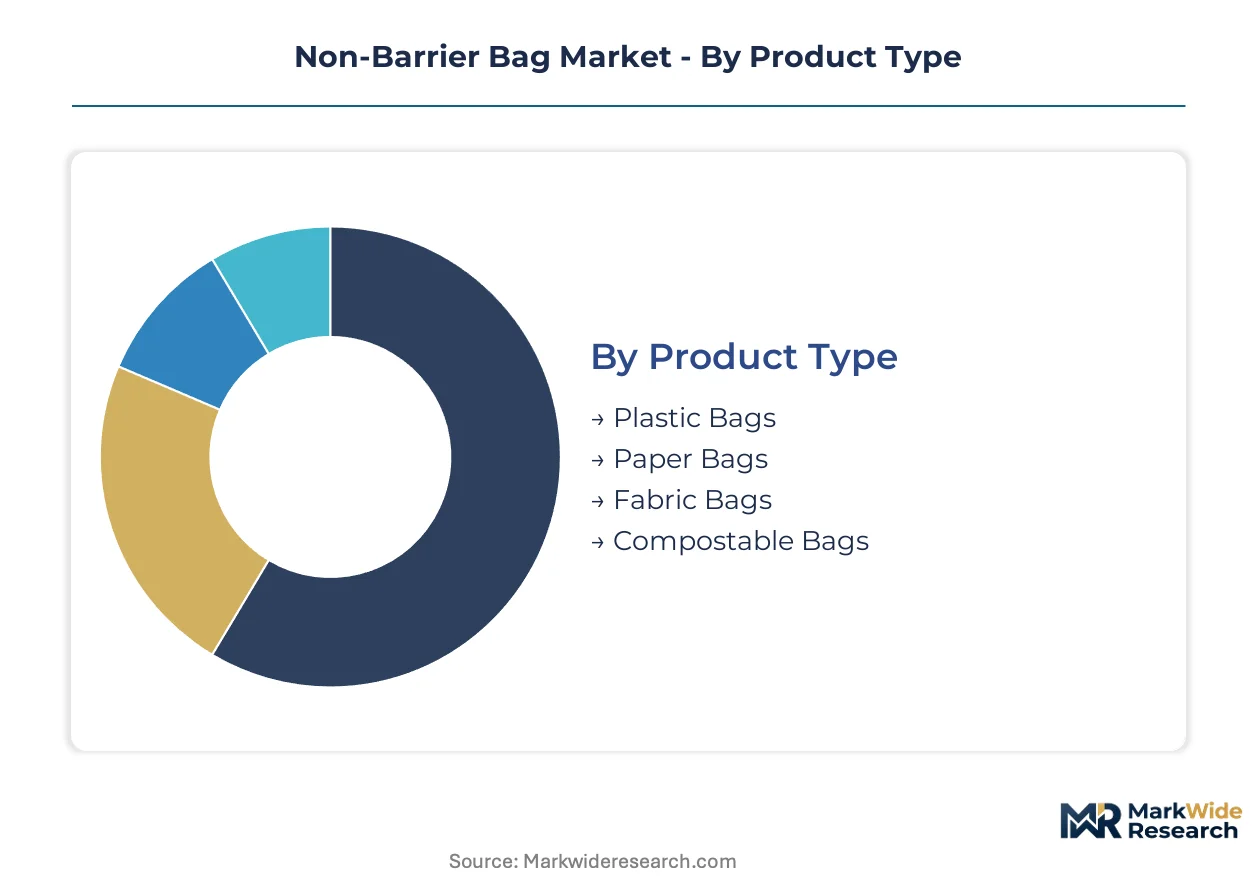
Non-barrier bag procurement decisions split sharply between cost-driven commodity specifications and performance-tuned applications. Segment boundaries are blurring as e-commerce fulfillment demands force paper and plastic formats to converge on lightweight, printable, automation-compatible designs.
Product Type:
Substitution pressure from compostable alternatives and regulatory bans on conventional plastics are reshaping material selection across all four product categories.
- Plastic Bags:Polyethylene and polypropylene constructions dominate food packaging and industrial dunnage where heat-seal compatibility and moisture resistance govern specifications. Demand concentrates in Indian quick-commerce logistics where ten-minute delivery platforms require ultra-lightweight printed sacks for rapid picking operations.
- Compostable Bags:PLA and PBAT formulations certified under BPI and TÜV OK Compost standards are displacing conventional plastics in European retail applications where EPR frameworks mandate recyclable or compostable alternatives. Supply scarcity concentrates margin pools with resin compounders possessing certified formulation expertise.
- Paper Bags:Kraft constructions with high printability serve premium retail branding where curbside recyclability aligns with corporate sustainability commitments.
- Fabric Bags:Woven polypropylene structures endure industrial bulk handling where tear resistance and reusability justify higher unit costs.
Plastic bags retain volume leadership; compostable bags hold the steepest expansion curve.
Application:
Cost tier stratification separates high-volume commodity specifications from premium branded applications with stringent print and sustainability requirements.
- Food Packaging:Single-ply polyethylene sacks with thicknesses of 2-3 mil serve dry goods, baked products, and frozen vegetables where oxygen exclusion is unnecessary. Demand concentrates in North American supermarket private-label programs where converters compete on resin cost and print registration precision.
- Retail Packaging:Paper and plastic carryout bags with reinforced handles and high-definition graphics support brand identity in organized grocery and apparel chains. European retailers under CSRD disclosure requirements are accelerating shifts toward recycled fiber and certified compostable alternatives.
- Industrial Packaging:Heavy-duty woven and laminated structures protect construction materials, agricultural inputs, and chemicals during bulk transport and warehousing.
- Household Use:Standard kitchen bags and storage sacks prioritize cost-per-unit and odor containment over structural performance.
Food packaging retains volume leadership; retail packaging holds the steepest expansion curve.
End User:
Customer type fragmentation creates divergent procurement patterns between centralized national contracts and fragmented local purchasing.
- E-Commerce:Fulfillment centers demand 1.5-2.0 mil shipping sacks optimized for dimensional weight reduction and automated sortation compatibility. Amazon and Flipkart distribution hubs in India and Germany are driving specification standardization across supplier bases.
- Food Service:Quick-service restaurants and catering operations require grease-resistant paper and plastic bags for hot food transport and delivery aggregation.
- Retailers:Modern grocery chains in Tier-2 Indian cities are consolidating procurement through centralized distribution hubs that standardize bag specifications.
- Manufacturing:Industrial buyers prioritize unit cost and supply continuity over print quality or sustainability certifications.
E-commerce retains volume leadership; food service holds the steepest expansion curve.
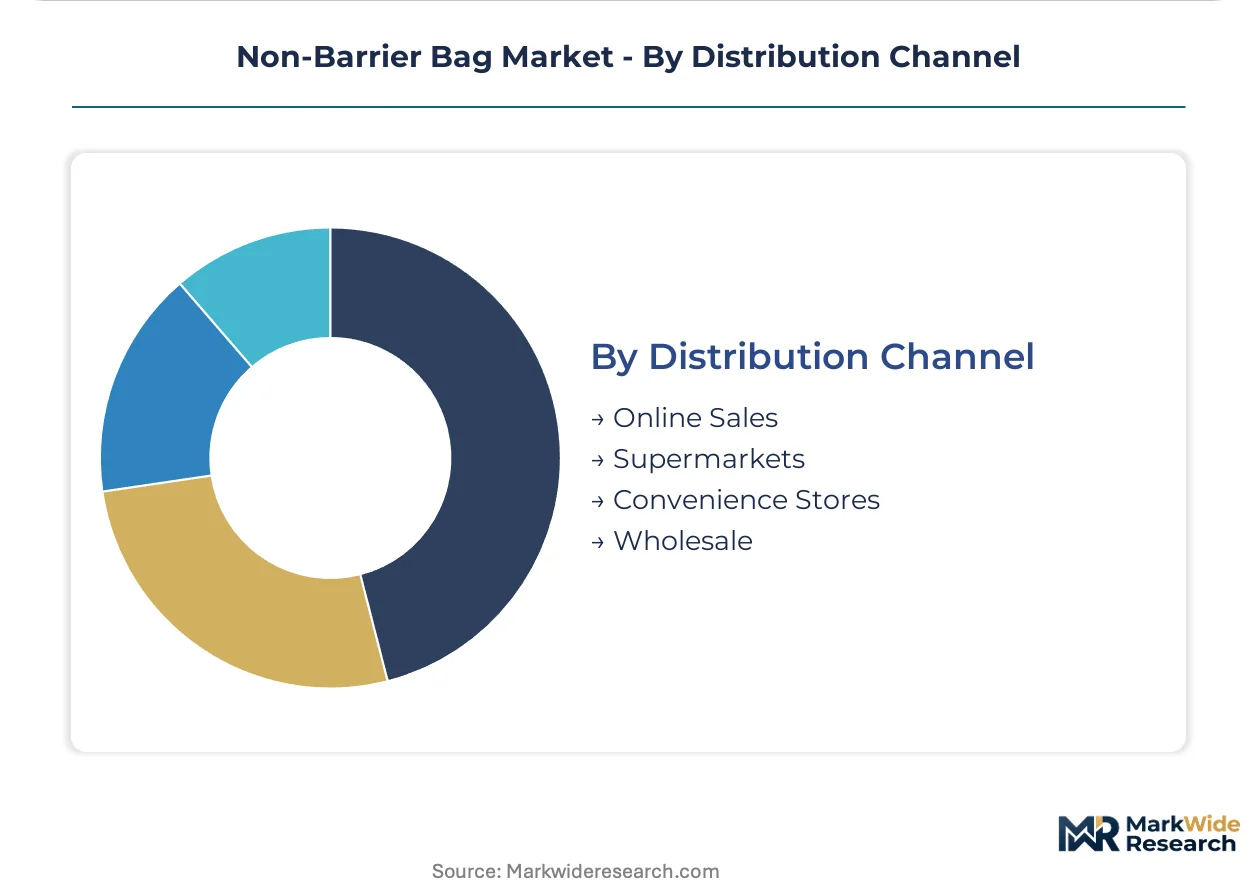
Distribution Channel:
Supply concentration in wholesale and supermarket networks is fragmenting as direct mill relationships displace traditional distributor intermediaries.
- Wholesale:Industrial and commercial buyers source through regional distributors offering consolidated SKU ranges and inventory financing. German and Dutch packaging wholesalers control recycled feedstock access for converters seeking 30% post-consumer content compliance.
- Online Sales:Direct-to-converter platforms and B2B marketplaces are compressing price discovery cycles and unbundling technical service from unit pricing.
- Supermarkets:Organized retail chains leverage volume concentration to mandate supplier sustainability documentation and carbon footprint disclosure.
- Convenience Stores:Fragmented local purchasing prioritizes immediate availability over specification optimization or cost minimization.
Wholesale retains volume leadership; online sales holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for non-barrier bags varies sharply by geography. Indian quick-commerce platforms absorb price premiums for lightweight printed sacks, while North American industrial buyers enforce rigid cost-per-unit procurement. European retailers accept sustainability-driven price premiums that Asian commodity markets reject.
United States
E-commerce fulfillment centers in Ohio and Pennsylvania drive specification standardization for 1.5-mil shipping sacks optimized for automated sortation. EPA recycled content guidelines and California SB 54 extended producer responsibility frameworks mandate verified post-consumer supply chains. The Midwest industrial corridor concentrates converter capacity serving Amazon and Walmart distribution networks.
Germany
REACH restrictions on intentionally added microplastics force reformulation of slip agents in European-bound production lines. The EU Packaging and Packaging Waste Regulation accelerates converter R&D into mono-material polyethylene structures. The Rhine-Ruhr industrial cluster hosts reprocessing facilities supplying post-consumer flake to converters seeking 30% recycled content compliance.
India
Quick-commerce platforms in Mumbai and Bangalore generate surging order volumes requiring ultra-lightweight printed bags for ten-minute delivery logistics. FSSAI food contact regulations and BIS quality standards govern specifications for food packaging applications. Organized retail chains penetrating Tier-2 cities establish centralized distribution hubs that consolidate procurement volumes.
China
Export-oriented manufacturers maintain dual product lines to serve REACH-compliant European orders alongside conventional formulations for other destinations. MIIT industrial standards and GB packaging regulations shape domestic specifications. The Yangtze River Delta concentrates film extrusion capacity serving both domestic e-commerce and export markets.
Brazil
Retail packaging demand concentrates in São Paulo and Rio de Janeiro metropolitan areas where organized grocery chains standardize bag specifications. ANVISA food contact regulations govern polyethylene constructions for dry goods applications. The Southeast industrial corridor hosts converters serving both domestic retail and Mercosur export markets.
Non-Barrier Bag Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the non-barrier bag value chain. Integrated resin producers leverage captive polyethylene supply to defend margin positions in commodity food packaging. Regional converters compete on print registration precision and rapid order turnaround for quick-commerce clients. Strategic moves center on backward integration into film extrusion and geographic expansion into Indian Tier-2 cities.
Among integrated packaging groups, Berry Global Group and Mondi Group exemplify divergent specialization paths—one anchored in North American resin economics, the other in European fiber-based sustainability positioning. Sealed Air Corporation occupies a distinct automation-focused tier where equipment bundling with consumables contracts displaces pure commodity competition. These three structures—resin-integrated, fiber-specialized, and systems-integrated—define the competitive terrain.
| Leading Market Players |
|---|
| Berry Global Group |
| Mondi Group |
| Amcor |
| Sealed Air Corporation |
| Huhtamaki |
| Coveris |
| Novolex |
| Sonoco Products |
| Winpak |
| Others |
Value Network & Pricing Analysis
BPI and TÜV OK Compost certification regimes gate both supplier qualification and price differentiation simultaneously, concentrating margin pools with compounders possessing certified formulation expertise while locking uncertified converters into commodity polyethylene pricing tiers. This dual-gate mechanism separates premium compostable resin streams from conventional plastic bag economics across procurement desks.
Pricing Analysis
After-sales technical service and automated bagging system integration drive lifetime value beyond unit resin costs. Three-tier pricing structure across premium compostable, standard recycled-content, and economy virgin-polyethylene levels governs procurement negotiations. Price differentiation rests on certification grade and volume scale, with quick-commerce platforms in India absorbing premiums for lightweight printed sacks. Cost compression in standard-grade polyethylene runs through naphtha-linked resin volatility, while food packaging converters face the sharpest price sensitivity due to supermarket private-label procurement.
Supply Chain Analysis
China and India anchor film extrusion capacity for e-commerce shipping sacks, while Germany and the Netherlands concentrate post-consumer polyethylene reprocessing for recycled feedstock. Raw material dependencies draw from naphtha-derived polyethylene resin, kraft pulp for retail paper bags, and PLA/PBAT biopolymers for compostable alternatives. Single-source vulnerability clusters in German-Dutch recycled flake supply for converters seeking 30% post-consumer compliance. Distribution runs through centralized procurement desks at quick-commerce platforms and Amazon-Flipkart fulfillment hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents an early-cycle expansion story driven by ten-minute delivery platform penetration in Indian metropolitan clusters, where surging order volumes outpace existing bag converter capacity.
For Market Incumbents: Fortify backward integration into captive resin compounding and film extrusion to defend margin positions against naphtha price volatility. Expand extrusion capacity in Tier-2 Indian cities where organized retail centralization concentrates procurement volumes. Prioritize BPI and TÜV OK Compost certification investment to capture premium pricing tiers before regulatory deadlines eliminate conventional material options. For New Entrants and Emerging Players: Differentiate on compostable formulation expertise and automated bagging system bundling rather than commodity resin economics. Target quick-commerce logistics in Indian metropolitan clusters as the most penetrable segment, where platform buyer consolidation favors direct mill relationships. Pursue national supply contracts with documented carbon footprints as the primary go-to-market angle. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across automated bagging system integration and certified compostable resin compounding, favoring players with equipment-consumables bundling capabilities. Long-term viability over the next decade centers on converters with verified post-consumer supply chains and dual REACH-conventional product line flexibility. Monitor California SB 54 implementation pace as the signal to watch for domestic converter margin inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive polyethylene and PLA supply shields margins from naphtha volatility at Berry Global scale. |
| Automated Bagging System Integration | Sealed Air's equipment-consumables bundling displaces pure commodity competition in e-commerce fulfillment. |
| Compostable Certification Investment | BPI and TÜV OK Compost qualification concentrates margin pools with formulation expertise holders. |
| Geographic Expansion into Tier-2 Indian Cities | Organized retail centralization in secondary urban hubs consolidates procurement volumes for early movers. |
| Recycled Feedstock Supply Agreements | Verified post-consumer flake access from German-Dutch reprocessors ensures California SB 54 compliance. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs and trade data, SEC filings from packaging groups, EPA recycled content guidelines, and EU Packaging and Packaging Waste Regulation documentation. Primary interviews engaged resin procurement managers at quick-commerce platforms, extrusion plant engineers at regional converters, sustainability officers at organized retail chains, and technical sales leads at automated bagging equipment suppliers. Secondary validation drew from BIS quality standards, FSSAI food contact regulations, and REACH restriction updates. Bottom-up demand modeling from end-use applications triangulated against top-down supply capacity assessments across film extrusion and reprocessing facilities.
Segmentation dimensions modeled span product type, application, end user, and distribution channel across the projection horizon. Product type splits capture plastic, compostable, paper, and fabric bag constructions. Application segmentation covers food packaging, retail packaging, industrial packaging, and household use. End user categories encompass e-commerce fulfillment, food service, retailers, and manufacturing. Distribution channel analysis tracks wholesale, online sales, supermarkets, and convenience stores. CAGRs were derived from elasticity modeling against polymer price indices and regulatory implementation schedules. Industry-specific forecast inputs include quick-commerce order volume trajectories in Indian metropolitan clusters and California SB 54 recycled content threshold compliance timelines.
Material uncertainties — polymer price volatility, recycled feedstock availability disruptions, and regulatory deadline acceleration — sit outside the modeled envelope. Forecasts reflect assumptions about certification adoption rates and platform buyer consolidation patterns. Recalibration cycles align with material shifts in EU Packaging and Packaging Waste Regulation enforcement and Indian FSSAI quality standard updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Liquid Packaging Bag Market
Bags and Containers
4-Loop FIBC Market
Bags and Containers
Carry Bag Market
Bags and Containers
PE Jumbo Bags Market
Bags and Containers
Tamper Evident Bag Sealers Market
Bags and Containers
Household and Cleaning Container Market
Bags and Containers
Cross Corner Industrial Bags Market
Bags and Containers
Multiwall Bags Market
Bags and Containers
Vertical Form Fill Seal Baggers Market
Bags and Containers
Slider Bags Market
Bags and Containers
Europe Bulk Bags Market
Bags and Containers
Bag Making Machine Market
Bags and Containers
Cross Bottom Bags Market
Bags and Containers
Drink Carrier Poly Bags Market
Bags and Containers
Aluminum Beverage Bags Market
Bags and Containers
PVDC Shrink Bags Market