
 Handle Gusseted Bags Market | 2026-2036
Handle Gusseted Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Handle Gusseted Bags Market Foresight
Capital-intensity divergence between integrated resin producers and converter-only operators is bifurcating competitive returns across the Handle Gusseted Bags landscape. Novolex leverages captive film extrusion to sustain margin compression resistance in North American retail supply chains. Mondi Group anchors European demand through integrated paper-based gusseted formats that navigate fiber sourcing constraints. Amcor competes via global pre-qualification systems for healthcare-grade handle bags with traceable sterilization compatibility.
Handle gusseted bags incorporate expandable side panels welded to a flat bottom and reinforced carry handles, typically manufactured through blown film extrusion or multiwall paper conversion with hot-melt adhesive handle attachment, enabling cubic volume expansion without topple risk during manual transport. Plastic bags dominate unit volume across retail and food service channels where moisture barrier and heat-seal integrity prove essential, while biodegradable bags represent the fastest-expanding product type as compostability certifications become a procurement gate for municipal and institutional buyers. Paper bags occupy a mature premium tier in boutique retail and quick-service dining where tactile brand expression offsets higher per-unit cost.
FDA food-contact substance regulations govern resin additives and migration limits for bags touching unpackaged edibles, while EPA state implementation plans for plastic waste reduction pressure converters toward recycled content verification. The EU Packaging and Packaging Waste Regulation extends design-for-recycling mandates to handle-integrated formats, reshaping adhesive and ink selection for export-bound production. ISO 9001 and BRCGS packaging certification increasingly determine supplier eligibility in consolidated retail and healthcare procurement. Stakeholders must monitor evolving extended producer responsibility fee structures and recyclability assessment protocols to preempt compliance-driven sourcing switches.
Market Dynamics
Handle gusseted bag converters face margin compression as FDA food-contact compliance costs and state plastic bans in the United States force substrate transitions before recycled-content infrastructure matures.
Growth Catalysts
- E-commerce fulfillment expansion:Heavy-capacity gusseted formats with reinforced handles penetrate warehouse-to-doorstep logistics chains as manual handling durability becomes non-negotiable.
- EU Packaging and Packaging Waste Regulation:Design-for-recycling mandates for handle-integrated formats accelerate adhesive and ink reformulation among export-oriented converters.
- Compostability certification procurement gates:Municipal and institutional buyers in North America and Europe require ASTM D6400 or EN 13432 verification, pulling biodegradable bag volumes upward.
Market Restraints
- Resin price volatility:Virgin polyethylene and polypropylene feedstock costs swing with crude oil and natural gas liquid indices, squeezing converter margins on fixed-price retail contracts.
- China manufacturing concentration:Export logistics and blown film extrusion capacity cluster in coastal provinces, creating single-source dependency risk for North American and European distributors.
- Heat-seal integrity limitations:Biodegradable films exhibit narrower processing windows than conventional plastics, constraining line speeds and reject rates at high-volume converters.
Strategic Opportunities
- Healthcare sterilization compatibility:Pre-qualified handle bags with ISO 11607 traceability capture surgical kit and pharmaceutical packaging spend as hospitals consolidate supplier bases.
- India quick-service dining penetration:Paper-based gusseted formats with hot-melt handles displace loose plastic in tier-1 and tier-2 city food courts as FSSAI packaging norms tighten.
- Extended producer responsibility fee structures:Early compliance with emerging state-level EPR frameworks in the United States positions converters for preferred retail procurement status.
Industry Challenges
- Multiwall paper adhesive formulation expertise:Hot-melt handle attachment chemistry for fiber-based gusseted bags requires specialized process engineering talent scarce outside established European and Japanese converters.
- BRCGS certification timelines:Retail and food service buyers demand 12-18 month audit cycles for packaging suppliers, delaying new entrant market access.
- Legacy extrusion line retrofit costs:Biodegradable film processing requires screw design and cooling tower modifications that strain mid-cap converter capex budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Handle Gusseted Bags Market |
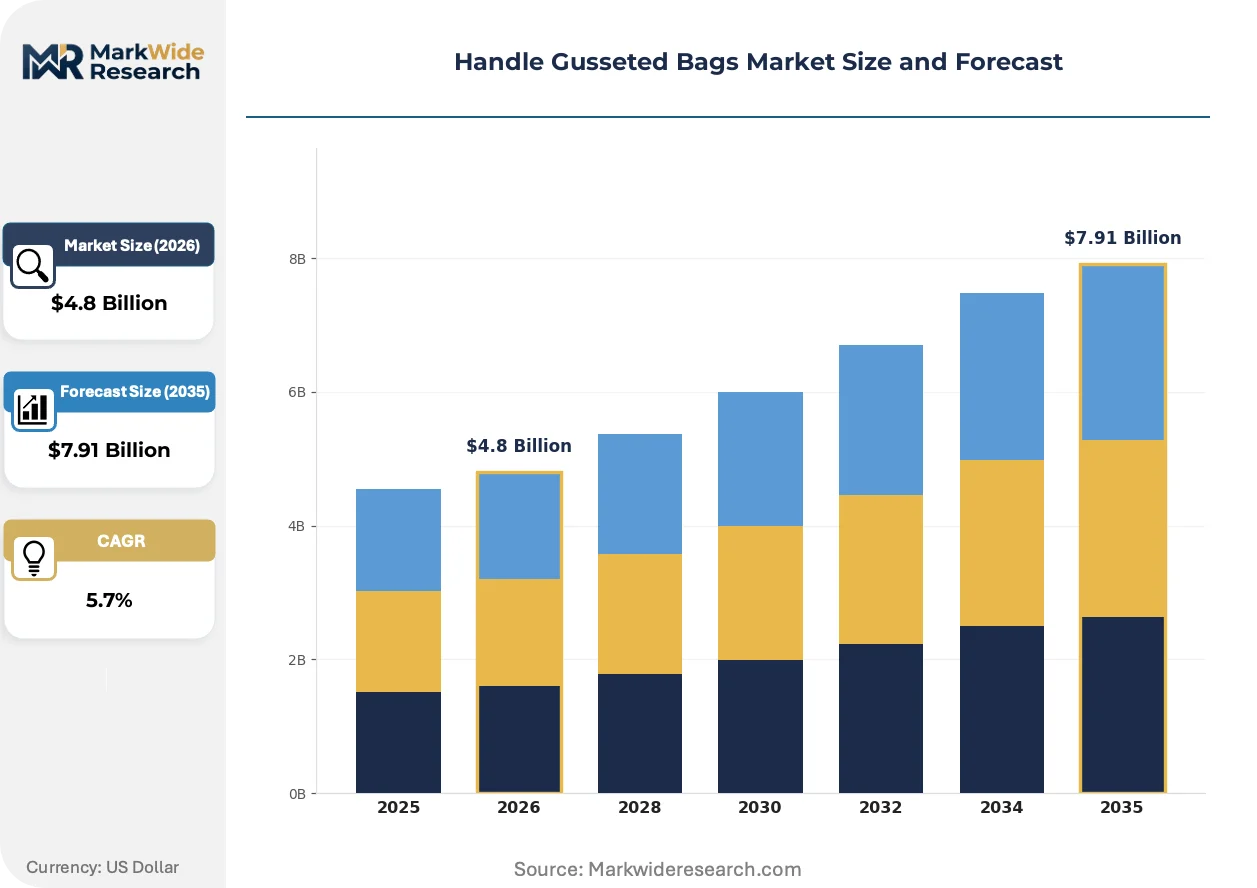
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Bags, Paper Bags, Biodegradable Bags, Woven Bags End User: Retail, Food Service, E-commerce, Healthcare Capacity: 1-5 kg, 6-10 kg, 11-15 kg, 16-20 kg Packaging Type: Flat Packs, Roll Form, Bundled Packs, Shrink Wrapped |
| Companies Covered | Novolex, Mondi Group, Amcor, Uline, Pacific Bag, International Plastics, Elkay Plastics, Berry Global, ProAmpac, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Handle Gusseted Bags Market Shifts & Advancements
Material science breakthroughs and regulatory design mandates are compressing traditional substrate hierarchies while procurement teams rewrite supplier scorecards around recyclability verification rather than unit cost alone.
Blown film extrusion lines configured for post-consumer recycled content are displacing virgin resin-dependent capacity as Walmart and Target supplier sustainability scorecards harden recycled-content thresholds. Food service distributors in the United States accelerate qualification timelines for rPE and rPP handle bags. The shift compresses margin structures for converters without backward integration into resin sourcing.
REACH SVHC candidate list expansion forces reformulation of slip agents and colorants in European-bound handle bag production. Converters serving dual US-EU markets now maintain separate additive masterbatch inventories to avoid cross-contamination. Healthcare-grade bag producers absorb the highest compliance burden as traceability documentation requirements multiply.
Consolidated retail procurement teams now mandate third-party recyclability assessment through How2Recycle or OPRL labeling before contract award. This behavior compresses supplier pools to converters with in-house laboratory capability. The pattern is most visible in United States grocery and mass merchandise channels where private-label bag programs dominate volume.
Handle Gusseted Bags Market Segmentation
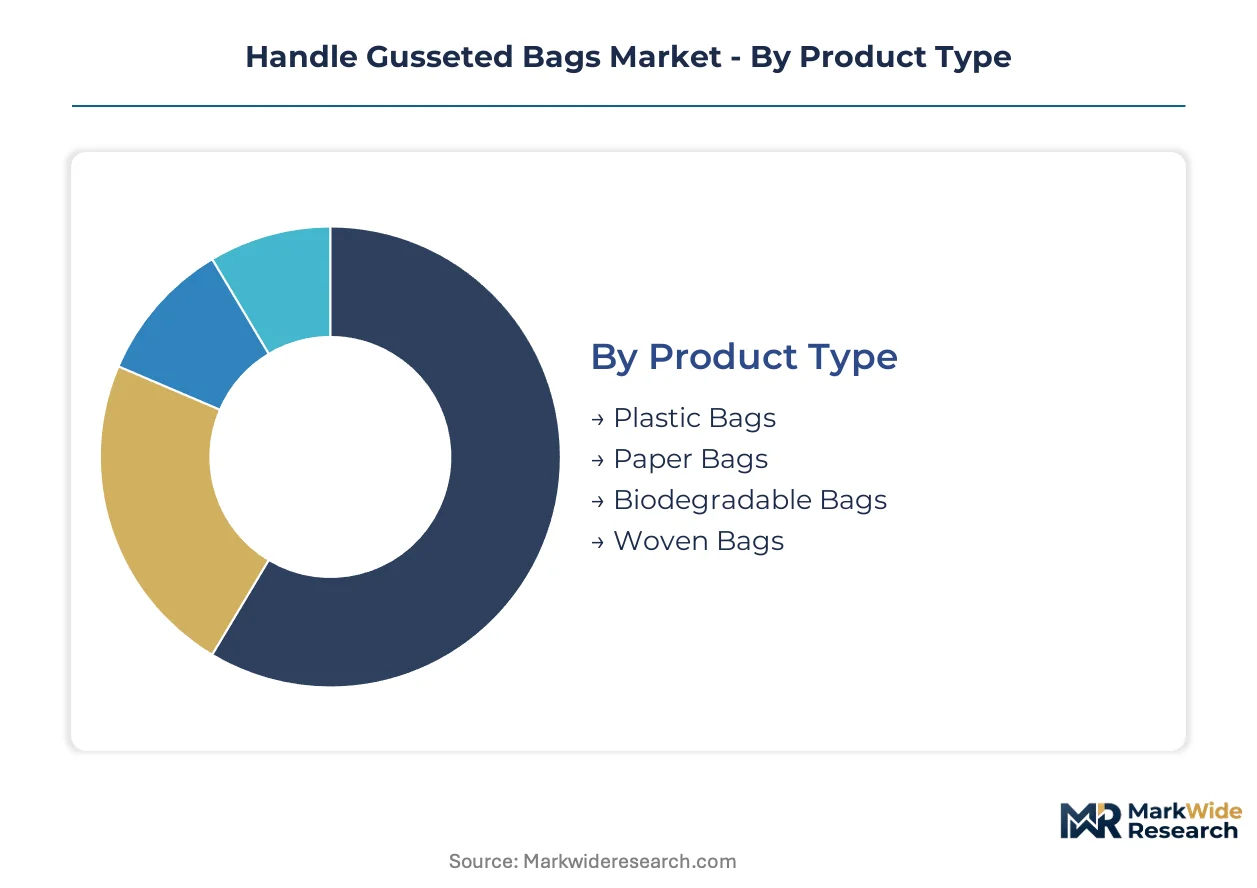
Handle gusseted bags fragment across four structural dimensions that determine converter capex allocation and margin capture. Product type and capacity specifications drive material science investment, while end-user verticals dictate certification requirements and packaging format preferences shape fulfillment economics.
Product Type:
Domestic consumption clusters around plastic and paper formats in North American and European retail channels, while woven and biodegradable variants serve export-led demand from Asian manufacturing hubs into regulated European markets.
- Plastic Bags:Blown film extrusion from polyethylene or polypropylene delivers moisture barrier and heat-seal integrity essential for frozen food and bulk retail. Demand concentrates in Walmart and Target supply chains where recycled-content thresholds now gate supplier qualification.
- Paper Bags:Multiwall fiber construction with hot-melt adhesive handle attachment serves quick-service dining and boutique retail where tactile brand expression offsets per-unit cost premiums. European quick-service dining chains drive specification tightening around fiber sourcing traceability.
- Biodegradable Bags:ASTM D6400 or EN 13432 certified films from PLA or starch blends capture municipal procurement in California and New York state where plastic bag bans have activated compostability mandates.
- Woven Bags:Polypropylene tape extrusion and circular loom weaving produce 25-50 kg agricultural and industrial formats with laminated gusset panels for chemical and grain handling.
Plastic bags command the established base. The steepest expansion runs through biodegradable bags as EPR frameworks harden disposal accountability.
End User:
Margin structures diverge sharply between price-sensitive retail volume and healthcare certification premiums that absorb compliance documentation costs.
- Retail:Grocery and mass merchandise channels demand high-velocity supply with How2Recycle labeling pre-qualification, compressing supplier pools to converters with in-house laboratory capability.
- E-commerce:Warehouse-to-doorstep logistics require reinforced handles and puncture resistance for parcel sortation systems, with Amazon and Shopify fulfillment networks driving 16-20 kg capacity adoption.
- Food Service:FDA food-contact compliance and grease resistance specifications govern quick-service and institutional dining procurement, with FSSAI norms tightening in India.
- Healthcare:ISO 11607 sterilization compatibility and traceable lot documentation capture surgical kit packaging spend as hospital systems consolidate supplier bases.
Retail absorbs the volume concentration. Healthcare delivers the margin premium trajectory.
Capacity:
Specification clustering reflects manual handling ergonomics and pallet cube optimization rather than continuous process variation.
- 1-5 kg:Boutique retail and pharmacy prescription formats dominate, with handle reinforcement specifications varying by carry distance requirements in urban versus suburban store formats.
- 6-10 kg:Standard grocery carry-home specifications align with average basket weights in European and North American supermarket channels.
- 11-15 kg:Bulk pet food and club store formats drive adoption, with Costco and Sam's Club supplier scorecards mandating drop-test performance thresholds.
- 16-20 kg:E-commerce fulfillment and industrial chemical handling require woven handle integration or film gauge increases that strain blown extrusion line configurations.
The 6-10 kg tier holds the volume anchor. The 16-20 kg range captures the logistics-upgrade momentum.
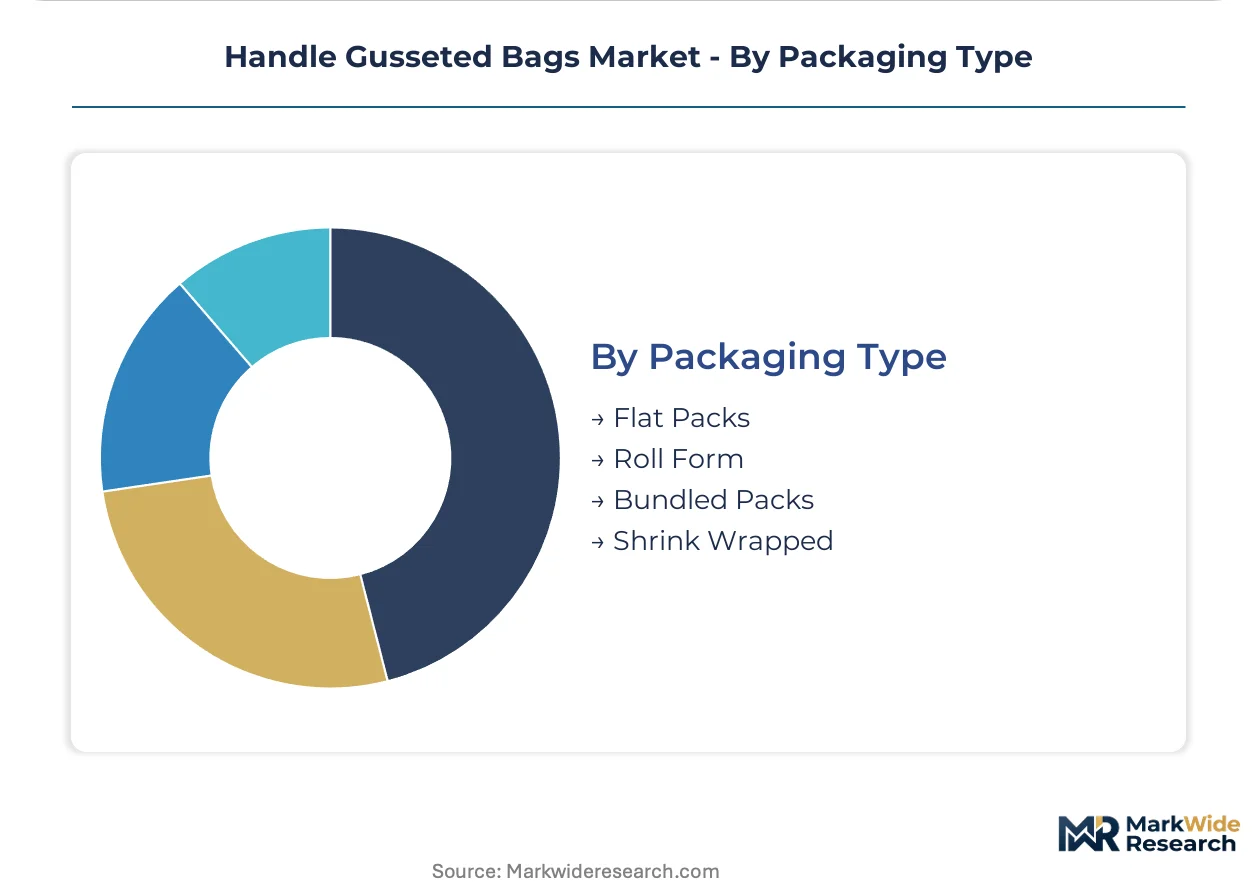
Packaging Type:
Fulfillment velocity and retail backroom storage constraints determine format selection across automated versus manual stocking environments.
- Flat Packs:Pre-formed bags ship in corrugated cases for direct-to-shelf presentation in convenience and pharmacy channels with limited backroom space.
- Roll Form:Continuous bag winding on cores feeds automated bagging machinery in distribution centers, with perforation spacing calibrated to line speed specifications.
- Bundled Packs:Hand-counted stacks with paper banding serve small-format retail and food service accounts without automated opening equipment.
- Shrink Wrapped:Polyethylene overwrap secures palletized loads for export shipment and protects against moisture intrusion in humid climate storage.
Roll form dominates automated fulfillment. Flat packs retain the fragmented retail base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in European converters navigating REACH SVHC compliance, while Chinese manufacturers absorb margin compression from export logistics volatility and state-mandated recycled-content transitions.
United States
Walmart and Target supplier scorecards now mandate How2Recycle labeling pre-qualification, compressing converter pools to operators with in-house laboratory capability. FDA food-contact substance regulations govern resin additives for bags touching unpackaged edibles. Blown film extrusion clusters in Ohio and Illinois serve Midwest distribution networks with rPE and rPP formats.
China
Manufacturing scale and export logistics sustain volume leadership as coastal province converters supply North American and European distributors. MEE dual carbon goals pressure substrate transitions toward bio-based alternatives. Zhejiang and Jiangsu provinces host blown film capacity serving e-commerce fulfillment demand.
Germany
EU Packaging and Packaging Waste Regulation design-for-recycling mandates reshape adhesive and ink selection for export-bound production. ECHA REACH SVHC candidate list expansion forces reformulation of slip agents and colorants. The Rhine-Ruhr industrial corridor anchors multiwall paper conversion with hot-melt handle expertise.
India
Quick-service dining penetration in tier-1 and tier-2 cities drives paper-based gusseted format adoption as FSSAI packaging norms tighten. DGFT import duty structures on virgin resin influence converter sourcing decisions. Maharashtra and Gujarat host converting capacity serving domestic food service channels.
Japan
Specialized process engineering talent for multiwall paper adhesive formulation concentrates among established converters serving boutique retail. METI circular economy roadmaps pressure design-for-recycling compliance. The Kansai region maintains legacy expertise in fiber-based gusseted bag production.
Handle Gusseted Bags Market Competitive Landscape
Concentration sits with integrated resin producers and converter-only operators bifurcating competitive returns across the landscape. Tiered supplier pools separate pre-qualified healthcare-grade operators from commodity retail converters. Strategic archetypes include backward-integrated film extruders, multiwall paper specialists, and healthcare certification holders. Dominant competitive moves encompass M&A for resin sourcing control and capacity expansion in biodegradable film processing.
Among North American integrated operators, Novolex leverages captive film extrusion to sustain margin compression resistance. Mondi Group anchors European demand through integrated paper-based formats. Amcor competes via global pre-qualification systems for healthcare-grade handle bags with traceable sterilization compatibility.
| Leading Market Players |
|---|
| Novolex |
| Mondi Group |
| Amcor |
| Uline |
| Pacific Bag |
| International Plastics |
| Elkay Plastics |
| Berry Global |
| ProAmpac |
| Others |
Supply & Pricing Matrix
How2Recycle labeling pre-qualification gates supplier pools and price differentiation simultaneously, compressing margins for converters without in-house laboratory capability while rewarding certified operators with contract premiums. This certification-driven segmentation feeds directly into supply chain consolidation as retail procurement teams consolidate vendor bases.
Pricing Analysis
The customization-premium spread separates standard off-the-shelf formats from configured-to-order specifications with ASTM D6400 or EN 13432 compostability verification. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with healthcare ISO 11607 holders capturing the top tier. Cost compression in biodegradable film processing is intensifying because blown extrusion line retrofits strain mid-cap converter budgets. Retail grocery channels exhibit the highest price sensitivity, while hospital systems consolidating supplier bases absorb certification premiums with minimal elasticity.
Supply Chain Analysis
Port congestion on the Shanghai-Los Angeles trade lane elevates inbound logistics costs for North American distributors sourcing from Zhejiang and Jiangsu province converters. Supply concentrates in China, Germany, and the United States, with blown film extrusion capacity clustering in coastal provinces and the Rhine-Ruhr corridor. Raw material dependencies draw from virgin polyethylene, polypropylene feedstock, and post-consumer recycled resin streams. Single-source vulnerability from China manufacturing concentration threatens supply continuity. Distribution runs through consolidated retail procurement teams and third-party logistics networks serving e-commerce fulfillment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Packaging and Packaging Waste Regulation design-for-recycling mandates are disrupting substrate hierarchies and procurement scorecards, creating asymmetric opportunity for early-compliant converters. This regulatory inflection compresses traditional competitive moats around unit cost optimization.
For Market Incumbents: Shield market position through captive resin sourcing and backward integration into post-consumer recycled content streams. Defend against margin compression by accelerating biodegradable film processing capacity additions in Germany and the United States. Prioritize ISO 11607 certification maintenance as hospital supplier consolidation intensifies.
For New Entrants and Emerging Players: Anchor in India quick-service dining penetration where FSSAI packaging norm tightening displaces loose plastic with paper-based gusseted formats. Target tier-2 city food courts with hot-melt handle attachment expertise as the most penetrable white space. Pursue white-label partnerships with established European multiwall converters to bypass BRCGS certification timeline barriers.
For Investors and Strategic Acquirers: Extended producer responsibility fee structure emergence in United States state legislatures reshapes the acquisition landscape toward converters with pre-qualified sustainability documentation systems. Five-to-ten year viability favors mid-cap specialists with laboratory in-house capability over commodity virgin-resin-dependent operators. Acquisition target archetype: converters with existing How2Recycle pre-qualification and blown film lines configurable for rPE/rPP. The signal to monitor is state-level EPR framework adoption velocity beyond California and New York.
| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Film Capacity Expansion | ASTM D6400 certification captures municipal procurement gates in California and New York state markets. |
| Backward Integration into Recycled Resin Sourcing | Walmart and Target supplier scorecard compliance requires verified post-consumer content thresholds. |
| Healthcare Sterilization Compatibility Investment | ISO 11607 traceability captures surgical kit packaging spend as hospital systems consolidate. |
| Multiwall Paper Adhesive Formulation Acquisition | Hot-melt handle expertise scarcity in Europe and Japan creates defensive moat for qualified operators. |
| Extended Producer Responsibility Early Compliance | State-level EPR framework positioning secures preferred retail procurement status before mandate expansion. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with retail procurement managers, blown film extrusion plant engineers, FDA regulatory affairs specialists, and healthcare packaging compliance officers. Secondary validation drew from FDA food-contact substance filings, EPA state implementation plans for plastic waste reduction, EU Packaging and Packaging Waste Regulation documentation, and customs trade data on resin and converted bag flows. Bottom-up capacity modeling triangulated against top-down demand segmentation across product type, end user, capacity tier, and packaging format dimensions.
Across the analysis window, volume and value outputs reflect analytical framework segmentation by material substrate, certification grade, regional regulatory cluster, and fulfillment channel automation level. CAGRs were derived from trend extrapolation moderated by regulatory inflection timing and capacity expansion pipeline visibility. Industry-specific forecast inputs incorporated e-commerce fulfillment center buildout rates and state-level plastic bag ban implementation schedules.
Decision-makers should treat outputs as directional under base assumptions of sustained regulatory tightening and recycled-content infrastructure maturation; material deviation would warrant model refresh. Specific risk factors include resin price volatility correlated with crude oil indices, China export logistics disruption, and biodegradable film processing yield uncertainty. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Lunch Boxes and Lunch Bags Market
Bags and Containers
Shrink Bags Market
Bags and Containers
Baggage Packaging Service Market
Bags and Containers
Piping Bags Market
Bags and Containers
Wooden Boxes Market
Bags and Containers
4-Loop FIBC Market
Bags and Containers
Padding Bags Market
Bags and Containers
Bag & Bag Aerosol Can Market
Bags and Containers
Global Bubble Lined Courier Bag Market
Bags and Containers
Lay Flat Bags Market
Bags and Containers
Isothermal Bags and Containers Market
Bags and Containers
Pasted Valve Bags Market
Bags and Containers
Bag Clips Market
Bags and Containers
Cooler Bags Market
Bags and Containers
Commodity Liners Market
Bags and Containers
Multiwall Bags Market