
 Air Bubble Bags Market | 2026-2036
Air Bubble Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Air Bubble Bags Market Outlook
E-commerce fulfillment channels is reconfiguring procurement patterns for protective packaging across North America and Europe. Sealed Air Corporation leverages its automated packaging systems footprint to control last-mile logistics partnerships. Pregis Corporation anchors its position through specialized cushioning films engineered for fragile electronics transit. Smurfit Kappa Group competes by integrating paper-based alternatives alongside traditional bubble formats.
Air bubble bags are flexible packaging enclosures fabricated from polyethylene film with trapped air pockets ranging from 3/16 inch to 1/2 inch in diameter, designed to absorb shock and prevent surface abrasion during transit. The manufacturing process employs extrusion lamination of two LDPE layers with vacuum-formed hemispherical chambers sealed at regular intervals. Self-seal pouches dominate unit volume in pharmaceutical distribution due to contamination-control requirements. Recycled film formulations command premium positioning as brand owners face Scope 3 emissions scrutiny. Bubble mailers sustain the fastest growth trajectory within e-commerce subscription box fulfillment.
The EPA regulates volatile organic compound emissions from polyethylene extrusion operations under Clean Air Act standards, while the EU Packaging and Packaging Waste Directive mandates minimum recycled content thresholds for plastic cushioning materials. California's SB 54 extended producer responsibility framework shapes product design decisions for manufacturers distributing into the United States' largest consumer economy. Stakeholders must monitor evolving extended producer responsibility schemes to determine whether mechanical recycling infrastructure or chemical recycling partnerships offer superior compliance pathways.
Market Dynamics
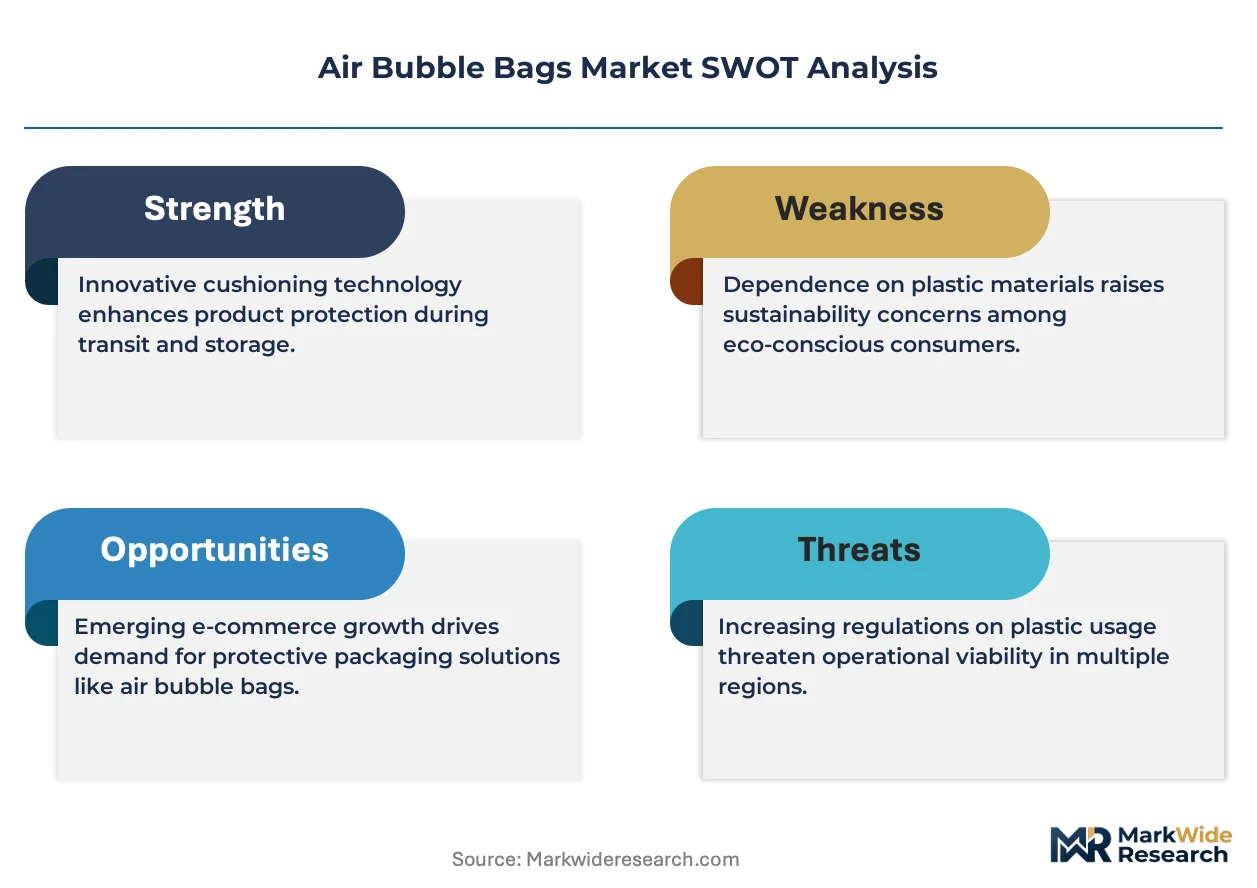
The EU Packaging and Packaging Waste Regulation is forcing polyethylene cushioning manufacturers to reconfigure film formulations and recyclability claims ahead of 2030 mandates, while e-commerce parcel density concentrates procurement power among fulfillment center operators.
Growth Catalysts
- Extended Producer Responsibility schemes:California's SB 54 framework and the EU PPWR directive create compliance-driven replacement cycles for non-recyclable legacy cushioning. Brand owners face Scope 3 emissions scrutiny that elevates recycled-content bubble films.
- Automotive parts logistics:Germany's Ruhr logistics corridor generates concentrated demand for high-performance void-fill solutions protecting precision components during multimodal transit. Tier-1 suppliers specify certified cushioning performance.
- Pharmaceutical cold chain expansion:Self-seal bubble pouches capture unit volume in temperature-sensitive drug distribution. Contamination-control requirements favor sealed cushioning over loose-fill alternatives.
Market Restraints
- LDPE resin price volatility:Ethylene feedstock costs fluctuate with crude oil and natural gas liquid pricing, compressing converter margins during upstream spikes. Long-term supply agreements with petrochemical producers offer partial hedging.
- Mechanical recycling infrastructure gaps:Post-consumer polyethylene film collection and reprocessing capacity concentrates in Germany, the Netherlands, and select US Gulf Coast hubs. Regional supply-demand imbalances strand material in non-compliant jurisdictions.
- Paper-based substitution threat:Smurfit Kappa and Mondi Group expand molded fiber and corrugated bubble alternatives targeting premium unboxing experiences. E-commerce fashion and cosmetics verticals pilot paper cushioning at scale.
Strategic Opportunities
- Chemical recycling partnerships:Pyrolysis and depolymerization investments by Shell, Dow, and SABIC enable food-grade recycled polyethylene feedstock. Air bubble bag converters secure offtake agreements for circular material claims.
- Subscription box fulfillment:Bubble mailers sustain volume growth in curated e-commerce channels requiring branded, damage-resistant presentation. Custom-printed films command price premiums over commodity clear bubble.
- India logistics modernization:Reliance Retail and Flipkart expand fulfillment center networks driving protective packaging procurement. Domestic LDPE film extrusion capacity scales to serve this demand.
Industry Challenges
- Multi-layer film delamination:Separating polyethylene from nylon or EVOH barrier layers in coextruded cushioning complicates mechanical recycling. Sorting technology and design-for-recycling protocols lag material innovation.
- Automated packaging system integration:Sealed Air's Pregis and Ranpak equipment requires dimensional tolerance calibration for custom bubble sizes. Converter technical service teams face capacity constraints supporting retrofit installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Bubble Bags Market |
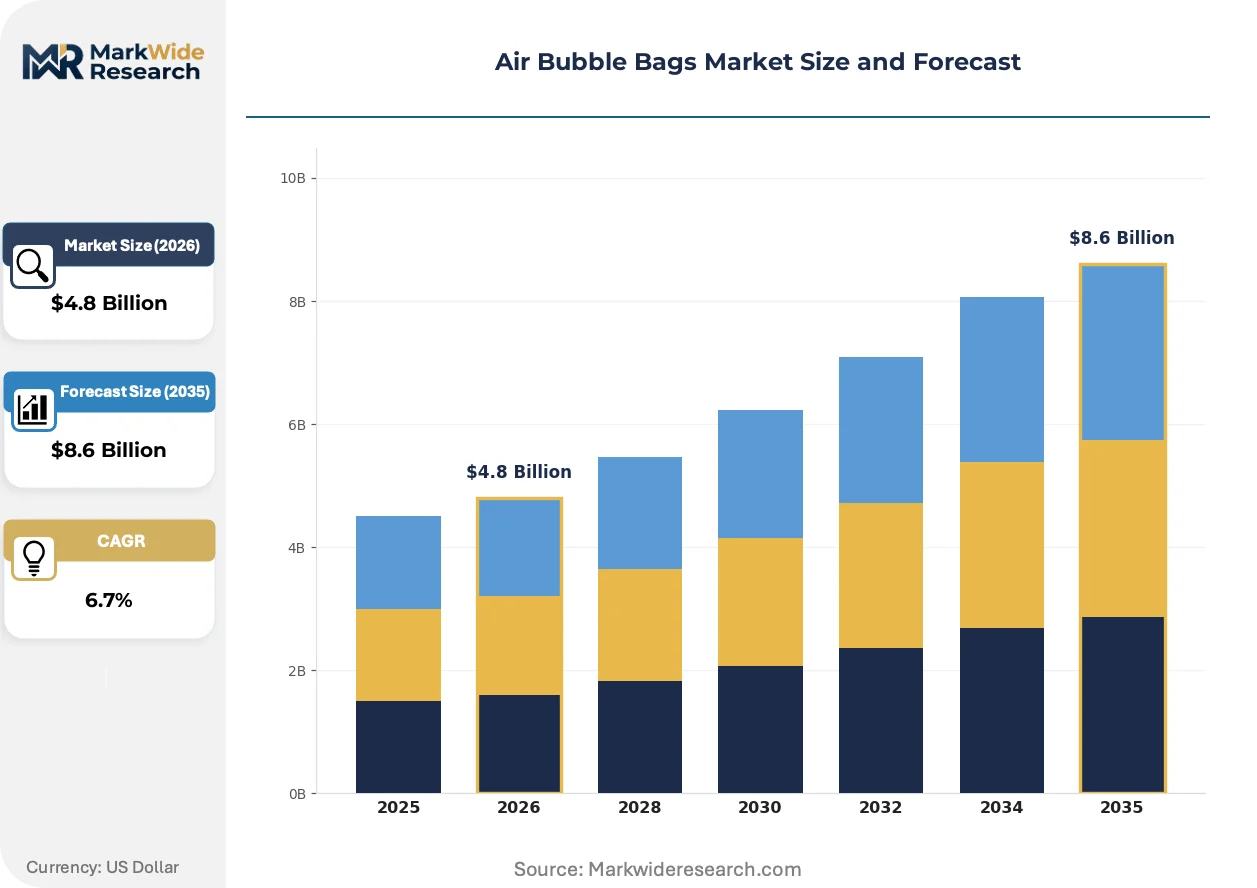
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Seal Pouches, Bubble Wrap Rolls, Bubble Mailers, Air Column Bags Material: Polyethylene, Polypropylene, Recycled Film, Foam End User: Retail, E-Commerce, Electronics, Pharmaceuticals Application: Packaging, Cushioning, Void Fill, Protective Shipping |
| Companies Covered | Sealed Air Corporation, Pregis Corporation, Storopack Hans Reichenecker GmbH, Smurfit Kappa Group, Intertape Polymer Group, FP International, Automated Packaging Systems, Polyair Interpack, AeroPack Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Bubble Bags Market Strategic Shifts
Digital tracking technologies and regulatory compliance automation are reshaping how polyethylene cushioning manufacturers verify recyclability claims and manage extended producer responsibility obligations across fragmented jurisdiction requirements.
Blockchain-enabled material provenance systems are digitizing supply chain transparency for recycled-content bubble films. Major e-commerce platforms and third-party logistics providers pilot these verification tools to satisfy corporate sustainability reporting under the EU CSRD. The technology is digitizing audit workflows that previously relied on paper certificates and supplier attestations.
REACH restrictions on intentionally added microplastics extend to loose-fill expanded polystyrene alternatives, accelerating specification shifts toward air bubble cushioning in European electronics distribution. The regulation compresses allowable particle migration thresholds for protective packaging. German and French electronics retailers now mandate supplier documentation proving compliance with migration test protocols.
Direct procurement relationships between polyethylene film converters and e-commerce fulfillment networks are displacing traditional distribution through industrial packaging distributors. Amazon, Zalando, and Otto Group negotiate volume commitments specifying recycled-content minimums and carbon intensity metrics. This concentration is most visible in the Netherlands and Belgium, where automated sortation hubs cluster near Rotterdam port logistics infrastructure.
Air Bubble Bags Market Segmentation
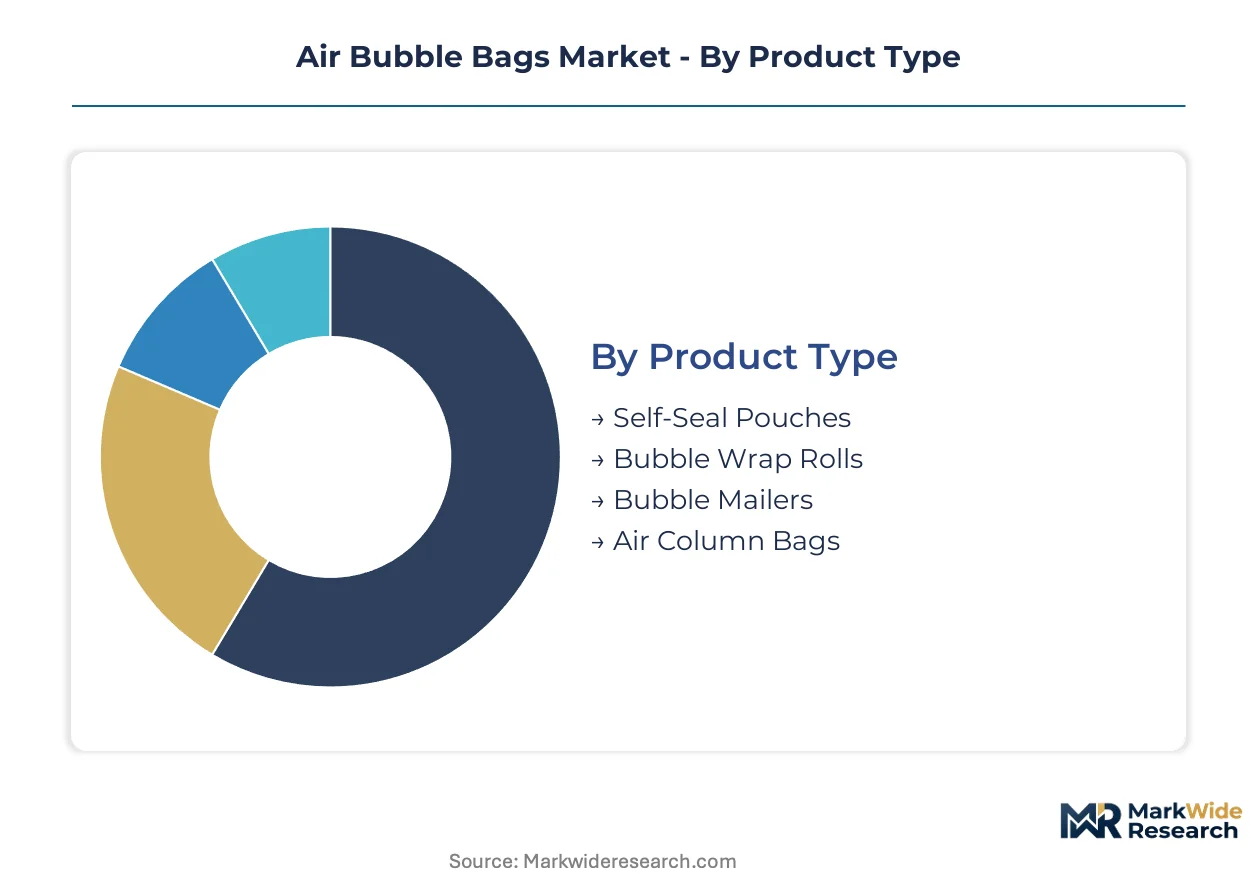
Air bubble bag procurement patterns diverge sharply across product formats, material specifications, and end-use verticals. Understanding these segment boundaries reveals where converter margins concentrate and where compliance-driven substitution risks emerge.
Product Type:
Mature formats dominate established logistics channels while emerging configurations capture e-commerce growth pockets.
- Self-Seal Pouches:These LDPE enclosures feature integrated adhesive strips enabling tamper-evident closure without additional sealing equipment. Pharmaceutical distributors in Germany's cold chain corridors specify these pouches for temperature-sensitive biologics requiring contamination barriers.
- Bubble Mailers:Laminated kraft-polyethylene hybrid envelopes combine rigid outer shells with internal bubble cushioning layers. Subscription box fulfillment operators in the Netherlands and Belgium negotiate direct volume commitments specifying custom-printed films and recycled-content minimums.
- Bubble Wrap Rolls:Continuous perforated sheeting remains the default for industrial void-fill operations with existing dispenser infrastructure.
- Air Column Bags:Inflatable chamber configurations target fragile electronics requiring corner-specific protection during multimodal transit.
Self-seal pouches handle the majority of throughput; bubble mailers are the fastest mover on share.
Material:
Cost tier stratification separates commodity resin formulations from certified circular alternatives commanding procurement premiums.
- Polyethylene:LDPE and LLDPE resins constitute the baseline extrusion feedstock for bubble film production, with density grades selected for specific puncture resistance requirements. Converters along the US Gulf Coast maintain long-term supply agreements with petrochemical producers to hedge ethylene feedstock volatility.
- Recycled Film:Post-industrial and post-consumer polyethylene reprocessing yields food-grade feedstock through mechanical or chemical recycling pathways. EU Packaging and Packaging Waste Regulation mandates are forcing brand owners to specify minimum recycled content thresholds ahead of 2030 compliance deadlines.
- Polypropylene:Higher stiffness and temperature resistance suits autoclave-sterilizable medical device packaging applications.
- Foam:Expanded polyethylene foam alternatives compete in heavy-duty industrial cushioning where repeated impact absorption exceeds bubble film durability limits.
Polyethylene handles the majority of throughput; recycled film is expanding most quickly as compliance deadlines approach.
End User:
Customer type concentration determines whether procurement runs through industrial distributors or direct converter negotiations.
- E-Commerce:Fulfillment center operators including Amazon, Zalando, and Otto Group consolidate protective packaging procurement across automated sortation hubs. Rotterdam port logistics infrastructure anchors European demand concentration where parcel density justifies direct converter relationships.
- Electronics:German and French retailers now mandate supplier documentation proving REACH compliance with microplastic migration test protocols, displacing loose-fill polystyrene alternatives.
- Retail:Brick-and-mortar distribution networks rely on standardized cushioning specifications through traditional packaging distributors.
- Pharmaceuticals:Cold chain expansion drives specification of self-seal pouches with barrier properties against moisture and temperature excursion.
E-commerce handles the majority of throughput; electronics is climbing the fastest as regulatory substitution accelerates.
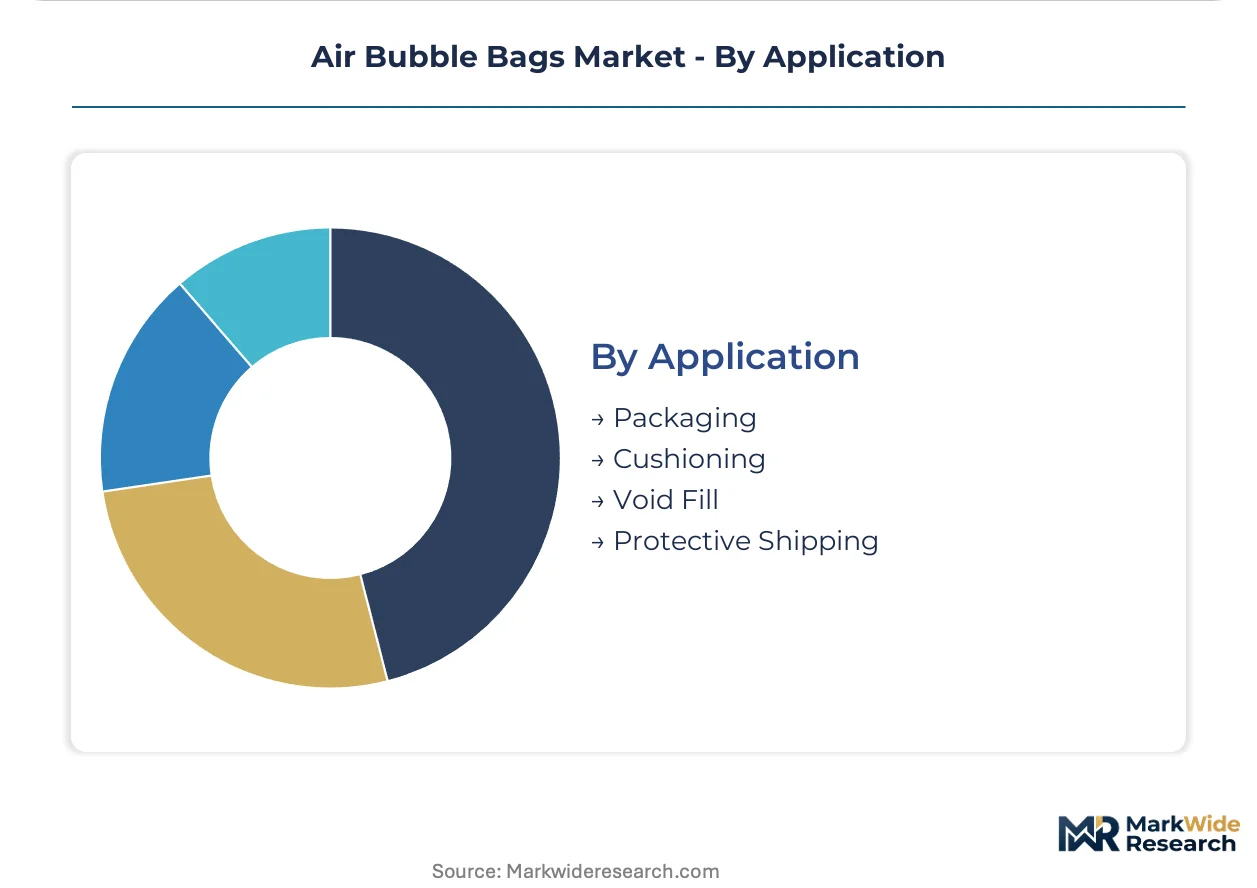
Application:
Functional use case determines performance specifications and margin capture potential across the value chain.
- Protective Shipping:Multi-layer coextruded films with nylon or EVOH barriers protect precision automotive components traversing Germany's Ruhr logistics corridor. Tier-1 suppliers specify certified cushioning performance validated through drop-test protocols.
- Void Fill:Loose-fill bubble configurations absorb dimensional irregularities in heterogeneous parcel contents. California's SB 54 extended producer responsibility framework shapes product design decisions for converters distributing into the United States' largest consumer economy.
- Packaging:Primary enclosure functions require seal integrity and print compatibility for branding requirements.
- Cushioning:Impact absorption specifications vary by fragility index of contained products, from glassware to semiconductor components.
Protective shipping handles the majority of throughput; void fill is gaining share fastest as e-commerce parcel volumes surge.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Extended producer responsibility schemes in California and the EU are redirecting procurement toward recycled-content cushioning. E-commerce fulfillment density now determines regional demand concentration more than manufacturing proximity.
United States
Amazon's fulfillment network expansion drives protective packaging procurement across Texas, California, and Illinois distribution clusters. California's SB 54 extended producer responsibility framework mandates minimum recycled content thresholds for plastic cushioning materials. The Dallas-Fort Worth logistics corridor concentrates automated sortation hub investment where parcel volumes justify direct converter relationships.
Germany
Automotive parts distributors along the Ruhr logistics corridor specify certified cushioning performance for precision components in multimodal transit. REACH restrictions on intentionally added microplastics accelerate displacement of loose-fill polystyrene alternatives. Hamburg's port infrastructure anchors cold chain pharmaceutical distribution using self-seal bubble pouches with barrier properties.
China
Reliance Retail and domestic e-commerce platforms expand fulfillment center networks driving LDPE film extrusion capacity scaling. The country's dual carbon goals pressure converters toward mechanical and chemical recycling feedstock integration. Yangtze River Delta manufacturing clusters serve both domestic logistics modernization and export packaging demand.
Netherlands
Rotterdam port logistics infrastructure anchors European automated sortation hub concentration where Zalando and Otto Group negotiate direct volume commitments. The EU Packaging and Packaging Waste Regulation mandates recyclability claims verification ahead of 2030 compliance deadlines. Eindhoven's electronics distribution corridor specifies REACH-compliant cushioning documentation for German and French retail contracts.
India
Flipkart and Reliance Retail fulfillment center expansion drives protective packaging procurement across Maharashtra and Karnataka state networks. The Bureau of Indian Standards regulates polyethylene film specifications for food-contact and industrial applications. Mumbai-Pune logistics corridor development concentrates void-fill demand from automotive component suppliers.
Air Bubble Bags Market Competitive Environment
On the supply side, the industry is consolidating around automated packaging system integrators and specialized film converters with recycling infrastructure partnerships. Three strategic archetypes dominate: multinational cushioning specialists with equipment-software integration capabilities, regional LDPE extrusion converters serving e-commerce fulfillment networks, and paper-based packaging conglomerates diversifying into hybrid bubble formats. Competitive positioning hinges on securing chemical recycling offtake agreements and embedding technical service teams within automated packaging retrofit installations.
Among North American-based multinationals, Sealed Air Corporation and Pregis Corporation exemplify the equipment-integrated archetype, leveraging automated packaging systems footprints to anchor last-mile logistics partnerships. Storopack Hans Reichenecker GmbH represents the European specialist model, while Smurfit Kappa Group occupies a position bridging paper-based alternatives with traditional bubble formats. These three anchors illustrate how geographic origin and corporate structure shape competitive approach without determining specific strategic outcomes.
| Leading Market Players |
|---|
| Sealed Air Corporation |
| Pregis Corporation |
| Storopack Hans Reichenecker GmbH |
| Smurfit Kappa Group |
| Intertape Polymer Group |
| FP International |
| Automated Packaging Systems |
| Polyair Interpack |
| AeroPack Industries |
| Others |
Value Chain & Pricing Dynamics
The US Gulf Coast petrochemical corridor concentrates LDPE resin capacity, giving converters with long-term ethylene supply agreements leverage over spot-market competitors serving e-commerce fulfillment networks. This upstream concentration cascades into tiered pricing power across bubble film grades, where mechanical recycling infrastructure access separates premium recycled-content suppliers from commodity producers facing margin compression.
Pricing Analysis
Certification level creates the primary spread, with EU PPWR-compliant recycled-content films commanding procurement premiums over virgin LDPE alternatives. Three-tier pricing structure separates pharmaceutical-grade barrier pouches, standard e-commerce bubble mailers, and industrial void-fill rolls. Pricing pressure stems from paper-based substitution in fashion and cosmetics verticals, squeezing mid-grade polyethylene margins. Small-batch pharmaceutical distributors show lowest price sensitivity; high-volume fulfillment operators negotiate hardest on unit economics.
Supply Chain Analysis
Extended payment terms from e-commerce platforms strain converter working capital, driving supply-chain finance facility adoption among mid-tier extruders. Manufacturing concentrates in Germany, the Netherlands, and the US Gulf Coast, with China's Yangtze River Delta scaling domestic capacity. Feedstock draws from naphtha crackers and natural gas liquids, tethering margins to crude oil volatility. Single-source vulnerability runs through specialized barrier film coextrusion equipment. Distribution runs through direct procurement relationships with fulfillment hubs, displacing traditional industrial packaging distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized technical service capacity for automated packaging system integration represents the critical scarcity, as converter engineering teams face backlog constraints supporting e-commerce fulfillment retrofit installations.
For Market Incumbents: Build chemical recycling offtake moats through partnerships with Shell, Dow, or SABIC pyrolysis facilities, securing circular material claims ahead of EU PPWR mandates. Anchor automated packaging equipment-software integration capabilities within Sealed Air and Pregis technical service footprints to defend against paper-based substitution threats from Smurfit Kappa. Add capacity in India's Maharashtra corridor to capture Flipkart and Reliance Retail fulfillment center procurement. For New Entrants and Emerging Players: Pursue India logistics modernization white space, where domestic LDPE extrusion capacity lags Flipkart and Reliance Retail fulfillment network expansion. Target pharmaceutical cold chain self-seal pouches in Germany's Hamburg corridor, where contamination-control requirements favor sealed cushioning over loose-fill alternatives. Lead with blockchain-enabled material provenance verification to satisfy EU CSRD corporate sustainability reporting requirements. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors equipment-integrated cushioning specialists with recycling infrastructure partnerships over pure-play film converters. Long-term viability hinges on chemical recycling feedstock access and automated packaging system retrofit capabilities. Watch for REACH microplastic migration test protocol enforcement acceleration as inflection signal for paper-based substitution pace.| Strategic Initiative | Industry Significance |
|---|---|
| Chemical Recycling Partnership | Pyrolysis offtake agreements with Shell enable food-grade recycled polyethylene feedstock claims. |
| Automated Packaging Integration | Technical service teams embedded in Amazon fulfillment hubs secure last-mile logistics relationships. |
| India Capacity Expansion | Domestic LDPE film extrusion scaling serves Flipkart and Reliance Retail procurement demand. |
| Blockchain Provenance System | Digital audit workflows satisfy EU CSRD sustainability reporting for Zalando and Otto Group. |
| Pharmaceutical Barrier Pouch Development | Self-seal configurations with EVOH layers capture Germany cold chain biologics distribution. |
Study Parameters
A standing panel of LDPE film extrusion plant managers, e-commerce fulfillment center procurement leads, pharmaceutical cold chain logistics directors, and automotive Tier-1 supplier packaging engineers provided ongoing calibration. Primary interview insights triangulated against secondary validation from US EPA Clean Air Act enforcement records, EU ECHA REACH restriction filings, SEC 10-K disclosures from petrochemical producers, and customs trade data tracking polyethylene resin flows. Bottom-up segment sizing and top-down macroeconomic anchoring converged through iterative reconciliation.
Scenario-bracketing framed low, base, and high cases across the projection horizon, with segmentation modeling across product type, material specification, end-use vertical, and geographic fulfillment hub density. CAGRs derived from trend extrapolation of e-commerce parcel volume growth, regulatory compliance deadline impacts, and resin cost pass-through elasticity. Industry-specific forecast inputs included automated packaging equipment installation rates and mechanical recycling infrastructure capacity buildout timelines.
Sensitivities concentrate around EU PPWR enforcement timing, crude oil price volatility affecting ethylene feedstock costs, and paper-based substitution acceleration in fashion and cosmetics verticals. Forecasts reflect documented assumptions regarding regulatory implementation schedules and technology adoption curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Garbage Bag Market
Bags and Containers
Wicketed Bags Market
Bags and Containers
Flip-Up Vacuum Pack Market
Bags and Containers
Bag-In-Box Market
Bags and Containers
Leno Bags Market
Bags and Containers
Bulk Bag Unloaders Market
Bags and Containers
Woven Sacks Market
Bags and Containers
Non-Laminated Heat-Sealed Bags Market
Bags and Containers
Bagster Bag Market
Bags and Containers
Inflatable Bags Packaging Market
Bags and Containers
Bag on Valve Technology Market
Bags and Containers
Multiwall Bags Market
Bags and Containers
Side Weld Bags Market
Bags and Containers
Bulk Bag Conditioners Market
Bags and Containers
Anti-Static Polyethylene Bag Market
Bags and Containers
Pasted Valve Bags Market