
 Bag-In-Box Filler Market | 2026-2036
Bag-In-Box Filler Market Size, Share, and Industry Trends Forecast 2026-2036
Bag-In-Box Filler Market Outlook
Preventive maintenance contracts is hardening into a standalone revenue stream for equipment vendors serving high-volume beverage co-packers. Smurfit Kappa Group leverages its integrated packaging portfolio to bundle filler systems with corrugated outer-box supply. IC Filling Systems anchors its competitive stance through specialized engineering for wine and edible-oil applications. Codi Manufacturing dominates the North American installed base with region-specific service networks.
A bag-in-box filler is an automated or semi-automated machine that dispenses liquid product through a spout into a collapsible inner bag while evacuating air, typically achieving fill accuracies within plus or minus one percent and handling viscosities from water-thin oils to high-solids sauces. The equipment serves commercial producers seeking extended shelf life, reduced shipping weight, and retail-ready dispensing formats. Automatic systems lead unit shipments among product types due to labor-cost pressures in European and North American beverage bottling. Pneumatic technology occupies the largest installed base for wine and juice applications, while electric drive systems are gaining share in pharmaceutical and personal care lines where cleanroom compatibility matters. The food and beverage end-user segment sustains the deepest replacement cycle, though chemical handlers are emerging as a faster-growing buyer category for corrosion-resistant filler configurations.
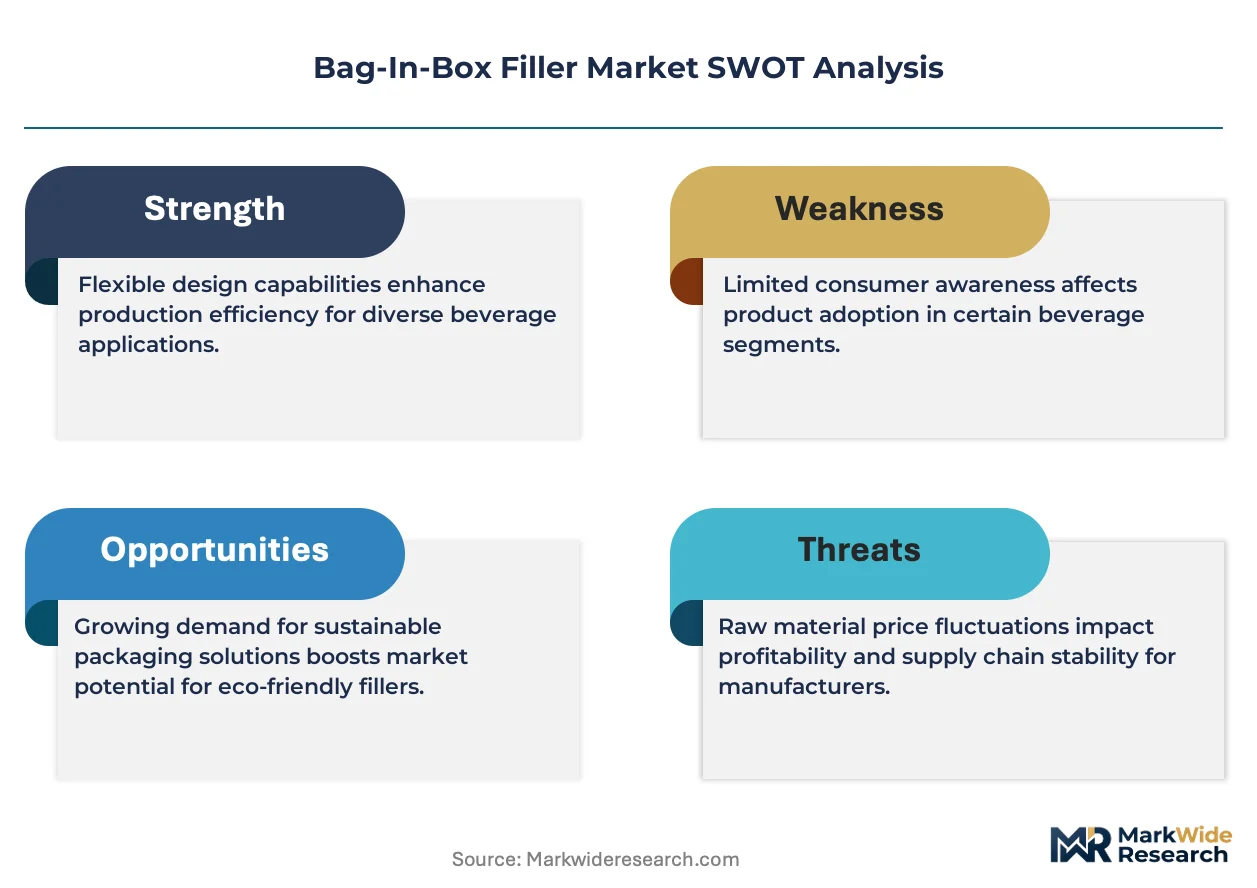
FDA food-contact substance notifications shape material selection for bags and spouts in US liquid-food applications, while EU REACH and F-Gas Regulation constrain refrigerant choices in cooled-fill processes for dairy and wine. BIS certification requirements in India limit market entry for non-compliant European and Chinese equipment suppliers. Stakeholders must weigh regulatory divergence against platform standardization when configuring regional product portfolios and service infrastructures.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing material specifications for bag-in-box formats, forcing wine and spirits producers to accelerate capital deployment toward automated filling lines that eliminate rigid bottle dependency.
Growth Catalysts
- REACH material compliance:European chemical registration mandates are disqualifying legacy bag films, creating replacement demand for spout-sealing equipment compatible with next-generation barrier polymers.
- Wine co-packer automation:French and Italian premium bottling facilities are retiring semi-automatic equipment to meet supermarket private-label volume commitments.
- Corrugated bundling economics:Outer-box integration with filler systems is reducing per-unit handling labor and damage rates in beverage distribution.
Market Restraints
- Stainless steel input volatility:Grade 316L surcharges for corrosion-resistant filler contact surfaces are compressing equipment margin structures.
- Service network concentration:North American aftermarket support clusters in the Upper Midwest and California, leaving Gulf Coast chemical handlers with extended downtime exposure.
- Glass bottle residual preference:Sparkling wine and prestige spirits segments in Italy and Spain maintain format loyalty that limits bag-in-box penetration.
Strategic Opportunities
- Indian FSSAI packaged food expansion:Edible oil and dairy processors in Maharashtra and Gujarat are converting from tin to bag-in-box for institutional channel supply.
- Electric-pneumatic hybrid architectures:Convergence of servo-driven filling heads with compressed-air evacuation is opening pharmaceutical cleanroom applications.
- IRA clean manufacturing credits:US beverage equipment purchasers can offset capital costs for energy-efficient filler retrofits qualifying under domestic content provisions.
Industry Challenges
- Mechatronics technician scarcity:European filler OEMs face 14-week lead times for field service engineers capable of diagnosing PLC-spout alignment faults.
- Multi-standard certification lag:Simultaneous FDA food-contact, EU 1935/2004, and BIS IS 9845 compliance for export-oriented Indian equipment vendors extends product launch timelines.
- Legacy DOS-control integration:1990s-vintage filler bases in California wine country require custom gateway hardware for Industry 4.0 data extraction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bag-In-Box Filler Market |
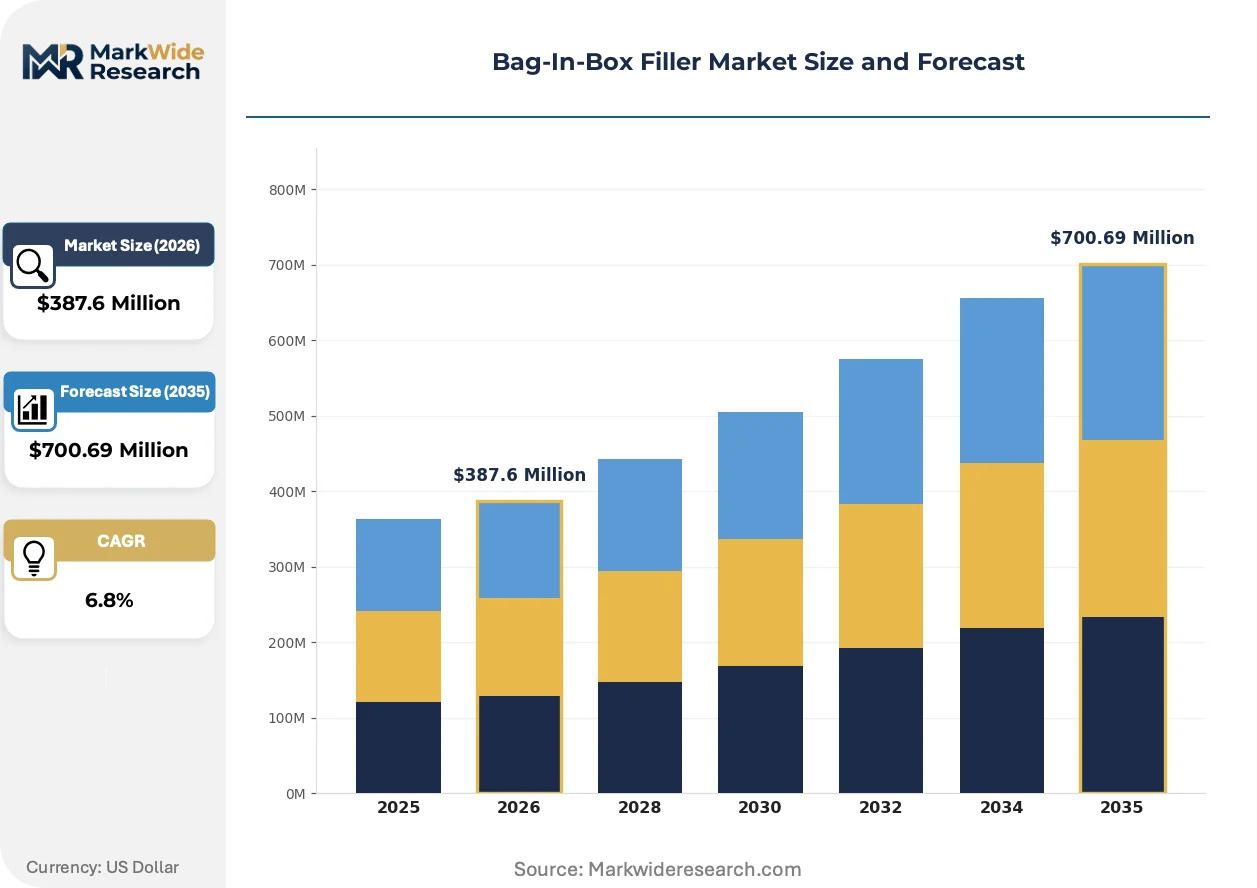
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Semi-Automatic, Manual, Portable End User: Food & Beverage, Chemicals, Pharmaceuticals, Personal Care Technology: Pneumatic, Electric, Hydraulic, Mechanical Container Size: 1L, 5L, 10L, 20L |
| Companies Covered | Smurfit Kappa Group, DS Smith, IC Filling Systems, TORR Industries, Codi Manufacturing, Flexifill, Sacmi Group, Della Toffola Group, A TriMas Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bag-In-Box Filler Market Strategic Shifts
Equipment architecture is bifurcating between pneumatic workhorses for high-volume beverage lines and precision electric systems for regulated pharmaceutical environments, with control software becoming the primary differentiation vector.
Servo-driven filling heads with real-time load-cell feedback are electrifying accuracy benchmarks in personal care and pharmaceutical applications. German and Swiss cosmetic contract manufacturers are specifying these systems for 0.3% fill-tolerance requirements. The technology is compressing changeover times between SKUs from 45 minutes to under 8 minutes.
EU F-Gas Regulation phase-down schedules are refrigerant choices for cooled-fill dairy and wine equipment, pushing vendors toward CO2 cascade systems. Italian prosecco co-packers are retrofitting existing lines to maintain fill temperatures below 8°C without hydrofluorocarbon dependency. The compliance burden falls heaviest on mid-volume producers with single-product lines lacking capital for full replacement.
After-sales service unbundling is accelerating among North American beverage co-packers. Large multi-site operators in Washington and Oregon are negotiating standalone preventive maintenance contracts separate from equipment purchase, displacing traditional warranty-bundled service models. The shift is most visible in wine regions with concentrated seasonal demand spikes requiring guaranteed technician availability.
Bag-In-Box Filler Market Segmentation
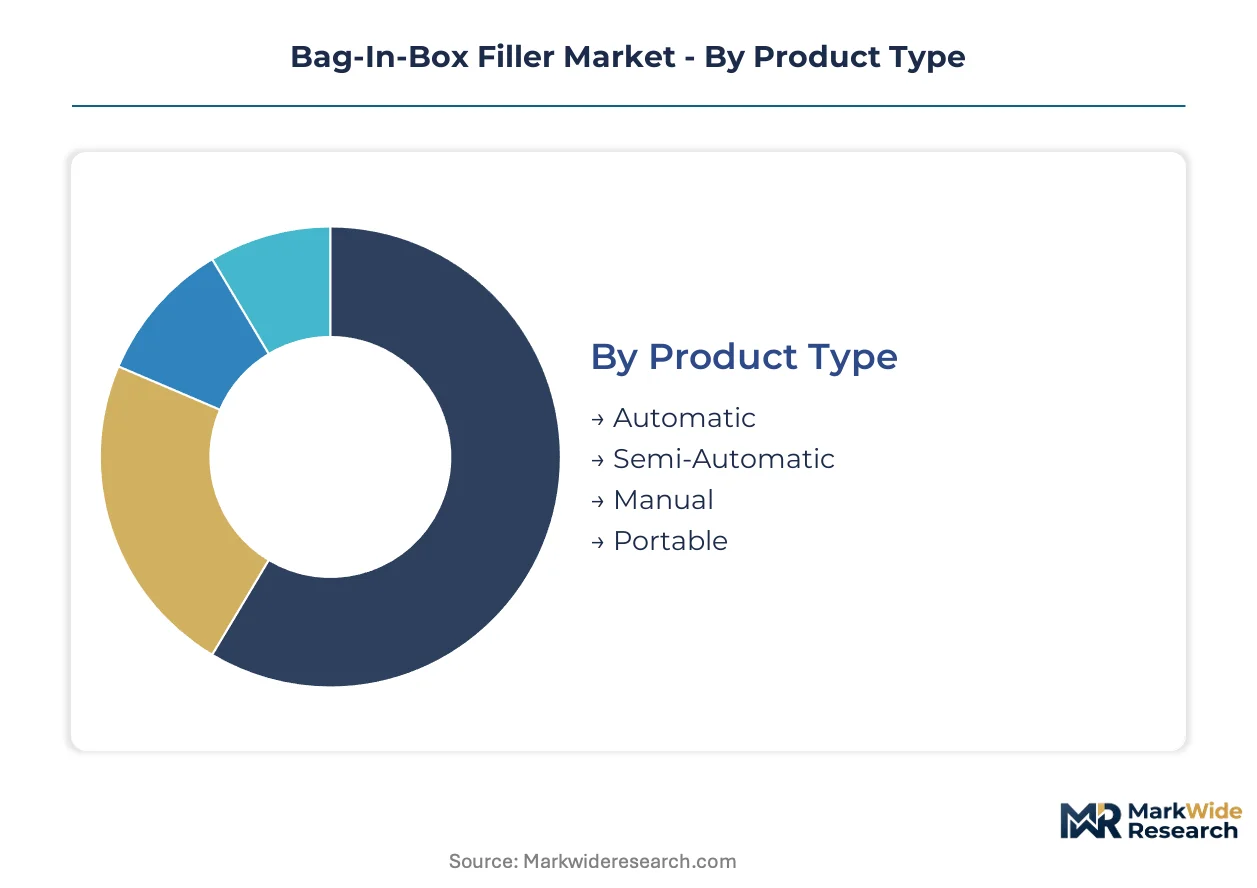
Bag-in-box filler procurement splits sharply between high-volume beverage co-packers seeking throughput maximization and specialty chemical handlers prioritizing containment integrity. Equipment specification cascades through four interdependent dimensions that determine capital allocation priorities and vendor selection criteria.
Product Type:
Capital intensity peaks with fully integrated automatic lines requiring precision spout-sealing robotics and evacuated-chamber architecture, while manual configurations demand minimal upfront outlay.
- Automatic:These systems integrate PLC-controlled filling heads with real-time load-cell feedback and automated spout insertion, achieving fill accuracies within one percent at throughputs exceeding 1200 bags hourly. French and Italian wine co-packers dominate order books as EU packaging waste regulations compress acceptable material specifications and labor costs harden.
- Semi-Automatic:Operators manually position bags while automated heads execute filling and sealing sequences, bridging cost and precision for mid-volume producers. German edible-oil processors in Bavaria favor this tier for seasonal SKU flexibility without full automation expenditure.
- Manual:Foot-pedal or hand-lever actuated units suit micro-producers and pilot lines with volumes below 5000 bags annually.
- Portable:Castor-mounted configurations serve mobile co-packing operations and temporary production lines in event catering and festival supply.
Most installed capacity flows through Automatic systems. Expansion is steepest in Semi-Automatic as mid-tier producers defer full automation commitments.
End User:
Application severity determines corrosion-resistant material specifications and cleanroom compatibility requirements across buyer categories.
- Food & Beverage:Wine, juice, and edible-oil handlers constitute the deepest replacement cycle, with European producers retiring 1990s-vintage equipment under regulatory pressure. FDA food-contact substance notifications and EU 1935/2004 compliance frame material selection for bags and spouts.
- Chemicals:Aggressive solvent and agricultural chemical handlers are emerging as a faster-growing buyer category, demanding 316L stainless contact surfaces and nitrogen-purged filling chambers. Gulf Coast US chemical processors face extended downtime exposure due to concentrated service network geography.
- Pharmaceuticals:Cleanroom-compatible electric drive systems with servo-controlled accuracy satisfy parenteral and ophthalmic liquid packaging.
- Personal Care:Cosmetic contract manufacturers in Switzerland and Germany specify 0.3% fill-tolerance systems for premium lotion and serum formats.
Food & Beverage retains the largest installed base. Chemicals is gaining share fastest as corrosion-resistant configurations penetrate agricultural and industrial solvent applications.
Technology:
Drive architecture selection trades compressed-air reliability against electric precision, with hybrid configurations emerging at the boundary.
- Pneumatic:Compressed-air evacuation and actuation dominate wine and juice applications, leveraging established maintenance protocols and lower capital cost. Italian prosecco co-packers retrofit existing pneumatic bases to accommodate CO2 cascade cooling under EU F-Gas Regulation phase-down schedules.
- Electric:Servo-driven filling heads with real-time feedback compress changeover times from 45 minutes to under 8 minutes, satisfying pharmaceutical and personal care accuracy demands.
- Hydraulic:High-force actuation serves viscous high-solids sauces and industrial adhesives where pneumatic pressure proves insufficient.
- Mechanical:Cam-and-linkage simplicity persists in emerging-market manual equipment where electrical infrastructure is unreliable.
Pneumatic systems anchor the majority of operating units. Electric configurations are expanding most quickly in regulated pharmaceutical and cosmetic environments.
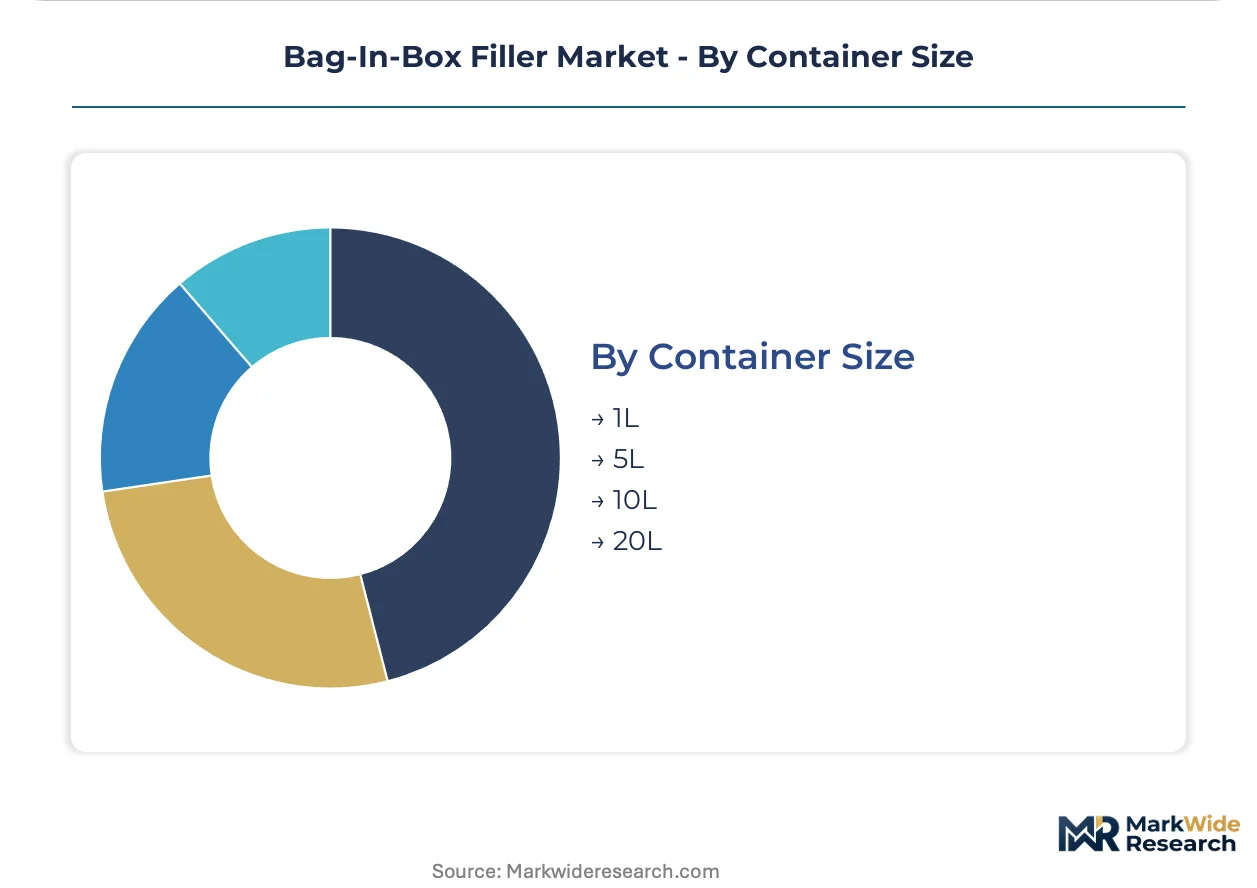
Container Size:
Volume specification correlates directly with end-use channel economics, from single-serve retail to institutional bulk supply.
- 1L:Single-serve retail formats for premium wine and personal care samples require precision low-volume filling heads with minimal product loss.
- 5L:Family-size beverage and edible-oil formats concentrate demand in European supermarket private-label supply.
- 10L:Foodservice and institutional channels in Maharashtra and Gujarat, India, favor this tier as FSSAI packaged food expansion accelerates tin-to-bag conversion for edible oil.
- 20L:Maximum-volume configurations serve industrial chemical handlers and winery bulk-to-retail redistribution.
Five-liter and 10-liter formats together carry the majority of shipment volume. Steepest expansion is occurring at 10 liters as Indian institutional channels scale bag-in-box adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France commands premium wine co-packer automation investments while India accelerates edible-oil format conversion, revealing divergent maturity curves across major demand centers.
France
French supermarket private-label volume commitments drive co-packers to retire semi-automatic equipment. EU REACH chemical registration mandates disqualify legacy bag films, forcing spout-sealing upgrades. The Bordeaux and Champagne clusters anchor automated line deployments for premium export formats.
Italy
Italian prosecco producers retrofit pneumatic filler bases with CO2 cascade cooling to satisfy EU F-Gas Regulation phase-down schedules. Sparkling wine segments maintain residual glass preference, constraining bag-in-box penetration in prestige categories. Veneto and Piedmont co-packers concentrate mid-volume equipment orders.
United States
Washington and Oregon wine regions unbundle after-sales service into standalone preventive maintenance contracts. IRA clean manufacturing credits offset capital costs for energy-efficient retrofits qualifying under domestic content provisions. California's Central Valley chemical handlers face extended downtime exposure from concentrated Gulf Coast service networks.
India
Maharashtra and Gujarat edible-oil processors convert from tin to bag-in-box for institutional channel supply under FSSAI packaged food expansion. BIS certification requirements limit market entry for non-compliant European and Chinese equipment suppliers. Mumbai-Pune industrial corridor concentrates 10-liter format adoption.
Germany
Bavarian edible-oil processors favor semi-automatic systems for seasonal SKU flexibility. Swiss and German cosmetic contract manufacturers specify 0.3% fill-tolerance electric systems for premium personal care formats. Baden-Württemberg machinery clusters supply servo-driven filling heads with real-time load-cell feedback.
Bag-In-Box Filler Market Competitive Environment
Top-tier vendors anchor integrated packaging-filler bundling, while mid-tier specialists occupy application-specific niches. The vendor base stratifies across corrugated converters diversifying into equipment, dedicated filling machinery engineers, and regional service-intensive operators. Three archetypes dominate: packaging conglomerates leveraging material supply integration, precision engineering houses targeting pharmaceutical-grade accuracy, and geographically focused aftermarket service providers. Competitive moves concentrate on outer-box bundling economics and preventive maintenance contract unbundling.
Within the packaging-integrated tier, Smurfit Kappa Group exemplifies corrugated bundling strategies that reduce per-unit handling labor. IC Filling Systems and Codi Manufacturing occupy distinct positioning vectors—one anchoring specialized wine and edible-oil engineering, the other dominating North American installed base density through region-specific service networks.
| Leading Market Players |
|---|
| Smurfit Kappa Group |
| DS Smith |
| IC Filling Systems |
| TORR Industries |
| Codi Manufacturing |
| Flexifill |
| Sacmi Group |
| Della Toffola Group |
| A TriMas Company |
| Others |
Value Chain & Pricing Dynamics
Captive corrugated supply integration by Smurfit Kappa Group and DS Smith anchors pricing power through bundled filler-plus-outer-box offerings, compressing procurement cycles for European beverage co-packers facing EU REACH material compliance costs while locking in volume commitments that insulate margin structures from spot-market volatility.
Pricing Analysis
Capacity additions in Germany and Italy are reshaping price floors for servo-driven electric systems as Baden-Württemberg machinery clusters expand output. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade 0.3% tolerance configurations from pneumatic workhorses for wine applications. Cost compression in mid-tier semi-automatic equipment is intensifying because Indian FSSAI expansion draws new entrants into 10-liter format supply. Chemical handlers in the US Gulf Coast exhibit highest price sensitivity due to extended downtime exposure from concentrated service networks, while Swiss cosmetic contract manufacturers show least sensitivity given fill-tolerance specifications.
Supply Chain Analysis
US domestic content provisions under IRA clean manufacturing credits are reshaping sourcing patterns for corrosion-resistant Grade 316L stainless contact surfaces. Component fabrication draws from Germany, Italy, and India, with servo motor assemblies resting on Baden-Württemberg precision engineering and pneumatic valve clusters anchored in Veneto supplier networks. Single-source vulnerability concentrates in specialized spout-sealing robotics sourced from Swiss automation houses. Distribution runs through OEM-direct channels for large co-packer accounts and regional machinery distributors serving mid-volume producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment vendors can exploit geographic arbitrage between EU REACH-driven replacement demand in France and Italy versus first-time adoption curves in Maharashtra and Gujarat, where FSSAI packaged food expansion lags European regulatory stringency by several cost-adjustment cycles.
For Market Incumbents: Hedge against electric-drive disruption in pharmaceutical segments by acquiring servo-control engineering capabilities in Baden-Württemberg or Switzerland. Consolidate aftermarket service density in the US Upper Midwest and California to offset Gulf Coast vulnerability, while bundling preventive maintenance contracts as standalone revenue streams displaces traditional warranty models. For New Entrants and Emerging Players: Beverage co-packer associations in Washington and Oregon offer channel partnership pathways for service-intensive market entry. White-space concentrates in Indian 10-liter edible-oil conversion and US chemical handler corrosion-resistant configurations. Pursue BIS certification pre-commitment to bypass entry barriers blocking non-compliant European and Chinese suppliers. For Investors and Strategic Acquirers: Roll-up economics work for regional service-intensive operators because North American aftermarket support clusters geographically concentrate technician availability. Long-term viability hinges on platform standardization across pneumatic-electric hybrid architectures. Watch EU F-Gas Regulation phase-down schedules as inflection indicator for CO2 cascade cooling retrofit demand.| Strategic Initiative | Industry Significance |
|---|---|
| Preventive Maintenance Contract Unbundling | Washington and Oregon wine co-packers now negotiate standalone service agreements separate from equipment purchase. |
| CO2 Cascade Cooling Retrofit | Italian prosecco producers retrofit pneumatic bases to satisfy EU F-Gas Regulation phase-down schedules. |
| Corrugated Outer-Box Bundling | Smurfit Kappa leverages integrated packaging portfolio to reduce per-unit handling labor for beverage distributors. |
| Servo-Driven Accuracy Migration | Swiss and German cosmetic manufacturers specify 0.3% fill-tolerance systems compressing changeover times under 8 minutes. |
| BIS Certification Pre-Investment | Mumbai-Pune industrial corridor entry requires compliance investment that disqualifies non-advantaged foreign suppliers. |
Study Parameters
Direct dialogue with plant engineers at French and Italian wine co-packers, aftermarket service directors at North American equipment vendors, procurement leads at Maharashtra edible-oil processors, and regulatory affairs specialists at EU packaging converters grounded qualitative findings. Secondary validation drew from EU REACH registration databases, FDA food-contact substance notifications, BIS certification records, and FSSAI packaged food expansion filings. Bottom-up unit economics triangulated against top-down macro demand drivers across the analysis window.
Segment-level projections incorporated automation intensity by beverage co-packer scale, technology migration curves between pneumatic and electric architectures, and regulatory compliance cost pass-through rates. Modeled dimensions spanned product type, end-user severity, drive technology, and container size tier. CAGRs derived from installed base retirement cycles in European wine regions and greenfield adoption curves in Indian institutional channels.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU Packaging and Packaging Waste Regulation enforcement timelines and Grade 316L stainless surcharge volatility. Forecasts reflect documented assumptions on technician availability constraints and multi-standard certification lag. A small set of triggers—IRA credit utilization rates, Indian BIS mutual recognition agreements, and mechatronics training program expansion—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Disposable Garbage Bags Market
Bags and Containers
North America Retail Bags Market
Bags and Containers
Laminated Woven PP Bags Market
Bags and Containers
Non-Barrier Bag Market
Bags and Containers
Liner Bags Market
Bags and Containers
Wooden Boxes Market
Bags and Containers
Trash Bags Market
Bags and Containers
Self-Sealing Bags Market
Bags and Containers
Mylar Bags Market
Bags and Containers
Bulk Bag Conditioners Market
Bags and Containers
Counter Bags Market
Bags and Containers
Circular Industrial Bags Market
Bags and Containers
Hanging Bags Market
Bags and Containers
Conical Bags Packaging Market
Bags and Containers
Twisted Handle Bags Market
Bags and Containers
Inclusion Bags Market