
 Silicone Storage Bags Market | 2026-2036
Silicone Storage Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Silicone Storage Bags Market Analysis
Chinese food-grade silicone production is decoupling from legacy petrochemical supply chains as domestic refiners build dedicated silicone monomer capacity. Stasher leverages its platinum-cured silicone expertise to anchor premium positioning in North American retail channels. Lekue competes through specialized microwave-safe designs that dominate Iberian and Latin European markets. Tupperware sustains global brand recognition while navigating direct-to-consumer channel shifts away from traditional party-plan distribution.
Silicone storage bags are flexible, heat-resistant containers manufactured from cross-linked polydimethylsiloxane (PDMS) with working temperature ranges typically spanning -40°C to 230°C, designed for repeated food preservation and cooking applications. Multi-purpose bags lead volume due to their adaptability across freezing, sous-vide, and microwave use cases, while freezer bags command margin premiums through thicker wall construction and reinforced sealing mechanisms. Food-grade silicone dominates material selection as consumers scrutinize platinum versus peroxide curing distinctions, and leak-proof features increasingly determine repurchase behavior in household and food delivery segments.
The FDA maintains 21 CFR 177.2600 compliance requirements for repeated-use rubber articles in food contact, while the EU's REACH regulation restricts certain platinum catalyst residues and phthalate plasticizers in silicone formulations. China's SAMR enforces GB 4806.11-2016 food-contact silicone standards that exporters must satisfy for market access. Stakeholders should monitor evolving state-level packaging Extended Producer Responsibility laws in California and New York, as these jurisdictions often prefigure broader North American regulatory patterns.
Market Dynamics
The European Union's Single-Use Plastics Directive is compressing substitution timelines across household food storage, forcing rapid capacity reallocation from conventional polyethylene production toward platinum-cured silicone alternatives.
Growth Catalysts
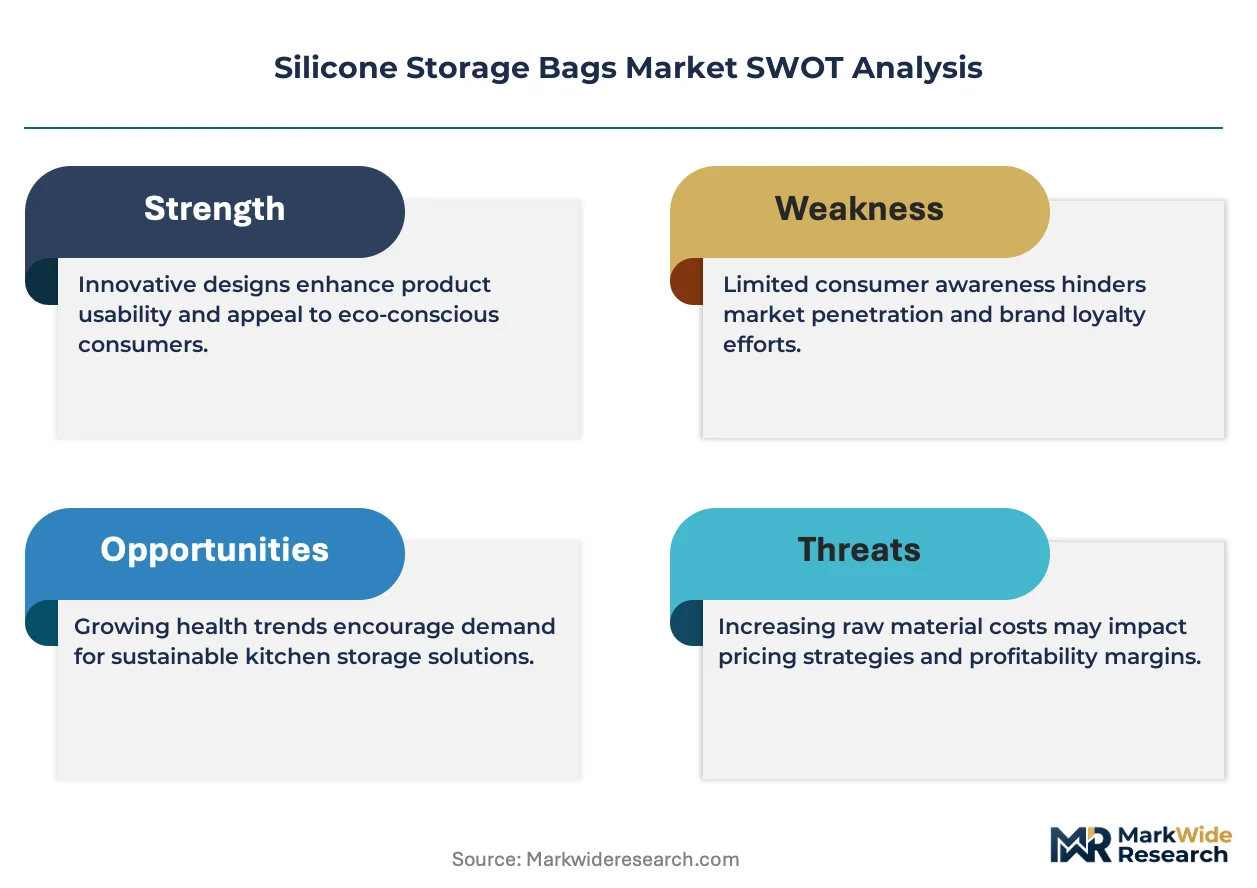
- REACH phthalate restrictions:The EU's tightening limits on plasticizer residues in food-contact materials accelerate silicone adoption as the compliant default for reusable storage.
- Sous-vide cooking expansion:Precision temperature control requirements in home and commercial kitchens drive heat-resistant bag demand beyond traditional freezing applications.
- German municipal waste targets:Strict reduction mandates in cities like Hamburg and Munich create immediate replacement demand for single-use alternatives.
Market Restraints
- Silicone monomer supply concentration:Chinese refiners control critical polydimethylsiloxane precursor capacity, exposing converters to input volatility.
- Platinum catalyst cost structure:Food-grade curing requires precious metal inputs that fluctuate with commodity markets, compressing margin flexibility.
- Glass container substitution:Borosilicate alternatives compete for premium positioning in microwave and oven applications where transparency matters.
Strategic Opportunities
- India FSSAI compliance pathways:Emerging food-contact standards create first-mover positioning for exporters meeting GB 4806.11-2016 equivalency.
- Food delivery logistics integration:Restaurant-to-consumer packaging reuse programs in dense urban corridors open B2B volume channels.
- California EPR prefiguration:Extended Producer Responsibility legislation signals North American regulatory convergence toward EU-style material mandates.
Industry Challenges
- Platinum versus peroxide certification expertise:Technical workforce gaps in curing chemistry differentiation slow quality assurance scaling.
- Multi-jurisdiction compliance synchronization:Simultaneous FDA 21 CFR 177.2600, REACH, and GB 4806.11-2016 testing extends product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silicone Storage Bags Market |
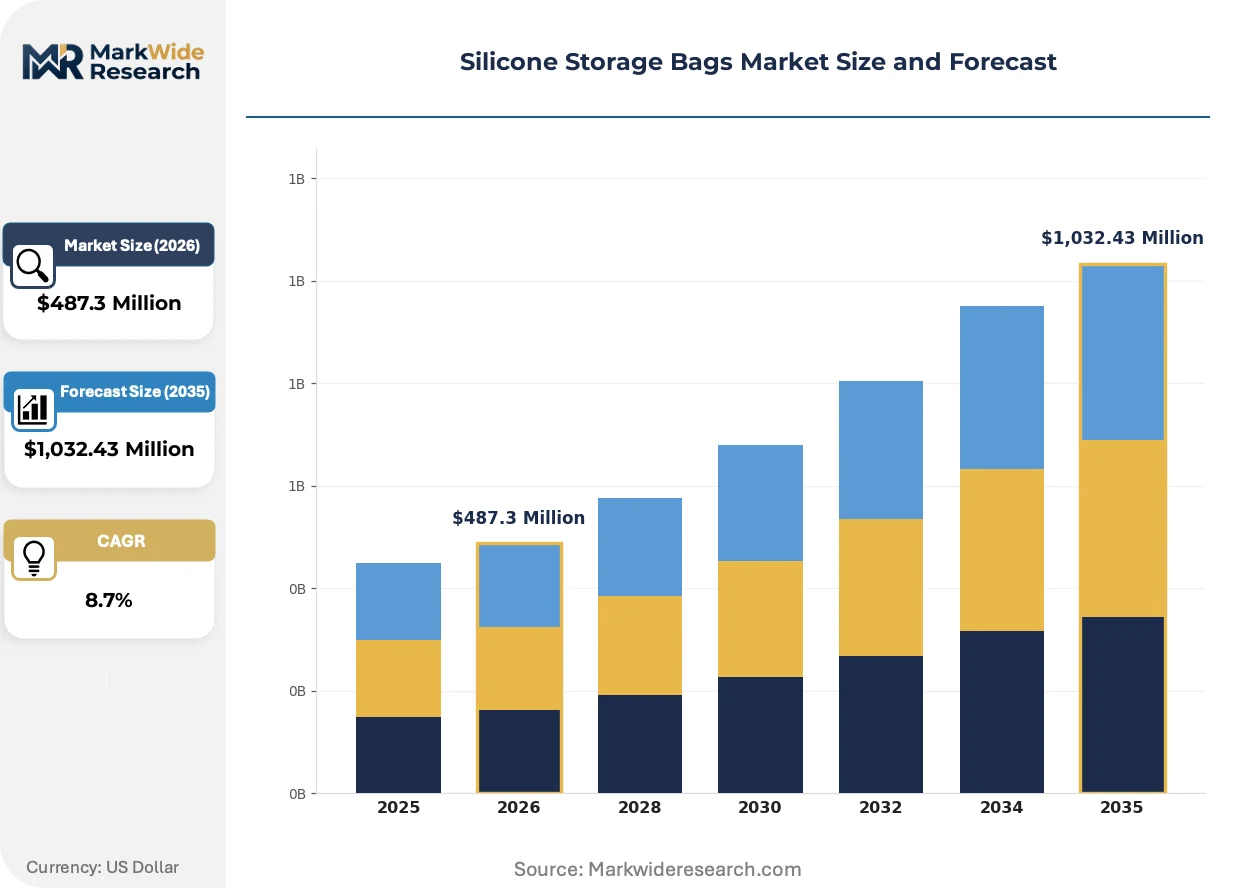
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Freezer Bags, Sandwich Bags, Multi-Purpose Bags, Snack Bags Material: Food-Grade Silicone, Reusable Silicone, BPA-Free Silicone, Eco-Friendly Silicone End User: Households, Restaurants, Catering Services, Food Delivery Feature: Microwave Safe, Dishwasher Safe, Leak-Proof, Freezer Safe |
| Companies Covered | Artfullife, Durbl, Stasher, Momcozy, WeeSprout, Zip Top, Tupperware, Haakaa, Lekue, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silicone Storage Bags Market Emerging Trajectories
Material science advances and regulatory convergence are compressing product development cycles while expanding functional boundaries beyond basic storage into integrated cooking applications.
Platinum-cured silicone formulations are decentralizing quality-tier access across mid-market retail channels. Regional converters in Poland and Turkey now deploy curing expertise previously concentrated among premium specialists. This capability diffusion compresses price positioning for incumbent North American brands.
REACH catalyst residue thresholds are tightening compliance burdens for peroxide-cured alternatives. Industrial consequences include accelerated R&D migration toward platinum systems and consolidation among testing laboratories. Iberian and Latin European markets show fastest response due to Lekue's established microwave-safe design precedence.
Subscription-based replenishment models are replacing conventional retail stocking in direct-to-consumer channels. Urban households in Germany and France now favor scheduled bag replacement programs over episodic purchasing. This pattern concentrates most visibly in Berlin and Paris metropolitan fulfillment zones where last-mile density supports reverse logistics for worn-product collection.
Silicone Storage Bags Market Segmentation
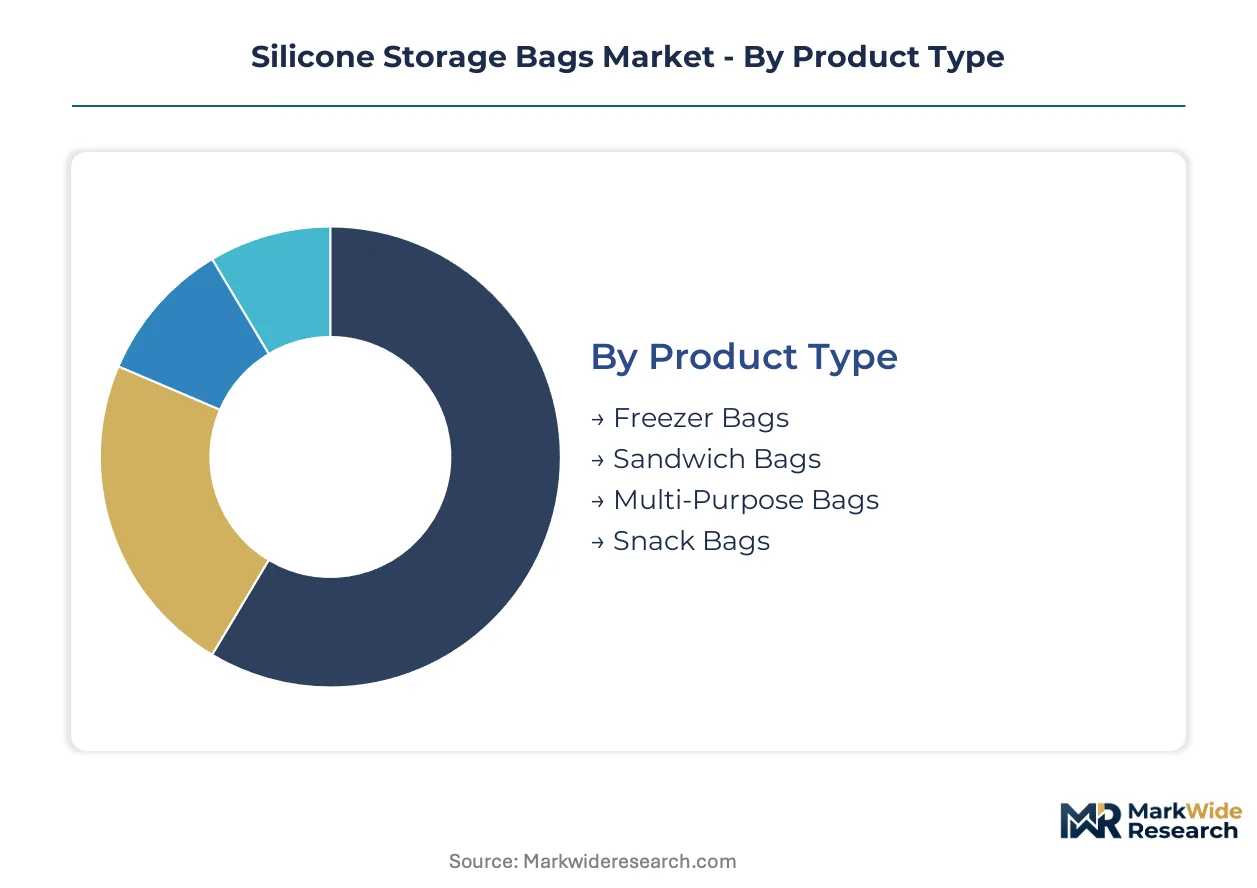
Silicone storage bag producers align manufacturing assets against distinct performance tiers and certification requirements. Each segment demands specialized curing expertise and compliance documentation that shapes procurement decisions across household and commercial channels.
Product Type:
Capacity allocation clusters around thermal performance specifications that determine wall thickness and sealing complexity.
- Multi-Purpose Bags:Cross-linked polydimethylsiloxane construction spans -40°C to 230°C operating ranges for freezing, sous-vide, and microwave applications. German urban households in Hamburg and Munich drive replacement demand under strict municipal waste reduction mandates. The segment captures volume leadership through adaptability across use cases.
- Freezer Bags:Thicker wall construction and reinforced sealing mechanisms command margin premiums in cold-chain applications. Iberian and Latin European markets concentrate demand where Lekue's microwave-safe design precedence has educated consumers on durability expectations. Commercial kitchens in France prioritize these specifications for inventory rotation protocols.
- Sandwich Bags:Compact form factors target portion-controlled meal preparation in UK and French metropolitan areas.
- Snack Bags:Reduced capacity variants address single-serve packaging needs in school and workplace environments.
Multi-purpose bags absorb the bulk of installed capacity; freezer bags are expanding most quickly.
Material:
Certification grade determines converter access to premium retail placement and food-service procurement channels.
- Food-Grade Silicone:Platinum-cured formulations meeting FDA 21 CFR 177.2600 and EU REACH catalyst residue thresholds dominate quality-tier positioning. Stasher anchors North American retail distribution through this specification. Household scrutiny of curing chemistry drives repurchase behavior.
- BPA-Free Silicone:Peroxide-cured alternatives face tightening REACH restrictions on plasticizer residues, compressing addressable market share. Chinese GB 4806.11-2016 compliance requirements increasingly filter export eligibility.
- Reusable Silicone:Durability claims support subscription-based replenishment models in Berlin and Paris metropolitan fulfillment zones.
- Eco-Friendly Silicone:Bio-based feedstock variants attract sustainability-positioned retailers in Scandinavian markets.
Food-grade silicone commands the widest regulatory clearance; BPA-free alternatives face steepest compliance compression.
End User:
Channel requirements diverge between household convenience priorities and commercial durability protocols.
- Households:Urban centers across Germany, France, and the United Kingdom drive replacement of single-use plastics under EU Single-Use Plastics Directive compression. Scheduled replacement programs are displacing episodic purchasing in dense metropolitan areas.
- Food Delivery:Restaurant-to-consumer packaging reuse programs in dense urban corridors open B2B volume channels with reverse logistics integration.
- Restaurants:Sous-vide cooking expansion in commercial kitchens specifies heat-resistant bag demand beyond traditional freezing.
- Catering Services:High-rotation inventory management favors standardized capacity formats with rapid cleaning turnaround.
Households absorb the bulk of unit volume; food delivery channels are climbing the fastest.
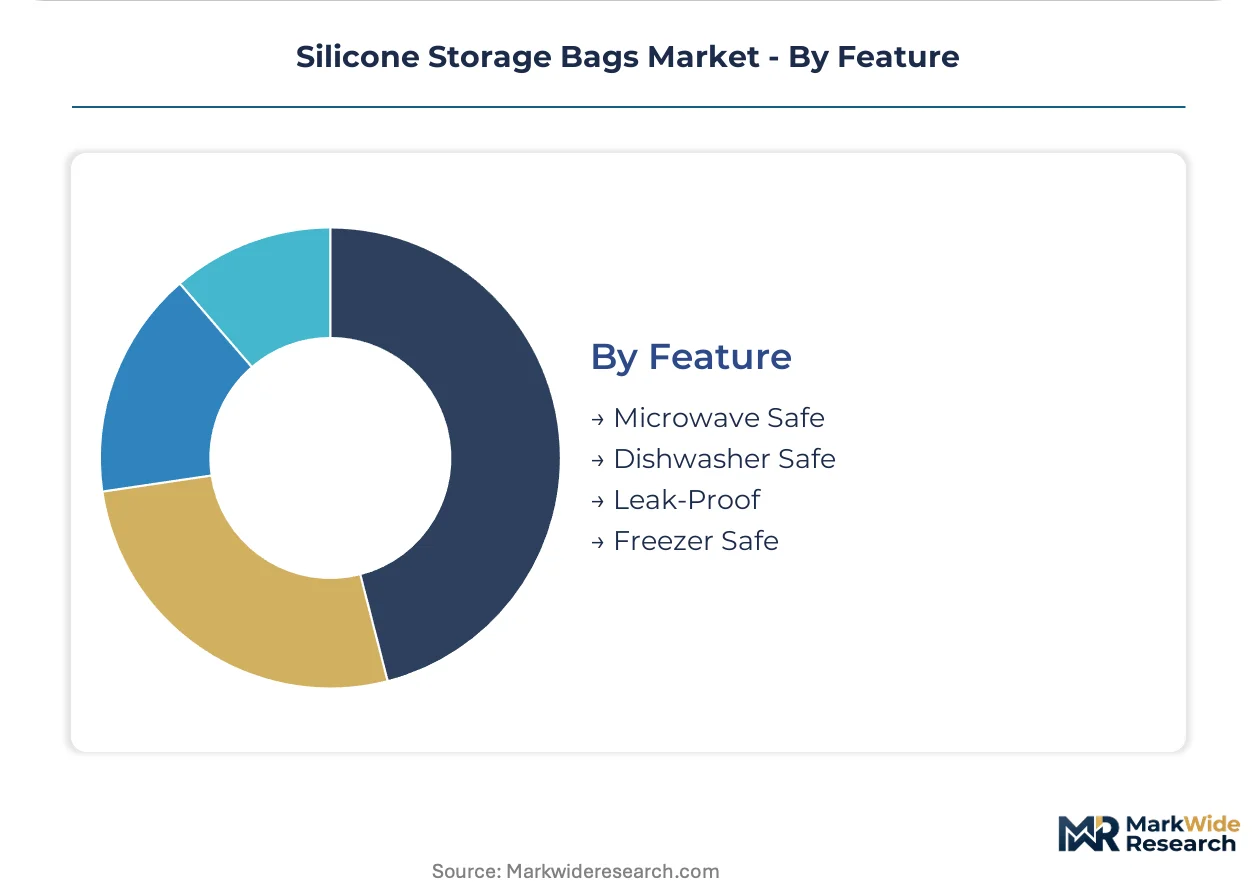
Feature:
Functional certification determines price positioning and cross-channel applicability.
- Leak-Proof:Sealing mechanism reliability increasingly determines repurchase behavior across household and food delivery segments. Reinforced closure designs command engineering investment priority.
- Microwave Safe:Lekue's established design precedence in Iberian and Latin European markets has elevated this specification to baseline expectation.
- Dishwasher Safe:Automated cleaning compatibility supports subscription replenishment model economics.
- Freezer Safe:Cold-chain integrity specifications align with freezer bag product category requirements.
Leak-proof certification anchors premium positioning; microwave-safe specifications are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese polydimethylsiloxane refiners in Jiangsu and Shandong provinces anchor upstream capacity for silicone monomer supply. This feedstock concentration shapes converter economics across downstream markets.
Germany
Hamburg and Munich municipal authorities enforce strict household waste reduction targets that accelerate single-use plastic replacement. The EU Single-Use Plastics Directive binds national implementation timelines. Berlin metropolitan fulfillment zones concentrate subscription-based replenishment program adoption.
United States
California and New York state-level Extended Producer Responsibility legislation prefigures broader packaging mandates. FDA 21 CFR 177.2600 compliance requirements govern food-contact silicone imports. Urban households in the Northeast Corridor and Pacific Northwest drive direct-to-consumer channel migration.
China
Domestic refiners build dedicated silicone monomer capacity that decouples from legacy petrochemical supply chains. SAMR enforces GB 4806.11-2016 food-contact standards for export market access. Yangtze River Delta manufacturing clusters supply platinum-cured formulations to North American and European converters.
France
Paris metropolitan households favor scheduled replacement programs over episodic purchasing for reusable storage. REACH phthalate restrictions tighten compliance burdens for peroxide-cured alternatives. Lyon and Marseille urban centers concentrate food delivery logistics integration for restaurant-to-consumer packaging reuse.
United Kingdom
London and Southeast England households replace single-use plastics under EU directive carryover obligations. Urban centers drive multi-purpose bag demand across freezing, sous-vide, and microwave applications. Midlands manufacturing regions host converters serving domestic retail and food-service procurement channels.
Silicone Storage Bags Market Vendor Landscape
Global majors compete with regional champions across curing expertise and certification tier access. The vendor base stratifies between platinum-cured quality specialists and peroxide-cured volume converters. Three archetypes dominate: premium-tier curing specialists, mid-market regional fabricators, and legacy direct-to-consumer brands navigating channel shifts. Capacity expansion and subscription model deployment constitute the dominant competitive moves.
Among North American premium-tier anchors, Stasher occupies a position exemplifying platinum-cured silicone expertise in retail distribution. Tupperware sits within the legacy brand archetype navigating direct-to-consumer channel migration away from traditional party-plan structures. Lekue represents the regional specialist tier with established microwave-safe design precedence in Iberian and Latin European markets.
| Leading Market Players |
|---|
| Artfullife |
| Durbl |
| Stasher |
| Momcozy |
| WeeSprout |
| Zip Top |
| Tupperware |
| Haakaa |
| Lekue |
| Others |
Supply Flow & Price Mechanics
Captive silicone monomer production in Chinese refiners anchors converter cost positions and pricing power across downstream markets. This backward integration into polydimethylsiloxane precursors insulates domestic manufacturers from petrochemical volatility while compressing margin flexibility for importers dependent on spot market sourcing.
Pricing Analysis
Warranty and certification bundling separates platinum-cured premiums from unbundled peroxide-cured alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects curing chemistry grade and REACH compliance tier. Cost compression in mid-market tiers intensifies as Polish and Turkish converters replicate curing expertise. Food-service procurement teams exhibit lowest price sensitivity due to durability protocol requirements, while household episodic buyers drive volume at entry price points.
Supply Chain Analysis
Direct-to-retail channels handle premium brand distribution while food-service procurement flows through specialized distributors. Jiangsu and Shandong province refiners supply polydimethylsiloxane monomer to Yangtze River Delta converters. Raw material dependencies center on platinum catalyst inputs and food-grade silicone formulations. Single-source vulnerability concentrates in Chinese monomer capacity. Distribution runs through North American retail chains, European specialty distributors, and Asian export trading houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platinum catalyst supply constraints prop pricing power for certified converters. Silicone monomer capacity expansion lags demand acceleration across food-contact applications.
For Market Incumbents: Acquire curing chemistry testing laboratories to compress quality assurance timelines. Strengthen backward integration into platinum catalyst sourcing to hedge commodity volatility. Glass container substitution threatens premium positioning in microwave-transparent applications. Certification investment in FSSAI compliance opens Indian market access before standards harden. For New Entrants and Emerging Players: Enter via food delivery logistics integration in dense European urban corridors where reverse logistics infrastructure supports reuse program economics. Target Indian FSSAI compliance pathways ahead of regulatory convergence with GB 4806.11-2016 standards. Commercial kitchen sous-vide applications offer penetrable white-space with lower incumbent saturation than household retail channels. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by consumer goods conglomerates seeking sustainability portfolio expansion. Five-to-ten year viability hinges on regulatory acceleration beyond EU directive carryover into North American EPR frameworks. Acquisition target archetype: regional converters with platinum-cured expertise and multi-jurisdiction certification documentation. Monitor California and New York EPR implementation timelines as inflection signals for broader North American mandate adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Monomer | Jiangsu and Shandong refiners decouple from legacy petrochemical supply chains. |
| Platinum-Cured Certification Investment | FDA 21 CFR 177.2600 and REACH compliance opens premium retail placement. |
| Food Delivery Logistics Partnership | Berlin and Paris metropolitan zones support reverse logistics for reuse programs. |
| Subscription Replenishment Model Launch | Scheduled replacement displaces episodic purchasing in dense urban households. |
| FSSAI Compliance Pathway Development | First-mover positioning in India before standards converge with Chinese GB requirements. |
Methodological Framework
Trade customs data, food-contact regulatory filings, and silicone industry association reports formed the secondary backbone. Primary interviews with platinum-curing technical directors, food-service procurement managers, retail category buyers, and regulatory compliance officers validated demand assumptions. Bottom-up unit economics triangulated against top-down market sizing across product type, material grade, end-user channel, and functional feature segments.
Historical trendline analysis identified inflection points in substitution patterns and regulatory enforcement intensity. Volume and value outputs reflect cross-referencing of production capacity announcements, import-export flows, and channel inventory data across the projection horizon. Segmentation modeling incorporated product type thermal specifications, certification tier access, end-user durability protocols, and regional regulatory cluster alignment. CAGR derivation weighted capacity expansion timelines against municipal waste reduction mandate implementation schedules.
Revisions become necessary when platinum catalyst supply disruptions, EPR legislation acceleration, or glass container substitution breakthroughs materialize. Forecasts reflect base-case assumptions regarding REACH phthalate restriction enforcement and Chinese export standard harmonization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Mylar Bags Market
Bags and Containers
Bag-In-Bottle Market
Bags and Containers
Net Bags Market
Bags and Containers
Global Bag Filling Machines Market
Bags and Containers
Single Lip Bags Market
Bags and Containers
Drum Liners Market
Bags and Containers
Piping Bags Market
Bags and Containers
Multiwall Bags Market
Bags and Containers
Trash Bags Market
Bags and Containers
Shopping Bag Market
Bags and Containers
Twisted Handle Bags Market
Bags and Containers
Tote and Ingredient Bags Packaging Market
Bags and Containers
Isothermal Bags Market
Bags and Containers
Nonwoven Containers Market
Bags and Containers
Quad Seal Bag Market
Bags and Containers
Self-Sealing Ziplock Bags Market