
 Child Resistant Bags Market | 2026-2036
Child Resistant Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Child Resistant Bags Market Outlook
North American flexible packaging converters is pivoting toward certified child-resistant formats as state cannabis programs expand. Amcor plc leverages its pharmaceutical barrier film expertise to supply multi-layer laminates with ASTM D3475 compliance. Berry Global Group, Inc. sustains a dominant position in preformed pouch capacity across the Midwest and Southeast. Dymapak specializes in custom-printed exit bags for California dispensaries, competing on turnaround speed and SKU flexibility.
Child resistant bags are engineered flexible containers incorporating reclosure mechanisms that require dual coordinated actions to open, typically constructed from multi-ply polyethylene or polyester laminates with tactile opening sequences tested against F2097 protocols. These bags serve primarily to prevent accidental ingestion by children under five years while preserving product freshness and providing tamper-evident security. Pouches and ziplock bags occupy the largest volume share due to their compatibility with automated filling lines and shelf-ready presentation. Laminated bags command premium positioning where oxygen and moisture barriers extend pharmaceutical stability. Plastic and polyethylene materials dominate unit economics, though paperboard alternatives gain traction in sustainability-sensitive personal care segments.
The US Consumer Product Safety Commission enforces Poison Prevention Packaging Act standards, while FDA regulations govern pharmaceutical primary packaging and state cannabis boards mandate ASTM-certified exit packaging. CE marking requirements under EU MDR and the F-Gas Regulation shape European import specifications for medical and refrigerant applications. Stakeholders must monitor evolving state-by-state cannabis packaging rules and anticipate harmonization pressures between ASTM protocols and ISO 8317 international standards.
Market Dynamics
State cannabis packaging mandates are compressing supplier timelines and forcing converters to maintain dual-certification inventories across ASTM D3475 and emerging ISO 8317 protocols. This regulatory layering creates a structural bottleneck where only certified converters capture volume from expanding dispensary networks.
Growth Catalysts
- US Poison Prevention Packaging Act enforcement:Federal compliance requirements for household chemicals and pharmaceuticals sustain baseline demand for certified child-resistant closures across retail channels.
- California cannabis exit packaging rules:State regulations mandate ASTM-certified bags for all dispensary sales, creating a captive demand pool for compliant converters.
- Multi-layer barrier films:Oxygen and moisture protection specifications for pharmaceutical stability are extending shelf life requirements into cannabis and nutraceutical applications.
Market Restraints
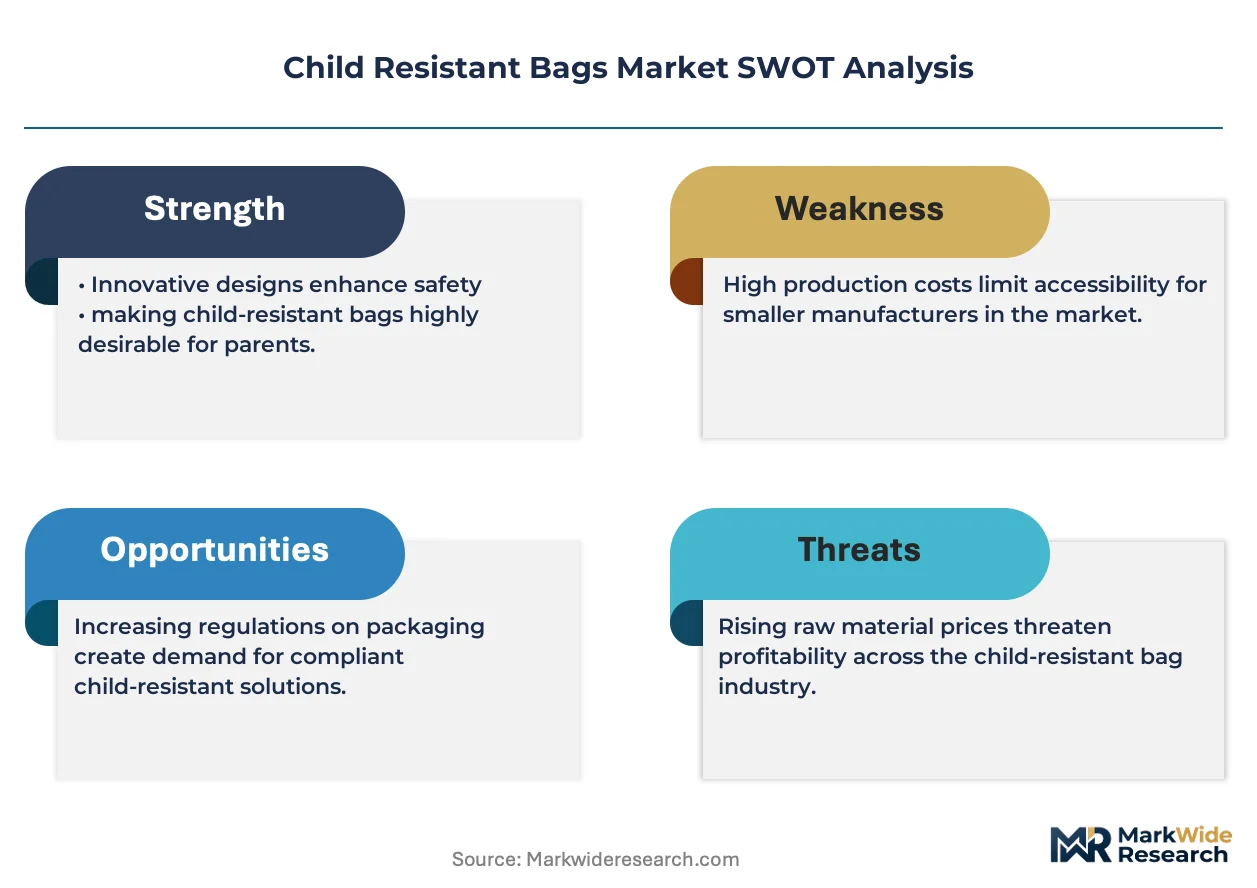
- Resin price volatility:Polyethylene and polyester input costs fluctuate with crude oil indices, compressing converter margins on fixed-price annual contracts.
- Certification timeline friction:ASTM D3475 testing protocols require 90-120 day validation cycles, delaying new product commercialization and locking out unqualified suppliers.
- Paperboard substitution threat:Sustainability-driven personal care brands are piloting fiber-based child-resistant formats in European markets with stricter single-use plastic restrictions.
Strategic Opportunities
- German medical cannabis distribution:Pharmacy-dispensed cannabis under BfArM licensing creates demand for pharmaceutical-grade barrier packaging with EU MDR traceability.
- Biodegradable laminate development:Convergence of compostable films with child-resistant zipper mechanisms opens premium positioning in California's organic cannabis segment.
- Direct-to-consumer subscription channels:E-commerce fulfillment of pharmaceuticals and hemp-derived products requires tamper-evident, child-resistant pouches with automated opening features.
Industry Challenges
- Dual-action mechanism engineering:Designing reclosures that satisfy both senior-friendly accessibility and child-resistant rigor demands specialized polymer rheology expertise that remains scarce among mid-tier converters.
- State-by-state regulatory fragmentation:Colorado, Illinois, and New York maintain divergent labeling and testing requirements, forcing SKU proliferation and inventory complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Child Resistant Bags Market |
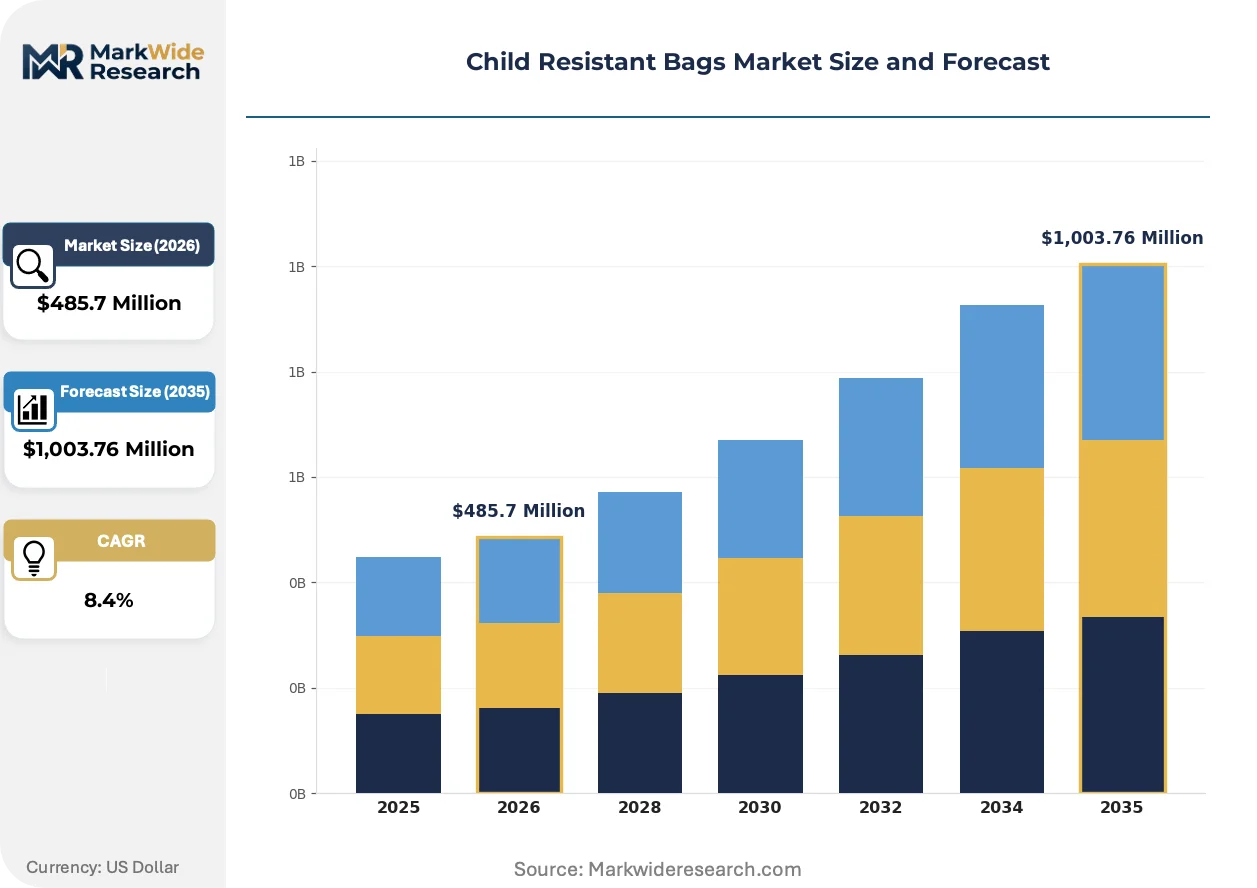
| Market Size in 2026 | $485.7 Million |
| Market Size in 2035 | $1,003.76 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ziplock Bags, Pouches, Laminated Bags, Resealable Bags Material: Plastic, Polyethylene, Polyester, Paperboard End User: Pharmaceuticals, Food Packaging, Personal Care, Household Products Certification: ISO 9001, FDA Approved, ASTM Certified, CE Marked |
| Companies Covered | Amcor plc, Berry Global Group, Inc., Constantia Flexibles, Bemis Company, Inc., Mondi Plc, Sealed Air Corporation, Sonoco Products Company, Sierra Bags, Dymapak, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Child Resistant Bags Market Strategic Shifts
Digital printing and smart packaging technologies are collapsing minimum order quantities and enabling lot-level traceability. These capabilities are restructuring how converters compete on speed versus scale.
Water-based inkjet printing on flexible films is rewriting the economics of short-run custom branding for California dispensaries. Small-batch cannabis cultivators now access 500-unit minimums with 48-hour turnaround, compressing the traditional 10,000-unit offset printing threshold by an order of magnitude. This capability is fragmenting volume concentration away from national converters toward regional specialists with digital asset workflows.
The EU F-Gas Regulation and REACH chemical restrictions are tightening material specifications for medical packaging imports into European markets. Converters serving pharmaceutical exports must now document fluorocarbon-free adhesive formulations and full substance-of-concern declarations. German and Swiss medical device distributors are prioritizing suppliers with pre-validated EU MDR technical files, creating a certification moat that Asian competitors struggle to cross.
Dispensary procurement teams are consolidating vendor relationships around full-service packaging partners who supply compliant bags, labels, and compliance consulting as a bundled offering. This behavior shift displaces the previous model of fragmented sourcing across bag converters, label printers, and regulatory consultants. Colorado and Michigan multi-location operators are most advanced in this consolidation, driven by state audit requirements that punish documentation gaps.
Child Resistant Bags Market Segmentation
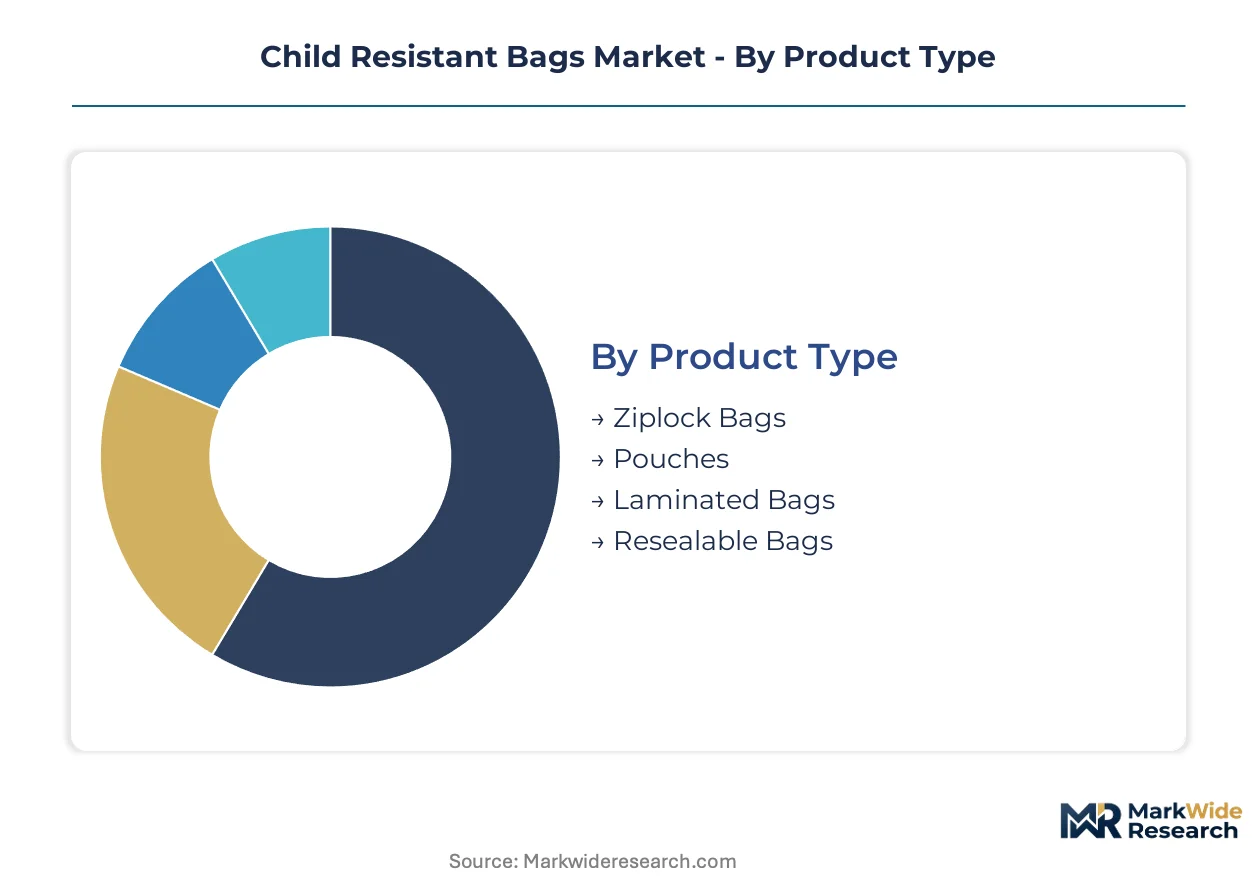
Child resistant bags serve divergent compliance regimes across pharmaceuticals, cannabis, and consumer goods. Segmentation reveals how certification requirements and barrier specifications fragment converter capabilities and buyer procurement patterns.
Product Type:
Buyers differentiate primarily by filling line compatibility and shelf presentation requirements rather than barrier performance alone.
- Pouches:Stand-up and flat pouch configurations dominate automated cannabis packaging lines in California and Colorado. Preformed pouch demand concentrates with multi-location dispensary operators who prioritize throughput speed over unit cost.
- Ziplock Bags:These feature press-to-close zipper mechanisms integrated with dual-action child-resistant sliders. Pharmaceutical mail-order pharmacies in the US specify ziplock formats for patient compliance packaging where senior accessibility conflicts with child safety.
- Laminated Bags:Multi-ply structures with aluminum or EVOH cores serve moisture-sensitive pharmaceuticals.
- Resealable Bags:Hook-and-loop or slider reclosures target household chemical applications under EPA guidelines.
Volume sits with pouches; growth tilts toward laminated bags as pharmaceutical stability requirements extend into cannabis and nutraceutical segments.
Material:
Cost tier and sustainability positioning separate buyers more than functional performance, since most child-resistant mechanisms achieve compliance across substrate classes.
- Polyethylene:LDPE and LLDPE films provide the cost baseline for high-volume cannabis exit bags. California dispensaries specify polyethylene for single-use compliance packaging where disposal cost externalization is permitted.
- Plastic:Multi-resin coextrusions blend polyethylene with polypropylene for enhanced puncture resistance. Pharmaceutical contract packers in the Midwest favor these structures for unit-dose blister alternatives.
- Polyester:PET films deliver dimensional stability for high-definition printing and premium shelf presence.
- Paperboard:Fiber-based child-resistant formats gain traction in European personal care markets facing single-use plastic restrictions under EU Green Deal implementation timelines.
Polyethylene captures current volume share; paperboard climbs the fastest as sustainability mandates reshape European procurement specifications.
End User:
Regulatory stringency and audit frequency create distinct buyer segments with divergent documentation and certification demands.
- Pharmaceuticals:FDA-regulated primary packaging demands ASTM D3475 and ISO 8317 dual certification with full batch traceability. US mail-order pharmacies and hospital systems drive specification rigor.
- Household Products:EPA and CPSC oversight of cleaning chemicals and pesticides sustains baseline demand for certified closures. Concentrated bleach and laundry pod packaging in the US requires Poison Prevention Packaging Act compliance.
- Food Packaging:Cannabis-infused edibles in California and Colorado must exit dispensaries in ASTM-certified bags regardless of food content.
- Personal Care:CBD topicals and hemp-derived cosmetics occupy a regulatory gray zone with emerging state-level packaging mandates.
Pharmaceuticals anchor revenue concentration; household products deliver steadiest contract renewal rates.
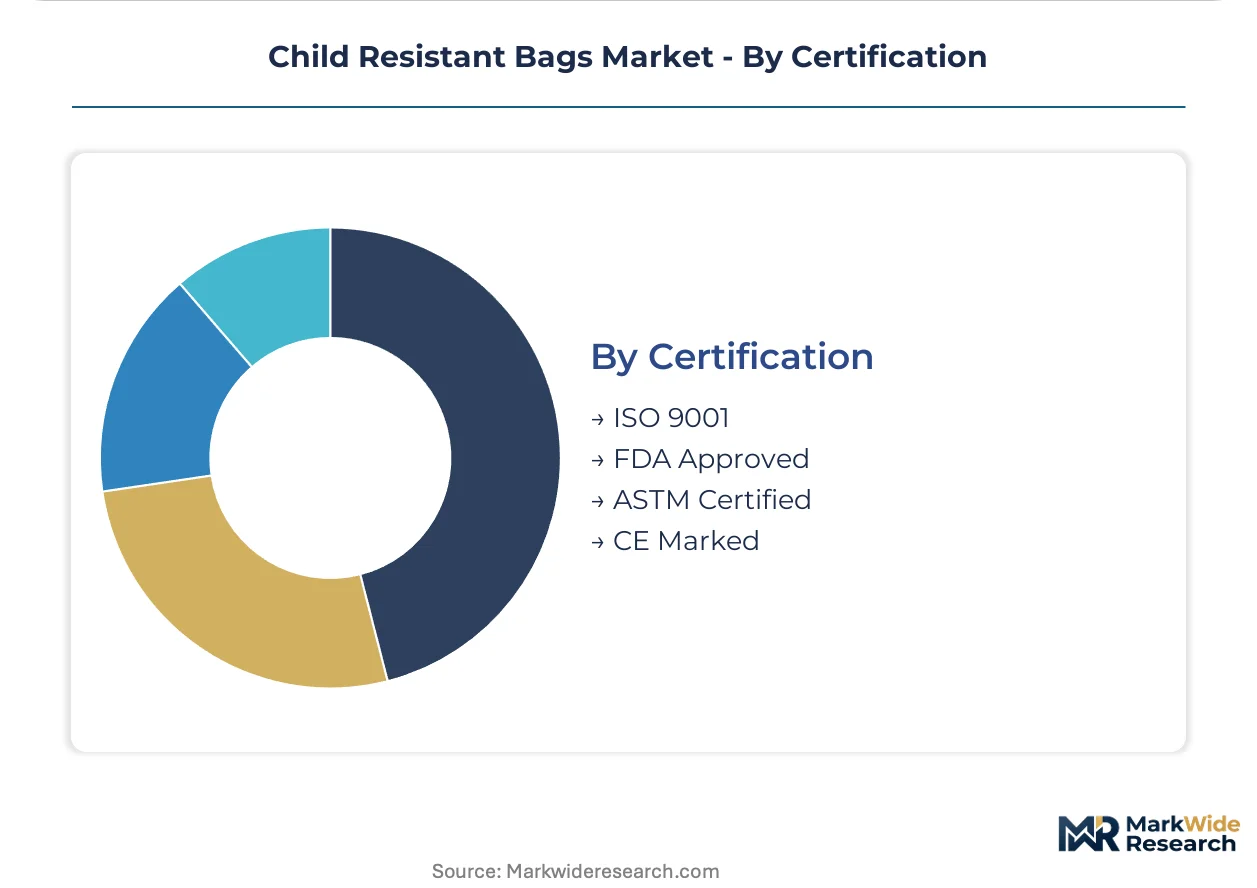
Certification:
Export destination and supply chain audit requirements determine which certification portfolios converters must maintain.
- ASTM Certified:ASTM D3475 protocol compliance is mandatory for US cannabis dispensary sales. California and Colorado state regulations explicitly reference this standard, creating a captive certification requirement for domestic converters.
- FDA Approved:Pharmaceutical primary packaging requires FDA 21 CFR compliance with drug master file documentation. US contract manufacturers will not qualify suppliers lacking established FDA regulatory histories.
- ISO 9001:Quality management certification serves as a baseline procurement filter for multinational pharmaceutical and personal care brands.
- CE Marked:EU MDR technical documentation and CE marking enable access to German and Swiss medical cannabis distribution channels.
ASTM certification dominates North American volume; CE marking opens the steepest expansion trajectory as European medical cannabis pharmacy distribution matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polyethylene resin production clusters along the US Gulf Coast anchor North American supply chains for multi-layer child-resistant laminates. Converter capacity concentrates near raw material sources and state cannabis distribution hubs.
United States
California and Colorado dispensary networks drive ASTM D3475-certified pouch demand. The Poison Prevention Packaging Act mandates child-resistant closures for pharmaceuticals and household chemicals. Los Angeles and Denver host dense converter ecosystems serving multi-location cannabis operators with rapid-turnaround exit packaging.
Germany
Pharmaceutical-grade barrier packaging demand accelerates under BfArM medical cannabis pharmacy distribution. EU MDR technical documentation requirements filter supplier qualification. The Rhine-Ruhr industrial corridor houses flexible packaging specialists pre-validated for CE-marked medical exports.
Canada
Health Canada cannabis regulations mandate child-resistant packaging for recreational and medical products. PMRA oversight extends similar requirements to pesticides and household chemicals. Ontario and British Columbia concentrate converter capacity serving Prairie province cultivators and Pacific Northwest export channels.
Switzerland
Swissmedic-regulated medical cannabis distribution demands pharmaceutical-grade packaging with full batch traceability. REACH chemical restrictions shape material specifications for European market access. Basel and Zurich host precision converters supplying German and Austrian pharmacy chains.
Australia
TGA medical cannabis licensing creates demand for ASTM and ISO 8317 dual-certified packaging. State-level cannabis access schemes in Victoria and New South Wales require compliant exit bags. Sydney and Melbourne converters develop export capacity for Asia-Pacific pharmaceutical markets.
Child Resistant Bags Market Competitive Environment
Global majors compete with regional champions across certification portfolios and geographic proximity to cannabis distribution hubs. The vendor base stratifies between pharmaceutical-grade specialists and high-volume cannabis packaging converters. Three archetypes dominate: diversified packaging conglomerates with pharmaceutical barrier expertise, regional specialists competing on turnaround speed, and sustainability-focused innovators developing fiber-based alternatives. Capacity expansion and certification portfolio diversification represent the primary competitive moves as state cannabis programs multiply.
Within the diversified conglomerate tier, Amcor plc and Berry Global Group, Inc. exemplify scale-driven positions anchored by pharmaceutical film expertise and preformed pouch capacity. Dymapak occupies a specialist position among California-focused converters competing on digital printing agility and SKU flexibility for dispensary procurement teams.
| Leading Market Players |
|---|
| Amcor plc |
| Berry Global Group, Inc. |
| Constantia Flexibles |
| Bemis Company, Inc. |
| Mondi Plc |
| Sealed Air Corporation |
| Sonoco Products Company |
| Sierra Bags |
| Dymapak |
| Others |
Value Chain & Pricing Dynamics
Captive resin production among Gulf Coast petrochemical complexes anchors converter margins and pricing power against polyethylene spot market swings. California dispensary procurement teams face limited alternative supply when ASTM-certified capacity concentrates with pre-qualified regional converters.
Pricing Analysis
Warranty and compliance documentation bundling separates full-service converter offerings from commodity bag suppliers. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and barrier performance specifications. Price differentiation centers on dual-certification portfolios versus single-standard compliance, with pharmaceutical-grade laminates commanding sustained premiums. Cost compression in standard-tier cannabis exit bags is intensifying because digital printing specialists erode volume thresholds. Multi-location dispensary operators exhibit lowest price sensitivity due to audit liability concentration, while single-store cultivators drive hard per-unit negotiations.
Supply Chain Analysis
Single-source vulnerability sits with South Korean and Taiwanese EVOH barrier film suppliers serving pharmaceutical laminate specifications. Raw material flows draw from US Gulf Coast polyethylene production, German adhesive formulation specialists, and Japanese zipper mechanism manufacturers. Supply chain risk centers on regulatory restriction propagation under EU REACH substance-of-concern declarations. Distribution runs through regional converter hubs co-located with state cannabis distribution centers in California, Colorado, and Michigan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where backward control over certified film extrusion and testing laboratory capacity determines who captures expanding state cannabis program volumes.
For Market Incumbents: Hedge against paperboard substitution threats by piloting fiber-based child-resistant formats with European personal care brands facing EU Green Deal plastic restrictions. Deepen captive supply of multi-layer barrier films through toll manufacturing agreements with Gulf Coast resin producers. Lock in dual-certification capacity before ISO 8317 harmonization pressures reshape ASTM-dominant supplier rankings. For New Entrants and Emerging Players: Enter via biodegradable laminate development targeting California's organic cannabis segment where sustainability premiums offset certification investment costs. White-space availability concentrates in German medical cannabis pharmacy distribution where EU MDR technical file pre-validation filters Asian competition. Pursue direct-to-consumer subscription channel partnerships requiring tamper-evident pouches with automated opening features. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified packaging conglomerates seeking ASTM-certified cannabis capacity. Five-to-ten year viability favors converters with dual pharmaceutical and cannabis certification portfolios rather than single-end-use specialists. Acquisition target archetype: regional digital printing specialists with validated California dispensary relationships and sub-500-unit minimum order capability. Monitor state-level cannabis packaging rule harmonization progress as inflection indicator for certification portfolio value.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Certification Portfolio Expansion | ASTM D3475 and ISO 8317 compliance captures volume from state cannabis program expansion and European medical cannabis distribution. |
| Biodegradable Laminate Development | Compostable child-resistant mechanisms open premium positioning in California organic cannabis and EU sustainability-sensitive segments. |
| Digital Printing Capability Investment | Water-based inkjet on flexible films collapses minimum order quantities and enables 48-hour turnaround for small-batch cultivators. |
| Backward Integration into Barrier Film Extrusion | Captive multi-layer laminate production insulates margins from polyethylene resin price volatility and Gulf Coast supply disruptions. |
| Full-Service Packaging Partnership Model | Bundled bags, labels, and compliance consulting displaces fragmented sourcing and captures dispensary procurement consolidation. |
Study Parameters
Multi-period observation of state cannabis packaging rule adoption, certification timeline compression, and resin price volatility anchored the trend analysis, supplemented by interviews with flexible packaging converters, dispensary procurement managers, pharmaceutical contract packers, and regulatory compliance consultants. Secondary validation drew from FDA 21 CFR filings, state cannabis board regulatory updates, ASTM protocol documentation, and SEC 10-K disclosures from diversified packaging conglomerates. Bottom-up demand modeling across product type, material, end user, and certification segments triangulated against top-down market sizing from trade association capacity surveys.
Segment-weighting approaches distributed volume and value projections across pouches, ziplock bags, laminated bags, and resealable formats by polyethylene, plastic, polyester, and paperboard substrates. Pharmaceutical, household products, food packaging, and personal care end-use categories were modeled with ASTM, FDA, ISO 9001, and CE marking certification tiers. CAGRs were derived from regression analysis of historical adoption curves and regulatory mandate implementation timelines. Forecast inputs incorporated state-by-state cannabis program expansion schedules and EU MDR technical documentation requirement phase-ins.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden resin price spikes, accelerated paperboard substitution, or federal cannabis rescheduling that harmonizes packaging requirements. Forecasts reflect documented assumptions about certification timeline friction, state regulatory fragmentation persistence, and barrier film technology evolution. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Anti-Corrosion Bags Market
Bags and Containers
Side Weld Bags Market
Bags and Containers
Bulk Bag Conditioners Market
Bags and Containers
Zipper Bags Market
Bags and Containers
Flip-Up Vacuum Pack Market
Bags and Containers
Conductive Bags Market
Bags and Containers
Trash Can Liners Market
Bags and Containers
Bag-In-Box Filler Market
Bags and Containers
Wicketed Bags Market
Bags and Containers
Piping Bags Market
Bags and Containers
Bag & Bag Aerosol Can Market
Bags and Containers
Inclusion Bags Market
Bags and Containers
Freezing Bags Market
Bags and Containers
Textile Bags Market
Bags and Containers
Aluminum Beverage Bags Market
Bags and Containers
Dome Shrink Basket Bags Market