
 Craft Bags Market | 2026-2036
Craft Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Craft Bags Market Outlook
The capital-intensity divergence between integrated pulp-to-bag manufacturers and converters reliant on merchant supply is collapsing as recycled fiber processing costs equalize. Mondi Group leverages captive forestry assets and on-site recycling to sustain margin structures that merchant-dependent competitors cannot replicate. Smurfit Kappa anchors its position through corrugated integration, extending containerboard expertise into premium craft bag grades. WestRock competes via automated converting lines that reduce unit labor across mid-volume orders.
Craft bags are paper, fabric, plastic, or jute containers engineered with specified basis weights, tensile strength ratings, and closure mechanisms for manual or light-mechanical handling of artisan goods, gifts, and specialty retail merchandise. Kraft paper grades between 80–150 gsm predominate in volume production, with bleached sulfate variants serving premium cosmetic and confectionery applications where surface printability and grease resistance matter. Paper material segments command the largest current volume position, though jute substrates are gaining fastest among event planners and luxury packaging buyers seeking tactile differentiation and natural fiber credentials. Customizable design types capture disproportionate margin pools, as digital print enablement allows short-run personalization at economics that previously required 10,000-unit minimums.
EU REACH chemical safety protocols and F-Gas Regulation indirectly shape substrate selection by restricting fluorinated coatings once common in grease-resistant paper bags. The US EPA recycled content guidelines and state-level extended producer responsibility frameworks in California and New York are elevating post-consumer fiber thresholds for craft bag suppliers seeking public-sector and enterprise contracts. Stakeholders must monitor how fragmented municipal composting certification standards across North American and European jurisdictions will determine which bio-based coating technologies achieve scalable adoption.
Market Dynamics
Recycled fiber processing cost equalization between integrated pulp-to-bag manufacturers and merchant-dependent converters is collapsing historical margin structures and forcing capital deployment decisions across the craft bags supply base.
Growth Catalysts
- EU Green Deal single-use plastic restrictions:Germany's specialty stationery retailers and craft supply distributors are accelerating paper substrate migration as regulatory deadlines approach, concentrating demand in Western European markets.
- Digital print enablement:Short-run personalization capabilities are capturing disproportionate margin pools by reducing minimum order quantities from 10,000 units to economically viable smaller batches for boutique retail chains.
- Jute substrate adoption:Event planners and luxury packaging buyers are driving fastest material segment expansion through tactile differentiation and natural fiber credentials in premium artisan packaging applications.
Market Restraints
- Recycled fiber input cost volatility:Post-consumer fiber price swings compress converter margins when merchant supply contracts reset quarterly, particularly affecting non-integrated producers without captive pulp sources.
- Fluorinated coating restrictions:EU REACH chemical safety protocols and F-Gas Regulation eliminate grease-resistant paper bag options, forcing reformulation investments before compliant bio-based alternatives achieve scale.
- Plastic bag substitution persistence:Thin-gauge polypropylene carry bags retain cost advantages in price-sensitive mass retail channels where sustainability premiums face buyer resistance.
Strategic Opportunities
- US state-level extended producer responsibility:California and New York frameworks are elevating post-consumer fiber thresholds, creating contract advantages for suppliers meeting EPA recycled content guidelines in public-sector procurement.
- Bio-based coating technology convergence:Water-based barrier coatings combined with compostable adhesive systems enable grease-resistant paper bags without fluorinated chemistry, opening food service applications previously closed to fiber substrates.
- Boutique retail chain expansion:Artisan packaging procurement from specialty retailers is concentrating volume among converters capable of customized design types with rapid turnaround.
Industry Challenges
- Fragmented municipal composting certification:Divergent standards across North American and European jurisdictions delay scalable adoption of bio-based coating technologies as suppliers await harmonized testing protocols.
- Automated converting line capex requirements:Mid-volume order competitiveness demands equipment investments that strain balance sheets for converters without corrugated integration or containerboard expertise to cross-subsidize.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Craft Bags Market |
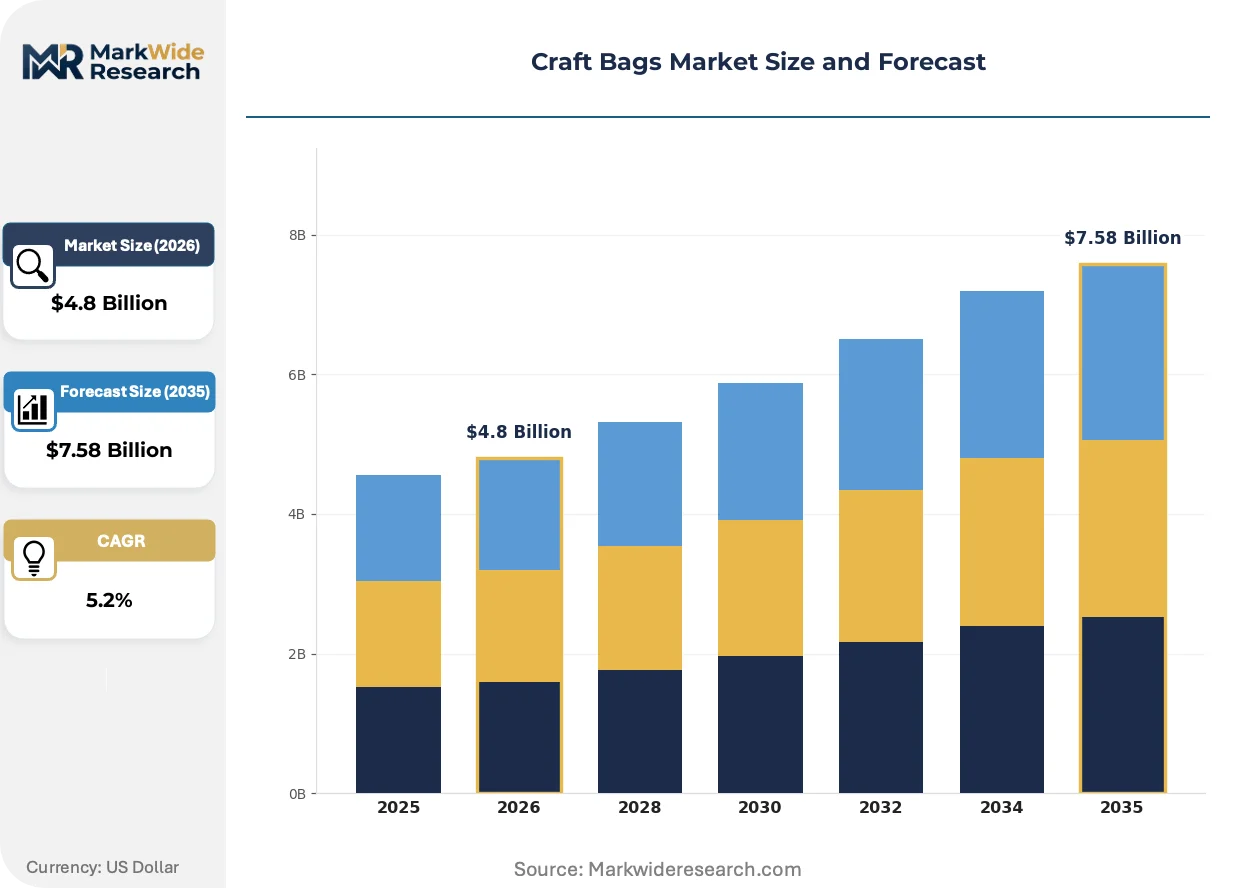
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.58 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Paper, Fabric, Plastic, Jute Design Type: Reusable, Foldable, Stand-Up, Customizable Size: Small, Medium, Large, Extra Large End User: Retailers, Artisans, Event Planners, Crafters |
| Companies Covered | Mondi Group, WestRock, Smurfit Kappa, International Paper, DS Smith, Novolex, Oji Holdings, Stora Enso, Genpak, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Craft Bags Market Strategic Shifts
Digital production technologies and regulatory chemistry restrictions are simultaneously enabling customization economics and eliminating incumbent material solutions across craft bag manufacturing.
Water-based barrier coating systems are decomposing the historical advantage of fluorinated grease-resistant papers by delivering comparable oil resistance without restricted perfluorinated substances. Premium cosmetic and confectionery packagers in Germany and France are adopting these reformulated substrates ahead of EU enforcement timelines. The technology is decomposing incumbent supply relationships as converters without coating partnerships lose access to food-contact compliant specifications.
REACH chemical safety protocols and F-Gas Regulation are eliminating fluorinated coating options for grease-resistant paper bags across European manufacturing. Industrial consequence includes accelerated R&D spending on polysaccharide and protein-based barrier layers that meet migration limits. Specialty stationery retailers and craft supply distributors in Germany are most affected, responding by qualifying alternative suppliers with compliant coating capabilities before 2025 restriction phases.
Buyer concentration among boutique retail chains is compressing supplier switching cycles from annual to quarterly review periods. Specialty retailers are consolidating craft bag procurement through direct converter relationships, displacing wholesale distributor intermediaries. This pattern is most visible in Germany's artisan packaging segment where retail chain expansion favors vendors with digital print infrastructure and design services.
Craft Bags Market Segmentation
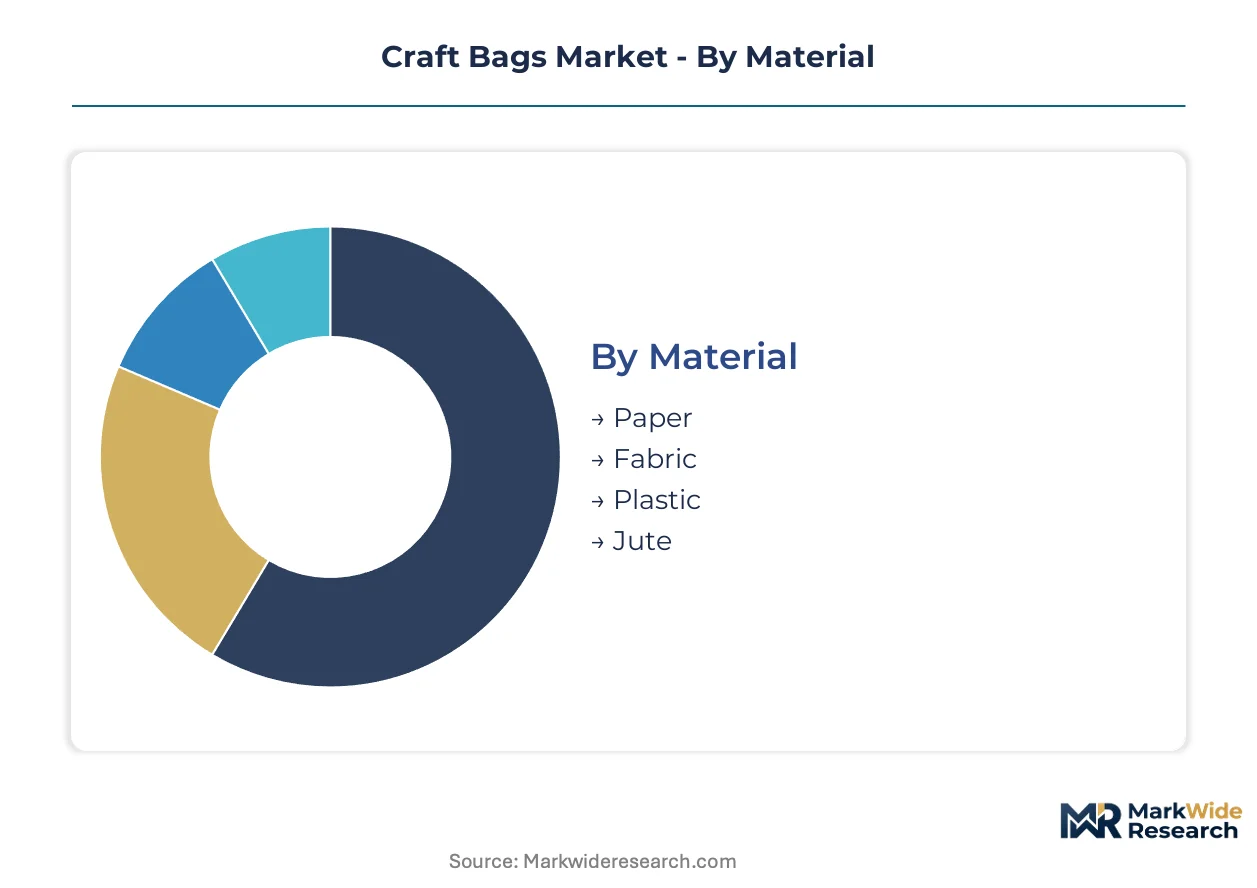
Segmentation in craft bags reveals how substrate chemistry, structural design, and buyer economics create distinct competitive arenas. Each dimension carries different margin profiles and regulatory exposure, forcing suppliers to prioritize capability investments against specific demand clusters.
Material:
Substitution pressure runs strongest against plastic substrates as regulatory bans and brand sustainability commitments erode incumbent positions.
- Paper:Kraft grades between 80–150 gsm dominate volume production, with bleached sulfate variants serving premium cosmetic and confectionery applications where surface printability and grease resistance matter. Germany's specialty stationery retailers and craft supply distributors are accelerating procurement as EU Green Deal deadlines approach.
- Jute:Natural fiber credentials and tactile differentiation are driving fastest expansion among event planners and luxury packaging buyers seeking artisan authenticity. The material commands premium positioning where sustainability signaling justifies cost multiples over paper alternatives.
- Fabric:Cotton and canvas variants serve reusable bag applications with extended lifecycle requirements, concentrating demand among boutique retail chains emphasizing durability messaging.
- Plastic:Thin-gauge polypropylene retains cost advantages in price-sensitive mass retail channels where regulatory enforcement remains fragmented and sustainability premiums face buyer resistance.
Paper anchors the volume base while jute gains share at the steepest rate.
Design Type:
Margin concentration follows customization depth, with digital print infrastructure determining competitive access to premium pricing tiers.
- Customizable:Digital print enablement allows short-run personalization at economics that previously required 10,000-unit minimums, capturing disproportionate margin pools. Boutique retail chains are consolidating procurement through direct converter relationships that displace wholesale distributor intermediaries.
- Reusable:Reinforced construction and extended lifecycle specifications align with corporate sustainability procurement frameworks, particularly in public-sector and enterprise contract segments where EPA recycled content guidelines apply.
- Stand-Up:Structural rigidity through bottom gusset engineering expands utility into food service and specialty retail display applications.
- Foldable:Compact storage characteristics serve event logistics and travel retail channels where space efficiency drives procurement decisions.
Customizable designs command the highest margin tier while reusable formats expand most quickly under regulatory pressure.
Size:
Volume distribution reflects retail channel concentration, with mid-size formats capturing the intersection of handling convenience and merchandise versatility.
- Medium:Standardized dimensions align with automated converting line economics and mid-volume order competitiveness, dominating procurement from specialty retailers.
- Small:Compact formats serve confectionery, cosmetics, and jewelry applications where premium presentation justifies per-unit cost premiums.
- Large:Extended capacity requirements concentrate in artisan goods and gift packaging segments where bulk merchandise handling drives specification.
- Extra Large:Oversized construction demands specialized equipment and material grades, limiting supplier participation to integrated manufacturers with containerboard expertise.
Medium sizes anchor production planning while small formats climb fastest through premium channel expansion.
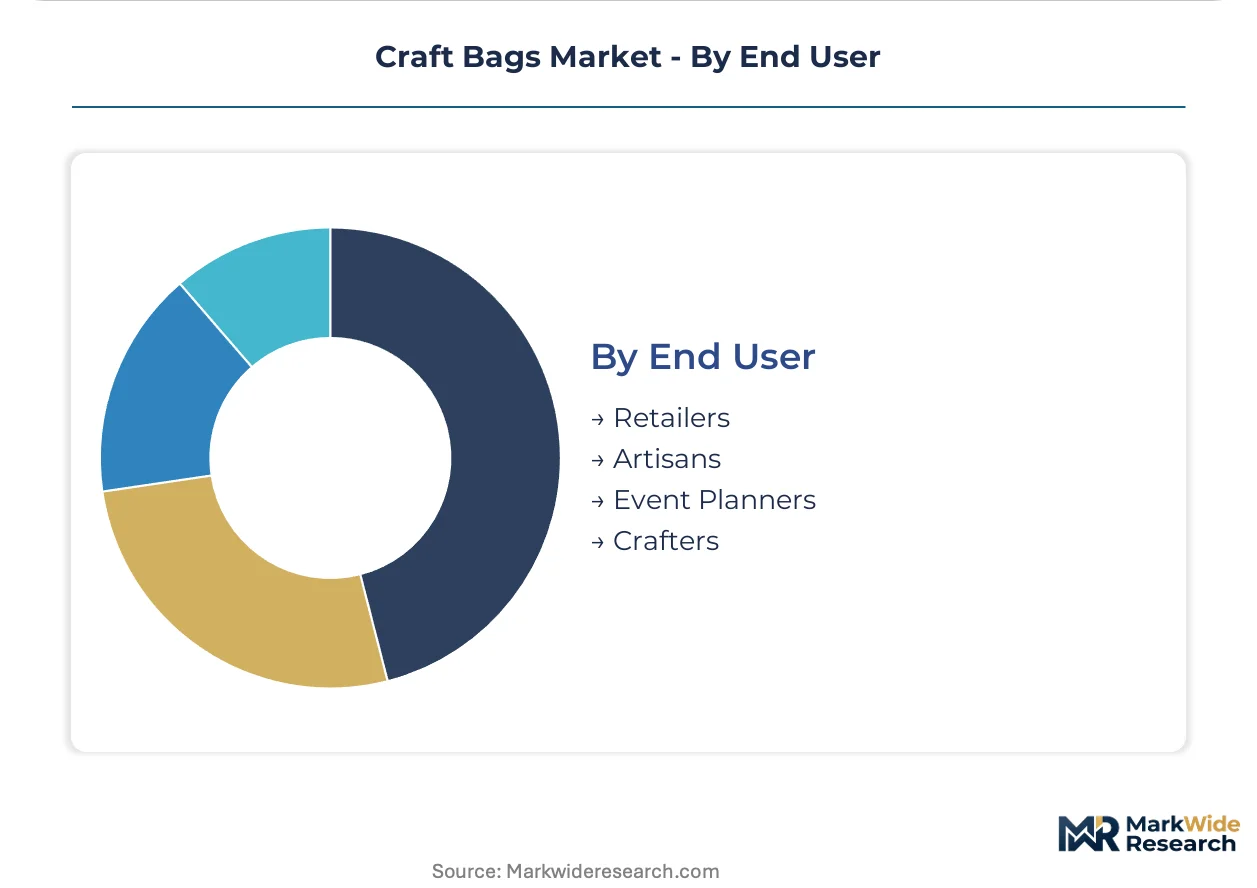
End User:
Procurement authority is shifting from wholesale distributors to direct retail chain relationships, compressing supplier switching cycles and demanding rapid turnaround capabilities.
- Retailers:Boutique retail chains are expanding craft bag procurement for artisan packaging, consolidating volume among converters with digital print infrastructure and design services. Germany's specialty stationery retailers demonstrate this pattern most visibly.
- Event Planners:Jute substrate adoption concentrates here, driven by tactile differentiation requirements and natural fiber credentials in luxury packaging applications.
- Artisans:Small-batch customization needs align with digital print enablement, though order fragmentation challenges unit economics for non-specialized suppliers.
- Crafters:Hobbyist demand channels through craft supply distributors, with price sensitivity limiting premium substrate penetration.
Retailers anchor volume concentration while event planners drive the steepest material mix shift toward natural fibers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and France absorb sustainability premiums with minimal price elasticity, while mass retail channels in the United States and India resist cost increases above commodity paper grades. This demand-elasticity contrast shapes regional procurement patterns and supplier margin structures.
Germany
Specialty stationery retailers and craft supply distributors dominate procurement, consolidating volume through direct converter relationships. The EU Green Deal's single-use plastic restrictions accelerate paper substrate migration ahead of enforcement deadlines. Berlin and Hamburg anchor demand concentration, with boutique retail chains expanding artisan packaging procurement.
United States
State-level extended producer responsibility frameworks in California and New York elevate post-consumer fiber thresholds for public-sector contracts. The EPA recycled content guidelines shape enterprise procurement specifications. Mid-Atlantic and Pacific Coast metropolitan clusters concentrate demand from event planners and luxury packaging buyers.
France
Premium cosmetic and confectionery packagers drive bleached sulfate grade consumption for surface printability and grease resistance applications. ECHA REACH protocols and F-Gas Regulation eliminate fluorinated coating options, forcing reformulation investments. Paris and Lyon metropolitan areas concentrate specialty retail and artisan goods packaging demand.
China
Dual carbon goals and MIIT sustainable packaging directives redirect manufacturing investment toward recycled fiber processing capabilities. Yangtze River Delta industrial clusters integrate digital print infrastructure for export-oriented craft bag production. Shanghai and Jiangsu province converters serve European and North American boutique retail chains.
India
Price-sensitive mass retail channels limit premium substrate penetration, with jute adoption concentrated among event planners in metropolitan centers. BIS packaging standards and DGFT export incentives shape domestic manufacturing investment. Maharashtra and Gujarat industrial corridors expand kraft paper converting capacity for domestic and Middle Eastern markets.
Craft Bags Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the craft bags supply base. Integrated pulp-to-bag manufacturers sustain margin structures through captive fiber sourcing, while merchant-dependent converters compete on automated throughput and short-run customization economics. Three archetypes dominate: forestry-integrated multinationals, corrugated-specialist converters, and digital-enabled boutique suppliers. Competitive moves concentrate on coating technology partnerships and regional capacity expansion.
Within the integrated forestry tier, Mondi Group and Smurfit Kappa exemplify archetypes leveraging captive pulp sources and containerboard expertise respectively. WestRock occupies a position at the automated converting intersection, representing scale-driven competitiveness in mid-volume order segments. These three entities anchor the competitive structure through differentiated control points: upstream fiber security, corrugated integration, and manufacturing automation.
| Leading Market Players |
|---|
| Mondi Group |
| WestRock |
| Smurfit Kappa |
| International Paper |
| DS Smith |
| Novolex |
| Oji Holdings |
| Stora Enso |
| Genpak |
| Others |
Value Chain & Pricing Dynamics
Automated converting line scale economies in Germany and China anchor price floors by compressing unit labor costs below thresholds that mid-volume merchant-dependent converters can match. This concentration of efficient capacity simultaneously elevates bargaining power for integrated manufacturers and forces smaller competitors toward digital customization niches where minimum order quantity economics no longer protect margins.
Pricing Analysis
After-sales revenue from design services and rapid-turnaround logistics drives lifetime value more than per-unit bag margins. Three-tier pricing structure across premium, standard, and economy levels segments buyers by customization depth and certification grade. Price differentiation hinges on digital print infrastructure ownership and EU Green Deal compliance certification. Pricing pressure stems from recycled fiber input cost volatility compressing converter margins when merchant supply contracts reset. Boutique retail chains demonstrate lowest price sensitivity, while mass retail channels in India resist premiums above commodity kraft grades.
Supply Chain Analysis
Strategic stockpile preferences dominate among integrated pulp-to-bag manufacturers with captive forestry assets, while just-in-time inventory governs merchant-dependent converters exposed to quarterly fiber price resets. Supply concentrates in Germany, China, and India as primary converting hubs. Raw material dependencies center on post-consumer recycled fiber, virgin kraft pulp, and jute fiber imports. Tariff exposure on coated paper substrates from F-Gas Regulation enforcement creates single-source vulnerability for grease-resistant grades. Distribution runs through direct converter relationships with boutique retail chains, displacing wholesale distributor intermediaries in Germany and France.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Craft bags constitute a defensive-moat market where regulatory entrenchment from EU REACH and F-Gas compliance creates switching costs that lock in qualified suppliers ahead of enforcement deadlines.
For Market Incumbents: Secure captive fiber sourcing through backward integration into recycled processing or long-term merchant supply contracts before quarterly price volatility escalates. Expand digital print infrastructure in Germany to capture boutique retail chain procurement consolidating away from wholesale distributors. Defend against jute substrate entrants by accelerating water-based barrier coating partnerships that maintain food-contact compliance without fluorinated chemistry. For New Entrants and Emerging Players: Design-service gaps in rapid-turnaround customization expose incumbents who optimize for volume over agility. Target artisan and event planner segments in France and the US Mid-Atlantic where digital print minimums still exclude small-batch buyers. Penetrate through compostable adhesive system partnerships that resolve fragmented municipal certification barriers before harmonized standards emerge. For Investors and Strategic Acquirers: Digital-enabled boutique suppliers with coating technology partnerships represent the most defensible acquisition archetype as regulatory chemistry restrictions eliminate incumbent options. Long-term viability rests on positioning ahead of bio-based barrier scale economics and EU Green Deal enforcement waves. Watch for water-based coating adoption rates crossing thresholds that signal sustainable margin structures.| Strategic Initiative | Industry Significance |
|---|---|
| Water-Based Barrier Coating Partnership | Enables EU REACH-compliant grease resistance without fluorinated chemistry for food service applications. |
| Digital Print Infrastructure Expansion | Captures boutique retail chain procurement consolidating through direct converter relationships in Germany. |
| Recycled Fiber Processing Investment | Equalizes cost structures with integrated manufacturers and stabilizes margin exposure to merchant volatility. |
| Compostable Adhesive System Qualification | Resolves fragmented municipal certification barriers delaying scalable bio-based coating adoption. |
| Jute Substrate Capacity Addition | Addresses fastest material segment expansion among event planners and luxury packaging buyers seeking tactile differentiation. |
Study Parameters
Initial hypotheses were tested against primary input from packaging procurement managers at boutique retail chains, converting line operations directors, sustainability compliance officers, and craft supply distributor category buyers and refined through secondary validation. Primary fieldwork combined structured interviews with secondary sources including EU ECHA regulatory filings, EPA recycled content guideline documentation, customs trade data on kraft paper and jute fiber flows, and SEC disclosures from integrated forestry multinationals. Bottom-up volume modeling across substrate grades and design types triangulated against top-down market sizing from trade association data.
Variance decomposition across material segments, design customization tiers, and regional regulatory clusters shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include substrate chemistry, structural design type, size format, and end-user procurement authority. CAGRs derived from elasticity-adjusted demand curves incorporating EU Green Deal enforcement phasing and digital print adoption S-curves. Industry-specific inputs encompassed post-consumer fiber price indices and boutique retail chain expansion rates.
Forecasts assume regulatory continuity in EU REACH, F-Gas Regulation, and US EPA recycled content frameworks; material policy shifts would require re-modeling substrate substitution trajectories. Specific risk factors include harmonized municipal composting certification delays and unexpected relaxation of single-use plastic restrictions. Revision becomes warranted when water-based barrier coating adoption crosses thresholds that signal incumbent fluorinated chemistry displacement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Scented Trash Bags Market
Bags and Containers
Self-Sealed Bubble Bags Market
Bags and Containers
Frosted Bag Market
Bags and Containers
Mylar Bags Market
Bags and Containers
Bag-In-Box Container Market
Bags and Containers
Liquid Packaging Bag Market
Bags and Containers
Drink Carrier Poly Bags Market
Bags and Containers
Self-Sealing Bags Market
Bags and Containers
Child Resistant Bags Market
Bags and Containers
Middle East & Africa Paper Bags Market
Bags and Containers
Bakery Bread Bag Market
Bags and Containers
Twisted Handle Bags Market
Bags and Containers
Hermetic Storage Bags Market
Bags and Containers
Vacuum Shrink Bags Market
Bags and Containers
Anti-Corrosion Bags Market
Bags and Containers
Non-Laminated Heat-Sealed Bags Market