
 Colombia Pouch Packaging Market | 2026-2036
Colombia Pouch Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Colombia Pouch Packaging Market Insights
Polyethylene terephthalate (PET) laminates is rebalancing cost-performance trade-offs as brand owners shift from rigid containers to flexible formats. Amcor Group GmbH leverages its global film technology portfolio to serve multinational food clients operating in Colombia. Colplas S.A.S anchors domestic supply through localized extrusion and converting capabilities for regional dairy and snack producers. Mondi PLC competes with specialized kraft-paper-barrier solutions targeting Colombia's growing sustainable packaging segment.
Pouch packaging denotes a flexible container formed from multilayer films or laminates, typically sealed on three or four sides with optional reclosure features, designed to protect contents from moisture, oxygen, and light while minimizing material weight versus rigid alternatives. Stand-up pouches dominate retail shelf presence in Colombia's supermarket channel due to their billboard effect and pallet efficiency. Spouted pouches represent the fastest-growing closure format as parents and on-the-go consumers prioritize controlled dispensing for beverages and baby food. Composites command premium positioning where aluminum-oxide or ethylene-vinyl-alcohol barrier layers extend shelf life for coffee exports and pharmaceutical sachets.
Colombia's Ministry of Health and Social Protection enforces food-contact material migration limits through resolutions aligned with Mercosur GMC standards, compelling converters to validate laminate safety for acidic and fatty food applications. The National Institute of Metrology (INM) and the Superintendency of Industry and Commerce monitor labeling accuracy and greenwashing claims on biodegradable assertions. Stakeholders must track impending regulatory revisions on single-use plastics in Colombia's Pacific and Caribbean coastal departments where marine-debris scrutiny intensifies.
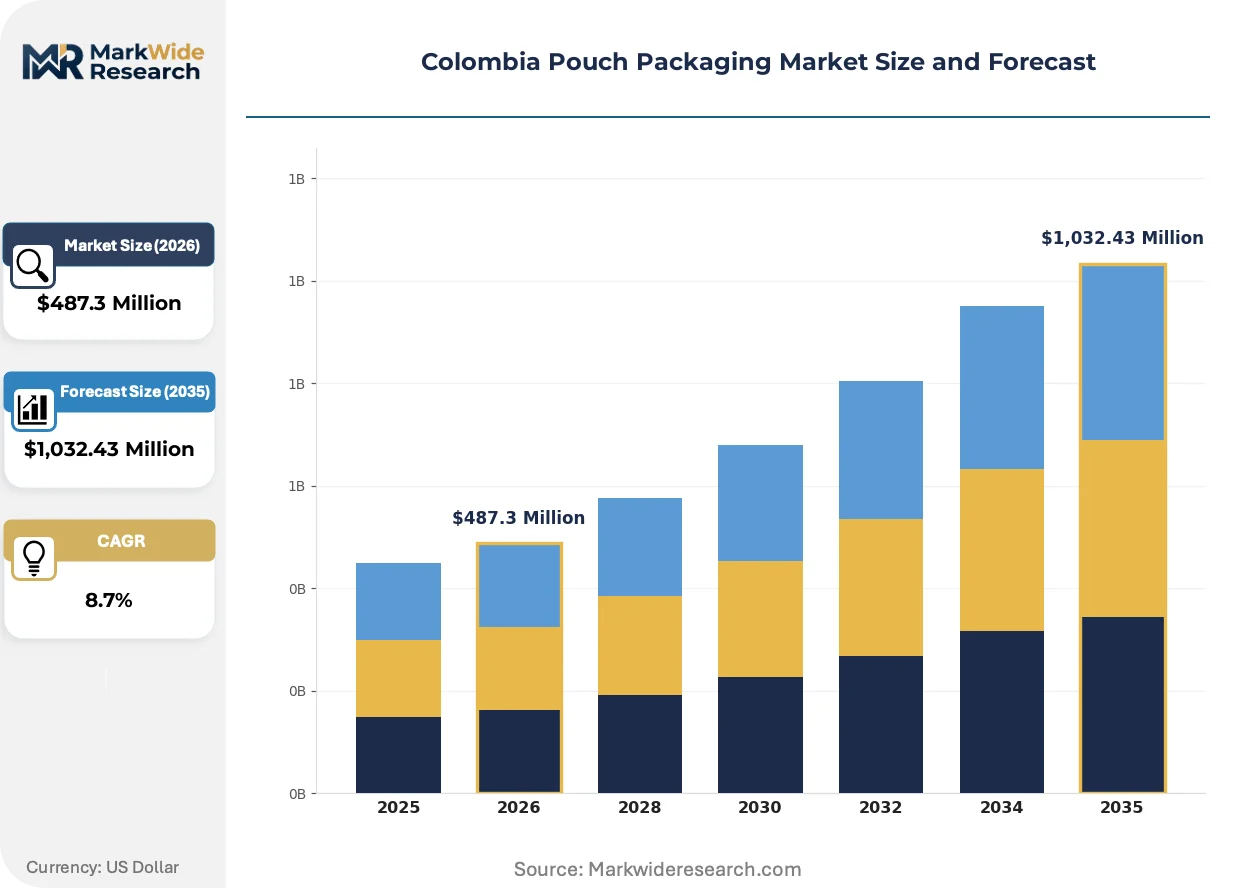
Market Dynamics
Colombia's Ministry of Environment and Sustainable Development is tightening extended producer responsibility rules for plastic packaging waste, forcing converters to redesign multilayer laminates for recyclability while maintaining barrier performance for coffee exports and ready-to-eat meals.
Growth Catalysts
- EPR Regulation Tightening:The Ministry of Environment and Sustainable Development's stricter producer responsibility rules are accelerating investment in mono-material and recyclable pouch structures among domestic converters.
- Coffee Export Quality Demands:Specialty coffee processors in Antioquia and Caldas require high-barrier aluminum-oxide laminates to preserve aroma during ocean freight to North American and European buyers.
- Spouted Pouch Adoption:Parents and on-the-go consumers in Bogotá's supermarket channel are prioritizing controlled dispensing formats for beverages and baby food, expanding addressable pouch applications.
Market Restraints
- Resin Import Dependency:Colombia's domestic petrochemical capacity covers less than half of polyethylene and polypropylene demand, exposing converters to dollar-denominated resin volatility and freight cost spikes from Gulf Coast suppliers.
- Multilayer Recyclability Gap:Current aluminum-oxide and ethylene-vinyl-alcohol barrier technologies create technically non-recyclable structures that conflict with impending single-use plastic restrictions in Pacific and Caribbean coastal departments.
- Converting Equipment Concentration:High-performance pouch converting lines from European and Japanese manufacturers require 18-24 month lead times, constraining rapid capacity expansion for mid-tier domestic processors.
Strategic Opportunities
- Paper-Barrier Convergence:Mondi PLC's kraft-paper-barrier solutions demonstrate viable fiber-based alternatives for Colombia's sustainable packaging segment, opening premium positioning in Bogotá's organic retail channel.
- Pharmaceutical Sachet Expansion:Colombia's generics pharmaceutical sector requires unit-dose pouch formats for rural distribution, creating demand for validated barrier laminates meeting Ministry of Health migration limits.
- Coastal Department Pre-Compliance:Anticipated marine-debris regulations in Pacific and Caribbean zones reward early movers with recyclable mono-material structures before mandatory implementation.
Industry Challenges
- Barrier Chemist Talent Scarcity:Colombia's technical universities produce limited graduates with expertise in coextrusion die design and adhesive lamination chemistry, forcing converters to recruit from Mexico and Brazil.
- Migration Testing Bottlenecks:INM-certified laboratories face 12-16 week queues for food-contact material validation, delaying new laminate launches for acidic sauce and fatty snack applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Colombia Pouch Packaging Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Up Pouches, Flat Pouches, Spouted Pouches, Vacuum Pouches Material: Plastic, Aluminum, Paper, Composites Application: Food & Beverage, Personal Care, Pharmaceuticals, Household Products Closure Type: Zip Lock, Heat Seal, Tear Notch, Spout |
| Companies Covered | Amcor Group GmbH, Mondi PLC, Berry Global Inc, Colplas S.A.S, Sonoco Products Company, Tetra Pak, Viappiani de Colombia S A S, PPC Flex Company Inc, Amfora Packaging S.A.S, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Colombia Pouch Packaging Market Trends and Innovations
Digital printing and smart packaging technologies are compressing minimum order quantities and enabling batch-level traceability for Colombia's export-oriented coffee and chocolate sectors, reshaping converter-customer relationships.
High-barrier mono-material polyethylene structures are converging with mechanical recycling streams to maintain shelf life for coffee exports while satisfying Ministry of Environment recyclability mandates. Antioquia-based cooperatives are piloting these structures for single-origin lots destined for European specialty roasters. The technology is converging with existing extrusion assets, allowing regional converters to avoid capital-intensive equipment replacement.
Colombia's Ministry of Health and Social Protection is enforcing food-contact material migration limits through resolutions aligned with Mercosur GMC standards. This regulatory alignment compels converters to validate laminate safety for acidic and fatty food applications before commercialization. Dairy processors in the Bogotá industrial corridor are responding by consolidating supplier bases to proven vendors with existing migration documentation.
Supermarket private-label buyers are consolidating pouch procurement through direct converter relationships, displacing traditional distributor intermediaries in Bogotá's retail channel. This channel compression demands converters invest in design services and inventory flexibility previously handled by intermediaries. The shift is most visible among mid-size snack brands seeking shelf differentiation in Éxito and Carulla store networks.
Colombia Pouch Packaging Market Segmentation
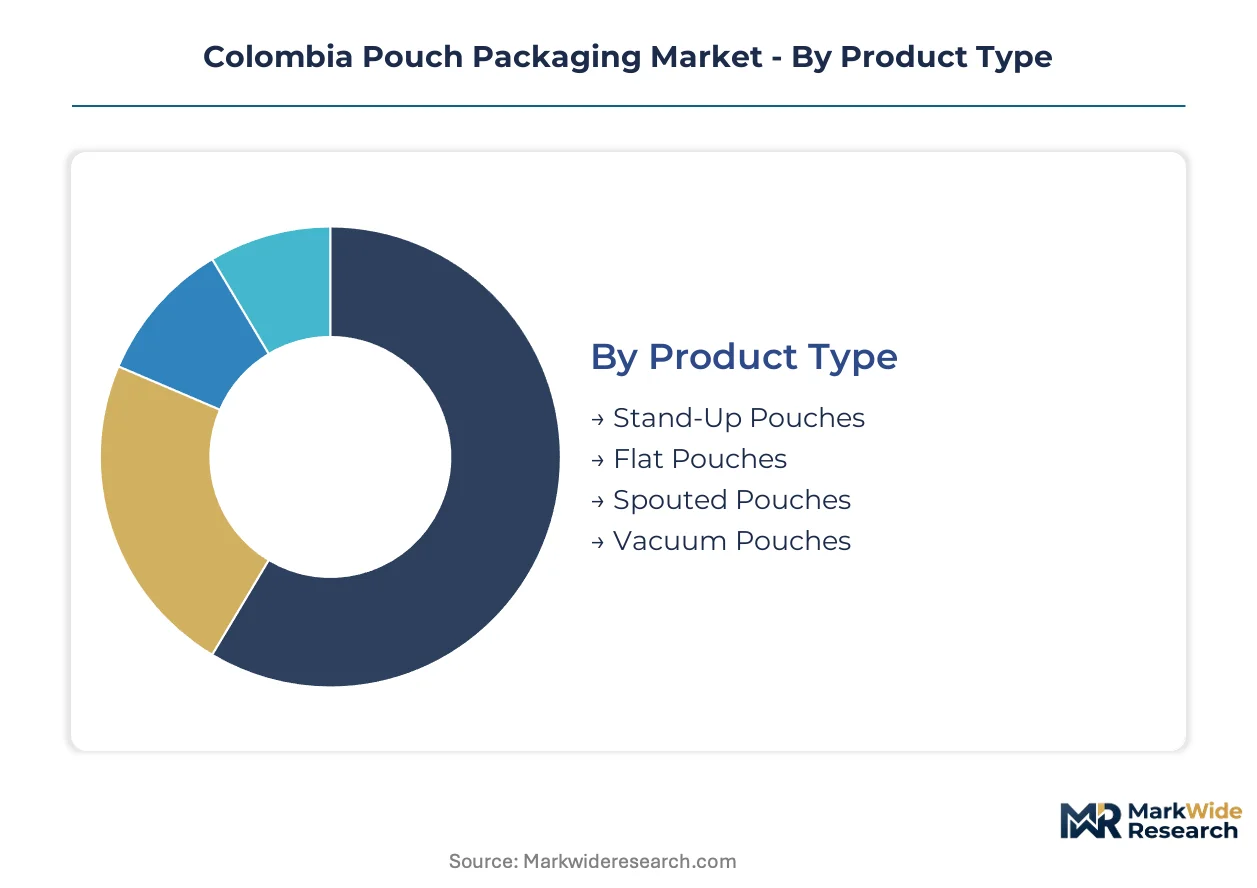
Pouch packaging in Colombia fragments across material barriers, dispensing formats, and regulatory exposure. Each segment carries distinct migration-testing burdens and EPR compliance timelines that reshape converter investment priorities.
Product Type:
Stand-up pouches and spouted variants demand Ministry of Health food-contact certifications for acidic sauces and beverages, while vacuum formats face lighter pharmaceutical-grade validation.
- Stand-Up Pouches:Multilayer laminates with gusseted bases create vertical shelf presence in Éxito and Carulla networks. Demand concentrates among coffee exporters in Antioquia requiring aluminum-oxide barriers for aroma retention during ocean freight to European buyers.
- Spouted Pouches:Injection-molded fitments welded to flexible faces enable controlled dispensing for infant nutrition and sports drinks. Parents in Bogotá's supermarket channel are prioritizing these formats, expanding addressable applications beyond traditional rigid alternatives.
- Flat Pouches:Three-side-seal structures dominate pharmaceutical sachet production for rural generics distribution.
- Vacuum Pouches:High-barrier coextrusions extend refrigerated meat shelf life in Caldas processing facilities.
Leading the category by volume: Stand-Up Pouches. Expanding most quickly: Spouted Pouches.
Material:
Material selection determines recyclability compliance under tightening Ministry of Environment rules and dictates resin import exposure for domestic converters.
- Plastic:Polyethylene and polypropylene laminates anchor cost-sensitive snack applications. Bogotá's industrial corridor processors are piloting mono-material polyethylene structures to align with impending single-use plastic restrictions in Pacific coastal departments.
- Composites:Aluminum-oxide and ethylene-vinyl-alcohol barrier layers preserve coffee aroma for export lots. Specialty roasters in Caldas require these premium laminates despite technical non-recyclability that conflicts with EPR mandates.
- Paper:Kraft-barrier hybrids from Mondi PLC serve organic retail channels seeking fiber-based alternatives.
- Aluminum:Pure foil structures command pharmaceutical unit-dose applications with strict migration limits.
Plastic dominates tonnage. Composites capture premium positioning. Paper gains share fastest in Bogotá's sustainable segment.
Application:
Food and pharmaceutical applications carry the heaviest regulatory burden, while personal care faces lighter cosmetic-grade standards.
- Food & Beverage:Acidic sauces and fatty snacks require INM-certified migration testing under Mercosur-aligned resolutions. Dairy processors in the Bogotá corridor are consolidating supplier bases to proven vendors with existing documentation, compressing qualification timelines.
- Pharmaceuticals:Unit-dose sachets for rural generics distribution demand validated barrier laminates meeting Ministry of Health limits. The segment is climbing the fastest as domestic pharmaceutical production expands beyond metropolitan centers.
- Personal Care:Stand-up pouches for shampoo and conditioner samples target hotel and travel retail channels.
- Household Products:Refill pouches for surface cleaners reduce rigid bottle consumption in urban supermarkets.
Food and Beverage leads by volume. Pharmaceuticals posts the steepest expansion trajectory. Personal Care and Household Products trail with lighter regulatory overhead.
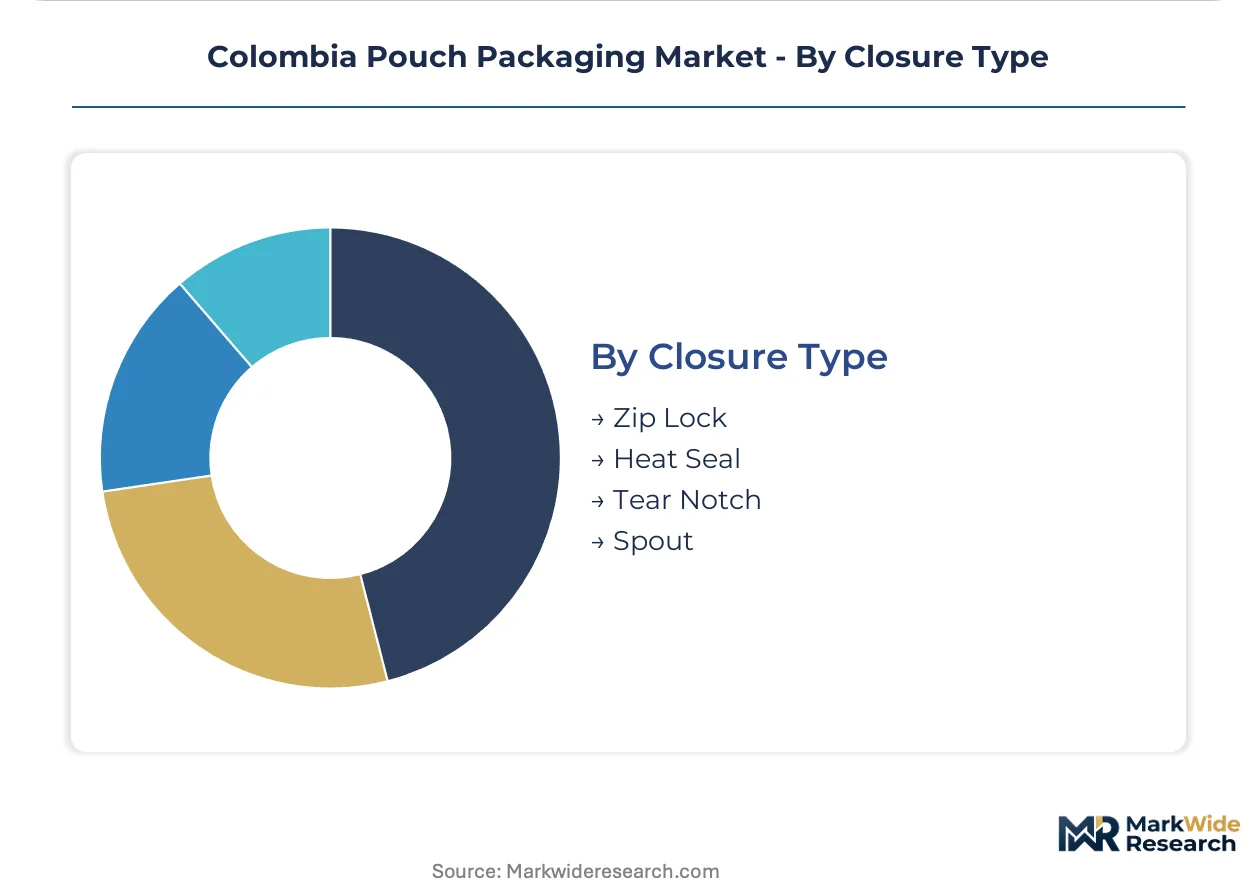
Closure Type:
Closure complexity determines reclosure performance and line-speed compatibility for Colombian converters with European and Japanese equipment.
- Heat Seal:Thermal bonding of multilayer films creates hermetic barriers for coffee and pharmaceutical applications. The format dominates export-oriented production in Antioquia due to equipment compatibility with existing converting lines.
- Spout:Injection-molded dispensing fitments require ultrasonic or thermal welding to pouch faces. Parents and on-the-go consumers in Bogotá are driving adoption for beverages and purees, though equipment lead times of 18-24 months constrain rapid capacity expansion.
- Zip Lock:Press-to-close profiles enable repeated access for snacks and dried fruits.
- Tear Notch:Laser-scored openings provide controlled initiation for single-serve pharmaceutical sachets.
Heat Seal dominates volume. Spout gains share fastest among premium formats. Zip Lock and Tear Notch serve niche convenience and compliance roles respectively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Colombia's Free Trade Zone regime accelerates pouch packaging concentration in designated industrial corridors, drawing multinational converters and domestic suppliers into tax-advantaged enclaves while shaping regional investment patterns across the Andean nation's key production clusters.
Bogotá Capital District
Multinational food processors and dairy conglomerates anchor demand for high-barrier laminates in the capital's industrial corridor. Colombia's Ministry of Health and Social Protection enforces Mercosur-aligned migration testing from its Bogotá headquarters, compelling converters to maintain certified laboratory partnerships within the metro area. The Fontibón and Soacha manufacturing zones concentrate extrusion and converting capacity serving Éxito and Carulla retail networks.
Antioquia Department
Specialty coffee exporters in Medellín and surrounding municipalities drive premium aluminum-oxide laminate consumption for North American and European shipments. The Ministry of Environment and Sustainable Development monitors extended producer responsibility compliance across Antioquia's processing cooperatives, pushing adoption of trial mono-material structures. The Rionegro and La Ceja industrial corridors host pilot programs for recyclable coffee pouches bound for EU specialty roasters.
Caldas Department
Manizales-based coffee federations and regional snack processors generate concentrated demand for spouted and stand-up pouch formats. The National Institute of Metrology maintains regional calibration facilities in the department, reducing validation timelines for local converters. The Chinchiná and Villamaría production clusters specialize in vacuum pouches for refrigerated meat exports to Panama and Ecuador.
Valle del Cauca Department
Cali's pharmaceutical manufacturing base expands unit-dose sachet requirements for rural generics distribution. Colombia's generics pharmaceutical sector sources validated barrier laminates from converters operating in the Yumbo and Palmira industrial zones. The Buenaventura Pacific port proximity intensifies scrutiny of marine-debris regulations, accelerating pre-compliance investments in recyclable structures.
Atlantic Coast Departments
Barranquilla and Cartagena processors face heightened single-use plastic restrictions in Caribbean coastal zones where tourism-driven marine conservation pressures mount. The Ministry of Environment targets these departments for impending EPR enforcement timelines ahead of interior regions. Local converters in the Malambo industrial corridor experiment with paper-barrier hybrids for hotel and travel retail channels serving cruise and resort markets.
Colombia Pouch Packaging Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with multinational film technology providers capturing premium export-oriented accounts while domestic extruders serve cost-sensitive regional dairy and snack producers. The market exhibits tiered concentration: global converters with patented barrier portfolios occupy the high-value coffee and pharmaceutical niches, mid-scale regional players dominate standard food applications, and small local shops fill custom short-run orders. Strategic archetypes include technology licensors leveraging global R&D, integrated converters with captive resin relationships, and design-focused specialists winning private-label supermarket contracts. Competitive intensity centers on migration documentation speed and EPR-compliant material portfolios rather than price alone.
Among globally positioned packaging groups, Amcor Group GmbH and Mondi PLC exemplify divergent approaches to Colombia's sustainability transition. Amcor's multinational film technology portfolio serves branded food clients requiring consistent barrier performance across Latin American operations. Mondi PLC anchors the paper-barrier convergence with kraft-based alternatives targeting Bogotá's organic retail channel. Domestic specialist Colplas S.A.S occupies a position bridging regional supply security and localized technical service for Antioquia and Caldas coffee processors. These three represent the archetype spectrum: global technology licensor, sustainable material innovator, and regional integrated converter.
| Leading Market Players |
|---|
| Amcor Group GmbH |
| Mondi PLC |
| Berry Global Inc |
| Colplas S.A.S |
| Sonoco Products Company |
| Tetra Pak |
| Viappiani de Colombia S A S |
| PPC Flex Company Inc |
| Amfora Packaging S.A.S |
| Others |
Pricing and Supply Chain Analysis
Barrier-certification divergence between aluminum-oxide laminates for coffee exports and mono-material polyethylene for domestic recyclability manifests in dual pricing tracks and bifurcated resin sourcing strategies across Colombian converters. This split forces processors to maintain parallel inventory positions for high-barrier premium grades and EPR-compliant standard grades, amplifying working capital intensity.
Pricing Analysis
Volume-margins split sharply between commodity polyethylene laminates serving Bogotá snack processors and specialty aluminum-oxide structures for Antioquia coffee exporters. Pricing stratifies across premium, standard, and economy tiers driven by barrier complexity and Ministry of Health migration certification status. Cost compression in standard-grade polyethylene intensifies because Gulf Coast resin volatility transmits directly through dollar-denominated import contracts. Supermarket private-label buyers in the Éxito network exhibit highest price sensitivity, while specialty coffee cooperatives in Caldas prioritize aroma preservation over unit cost.
Supply Chain Analysis
Ministry of Health migration certification gates supplier qualification, creating 12-16 week validation queues at INM-certified laboratories that filter converter access to food-contact applications. Resin supply concentrates in the United States, Saudi Arabia, and Brazil, with Bogotá processors drawing from Gulf Coast polyethylene and polypropylene shipments through Cartagena port. Raw material dependencies center on ethylene feedstock, metallocene catalysts, and adhesive lamination chemistries. Single-source vulnerability runs through European and Japanese converting equipment manufacturers with 18-24 month delivery timelines. Distribution runs through direct converter relationships with multinational food clients and regional dairy processors, displacing traditional distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Colombia's pouch packaging sector is becoming a vertical-integration race as converters pursue captive resin relationships and in-house migration testing to compress qualification timelines and defend margin structures.
For Market Incumbents: Anchor market position through backward integration into polyethylene extrusion and exclusive partnerships with INM-certified laboratories to bypass validation bottlenecks. Invest in mono-material pilot lines for Pacific coastal pre-compliance ahead of marine-debris regulations. Consolidate supplier relationships with Antioquia coffee cooperatives to lock in high-barrier laminate demand against emerging domestic competitors. For New Entrants and Emerging Players: Digital printing capabilities for short-run coffee and chocolate export batches represent a technology-first wedge into Bogotá's specialty retail channel. Target pharmaceutical sachet production for rural generics distribution in Valle del Cauca, where validated barrier demand outpaces local converter capacity. Pursue equipment-leasing arrangements with European manufacturers to circumvent 18-24 month purchase lead times. For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale regional converters possessing existing migration documentation and EPR-compliant material portfolios given impending coastal department enforcement timelines. Long-term viability centers on backward integration into resin compounding and captive recycling infrastructure. Watch for Ministry of Environment announcements on Pacific and Caribbean single-use plastic implementation dates as the inflection signal for recyclable structure demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive polyethylene supply insulates Bogotá converters from Gulf Coast price volatility and currency exposure. |
| Migration Testing Laboratory Partnership | Exclusive INM-certified access compresses 12-16 week validation queues for acidic sauce laminate launches. |
| Mono-Material Pilot Line Deployment | Antioquia coffee cooperatives trial recyclable structures for EU specialty roaster compliance requirements. |
| Digital Printing Capability Addition | Short-run flexibility serves Colombia's export-oriented chocolate sector with batch-level traceability. |
| Direct Retail Channel Relationship | Éxito and Carulla private-label procurement bypasses distributor intermediaries for margin capture. |
Research Methodology
Document review covered Ministry of Environment resolutions, INM certification records, and Mercosur GMC food-contact standards, complemented by interviews with extrusion plant managers, supermarket category buyers, coffee cooperative processing directors, and pharmaceutical packaging procurement leads. Secondary validation drew from customs import data for polyethylene and polypropylene resins, Superintendency of Industry and Commerce enforcement records, and National Institute of Metrology laboratory capacity reports. Bottom-up demand modeling from end-use applications triangulated against top-down converter capacity assessments.
Cross-reference between historical pricing volatility patterns and expert panel input on EPR implementation timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include material barrier tier, closure complexity, regulatory exposure level, and regional industrial cluster concentration. CAGRs were derived from elasticity-adjusted demand projections and capacity expansion schedules. Industry-specific forecast inputs incorporated coffee export volume trajectories to North American and European buyers and pharmaceutical generics distribution expansion into rural municipalities.
Several conditions sit outside the modeled scope, including abrupt peso-dollar exchange rate movements, force majeure disruptions to Gulf Coast petrochemical supply, and unilateral Mercosur standard revisions beyond current resolution alignment. Forecasts reflect documented assumptions on Ministry of Environment enforcement pacing and resin import tariff stability. A model refresh is warranted upon material change in Pacific or Caribbean coastal department regulatory implementation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Digital Printed Pouch Market
Pouch
Center Seal Pouch Making Machine Market
Pouch
Retort Pouch Market
Pouch
Vietnam Pouch Packaging Market
Pouch
PPWR-Compliant Recyclable PE/PP Stand-Up Pouch Recycling Systems Market
Pouch
Pouches Market
Pouch
Horizontal Premade Pouch Packing Machine Market
Pouch
Vented Stretch Wrap Market
Pouch
Liquid Pouch Packaging Market
Pouch
Slider Pouches Market
Pouch
Contour Pouches Market
Pouch
Center Sealed Pouch Packaging Market
Pouch
Europe Retort Pouches Market
Pouch
Rice Paper Stand Up Pouch Market
Pouch
Twist Wrap Packaging Market
Pouch
Asia-Pacific Retort Pouch Market