
 Low Melt Point Bags Market | 2026-2036
Low Melt Point Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Low Melt Point Bags Market Outlook
ASTM D4974 thermal qualification for low-melt polymer films is reorganizing supplier eligibility across North America and Europe. Sealed Air Corporation leverages captive resin compounding to sustain margin control in industrial-grade formulations. Mondi Group anchors European supply through integrated kraft-polymer hybrid production. Berry Global competes via high-volume extrusion scale across multiple melt-point specifications.
Low melt point bags are engineered polymer containers designed to soften or release at controlled temperatures between 80°C and 115°C, typically manufactured through blown-film extrusion of modified polyethylene or starch-blended compounds for temperature-triggered dispensing, batch inclusion, or protective packaging applications. Industrial bags dominate current volume due to widespread use in rubber compounding and chemical processing where controlled release prevents contamination. Biodegradable bags represent the fastest-expanding material category as food processors switch from conventional polyethylene to starch-based alternatives that satisfy compostability mandates without sacrificing melt-point precision.
FDA food-contact substance notifications govern polymer migration limits for bags used in edible-product applications, while EPA regulations on microplastic discharge constrain conventional polyethylene formulations in industrial settings. The EU REACH framework restricts specific phthalate plasticizers common in legacy low-melt formulations, redirecting R&D toward bio-based plasticizer systems. Stakeholders must monitor evolving compostability certifications and polymer migration thresholds to determine which material platforms warrant capacity investment.
Market Dynamics
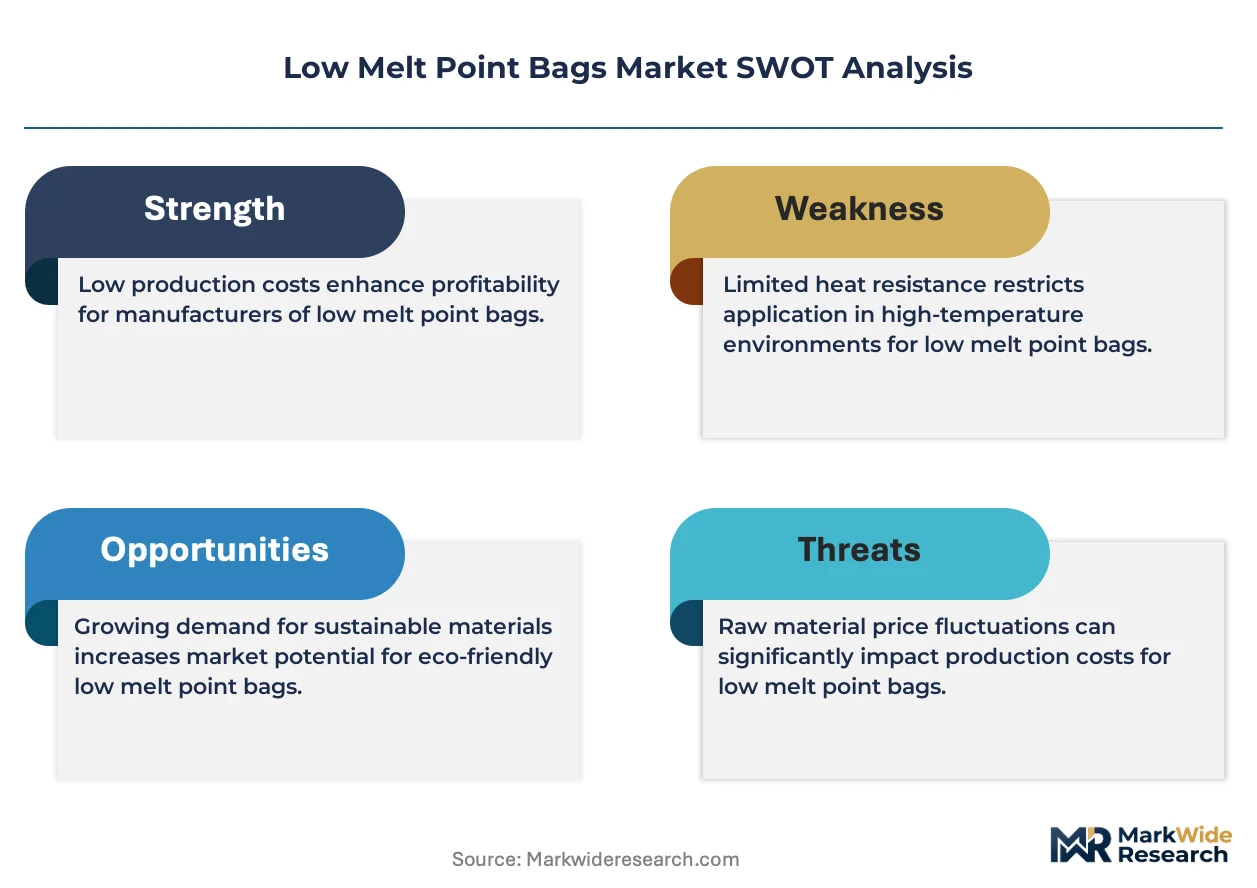
REACH compliance deadlines are forcing wholesale reformulation of plasticizer systems across European supply chains, redirecting capital toward bio-based alternatives while legacy phthalate-dependent production lines face accelerated obsolescence.
Growth Catalysts
- Compostability mandates:EU packaging waste directives are mandating industrial compostability for food-contact materials, driving food processors toward starch-blended low-melt formulations that satisfy both melt-point precision and end-of-life requirements.
- Rubber compounding automation:Tire manufacturers and industrial rubber formulators are adopting temperature-triggered batch inclusion systems to eliminate manual handling of chemical additives and reduce workplace contamination incidents.
- FDA migration threshold revisions:Updated food-contact substance notifications are narrowing acceptable polymer migration limits, advantaging suppliers with advanced multi-layer coextrusion capabilities that legacy mono-film producers cannot match.
Market Restraints
- Specialty resin supply concentration:Modified polyethylene grades with precise melt-point windows depend on a concentrated US Gulf Coast petrochemical base, exposing converters to hurricane-season disruption and force majeure pricing volatility.
- Starch-based moisture sensitivity:Biodegradable low-melt formulations exhibit hydrolytic degradation during extended storage, limiting shelf life and complicating inventory management for distributors in humid climates.
- REACH authorization timelines:The ECHA substance evaluation process for novel bio-plasticizers extends 18-24 months, delaying commercialization of compliant formulations and freezing R&D returns.
Strategic Opportunities
- Indian pharmaceutical packaging:CDSCO quality guidelines for active pharmaceutical ingredient handling are creating demand for contamination-free dispensing solutions in Mumbai-Pune and Hyderabad bulk drug manufacturing clusters.
- Dual-carbon policy alignment:China's MIIT industrial greening standards are incentivizing starch-polymer hybrid adoption in chemical processing applications previously served by conventional polyethylene.
- Direct-to-compounder distribution:Bypassing traditional film distributors through captive extrusion partnerships with rubber and chemical compounders is capturing margin previously lost to channel intermediaries.
Industry Challenges
- Polymer rheology expertise scarcity:Formulating precise melt-point control across 80-115°C ranges requires specialized knowledge of crystallization kinetics that conventional extrusion engineers rarely possess.
- Compostability certification fragmentation:Divergent requirements between TÜV Austria's OK Compost INDUSTRIAL, BPI certification in North America, and Australia's AS 4736 are multiplying testing costs and delaying multi-market launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Melt Point Bags Market |
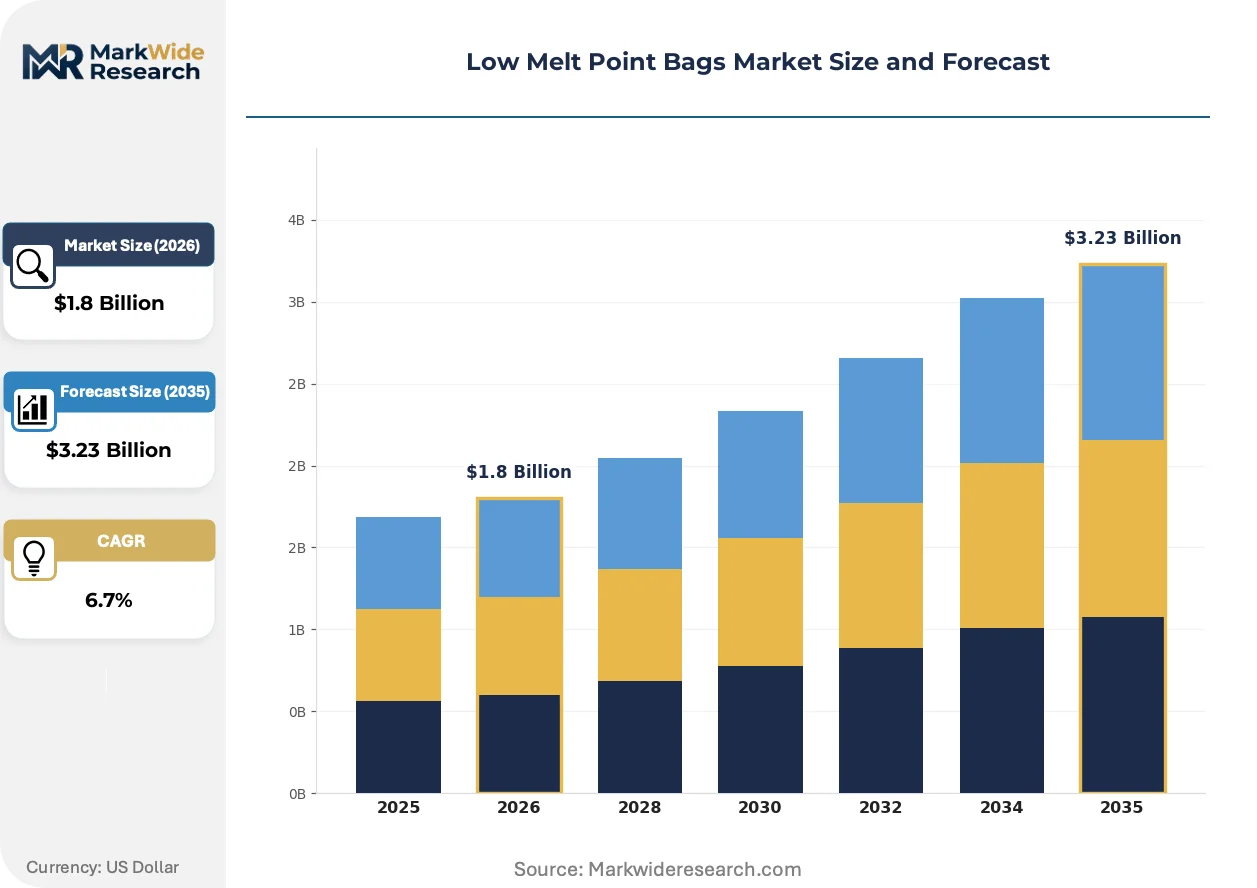
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biodegradable Bags, Reusable Bags, Disposable Bags, Industrial Bags Material: Polyethylene, Polypropylene, Starch-based, Other Polymers End User: Retail Sector, Food Industry, Consumer Goods, Healthcare Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Sealed Air Corporation, Amcor plc, Mondi Group, Berry Global Inc., Novolex Holdings LLC, Sonoco Products Company, ProAmpac LLC, Inteplast Group Ltd., International Plastics Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Melt Point Bags Market Strategic Shifts
Material science advances and regulatory stringency are converging to redefine competitive advantage around formulation precision rather than extrusion scale alone.
Multi-layer coextrusion with ethylene-vinyl acetate tie layers is displacing single-polymer constructions in food-contact applications. Prepared meal manufacturers in Germany and the Netherlands are specifying these structures to achieve sub-50°C seal initiation without compromising 110°C melt-point release. The technology is displacing conventional low-density polyethylene mono-films in premium frozen goods packaging where migration control and thermal performance must coexist.
REACH Annex XIV authorization requirements for di(2-ethylhexyl) phthalate are eliminating legacy plasticizer systems from European supply chains. Compounders serving rubber and chemical processing sectors must reformulate with citrate or epoxidized vegetable oil alternatives, increasing raw material costs but opening patent-protected formulation premiums. Industrial-grade bag producers with early bio-plasticizer adoption are capturing specification authority from commodity extruders.
Compounders are consolidating purchase volumes around qualified suppliers capable of documenting batch-level melt-point consistency and migration test results. This consolidation is compressing the viable supplier base for food and pharmaceutical applications while elevating technical service capabilities to primary selection criteria. The shift is most pronounced in Japan's Kanto industrial corridor where METI quality traceability guidelines reward documented supply chain transparency.
Low Melt Point Bags Market Segmentation
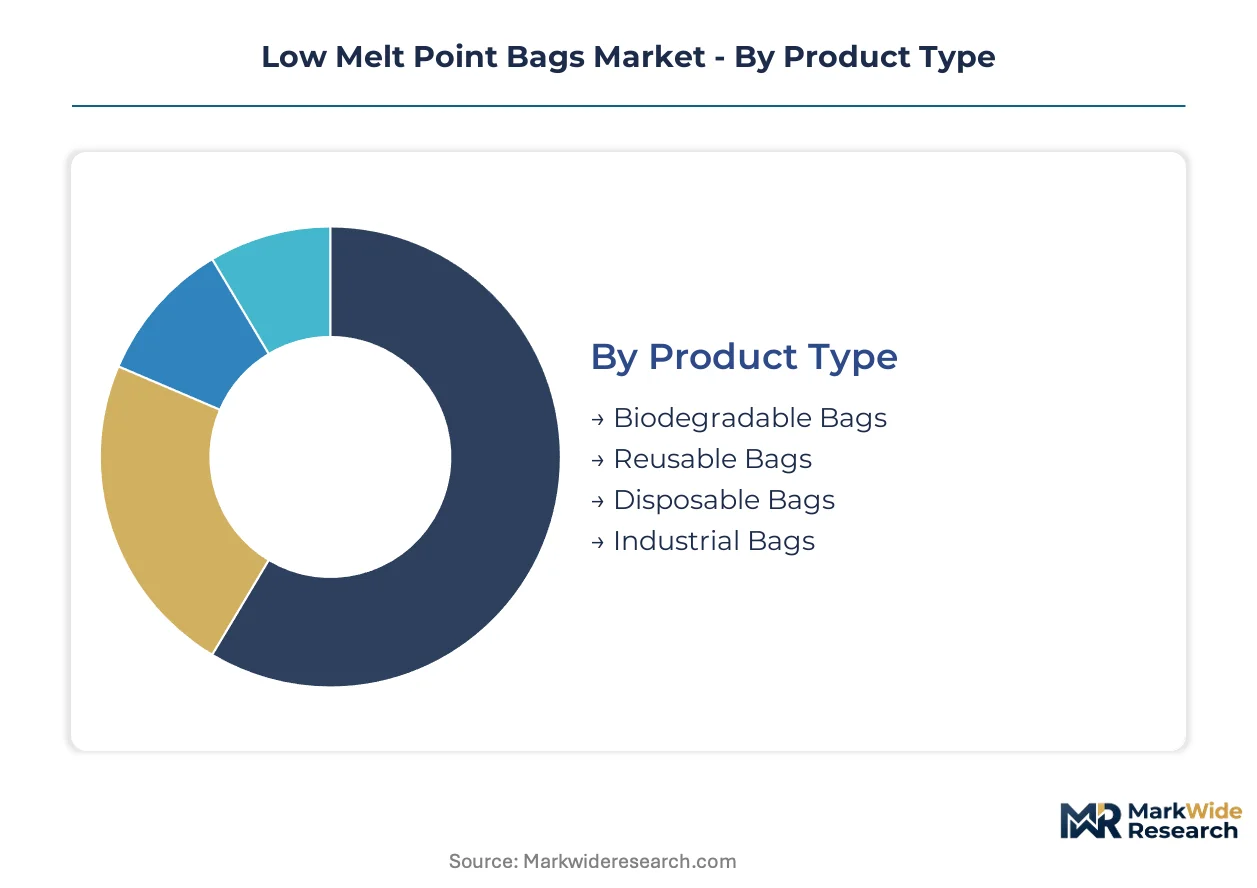
Segmentation in low-melt packaging reveals where formulation precision commands premium positioning versus where commodity extrusion suffices. Material choices and end-use specifications determine which converters capture specification authority and which face margin compression from substitute technologies.
Product Type:
Substitution pressure from conventional packaging intensifies where melt-point precision offers marginal operational benefit rather than essential contamination control.
- Industrial Bags:These heavy-gauge formulations incorporate modified polyethylene or ethylene-vinyl acetate blends calibrated for 95-115°C release thresholds. Tire manufacturers in Germany's Ruhr industrial cluster and rubber compounders across the US Gulf Coast specify these bags for automated batch inclusion systems that eliminate manual additive handling. REACH Annex XIV phthalate restrictions are forcing reformulation of legacy industrial grades, advantaging suppliers with early bio-plasticizer adoption.
- Biodegradable Bags:Starch-polymer hybrids engineered for controlled compostability maintain melt-point windows through precise crystallization kinetics management. Food processors in the Netherlands and Denmark specify these formulations to satisfy EU packaging waste directives without sacrificing thermal release performance. Moisture sensitivity during extended storage remains the primary constraint limiting distributor inventory cycles in humid supply chain corridors.
- Reusable Bags:Multi-layer constructions with reinforced seams support repeated thermal cycling without degradation of melt-point precision. Chemical processors specify these for closed-loop additive dispensing systems.
- Disposable Bags:Single-use mono-film constructions prioritize cost minimization over extended thermal stability. Limited to applications where precise melt-point control carries secondary importance.
Industrial bags retain volume leadership; biodegradable bags hold the steepest expansion curve.
Material:
Cost tier stratification separates captive resin compounders from converters dependent on spot-market polyethylene procurement.
- Starch-based:Compostable formulations blend thermoplastic starch with aliphatic polyesters to achieve melt-point precision without fossil-derived content. EU industrial compostability certification requirements are concentrating demand among converters with TÜV Austria OK Compost INDUSTRIAL documentation capabilities. Formulation complexity elevates pricing relative to conventional polyethylene but satisfies end-of-life mandates in German and French food packaging specifications.
- Polyethylene:Modified LDPE and LLDPE grades dominate current volume through established blown-film extrusion infrastructure and predictable rheological behavior. FDA food-contact substance notification compliance is narrowing the supplier base to converters with documented migration testing protocols.
- Polypropylene:Higher melting point base resin requires more aggressive plasticizer loading to achieve low-melt performance, limiting adoption to specialized chemical processing applications.
- Other Polymers:Niche formulations including polylactic acid and polyhydroxyalkanoates serve experimental pharmaceutical packaging applications with stringent purity requirements.
Polyethylene dominates current procurement volumes; starch-based materials are climbing the fastest as compostability mandates harden.
End User:
Application-specific migration thresholds and thermal performance requirements fragment demand across qualification-intensive sectors.
- Food Industry:Prepared meal manufacturers and frozen goods processors specify multi-layer coextruded structures with sub-50°C seal initiation and 110°C controlled release. FDA notification compliance and EU food-contact framework requirements are compressing the qualified supplier base to converters with documented batch-level consistency.
- Healthcare:Active pharmaceutical ingredient handling in India's Mumbai-Pune corridor demands contamination-free dispensing with CDSCO-traceable quality documentation. Sterility requirements elevate specification complexity beyond standard industrial grades.
- Retail Sector:Private-label packaging programs prioritize cost efficiency over melt-point precision, exposing suppliers to substitution from conventional polyethylene bags.
- Consumer Goods:Household chemical packaging applications tolerate broader melt-point windows, limiting premium pricing potential for precision formulations.
Food industry specifications retain the most stringent qualification barriers; healthcare applications are gaining share fastest as pharmaceutical manufacturing decentralizes.
Distribution Channel:
Customer type determines whether technical service capabilities or logistics efficiency drives channel selection.
- Direct Sales:Rubber compounders and chemical processors consolidate procurement around qualified suppliers capable of documenting batch-level melt-point consistency and migration test results. Technical service integration including on-site extrusion parameter consultation supports premium positioning.
- Specialty Stores:Regional packaging distributors serving mid-tier food processors maintain inventory of standard melt-point specifications with limited customization capability.
- Online Retail:Catalog-based procurement suits standardized industrial grades where specification complexity remains low and immediate availability outweighs technical consultation.
- Supermarkets:Limited to consumer-facing retail bag applications with minimal melt-point precision requirements.
Direct sales captures the highest-margin procurement; online retail is expanding most quickly for standardized industrial specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU packaging waste directives and FDA migration threshold revisions are redirecting procurement toward qualified suppliers with documented batch-level consistency across multiple jurisdictions.
United States
Rubber compounders across the US Gulf Coast specify modified polyethylene bags for automated batch inclusion systems that eliminate manual additive handling. EPA regulations on microplastic discharge constrain conventional polyethylene formulations in industrial settings. Houston-area petrochemical corridors supply specialty resin grades with precise melt-point windows to domestic converters.
Germany
Tire manufacturers in the Ruhr industrial cluster demand heavy-gauge formulations calibrated for controlled release during rubber compounding operations. REACH Annex XIV authorization requirements for di(2-ethylhexyl) phthalate are eliminating legacy plasticizer systems from European supply chains. Frankfurt-Rhine-Main packaging distributors serve prepared meal manufacturers specifying multi-layer coextruded structures with sub-50°C seal initiation.
China
Chemical processors are adopting starch-polymer hybrid formulations to align with MIIT industrial greening standards and dual-carbon policy targets. The country's national packaging regulator enforces migration limits for food-contact materials that narrow acceptable polymer thresholds. Yangtze River Delta manufacturing clusters concentrate demand for temperature-triggered dispensing solutions in bulk chemical handling.
India
Active pharmaceutical ingredient manufacturers in the Mumbai-Pune corridor require contamination-free dispensing with CDSCO-traceable quality documentation. The national pharmaceutical regulator mandates sterility protocols that elevate specification complexity beyond standard industrial grades. Hyderabad bulk drug manufacturing clusters are consolidating procurement around suppliers capable of documenting melt-point consistency.
Japan
Rubber and chemical compounders in the Kanto industrial corridor consolidate purchase volumes around qualified suppliers with documented supply chain transparency. METI quality traceability guidelines reward batch-level documentation capabilities. Tokyo-Osaka industrial belt distributors maintain limited inventory of biodegradable formulations due to moisture sensitivity concerns during humid-season storage.
Low Melt Point Bags Market Competitive Environment
Player mix skews toward diversified packaging conglomerates with captive resin capabilities and specialized film converters serving qualification-intensive end-uses. Market structure exhibits tiered consolidation where premium food and pharmaceutical specifications concentrate among converters with documented FDA notification compliance and multi-layer coextrusion assets. Strategic archetypes include integrated resin-to-film producers, regional extrusion specialists with formulation expertise, and global distributors leveraging logistics scale. Dominant competitive moves encompass backward integration into specialty resin compounding and direct-to-compounder distribution partnerships that bypass traditional channel intermediaries.
Among North American packaging conglomerates, Sealed Air Corporation and Berry Global Inc. exemplify scale-driven archetypes with broad extrusion capabilities across multiple melt-point specifications. Mondi Group anchors European supply positioning through integrated kraft-polymer hybrid production serving industrial and food-contact applications. These three represent distinct geographic and capability positioning within a supplier base increasingly segmented by regulatory qualification depth rather than volume scale alone.
| Leading Market Players |
|---|
| Sealed Air Corporation |
| Amcor plc |
| Mondi Group |
| Berry Global Inc. |
| Novolex Holdings LLC |
| Sonoco Products Company |
| ProAmpac LLC |
| Inteplast Group Ltd. |
| International Plastics Inc. |
| Others |
Value Chain & Pricing Dynamics
Blown-film extrusion scale economies in the US Gulf Coast petrochemical corridor concentrate cost leadership among converters with captive resin compounding, compressing price floors for commodity-grade modified polyethylene while elevating premiums for REACH-compliant bio-plasticizer formulations.
Pricing Analysis
Certification level creates the primary spread between commodity and qualified supply tiers. Three-tier pricing structure across FDA-notified, REACH-compliant, and uncertified industrial grades reflects migration testing documentation costs. Price differentiation stems from batch-level consistency guarantees and multi-layer coextrusion capability. Pricing pressure intensifies in mono-film constructions as starch-based alternatives capture specification authority in EU food-contact applications. Rubber compounders exhibit lowest price sensitivity due to contamination risk costs; retail private-label buyers drive hardest negotiations.
Supply Chain Analysis
Hurricane-season disruption risk through Houston-Beaumont petrochemical corridors exposes specialty modified polyethylene supply to force majeure volatility. Production concentrates in the United States, Germany, and China. Raw material flows draw from ethylene crackers, bio-plasticizer compounders, and thermoplastic starch processors. Single-source vulnerability runs through concentrated US Gulf Coast resin supply. Distribution runs through direct-to-compounder partnerships bypassing traditional film distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from reusable closed-loop dispensing systems that eliminate single-use bag consumption entirely in chemical processing applications.
For Market Incumbents: Shield specification authority by deepening backward integration into specialty resin compounding and securing early REACH Annex XIV bio-plasticizer adoption. Defend against starch-based substitution by documenting industrial compostability certification ahead of EU packaging waste directive deadlines. Prioritize captive extrusion partnerships with rubber compounders to lock in volume commitments. For New Entrants and Emerging Players: Lead with CDSCO-traceable quality documentation targeting India's Mumbai-Pune pharmaceutical corridor where sterility requirements exceed incumbent capability. Capture share in biodegradable bag segments where moisture sensitivity barriers deter established polyethylene converters. Deploy direct technical service teams to compounders seeking batch-level melt-point consistency guarantees. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among converters with FDA food-contact notification compliance and multi-layer coextrusion assets serving prepared meal manufacturers. Long-term viability favors integrated resin-to-film producers with documented supply chain transparency meeting METI quality traceability guidelines. Watch for ECHA substance evaluation timeline acceleration as inflection signal for bio-plasticizer formulation commercialization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Resin Compounding | Captive supply of modified polyethylene grades insulates margin from Gulf Coast petrochemical price volatility. |
| REACH Annex XIV Bio-Plasticizer Adoption | Early citrate and epoxidized vegetable oil formulation secures specification authority as phthalate-dependent lines obsolete. |
| Direct-to-Compounder Distribution Partnership | Bypassing traditional film distributors captures margin previously lost to channel intermediaries in rubber processing. |
| Multi-Layer Coextrusion Capacity Expansion | EVA tie-layer technology addresses FDA migration threshold revisions that mono-film producers cannot satisfy. |
| Industrial Compostability Certification Investment | TÜV Austria OK Compost INDUSTRIAL documentation opens EU food-contact procurement previously closed to polyethylene. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with blown-film extrusion engineers, rubber compounding procurement leads, food packaging technical directors, and pharmaceutical quality assurance managers. Secondary validation drew from ECHA substance registration databases, FDA food-contact substance notifications, EU packaging waste directive implementation reports, and customs trade flow records. Bottom-up resin consumption estimates and top-down packaging spend analysis were triangulated to reconcile volume and value outputs.
Across the analysis window, the forecasting framework modeled demand by product type, material platform, end-use industry, and geographic regulatory cluster. CAGRs were derived from segment-level growth trajectories weighted by base-year revenue contribution. Industry-specific inputs included REACH authorization timeline assumptions, starch-polymer hybrid adoption curves under EU compostability mandates, and rubber compounding automation penetration rates.
Forecasts assume regulatory continuity in REACH, FDA food-contact, and CDSCO quality frameworks; material policy shifts would require re-modeling. Specific risks include ECHA bio-plasticizer evaluation delays, hurricane-season supply disruptions, and moisture sensitivity constraints on biodegradable inventory cycles. Practitioners should keep alternative scenarios live as EU packaging waste directive enforcement intensity evolves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Handle Gusseted Bags Market
Bags and Containers
Cross Corner Industrial Bags Market
Bags and Containers
Trash Can Liners Market
Bags and Containers
Isothermal Bags and Containers Market
Bags and Containers
Gusseted Bags Market
Bags and Containers
Craft Bags Market
Bags and Containers
Crates Market
Bags and Containers
Middle East & Africa Paper Bags Market
Bags and Containers
Americas Plastic Bags and Sacks Market
Bags and Containers
Wooden Boxes Market
Bags and Containers
Non-Barrier Bag Market
Bags and Containers
Twisted Handle Bags Market
Bags and Containers
Insulated Bags Market
Bags and Containers
Drum Liners Market
Bags and Containers
Nonwoven Containers Market
Bags and Containers
Waterproof Bags Market