
 Trash Can Liners Market | 2026-2036
Trash Can Liners Market Size, Share, and Industry Trends Forecast 2026-2036
Trash Can Liners Market Analytics
China's manufacturing base expansion is reshaping global supply dynamics for polyethylene film production. Berry Global leverages vertical integration across resin sourcing and blown film extrusion to sustain cost leadership in North America. Novolex anchors its position through channel control with major foodservice and retail distributors. Reynolds Consumer Products differentiates via brand strength in consumer-facing retail segments.
Trash can liners are flexible polymer containers engineered from LDPE, LLDPE, or HDPE resins, typically manufactured through blown film extrusion to specified thicknesses measured in mils, designed to contain and transport solid waste while resisting puncture and leakage. Their primary commercial purpose spans residential waste containment, industrial hazardous material handling, and healthcare infection control protocols. LLDPE formulations capture expanding share in heavy-duty applications due to superior puncture resistance relative to linear low-density alternatives. The healthcare end-user segment commands premium margin pools as facilities mandate ASTM-tested puncture resistance and odor-barrier specifications. Biodegradable material grades remain nascent but attract capital as municipal composting infrastructure expands.
EPA guidelines on municipal solid waste landfill criteria shape product durability requirements and disposal pathways for conventional polyethylene liners. FDA regulations governing food-contact surfaces influence resin selection and additive packages for foodservice and grocery channel products. ISO 9001 quality management certifications function as baseline market access credentials for commercial and industrial procurement tenders. Stakeholders must monitor evolving state-level extended producer responsibility frameworks and their implications for liner recyclability claims and post-consumer content mandates.
Market Dynamics
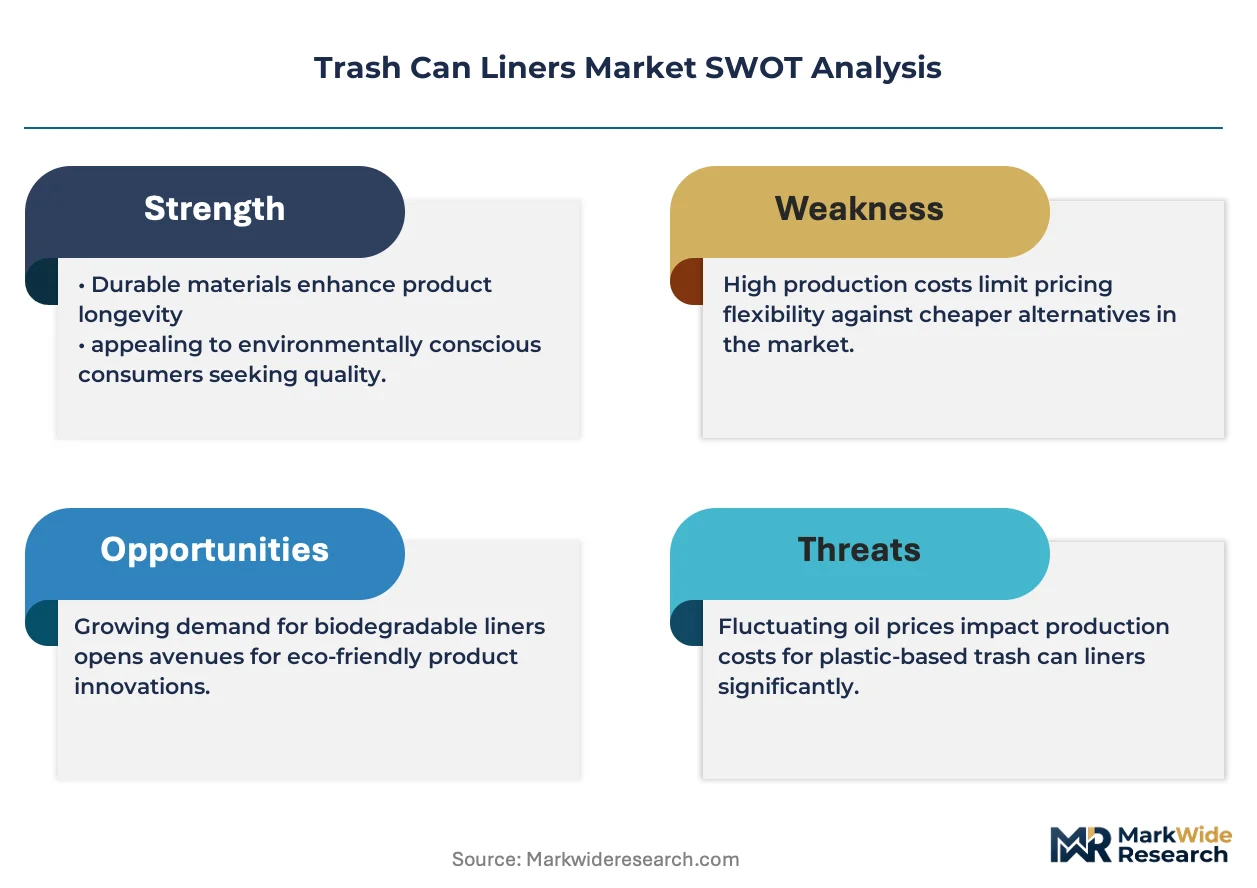
EPA regulations on single-use plastics are compressing demand for conventional polyethylene liners while accelerating capital flows into biodegradable resin development and composting infrastructure partnerships.
Growth Catalysts
- Healthcare Infection Control Mandates:ASTM-tested puncture resistance specifications are expanding procurement volumes from hospitals and long-term care facilities. Facilities now require odor-barrier properties alongside mechanical performance.
- Extended Producer Responsibility Frameworks:State-level EPR legislation in the United States is creating mandated demand for post-consumer recycled content. California and Oregon frameworks specifically target plastic film recovery rates.
- Biodegradable Resin Formulation:PLA and PBAT blends are achieving cost parity with virgin polyethylene in select municipal composting corridors. Material scientists have improved tear strength to match LLDPE benchmarks in light-duty applications.
Market Restraints
- Resin Price Volatility:Ethylene feedstock costs track crude oil and natural gas liquids, compressing margin predictability for blown film extruders. Naphtha-based producers in Asia face particular exposure to Brent crude fluctuations.
- Composting Infrastructure Gaps:Industrial composting facilities remain concentrated in coastal United States municipalities and select European capitals. Most biodegradable liners still route to anaerobic landfills where degradation benefits nullify.
- Mechanical Performance Trade-offs:Biodegradable formulations sacrifice puncture resistance at sub-1.5 mil thicknesses, limiting adoption in construction and industrial hazardous waste segments where HDPE dominates.
Strategic Opportunities
- India Urban Waste Management Expansion:Smart Cities Mission funding is modernizing municipal solid waste collection in Tier-2 and Tier-3 urban centers. Centralized procurement by municipal corporations favors standardized liner specifications at volume scale.
- Foodservice Channel Consolidation:National restaurant chains are unifying waste stream protocols across franchise networks. Corporate sustainability mandates are creating specification pull-through for certified compostable products.
- Film-to-Film Recycling Technology:Advanced sorting and reprocessing systems are enabling closed-loop recovery of post-consumer stretch film and liners. This convergence of mechanical recycling and AI-driven optical sorting is creating certified recycled content supply.
Industry Challenges
- Compostability Certification Timeline:BPI and TUV OK Compost certifications require 90-180 day validation cycles that delay product launches. Testing protocols vary between North American and European certifying bodies.
- Blown Film Equipment Retrofit Costs:Transitioning extrusion lines from polyethylene to PLA-based formulations requires screw and die modifications. Capital expenditure intensity limits converter flexibility in responding to resin price spreads.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trash Can Liners Market |
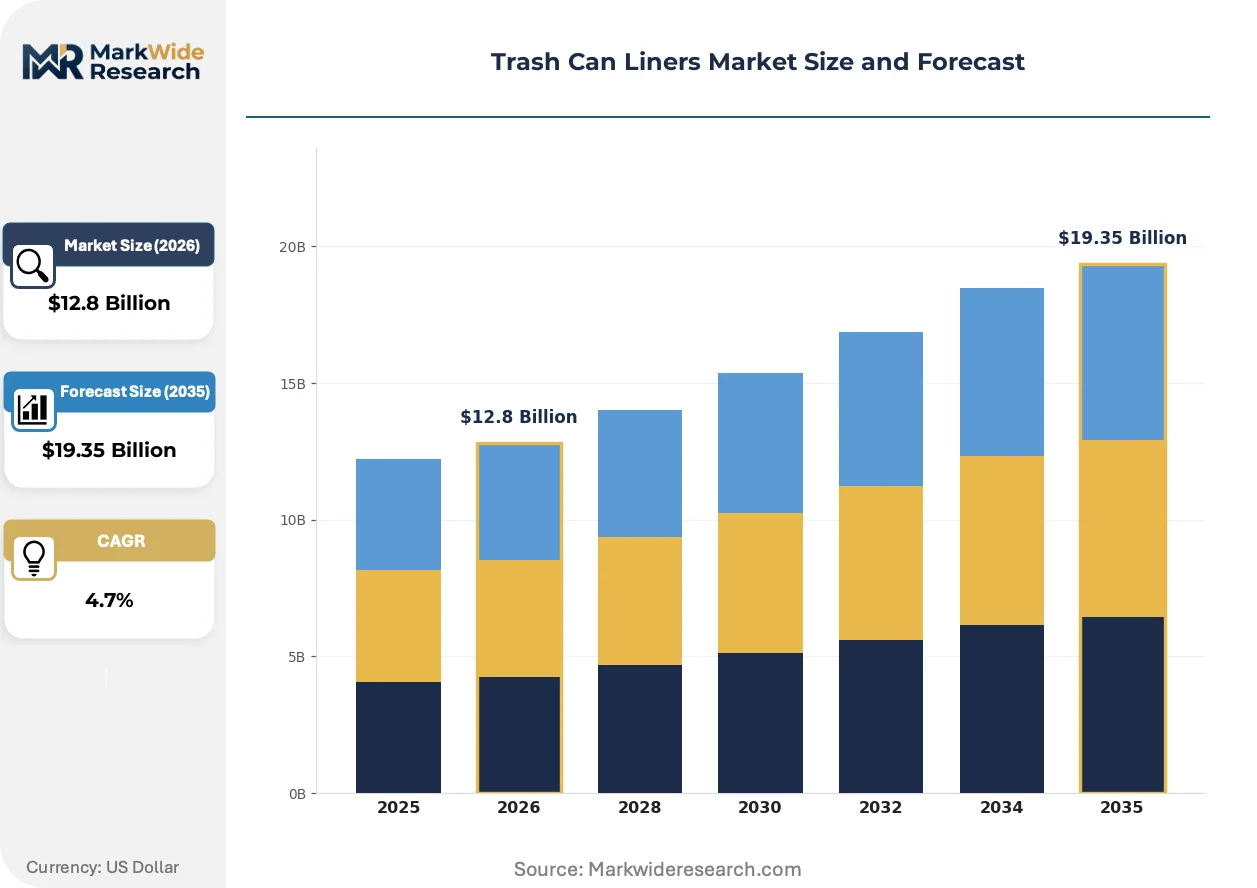
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $19.35 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: LDPE, HDPE, LLDPE, Biodegradable Thickness: Light, Standard, Heavy, Extra Heavy End User: Residential, Commercial, Industrial, Healthcare Packaging Type: Rolls, Flat Pack, Dispenser Boxes, Bulk |
| Companies Covered | Berry Global, Reynolds Consumer Products, Novolex, Inteplast Group, Poly-America, The Clorox Company, International Plastics, Four Star Plastics, Aluf Plastics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trash Can Liners Market Evolving Landscape
Digital specification tools and resin traceability platforms are compressing procurement cycles while raising compliance documentation requirements across institutional buyer segments.
Smart liner technology embedding RFID tags and fill-level sensors is virtualizing waste collection logistics. Healthcare facilities and university campuses are piloting sensor-equipped liners to optimize haul schedules and reduce labor costs. This virtualization is compressing the traditional relationship between liner manufacturers and waste service providers.
REACH restrictions on intentionally added microplastics are reshaping additive packages in European-sourced liners. The European Chemicals Agency enforcement timeline is accelerating reformulation investments among exporters serving EU member states. Foodservice distributors with cross-border supply chains are consolidating specifications to meet the strictest jurisdictional standard.
Direct contracting between resin producers and institutional waste generators is shortening channel structures. Large healthcare systems and retail chains are negotiating master service agreements that bypass traditional distribution intermediaries. This pattern is most pronounced in the United States where Group Purchasing Organizations are losing share to enterprise-level sustainability procurement offices.
Trash Can Liners Market Segmentation
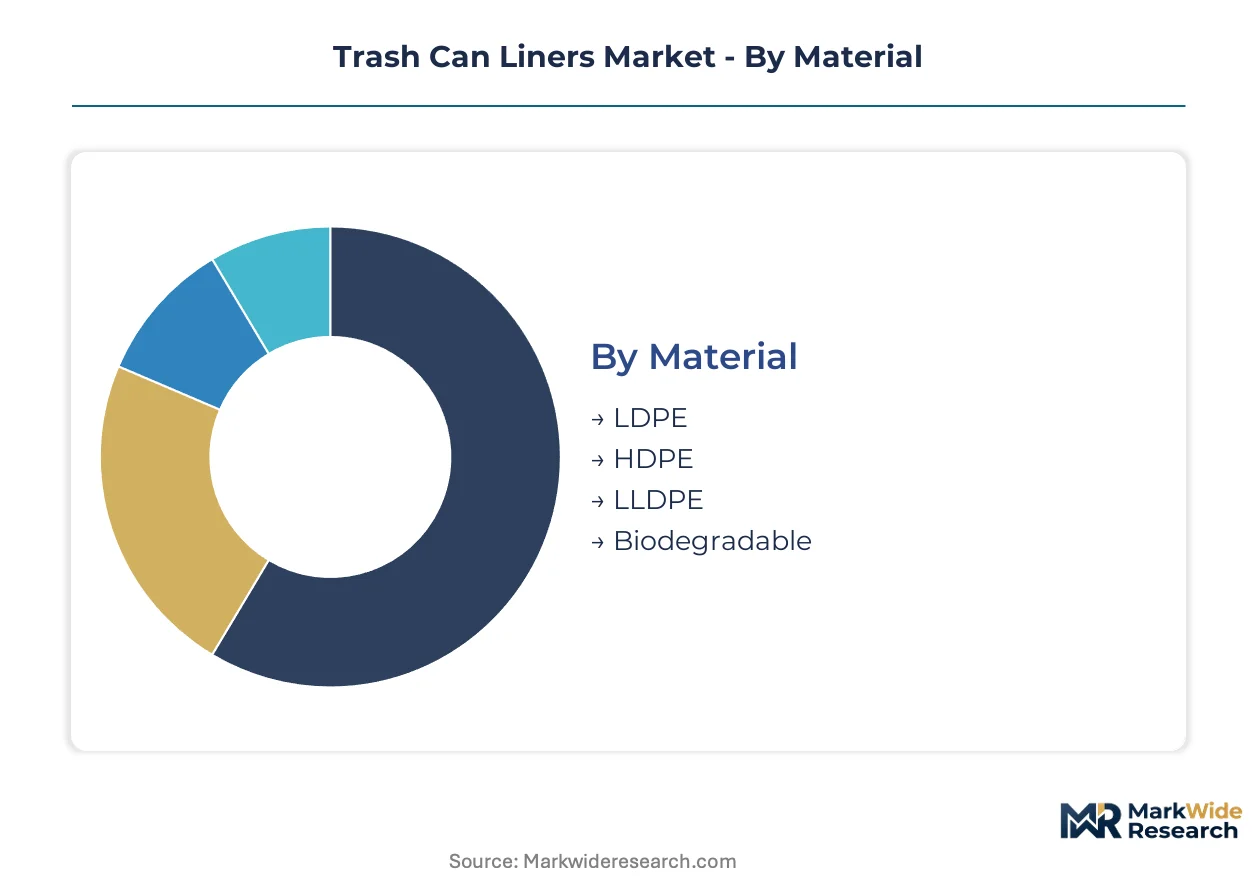
Material formulation and thickness specification determine mechanical performance thresholds, while end-user protocols and packaging formats shape procurement economics and channel access. Segmentation discipline separates commodity polyethylene volumes from premium-certified alternatives commanding divergent margin structures.
Material:
Mature resin categories dominate installed production capacity, though emerging biodegradable alternatives are capturing specification share in municipal composting corridors.
- LDPE:Low-density polyethylene offers superior clarity and flexibility for light-duty residential containment. Demand concentrates in North American retail channels where cost sensitivity dominates household purchasing decisions, though resin price volatility compresses converter margins unpredictably.
- LLDPE:Linear low-density formulations deliver puncture resistance advantages through molecular branching architecture. Healthcare procurement specifications increasingly mandate LLDPE for ASTM-tested clinical waste containment, with odor-barrier coextrusions commanding premium positioning.
- HDPE:High-density variants provide stiffness and chemical resistance for industrial hazardous material handling.
- Biodegradable:PLA and PBAT blends serve certified composting infrastructure in coastal United States municipalities.
LLDPE handles the majority of throughput; Biodegradable is climbing the fastest on specification share.
Thickness:
Cost tier stratification separates commodity light-duty rolls from engineered heavy-duty alternatives serving regulated waste streams.
- Heavy:2.0-3.0 mil constructions balance puncture resistance with material efficiency for commercial foodservice and institutional applications. Demand concentrates in United States restaurant chains unifying waste protocols across franchise networks, with corporate sustainability mandates pulling certified compostable specifications.
- Extra Heavy:Exceeding 3.0 mil thickness, these constructions serve construction debris and industrial hazardous waste where mechanical failure carries regulatory liability. HDPE dominates this tier due to stiffness requirements that biodegradable formulations cannot yet satisfy.
- Light:Sub-1.0 mil constructions minimize material cost for residential bathroom and office wastebasket containment.
- Standard:1.0-2.0 mil range captures mainstream kitchen and commercial office applications.
Heavy thickness generates the dominant revenue pool; Extra Heavy is expanding most quickly on industrial waste regulation tightening.
End User:
Application intensity separates high-frequency institutional procurement from intermittent residential purchasing patterns.
- Healthcare:Hospitals and long-term care facilities mandate ASTM-tested puncture resistance, odor-barrier properties, and infection control documentation. United States Group Purchasing Organizations are losing share to enterprise sustainability procurement offices negotiating direct master service agreements.
- Commercial:Office buildings, retail establishments, and hospitality operations standardize on mid-tier specifications balancing durability with cost efficiency.
- Residential:Household purchasing concentrates in retail supercenters and dollar store channels.
- Industrial:Manufacturing and construction sites require chemical resistance and load-bearing capacity for heavy debris.
Healthcare commands the steepest premium positioning; Commercial delivers the largest absolute volume throughput.
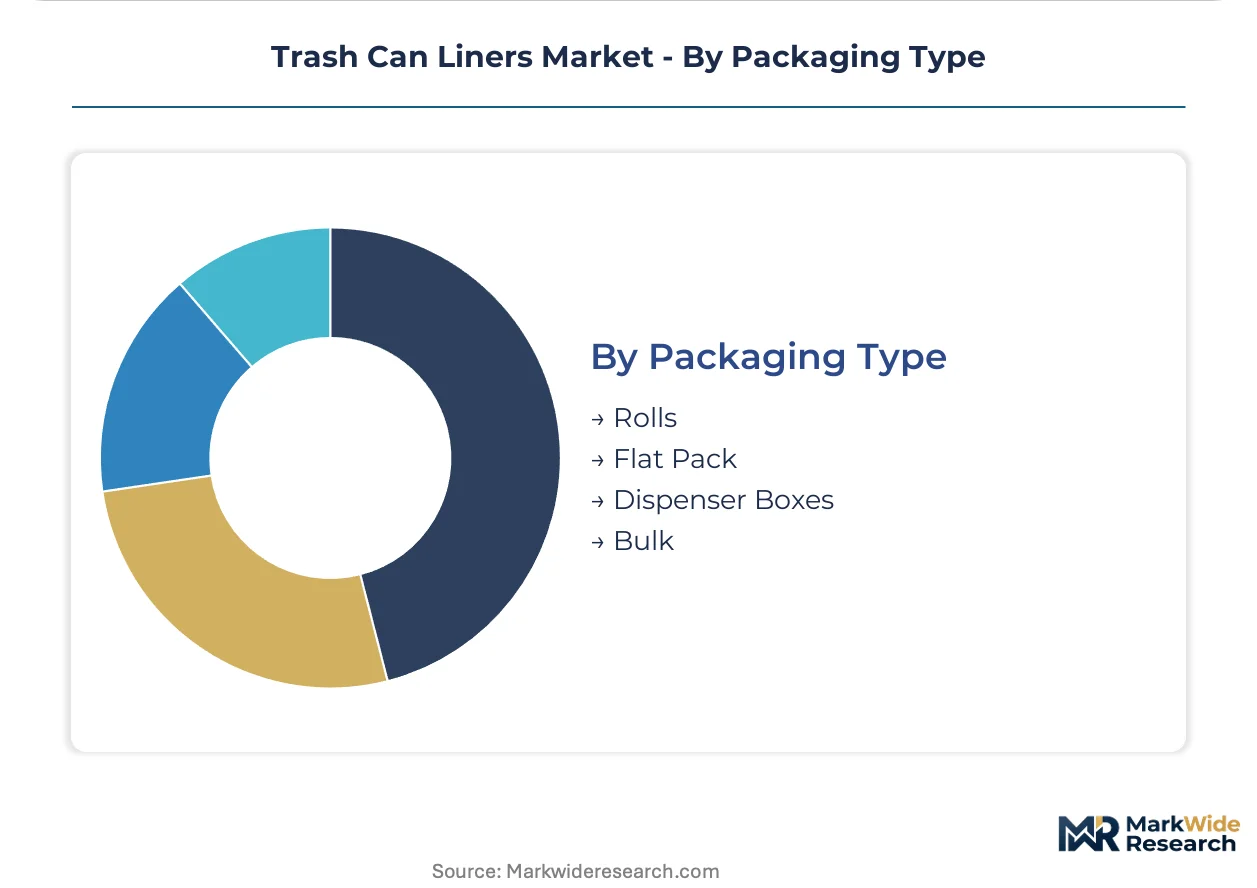
Packaging Type:
Customer type and usage frequency determine format economics, from dispenser convenience to bulk scale efficiency.
- Rolls:Continuous perforated formats dominate residential retail and light commercial procurement. United States consumer preference for coreless rolls reduces shipping cube and shelf space requirements.
- Bulk:Loose-packed cases serve high-volume institutional accounts with dedicated storage infrastructure and automated dispensing systems.
- Flat Pack:Pre-separated individual liners suit hospitality and healthcare applications requiring rapid deployment.
- Dispenser Boxes:Countertop or wall-mounted containers target foodservice and medical examination room convenience.
Rolls handle the majority of unit volume; Bulk is gaining share fastest on institutional direct contracting expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Blown film extrusion capacity clusters in the United States, China, Germany, and India, with resin access and end-user density determining regional competitive intensity. Municipal procurement scale and regulatory stringency separate high-margin markets from commodity supply zones.
United States
Healthcare systems and restaurant chains drive specification-grade demand for ASTM-tested liners. EPA landfill criteria and emerging state-level extended producer responsibility frameworks tighten material accountability. The Gulf Coast petrochemical corridor supplies captive polyethylene resin to extrusion facilities across Texas and Louisiana.
China
Coastal manufacturing provinces serve export markets while inland cities absorb domestic commercial waste management upgrades. GB standards on plastic pollution control accelerate biodegradable resin pilot programs. The Yangtze River Delta concentration of blown film converters supplies global private-label demand.
Germany
REACH restrictions on intentionally added microplastics force additive package reformulation for EU-bound production. Industrial composting infrastructure density supports certified biodegradable liner adoption. The North Rhine-Westphalia plastics processing cluster integrates mechanical recycling streams into film-grade resin supply.
India
Smart Cities Mission funding modernizes municipal solid waste collection in Tier-2 urban centers. Central Pollution Control Board guidelines on plastic waste management concentrate procurement authority at state levels. Gujarat's petrochemical complex feeds downstream film extrusion in Ahmedabad and Vadodara industrial zones.
Brazil
Foodservice channel growth and hospitality sector expansion pull mid-thickness liner imports. ANVISA sanitary regulations govern healthcare waste containment specifications. São Paulo's packaging industry cluster serves Mercosur distribution networks with converted film products.
Trash Can Liners Market Competitive Landscape
Vertically integrated resin-to-film producers and specialized converters split the market between cost leadership and specification expertise. Tiered competitive dynamics separate commodity polyethylene volume players from certified compostable specialists. Strategic archetypes include captive resin producers with extrusion assets, independent converters sourcing spot resin, and biodegradable material innovators partnering with composting operators. Dominant competitive moves encompass backward integration into resin production and direct contracting with institutional waste generators.
Among North American integrated producers, Berry Global exemplifies captive supply chain control from resin sourcing through blown film extrusion. Reynolds Consumer Products occupies a position anchoring retail-facing brand strength in consumer segments. Novolex represents channel control archetypes through distributor relationships with foodservice and retail networks.
| Leading Market Players |
|---|
| Berry Global |
| Reynolds Consumer Products |
| Novolex |
| Inteplast Group |
| Poly-America |
| The Clorox Company |
| International Plastics |
| Four Star Plastics |
| Aluf Plastics |
| Others |
Value Network & Pricing Analysis
The Houston Ship Channel freight corridor cost dynamics compress margins for Gulf Coast resin shipments while amplifying price differentiation between captive polyethylene producers and spot-dependent converters serving healthcare and foodservice buyers.
Pricing Analysis
EPA landfill criteria dictate the pricing tier structure across ASTM-certified, compostable-certified, and commodity polyethylene grades. Three-tier pricing structure across premium, standard, and economy levels separates infection-control liners with odor-barrier coextrusions from mid-thickness foodservice rolls and light-duty residential products. Cost compression in commodity LDPE rolls is intensifying because naphtha-based Asian imports undercut domestic blown film margins. Retail supercenters and dollar store channels exhibit the highest price sensitivity, while healthcare systems negotiating direct master service agreements absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculations for private-label converters sourcing masterbatch additives and specialized coextrusion equipment. Blown film extrusion capacity clusters in the United States, China, and Germany, with ethylene feedstock from the Gulf Coast petrochemical corridor feeding North American operations. Raw material dependencies rest on LLDPE resin pellets, calcium carbonate filler masterbatch, and slip additives for processing efficiency. Distribution runs through foodservice distributors, Group Purchasing Organizations, and direct institutional contracting channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biodegradable resin formulation breakthroughs and EPA regulatory compression on single-use plastics create a high-growth disruption window for specification-grade producers.
For Market Incumbents: Pre-empt margin erosion from PLA-PBAT cost parity achievements by locking long-term resin offtake agreements with Gulf Coast petrochemical producers and accelerating ASTM-certified odor-barrier product line extensions. Backward integration into film-grade recycling streams defends positioning against post-consumer content mandates from California and Oregon EPR frameworks. For New Entrants and Emerging Players: Pursue certified compostable liner contracts with national restaurant chains unifying waste protocols across franchise networks, where corporate sustainability mandates override first-cost procurement criteria. Foodservice channel consolidation represents the most penetrable entry vector, with BPI certification investments unlocking specification access ahead of 90-180 day validation cycles. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified packaging conglomerates with stranded polyethylene film assets facing regulatory obsolescence. Five-to-ten year viability hinges on composting infrastructure buildout velocity in coastal United States municipalities. The signal to watch is industrial composting facility permitting acceleration in Tier-2 urban centers.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Resin Formulation Partnership | PLA-PBAT cost parity in municipal composting corridors unlocks specification share from healthcare and foodservice accounts. |
| Film-to-Film Recycling Capacity Buildout | AI-driven optical sorting integration enables certified post-consumer content supply for California EPR compliance. |
| Direct Institutional Contracting Expansion | Bypassing Group Purchasing Organizations captures premium margin pools from enterprise sustainability procurement offices. |
| Smart Liner Technology Pilot Deployment | RFID-enabled fill-level sensors compress haul schedules for healthcare facilities and university campuses. |
| Blown Film Equipment Retrofit Investment | Screw and die modifications for PLA processing expand converter flexibility amid resin price spread volatility. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with blown film extrusion plant managers, healthcare procurement directors, foodservice distributor category buyers, and resin sourcing leads; and secondary validation through EPA regulatory filings, FDA food-contact surface guidelines, customs trade data on polyethylene film imports, and hospital Group Purchasing Organization contract databases. Bottom-up capacity modeling across resin formulation, thickness specification, and end-user segments triangulated against top-down macro demand indicators.
Forecast inputs span material grade substitution curves, composting infrastructure buildout timelines, and state-level EPR adoption patterns across the projection horizon. Segmentation dimensions modeled include resin chemistry, thickness tier, end-user protocol intensity, packaging format, and regional regulatory cluster. CAGRs derive from volume-weighted average growth across these intersecting categories, with particular sensitivity to healthcare infection control mandate expansion and biodegradable resin tear strength improvements.
Macroeconomic conditions sit as an overlay; deviation in ethylene feedstock costs tied to crude oil volatility or natural gas liquids pricing would shift the trajectory. Forecasts reflect documented assumptions on regulatory enforcement timelines and certification body harmonization between BPI and TUV OK Compost protocols. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Woven Bags Market
Bags and Containers
Compression Baggers Market
Bags and Containers
Mylar Bags Market
Bags and Containers
Bakery Bread Bag Market
Bags and Containers
Global Household Food Storage Containers Market
Bags and Containers
Ventilated FIBC Market
Bags and Containers
Bulk Bag Divider Market
Bags and Containers
Scented Trash Bags Market
Bags and Containers
Portion Bags Market
Bags and Containers
Anti-Static Polyethylene Bag Market
Bags and Containers
Archive Boxes Market
Bags and Containers
Conical Top Bulk Bag Market
Bags and Containers
Bag on Valve Technology Market
Bags and Containers
Lunch Boxes and Lunch Bags Market
Bags and Containers
Hermetic Storage Bags Market
Bags and Containers
Leno Bags Market