
 Vegan Dessert Market | 2026-2036
Vegan Dessert Market Size, Share, and Industry Trends Forecast 2026-2036
Vegan Dessert Market Intelligence
The Vegan Society's trademark certification is unwinding the traditional dairy-centric supply chain, creating space for specialized producers. Large conglomerates like Unilever PLC leverage extensive distribution networks to introduce plant-based lines. Oatly Group AB specializes in oat-based formulations, achieving significant brand recognition. Meanwhile, Daiya Foods Inc. focuses on dairy-free cheese alternatives that are often incorporated into dessert products.
Vegan desserts are food products that replicate traditional sweets without using any animal-derived ingredients, including dairy, eggs, or honey. These products often rely on plant milks, nut butters, and hydrocolloids to achieve desired textures and flavors. Within product types, ice cream remains a dominant category, while cakes and cookies show strong growth. Ingredient choices like coconut and nuts are critical, providing the necessary fat content and mouthfeel that consumers expect from indulgent desserts.
Food labeling regulations from bodies like the U.S. FDA and the European Food Safety Authority (EFSA) govern allergen declarations and health claims. The ISO 23662 standard provides a clear definition for vegan food, helping to standardize claims across different markets. These frameworks compel manufacturers to ensure ingredient transparency. The key decision for producers now involves balancing consumer demand for clean-label products against the functional necessity of certain additives for texture and shelf life.
Market Dynamics
The central force shaping the vegan dessert market is the technical challenge of meeting consumer demand for clean-label products while using functional additives. This creates a development trade-off between minimalist ingredient lists and achieving the indulgent textures of traditional desserts.
Growth Catalysts
- Standardized Labeling:The ISO 23662 standard provides a globally recognized definition for vegan food, increasing consumer trust and simplifying market access for producers by creating a clear benchmark for product claims.
- Ingredient Innovation:Advances in plant-based protein texturization and hydrocolloid science enable manufacturers to replicate the mouthfeel of dairy and eggs, expanding the scope of possible product formulations from ice cream to complex pastries.
- Demographic Shifts:A significant and growing vegan and flexitarian population, particularly in European countries like Germany, provides a stable and expanding consumer base that actively seeks out plant-based dessert alternatives in retail channels.
Market Restraints
- Ingredient Cost and Volatility:Key inputs like high-quality nut butters, coconut cream, and specialized hydrocolloids carry a significant price premium over conventional dairy ingredients, elevating final product costs for consumers.
- Supply Chain Concentration:The supply of critical ingredients such as almonds and coconuts is concentrated in a few agricultural regions, making the market vulnerable to price shocks from climate events or local policy changes.
- Texture Replication Challenges:Formulators struggle to mimic the specific functional properties of dairy fats and egg proteins, especially in baked goods, often leading to products with compromised texture or a reliance on additives.
Strategic Opportunities
- Geographic Expansion:Markets in Latin America and parts of Asia-Pacific represent significant white space, where rising health consciousness and disposable incomes are creating new demand for plant-based foods but dessert options remain limited.
- Product Line Extension:There is a clear opportunity to move beyond frozen desserts and cookies into more sophisticated categories like refrigerated cheesecakes, multi-layered tortes, and ready-to-eat mousses that command higher price points.
- Clean-Label Formulations:Developing desserts that use whole-food ingredients like dates, avocados, or sweet potatoes as functional texturizers and sweeteners can capture the growing consumer segment that avoids processed additives and refined sugars.
Industry Challenges
- Allergen Management Complexity:The prevalent use of major allergens like tree nuts, soy, and gluten as base ingredients necessitates stringent, costly production protocols to prevent cross-contamination and comply with food safety regulations.
- Ingredient Sourcing Consistency:Manufacturers face difficulties in maintaining product consistency batch-to-batch due to the natural variability in flavor, fat content, and texture of plant-based raw materials compared to standardized dairy inputs.
- Cold Chain Logistics:Expanding distribution for frozen and refrigerated vegan desserts requires significant investment in an unbroken cold chain, presenting a high barrier to entry for smaller producers and complicating expansion into new regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegan Dessert Market |
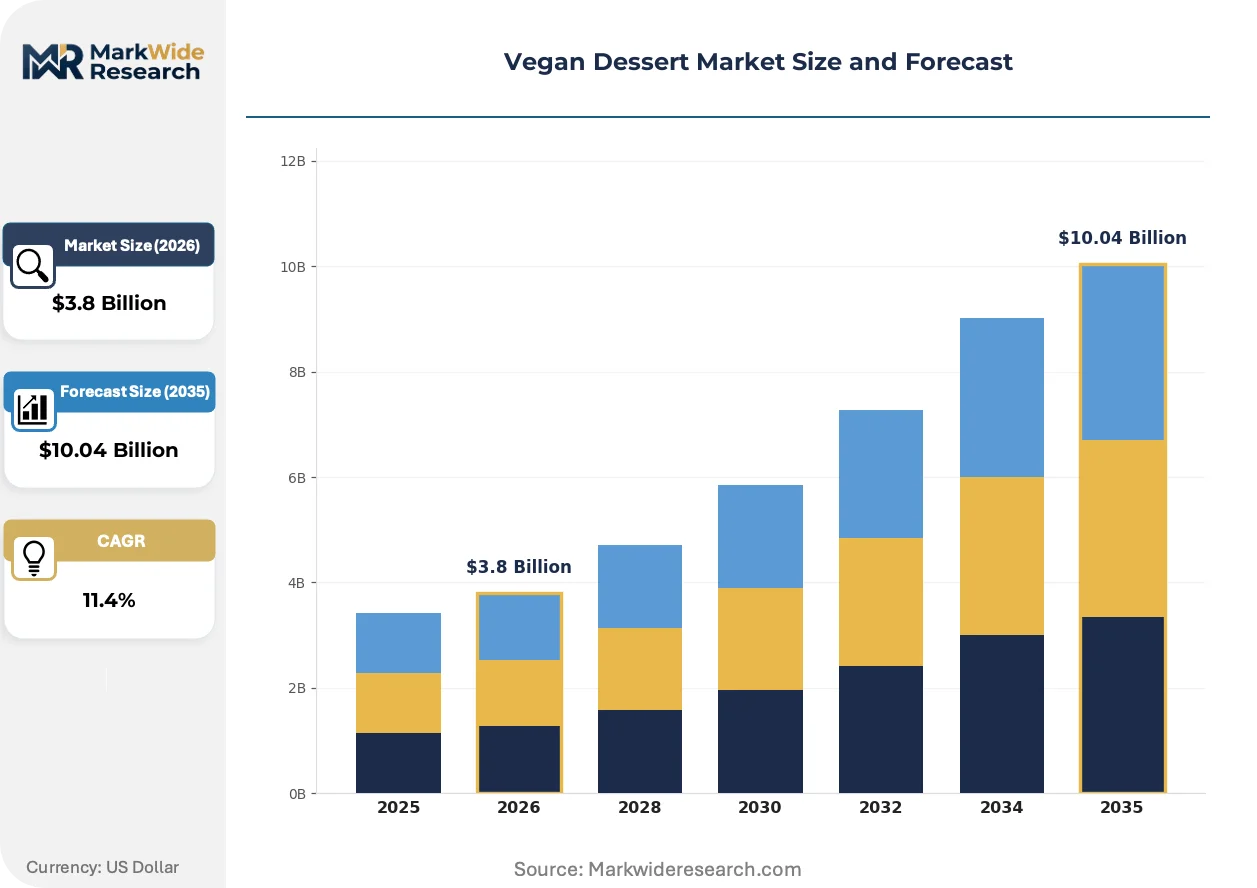
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cakes, Cookies, Ice Cream, Puddings Ingredient: Nuts, Fruits, Coconut, Seed-Based Distribution Channel: Online Retail, Supermarkets, Health Stores, Cafés Customer Type: Health Conscious, Lactose Intolerant, Ethical Consumers, Vegans |
| Companies Covered | Unilever PLC, Nestlé S.A., Danone S.A., Oatly Group AB, Tofutti Brands Inc., Daiya Foods Inc., Ben & Jerry's Homemade, Inc., NadaMoo!, OGGS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegan Dessert Market Strategic Shifts & Innovations
Ingredient science is rapidly evolving to solve the core formulation challenge of replicating traditional dessert textures without animal products. This push for authenticity is occurring alongside a demand-side shift toward mainstream retail availability, moving products beyond niche health stores.
Advanced texturizing agents, including novel hydrocolloid blends and precision fermentation-derived proteins, provide the specific gelling, emulsifying, and foaming properties of dairy. Premium dessert brands are adopting these systems to create richer ice creams and more stable mousses. This technology is supplanting older formulation methods that relied heavily on modified starches, which often imparted a gritty mouthfeel or undesirable aftertaste.
Regulatory frameworks from bodies like the European Food Safety Authority (EFSA) are tightening scrutiny over nutritional and health claims. This compels manufacturers to substantiate any on-package marketing, such as "high protein," with rigorous scientific evidence, influencing formulation decisions. The segment most impacted is functional desserts, where brands must now prioritize transparent, defensible ingredient choices over ambitious marketing language.
Consumer purchasing behavior is moving from specialty health food stores toward conventional supermarkets for vegan products. This channel shift is disrupting the established distribution networks of early-market pioneers and forcing brands to compete for shelf space within major retail chains. The trend is most prominent in the United Kingdom and Germany, where large grocers have dedicated significant freezer and aisle space to plant-based offerings.
Vegan Dessert Market Segmentation
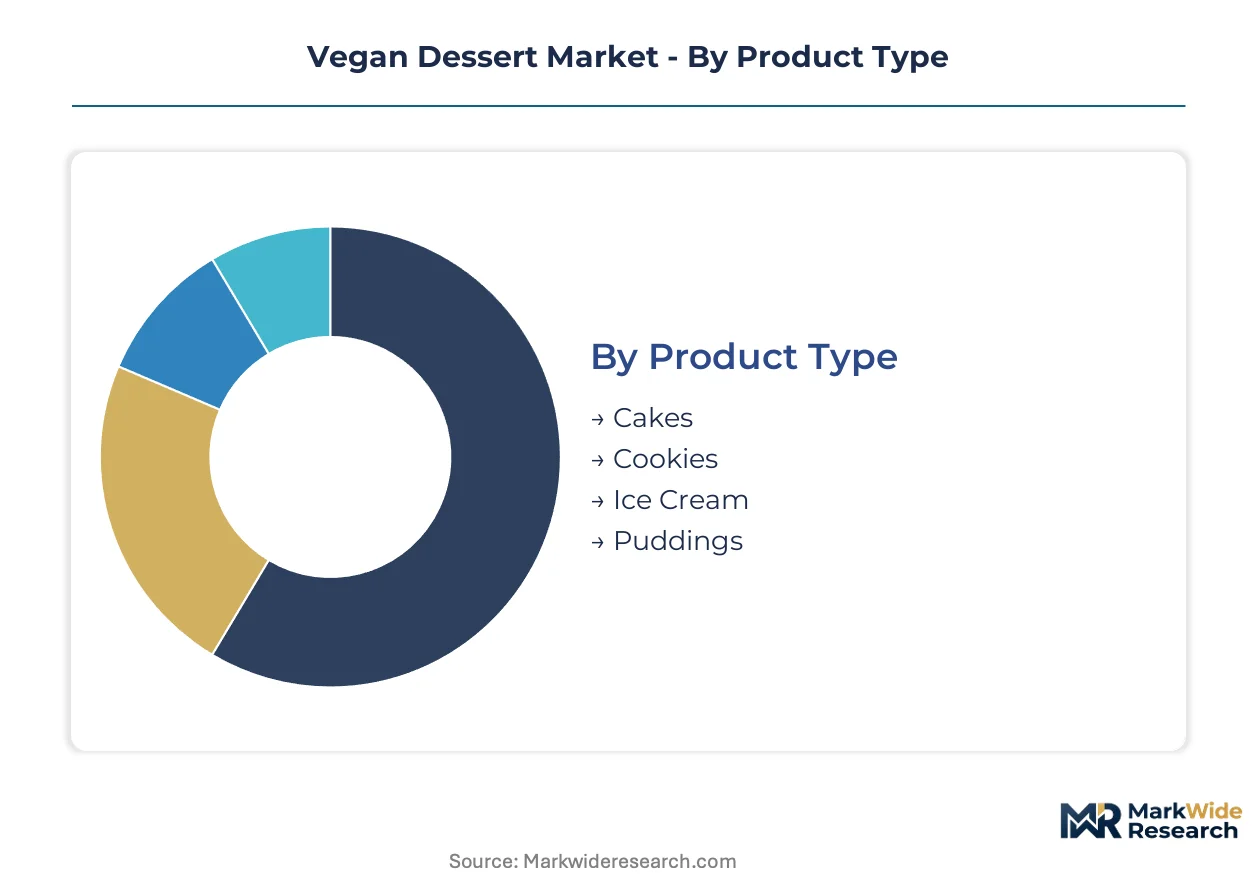
Market segmentation provides a granular view of the Vegan Dessert Market, highlighting distinct consumer preferences and operational dynamics. Understanding these segments is crucial for manufacturers to tailor product development, optimize distribution strategies, and effectively address specific demand drivers within the plant-based food sector.
Product Type:
The product type segment faces considerable substitution pressure from traditional dairy desserts, requiring manufacturers to continuously innovate in texture and flavor.
- Ice Cream:These frozen desserts replicate traditional dairy ice cream using plant milks like oat, almond, or coconut as their primary base. Demand concentrates in developed markets like Germany, driven by innovations in texture and flavor that successfully mimic dairy richness.
- Cakes:This category includes a variety of baked goods, from cupcakes to multi-layered celebration cakes, formulated without eggs or dairy. Demand is growing in retail channels, supported by increasing consumer desire for indulgent plant-based options for special occasions.
- Cookies:These popular baked treats offer convenient, plant-based snacking options, often using nut butters or flax eggs as binders.
- Puddings:Smooth, creamy desserts typically made with plant milks and starches, providing a quick, ready-to-eat vegan option.
Ice Cream anchors the volume base while Cakes gain share at the steepest rate.
Ingredient:
Ingredient choices often dictate the final product's cost tier, with premium plant-based components influencing consumer price sensitivity.
- Nuts:Ingredients like almonds, cashews, and peanuts are crucial for providing fat content, protein, and creamy texture in vegan desserts. Demand is strong across all product types, particularly for premium ice creams and cheesecakes, where their richness is highly valued.
- Coconut:Coconut milk, cream, and oil are widely used for their rich texture and distinct flavor, serving as a base for many dairy-free alternatives. Its versatility drives demand in frozen desserts and whipped toppings, especially in tropical regions and health-conscious markets.
- Fruits:Natural sweeteners and flavorings such as dates, berries, and bananas are increasingly used to create clean-label, whole-food vegan desserts.
- Seed-Based:Ingredients like sunflower seeds, chia seeds, and flax seeds offer allergen-friendly alternatives and functional properties for binding and thickening.
Demand for Nuts-based ingredients demonstrates consistent strength, while Seed-Based alternatives are expanding most quickly.
Distribution Channel:
Distribution channels reflect evolving consumer purchasing habits, with accessibility and convenience driving channel growth across various customer types.
- Supermarkets:Large grocery chains offer wide accessibility and significant shelf space for vegan desserts, catering to mainstream consumers. This channel is critical in countries like the UK and Germany, providing convenience for daily purchases and driving market penetration.
- Online Retail:E-commerce platforms provide extensive product variety and direct-to-consumer delivery, reaching niche markets and urban consumers. This channel facilitates discovery of specialized vegan dessert brands and supports subscription models.
- Health Stores:These specialized retailers cater to consumers actively seeking organic, allergen-free, and niche plant-based dessert options.
- Cafés:Food service establishments provide immediate consumption opportunities for vegan desserts, contributing to impulse purchases and product sampling.
Supermarkets drive the largest sales volume, with Online Retail showing significant expansion due to convenience and broader product availability.
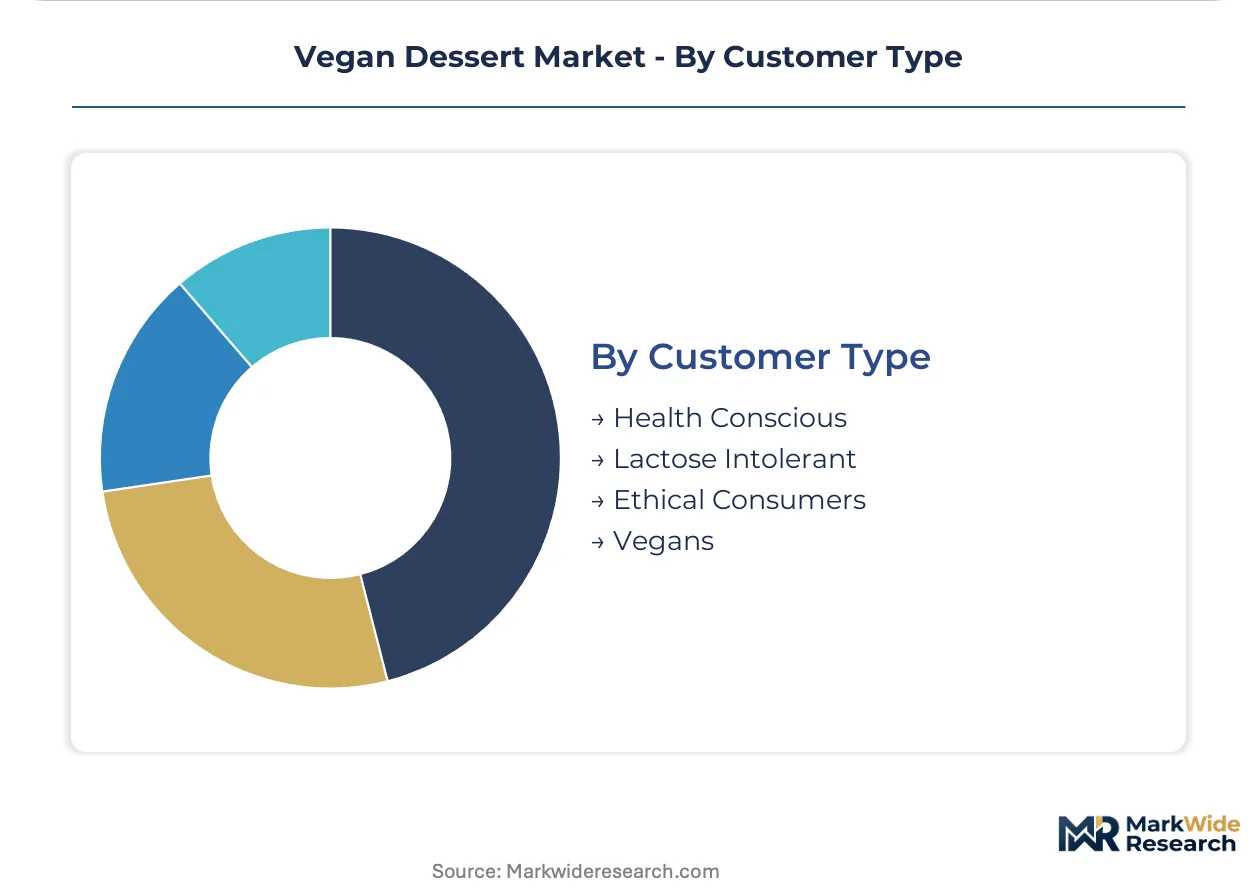
Customer Type:
Customer types often correlate with specific purchasing motivations, influencing manufacturers' margin strategies and product development focus.
- Health Conscious:Consumers prioritizing nutritional benefits, lower sugar content, and natural ingredients drive demand for clean-label vegan desserts. This segment influences product innovation towards whole-food formulations and functional ingredients.
- Vegans:Individuals adhering strictly to a plant-based diet form the core consumer base, seeking authentic and diverse dessert options free from animal products. Their demand ensures a steady market for innovative dairy and egg substitutes.
- Lactose Intolerant:Consumers avoiding dairy due to digestive issues seek vegan desserts as a palatable and safe alternative to traditional options.
- Ethical Consumers:Individuals motivated by animal welfare and environmental concerns actively choose vegan desserts, supporting brands aligned with their values.
Health Conscious consumers represent a foundational demand, while Ethical Consumers are increasingly influencing product innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government initiatives actively promoting plant-based diets are stimulating demand for vegan desserts across diverse regions. These policies, coupled with consumer health trends, drive localized market expansion. Support for sustainable food systems further underpins this growth.
Germany
Germany's large vegan population and extensive retail availability drive consistent demand for vegan desserts. The ISO 23662 standard provides a clear definition for vegan food, enhancing consumer trust. Berlin's vibrant food tech scene actively develops innovative plant-based formulations.
United Kingdom
The United Kingdom experiences a significant channel shift toward mainstream retail for vegan desserts. EFSA regulations compel manufacturers to ensure ingredient transparency for health claims. London's diverse food scene fosters new product development and market accessibility.
United States
Health-conscious consumers and lactose-intolerant individuals fuel demand for vegan dessert alternatives in the United States. U.S. FDA food labeling regulations govern allergen declarations and health claims on products. California's innovation hubs are a center for plant-based food startups.
Canada
Growing flexitarian populations and ethical consumerism bolster demand for vegan desserts across Canada. Health Canada's dietary guidelines encourage plant-based food consumption, influencing product development. Toronto's burgeoning plant-based food industry develops diverse vegan dessert options.
Australia
Rising health consciousness and environmental concerns contribute to robust demand for vegan desserts in Australia. Food Standards Australia New Zealand (FSANZ) labeling requirements ensure ingredient transparency for consumers. Melbourne's innovative café culture supports the adoption of new vegan dessert trends.
Vegan Dessert Market Key Industry Players
Listed leaders compete with private specialists across product innovation, market share, and distribution reach within the vegan dessert market. The market structure is tiered, characterized by large conglomerates leveraging extensive networks alongside specialized producers focusing on niche segments and clean-label formulations. Strategic archetypes include global food giants, dedicated plant-based innovators, and ingredient technology providers. Competitive moves involve strategic partnerships for market entry, continuous product line extension, and geographic expansion into underpenetrated markets.
Within the large conglomerate archetype, Unilever PLC represents the strategy of integrating plant-based lines into established distribution networks, leveraging its global reach. Oatly Group AB occupies a position as a specialized innovator, anchoring the oat-based formulation segment with significant brand recognition among consumers seeking dairy alternatives. Daiya Foods Inc. exemplifies a focused approach, sitting within the dairy-free alternatives segment and specializing in cheese-based dessert components that are often incorporated into broader product offerings.
| Leading Market Players |
|---|
| Unilever PLC |
| Nestlé S.A. |
| Danone S.A. |
| Oatly Group AB |
| Tofutti Brands Inc. |
| Daiya Foods Inc. |
| Ben & Jerry's Homemade, Inc. |
| NadaMoo! |
| OGGS |
| Others |
Cost & Logistics Intelligence
Plant-based ingredient substitution for traditional dairy products simultaneously reshapes agricultural supply geography and alters consumer pricing economics. This dynamic drives innovation in sourcing and formulation across the vegan dessert sector.
Pricing Analysis
Clean-label certification creates the primary spread between premium and standard vegan dessert offerings. The dominant pricing structure is value-based, reflecting ingredient quality and brand perception among consumers. Price differentiation stems from the use of specialized plant proteins and the complexity of texture replication. Pricing pressure stems from the high cost and volatility of key inputs like nuts and hydrocolloids. Health-conscious consumers are generally less price-sensitive for clean-label, high-quality options, while mainstream supermarket shoppers exhibit higher price sensitivity.
Supply Chain Analysis
Just-in-time inventory strategies are difficult to implement given the natural variability of plant-based raw materials. Geographic supply concentration for critical inputs like almonds and cashews sits primarily in California, India, and Vietnam. Coconut products are sourced heavily from Southeast Asia, including the Philippines and Indonesia. The market depends on specialized hydrocolloids and plant-based protein isolates. Commodity price volatility for nuts and coconut represents a significant structural risk. Distribution runs through established retail channels, with a strong emphasis on cold chain logistics for frozen and refrigerated products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The vegan dessert market is experiencing a cyclical recovery, driven by a renewed consumer focus on health and sustainable dietary choices post-pandemic.
For Market Incumbents: Fortify existing distribution networks within mainstream supermarkets to capture a broader consumer base against niche brand competition. Diversify ingredient sourcing to mitigate commodity price volatility for nuts and coconut. Invest in advanced R&D for novel plant-based protein texturizers to enhance product authenticity. Acquire specialized ingredient suppliers to gain upstream control over critical inputs and manage supply chain risks.
For New Entrants and Emerging Players: Unaddressed consumer demand for sophisticated, clean-label dessert categories represents a significant service-layer gap. Target white spaces like refrigerated cheesecakes and multi-layered tortes to command higher price points. The ethical consumer segment, seeking transparent ingredient lists, is the most penetrable. A direct-to-consumer (DTC) model, emphasizing ingredient provenance and sustainability, offers a compelling go-to-market angle.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with innovative plant-based brands that have achieved early traction in niche segments. The long-term viability of the vegan dessert market remains strong over a 5-10 year window, supported by sustained demographic shifts. Acquisition targets should focus on companies with proprietary ingredient technology or strong clean-label positioning. The successful scaling of precision fermentation-derived proteins signals a key inflection point for future investment.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Cold Chain Logistics | Unilever PLC can reach new geographic markets with temperature-sensitive vegan frozen desserts. |
| Invest in Novel Protein Texturization | Oatly Group AB can replicate dairy mouthfeel more authentically across its oat-based product lines. |
| Acquire Clean-Label Ingredient Suppliers | Daiya Foods Inc. can secure consistent supply of high-quality, natural inputs for its dairy-free alternatives. |
| Introduce Refrigerated Dessert Lines | Nestlé S.A. can capture higher price points in the growing market for sophisticated plant-based treats. |
| Secure ISO 23662 Certification | Danone S.A. can enhance consumer trust and simplify market access for its vegan product claims. |
Research Approach
Two parallel data streams informed the analysis: primary field interviews and extensive secondary research. Industry stakeholders, including food scientists, retail category managers, plant-based brand founders, and ingredient suppliers, provided critical qualitative insights. Secondary data sources comprised EFSA reports, U.S. FDA filings, ISO standards documents, and company sustainability reports, supporting bottom-up and top-down triangulation.
The analytical framework modeled market segmentation across product types, ingredients, distribution channels, customer types, and regional consumption patterns over the projection horizon. Compound annual growth rates were derived by integrating historical market performance with forward-looking economic indicators. Plant-based ingredient pricing trends and evolving consumer dietary shifts served as key industry-specific forecast inputs.
Material uncertainties — including rapid breakthroughs in food science or significant shifts in agricultural commodity prices — sit outside the modeled envelope. Forecasts reflect assumptions documented through stakeholder consensus and historical trends. Revision becomes warranted when new ingredient technologies or major regulatory changes cross established thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Vegan Gelatin Market
Plant Based Food
Global Vegan Fast Foods Market
Plant Based Food
Plant-Based Protein Food Market
Plant Based Food
Vegan Pizza Crust Market
Plant Based Food
Germany Plant Protein Market
Plant Based Food
Plant-Based Vegan Eggs Market
Plant Based Food
Plant Based Collagen Market
Plant Based Food
USA Plant-Based Creamers Market
Plant Based Food
Mexico Plant-Based Food and Beverages Market
Plant Based Food
Burdock Root Extract Market
Plant Based Food
China Rice Protein Market
Plant Based Food
Insoluble Pea Protein Market
Plant Based Food
Plant Based Ice Cream Market
Plant Based Food
Plant-Based Flour Market
Plant Based Food
Plant-Based Ham Market
Plant Based Food
Plant-Based Food and Beverages Market