
 Vegan Pizza Crust Market | 2026-2036
Vegan Pizza Crust Market Size, Share, and Industry Trends Forecast 2026-2036
Vegan Pizza Crust Market Analytics
Subscription-based replenishment programs for frozen vegan pizza crusts is realigning how manufacturers capture recurring revenue beyond one-time retail purchases. Bob's Red Mill leverages its vertically integrated flour milling to secure consistent organic supply chains for private-label crust production. Rustic Crust anchors its position through direct-to-restaurant distribution, bypassing conventional retail markup structures entirely.
A vegan pizza crust is a leavened or unleavened flatbread base formulated without animal-derived ingredients such as dairy, eggs, or honey, typically employing cold-pressed olive oil, yeast, and plant-based binders to achieve structural integrity at baking temperatures exceeding 230°C. Its primary commercial purpose is to serve as a ready-to-top foundation for foodservice and retail pizza products targeting consumers with ethical dietary restrictions or allergen sensitivities. Cauliflower-based formulations now command premium shelf positioning as the fastest-growing product type, though almond flour variants retain higher margin pools due to ingredient scarcity and longer production cycles. The frozen form dominates volume throughput in supermarkets, while fresh and mix formats capture disproportionate attention from health food stores seeking shorter ingredient lists.
The FDA's Food Safety Modernization Act and USDA organic certification requirements govern ingredient traceability and labeling claims for crusts distributed across United States retail channels. The EU Green Deal and EFSA novel food assessments shape which plant proteins gain rapid market access within European Union member states. Stakeholders must monitor evolving allergen thresholds and cross-contamination standards as cauliflower and chickpea processing facilities expand shared equipment footprints.
Market Dynamics
Restaurant chains and foodservice operators are consolidating procurement power through plant-based menu mandates, compressing margin structures for crust suppliers while accelerating volume commitments. This buyer concentration is forcing manufacturers to reconfigure production capacity toward frozen bulk formats.
Growth Catalysts
- EU Green Deal sustainable food targets:The European Commission's binding sustainability requirements are redirecting ingredient sourcing toward certified organic supply chains and regenerative agriculture partnerships.
- Cauliflower processing scale-up:Specialized extraction facilities in Germany and the Netherlands are achieving cost parity with wheat-based alternatives through continuous fermentation optimization.
- Foodservice contract consolidation:Multi-unit restaurant operators are mandating vegan crust availability across entire portfolios, creating guaranteed offtake volumes that de-risk capital investments.
Market Restraints
- Almond flour input scarcity:California drought cycles and water allocation disputes are creating price volatility for premium nut-based formulations.
- Shared equipment allergen thresholds:Cauliflower and chickpea processing facilities face EFSA-mandated cleaning protocols that extend changeover downtime.
- Technical textural limitations:Plant-based binders struggle to replicate the chew resistance of gluten networks above 250°C baking temperatures.
Strategic Opportunities
- German retail shelf expansion:Discounters and premium organic chains are dedicating dedicated freezer sections to plant-based pizza components.
- Subscription replenishment models:Direct-to-consumer frozen crust programs are capturing recurring revenue streams outside traditional retail markup structures.
- Cold-pressed oil convergence:Olive oil extraction technology is merging with high-pressure processing to extend frozen shelf life without chemical preservatives.
Industry Challenges
- Organic certification timeline compression:USDA and EU organic equivalency negotiations are delaying cross-border shipment approvals.
- Legacy frozen dough line retrofitting:Existing wheat-dedicated facilities require six-figure capital outlays for allergen segregation infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegan Pizza Crust Market |
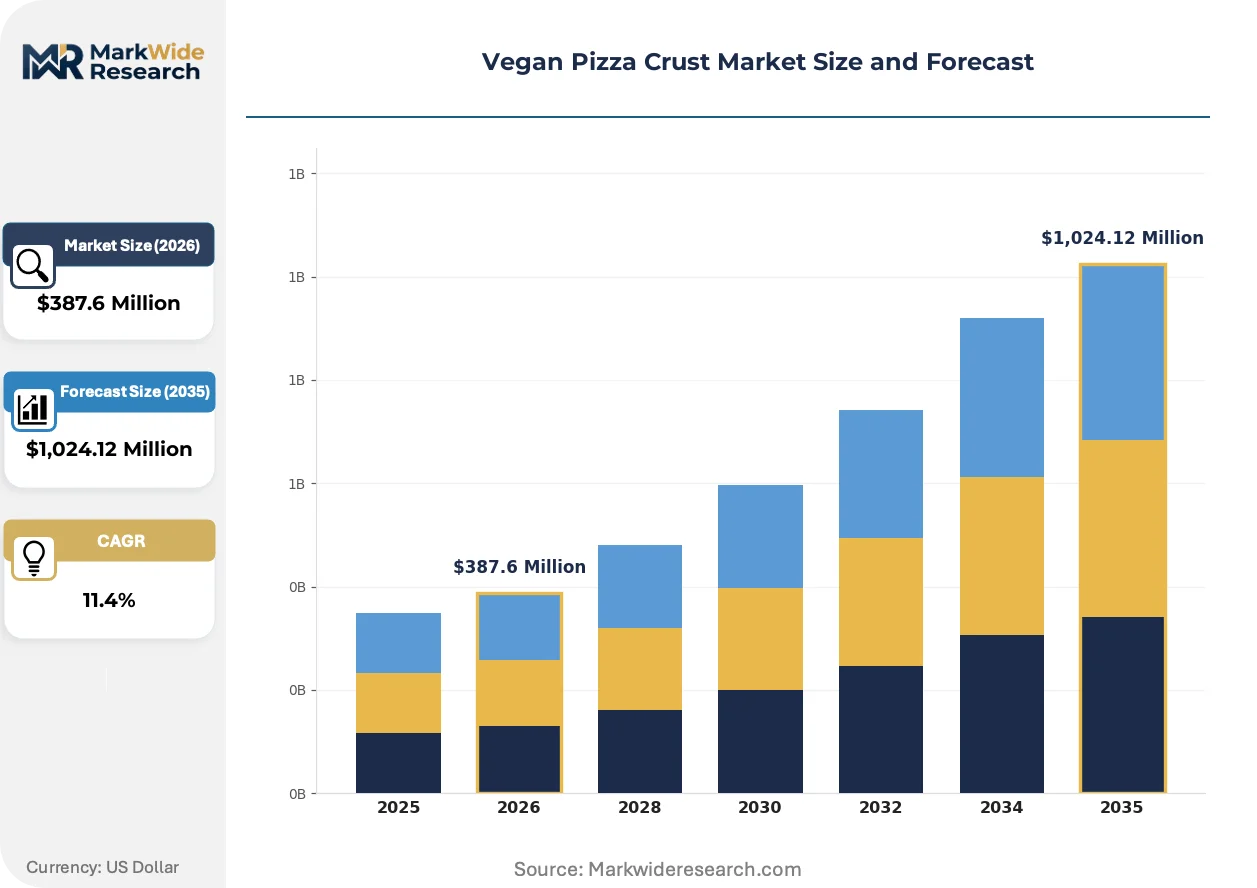
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,024.12 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cauliflower, Almond Flour, Chickpea, Whole Wheat Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Restaurants Consumer Type: Vegetarians, Vegans, Health-Conscious Individuals, Gluten-Free Consumers Form: Frozen, Fresh, Pre-Cooked, Mix |
| Companies Covered | Simple Truth Organic, Rustic Crust, Namaste Foods, Golden Home Bakery, Little Northern Bakehouse, Bob's Red Mill, Cali'flour Foods, Daiya, Angelic Bakehouse, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegan Pizza Crust Market Evolving Landscape
Formulation science and regulatory compliance frameworks are converging to redefine acceptable ingredient declarations and processing claims. Manufacturers must now validate structural performance under dual certification regimes.
Sourdough-fermented cauliflower bases are overtaking conventional yeast-leavened alternatives in premium positioning. Artisan pizzeria chains in Italy and Spain are adopting these formulations for their extended fermentation depth. The technology is overtaking commodity wheat crusts in margin capture by commanding shelf space in organic retail channels.
EFSA novel food assessments are tightening approval pathways for emerging plant proteins like fava bean isolates. Manufacturers must submit comprehensive toxicology dossiers before commercial launch. The frozen pizza segment is responding by accelerating dossier preparation for chickpea and lentil protein variants.
Buyer consolidation among contract foodservice operators is compressing supplier negotiation cycles from annual to quarterly terms. Multi-unit chains are unbundling crust procurement from full pizza kit sourcing. This shift is most visible in Germany, where institutional catering contracts now specify vegan crust minimums.
Vegan Pizza Crust Market Segmentation
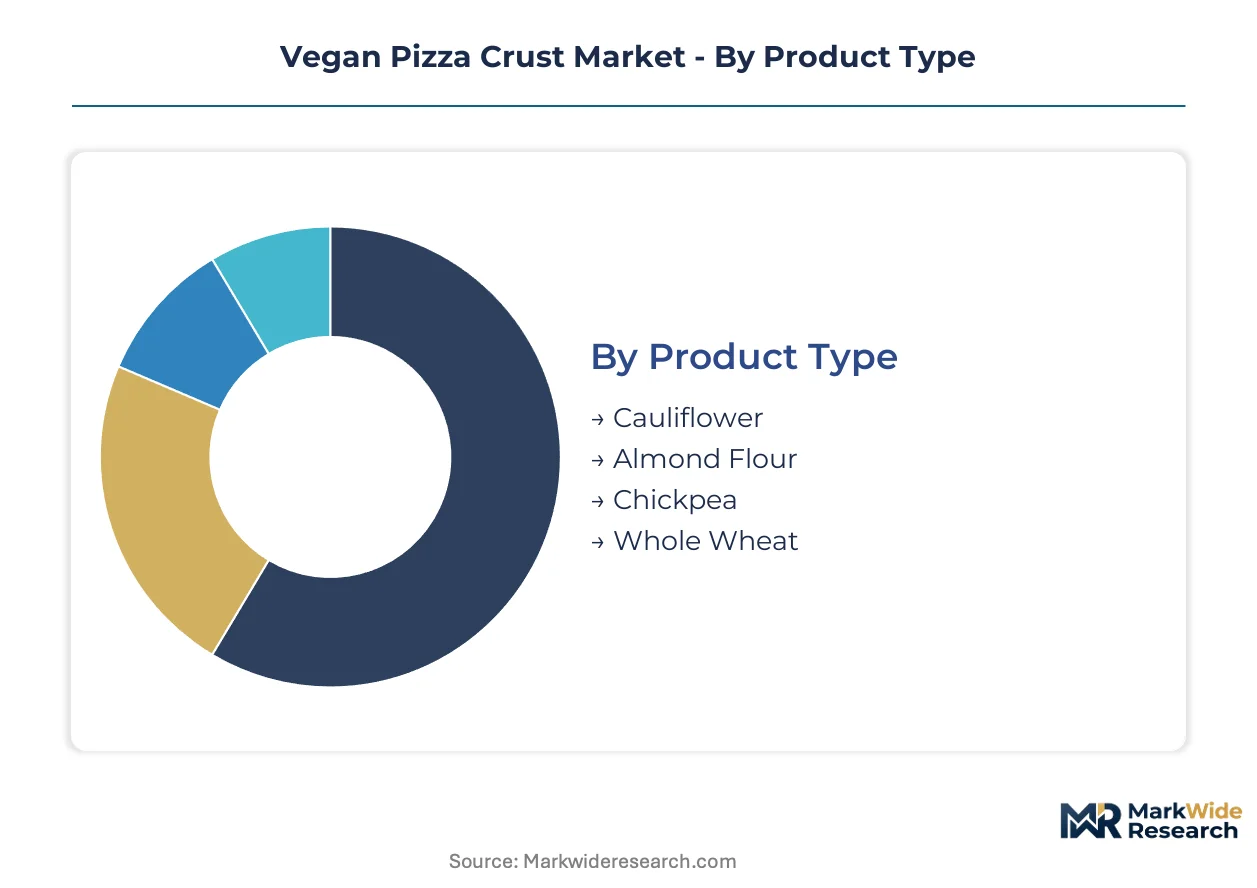
Segmentation in the vegan pizza crust market reveals how formulation technology, channel economics, and dietary identity intersect to create distinct profit pools. Understanding these divisions exposes where capital deployment yields the highest returns.
Product Type:
Upgrade cycles in this category accelerate when consumers trade up from commodity wheat alternatives to functional ingredient bases with specific nutritional claims.
- Cauliflower:Formulated from riced cauliflower bound with tapioca starch and nutritional yeast, achieving structural integrity through high-pressure extrusion. Demand concentrates in German supermarket freezer sections where discounters have doubled shelf space allocations for plant-based pizza components, driven by EU Green Deal procurement mandates favoring low-carbon ingredient sourcing.
- Almond Flour:Dense, protein-rich base requiring extended mixing cycles and lower hydration thresholds to prevent oil separation during baking. Premium positioning in US health food channels reflects California almond processing consolidation and sustained input scarcity from drought-driven water allocation disputes.
- Chickpea:Neutral-flour base with high fiber content and moderate protein density, processed through conventional milling equipment with minimal retrofit requirements.
- Whole Wheat:Traditional vegan formulation omitting dairy and egg binders in favor of cold-pressed olive oil and modified starches, serving cost-sensitive foodservice contracts.
Cauliflower sits at the top of the volume ranking, with chickpea climbing the fastest as EFSA novel food pathways streamline for legume-based formulations.
Distribution Channel:
Channel selection determines margin capture, with direct routes preserving 15-25 percentage points more gross profit than conventional retail intermediation.
- Online Retail:Subscription-based replenishment programs capture recurring revenue through automated delivery schedules, bypassing slotting fees and seasonal promotional cycles that erode profitability in brick-and-mortar.
- Supermarkets:Frozen form dominates volume throughput here, with dedicated plant-based freezer sections expanding in German discounters and premium organic chains across the EU.
- Health Food Stores:Fresh and mix formats disproportionately concentrate in this channel, where shorter ingredient lists and fermentation depth command price premiums from label-conscious shoppers.
- Restaurants:Direct-to-restaurant distribution bypasses retail markup structures entirely, with multi-unit chains mandating vegan crust availability across entire portfolios under plant-based menu mandates.
Restaurants lead in value capture per unit, while online retail expands most quickly as manufacturers build proprietary subscription infrastructure.
Consumer Type:
Dietary identity creates distinct willingness-to-pay thresholds, with medical necessity driving higher price tolerance than ethical preference alone.
- Vegetarians:Flexible dietary framework accepting dairy and egg derivatives, requiring explicit vegan labeling to prevent confusion at point of purchase.
- Vegans:Strict exclusion of all animal-derived inputs, with heightened sensitivity to cross-contamination protocols and supply chain transparency claims.
- Health-Conscious Individuals:Nutrient-density seekers prioritizing fiber and protein content over caloric reduction, receptive to fermentation-based positioning and sourdough cauliflower variants.
- Gluten-Free Consumers:Medical necessity segment with zero tolerance for wheat cross-contamination, driving demand for dedicated processing facilities and third-party certification.
Vegans anchor the premium tier in absolute margin per transaction, with gluten-free consumers gaining share fastest as diagnostic rates for celiac and non-celiac wheat sensitivity climb.
Form:
Form selection reflects trade-offs between convenience, sensory quality, and inventory carrying costs across different usage occasions.
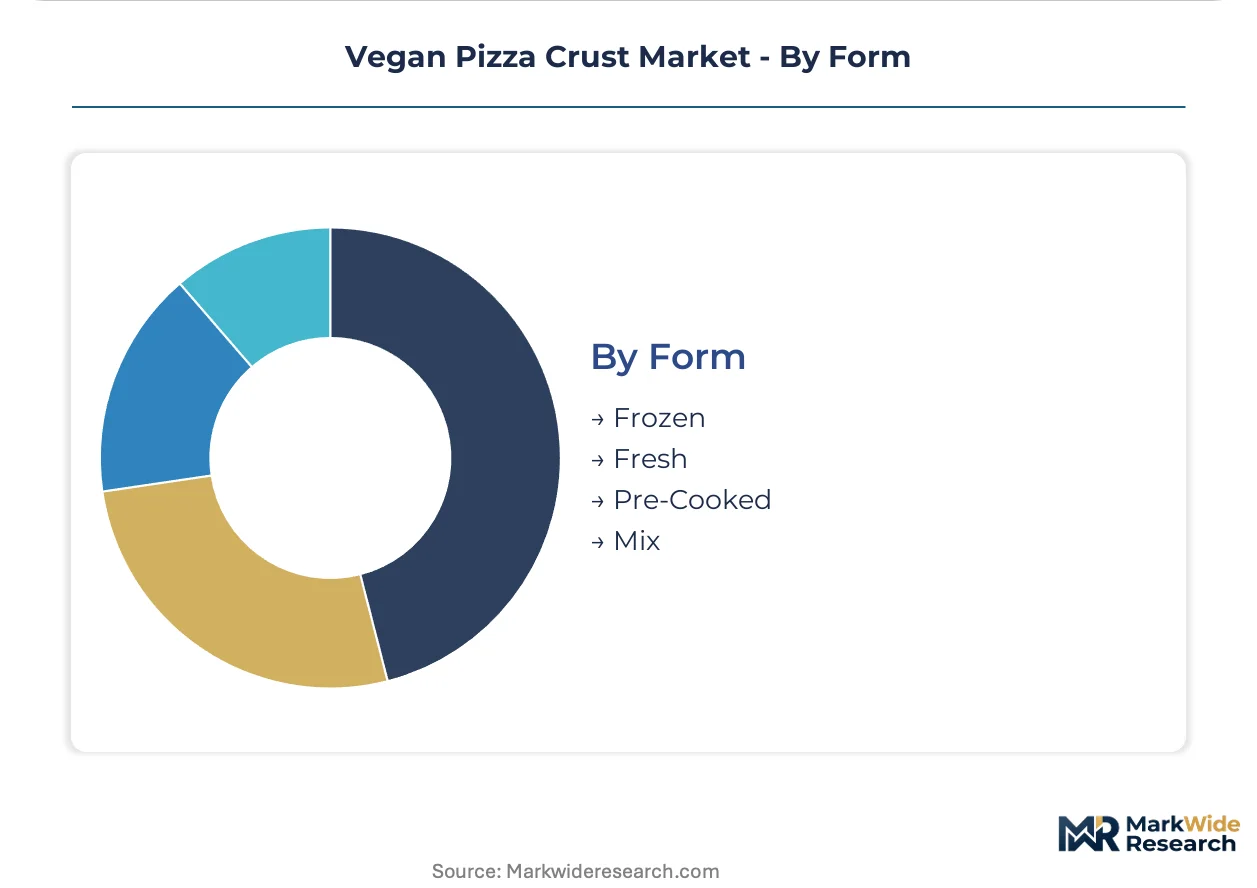
- Frozen:Blast-frozen at -18°C immediately after par-baking, extending shelf life without chemical preservatives through cold-pressed oil convergence with high-pressure processing technology.
- Fresh:Refrigerated distribution with 7-14 day shelf life, capturing disproportionate attention from health food stores seeking shorter ingredient lists and live fermentation cultures.
- Pre-Cooked:Fully baked shells requiring only topping application and final warming, dominating foodservice prep-line efficiency requirements.
- Mix:Dehydrated flour blends requiring hydration and proofing, appealing to scratch-cooking enthusiasts and institutional catering operations with on-site baking capability.
Frozen commands absolute volume leadership, with mix formats expanding most quickly in German institutional catering contracts specifying on-site preparation protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany outpaces the United States in vegan pizza crust shelf space allocation, while California almond supply constraints reshape premium formulation economics across North American markets.
Germany
Discounters and organic chains have doubled freezer section allocations for plant-based pizza components. The EU Green Deal's sustainable food system targets mandate certified organic sourcing for institutional procurement. Berlin and Munich host specialized cauliflower extraction facilities achieving cost parity with wheat through continuous fermentation optimization.
United States
Multi-unit restaurant chains now mandate vegan crust availability across entire portfolios under plant-based menu mandates. The FDA's Food Safety Modernization Act governs ingredient traceability and labeling claims for retail distribution. California's Central Valley almond processing consolidation faces sustained input scarcity from drought-driven water allocation disputes.
Netherlands
Specialized legume protein processing facilities are streamlining EFSA novel food dossiers for chickpea and lentil variants. The EU Green Deal redirects ingredient sourcing toward regenerative agriculture partnerships. Rotterdam and Amsterdam anchor cold-chain logistics hubs serving frozen crust distribution across northwestern Europe.
Italy
Artisan pizzeria chains are adopting sourdough-fermented cauliflower bases for extended fermentation depth positioning. EFSA novel food assessments govern approval pathways for emerging plant proteins. Milan and Bologna concentrate premium organic retail channels commanding margin capture from fermentation-based formulations.
United Kingdom
Health food stores disproportionately stock fresh and mix formats with shorter ingredient lists and live fermentation cultures. The UK's post-Brexit organic certification timeline compresses cross-border shipment approvals with EU suppliers. London's foodservice procurement offices are consolidating contract terms from annual to quarterly cycles.
Vegan Pizza Crust Market Competitive Landscape
Top-tier vendors anchor premium organic positioning, while mid-scale specialists occupy private-label and foodservice tiers. The vendor base stratifies across three functional layers: vertically integrated flour millers, direct-to-restaurant distributors, and cauliflower-focused formulation innovators. Two dominant competitive moves are reshaping positioning: backward integration into captive organic supply chains, and direct distribution partnerships bypassing retail markup structures.
Within the vertically integrated tier, Bob's Red Mill represents upstream control over organic flour milling for private-label crust production. Rustic Crust occupies a position exemplifying direct-to-restaurant distribution archetypes that bypass conventional retail channels entirely. Cali'flour Foods anchors the cauliflower-specialist vector, sitting within the premium formulation segment targeting health-conscious consumers.
| Leading Market Players |
|---|
| Simple Truth Organic |
| Rustic Crust |
| Namaste Foods |
| Golden Home Bakery |
| Little Northern Bakehouse |
| Bob's Red Mill |
| Cali'flour Foods |
| Daiya |
| Angelic Bakehouse |
| Others |
Value Network & Pricing Analysis
High-pressure extrusion technology for cauliflower-based formulations is compressing production costs while concentrating manufacturing capacity in Germany and the Netherlands, simultaneously reshaping price floors for commodity wheat alternatives and concentrating supplier bargaining power among equipment owners.
Pricing Analysis
Capacity additions in Germany and the Netherlands are reshaping price floors for cauliflower-based crusts as continuous fermentation optimization achieves cost parity with wheat alternatives. Three-tier pricing structure across premium, standard, and economy levels separates certified organic sourdough-fermented bases from conventional yeast-leavened formats and private-label commodity options. Pricing pressure stems from foodservice contract consolidation compressing supplier margins under quarterly negotiation cycles. Quick-service restaurant chains exhibit highest price sensitivity due to volume procurement mandates, while health food stores tolerate premium positioning for shorter ingredient lists and live fermentation cultures.
Supply Chain Analysis
Skilled fermentation technicians and extrusion equipment operators concentrate in German industrial clusters around Berlin and Munich, creating workforce bottlenecks that constrain capacity expansion timelines. Raw material sourcing draws from California almond orchards facing drought-driven water allocation disputes, Italian olive oil cooperatives supplying cold-pressed inputs, and Dutch legume protein processors streamlining EFSA novel food dossiers. Single-source vulnerability runs through California almond flour supply for premium formulations. Distribution runs through Rotterdam cold-chain hubs serving frozen crust logistics across northwestern Europe, with direct-to-restaurant routes bypassing retail intermediation entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on fermentation technology cost-down curves and the shift toward sourdough-fermented premium tiers commanding organic certification premiums.
For Market Incumbents: Anchor market position through backward integration into captive organic supply chains and direct distribution partnerships that bypass retail slotting fees. Defend against cauliflower-specialist entrants by securing exclusive multi-year foodservice contracts before quarterly procurement consolidation accelerates. Invest in high-pressure extrusion capacity additions in Germany to maintain cost-parity positioning against wheat alternatives. For New Entrants and Emerging Players: Launch via subscription-based replenishment programs targeting health-conscious consumers outside conventional retail markup structures. White-space opportunity concentrates in fresh and mix formats for UK health food stores seeking live fermentation cultures. German institutional catering contracts specifying on-site preparation protocols offer the most penetrable entry point for chickpea-based formulations with minimal equipment retrofit requirements. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale cauliflower-specialist manufacturers because EFSA novel food approval timelines create barriers against rapid follower entry. Five-to-ten year viability hinges on certified organic supply chain control rather than formulation patents alone. Signal to watch: EU Green Deal procurement mandate adoption rates across German discounters indicating institutional demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Supply | Captive sourcing from regenerative agriculture partnerships secures EU Green Deal compliance and margin protection. |
| Direct-to-Restaurant Distribution Buildout | Bypassing retail intermediation preserves 15-25 percentage points of gross profit for foodservice-focused suppliers. |
| High-Pressure Extrusion Scale-Up | German and Dutch facilities achieving cost parity with wheat through continuous fermentation optimization. |
| EFSA Novel Food Dossier Preparation | Early submission for chickpea and lentil protein variants accelerates market access before regulatory pathways tighten. |
| Subscription Infrastructure Investment | Proprietary replenishment programs capture recurring revenue outside seasonal promotional cycles eroding brick-and-mortar profitability. |
Research Methodology
Bottom-up foodservice and retail channel modeling reconciled against top-down ingredient supply and production capacity tracking forms the analytical core of this study. Primary interviews with plant-based menu development executives at multi-unit restaurant chains, procurement directors at German discounters, organic certification specialists, and frozen distribution logistics managers combined with secondary validation from EU Green Deal policy documents, EFSA novel food assessment registers, USDA organic equivalency negotiation records, and customs trade data for almond and cauliflower ingredient flows.
Input-output matrices map cauliflower and legume protein supply volumes against foodservice contract commitments and retail shelf space allocations across the analysis window. Segmentation dimensions include product type, distribution channel, consumer dietary identity, and form factor. CAGRs derive from trend extrapolation of contract consolidation patterns and fermentation technology adoption curves, cross-referenced against EU sustainable procurement mandate implementation schedules and California water allocation dispute resolutions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt EU organic certification timeline compression or California almond harvest collapses. Projections reflect documented assumptions regarding EFSA novel food approval velocity and foodservice buyer concentration trajectories. Material deviation in German institutional procurement mandate adoption or high-pressure extrusion equipment delivery delays warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Plant Based Collagen Market
Plant Based Food
North America Tofu Market
Plant Based Food
Europe Meat Substitutes Market
Plant Based Food
Plant Based Pork Market
Plant Based Food
Plant Based Supplement Market
Plant Based Food
Plant Based Protein Market
Plant Based Food
Flax-Based Protein Market
Plant Based Food
Faba Bean Protein Market
Plant Based Food
Soy Food Products Market
Plant Based Food
Kava Root Extract Market
Plant Based Food
Europe Pea Protein Market
Plant Based Food
Extruded Soy Products Market
Plant Based Food
Plant-Based Milk Alternatives Market
Plant Based Food
Vegan Flour Market
Plant Based Food
Mexico Plant-Based Food and Beverages Market
Plant Based Food
Fermented Plant-Based Food Market