
 China Milk Protein Market | 2026-2036
China Milk Protein Market Size, Share, and Industry Trends Forecast 2026-2036
China Milk Protein Market Outlook
Sports nutrition brands are reorganizing procurement priorities toward domestic whey protein suppliers as fitness enthusiasts expand as the fastest-growing end user archetype. Fonterra Co-operative Group Limited anchors its position through captive dairy sourcing relationships across China's coastal processing zones. China Mengniu Dairy Company Limited leverages vertical manufacturing scale to dominate casein and milk protein concentrate output for food manufacturers. Arla Foods Ingredients Group differentiates through specialized whey protein isolate formulations targeting hospital and clinical nutrition channels.
China milk protein encompasses concentrated or isolated dairy fractions—typically containing 34% to 90% protein by dry weight—extracted through membrane filtration, ion exchange, or acid precipitation for nutritional fortification and functional food applications. Whey protein leads volume consumption in sports nutrition and nutritional supplements where rapid amino acid absorption drives formulation choices, while milk protein isolate commands premium positioning in specialty foods and clinical applications requiring controlled digestion profiles. Casein retains structural importance in food manufacturing for emulsification and texture modification across baked goods and processed dairy categories.
China's national dairy regulator enforces GB standards for protein content labeling and microbiological safety that directly shape import clearance timelines and domestic facility certification requirements. The NMPA nutritional fortification framework governs permitted protein claims in supplements and infant-adjacent products, filtering which formulations reach hospital and fitness channels. Stakeholders must monitor evolving SAMR enforcement patterns around protein adulteration testing and traceability mandates to anticipate compliance cost trajectories and sourcing strategy adjustments.
Market Dynamics
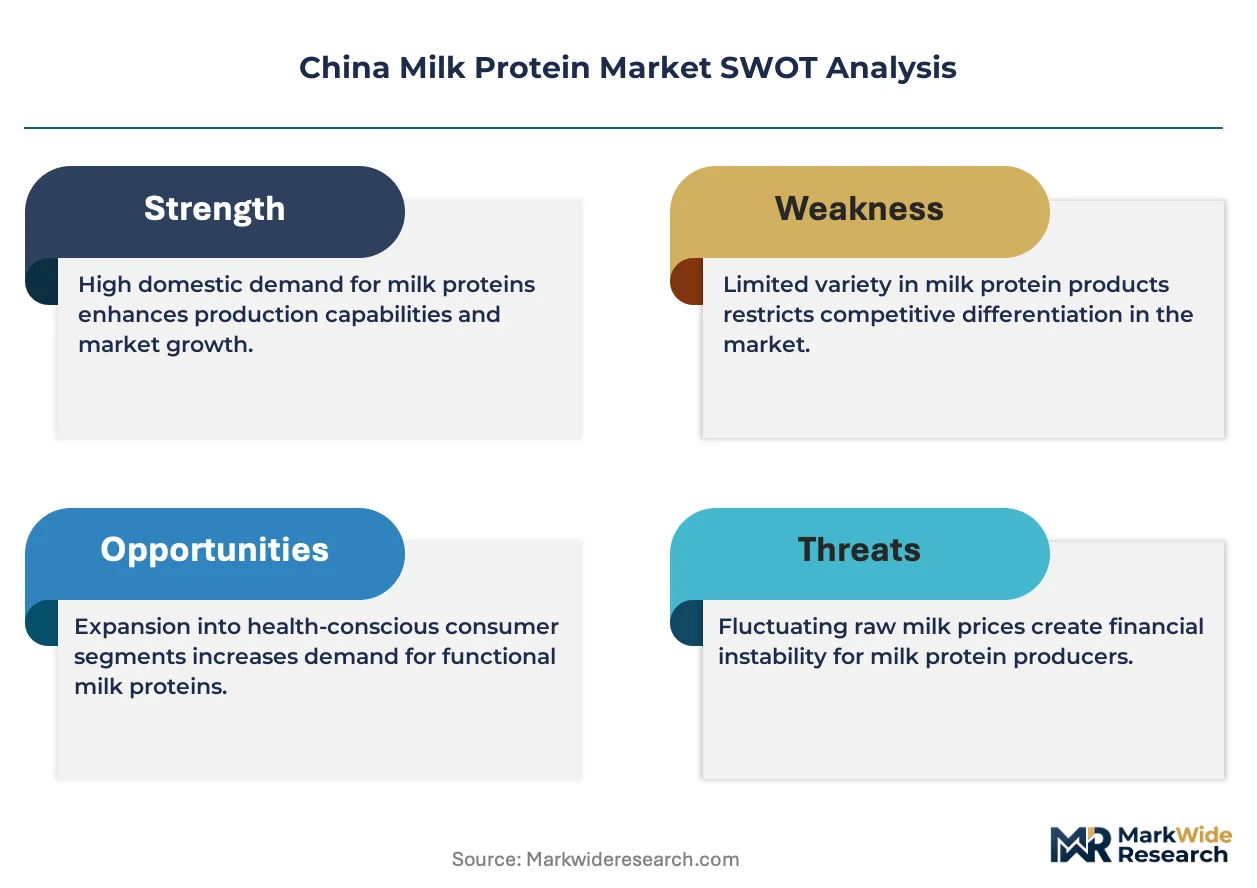
Fitness culture proliferation in Shanghai and Guangdong is compressing procurement cycles for domestic whey suppliers, while NMPA nutritional fortification rules and GB standards for dairy protein purity reshape import clearance timelines and domestic facility certification requirements.
Growth Catalysts
- GB Standards Enforcement:China's national dairy regulator enforces protein content labeling and microbiological safety standards that accelerate domestic facility upgrades and filter substandard imports from hospital and fitness channels.
- Fitness Enthusiast Expansion:Sports nutrition brands reorganize procurement toward domestic whey suppliers as gym membership density rises fastest in coastal manufacturing clusters.
- Membrane Filtration Advancement:Ion exchange and acid precipitation technologies enable protein concentration from 34% to 90% dry weight, expanding functional food applications.
Market Restraints
- Import Clearance Friction:SAMR enforcement patterns around protein adulteration testing and traceability mandates extend compliance timelines for foreign suppliers.
- Raw Milk Supply Concentration:Captive dairy sourcing relationships concentrate in coastal processing zones, limiting independent processor access to quality feedstock.
- Plant Protein Substitution:Soy and pea protein isolates gain formulation share in nutritional supplements where rapid amino acid absorption is less critical.
Strategic Opportunities
- Clinical Nutrition Penetration:Hospital and elderly care channels remain underdeveloped for specialized whey protein isolate formulations requiring controlled digestion profiles.
- Dual Carbon Alignment:China's dual carbon goals create incentive structures for low-carbon dairy processing technologies and regional supply chain shortening.
- E-Commerce Direct Distribution:Fitness supplement brands bypass traditional wholesale layers through live-streaming commerce platforms targeting tier-two city consumers.
Industry Challenges
- Specialized Technician Scarcity:Membrane filtration operation and protein fractionation quality control require skills concentrated in coastal dairy science programs.
- Certification Timeline Compression:NMPA nutritional fortification framework updates demand rapid reformulation and label revision for supplement manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Milk Protein Market |
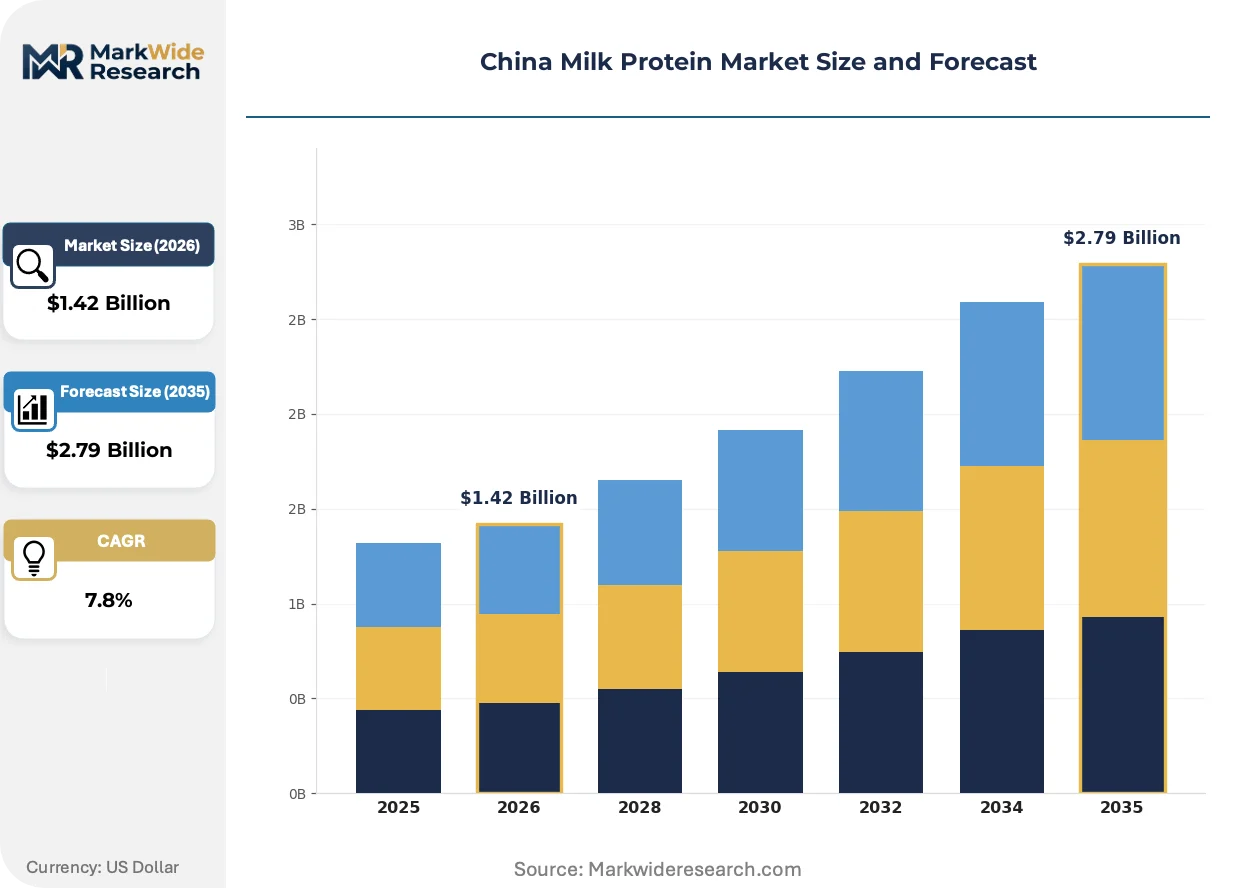
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.79 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whey Protein, Casein, Milk Protein Concentrate, Milk Protein Isolate Application: Food & Beverage, Nutritional Supplements, Sports Nutrition, Specialty Foods Distribution Channel: Online Retail, Supermarkets, Health Stores, Wholesalers End User: Individuals, Food Manufacturers, Fitness Enthusiasts, Hospitals |
| Companies Covered | LACTALIS Ingredients, FrieslandCampina, Fonterra Co-operative Group Limited, Nestlé, a2 Milk Company, Saputo Inc., Arla Foods Ingredients Group, Danone, China Mengniu Dairy Company Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Milk Protein Market Strategic Shifts
Protein extraction technologies and regulatory enforcement patterns are compressing traditional supply relationships, while fitness channel procurement models rotate toward domestic sourcing and direct-to-consumer distribution.
Microfiltration and ultrafiltration membrane systems are displacing traditional heat-based protein concentration methods in coastal processing facilities. Sports nutrition manufacturers adopt these systems fastest in Guangdong and Shanghai zones. This technology shift is displacing energy-intensive legacy equipment and enabling higher protein purity at lower thermal degradation.
SAMR traceability mandates and GB standard updates for dairy protein labeling tighten compliance verification requirements across import and domestic production streams. Facility certification timelines extend for foreign suppliers while domestic processors accelerate HACCP and ISO alignment. Hospital and clinical nutrition channels face the steepest reformulation burdens as protein adulteration testing protocols expand.
Direct procurement contracts between fitness brands and domestic whey processors are shortening traditional multi-tier distribution structures. E-commerce live-streaming platforms displace conventional supplement retail in tier-two and tier-three city penetration. This channel rotation is most visible in Sichuan and Zhejiang where fitness culture growth outpaces brick-and-mortar retail expansion.
China Milk Protein Market Segmentation
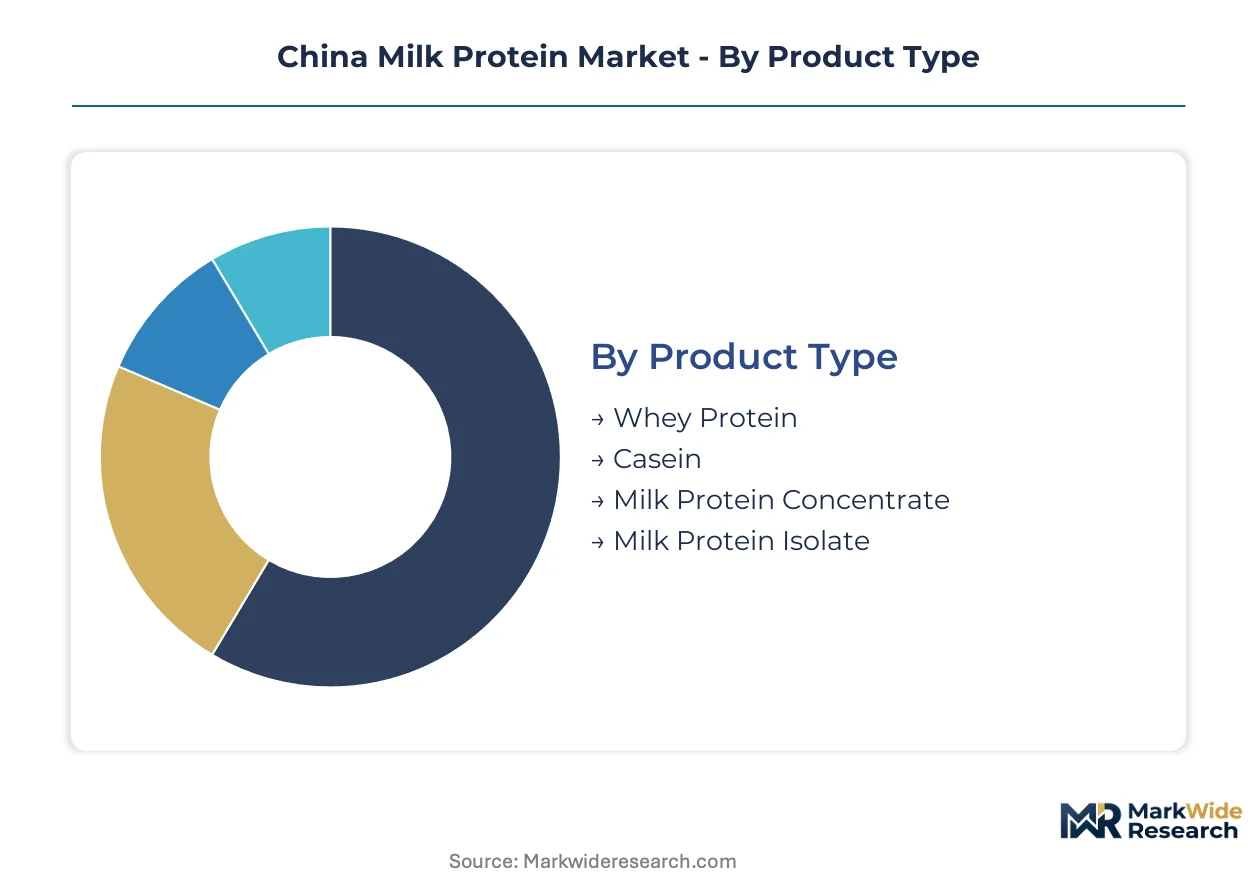
Protein purity thresholds and NMPA nutritional fortification classifications determine which segments access hospital and fitness channels. GB standards enforcement creates divergent compliance burdens across product types and applications.
Product Type:
NMPA nutritional fortification rules and GB standards for dairy protein purity enforce differentiated labeling requirements across concentration levels and extraction methods.
- Whey Protein:Rapid amino acid absorption drives formulation preference in sports nutrition. Demand concentrates in Shanghai and Guangdong where gym membership density rises fastest and procurement cycles compress for domestic suppliers.
- Milk Protein Isolate:Controlled digestion profiles command premium positioning in clinical applications. Hospital and elderly care channels in coastal manufacturing clusters absorb volume where NMPA rules filter lower-purity alternatives from therapeutic nutrition.
- Casein:Emulsification and texture modification properties sustain structural importance across baked goods and processed dairy categories.
- Milk Protein Concentrate:Mid-range protein concentration enables cost-efficient fortification for mass-market food manufacturers.
Whey protein handles the majority of throughput; milk protein isolate is gaining share fastest on clinical channel expansion.
Application:
Cost tier stratification separates premium clinical formulations from mass-market fortification across coastal processing zones.
- Sports Nutrition:Fitness culture proliferation in tier-two cities drives live-streaming commerce penetration. Sichuan and Zhejiang absorb volume fastest where e-commerce platforms displace conventional retail.
- Nutritional Supplements:SAMR traceability mandates extend compliance timelines for import-dependent formulations targeting hospital channels.
- Specialty Foods:Premium positioning depends on membrane filtration technology adoption in Guangdong processing facilities.
- Food & Beverage:Mass-market fortification applications concentrate procurement among vertically integrated dairy processors.
Sports nutrition commands the steepest expansion trajectory; nutritional supplements carry the heaviest regulatory compliance burden.
Distribution Channel:
Channel selection correlates with customer geography and purchase urgency across tiered urban markets.
- Online Retail:Live-streaming platforms bypass traditional wholesale layers. Fitness supplement brands target tier-two city consumers through direct distribution models.
- Health Stores:Professional consultation requirements sustain brick-and-mortar presence for clinical nutrition products.
- Supermarkets:Mass-market protein fortification products concentrate in premium retail formats.
- Wholesalers:Food manufacturer procurement maintains multi-tier structures for bulk concentrate purchases.
Online retail is expanding most quickly on fitness channel rotation; wholesalers retain volume dominance in food manufacturing supply chains.
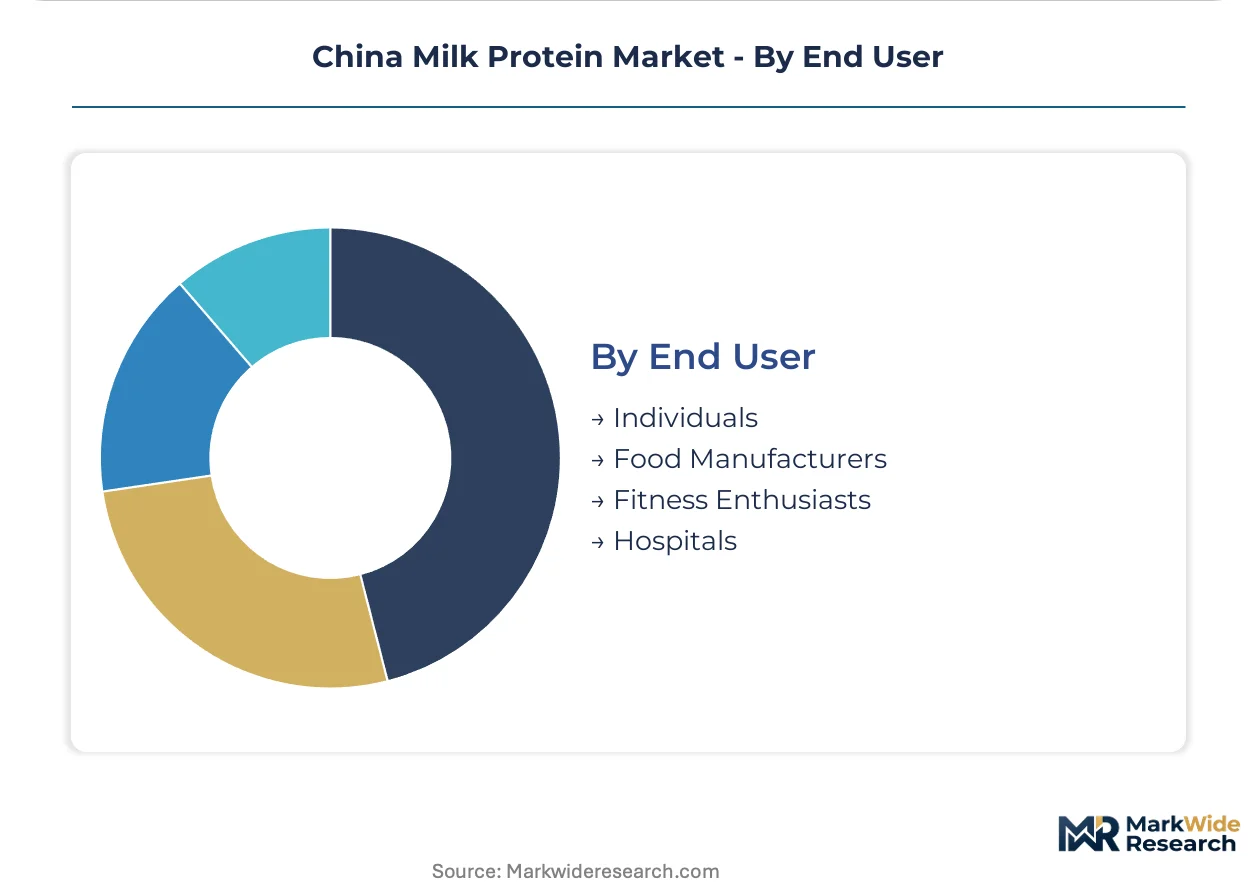
End User:
User sophistication determines formulation complexity and regulatory scrutiny intensity.
- Fitness Enthusiasts:Rapid absorption requirements and brand loyalty drive premium whey protein selection. Procurement reorganization toward domestic suppliers accelerates as gym density rises in coastal clusters.
- Hospitals:Controlled digestion profiles and NMPA nutritional fortification compliance filter supplier pools to specialized isolate formulators.
- Food Manufacturers:Texture modification and emulsification specifications sustain casein demand across baked goods production.
- Individuals:Convenience-oriented purchasing through e-commerce platforms concentrates in tier-two urban markets.
Fitness enthusiasts represent the fastest-growing demand archetype; hospitals impose the strictest purity verification requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New Zealand dairy exporters ship whey protein concentrate and milk protein isolate through Shanghai and Guangdong ports, feeding coastal manufacturing clusters where fitness brands compress procurement cycles toward domestic suppliers.
Shanghai
Gym membership density and sports nutrition brand headquarters drive whey protein demand fastest here. SAMR enforces GB standards for protein content labeling through port-of-entry inspections. The Yangpu and Pudong processing zones host membrane filtration facilities serving fitness supplement manufacturers.
Guangdong
Live-streaming commerce platforms displace conventional retail for fitness enthusiasts in tier-two city expansion. NMPA nutritional fortification rules filter lower-purity imports from hospital channels. The Pearl River Delta concentrates whey isolate processing for clinical nutrition applications.
Beijing-Tianjin-Hebei
Hospital procurement of specialized milk protein isolate for therapeutic nutrition sustains premium demand. MEE enforcement of dual carbon goals accelerates energy-efficient membrane system adoption. The Tianjin port corridor handles bulk casein imports for northern food manufacturers.
Sichuan-Chongqing
Fitness culture proliferation outpaces brick-and-mortar retail expansion, channeling volume through e-commerce direct distribution. GB standard updates for dairy protein traceability extend domestic facility certification timelines. Chengdu anchors western China sports nutrition brand distribution.
Zhejiang
Online retail penetration for protein supplements exceeds national averages through Alibaba ecosystem integration. SAMR protein adulteration testing protocols concentrate enforcement resources at Ningbo port. Hangzhou-based fitness brands reorganize procurement toward domestic whey processors.
China Milk Protein Market Competitive Environment
Player mix skews toward multinational dairy cooperatives with captive sourcing relationships and vertically integrated Chinese dairy conglomerates. Structure concentrates around three archetypes: New Zealand-Australian cooperatives controlling oceanic raw milk supply, European ingredients specialists commanding clinical nutrition premiums, and domestic dairy majors leveraging scale for food manufacturing supply. Competitive moves center on coastal processing zone capacity expansion and NMPA certification alignment for hospital channel access.
Among New Zealand-Australian cooperatives, Fonterra Co-operative Group Limited and a2 Milk Company exemplify the raw milk supply control archetype, while Arla Foods Ingredients Group occupies a position within the European clinical-specialist tier. China Mengniu Dairy Company Limited anchors the domestic scale-driven segment alongside FrieslandCampina's hybrid Asia-Pacific presence. These five represent divergent strategic positions around sourcing geography, purity tier, and channel specialization rather than direct product competition.
| Leading Market Players |
|---|
| LACTALIS Ingredients |
| FrieslandCampina |
| Fonterra Co-operative Group Limited |
| Nestlé |
| a2 Milk Company |
| Saputo Inc. |
| Arla Foods Ingredients Group |
| Danone |
| China Mengniu Dairy Company Limited |
| Others |
Value Chain & Pricing Dynamics
Forty-five to sixty-day import clearance timelines for foreign whey suppliers compress domestic processor pricing power while expanding margin capture for NMPA-certified domestic facilities. This lead-time differential anchors a supply chain where coastal manufacturing clusters command premium positioning against inland distributors.
Pricing Analysis
Membrane filtration technology-generation pricing gaps separate heat-based legacy systems from microfiltration-equipped facilities. Three-tier pricing structure across premium isolate, standard concentrate, and economy casein levels tracks protein purity thresholds and NMPA certification status. Pricing pressure stems from plant protein substitution in mass-market supplements where amino acid absorption speed matters less. Food manufacturers exhibit highest price sensitivity due to bulk procurement volumes, while hospital channels accept premium tiers for therapeutic nutrition compliance.
Supply Chain Analysis
Inventory compression to thirty-day cycles for domestic whey reflects fitness brand demand volatility and live-streaming commerce fulfillment requirements. Raw milk supply concentrates in New Zealand, Australia, and China's coastal processing zones where Fonterra and Mengniu maintain captive sourcing relationships. Ion exchange resins, ultrafiltration membranes, and acid precipitation chemicals constitute critical input dependencies. Single-source vulnerability runs through membrane equipment suppliers concentrated in European and Japanese manufacturing bases. Distribution runs through e-commerce direct channels displacing traditional wholesale layers in tier-two city expansion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fitness culture cyclicality in China tracks gym membership penetration waves, positioning the market for recovery as post-pandemic health consciousness sustains structural demand elevation.
For Market Incumbents: Shield market position by accelerating NMPA nutritional fortification certification alignment ahead of framework updates, and deepen backward integration into Yangpu and Pudong processing zone membrane filtration capacity. Fonterra's captive coastal sourcing relationships and Mengniu's vertical manufacturing scale represent defensible moats against emerging domestic challengers. Plant protein substitution in nutritional supplements constitutes the primary substitution threat requiring isolate purity differentiation.
For New Entrants and Emerging Players: NMPA fast-track certification for whey protein isolate formulations opens hospital channel access where Arla Foods Ingredients Group currently dominates. Target Sichuan-Chongqing and Zhejiang e-commerce penetration zones where fitness culture outpaces brick-and-mortar retail infrastructure. Live-streaming commerce platform partnerships offer the most penetrable go-to-market angle for tier-two city consumer acquisition without wholesale layer margin erosion.
For Investors and Strategic Acquirers: Long-term, this sits as a clinical nutrition infrastructure play because hospital and elderly care channel underdevelopment creates sustained isolate formulation demand expansion. Acquisition targets should emphasize membrane filtration technology adoption and NMPA certification completion rather than raw scale. The signal to watch is SAMR enforcement pattern intensification around protein adulteration testing, which would accelerate domestic facility preference and compress import-dependent valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Capacity Expansion | Microfiltration and ultrafiltration adoption in Guangdong facilities displaces heat-based legacy concentration methods. |
| NMPA Certification Fast-Track Investment | Nutritional fortification framework alignment filters hospital channel access to specialized isolate formulators. |
| Live-Streaming Commerce Platform Partnership | Direct distribution models bypass wholesale layers in Sichuan and Zhejiang tier-two city penetration. |
| Backward Integration into Coastal Processing Zones | Yangpu and Pudong captive sourcing relationships secure quality feedstock access against raw milk concentration. |
| Clinical Nutrition Channel Development | Hospital and elderly care penetration for controlled digestion profile formulations commands premium positioning. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with sports nutrition brand procurement directors, dairy processing facility managers, NMPA regulatory affairs specialists, and hospital nutrition department purchasing committees. Secondary validation drew from SAMR enforcement bulletins, GB standards documentation, NMPA nutritional fortification framework updates, and coastal customs zone import clearance records. Bottom-up volume triangulation across whey protein, milk protein isolate, casein, and concentrate segments was cross-checked against top-down market sizing from processor capacity disclosures.
Across the analysis window, forecast outputs were generated through segmentation modeling across protein purity tiers, extraction technology generations, application channels, and end-user sophistication levels. CAGRs were derived from demand elasticity coefficients calibrated against gym membership density trajectories and e-commerce penetration rates. Hospital procurement cycle analysis and clinical nutrition reimbursement pathway evolution provided industry-specific forecast anchors.
Decision-makers should treat outputs as directional under sustained NMPA framework stability and dual carbon goal enforcement continuity; material deviation in SAMR adulteration testing protocols or membrane equipment import restrictions would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Sour Milk Drinks Market
Dairy Products
Lactose Market
Dairy Products
Organic Cheese Market
Dairy Products
UAE Camel Dairy Market
Dairy Products
Parmesan Cheese Market
Dairy Products
Europe Yogurt Market
Dairy Products
Global Cultured Dairy Products Market
Dairy Products
China Dairy Market
Dairy Products
Saudi Arabia Dairy Products Market
Dairy Products
Reduced Fat Cheeses Market
Dairy Products
Cholesterol Reduced Butter Market
Dairy Products
Dry Whole Milk Powder Market
Dairy Products
Fermented Dairy Ingredients Market
Dairy Products
Malted Milk Powder Market
Dairy Products
Global Quark and Fromage Frais Market
Dairy Products
United States Casein and Caseinate Market