
 Plant-Based Food and Beverages Market | 2026-2036
Plant-Based Food and Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Plant-Based Food and Beverages Market Analytics
The EU Green Deal is decoupling European protein consumption from intensive animal agriculture, creating procurement mandates that ripple through retail and foodservice channels. Danone S.A. anchors its position through captive soy and oat sourcing networks spanning France and Belgium. Beyond Meat competes on extrusion technology leadership, while Oatly Group AB navigates capacity constraints by controlling its proprietary enzymatic production process.
Plant-based food and beverages comprise formulated products using proteins, oils, fibers, and flavor systems derived from legumes, cereals, nuts, and oilseeds, processed through extrusion, fermentation, or enzymatic conversion to replicate the sensory and nutritional profiles of animal-derived counterparts. Dairy alternatives lead current retail velocity due to oat and almond milk penetration in conventional grocery, while meat alternatives represent the fastest-growing margin pool as extruded whole-muscle structures achieve price parity with conventional proteins in select channels. The flexitarian end-user segment now exceeds vegetarians and vegans in absolute spend, reshaping how brands calibrate taste and nutrition claims.
The FDA governs allergen labeling and nutrient content claims for plant-based products in the United States, while EFSA evaluates novel protein safety dossiers before EU market authorization, and the USDA oversees organic certification pathways that premium brands exploit for shelf differentiation. The EU F-Gas Regulation indirectly shapes refrigerated supply chains for plant-based dairy, raising compliance costs for conventional cooling systems. Stakeholders must monitor whether European member states tighten protein origin disclosure rules beyond current voluntary frameworks, as this would force reformulation investments across multinational portfolios.
Market Dynamics
Extrusion and enzymatic processing platforms are compressing formulation costs while flexitarian demand volumes force supply chain reconfiguration across cold-chain dairy alternatives and ambient meat substitutes.
Growth Catalysts
- EU Farm to Fork Strategy:Procurement mandates in Germany and France require public foodservice to source plant proteins, creating guaranteed offtake volumes for oat milk and extruded meat analogues.
- Precision fermentation:Whey and casein proteins produced via microbial hosts achieve functional parity with animal dairy, unlocking clean-label applications in barista-grade beverages.
- Flexitarian household penetration:United States and United Kingdom retail data shows repeat purchase rates for plant-based SKUs now exceed trial-to-adoption thresholds in conventional grocery channels.
Market Restraints
- Pulse protein input volatility:Yellow pea and fava bean concentrate prices fluctuate with Canadian and Australian harvest yields, compressing margin visibility for meat analogue formulators.
- EFSA novel food dossier timelines:Cell-cultured and precision-fermented proteins face 18-24 month safety evaluation windows that delay EU commercialization against North American counterparts.
- Refrigerated supply chain concentration:EU F-Gas Regulation compliance costs for hydrofluorocarbon cooling systems disproportionately burden small-scale oat milk processors in Belgium and the Netherlands.
Strategic Opportunities
- Underpenetrated German foodservice:Contract catering and QSR channels in Bavaria and North Rhine-Westphalia show sub-15% plant-based menu penetration versus 35% in Nordic markets.
- Hybrid protein formulations:Blending extruded plant fibers with fermentation-derived fats addresses texture deficits in whole-muscle chicken alternatives for United States foodservice.
- USDA organic certification pathways:Premium shelf positioning in United States natural retail channels commands 40-60% price premiums over conventional plant-based SKUs.
Industry Challenges
- Food technologist talent scarcity:Formulation expertise spanning protein chemistry, sensory science, and scale-up engineering concentrates in Netherlands and California clusters, creating recruitment bottlenecks for European mid-cap entrants.
- Extrusion equipment lead times:High-shear twin-screw systems from specialized German and Italian manufacturers require 12-18 month delivery windows that constrain capacity expansion timelines.
- Allergen cross-contamination protocols:Shared production lines for nut, soy, and oat milks demand validated cleaning procedures that extend changeover downtime in contract manufacturing environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant-Based Food and Beverages Market |
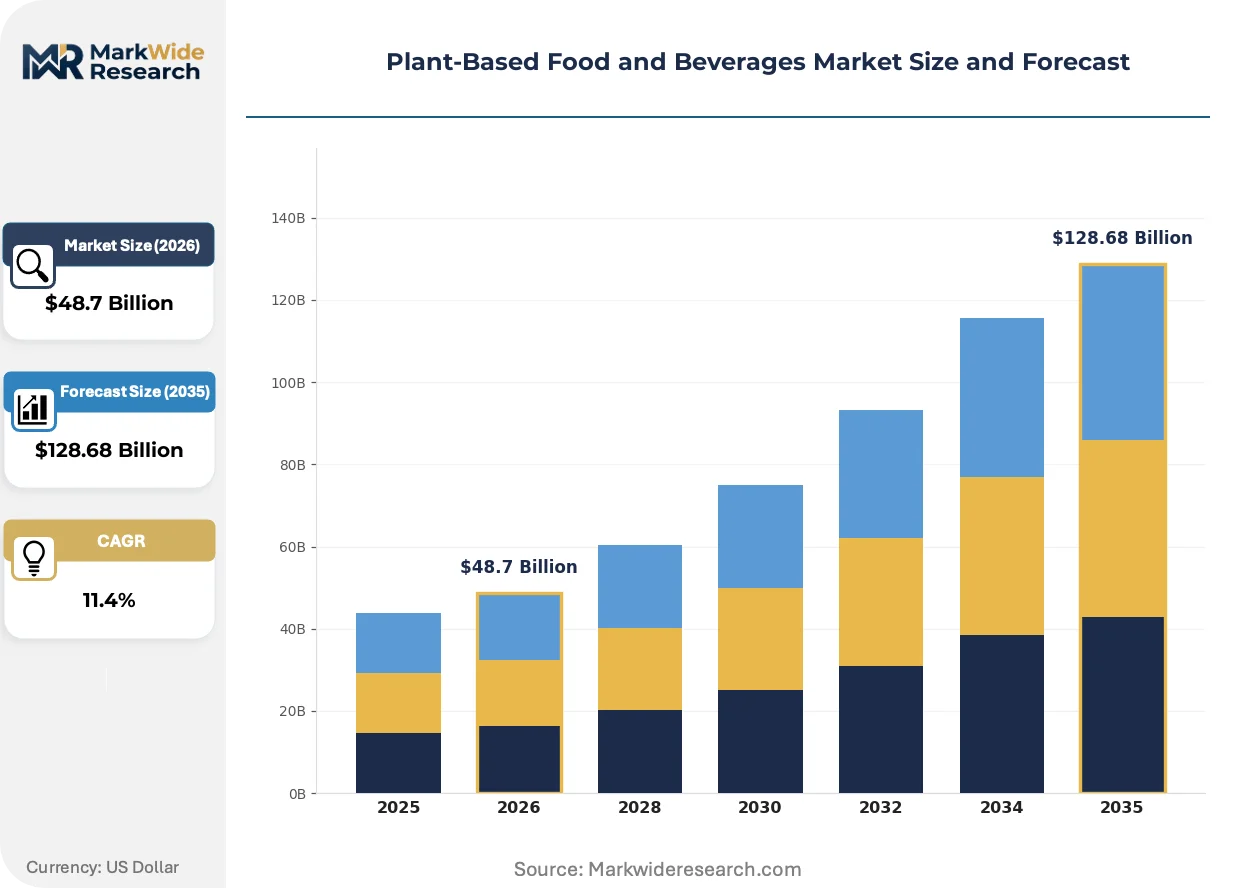
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $128.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Meat Alternatives, Dairy Alternatives, Snacks, Beverages End User: Vegetarians, Vegans, Flexitarians, Health-Conscious Consumers Distribution Channel: Supermarkets, Online Retail, Health Food Stores, Foodservice Packaging Type: Boxed, Bottled, Canned, Pouched |
| Companies Covered | The Hain Celestial Group, Inc., Oatly Group AB, Danone S.A., Impossible Foods, Beyond Meat, Blue Diamond Growers, Inc., SunOpta Inc., Quorn, Califia Farms, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant-Based Food and Beverages Market Evolving Landscape
Processing technology maturation and regulatory disclosure requirements are compressing the gap between pilot-scale innovation and commercial viability across plant-based categories.
High-moisture extrusion is consolidating competitive positioning in meat analogue manufacturing. This thermomechanical process aligns protein fibers into anisotropic structures that replicate whole-muscle chew and bite. United States and German foodservice operators are adopting these formulations for breaded cutlet and ground applications at accelerating pace. The technology is consolidating supplier bases by rewarding capital-intensive equipment operators with proprietary screw and die configurations.
EFSA novel protein safety dossiers are reshaping European launch timelines. The evaluation framework requires comprehensive allergenicity, toxicity, and nutritional equivalence data for fermentation-derived and cell-cultured ingredients. Manufacturers targeting EU market entry must front-load regulatory affairs investment 24-36 months ahead of commercial targets. Dairy alternative brands with existing GRAS or self-affirmed status in the United States face asymmetric compliance burdens when expanding into France, Italy, and Spain.
Direct-to-foodservice distribution is displacing traditional broker networks in plant-based beverage procurement. Large United States and United Kingdom QSR chains now negotiate volume commitments directly with oat milk processors, bypassing regional dairy distributors. This channel compression reduces slotting fee burdens but demands dedicated technical service support for equipment calibration and barista training. The shift is most visible in coastal United States metropolitan markets where independent coffee chains aggregate sufficient volume to justify direct supplier relationships.
Plant-Based Food and Beverages Market Segmentation
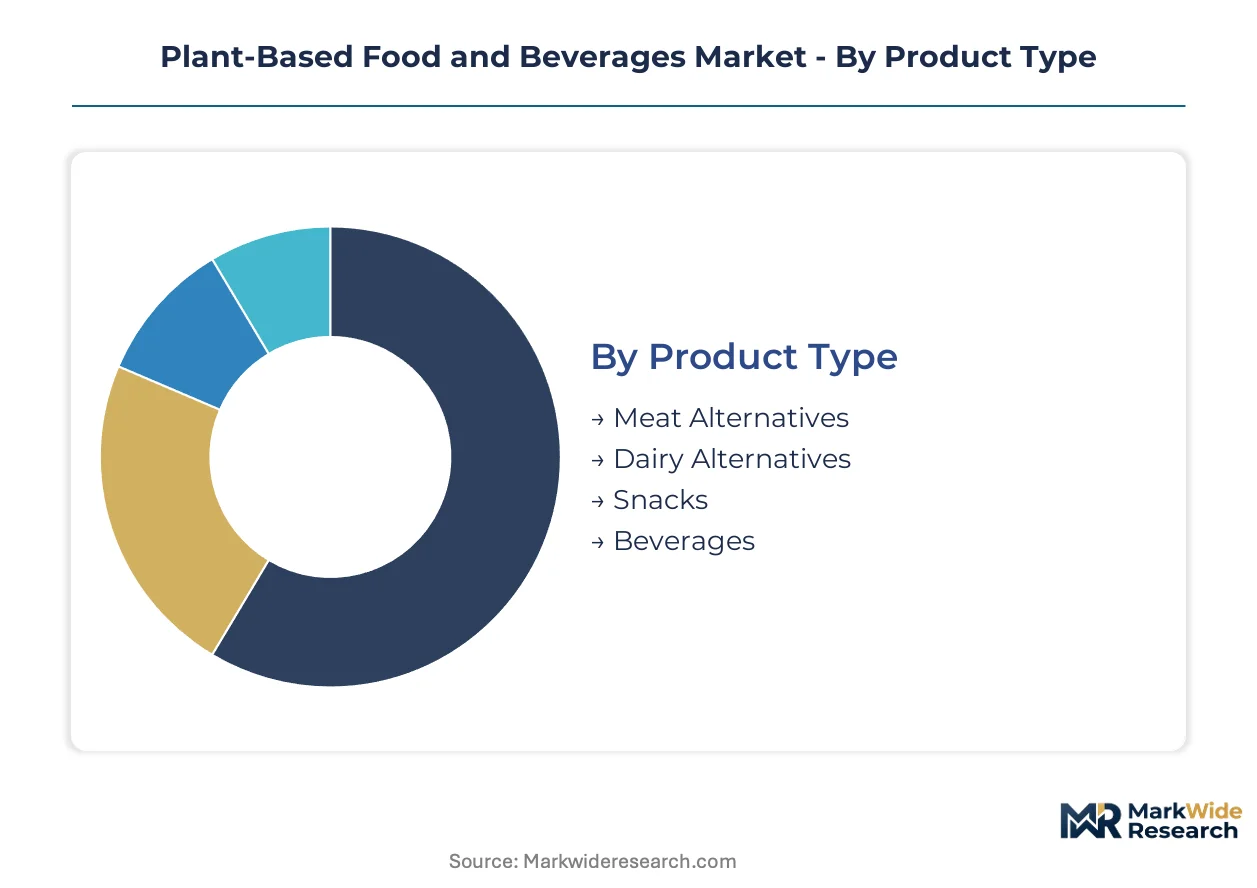
Plant-based food and beverages demand heterogeneous regulatory pathways across product categories. Segmentation reveals which formulations trigger EFSA novel food reviews versus self-affirmed GRAS designations, directly shaping commercialization timelines and capital allocation priorities.
Product Type:
Certification burden varies sharply across this category. Dairy alternatives leveraging established soy and oat proteins face streamlined FDA GRAS pathways, while precision-fermented casein analogues trigger mandatory EFSA dossier submissions regardless of prior US approvals.
- Dairy Alternatives:Oat, almond, and soy milk formulations dominate refrigerated retail velocity in Germany, the United Kingdom, and the United States. Barista-grade oat milk commands premium positioning in United States coastal metropolitan foodservice, though EFSA novel protein evaluations delay precision-fermented whey launches in France and Italy.
- Meat Alternatives:Extruded whole-muscle structures from pea and fava protein concentrates replicate chicken and beef sensory profiles for United States and German QSR breaded cutlet applications. High-moisture extrusion equipment lead times from Italian and German manufacturers constrain capacity scaling for mid-cap entrants.
- Beverages:Functional shots and protein-fortified ready-to-drink formats target gym and convenience channels in the United States and United Kingdom.
- Snacks:Puffed legume crisps and extruded protein puffs occupy impulse purchase locations in conventional grocery.
Dairy alternatives sit at the top of the volume ranking, with meat alternatives climbing the fastest.
End User:
Customer archetypes stratify by purchase frequency, basket composition, and price elasticity, reshaping how brands configure trade spend and loyalty programming.
- Flexitarians:Households reducing but not eliminating animal protein intake now exceed vegetarians and vegans in absolute spend across United States and United Kingdom retail. Repeat purchase rates for plant-based SKUs in conventional grocery channels now sustain permanent shelf space allocations previously reserved for trial periods.
- Health-Conscious Consumers:Buyers prioritizing clean-label ingredient decks and organic certification drive 40-60% price premiums in United States natural retail channels. USDA organic pathways command dedicated freezer and refrigerated placement distinct from conventional plant-based sets.
- Vegans:Strict plant-based adherence creates concentrated demand in specialty health food stores and dedicated online subscription services.
- Vegetarians:Longstanding lacto-ovo dietary patterns show stable but slower growth in absolute spend versus flexitarian conversion.
Flexitarians anchor current volume concentration, with health-conscious consumers expanding most quickly.
Distribution Channel:
Channel selection determines working capital intensity, technical service obligations, and margin capture through direct relationships versus broker-mediated access.
- Supermarkets:Conventional grocery chains in Germany, the United States, and the United Kingdom now dedicate permanent refrigerated sets to oat milk and frozen meat alternatives. Slotting fee structures and promotional calendar alignment dominate supplier negotiations.
- Foodservice:Direct-to-operator procurement bypasses traditional dairy distributors in United States coastal metropolitan markets, demanding dedicated barista training and equipment calibration support.
- Online Retail:Subscription replenishment models capture pantry-stocking occasions for ambient meat substitutes and bulk beverage purchases.
- Health Food Stores:Independent natural retailers in the United States and United Kingdom maintain curated premium assortments with higher organic SKU penetration.
Supermarkets retain volume leadership, with foodservice gaining share fastest.
Packaging Type:
Format selection interfaces with shelf-life requirements, cold-chain infrastructure, and EU F-Gas Regulation compliance costs for refrigerated distribution.
- Bottled:Aseptic and refrigerated PET formats dominate oat milk and ready-to-drink protein beverages in United States and German retail. Extended shelf-life variants reduce spoilage allowances but require higher capital investment in filling line sterilization.
- Pouched:Flexible retort pouches for ambient meat substitutes minimize shipping cube and shelf footprint in United Kingdom and United States online fulfillment centers. Material specifications must reconcile oxygen barrier performance with recycling stream compatibility under evolving extended producer responsibility frameworks.
- Boxed:Aseptic cartons for shelf-stable plant milks optimize pallet density for export shipments to markets with limited cold-chain infrastructure.
- Canned:Metal formats for beans and prepared legume products occupy center-store ambient shelves with minimal refrigeration burden.
Bottled formats command the highest current volume, with pouched alternatives showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Plant-based food and beverage manufacturing originated in European and North American food technology clusters during the 1990s, with early soy milk commercialization in Germany and almond milk scaling in California establishing the template for modern extrusion and enzymatic processing platforms.
United States
Flexitarian household penetration and direct-to-foodservice procurement now exceed traditional retail velocity in coastal metropolitan markets. The FDA governs allergen labeling and nutrient content claims for plant-based products, while the USDA oversees organic certification pathways that premium brands exploit for shelf differentiation. Greater Los Angeles and San Francisco Bay Area clusters concentrate precision fermentation startups and high-moisture extrusion R&D facilities.
Germany
Public foodservice procurement mandates under the EU Farm to Fork Strategy create guaranteed offtake volumes for oat milk and extruded meat analogues in Bavaria and North Rhine-Westphalia. The EU F-Gas Regulation raises compliance costs for hydrofluorocarbon cooling systems in refrigerated supply chains. Cologne and Hamburg host major extrusion equipment manufacturers and contract manufacturing facilities serving Central European markets.
United Kingdom
Repeat purchase rates for plant-based SKUs in conventional grocery channels now sustain permanent shelf space allocations previously reserved for trial periods. EFSA novel food dossier timelines for fermentation-derived proteins delay commercialization against North American counterparts. London and Manchester concentrate food technologist talent spanning protein chemistry, sensory science, and scale-up engineering.
France
EFSA safety evaluations for novel proteins require 18-24 month assessment windows that constrain launch timelines for precision-fermented dairy alternatives. The EU Green Deal decouples protein consumption from intensive animal agriculture through procurement mandates rippling through retail and foodservice channels. Paris and Lyon anchor captive soy and oat sourcing networks spanning northern France and Belgium.
Netherlands
Contract manufacturing environments face allergen cross-contamination protocol demands that extend changeover downtime across shared production lines for nut, soy, and oat milks. EFSA evaluates novel protein safety dossiers before EU market authorization, creating asymmetric compliance burdens for US brands. Amsterdam and Rotterdam concentrate foodservice distribution infrastructure and cold-chain logistics for plant-based dairy alternatives.
Plant-Based Food and Beverages Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification tier and proprietary processing technology ownership. The vendor base stratifies between multinational food conglomerates with captive ingredient sourcing, specialized plant-based pure-plays with extrusion or fermentation technology leadership, and private-label contract manufacturers serving retail channel consolidation. Three archetypes dominate: vertically integrated ingredient-to-brand operators, technology-licensing specialists, and scale-driven private-label suppliers. Competitive moves concentrate on M&A for manufacturing capacity and strategic partnerships for foodservice distribution access.
Within the multinational conglomerate tier, Danone S.A. and Beyond Meat occupy positions as archetype anchors for contrasting strategic approaches. Oatly Group AB exemplifies the technology-pure-play model through proprietary production process control. These three companies represent the spectrum from diversified food manufacturing to specialized plant-based innovation, illustrating how competitive positioning depends on upstream supply control versus downstream brand equity investment.
| Leading Market Players |
|---|
| The Hain Celestial Group, Inc. |
| Oatly Group AB |
| Danone S.A. |
| Impossible Foods |
| Beyond Meat |
| Blue Diamond Growers, Inc. |
| SunOpta Inc. |
| Quorn |
| Califia Farms |
| Others |
Value Network & Pricing Analysis
High-moisture extrusion technology maturation is compressing unit economics for meat analogues while concentrating supplier power among German and Italian equipment manufacturers with proprietary screw configurations. This production-method transition simultaneously lowers formulation costs and tightens upstream control, reshaping how brands negotiate ingredient contracts and allocate capital across oat enzymatic processing versus extruded protein capacity.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates USDA-certified organic SKUs commanding shelf-space premiums from conventional plant-based alternatives and private-label economy tiers. Price differentiation hinges on certification grade and volume scale, with health-conscious consumers in United States natural retail channels showing lowest price sensitivity while German foodservice procurement mandates drive volume discounts. Pricing pressure stems from pulse protein input volatility as Canadian yellow pea harvests fluctuate, compressing margin visibility for mid-tier meat analogue formulators.
Supply Chain Analysis
Reverse-logistics flows for refrigerated oat milk returns and expired SKUs concentrate rework costs in Netherlands and Belgium cold-chain hubs, where EU F-Gas Regulation compliance burdens small-scale processors. Geographic supply concentration centers on Germany for extrusion equipment, Canada for yellow pea protein, and Sweden for proprietary oat processing technology. Raw material dependencies include fava bean concentrates, enzymatically treated oats, and high-oleic sunflower oils. Single-source vulnerability for twin-screw extrusion systems from Italian manufacturers creates bottleneck risk. Distribution runs through direct-to-foodservice procurement in United States coastal metropolitan markets, bypassing traditional dairy broker networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in plant-based food and beverages rests on enzymatic processing cost-down curves and organic certification tier shifts that sustain price premiums in United States natural retail channels.
For Market Incumbents: Cement control over captive ingredient sourcing networks spanning France and Belgium to defend against precision-fermentation entrants achieving functional dairy parity. Add high-moisture extrusion capacity in Germany to lock in equipment allocation before 12-18 month lead times widen. Vertical integration into proprietary oat cultivar development addresses supply volatility from Nordic harvest fluctuations. For New Entrants and Emerging Players: Foodservice contract catering in Bavaria and North Rhine-Westphalia represents an underserved buyer archetype with sub-15% plant-based menu penetration versus Nordic benchmarks. Target hybrid protein formulations blending extruded fibers with fermentation-derived fats for whole-muscle chicken alternatives in United States QSR channels. Pursue direct-to-operator procurement relationships that bypass slotting fee structures dominating conventional grocery. For Investors and Strategic Acquirers: Valuations sit cheapest among contract manufacturing pure-plays with validated allergen segregation protocols and multi-protein line flexibility. Long-term viability over the next decade favors operators controlling proprietary enzymatic or extrusion technology rather than brand-dependent marketing plays. Monitor EFSA novel food dossier approval timelines as inflection indicators for precision-fermented protein commercialization velocity in France and Italy.| Strategic Initiative | Industry Significance |
|---|---|
| High-Moisture Extrusion Capacity Expansion | Proprietary screw configurations from German manufacturers consolidate competitive positioning in whole-muscle analogue production. |
| Direct-to-Foodservice Distribution Buildout | Bypassing dairy broker networks in Los Angeles and San Francisco reduces slotting fees while demanding technical service investment. |
| Precision Fermentation Scale-Up | Microbial-derived whey proteins unlock clean-label barista-grade applications pending EFSA safety dossier approvals. |
| USDA Organic Certification Pathway Investment | Premium shelf positioning in United States natural retail commands sustained price premiums over conventional plant-based sets. |
| Captive Oat Cultivar Development | In-house breeding programs reduce dependency on Nordic harvest volatility and proprietary enzymatic processing inputs. |
Research Methodology
Direct dialogue with plant-based food technologists, foodservice procurement directors, extrusion equipment manufacturers, and retail category buyers grounded qualitative insights in operational reality. Secondary validation drew from FDA GRAS notifications, EFSA novel food dossier submissions, USDA organic certification databases, and Nielsen retail audit data for United States and United Kingdom conventional grocery channels. Bottom-up SKU-level volume modeling triangulated against top-down category spend estimates from foodservice distribution records.
Segmented outputs across product type, end-user archetype, distribution channel, and packaging format fed into analytical frameworks spanning the projection horizon. CAGRs derived from historical velocity trends in Germany, United States, and United Kingdom retail channels, adjusted for EFSA regulatory lag effects and foodservice procurement mandate implementation timelines. Forecast inputs included pulse protein commodity price indices, extrusion equipment order backlogs, and flexitarian household penetration rates from longitudinal purchase panel data.
Underlying measurement precision varies by segment; dairy alternatives with established GRAS status carry tighter precision than precision-fermented proteins pending EFSA evaluation. Forecasts reflect assumptions about regulatory approval timelines, harvest yield stability, and foodservice adoption curves that external shocks could revise. Practitioners should monitor EU member state protein origin disclosure rule developments and F-Gas Regulation enforcement intensity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Vegan Protein Concentrate Market
Plant Based Food
Plant Chocolate Protein Powder Market
Plant Based Food
India Pea Protein Market
Plant Based Food
Vegan Protein Foods Market
Plant Based Food
Plant-Based Protein Food Market
Plant Based Food
North America Rice Protein Market
Plant Based Food
Plant-Based Diet Market
Plant Based Food
Plant-Based Flour Market
Plant Based Food
Veggie Meals Market
Plant Based Food
Soy Protein Market
Plant Based Food
Organic Pea Protein Market
Plant Based Food
Vegan Protein Blend Market
Plant Based Food
Europe Plant-Based Food and Beverage Market
Plant Based Food
India Meat Substitutes Market
Plant Based Food
Vegan Marshmallows Market
Plant Based Food
Meatless Meat Market