
 France Sodium Reduction Ingredients Market | 2026-2036
France Sodium Reduction Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
France Sodium Reduction Ingredients Market Foresight
A capital-intensity divergence between R&D-heavy multinationals and regional specialists is rotating competitive dynamics in France. Cargill Inc. leverages its integrated salt-alternative supply chain to secure bulk contracts with national retailers. Biospringer sustains fermentation-derived yeast extract capacity that dominates flavor-masking applications for potassium chloride. Armor Proteines SAS anchors dairy-protein based sodium replacers in the processed meat segment.
France sodium reduction ingredients comprise mineral salts, plant extracts, and fermentation-derived compounds formulated to replicate sodium chloride's functional properties in food matrices while maintaining microbial stability and protein solubility. Potassium chloride leads ingredient type volumes due to established GRAS status and cost parity with standard salt, though seaweed extracts represent the fastest-growing category as clean-label positioning intensifies among French food processors. Ready-to-eat meals and processed meat applications concentrate margin pools, where sodium reduction directly impacts shelf-life formulation complexity and drives premium pricing for technical ingredient solutions.
ANSES sets enforceable sodium benchmarks through the PNNS framework, while EFSA evaluates novel mineral salt health claims that shape product positioning. France's DGCCRF enforces front-of-pack Nutri-Score labeling that penalizes high-sodium formulations, compelling reformulation investments across the supply chain. Stakeholders must monitor pending EU-wide sodium reduction targets and assess captive R&D partnerships before regulatory deadlines tighten.
Market Dynamics
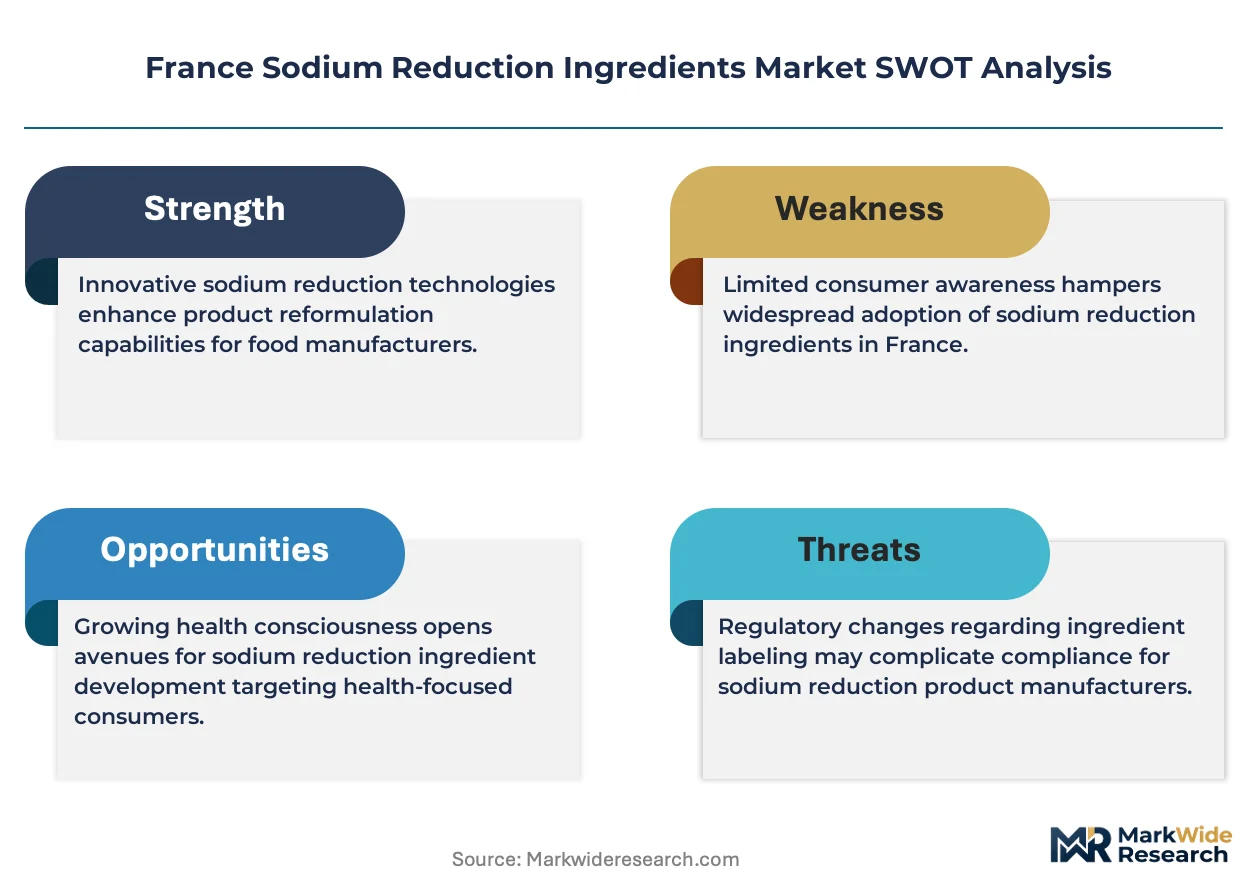
France's sodium reduction ingredients sector is compressing around regulatory enforcement velocity and the technical complexity of reformulating processed foods without compromising shelf stability or sensory profiles.
Growth Catalysts
- PNNS sodium benchmarks:The French National Nutrition and Health Program mandates progressive sodium reduction targets across food categories, forcing manufacturers to source technical salt alternatives.
- Processed meat reformulation:Charcuterie and ready-meal producers in the Lyon-Rhône corridor are accelerating adoption of mineral salt blends to maintain product integrity under reduced-sodium protocols.
- Nutri-Score labeling pressure:DGCCRF enforcement of front-of-pack scoring penalizes high-sodium formulations, creating immediate commercial incentive for ingredient substitution.
Market Restraints
- Potassium chloride supply concentration:Bulk mineral salt production clusters in northeastern France and adjacent Benelux regions create geographic dependency risk for domestic formulators.
- Bitter off-taste technical ceiling:Potassium chloride's metallic aftertaste limits substitution rates in delicate applications like dairy and fine bakery without expensive masking systems.
- EFSA health claim evaluation delays:Pending novel mineral salt approvals slow product positioning and marketing claims for innovative sodium replacers.
Strategic Opportunities
- Seaweed extract clean-label positioning:Brittany's coastal processing infrastructure supports scale-up of marine-derived sodium alternatives for premium organic product lines.
- Ready-to-eat meal segment expansion:Paris-Ile-de-France food service and retail channels present concentrated demand for extended-shelf-life low-sodium formulations.
- Fermentation-derived flavor masking:Yeast extract technology convergence with mineral salts enables higher potassium chloride inclusion rates without sensory compromise.
Industry Challenges
- Food matrix reformulation expertise shortage:France lacks sufficient trained technologists capable of balancing sodium reduction with microbial safety in complex processed meat systems.
- Dual certification timeline compression:Simultaneous ANSES compliance and EU-wide sodium target alignment demands accelerated R&D cycles that strain mid-tier ingredient suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Sodium Reduction Ingredients Market |
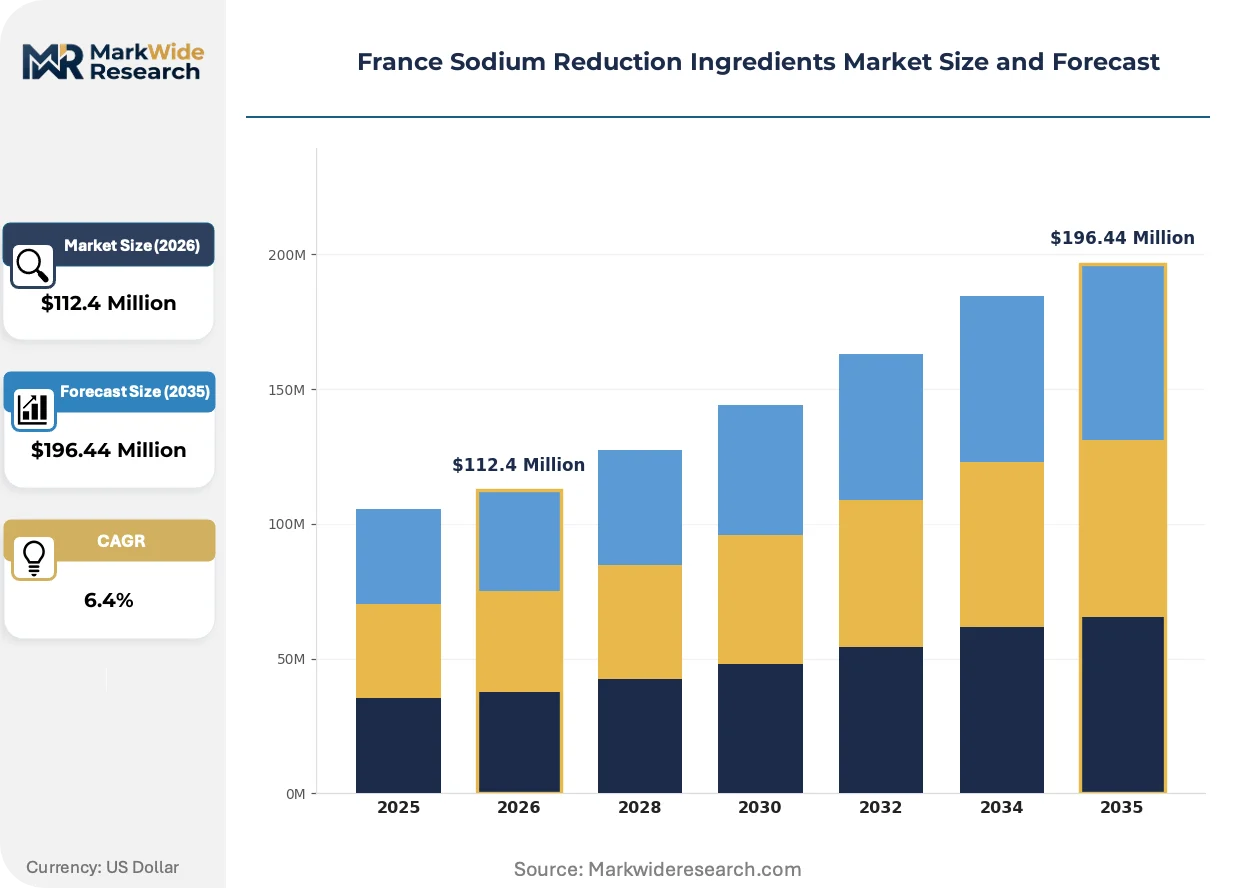
| Market Size in 2026 | $112.4 Million |
| Market Size in 2035 | $196.44 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ingredient Type: Potassium Chloride, Calcium Chloride, Magnesium Sulfate, Seaweed Extracts, Flavor Enhancers Application: Processed Meat, Bakery Products, Dairy Alternatives, Ready-to-Eat Meals, Snacks Customer Type: Food Processors, Ingredient Suppliers, Foodservice Providers, Nutraceutical Companies, Private Label Brands Packaging Type: Bulk Bags, Retail Packs, Sachets, Liquid Containers, Aerosol Cans |
| Companies Covered | Armor Proteines SAS, Biospringer, Cargill Inc., Tate & Lyle PLC, BASF, Givaudan SA, Kudos Blends, Sensient Technologies Corporation, DSM NV, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Sodium Reduction Ingredients Market Shifts & Advancements
Ingredient functionality is fragmenting into specialized solutions as clean-label imperatives collide with technical performance requirements in French food processing.
Seaweed-derived mineral complexes are decomposing the traditional potassium chloride monopoly in premium applications. Brittany-based processors are extracting bioavailable sodium alternatives from Laminaria and Palmaria species for organic meat and dairy lines. This marine sourcing is decomposing cost structures in the clean-label segment by enabling price premiums that offset extraction complexity.
ANSES is tightening enforceable sodium benchmarks through successive PNNS framework iterations. The regulator's 2024-2026 target acceleration compresses reformulation timelines for national retail chains. Processed meat manufacturers in the Grand Est region are responding by pre-qualifying multiple mineral salt suppliers to ensure continuity.
Ingredient procurement is consolidating around technical partnership models rather than transactional purchasing. Large French retailers now mandate collaborative R&D commitments from sodium reduction suppliers before awarding multi-year contracts. This specification-driven selection is most visible in the Paris-Ile-de-France retail cluster, where Carrefour and Casino Group buyers prioritize reformulation support capabilities over unit pricing.
France Sodium Reduction Ingredients Market Segmentation
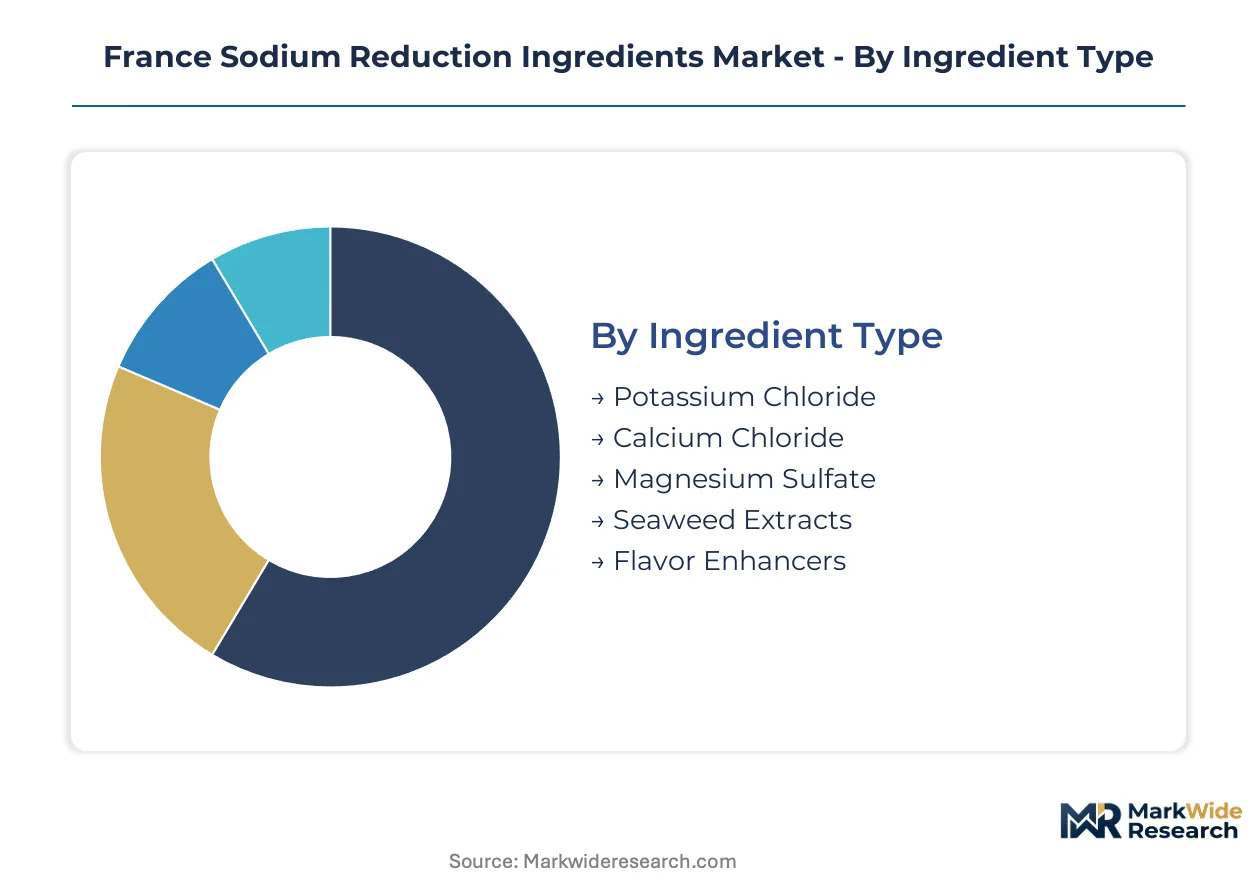
Segmentation in the France sodium reduction ingredients market reveals how technical performance requirements and regulatory pressure channel demand toward specific formulation solutions. Understanding these divisions exposes where margin pools concentrate and which customer relationships command strategic priority.
Ingredient Type:
Channel flows diverge sharply by ingredient type, with bulk mineral salts dominating industrial procurement while specialty extracts penetrate premium retail formulations.
- Potassium Chloride:Crystalline mineral salt with established GRAS status replicates sodium chloride's water-binding and preservative functions. Demand concentrates in Lyon-based processed meat operations where ANSES-mandated reduction targets force high-volume substitution. The metallic aftertaste limits inclusion rates without masking systems.
- Seaweed Extracts:Marine-derived mineral complexes from Laminaria and Palmaria species provide bioavailable sodium alternatives with clean-label positioning. Brittany coastal processors supply Paris-Ile-de-France organic meat and dairy lines where Nutri-Score premiums justify extraction costs. This segment is gaining share fastest among French formulators.
- Calcium Chloride:Hygroscopic salt alternative with firming properties serves dairy alternative applications in northwestern France.
- Magnesium Sulfate:Bitter salt compound finds niche use in mineral-fortified snack seasoning blends.
- Flavor Enhancers:Yeast extract and nucleotide-based masking systems enable higher potassium chloride inclusion in delicate applications.
Potassium chloride dominates installed base. Seaweed extracts are where expansion concentrates.
Application:
Application segmentation tracks margin stratification, with shelf-life-critical categories commanding technical premiums over commodity replacement scenarios.
- Processed Meat:Charcuterie and cured meat formulations require sodium reduction without compromising microbial safety or protein solubility. Grand Est manufacturers pre-qualify multiple mineral salt suppliers to ensure continuity under compressed PNNS timelines. Reformulation complexity sustains ingredient premiums.
- Ready-to-Eat Meals:Extended-shelf-life formulations in Paris-Ile-de-France food service channels demand integrated sodium replacement and flavor masking. Carrefour and Casino Group procurement mandates collaborative R&D commitments from suppliers. This application shows steepest expansion trajectory.
- Bakery Products:Sodium reduction challenges yeast activation and gluten development in traditional French bread systems.
- Dairy Alternatives:Plant-based milk and cheese analogs require mineral salt blends to compensate for protein matrix deficiencies.
- Snacks:Seasoning applications prioritize cost parity over technical performance in high-volume retail channels.
Processed meat anchors current revenue. Ready-to-eat meals concentrate growth investment.
Customer Type:
Customer segmentation reflects procurement sophistication tiers, from specification-driven multinationals to price-sensitive private label operators.
- Food Processors:National meat and dairy manufacturers with captive R&D capabilities integrate sodium reduction into core formulation pipelines. These buyers negotiate multi-year technical partnerships rather than transactional supply agreements. Volume concentration in Lyon-Rhône and Grand Est corridors shapes supplier location strategy.
- Private Label Brands:Retail-controlled product lines in Paris-Ile-de-France prioritize Nutri-Score optimization for shelf positioning. Specification-driven selection favors suppliers with demonstrated reformulation support capabilities. This customer tier is expanding most quickly.
- Ingredient Suppliers:Mid-tier formulators blend mineral salts and masking systems for downstream redistribution.
- Foodservice Providers:Contract catering and restaurant chains seek cost-neutral sodium reduction for menu labeling compliance.
- Nutraceutical Companies:Health-positioned products utilize sodium reduction as a marketing claim differentiator.
Food processors dominate technical specification authority. Private label brands concentrate emerging demand.
Packaging Type:
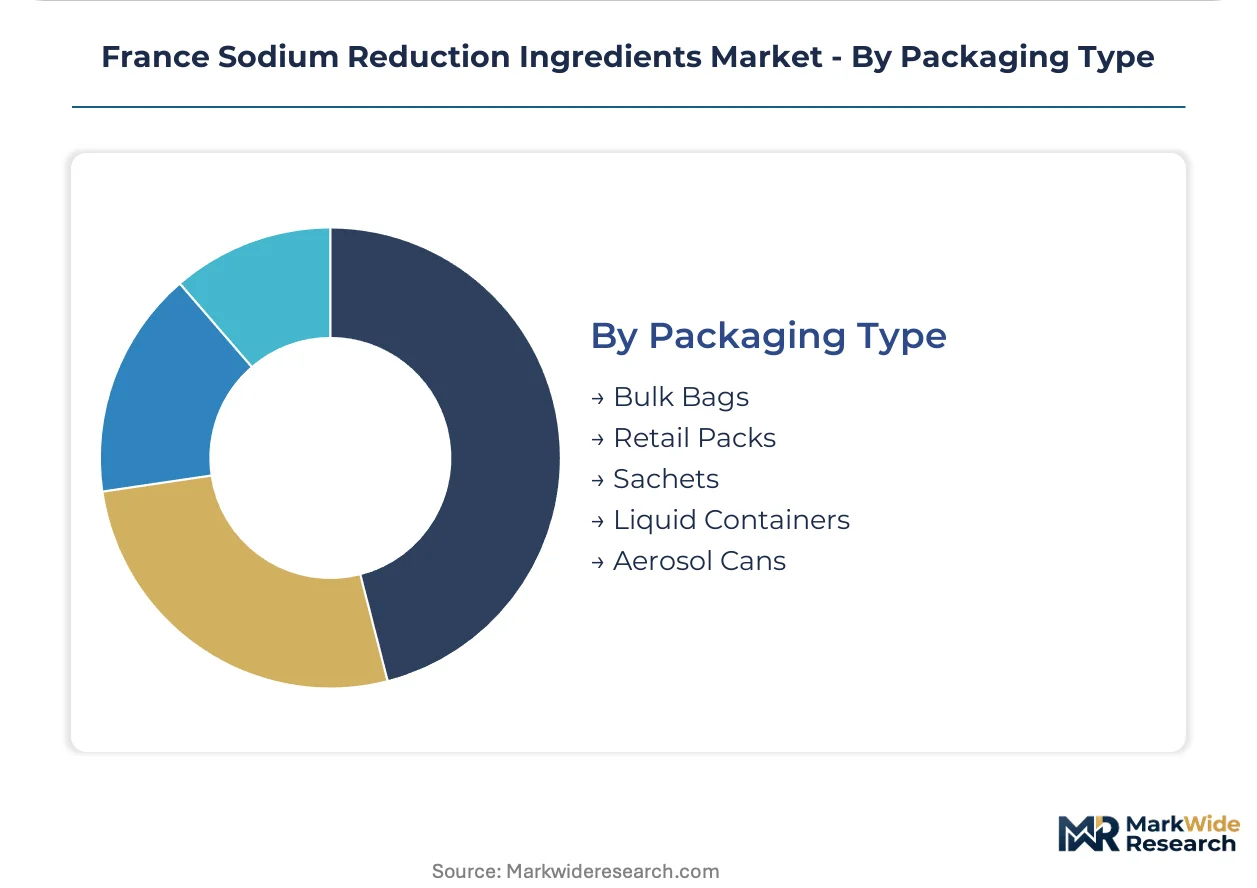
Packaging segmentation tracks supply chain configuration, with bulk industrial formats separating from retail-ready units on handling infrastructure requirements.
- Bulk Bags:Multi-ton flexible containers serve high-volume mineral salt shipments to Grand Est and Lyon-Rhône processing clusters. Rail and barge logistics integration reduces landed cost for potassium chloride concentrates.
- Retail Packs:Consumer-facing sodium alternative products for home cooking applications concentrate in Paris-Ile-de-France hypermarket channels.
- Sachets:Single-serve portions support foodservice portion control and sampling programs.
- Liquid Containers:Brine and suspension formats enable precise dosing in automated production lines.
- Aerosol Cans:Pressurized dispensing systems serve specialty finishing salt applications in premium gastronomy.
Bulk bags dominate industrial throughput. Retail packs concentrate consumer market development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across French sub-regions, with Paris-Ile-de-France buyers absorbing technical premiums for reformulation support while Grand Est processors prioritize mineral salt cost parity.
Île-de-France
Carrefour and Casino Group procurement mandates collaborative R&D commitments from sodium reduction suppliers. ANSES enforces PNNS sodium benchmarks through accelerated 2024-2026 targets. Paris-based food service channels concentrate demand for extended-shelf-life low-sodium ready-to-eat meal formulations.
Auvergne-Rhône-Alpes
Lyon-Rhône charcuterie manufacturers accelerate adoption of mineral salt blends to maintain protein solubility under reduced-sodium protocols. DGCCRF Nutri-Score labeling enforcement penalizes high-sodium formulations in retail channels. The corridor's processed meat operations pre-qualify multiple suppliers to ensure continuity under compressed reformulation timelines.
Brittany
Coastal processors extract bioavailable sodium alternatives from Laminaria and Palmaria seaweed species for organic meat and dairy lines. EFSA evaluates novel mineral salt health claims that shape clean-label product positioning. Brest and Saint-Malo processing infrastructure supports scale-up of marine-derived sodium alternatives commanding price premiums.
Grand Est
Strasbourg and Reims meat processors face acute potassium chloride supply concentration risk from northeastern France and adjacent Benelux production clusters. PNNS framework iterations tighten enforceable sodium benchmarks across charcuterie categories. Regional manufacturers balance cost parity pressures with microbial safety requirements in cured meat reformulation.
Occitanie
Toulouse-based dairy alternative producers utilize mineral salt blends to compensate for protein matrix deficiencies in plant-based cheese analogs. ANSES nutritional guidelines mandate progressive sodium reduction targets across food categories. The region's ingredient suppliers integrate fermentation-derived masking systems to enable higher potassium chloride inclusion rates.
France Sodium Reduction Ingredients Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes in France's sodium reduction ingredients sector. The market compresses around R&D-heavy multinationals with integrated supply chains and regional specialists with fermentation-derived capabilities. Three archetypes dominate: bulk mineral salt suppliers with rail-logistics integration, marine extract processors leveraging Brittany coastal infrastructure, and flavor-masking technology providers. Competitive moves concentrate on strategic partnerships with national retailers and capacity expansion in yeast extract fermentation.
Within the integrated supply chain tier, Cargill Inc. anchors bulk mineral salt procurement relationships with national retailers. Biospringer occupies a position exemplifying fermentation-derived yeast extract specialization for flavor-masking applications. Armor Proteines SAS represents the regional specialist archetype anchoring dairy-protein based sodium replacer formulation for processed meat segments.
| Leading Market Players |
|---|
| Armor Proteines SAS |
| Biospringer |
| Cargill Inc. |
| Tate & Lyle PLC |
| BASF |
| Givaudan SA |
| Kudos Blends |
| Sensient Technologies Corporation |
| DSM NV |
| Others |
Supply & Pricing Matrix
ANSES certification requirements for novel sodium replacers simultaneously gate supplier qualification and stratify price tiers across French procurement channels. Buyers face dual hurdles: technical validation for PNNS compliance and premium positioning for Nutri-Score optimization, compressing vendor pools while amplifying price spreads between validated and non-validated mineral salt sources.
Pricing Analysis
After-sales reformulation support contracts now drive lifetime value more than bulk mineral salt unit pricing. Three-tier pricing structure across premium, standard, and economy levels reflects certification status, with EFSA-evaluated novel salts commanding technical premiums. Cost compression in standard potassium chloride runs through Benelux supply concentration and rail logistics integration. Private label brands at Carrefour and Casino Group exhibit highest price sensitivity, while national charcuterie processors absorb premiums for shelf-life stability guarantees.
Supply Chain Analysis
Strategic stockpiling of potassium chloride concentrates dominates inventory strategy among Grand Est processors facing northeastern France and adjacent Benelux supply concentration. Raw material dependencies center on potash mining operations in Germany, Belarus, and Canada, with seaweed extract supply drawing from Brittany coastal harvesting and Norwegian kelp farming. Single-source vulnerability permeates yeast extract fermentation capacity, where Biospringer anchors French flavor-masking supply. Distribution runs through Paris-Ile-de-France consolidation hubs serving retail channel demand, with Lyon-Rhône processors receiving direct rail shipments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power has shifted toward consolidated national retail chains, with Carrefour and Casino Group procurement mandates forcing collaborative R&D commitments that fragment supplier margins across technical service obligations.
For Market Incumbents: Consolidate captive fermentation capacity in yeast extract flavor-masking to defend against emerging marine extract specialists. Deepen backward integration into Brittany seaweed harvesting infrastructure before coastal processing permits tighten. Priority lever: pre-qualify multiple mineral salt suppliers under compressed PNNS timelines to ensure continuity. For New Entrants and Emerging Players: Technical reformulation support gaps in mid-tier private label supply create immediate white-space opportunity. Target Occitanie dairy alternative producers seeking mineral-fortified protein matrix solutions underserved by incumbent mineral salt suppliers. Go-to-market angle: position fermentation-derived masking systems as enabling higher potassium chloride inclusion without sensory compromise. For Investors and Strategic Acquirers: Pending EFSA novel mineral salt approvals reshape the acquisition landscape toward clean-label positioning capabilities. Five-to-ten year viability favors marine extract processors with Brittany coastal access and organic certification pathways. Signal to watch: ANSES acceleration of PNNS sodium benchmarks beyond current enforcement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seaweed Harvesting | Brittany coastal permits and organic certification secure clean-label supply for premium charcuterie lines. |
| Fermentation Capacity Expansion | Yeast extract flavor-masking enables higher potassium chloride rates in delicate dairy applications. |
| Technical Partnership with National Retailers | Carrefour and Casino Group mandates reformulation support capabilities over unit pricing. |
| Novel Mineral Salt Regulatory Submission | EFSA health claim evaluations unlock premium positioning for innovative sodium replacers. |
| Multi-Supplier Pre-Qualification Program | Grand Est processors ensure continuity under compressed ANSES sodium reduction timelines. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across formulation technologists at Lyon-Rhône charcuterie manufacturers, procurement directors at Paris-Ile-de-France retail chains, regulatory affairs specialists navigating ANSES submissions, and Brittany coastal seaweed processors. Secondary validation drew from ANSES technical guidance documents, EFSA novel food opinions, DGCCRF enforcement bulletins, and PNNS framework iterations. Bottom-up volume modeling triangulated against top-down ingredient consumption estimates.
Across the analysis window, projections incorporate ingredient type segmentation by mineral salt, marine extract, and fermentation-derived compound categories; application segmentation spanning processed meat, ready-to-eat meals, and dairy alternatives; and customer type tiers from national processors to private label brands. CAGRs were derived from regression analysis of historical adoption curves against regulatory enforcement velocity. Forecast inputs include PNNS target acceleration schedules and Nutri-Score labeling diffusion rates.
Forecasts assume regulatory continuity in ANSES sodium benchmark regimes and EFSA novel salt evaluation timelines; material policy shifts would require re-modeling. Specific risks include potassium chloride supply disruption from Benelux logistics chokepoints and delayed clean-label certification for Brittany marine extracts. Revision becomes warranted when PNNS enforcement velocity crosses thresholds beyond current ANSES guidance.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Baking Ingredients Market
Ingredients
Vitamin D Ingredients Market
Ingredients
Horehound Extract Market
Ingredients
Europe Dairy Ingredients Market
Ingredients
Dry Brewing Ingredients Market
Ingredients
Cocoa Maker Market
Ingredients
Freeze-Dried Vegetable Powder Market
Ingredients
Casein Market
Ingredients
Cocoa Solids Market
Ingredients
Global Arabinoxylan Fiber Market
Ingredients
North America Rice Protein Ingredients Market
Ingredients
Red Orange Anthocyanin Extract Ingredients Market
Ingredients
Citrus Based Dietary Fibers Market
Ingredients
Cold-Pressed Citrus Seed Oil Ingredients Market
Ingredients
Specialty Yeast Market
Ingredients
North America Potato Protein Market