
 Plant-Based Vegan Eggs Market | 2026-2036
Plant-Based Vegan Eggs Market Size, Share, and Industry Trends Forecast 2026-2036
Plant-Based Vegan Eggs Market Insights
North American mung bean processors is decoupling from traditional soy-dependent supply chains as regional ingredient infrastructure matures. Eat Just leverages its proprietary protein extraction technology to sustain manufacturing scale in liquid egg substitutes. Follow Your Heart anchors the scramble mix segment through decades of brand strength in natural retail channels. Bob's Red Mill Natural Foods competes on heritage positioning and direct-to-consumer distribution control.
Plant-based vegan eggs are formulated emulsions or dried blends of legume, cereal, or algal proteins designed to replicate the functional properties—coagulation, foaming, and emulsification—of conventional chicken eggs in cooking and baking applications. Liquid egg substitutes lead current volume due to their direct usability in commercial kitchens, while egg powder represents the fastest-growing format driven by extended shelf stability and reduced cold-chain dependency. Pea protein dominates ingredient sourcing for its neutral flavor and allergen-friendly profile, though mung bean protein differentiates on functional performance in scramble applications.
The FDA oversees labeling integrity for plant-based egg products in the United States, while the USDA regulates certain processing and packaging standards applicable to interstate commerce. EFSA and national regulators across Europe enforce novel food authorization pathways that constrain speed-to-market for emerging protein sources. Stakeholders must monitor how evolving clean-label standards and carbon accounting requirements reshape ingredient sourcing decisions and regional market access conditions.
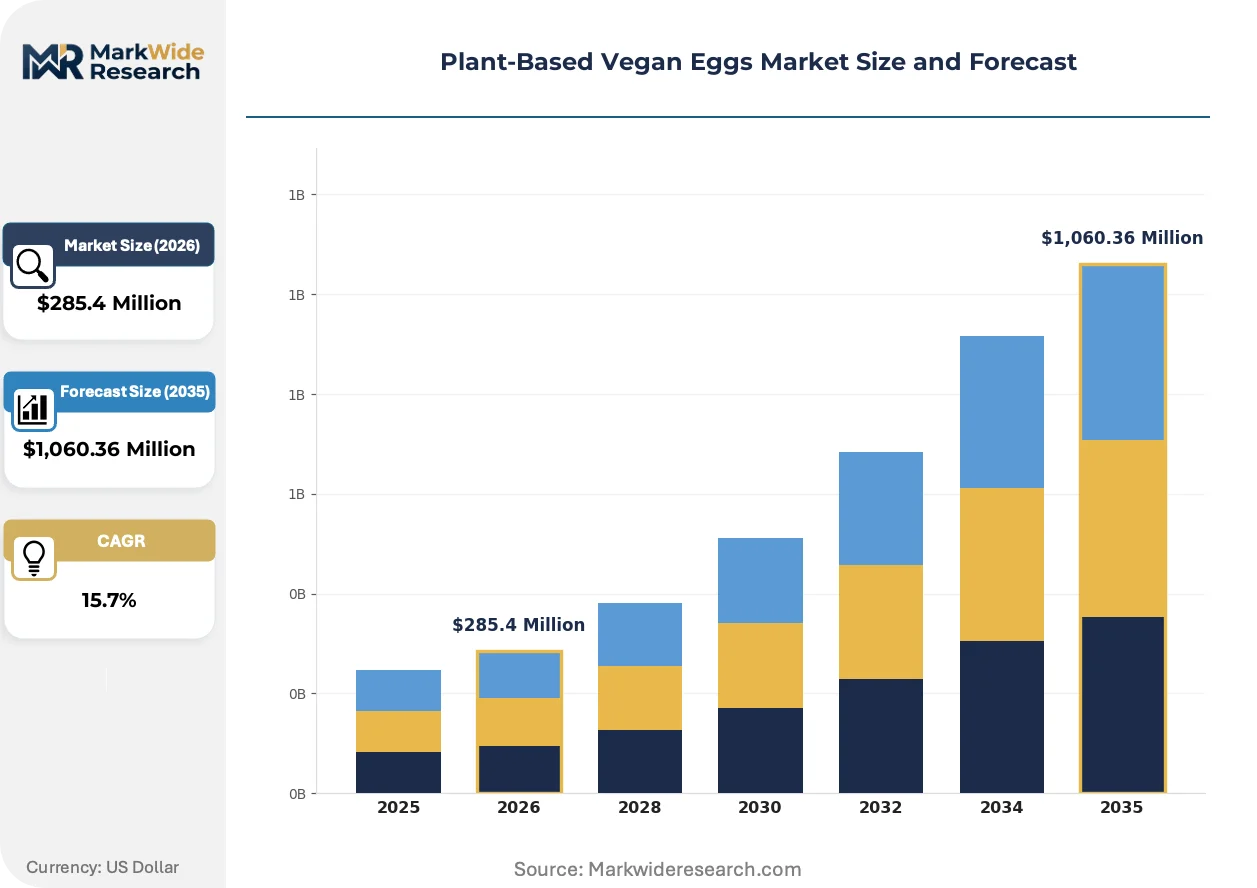
Market Dynamics
Protein extraction technology maturation is collapsing cost curves for mung bean and pea isolates, enabling commercial kitchens to substitute conventional eggs at functional parity without reformulating recipes. This technical inflection is redrawing competitive boundaries between liquid emulsion and dried powder formats.
Growth Catalysts
- Clean-label mandates:EFSA novel food authorization pathways are accelerating ingredient safety validation across European markets, compressing time-to-shelf for emerging protein sources.
- Foodservice penetration:Quick-service restaurant chains are integrating liquid egg substitutes into breakfast menus, driven by operational consistency and extended refrigerated shelf life.
- Carbon accounting frameworks:Corporate Scope 3 reporting requirements under CSRD are forcing food manufacturers to document ingredient-level emissions, favoring plant-derived inputs over conventional eggs.
Market Restraints
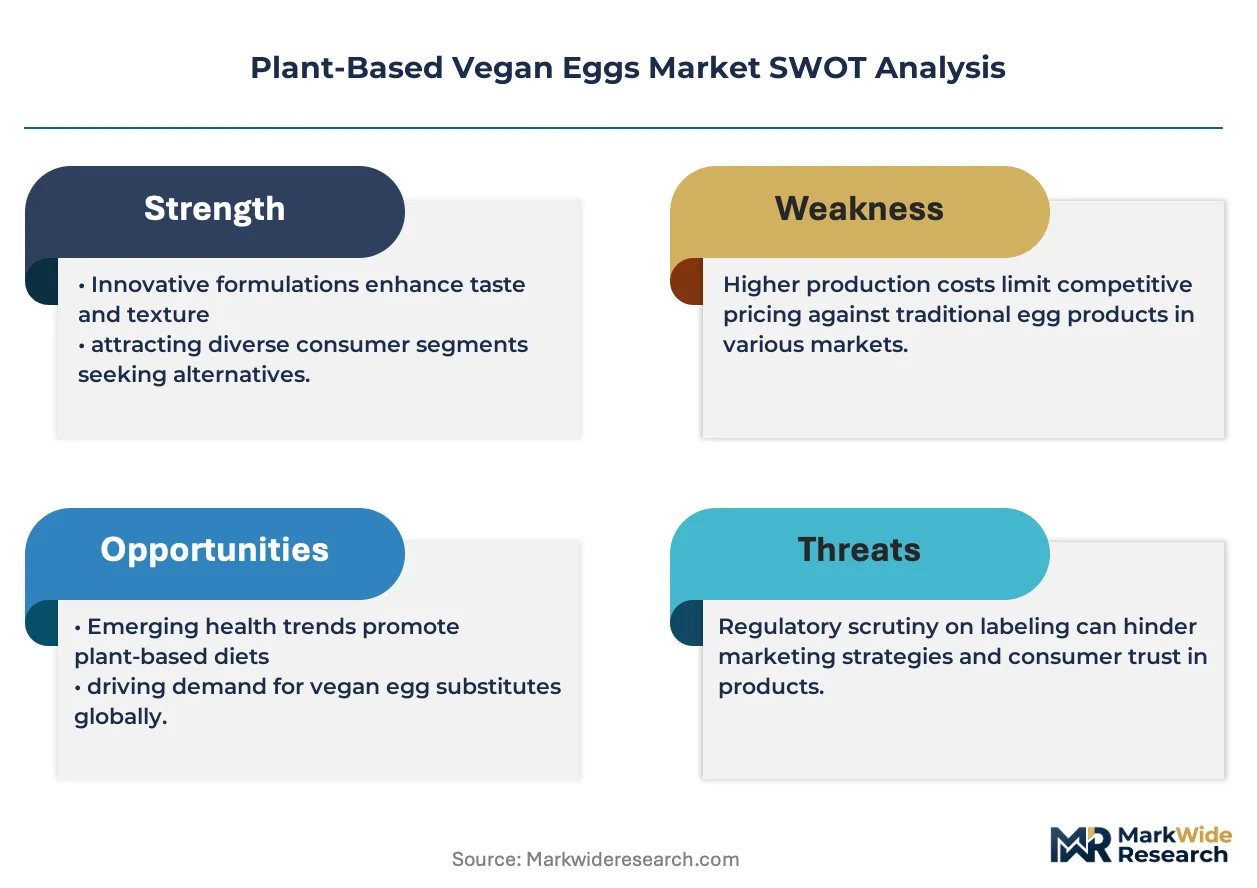
- Input cost volatility:Yellow pea protein concentrate prices fluctuate with Canadian prairie harvest yields, exposing margins to weather-driven supply shocks.
- Functional performance gaps:Algal protein isolates struggle to replicate egg white foaming stability in angel food cake applications, limiting bakery segment penetration.
- Regulatory friction:FDA labeling standards for plant-based egg terminology remain unsettled, creating compliance uncertainty for packaging claims across interstate commerce.
Strategic Opportunities
- Emerging geography:German retail channels show underpenetrated shelf space for powdered scramble mixes, presenting first-mover positioning for brands with extended ambient stability.
- Technology convergence:Precision fermentation-derived proteins combined with traditional legume extrusion are enabling texture profiles previously unattainable in vegan omelet applications.
- Channel innovation:Direct-to-foodservice distribution bypassing traditional broadline distributors is capturing margin previously allocated to intermediary logistics layers.
Industry Challenges
- Formulation expertise scarcity:Food scientists with cross-training in protein chemistry and sensory evaluation command premium compensation, constraining R&D expansion timelines.
- Certification complexity:Dual organic and non-GMO verification processes require parallel audit streams, extending product launch cycles by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant-Based Vegan Eggs Market |
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $1,060.36 Million |
| CAGR (2026 – 2036) | 15.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Scramble Mix, Liquid Egg Substitute, Egg Powder, Ready-to-Eat Ingredient Source: Legume-Based, Wheat Protein, Pea Protein, Other Plants Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Food Service End User: Households, Restaurants, Cafes, Meal Kits |
| Companies Covered | EVO Foods, Orgran Foods, Eat Just, Lovely Day Foods, Perfeggt, Follow Your Heart, Bob’s Red Mill Natural Foods, Puris Holdings, Vegg, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant-Based Vegan Eggs Market Trends and Innovations
Ingredient sourcing decisions are decoupling from commodity agriculture toward controlled-environment production, while regulatory frameworks on both sides of the Atlantic harden disclosure requirements for novel proteins.
High-pressure processing of mung bean protein isolates is electrifying scramble texture replication, achieving curd coagulation kinetics matching conventional eggs. Foodservice operators in United States commercial kitchens are adopting these liquid formats at accelerating pace for breakfast burrito and patty applications. The technology is electrifying competitive dynamics between established powder mixes and emerging refrigerated emulsions, compressing the addressable market for legacy dry blends.
EFSA novel food authorization requirements are mandating extended safety dossiers for emerging protein sources, extending time-to-market by eighteen to thirty-six months for non-legume entrants. European manufacturers are responding by prioritizing mung bean and pea proteins with established regulatory histories over experimental algal or fungal inputs. The policy friction is concentrating innovation investment in proven ingredient platforms rather than speculative protein discovery.
Buyer concentration among national foodservice distributors is consolidating procurement leverage, squeezing ingredient suppliers into multi-year volume commitments with price escalation caps. Smaller regional operators are responding by forming purchasing cooperatives to match distributor negotiating power. The pattern is most visible in United States institutional feeding contracts, where healthcare and education sectors are consolidating supplier panels to three approved vendors per protein category.
Plant-Based Vegan Eggs Market Segmentation
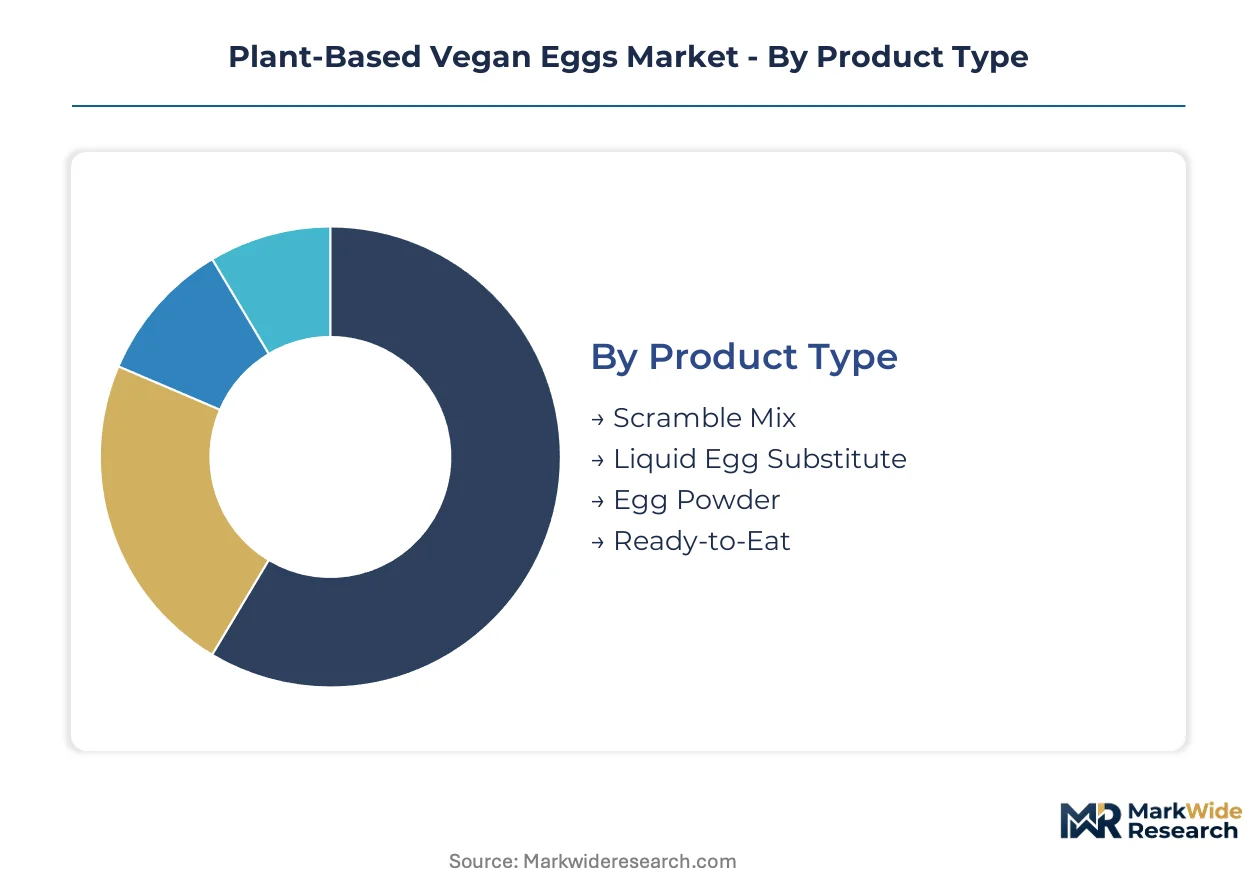
Segmentation in plant-based vegan eggs reveals how functional requirements diverge across preparation contexts. Product formats, protein sources, and channel strategies each command distinct supply chain configurations and margin structures.
Product Type:
Manufacturing scale concentrates in liquid formats where high-pressure processing infrastructure achieves scramble texture parity with conventional eggs.
- Liquid Egg Substitute:Refrigerated emulsions of mung bean or pea protein isolates replicate coagulation kinetics for commercial breakfast applications. United States foodservice operators are standardizing these formats for operational consistency in high-volume kitchens.
- Egg Powder:Spray-dried or freeze-dried protein concentrates eliminate cold-chain dependency and extend ambient shelf stability. German retail channels show accelerating penetration for powdered scramble mixes targeting home bakers.
- Scramble Mix:Dried blends requiring reconstitution dominate natural retail heritage positioning.
- Ready-to-Eat:Pre-cooked refrigerated patties and burrito fillings serve convenience-oriented channels.
Today's leader: Liquid Egg Substitute. Tomorrow's challenger: Egg Powder.
Ingredient Source:
Cost tier differentiation separates premium mung bean isolates from commodity pea protein concentrates in formulation economics.
- Pea Protein:Yellow pea concentrates from Canadian prairie harvests deliver neutral flavor and allergen-friendly labeling. Price volatility exposes margins to weather-driven supply shocks.
- Legume-Based:Mung bean protein extraction achieves superior curd formation in scramble applications through proprietary high-pressure processing. United States manufacturers are decoupling from soy-dependent supply chains as regional mung bean infrastructure matures.
- Wheat Protein:Gluten-containing isolates serve European bakery segments with established regional supply.
- Other Plants:Algal and fungal proteins face EFSA novel food authorization delays.
Pea Protein commands current volume. Legume-Based formats are climbing the fastest on functional performance premiums.
Distribution Channel:
Volume concentration in foodservice is compressing retail margin structures and forcing direct-to-operator distribution models.
- Food Service:Direct procurement by quick-service chains and institutional feeders bypasses traditional broadline distributors. United States healthcare and education sectors are consolidating supplier panels to three approved vendors per protein category.
- Supermarkets:Conventional grocery shelf space for egg alternatives is widening in United States markets.
- Online Retail:Direct-to-consumer subscription models capture repeat purchase loyalty.
- Health Food Stores:Natural channel placement rewards heritage brand positioning.
Food Service anchors procurement leverage. Online Retail represents the steepest expansion trajectory on subscription retention economics.
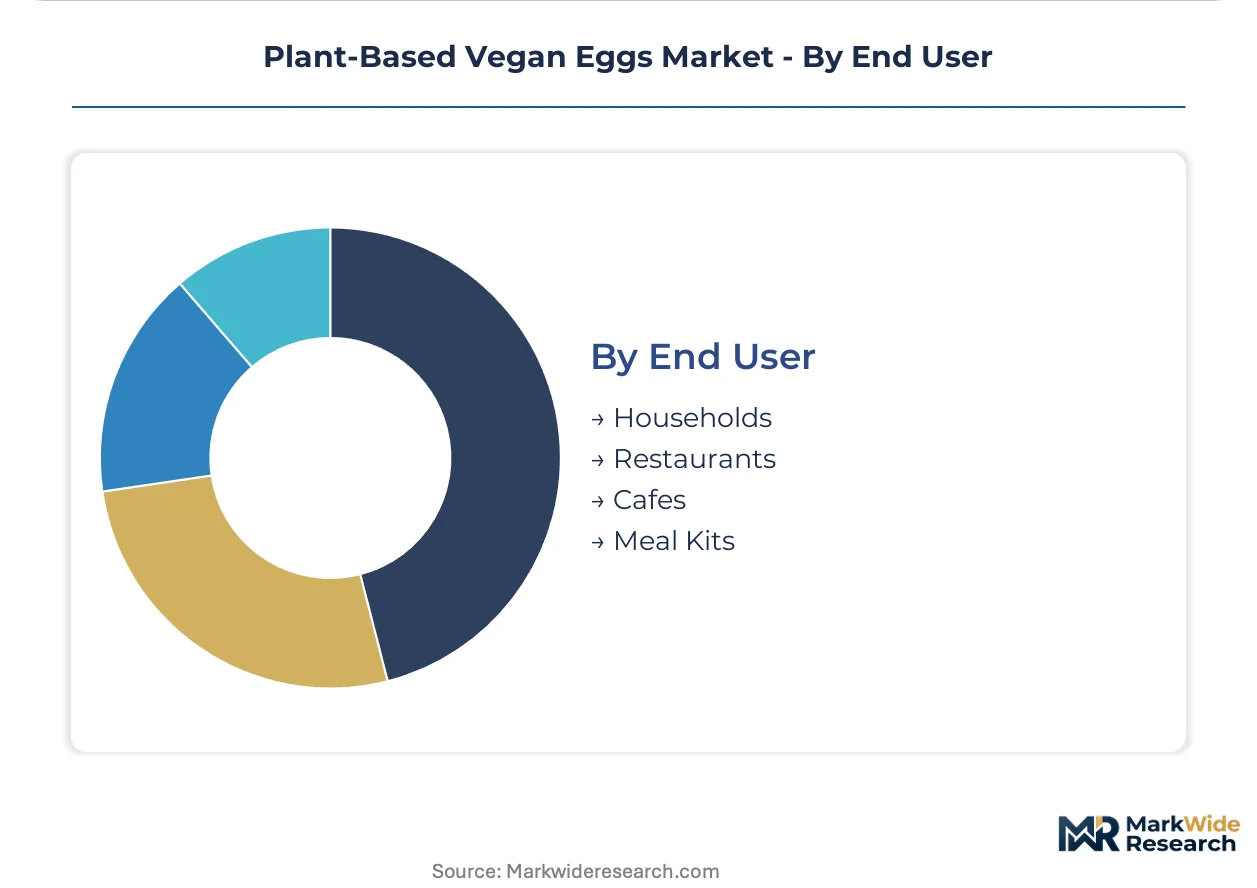
End User:
Application maturity separates commercial kitchen standardization from household experimentation in adoption patterns.
- Restaurants:Breakfast menu integration drives liquid format standardization for operational consistency.
- Households:Home cooking applications concentrate demand for powder and scramble mix formats.
- Cafes:Specialty coffee shops favor ready-to-eat formats for speed of service.
- Meal Kits:Pre-portioned ingredients require extended refrigerated stability.
Restaurants define current specification standards. Meal Kits are gaining share fastest on convenience positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting production investment toward jurisdictions with established novel-food approval pathways, compressing time-to-market for mung bean and pea protein isolates while delaying commercialization in stricter authorization regimes.
United States
Foodservice operators in quick-service chains are standardizing liquid egg substitutes for breakfast menu consistency, driving procurement consolidation among institutional feeders. The FDA oversees labeling integrity for plant-based egg products, though unsettled terminology standards create compliance uncertainty for interstate packaging claims. Chicago and Austin clusters concentrate manufacturing scale for refrigerated emulsion formats serving commercial kitchens.
Germany
Retail channels show accelerating penetration for powdered scramble mixes targeting home bakers seeking extended ambient stability. EFSA novel food authorization requirements mandate extended safety dossiers, extending time-to-market for non-legume protein entrants. Berlin-Brandenburg industrial zones host formulation facilities prioritizing mung bean and pea proteins with established regulatory histories over experimental inputs.
Canada
Yellow pea protein concentrate supply chains anchor ingredient sourcing for North American manufacturers, though prairie harvest yields expose margins to weather-driven price volatility. Health Canada and PMRA regulate processing standards applicable to plant-based food products crossing provincial borders. Saskatchewan and Alberta agricultural zones concentrate pea protein extraction infrastructure serving downstream emulsion producers.
United Kingdom
Natural retail channels reward heritage brand positioning in scramble mix segments, with direct-to-consumer subscription models capturing repeat purchase loyalty. Post-Brexit regulatory divergence from EU novel food frameworks creates parallel authorization requirements for emerging protein sources. London and Southeast England clusters coordinate distribution control for premium-positioned dried blend formats.
India
Domestic mung bean processing infrastructure is maturing as regional ingredient supply chains decouple from import-dependent models, enabling cost curve compression for isolate production. FSSAI regulates food safety standards for plant-based alternatives entering interstate commerce. Maharashtra and Gujarat industrial corridors concentrate extraction technology investment serving both domestic formulation and export markets.
Plant-Based Vegan Eggs Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue precision fermentation and controlled-environment protein production. The vendor base stratifies across three maturity tiers: heritage natural-channel brands with decades of retail presence, venture-backed technology specialists leveraging proprietary extraction methods, and commodity ingredient suppliers scaling isolate production for downstream formulation. Dominant competitive moves include backward integration into captive mung bean and pea protein supply, and direct-to-foodservice distribution bypassing traditional broadline intermediaries.
Among technology-driven specialists, Eat Just and Perfeggt exemplify the proprietary extraction archetype, while Follow Your Heart and Bob's Red Mill Natural Foods anchor heritage positioning in natural retail channels. EVO Foods and Orgran Foods occupy positions bridging regional market development with format diversification. Lovely Day Foods, Vegg, and Puris Holdings represent scale-oriented and ingredient-supply archetypes respectively, each sitting within distinct competitive vectors defined by supply chain control versus channel access priorities.
| Leading Market Players |
|---|
| EVO Foods |
| Orgran Foods |
| Eat Just |
| Lovely Day Foods |
| Perfeggt |
| Follow Your Heart |
| Bob's Red Mill Natural Foods |
| Puris Holdings |
| Vegg |
| Others |
Pricing and Supply Chain Analysis
CSRD-driven Scope 3 disclosure mandates gate both qualified supply and premium-tier pricing access for plant-based egg manufacturers, forcing ingredient documentation that only vertically integrated mung bean processors can satisfy while excluding commodity traders from certified contract pools.
Pricing Analysis
Direct-to-foodservice distribution discounts compress traditional broadline distributor markups by eight to fifteen points for volume-committed operators. Three-tier pricing structure across premium, standard, and economy levels separates proprietary high-pressure processed mung bean isolates from commodity pea concentrates from generic soy-dependent blends. Cost compression in the standard tier is intensifying because Canadian prairie harvest volatility transmits directly into yellow pea protein concentrate contracts. Quick-service restaurant chains exhibit highest price sensitivity due to standardized menu cost targets, while healthcare institutional feeders accept premium positioning for allergen-free certification.
Supply Chain Analysis
Single-source vulnerability sits with Saskatchewan and Alberta pea protein extraction infrastructure serving North American downstream formulation. Raw material flows draw from Canadian prairie yellow pea harvests, Indian mung bean processing corridors in Maharashtra and Gujarat, and German algal cultivation pilots. Tariff exposure on isolate imports into the European Union threatens margin structures for non-regional suppliers. Distribution runs through temperature-controlled foodservice broadline networks and direct-to-operator refrigerated logistics for liquid emulsion formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plant-based vegan eggs function as a regulatory compounder where EFSA novel food authorization timelines and FDA labeling uncertainty create demand windows for established legume protein platforms over speculative alternatives.
For Market Incumbents: Lock in captive mung bean supply through backward integration into Indian and North American processing infrastructure before prairie harvest volatility escalates input cost spreads. Secure multi-year direct-to-foodservice contracts with price escalation caps to defend margin position against emerging precision fermentation entrants targeting scramble texture parity. For New Entrants and Emerging Players: Foodservice purchasing cooperatives represent the most penetrable channel for regional operators lacking national distributor relationships. Target German retail powdered scramble mix shelves where ambient stability requirements favor new shelf-stable entrants over refrigerated legacy brands. Lead with carbon-accounting documentation to capture CSRD-compliant procurement panels in European institutional feeding. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap mung bean isolate specialists because buyer concentration among national foodservice distributors is consolidating procurement leverage and squeezing standalone suppliers into distressed exit valuations. Monitor EFSA approval velocity for non-legume proteins as the inflection signal for platform obsolescence risk in established pea and mung bean positions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mung Bean Processing | Captive supply from Maharashtra extraction facilities insulates margins from Indian export tariff volatility. |
| Direct-to-Foodservice Distribution Launch | Bypassing broadline distributors captures margin layers previously allocated to intermediary refrigerated logistics. |
| High-Pressure Processing Capacity Expansion | Chicago and Austin manufacturing clusters achieve scramble texture parity that commands premium tier positioning. |
| Carbon Accounting Certification Program | CSRD-compliant documentation unlocks European healthcare and education procurement panels requiring Scope 3 disclosure. |
| Precision Fermentation Partnership | Technology convergence with traditional legume extrusion enables texture profiles previously unattainable in vegan omelet applications. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with foodservice procurement directors, plant-based formulation scientists, mung bean protein extraction engineers, and retail category buyers with secondary validation against FDA labeling guidance documents, EFSA novel food authorization registers, CSRD disclosure frameworks, and Canadian prairie agricultural yield data. Bottom-up volume estimates from individual manufacturer capacity announcements triangulated against top-down demand projections from foodservice operator menu integration rates.
Segment-weighting distributed value and volume across product type, ingredient source, distribution channel, and end-user application dimensions throughout the forecast period. CAGRs derived from slope-intercept modeling of historical adoption curves adjusted for regulatory authorization timelines and protein extraction technology maturation trajectories. Forecast inputs incorporated high-pressure processing equipment installation rates and EFSA safety dossier submission velocities as industry-specific demand accelerators.
Revisions become necessary when FDA labeling terminology standards crystallize, EFSA accelerates novel food pathways for non-legume proteins, or Canadian prairie weather patterns disrupt yellow pea harvest yields. Forecasts reflect documented assumptions about foodservice menu standardization rates and carbon accounting mandate enforcement timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Organic Rice Protein Market
Plant Based Food
Mexico Plant-Based Food and Beverages Market
Plant Based Food
South America Rice Protein Market
Plant Based Food
Organic Pea Protein Market
Plant Based Food
Plant Based Meal Kit Market
Plant Based Food
Plant-Based Bars Market
Plant Based Food
Plant-Based Milk Alternatives Market
Plant Based Food
Fermented Plant Extracts Market
Plant Based Food
Plant-Based Ham Market
Plant Based Food
Dandelion Root Extract Market
Plant Based Food
Middle East Plant Protein Market
Plant Based Food
Vegan Steak Market
Plant Based Food
Canada Plant-Based Food and Beverages Market
Plant Based Food
Lentil Protein Market
Plant Based Food
US Plant-Based Meat Market
Plant Based Food
India Plant Based Milk Market