
 Plant-Based Ham Market | 2026-2036
Plant-Based Ham Market Size, Share, and Industry Trends Forecast 2026-2036
Plant-Based Ham Market Analytics
Europe is fragmenting as production capacity for plant-based deli proteins spreads across the Netherlands, Germany, and Belgium. Tofurky anchors its position through decades of vegetarian brand equity and dedicated seitan processing infrastructure. Beyond Meat competes via pea-protein extrusion scale and rapid food-service penetration. Nestlé leverages its chilled distribution networks to secure retail shelf space for Garden Gourmet branded ham alternatives.
Plant-based ham denotes cured, sliced, or formed meat analogues manufactured from pea protein, soy protein, or wheat gluten (seitan), typically employing high-moisture extrusion and alginate or carrageenan binding to replicate muscle fiber texture and mouthfeel; the product serves commercial deli counters, ready-to-eat retail packs, and food-service sandwich programs seeking pork-free protein alternatives. Slices dominate current volume as the default format for retail deli cases and pre-packaged lunch solutions, while shreds represent the fastest-growing configuration driven by pizza topping and prepared salad applications. Online retail channels capture expanding margin pools through subscription models and direct-to-consumer sampling, though supermarkets still control the bulk of physical discovery and impulse purchase behavior.
FDA oversees labeling integrity for plant-based meat alternatives in the United States, while EFSA governs novel protein ingredient approvals and health claim substantiation across European markets. USDA Food Safety and Inspection Service engagement with simulated meat products shapes inspection protocols and facility compliance requirements for domestic manufacturers. Stakeholders must monitor evolving allergen declaration thresholds for pea and soy proteins as these ingredients concentrate formulation recipes.
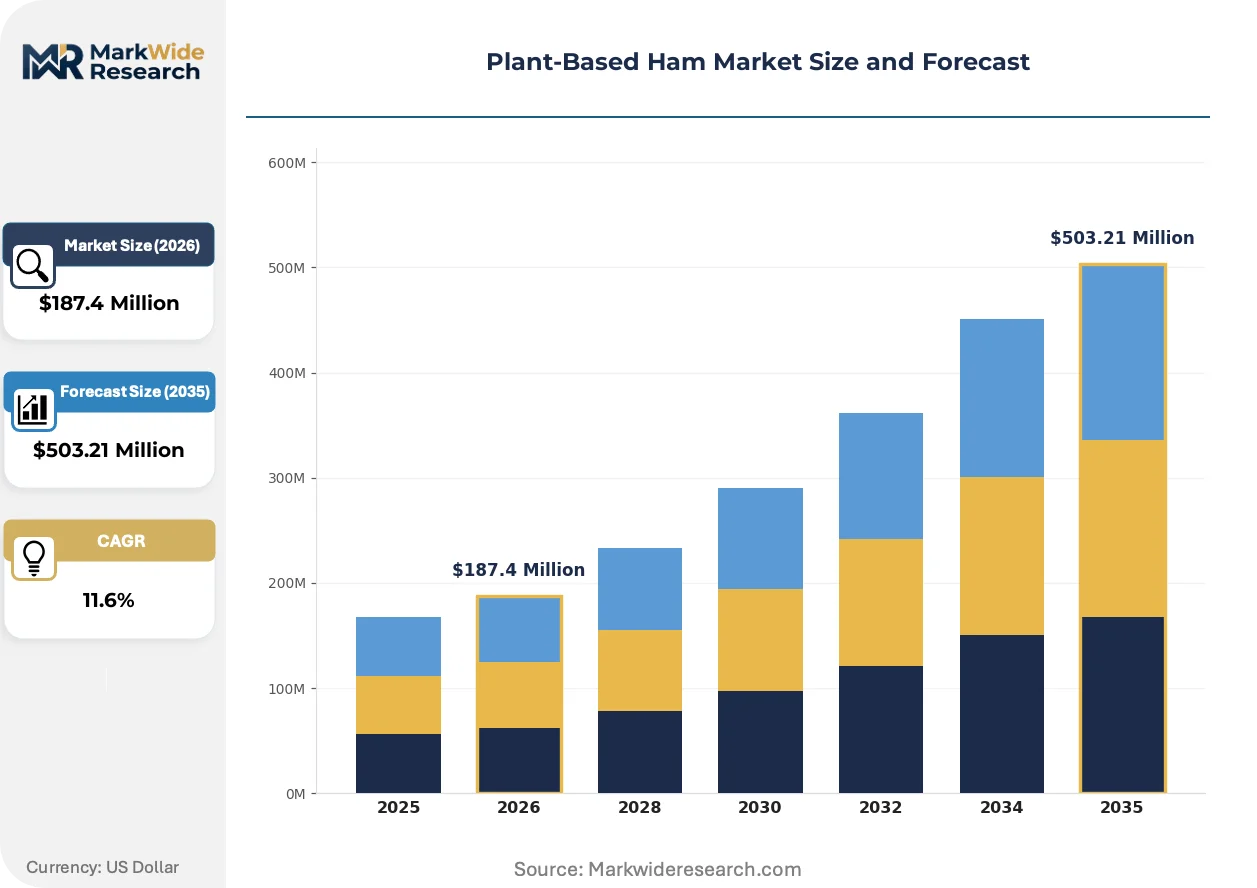
Market Dynamics
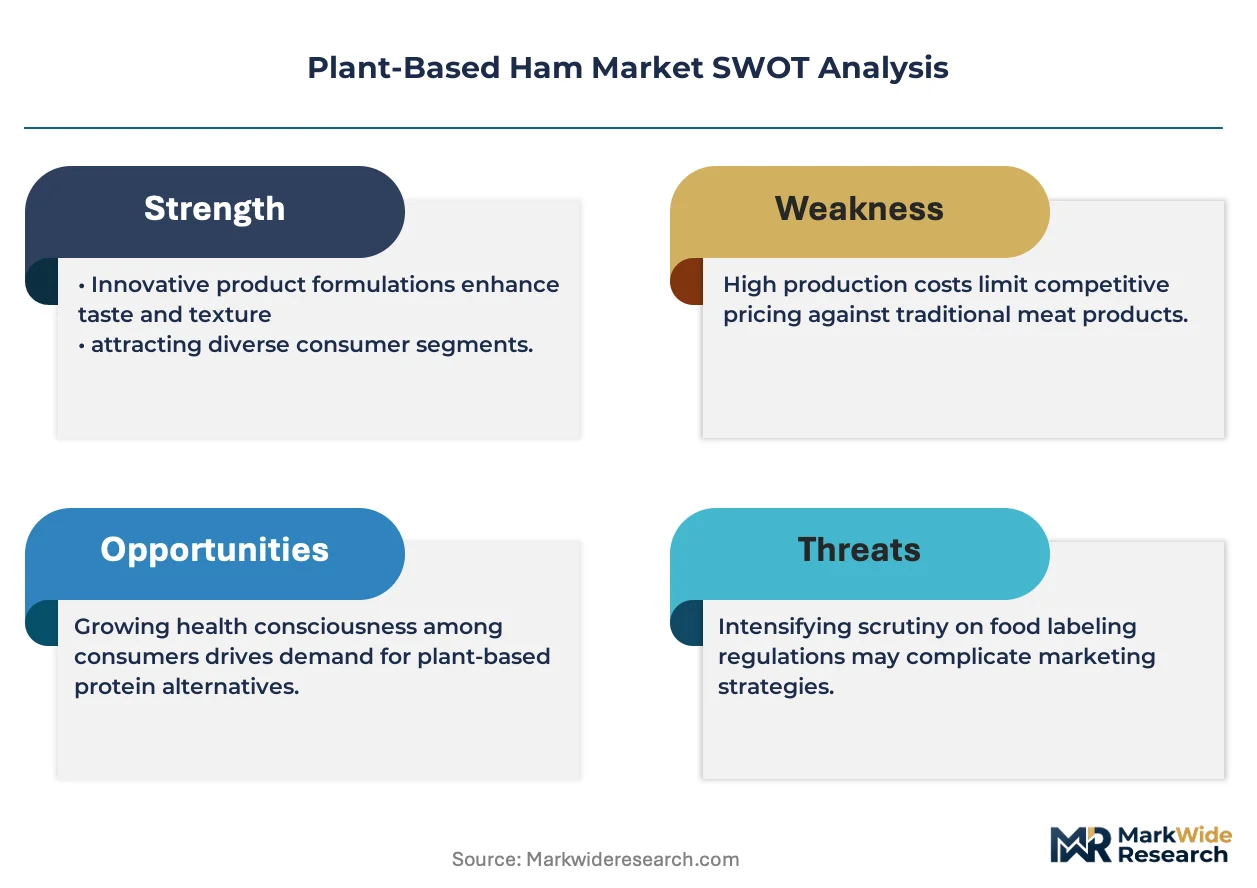
High-moisture extrusion capacity is concentrating in the Netherlands and Germany as FDA labeling scrutiny tightens and EFSA novel food assessments lengthen approval timelines for new entrants.
Growth Catalysts
- EFSA Clean-Label Pathways:Established formulations with completed novel food dossiers bypass retail listing delays in Germany, accelerating shelf placement versus newer competitors.
- Food Service Sandwich Programs:North American deli operators expand refrigerated plant-based SKU counts to capture lunch traffic seeking pork-free protein alternatives.
- Seitan Processing Infrastructure:Dedicated wheat gluten extrusion lines in Belgium enable texture replication that alginate-bound pea proteins struggle to match.
Market Restraints
- Pea Protein Input Volatility:Concentrated Canadian and Ukrainian yellow pea supply exposes margins to weather-driven price swings and export disruption.
- Alginate Binding Cost Structure:Seaweed-derived hydrocolloid prices fluctuate with Chilean and Norwegian harvest yields, compressing formulation economics.
- FDA Labeling Uncertainty:Pending standardized of identity rules for simulated meat products create inventory risk for US manufacturers awaiting compliance clarity.
Strategic Opportunities
- Pizza Topping Applications:Shred-format plant-based ham captures prepared food manufacturers seeking consistent cook stability and cross-utilization across menu items.
- Subscription Direct-to-Consumer:Online retail channels bypass supermarket slotting fees while building repeat purchase data for flavor optimization.
- EU Green Deal Procurement Mandates:Public sector food service contracts across Germany and the Netherlands now specify carbon-labeled protein alternatives.
Industry Challenges
- High-Moisture Extrusion Technician Scarcity:Operational expertise for twin-screw parameter optimization remains concentrated among veteran food engineers at legacy meat analogue facilities.
- Allergen Declaration Complexity:Concentrated pea and soy protein formulations trigger evolving threshold debates between FDA guidance and EU 1169/2011 implementation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant-Based Ham Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Slices, Cubes, Rounds, Shreds End User: Households, Restaurants, Cafés, Food Services Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales Ingredient Type: Pea Protein, Soy Protein, Seitan, Others |
| Companies Covered | Tofurky, Nestlé, Lightlife Foods, The Vegetarian Butcher, Gardein, Beyond Meat, Impossible Foods, Quorn Foods, Hain Celestial Canada ULC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant-Based Ham Market Evolving Landscape
Extrusion technology is virtualizing muscle fiber architecture while regulatory frameworks harden around protein source transparency and carbon accounting methodologies.
Shear-cell technology is virtualizing traditional high-moisture extrusion by generating aligned protein fibers without the energy intensity of twin-screw systems. European equipment manufacturers are retrofitting pilot lines for plant-based ham producers seeking texture parity at lower operational cost. This compression of capital requirements is virtualizing the barrier between artisan seitan operations and industrial-scale output.
EFSA's 2023 updated guidance on novel protein ingredient safety assessments is extending evaluation timelines for emerging fermentation-derived proteins. Manufacturers with legacy dossiers gain competitive runway as newer entrants face 18-24 month approval cycles. German retail buyers are responding by consolidating listings around established clean-label suppliers with completed safety packages.
Food service procurement is consolidating spend around single-source plant-based protein vendors capable of delivering slice, shred, and formed formats from unified extrusion facilities. Broadline distributors in North America are displacing fragmented specialty suppliers with house-brand alternatives manufactured under co-manufacturing agreements. This vendor consolidation is most visible in US K-12 and healthcare cafeteria contracts where specification standardization reduces kitchen complexity.
Plant-Based Ham Market Segmentation
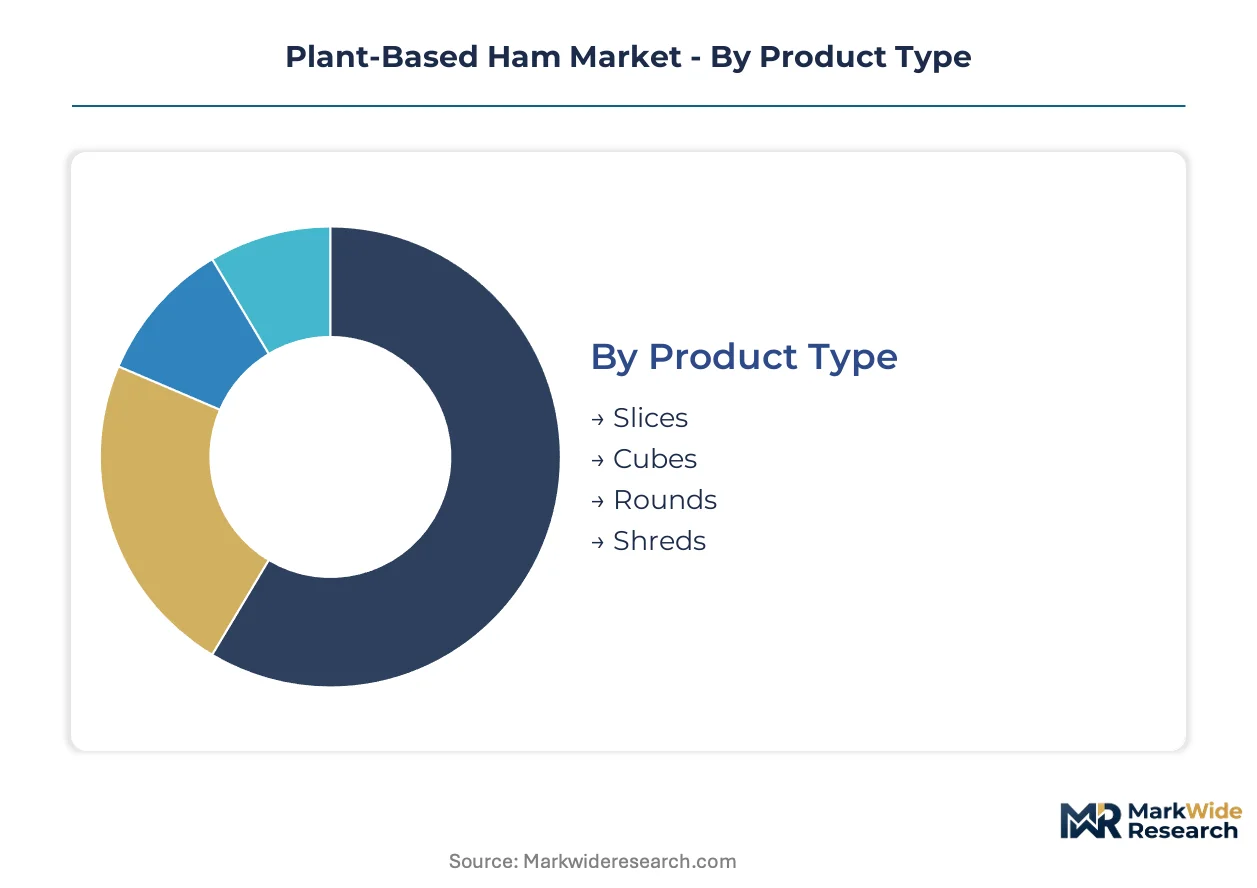
Plant-based ham producers calibrate extrusion parameters and binding systems differently for each product geometry, while distribution channel selection determines margin capture and regulatory compliance burden. Segmentation reveals where formulation investments concentrate and which customer interfaces reward premium positioning versus volume scale.
Product Type:
Use-case spectrum spans grab-and-go retail packs through industrial ingredient formats, with each geometry demanding distinct moisture retention and slice integrity specifications.
- Slices:Thin-cut deli sheets rely on alginate or carrageenan binding to maintain fold integrity across refrigerated shelf life. North American supermarket deli counters specify this format for pre-packaged lunch solutions, though alginate cost volatility compresses margin pools.
- Shreds:Pulled-fiber configurations employ high-moisture extrusion with post-processing shear to generate stringy texture mimicking hand-torn ham. Pizza topping manufacturers and prepared salad processors in Germany drive specification tightening for cook stability and cross-utilization.
- Cubes:Diced formats suit breakfast bowl and soup applications where edge definition matters less than rehydration performance.
- Rounds:Whole-muscle analogues target premium charcuterie plating and holiday centerpiece presentations.
The dominant share belongs to Slices, while Shreds is closing the gap fastest.
End User:
Customer type dictates batch size, certification requirements, and price elasticity thresholds across the value chain.
- Households:Individual consumers purchasing retail packs prioritize clean-label ingredient lists and recognizable protein sources. German households with completed EFSA novel food dossiers favor established formulations over newer entrants facing retail listing delays.
- Food Services:Broadline distributors and contract caterers consolidate procurement around unified extrusion facilities capable of delivering multiple formats. US K-12 and healthcare cafeteria contracts now specify carbon-labeled alternatives under evolving procurement mandates.
- Restaurants:Independent operators and chains seek consistent portion control and cross-menu versatility.
- Cafés:Limited-service formats emphasize grab-and-go compatibility and minimal preparation steps.
Food Services commands the volume base, yet Households is expanding most quickly through subscription direct-to-consumer channels.
Distribution Channel:
Channel selection determines discovery mechanics, slotting fee exposure, and repeat purchase data capture.
- Supermarkets:Physical retail controls bulk discovery and impulse purchase behavior, with chilled distribution networks securing premium shelf positioning. Nestlé leverages existing infrastructure for Garden Gourmet branded placement in European multiples.
- Online Retail:Subscription models and direct-to-consumer sampling bypass supermarket slotting fees while building repeat purchase datasets for flavor optimization. Belgian seitan specialists use this channel to reach German consumers outside conventional retail listings.
- Specialty Stores:Natural food retailers and deli counters serve early-adopter demographics seeking artisan positioning.
- Direct Sales:Food service route trucks and institutional contracts enable specification customization.
Supermarkets retain the volume anchor, though Online Retail is gaining share fastest through margin expansion and data capture.
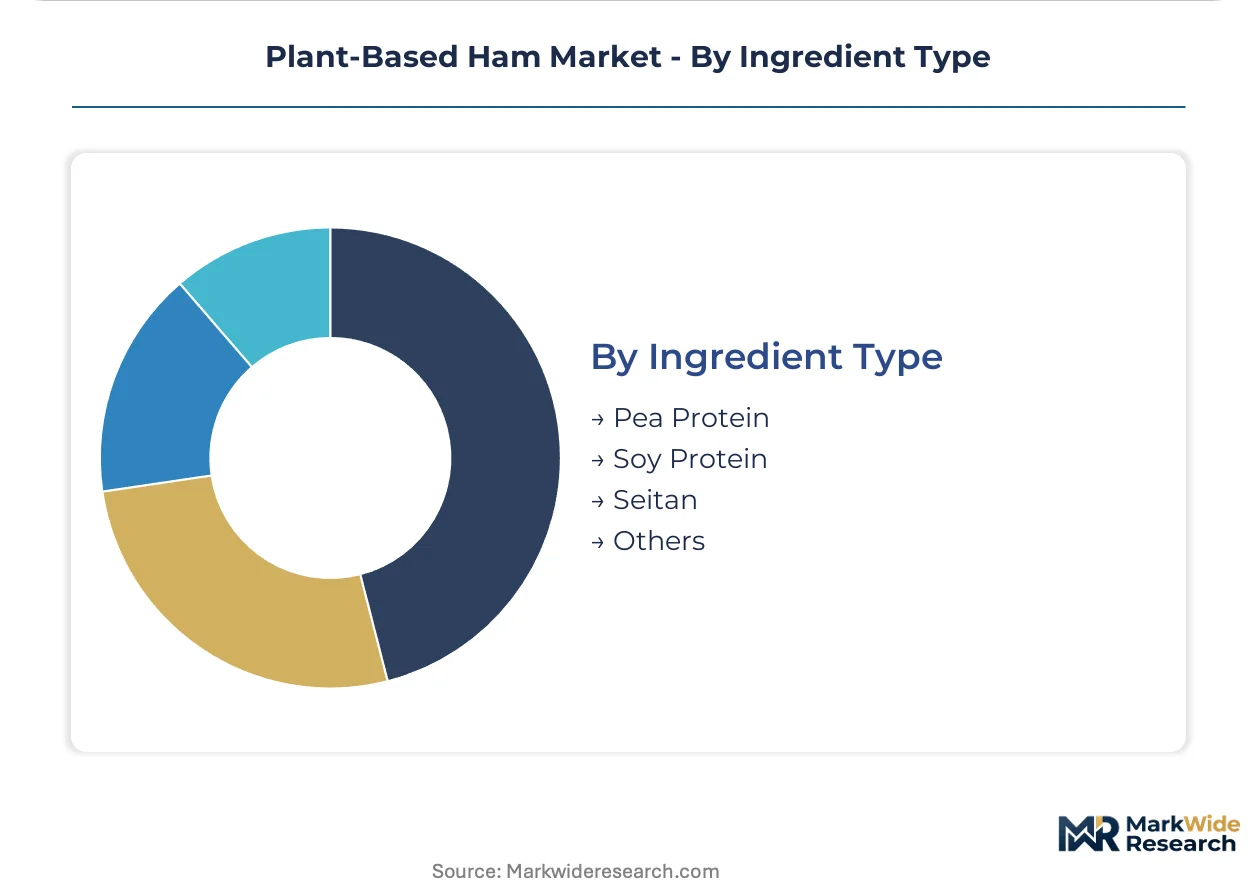
Ingredient Type:
Protein source selection governs texture replication, allergen profile, and supply chain risk exposure.
- Seitan:Wheat gluten extrusion generates aligned fiber structures through mechanical shear rather than high-moisture thermal processing. Dedicated production lines in Belgium enable texture parity that alginate-bound alternatives struggle to match.
- Pea Protein:Yellow pea isolate concentrates formulation recipes for clean-label positioning, though Canadian and Ukrainian supply concentration exposes margins to weather-driven price swings and export disruption.
- Soy Protein:Legacy ingredient with established processing infrastructure and cost structure, facing evolving allergen declaration thresholds in both FDA and EU 1169/2011 implementations.
- Others:Emerging fermentation-derived and novel protein sources await EFSA safety assessment completion.
Seitan holds the texture premium, while Pea Protein is climbing the fastest on clean-label momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-moisture extrusion capacity clusters in the Netherlands and Germany as regulatory scrutiny intensifies on both sides of the Atlantic. FDA labeling uncertainty in the United States and EFSA novel food assessments in Europe are lengthening approval timelines for new entrants. Manufacturers with legacy dossiers and established clean-label formulations gain competitive runway as newer competitors face extended evaluation cycles.
Germany
Food service procurement teams specify carbon-labeled protein alternatives under EU Green Deal mandates for public sector contracts. EFSA novel food assessments favor established clean-label suppliers with completed safety packages, delaying retail listings for newer entrants. The Ruhr Valley and Berlin-Brandenburg corridor host dedicated seitan processing infrastructure that Tofurky leverages for texture replication.
United States
Broadline distributors consolidate spend around unified extrusion facilities capable of delivering multiple formats for K-12 and healthcare cafeteria contracts. FDA pending standardized identity rules for simulated meat products create inventory risk for domestic manufacturers awaiting compliance clarity. The Midwest corn-soy belt concentrates pea protein processing infrastructure, though Canadian yellow pea supply exposes margins to weather-driven disruptions.
Netherlands
Shear-cell technology pilot lines retrofit existing facilities to generate aligned protein fibers without twin-screw energy intensity. EFSA updated guidance on novel protein ingredient safety assessments extends evaluation timelines for fermentation-derived alternatives. The Eindhoven region and Randstad corridor anchor European extrusion equipment manufacturing and plant-based protein R&D clusters.
Belgium
Dedicated wheat gluten extrusion lines enable texture parity that alginate-bound pea proteins struggle to match for pizza topping and prepared salad applications. EU 1169/2011 allergen declaration thresholds trigger evolving compliance debates for concentrated gluten formulations. The Flanders region concentrates artisan seitan operations scaling toward industrial output through co-manufacturing partnerships.
Canada
Hain Celestial Canada ULC leverages domestic yellow pea supply chains for clean-label isolate production serving North American retail and food service channels. Health Canada nutrition labeling alignment with FDA tightening creates cross-border compliance efficiencies for integrated manufacturers. The Prairie Provinces concentrate agricultural protein processing with Winnipeg and Saskatoon anchoring extrusion ingredient supply.
Plant-Based Ham Market Competitive Landscape
Legacy vegetarian specialists and scaled alternative protein platforms split the market between texture authenticity and manufacturing throughput. The vendor base concentrates around three strategic archetypes: dedicated seitan processors with decades of brand equity, pea-protein extrusion scale players, and diversified food conglomerates leveraging chilled distribution networks. Competitive moves center on co-manufacturing agreements with broadline distributors and backward integration into high-moisture extrusion capacity.
Within the legacy specialist tier, Tofurky and The Vegetarian Butcher exemplify decades-long vegetarian brand equity and dedicated wheat gluten processing infrastructure. Among diversified food conglomerates, Nestlé occupies a position leveraging existing chilled distribution networks for retail shelf placement. At the scale-driven end, Beyond Meat represents pea-protein extrusion manufacturing and rapid food-service penetration capabilities.
| Leading Market Players |
|---|
| Tofurky |
| Nestlé |
| Lightlife Foods |
| The Vegetarian Butcher |
| Gardein |
| Beyond Meat |
| Impossible Foods |
| Quorn Foods |
| Hain Celestial Canada ULC |
| Others |
Value Network & Pricing Analysis
Undercapacity in Belgian seitan processing lines is compressing supplier bargaining power while pushing contract manufacturers toward longer-term offtake commitments with wheat gluten processors. This utilization squeeze simultaneously elevates input security premiums and constrains spot-market flexibility for North American buyers facing FDA labeling uncertainty.
Pricing Analysis
FDA pending standardized identity rules dictate the pricing tier structure across US manufacturing, separating EFSA-dossiered clean-label premiums from reformulation-risk-discounted alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification completion status, with German retail buyers paying premiums for established novel food approvals. Price differentiation centers on alginate binding costs versus seitan texture parity, with food service sandwich programs showing highest sensitivity to per-unit fluctuations while direct-to-consumer subscription buyers absorb modest premiums for ingredient transparency.
Supply Chain Analysis
Co-manufacturing concentration among Dutch and German extrusion specialists anchors European capacity, with Belgian wheat gluten processors and Canadian yellow pea isolate facilities feeding formulation pipelines. Raw material dependencies center on Ukrainian and Canadian yellow pea supply, Chilean and Norwegian seaweed harvests for alginate binders, and European wheat gluten streams. Single-source vulnerability in Canadian pea protein concentration exposes margins to Prairie Provinces weather disruption. Distribution runs through chilled broadline networks for food service penetration and direct-to-consumer subscription platforms for margin retention.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is cycling through a regulatory compliance trough as EFSA novel food assessment backlogs and FDA labeling uncertainty simultaneously extend approval timelines and compress near-term capacity utilization.
For Market Incumbents: Pre-empt co-manufacturing consolidation by locking multi-format extrusion capacity in the Netherlands and Germany before shear-cell technology retrofits fragment technician availability. Secure backward integration into wheat gluten processing or pea protein isolate production to defend margin position against alginate cost volatility and Canadian supply disruption.
For New Entrants and Emerging Players: Build out shred-format capabilities targeting pizza topping and prepared salad manufacturers in Germany, where EFSA retail listing delays handicap established competitors less than slice-format incumbents. Leverage online retail subscription models to bypass supermarket slotting fees and accumulate repeat purchase data before seeking chilled distribution partnerships.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among direct-to-consumer subscription operators with completed EFSA dossiers and proprietary flavor datasets. Target acquisition candidates with seitan processing infrastructure or shear-cell technology pilots rather than pure pea-protein extrusion scale. Monitor EFSA novel food approval velocity as the inflection signal distinguishing sustainable competitive runway from stranded reformulation risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Shear-Cell Technology Retrofit | Reduces twin-screw energy intensity while maintaining fiber alignment for texture parity. |
| EFSA Novel Food Dossier Completion | Bypasses 18-24 month approval delays that block German retail listings for competitors. |
| Direct-to-Consumer Subscription Launch | Captures repeat purchase data and margin pools outside supermarket slotting fee structures. |
| Backward Integration into Pea Protein Isolate | Defends formulation economics against Prairie Provinces supply disruption and export volatility. |
| Co-Manufacturing Agreement with Broadline Distributor | Secures unified extrusion facility access for multi-format delivery to K-12 and healthcare contracts. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA labeling guidance documents, EFSA novel food safety assessments, and EU Green Deal procurement mandate texts. Primary interviews engaged plant-based protein R&D directors, food service procurement managers at broadline distributors, retail category buyers in German multiples, and high-moisture extrusion technicians at legacy meat analogue facilities. Secondary validation drew from customs records tracking yellow pea and wheat gluten trade flows, SEC filings of publicly traded alternative protein platforms, and chilled distribution network capacity disclosures. Bottom-up segment sizing triangulated against top-down market value reconstruction.
Forecast inputs span product geometry specifications, protein source concentration trends, distribution channel migration patterns, and regulatory approval timeline distributions across the analysis window. Segmentation modeling incorporated ingredient type, end-user procurement behavior, and regional compliance cluster variations. CAGRs derived from elasticity-adjusted volume projections and value-per-unit evolution across format tiers. Industry-specific inputs included shear-cell technology adoption curves and EFSA dossier completion rates.
Stress conditions across Ukrainian yellow pea export disruption, Norwegian alginate harvest yield variance, and FDA standardized identity rule implementation timing were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding EFSA assessment velocity and broadline distributor consolidation momentum. Quarterly review of novel food approval queue lengths and co-manufacturing capacity utilization rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
United States Textured Vegetable Protein Market
Plant Based Food
Plant Based Pork Market
Plant Based Food
Plant Based Protein Market
Plant Based Food
Vegan Cookies Market
Plant Based Food
Plant Based Supplement Market
Plant Based Food
Plant-Based Shrimp Market
Plant Based Food
Plant Based Ice Cream Market
Plant Based Food
Rhubarb Root Extract Market
Plant Based Food
Africa Soy Beverages Market
Plant Based Food
Singapore Plant-Based Food and Beverages Market
Plant Based Food
Canada Plant Protein Market
Plant Based Food
Plant-Based Bars Market
Plant Based Food
Fractionated Pulses Market
Plant Based Food
Veggie Meals Market
Plant Based Food
Middle East and Africa Plant-Based Meat and Dairy Products Market
Plant Based Food
South America Rice Protein Market