
 Vegan Gelatin Market | 2026-2036
Vegan Gelatin Market Size, Share, and Industry Trends Forecast 2026-2036
Vegan Gelatin Market Analytics
Clean-label certification tiers is reorganizing procurement priorities across the vegan gelatin value chain. Cargill, Incorporated leverages its global agricultural sourcing network to secure consistent plant-derived hydrocolloid supply. GELITA AG anchors European production capacity for specialized gelling agents, while Kerry Group plc differentiates through integrated flavor-texture systems for dairy alternatives.
Vegan gelatin comprises plant-derived hydrocolloids—primarily agar-agar, carrageenan, pectin, and gellan gum—extracted through aqueous processing of seaweed, citrus peel, or microbial fermentation, forming thermoreversible gels at concentrations of 0.5–2.0% by weight. These functional ingredients replace animal collagen in applications requiring gel strength of 50–500 g/cm², serving food manufacturers seeking to eliminate porcine and bovine derivatives from formulations. Carrageenan dominates commercial volume due to its cost-efficient milk-protein interaction in dairy alternatives, while gellan gum commands premium positioning in transparent dessert gels and bakery glazes where clarity and thermal stability justify higher ingredient spend. Pectin occupies a mature, margin-compressed niche in conventional fruit-spread applications, though low-methoxyl variants are gaining traction in reduced-sugar bakery formulations.
EU REACH and EFSA food additive evaluations shape ingredient approval timelines and maximum usage levels for carrageenan and gellan gum in European formulations. FDA GRAS self-affirmation pathways and USDA organic certification requirements influence market access for agar-agar and pectin suppliers targeting North American clean-label segments. Stakeholders must monitor evolving EFSA re-evaluations of refined carrageenan safety classifications and adapt formulation portfolios accordingly.
Market Dynamics
EU Green Deal sustainability mandates are compressing ingredient sourcing timelines for food manufacturers, forcing rapid substitution of animal-derived hydrocolloids with plant-based alternatives across European formulation facilities.
Growth Catalysts
- REACH-compliant extraction protocols:ECHA registration requirements for carrageenan and agan-agar are accelerating aqueous processing investments in certified European facilities.
- Dairy alternative formulation expansion:Plant-based milk and yogurt manufacturers are locking in multi-year supply contracts for gellan gum to achieve thermal-stable gel textures.
- South Korea functional food sector:MFDS-approved health claims for seaweed-derived hydrocolloids are driving concentrated demand for carrageenan in probiotic delivery systems.
Market Restraints
- Red seaweed harvest volatility:Philippine and Indonesian coastal farming disruptions are transmitting price instability directly into carrageenan input costs.
- Refined carrageenan safety re-evaluations:EFSA's ongoing additive assessments are creating formulation uncertainty and inventory hesitation among European dessert manufacturers.
- Animal gelatin price competitiveness:Bovine and porcine collagen derivatives retain cost advantages in non-EU markets with weaker clean-label enforcement.
Strategic Opportunities
- Reduced-sugar bakery segment:Low-methoxyl pectin variants are capturing formulation slots in German and French industrial bakeries reformulating for EU nutrition labeling.
- Transparent dessert gel positioning:Gellan gum's optical clarity properties are opening premium pricing tiers in Japanese and South Korean convenience retail channels.
- USDA organic certification pathways:Self-affirmed GRAS status for agar-agar is unlocking direct-to-manufacturer supply relationships bypassing conventional distributor markups.
Industry Challenges
- Clean-label certification backlog:Third-party auditors in Germany and France are extending lead times for plant-derived hydrocolloid verification, delaying product launches.
- Legacy dairy equipment incompatibility:Retrofitting existing gelling agent dosing systems for lower-concentration plant hydrocolloids requires capital expenditure that mid-tier manufacturers are deferring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegan Gelatin Market |
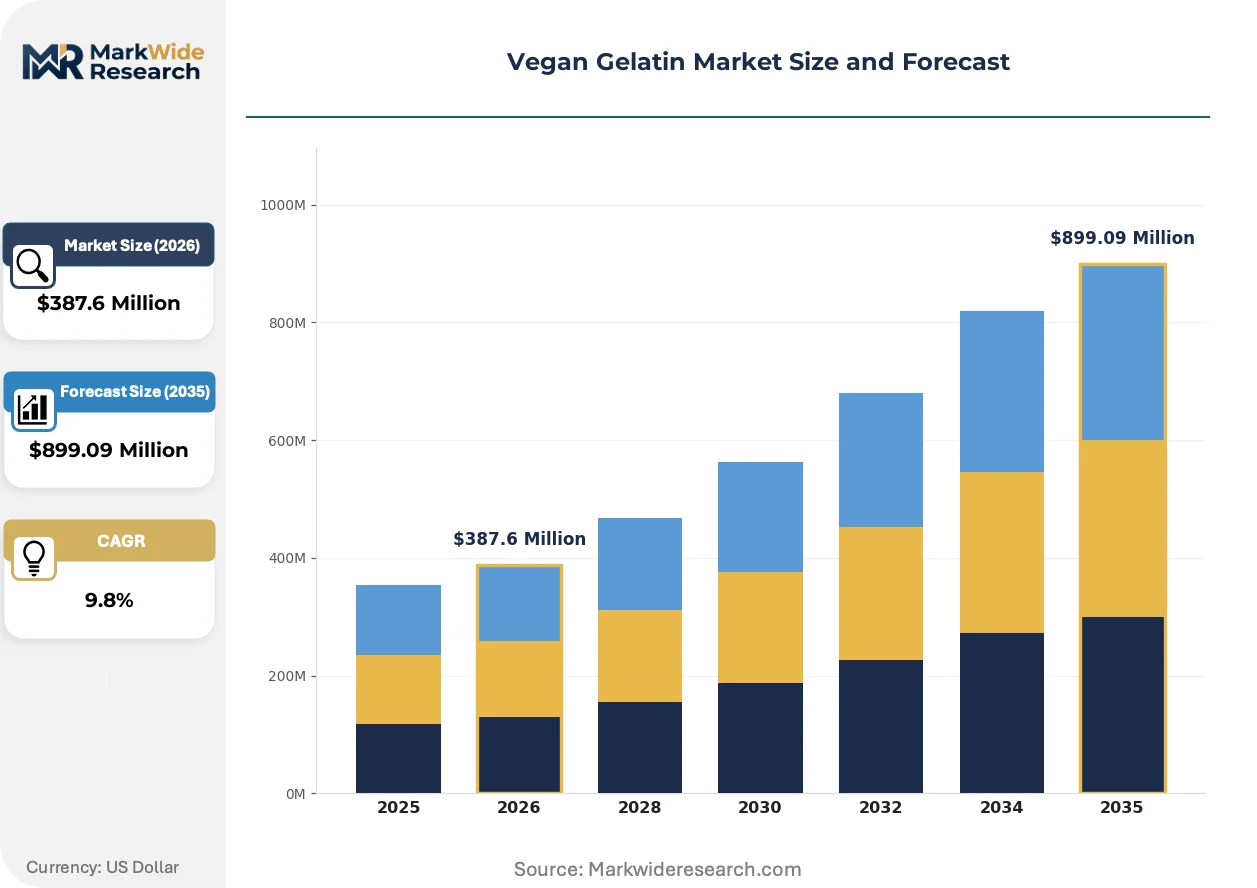
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $899.09 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Agar-Agar, Carrageenan, Pectin, Gellan Gum Application: Desserts, Snacks, Dairy Alternatives, Bakery Distribution Channel: Supermarkets, Online Stores, Health Food Shops, Specialty Retailers End User: Food Manufacturers, Restaurants, Home Cooks, Bakers |
| Companies Covered | Ingredion Incorporated, NOW Foods, Cargill, Incorporated, CP Kelco, Tate & Lyle PLC, Kerry Group plc, GELITA AG, ADM, Great American Spice Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegan Gelatin Market Evolving Landscape
Processing technology and regulatory classification are diverging paths for plant-derived hydrocolloids, separating premium-positioned ingredients from commodity-grade alternatives.
Precision fermentation for gellan gum production is bifurcating the high-performance gelling segment. Microbial-derived variants achieve 0.3% concentration thresholds versus 1.5% for seaweed extracts. Specialty dessert and pharmaceutical capsule manufacturers are adopting fermentation-grade material within eighteen-month validation cycles. This concentration efficiency is compressing freight and storage costs for long-distance supply chains.
EFSA's additive re-evaluation schedule is forcing preemptive formulation diversification. Refined carrageenan's pending safety classification review has triggered parallel testing of agar-agar and pectin blends in European dairy alternatives. German and Dutch manufacturers are submitting dual-formulation dossiers to accelerate regulatory contingency approval.
Direct-procurement contracts are displacing spot-market purchasing for strategic hydrocolloid volumes. Large-scale food manufacturers in France and Italy are negotiating eighteen to thirty-six month offtake agreements with Philippine and Chilean seaweed processors. This channel consolidation is squeezing regional distributor margins and concentrating price-setting power with integrated agricultural processors.
Vegan Gelatin Market Segmentation
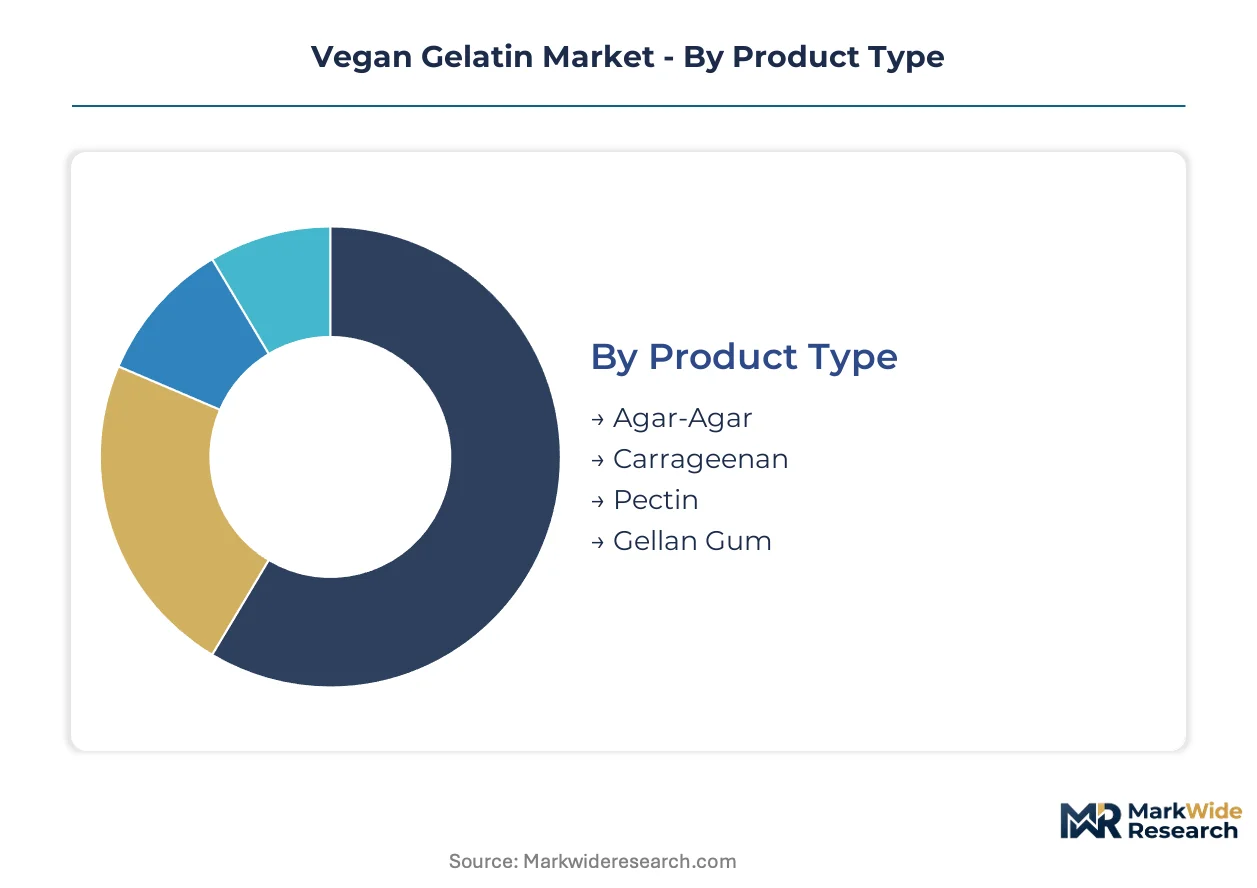
Vegan gelatin segmentation reveals distinct channel affinities that shape procurement patterns. Product type determines margin structure, while application and end-user categories dictate formulation complexity and volume scale.
Product Type:
Carrageenan and agar-agar flow predominantly through industrial distributors serving food manufacturers, while gellan gum and premium pectin variants reach formulators via specialty chemical channels with technical service support.
- Carrageenan:Extracted from red seaweed through aqueous processing, this hydrocolloid delivers cost-efficient milk-protein interaction at 0.5–1.5% concentration thresholds. German and Dutch dairy alternative manufacturers are locking in multi-year supply contracts to secure thermal-stable gel textures amid EU Green Deal sourcing mandates.
- Agar-Agar:Derived from red algae, this thermoreversible gelling agent forms firm gels at 1–2% concentrations with superior clarity. South Korea's functional food sector is driving concentrated demand through MFDS-approved health claims for seaweed-derived hydrocolloids in probiotic delivery systems.
- Pectin:Citrus peel and apple pomace extraction yields this mature hydrocolloid for conventional fruit-spread applications.
- Gellan Gum:Microbial fermentation produces this premium-positioned hydrocolloid for transparent dessert gels requiring optical clarity.
By volume, carrageenan leads. By expansion trajectory, gellan gum is climbing the fastest.
Application:
Margin profiles diverge sharply across applications, with dairy alternatives commanding premium pricing for thermal stability while bakery applications face cost compression from reduced-sugar reformulation pressures.
- Dairy Alternatives:Plant-based milk and yogurt formulations require hydrocolloids with specific protein interaction properties. French and Italian manufacturers are submitting dual-formulation dossiers to EFSA to preempt regulatory contingency requirements.
- Desserts:Transparent gel applications favor gellan gum's optical clarity, opening premium pricing tiers in Japanese and South Korean convenience retail channels.
- Bakery:Low-methoxyl pectin variants are capturing formulation slots in German and French industrial bakeries reformulating for EU nutrition labeling mandates.
- Snacks:Texture modification for plant-based confectionery drives hydrocolloid demand through conventional food ingredient distributors.
Dairy alternatives generate the highest per-kilogram value. Desserts are gaining share fastest as clean-label positioning intensifies.
Distribution Channel:
Channel consolidation is squeezing regional distributor margins as large-scale manufacturers negotiate direct-procurement contracts with integrated agricultural processors.
- Supermarkets:Mass-market retail chains stock commodity-grade agar-agar and standard pectin for home cooking segments.
- Online Stores:E-commerce platforms enable direct-to-manufacturer supply relationships for USDA organic-certified agar-agar, bypassing conventional distributor markups.
- Health Food Shops:Specialty retail channels serve clean-label consumers seeking certified organic hydrocolloids with third-party verification.
- Specialty Retailers:Technical ingredient suppliers provide formulation support for professional bakers and small-batch food manufacturers.
Supermarkets move the largest absolute volumes. Online channels are expanding most quickly as procurement digitization accelerates.
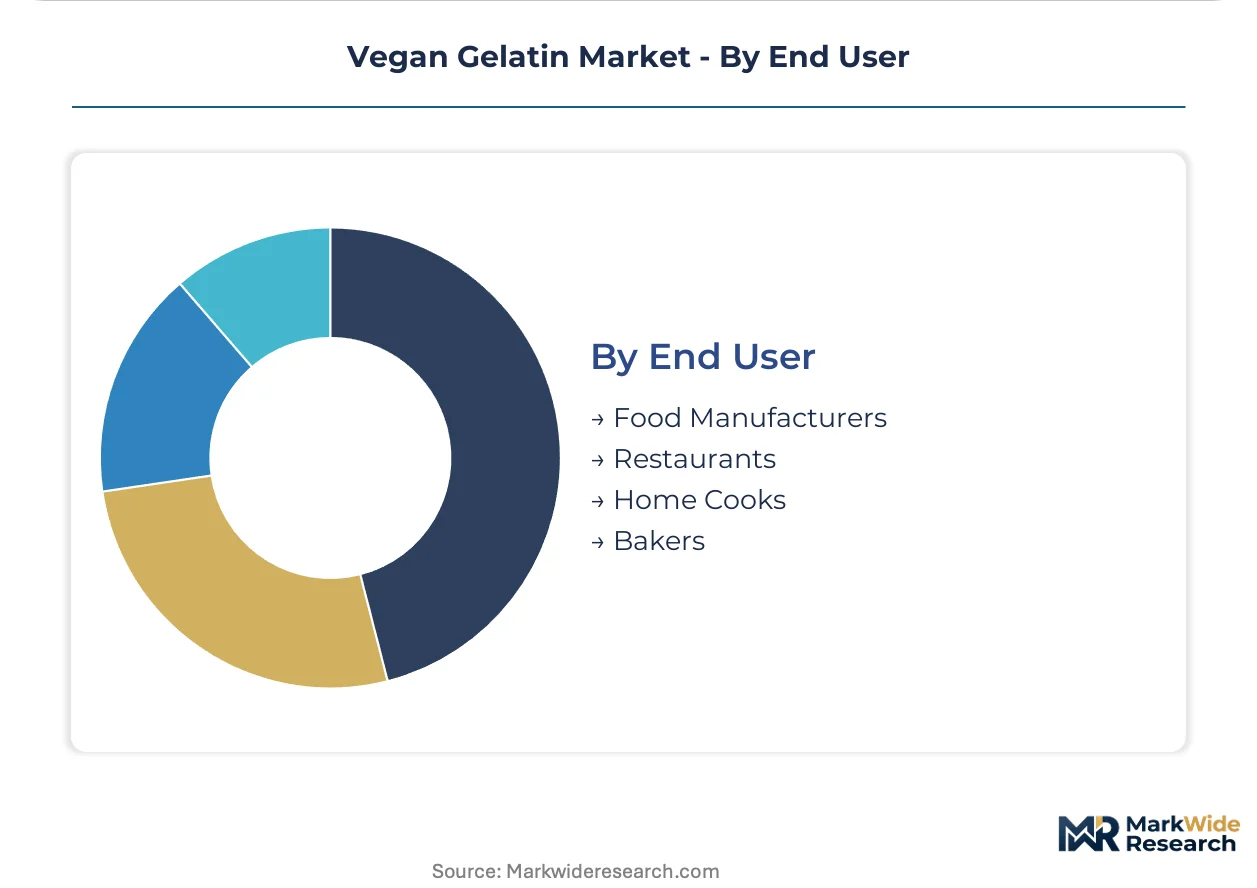
End User:
Equipment compatibility requirements create diverging service needs, with food manufacturers demanding retrofit support while home cooks prioritize convenience packaging.
- Food Manufacturers:Industrial-scale formulators face legacy dairy equipment incompatibility challenges when retrofitting dosing systems for lower-concentration plant hydrocolloids.
- Restaurants:Foodservice operators seek consistent hydration properties for menu item standardization across multiple locations.
- Home Cooks:Retail-packaged hydrocolloids with usage instructions target the amateur segment through consumer-facing channels.
- Bakers:Professional and artisanal bakers require precise gel strength specifications for decorative and structural applications.
Food manufacturers dominate volume offtake. Restaurants are adopting plant-based alternatives most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Red seaweed farming clusters in the Philippines and Indonesia concentrate carrageenan feedstock supply, while fermentation facilities in Japan and South Korea anchor gellan gum production. EU Green Deal mandates are accelerating plant-based hydrocolloid substitution across European formulation networks.
Germany
Industrial bakeries in Bavaria and North Rhine-Westphalia are locking in low-methoxyl pectin contracts for reduced-sugar reformulations. EFSA additive re-evaluations are forcing dual-formulation dossier submissions from Frankfurt and Hamburg headquarters of major dairy alternative manufacturers. Clean-label certification backlogs at German third-party auditors are extending ingredient verification timelines by four to six months.
United States
FDA GRAS self-affirmation pathways are unlocking direct-to-manufacturer agar-agar supply relationships bypassing conventional distribution markups. USDA organic certification requirements shape procurement priorities for clean-label hydrocolloid segments. Chicago and Minneapolis food ingredient clusters are retrofitting legacy dairy equipment for lower-concentration plant hydrocolloid dosing systems.
South Korea
MFDS-approved health claims for seaweed-derived hydrocolloids are driving concentrated carrageenan demand in probiotic delivery systems. Seoul and Busan functional food manufacturers are expanding gellan gum procurement for transparent dessert gel applications. Domestic fermentation capacity is scaling to serve Japanese and Southeast Asian export channels.
Japan
Precision fermentation for gellan gum production is concentrating in Nagoya and Osaka industrial corridors. METI standards for microbial-derived food additives are validating eighteen-month qualification cycles for dessert and pharmaceutical capsule manufacturers. Tokyo-based trading houses are negotiating direct-procurement contracts with Philippine seaweed processors.
France
Paris and Lyon dairy alternative manufacturers are submitting parallel formulation dossiers to preempt EFSA regulatory contingency requirements. EU REACH-compliant extraction protocols are accelerating aqueous processing investments at certified facilities in Normandy. French industrial bakeries are capturing formulation slots for EU nutrition labeling compliance ahead of 2025 enforcement deadlines.
Vegan Gelatin Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the vegan gelatin value chain. Integrated agricultural processors dominate volume supply through captive seaweed farming and fermentation infrastructure. Specialty chemical distributors occupy technical service-intensive segments requiring formulation support. The competitive arena is consolidating through direct-procurement contract displacement of spot-market purchasing and eighteen-to-thirty-six month offtake agreement negotiation.
Among integrated agricultural processors, Cargill, Incorporated and ADM represent scale-driven supply security archetypes with global sourcing networks. GELITA AG occupies a position within the European specialized gelling agent tier, anchoring regional production capacity. Kerry Group plc exemplifies the integrated flavor-texture systems vector, differentiating through combined hydrocolloid and sensory ingredient portfolios for dairy alternative manufacturers.
| Leading Market Players |
|---|
| Ingredion Incorporated |
| NOW Foods |
| Cargill, Incorporated |
| CP Kelco |
| Tate & Lyle PLC |
| Kerry Group plc |
| GELITA AG |
| ADM |
| Great American Spice Company |
| Others |
Value Network & Pricing Analysis
Multi-year offtake agreements between European dairy alternative manufacturers and Philippine seaweed processors lock in both carrageenan supply access and eighteen-to-thirty-six month price visibility against red seaweed harvest volatility.
Pricing Analysis
EU REACH dictates the pricing tier structure across the vegan gelatin value chain by imposing compliance cost differentials on extraction protocols. Three-tier pricing structure across premium fermentation-grade gellan gum, standard carrageenan, and economy-grade agar-agar reflects certification grade and volume scale. Cost compression in standard-tier carrageenan is intensifying because EFSA's pending refined carrageenan safety re-evaluation triggers inventory hesitation. Food manufacturers exhibit highest price sensitivity in bakery applications facing reduced-sugar reformulation pressures, while pharmaceutical capsule manufacturers show lowest sensitivity for optical-clarity gellan gum.
Supply Chain Analysis
Inventory lead times for red seaweed-derived hydrocolloids extend four to six months during Philippine and Indonesian monsoon disruptions, forcing German manufacturers to carry buffer stocks. Supply concentrates in the Philippines, Indonesia, and Chile for carrageenan and agar-agar feedstock, while Japan and South Korea anchor gellan gum fermentation capacity. Raw material dependencies rest on red seaweed biomass, citrus peel pomace, and microbial fermentation substrates. Single-source vulnerability from coastal farming concentration in Southeast Asia creates structural exposure to climate-driven harvest failures. Distribution runs through integrated agricultural processors supplying direct-procurement contracts to large-scale food manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating among large-scale European dairy alternative manufacturers negotiating direct-procurement contracts, squeezing regional distributor margins and concentrating price-setting leverage with integrated processors.
For Market Incumbents: Compound defensive positioning by locking in backward integration into Philippine and Chilean seaweed farming operations to secure captive carrageenan feedstock against harvest volatility. Expand fermentation capacity in Nagoya and Osaka industrial corridors to capture premium gellan gum demand from pharmaceutical capsule manufacturers. Prioritize EU REACH-compliant extraction protocol investments to maintain formulation access as EFSA additive re-evaluations tighten.
For New Entrants and Emerging Players: Lead with USDA organic certification pathways for agar-agar to bypass conventional distributor markups through direct-to-manufacturer e-commerce channels. Target the reduced-sugar bakery segment in Germany and France where low-methoxyl pectin formulation slots remain open ahead of EU nutrition labeling enforcement. Position through technical service support for clean-label certification backlogs extending German third-party auditor timelines.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated agricultural processors with captive seaweed farming and multi-year offtake agreements. Five-to-ten year viability favors processors consolidating direct-procurement relationships with European dairy alternative manufacturers. Target acquisition archetypes include fermentation-grade gellan gum specialists in Japan and South Korea. Watch EFSA's refined carrageenan safety classification decision as inflection indicator for formulation substitution acceleration toward agar-agar and pectin blends.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seaweed Farming | Captive red seaweed supply from Philippine and Indonesian coastal operations insulates against harvest-driven price spikes. |
| Precision Fermentation Scale-Up | Microbial-derived gellan gum production in Nagoya and Osaka achieves concentration efficiency that compresses freight costs. |
| EU REACH-Compliant Extraction Investment | Certified aqueous processing facilities in Normandy secure formulation access amid tightening ECHA registration requirements. |
| Direct-Procurement Contract Expansion | Eighteen-to-thirty-six month offtake agreements with French and Italian manufacturers displace spot-market purchasing. |
| Clean-Label Certification Fast-Track | Expedited third-party verification in Germany reduces four-to-six month backlog delays for plant-derived hydrocolloid launches. |
Research Methodology
Desk research of EFSA additive evaluation databases, EU REACH registration filings, and MFDS health claim approvals preceded structured interviews with procurement directors at German dairy alternative manufacturers, technical R&D leads at Japanese fermentation facilities, and third-party certification auditors in France. Primary fieldwork with Philippine seaweed farming cooperatives and Chilean coastal processors validated harvest volume assumptions. Secondary sources included customs trade data for hydrocolloid imports, SEC filings from integrated agricultural processors, and ECHA substance registration databases. Bottom-up volume modeling across product type, application, and end-user segments triangulated against top-down market sizing from regulatory filing trends.
Variance decomposition across the projection horizon isolates volume drivers by segmentation dimension: product type tier, application heat-stability requirement, end-user equipment retrofit capability, and regional regulatory enforcement intensity. CAGRs derive from segment-level growth rate blending weighted by base-year volume shares. Industry-specific forecast inputs incorporate EFSA re-evaluation timeline scenarios for refined carrageenan and EU Green Deal sourcing mandate compliance trajectories.
Underlying assumptions cover sustained EU REACH enforcement, stable Philippine and Indonesian coastal farming conditions, and continued dairy alternative formulation expansion, with deviation risk concentrated in EFSA safety classification changes and red seaweed harvest disruptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Oat-Based Cereals Market
Plant Based Food
Vegan Spaghetti Market
Plant Based Food
Enzyme-Based Plant Protein Market
Plant Based Food
Plant-Based Beef Market
Plant Based Food
Vegan Meat Alternatives Market
Plant Based Food
Meat Substitutes Market
Plant Based Food
Faba Bean Protein Market
Plant Based Food
United States Meat Substitutes Market
Plant Based Food
Plant-Based Chorizo Market
Plant Based Food
Veggie Meals Market
Plant Based Food
United Kingdom Plant Protein Market
Plant Based Food
Vegan Flour Market
Plant Based Food
Plant-Based Flour Market
Plant Based Food
Plant-Based Bars Market
Plant Based Food
Organic Pea Protein Market
Plant Based Food
Vegan Dips Market