
 Burdock Root Extract Market | 2026-2036
Burdock Root Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Burdock Root Extract Market Insights
China is tilting toward larger-scale botanical extraction capacity as domestic herbal medicine demand rises and export orders from European cosmetics houses expand. Taiyo Life Sciences leverages its Japan-based R&D infrastructure to supply high-purity arctiin fractions for functional food applications. Naturalin BioResources anchors its position through backward integration into organic burdock cultivation across Hunan province. Sabinsa Corporation competes on phytochemical standardization, publishing monograph-grade specifications that pharmaceutical buyers require.
Burdock root extract comprises bioactive compounds including arctin, arctigenin, and inulin, typically standardized to specific polyphenol concentrations through ethanol or supercritical CO2 extraction for use in dermatological, nutraceutical, and gastrointestinal therapeutic formulations. Powder formats dominate volume shipments to dietary supplement contract manufacturers, while liquid extracts command premium positioning in cosmeceutical serums where solubility and sensory profile determine formulation compatibility. The pharmaceutical application segment sustains the most rigorous purity thresholds, with pharmacopeial-grade extracts requiring residual solvent controls that filter out smaller solvent-based processors.
FDA dietary supplement Current Good Manufacturing Practices and EMA herbal medicine product directives impose identity-testing and heavy-metal limits that reshape supplier qualification criteria across export markets. ISO 17025-accredited laboratories now function as gatekeepers for market access, with certificates of analysis replacing commercial relationships as the primary buyer filter. Stakeholders must monitor evolving pharmacovigilance reporting obligations for botanical ingredients in both European and North American jurisdictions, as adverse event databases increasingly influence retailer procurement blacklists.
Market Dynamics
Cosmetic formulators are accelerating botanical ingredient substitution programs as clean-label mandates harden across EU and North American retail channels, compressing synthetic preservative tolerance thresholds and elevating pharmacopeial-grade extract specifications.
Growth Catalysts
- EU Cosmetics Regulation Article 15:The ban on animal-tested ingredients forces formulators toward validated botanical alternatives, with burdock-derived antimicrobials displacing paraben systems in scalp-care and anti-aging products.
- Supercritical CO2 extraction:This solvent-free technology unlocks pharmaceutical-grade arctiin concentrations without residual ethanol, opening FDA-compliant pathways for nutraceutical capsule manufacturers.
- German personal care clusters:Clean-label brand concentration around Hamburg and Munich generates concentrated demand for ISO 17025-certified organic extracts with full supply-chain traceability.
Market Restraints
- Arable land competition:Burdock cultivation competes with staple crops across Hunan and Shandong provinces, creating input cost volatility during regional drought cycles.
- Heavy-metal bioaccumulation:Root systems concentrate cadmium and lead from contaminated soils, forcing processors to reject 15-20% of raw material harvests from non-certified organic plots.
- Synthetic peptide substitution:Laboratory-derived anti-aging actives from DSM and BASF achieve comparable collagen-stimulation metrics at lower batch-to-batch variance, threatening standardized botanical positioning.
Strategic Opportunities
- South Korean functional food channel:MFDS novel food ingredient approvals for arctigenin-fortified beverages remain underpenetrated relative to Japan and create first-mover positioning for extract suppliers with clinical dossiers.
- EMA herbal medicine product registration:The simplified traditional use registration pathway offers 15-year market exclusivity for gastrointestinal indication extracts meeting THMPD quality standards.
- Blockchain-IoT integration:Real-time soil-moisture and phytochemical tracking from farm to extraction facility enables premium pricing for fully documented organic batches.
Industry Challenges
- Phytochemist talent scarcity:The intersection of analytical chemistry and botanical taxonomy lacks formal training pipelines, forcing processors to poach from pharmaceutical QC departments at 40% wage premiums.
- Dual certification timelines:Simultaneous USDA Organic and EU Organic logo approvals require 18-24 month documentation cycles that freeze working capital in pre-qualified inventory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Burdock Root Extract Market |
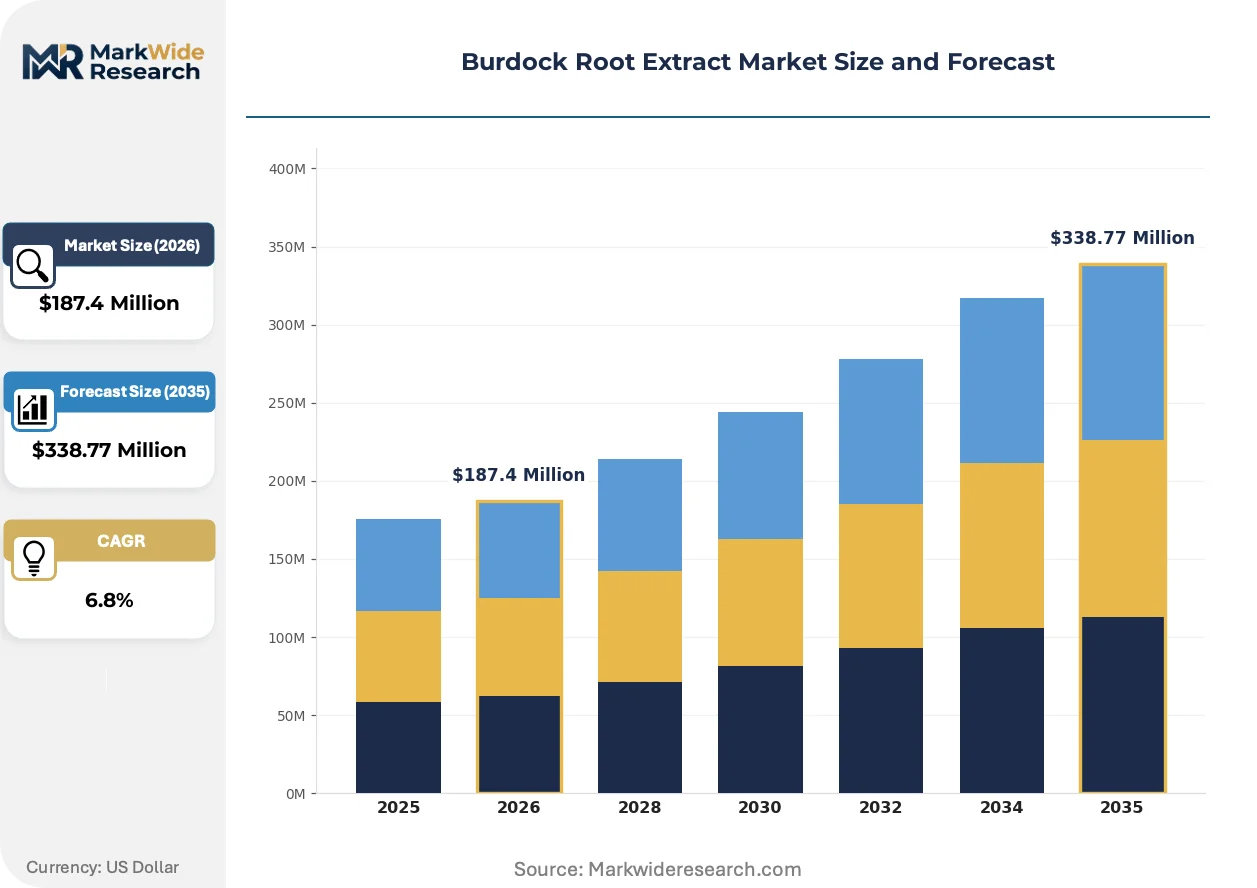
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Capsule, Tea Application: Cosmetics, Dietary Supplements, Food & Beverages, Pharmaceuticals End User: Health-conscious Consumers, Cosmetics Manufacturers, Nutraceutical Companies, Pharmacies Distribution Channel: Online Sales, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | Taiyo Life Sciences, Naturalin BioResources, Sabinsa Corporation, Indena, NOW Foods, Arjuna Natural Extracts Ltd., LGC Standards, NutraMax Laboratories, Akay Natural Extract, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Burdock Root Extract Market Trends and Innovations
Extraction technology convergence with digital quality assurance systems is compressing batch release timelines while hardening compliance documentation. Formulation science advances are unlocking new delivery formats beyond traditional powder and liquid concentrates.
Supercritical CO2 extraction with inline near-infrared spectroscopy is collapsing traditional quality-control bottlenecks. Cosmetic contract manufacturers in Italy and France are adopting these integrated systems to reduce batch release from 14 days to 72 hours. The structural compression of testing timelines enables just-in-time inventory models that reduce working capital requirements by 30-40% for mid-scale processors.
REACH Annex XIV authorization requirements for residual solvents are forcing ethanol-based extractors toward closed-loop recovery systems or solvent substitution. The industrial consequence is a bifurcation of the supplier base: capital-intensive supercritical operators capture pharmaceutical contracts while solvent-dependent processors retreat to feed-grade applications. German and Dutch cosmetic houses are responding by consolidating supplier panels to three qualified vendors with full solvent-trace documentation.
Direct-to-brand procurement is displacing traditional distributor intermediaries for certified organic extracts. Clean-label personal care brands in California and New York are establishing captive supply agreements with Hunan-based organic cultivators, bypassing Tokyo and Rotterdam trading houses. This channel compression is most visible in the scalp-care segment, where founders with chemistry backgrounds conduct their own supplier audits and specify extraction parameters in purchase contracts.
Burdock Root Extract Market Segmentation
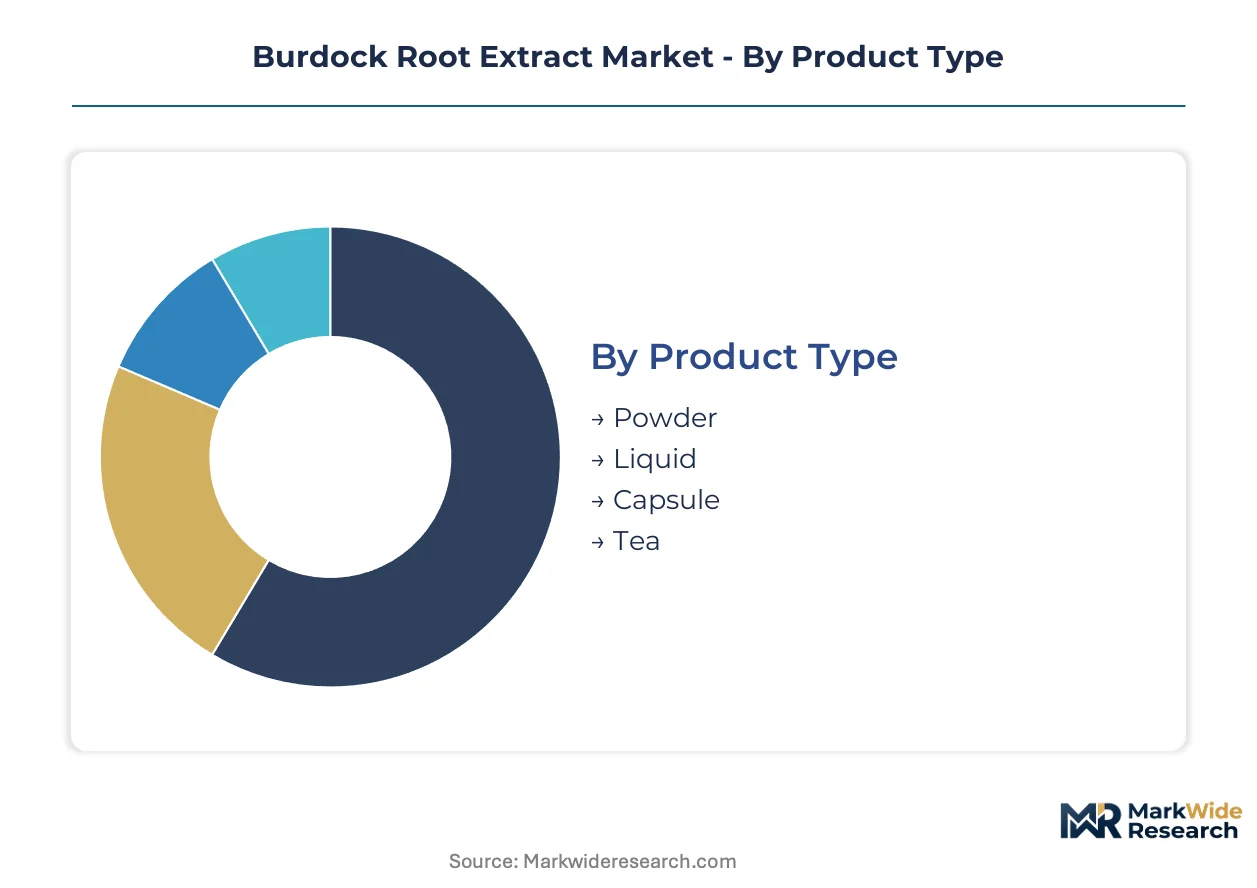
Segmentation in burdock root extract markets reflects divergent purity requirements across therapeutic and cosmetic applications. Each category channels distinct procurement behaviors, from pharmacopeial-grade pharmaceutical sourcing to sensory-optimized cosmetic formulation.
Product Type:
Cosmetic serums demand solubility-optimized formats, while nutraceutical manufacturers prioritize stability and dosing precision in dry delivery systems.
- Powder:Spray-dried or freeze-dried concentrates standardized to polyphenol content serve contract manufacturers of dietary supplements. German encapsulation facilities in Bavaria specify particle size distributions below 100 microns for uniform capsule fill weights, rejecting batches with moisture content exceeding 5%.
- Lipuid:Hydroalcoholic or glyceritic solutions enable rapid incorporation into water-based cosmetic matrices. French and Italian formulators source propylene glycol-free variants for clean-label scalp treatments, paying 15-25% premiums for supercritical CO2-derived extracts with zero residual ethanol.
- Capsule:Pre-measured gelatin or HPMC shells containing standardized arctiin doses target direct-to-consumer nutraceutical channels.
- Tea:Cut-and-sifted root material or instant granules serve traditional medicine practitioners and functional beverage developers.
Established volume favors powder; emerging adoption favors liquid.
Application:
Regulatory stringency escalates from cosmetic to pharmaceutical endpoints, filtering supplier qualification tiers.
- Cosmetics:Anti-aging and scalp-care formulations leverage burdock's antimicrobial polyphenols as paraben replacements. Hamburg-based clean-label brands require ISO 17025-certified organic extracts with blockchain-traceable supply chains, consolidating procurement to three qualified vendors per brand.
- Dietary Supplements:Gastrointestinal and detoxification positioning drives capsule and tablet demand. FDA Current Good Manufacturing Practices compliance separates contract-manufacturable grades from retail-ready finished goods, with identity testing adding 8-12% to raw material costs.
- Food & Beverages:Functional beverage applications in South Korea and Japan utilize arctigenin-fortified formulations following novel food approvals.
- Pharmaceuticals:Pharmacopeial-grade extracts for gastrointestinal indications require EMA herbal medicine product directive compliance, with residual solvent controls and heavy-metal limits excluding smaller processors from hospital procurement channels.
Pharmaceutical margins concentrate supply; cosmetic volumes expand fastest.
End User:
Procurement sophistication varies from ingredient specification by chemistry-trained founders to commodity purchasing by retail distributors.
- Health-conscious Consumers:Direct purchasers of finished supplements and teas prioritize organic certification and transparent sourcing, driving single-origin marketing claims.
- Cosmetics Manufacturers:R&D departments in California and New York specify extraction parameters in purchase contracts, conducting independent supplier audits that bypass traditional Tokyo and Rotterdam trading intermediaries.
- Nutraceutical Companies:Contract manufacturers demand certificates of analysis from ISO 17025-accredited laboratories, replacing relationship-based procurement with documentation-gated supplier panels.
- Pharmacies:Hospital and retail pharmacy procurement requires EMA-registered traditional herbal medicinal products or FDA-compliant dietary supplements, with pharmacovigilance reporting obligations influencing retailer blacklists.
Manufacturer specification depth determines premium capture; consumer direct channels scale volume.
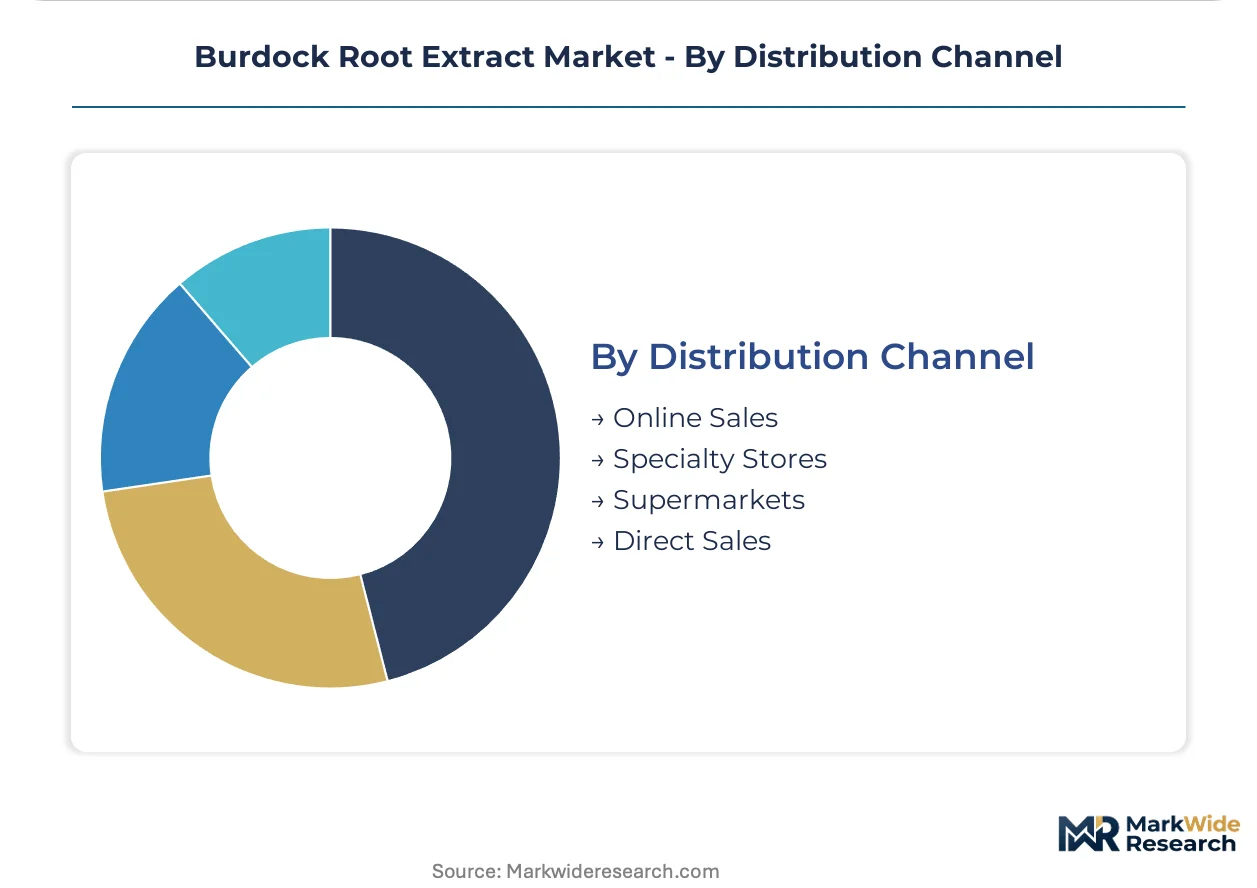
Distribution Channel:
Channel selection reflects certification requirements and buyer technical sophistication.
- Online Sales:Direct-to-consumer platforms enable clean-label brands to communicate supply-chain transparency, with California-based scalp-care startups leveraging founder chemistry credentials to justify premium positioning.
- Specialty Stores:Health food retailers and apothecaries stock pharmacopeial-grade extracts for knowledgeable self-medicating consumers.
- Supermarkets:Mass-market placement requires price-competitive positioning, favoring conventional over certified organic grades.
- Direct Sales:Captive supply agreements between Hunan organic cultivators and European cosmetic houses eliminate intermediary margins while locking in multi-year volume commitments.
Direct sales concentrate high-value contracts; online channels fragment price discovery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EMA herbal medicine product directives anchor European demand, while FDA dietary supplement guidelines shape North American procurement protocols. China and Japan concentrate extraction capacity and botanical R&D investment respectively.
Germany
Clean-label personal care brands in Hamburg and Munich drive concentrated demand for ISO 17025-certified organic extracts. EU Cosmetics Regulation Article 15 compliance mandates validate botanical antimicrobials as paraben replacements. Bavarian encapsulation facilities enforce particle size specifications below 100 microns for dietary supplement contract manufacturers.
United States
California and New York-based cosmetics manufacturers specify extraction parameters directly in purchase contracts, bypassing traditional trading intermediaries. FDA Current Good Manufacturing Practices impose identity-testing and heavy-metal limits that reshape supplier qualification. Direct-to-consumer scalp-care startups leverage founder chemistry credentials to justify premium positioning in online channels.
China
Domestic herbal medicine demand rises alongside export orders from European cosmetics houses. Hunan province organic cultivation supplies backward-integrated processors with traceable raw material. Shandong and Hunan processors face arable land competition with staple crops during regional drought cycles.
Japan
Taiyo Life Sciences leverages domestic R&D infrastructure to supply high-purity arctiin fractions for functional food applications. METI standards and PMDA novel food frameworks govern extract commercialization pathways. Tokyo-area trading houses face displacement as European buyers pursue direct procurement relationships with Chinese cultivators.
South Korea
MFDS novel food ingredient approvals for arctigenin-fortified beverages remain underpenetrated relative to Japan. Functional beverage developers seek clinical dossiers to secure first-mover positioning. Seoul-based formulation houses import standardized extracts for cosmeceutical serum production targeting domestic and export markets.
Burdock Root Extract Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another, producing a bifurcated supplier base. Supercritical CO2 operators capture pharmaceutical contracts through pharmacopeial-grade compliance, while solvent-dependent processors retreat to feed-grade applications. Three archetypes dominate: R&D-driven Japanese specialists, backward-integrated Chinese cultivators, and phytochemical standardization leaders. Competitive moves center on captive supply agreements and ISO 17025 laboratory accreditation.
Within the R&D-specialist tier, Taiyo Life Sciences exemplifies Japan-based high-purity fraction supply for functional food channels. Naturalin BioResources anchors the backward-integrated archetype through organic cultivation control in Hunan province. Sabinsa Corporation occupies the standardization-leader position, publishing monograph-grade specifications that pharmaceutical buyers require for EMA compliance.
| Leading Market Players |
|---|
| Taiyo Life Sciences |
| Naturalin BioResources |
| Sabinsa Corporation |
| Indena |
| NOW Foods |
| Arjuna Natural Extracts Ltd. |
| LGC Standards |
| NutraMax Laboratories |
| Akay Natural Extract |
| Others |
Pricing and Supply Chain Analysis
Hunan province organic cultivation clusters anchor upstream supply for European cosmetic houses, concentrating margin capture with ISO 17025-certified processors who command 15-25% premiums over conventional grades. This geographic concentration of certified organic raw material shapes downstream pricing power, as German clean-label brands consolidate procurement to three qualified vendors with full solvent-trace documentation.
Pricing Analysis
Price spreads between supercritical CO2-derived and ethanol-extracted grades widen from Hamburg to California, with zero-residual-solvent liquid extracts capturing premium positioning in scalp-care formulations. Three-tier pricing structure across pharmacopeial-grade, certified organic, and conventional feed-grade segments reflects certification investment and extraction technology differentiation. Cost compression in solvent-dependent tiers is intensifying because REACH Annex XIV authorization requirements force capital migration toward closed-loop recovery systems. Contract manufacturers of dietary supplements exhibit highest price sensitivity, while R&D-led cosmetics houses prioritize batch-to-batch consistency over unit cost.
Supply Chain Analysis
Extended payment terms from German cosmetic houses are reshaping working capital structures for Hunan-based organic cultivators, with supply-chain finance facilities emerging as competitive differentiators. Raw material sourcing draws from Hunan and Shandong province cultivation bases, with arctiin-rich rootstock and certified organic acreage as critical inputs. Single-source vulnerability concentrates in supercritical CO2 equipment supply, where German and Italian machinery providers face 18-24 month order backlogs. Distribution runs through direct captive agreements between cultivators and European cosmetic brands, displacing Tokyo and Rotterdam trading intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Phytochemist talent scarcity constrains batch release velocity, with processors poaching from pharmaceutical QC departments at wage premiums that signal structural capability gaps. This analytical chemistry-botanical taxonomy intersection determines which suppliers qualify for pharmacopeial-grade contracts versus commodity feed-grade retreat.
For Market Incumbents: Insulate market position by deepening backward integration into Hunan organic cultivation with blockchain-IoT traceability systems that preempt buyer audit requirements. Acquire ISO 17025 laboratory accreditation to capture EMA herbal medicine product registration pathways before smaller processors face exclusion from hospital procurement channels. Synthetic peptide substitution from DSM and BASF threatens standardized botanical positioning in anti-aging applications. For New Entrants and Emerging Players: Build out clinical dossier capabilities to secure MFDS novel food ingredient approvals for arctigenin-fortified beverages in South Korea, where functional beverage penetration lags Japan. Target direct-to-brand procurement relationships with California scalp-care startups by offering specification-grade supercritical CO2 extracts with founder-conducted audit protocols. White-space positioning centers on pharmacopeial-grade gastrointestinal indication extracts through EMA simplified traditional use registration. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed supercritical CO2 operators holding pharmaceutical contracts but lacking organic certification breadth. Long-term viability over the next decade hinges on regulatory moat depth around EMA registrations and FDA dietary supplement Current Good Manufacturing Practices compliance. Acquisition target archetype: mid-scale processors with captive organic cultivation and pending ISO 17025 accreditation. Watch for adverse event database entries influencing retailer procurement blacklists as inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Cultivation | Hunan province acreage control secures traceable raw material for EU Cosmetics Regulation compliance. |
| ISO 17025 Laboratory Accreditation | Certificates of analysis replace commercial relationships as primary buyer filter in German procurement. |
| EMA Traditional Herbal Medicine Registration | Simplified registration pathway offers market exclusivity for gastrointestinal indication extracts. |
| Blockchain-IoT Supply Chain Integration | Real-time phytochemical tracking enables premium pricing for fully documented organic batches. |
| Supercritical CO2 Capacity Expansion | Solvent-free technology unlocks pharmaceutical-grade arctiin concentrations for FDA-compliant nutraceuticals. |
Research Methodology
Initial hypotheses were tested against primary input from extraction technology directors, cosmetic formulation chemists, regulatory affairs specialists at botanical extract suppliers, and procurement managers at German clean-label brands, then refined through secondary validation. FDA dietary supplement guidance documents, EMA herbal medicine product directives, EU Cosmetics Regulation technical files, and customs trade data for burdock root raw material shipments provided foundational datasets. Bottom-up volume modeling from cultivation acreage and extraction capacity was triangulated against top-down demand estimates from end-use application segments.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation modeled by product format, application endpoint, and extraction technology tier. CAGRs were derived from weighted capacity expansion schedules and end-use adoption curves. Forecast inputs incorporated supercritical CO2 equipment installation pipelines, organic certification approval timelines, and MFDS novel food ingredient submission trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive moves by capital-intensive supercritical operators or sudden EMA regulatory reinterpretations would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Plant-Based Wafer Biscuits Market
Plant Based Food
Vegan Flavor Market
Plant Based Food
Packed Vegan Foods Market
Plant Based Food
Africa Soy Beverages Market
Plant Based Food
Plant-Based Burger Market
Plant Based Food
Plant-Based Milk Alternatives Market
Plant Based Food
Plant Based Cheese Market
Plant Based Food
Canada Plant Protein Market
Plant Based Food
Vegan Noodles Market
Plant Based Food
Vegan Pasta Market
Plant Based Food
Plant-Based Vegan Eggs Market
Plant Based Food
North America Rice Protein Market
Plant Based Food
Textured Pea Protein Market
Plant Based Food
Meatless Meat Market
Plant Based Food
Germany Plant Protein Market
Plant Based Food
South America Soy Beverages Market