
 Plant-Based Protein Food Market | 2026-2036
Plant-Based Protein Food Market Size, Share, and Industry Trends Forecast 2026-2036
Plant-Based Protein Food Market Insights
Subscription-based replenishment models for plant-based protein products is hardening into a core revenue layer for direct-to-consumer brands. Beyond Meat Inc. leverages retail shelf-space negotiations to sustain visibility in conventional grocers. Impossible Foods Inc. anchors its position through foodservice partnerships with national restaurant chains. Danone SA competes in dairy-alternative extensions using fermented protein bases.
Plant-based protein food encompasses formulations derived from legumes, oilseeds, and grains that deliver amino acid profiles matching or approximating animal proteins, typically processed through extrusion, fermentation, or mechanical separation to achieve functional textures. These products serve commercial food manufacturing and retail channels seeking to replace or reduce animal-derived ingredients. Pea protein isolates command the largest volume share among ingredient categories due to their neutral flavor and allergen-friendly profile. Meat alternatives represent the fastest-growing application segment as formulation science improves chew and moisture retention. Online retailers are capturing disproportionate growth in distribution channel dynamics, though supermarkets still hold the dominant transaction volume.
FDA nutrition labeling requirements and EFSA novel food authorization processes shape product development timelines and market access pathways for new entrants. USDA organic certification and EU Green Deal agricultural standards influence sourcing decisions and consumer price tolerance across North American and European supply chains. Stakeholders must monitor evolving protein quality scoring methodologies and carbon accounting rules that will determine which ingredient sources retain formulation preference.
Market Dynamics
Precision fermentation technology is compressing production economics for alternative proteins while FDA and EFSA labeling frameworks simultaneously clarify protein content claims and extend compliance timelines for new entrants.
Growth Catalysts
- EFSA Novel Food Authorization:The streamlined safety assessment pathway accelerates market access for fermented protein ingredients across European retail channels.
- Foodservice Menu Expansion:National restaurant chains in the United States and United Kingdom are embedding plant-based proteins into permanent core offerings rather than limited-time promotions.
- Pea Protein Isolate Supply:Processing capacity concentration in Canada and France secures allergen-friendly raw material flows for formulation houses.
Market Restraints
- Input Cost Volatility:Yellow pea and fava bean prices fluctuate with Canadian prairie drought cycles, squeezing margin structures for isolate producers.
- Technical Texture Limitations:Extrusion technologies struggle to replicate collagen-derived chew in whole-muscle analogs above 20% protein concentration.
- Regulatory Friction:USDA organic certification requirements for non-GMO sourcing constrain supply base flexibility during volume ramp phases.
Strategic Opportunities
- Brazilian Retail Penetration:Supermarket chains in São Paulo and Rio de Janeiro lack dedicated plant-based protein sections, creating first-mover shelf space advantages.
- Hybrid Protein Convergence:Blending precision-fermented dairy proteins with plant bases opens formulation space in sports nutrition and infant formula adjacent categories.
- Direct-to-Consumer Subscription:Replenishment models bypass traditional wholesale markups while capturing recurring revenue and consumption data.
Industry Challenges
- Flavor Chemist Talent Scarcity:Formulation teams lack sufficient expertise in masking bitter off-notes from high-concentration legume proteins without sugar load increases.
- Carbon Accounting Verification:Divergent lifecycle assessment methodologies between ISO 14040 and EU Green Deal standards complicate consumer-facing environmental claims.
- Extrusion Equipment Lead Times:Twin-screw processing line delivery schedules from European manufacturers extend 14-18 months, throttling capacity expansion timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant-Based Protein Food Market |
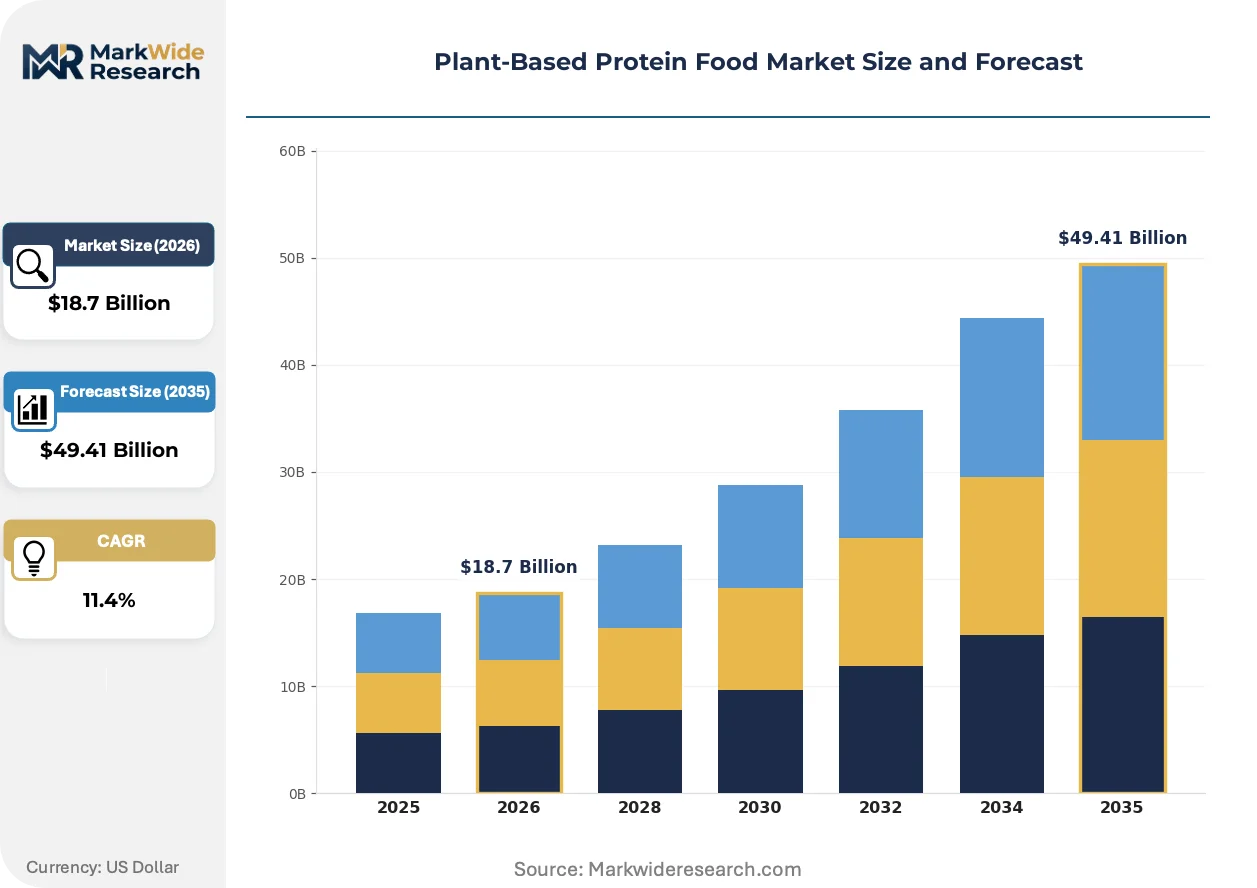
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tofu, Tempeh, Seitan, Pea Protein End User: Fitness Enthusiasts, Vegans, Vegetarians, Health-Conscious Consumers Application: Meat Alternatives, Dairy Alternatives, Snack Foods, Protein Supplements Distribution Channel: Supermarkets, Health Food Stores, Online Retailers, Specialty Stores |
| Companies Covered | Beyond Meat Inc., Impossible Foods Inc., Garden Protein International Inc., Lightlife Foods Inc., Danone SA, Nestlé S.A., Conagra Brands, Monde Nissin Corporation, Tyson Foods Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant-Based Protein Food Market Trends and Innovations
Bioprocess engineering advances and regulatory clarity are converging to reshape competitive positioning around protein quality scoring and carbon footprint transparency rather than taste parity alone.
Precision fermentation is integrating recombinant protein production into existing brewery and bioethanol infrastructure, repurposing anaerobic fermentation tanks and downstream purification skids. Contract manufacturers in the Netherlands and United States are retrofitting idled biofuel capacity to produce heme and whey-identical proteins at sub-$10 per kilogram cost structures. This asset-light expansion model is compressing capital barriers for ingredient suppliers seeking scale without greenfield construction.
EU Green Deal agricultural standards are binding farm-level carbon accounting to finished product labeling, forcing reformulation decisions toward lower-methane feedstocks. The Farm to Fork Strategy mandates 25% organic farming coverage by 2030, tightening conventional pea and soy supply availability. Protein isolate buyers are responding with multi-year offtake agreements tied to regenerative agriculture verification.
Restaurant procurement teams are unbundling protein specifications from bundled meat-category purchasing, creating standalone plant-based vendor tiers with separate RFP cycles. This shift decouples volume commitments from legacy beef and poultry contracts, enabling dedicated supplier performance scorecards. The United Kingdom foodservice sector shows the clearest execution of this model, with contract caterers and pub chains issuing separate sustainability-weighted tenders.
Plant-Based Protein Food Market Segmentation
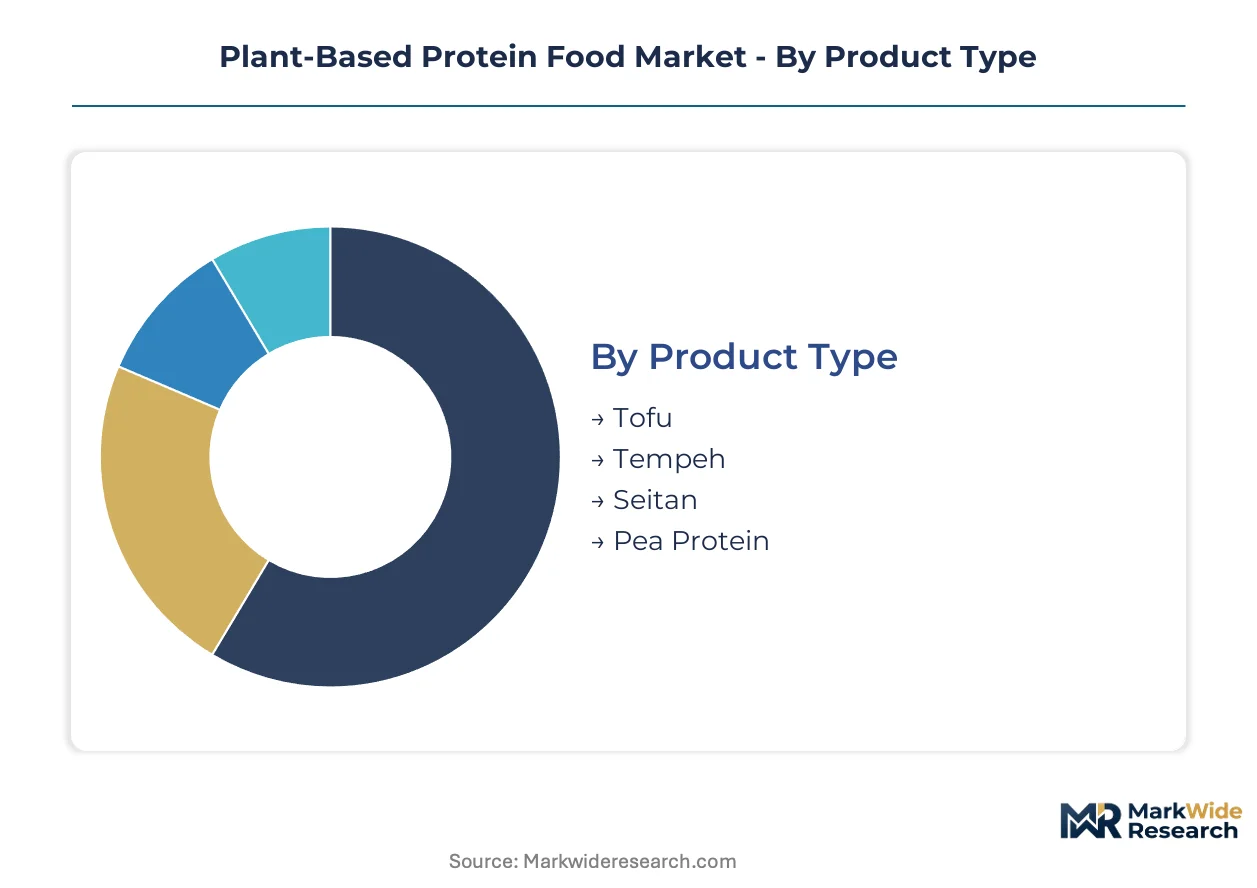
Plant-based protein food segmentation reveals distinct capital requirements across production technologies, from low-investment tofu fermentation to high-cost precision fermentation infrastructure. Understanding these investment tiers helps stakeholders allocate resources toward segments matching their balance sheet capacity and risk tolerance.
Product Type:
Pea protein isolate production demands the heaviest upfront capital, with extraction facilities requiring multi-million dollar wet-fractionation lines and spray-drying towers.
- Pea Protein:Isolates and concentrates achieve 80-90% protein content through alkaline extraction and membrane filtration. Demand concentrates in sports nutrition formulations across Germany and the United States, where EFSA novel food approvals and FDA GRAS notifications have cleared regulatory pathways for high-concentration applications. Input cost volatility from Canadian prairie drought cycles squeezes margin structures for isolate producers.
- Seitan:Vital wheat gluten forms the protein base through simple hydration and kneading, yielding a fibrous meat-like texture. Foodservice operators in the United Kingdom favor seitan for its superior chew and moisture retention in hot-held applications, though celiac disease prevalence limits retail expansion in European markets with strict allergen labeling.
- Tofu:Soybean curd coagulated with calcium sulfate or magnesium chloride requires minimal equipment investment. Traditional production dominates Asian supply chains with established fermentation expertise.
- Tempeh:Whole soybean fermentation using Rhizopus oligosporus mold delivers complete protein with fiber retention. Indonesian-origin production maintains cost advantages through ambient-temperature fermentation.
Pea protein absorbs the bulk of installed capacity; seitan is expanding most quickly among traditional formats.
End User:
Customer acquisition costs vary sharply across motivation profiles, with fitness enthusiasts commanding premium pricing tolerance for performance-verified formulations.
- Fitness Enthusiasts:Protein-per-serving metrics and leucine content verification drive purchasing decisions. Sports nutrition brands in the United States target this segment with isolate-based powders and ready-to-drink formats, where subscription replenishment models capture recurring revenue and consumption data.
- Health-Conscious Consumers:Cholesterol reduction and cardiovascular wellness claims influence basket composition. Retail distribution in Germany and the United Kingdom emphasizes clean-label positioning with minimal ingredient lists.
- Vegans:Ethical alignment and complete amino acid profiles shape loyalty. This segment accepts taste trade-offs unavailable to flexitarian converts.
- Vegetarians:Lacto-ovo dietary patterns create hybrid protein preferences, often combining dairy and plant sources in meal planning.
Fitness enthusiasts generate the highest per-capita expenditure; health-conscious consumers represent the steepest expansion trajectory as formulation science improves palatability.
Application:
Meat alternatives command the most complex R&D investment, requiring extrusion technology and flavor masking systems unavailable to simpler applications.
- Meat Alternatives:Whole-muscle analogs and ground formats utilize high-moisture extrusion to achieve fibrous textures. National restaurant chains in the United States and United Kingdom embed these proteins into permanent core offerings rather than limited-time promotions, driving volume commitments from dedicated supplier tiers.
- Protein Supplements:Powders and bars prioritize solubility and mouthfeel over structural integrity. Direct-to-consumer brands bypass traditional wholesale markups while capturing consumption patterns.
- Dairy Alternatives:Fermented bases from pea and oat require enzymatic treatment to reduce beany off-notes. Danone SA competes in this space with extended fermentation protocols.
- Snack Foods:Puffed and extruded formats emphasize shelf stability and portability. Lower protein concentrations reduce formulation complexity.
Meat alternatives dominate capital deployment; protein supplements are gaining share fastest through e-commerce penetration.
Distribution Channel:
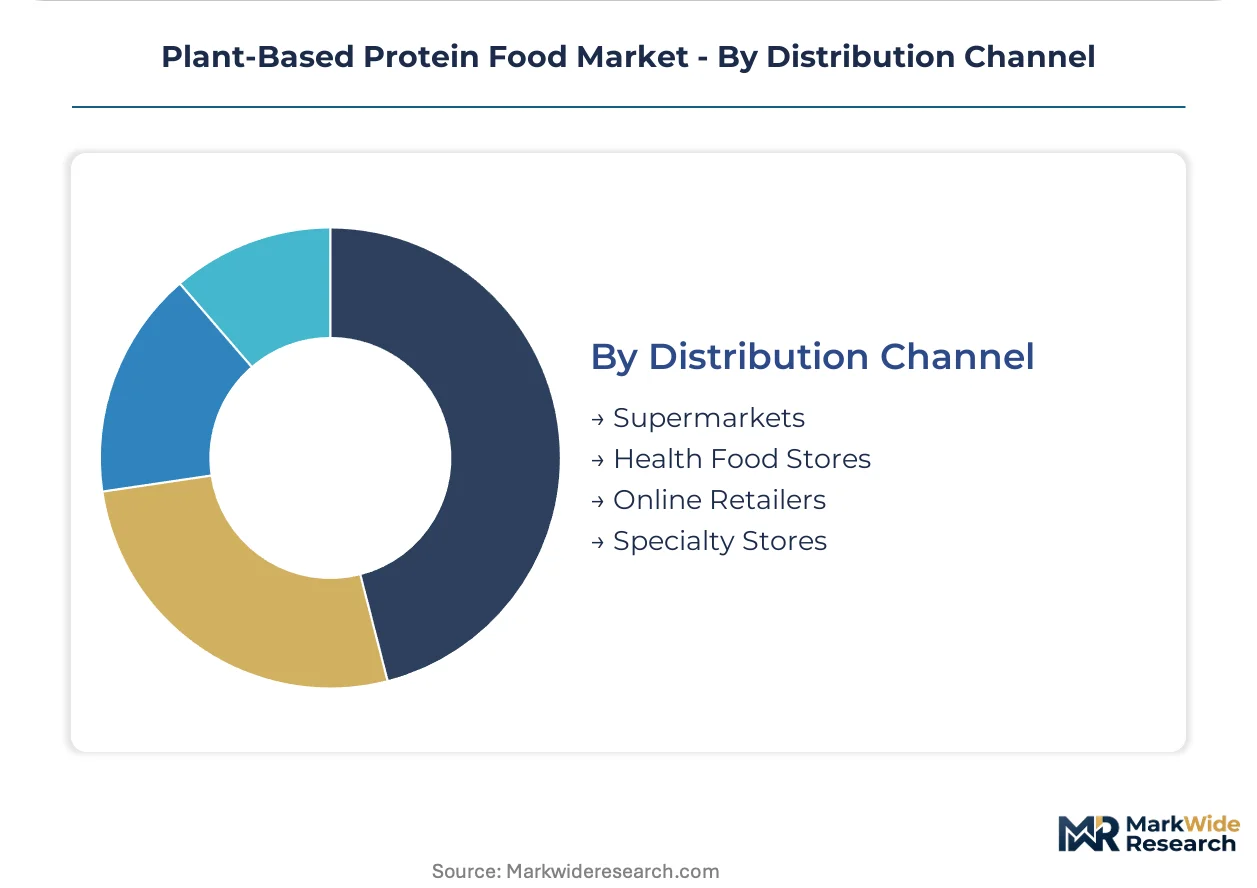
Supermarket slotting fees and promotional allowances create the steepest barrier to entry, favoring established brands with trade marketing budgets.
- Supermarkets:Conventional grocers in Germany, the United States, and the United Kingdom maintain dominant transaction volume through dedicated plant-based sections. Beyond Meat Inc. leverages retail shelf-space negotiations to sustain visibility against private-label encroachment.
- Online Retailers:E-commerce platforms capture disproportionate growth with lower customer acquisition costs and richer data capture. Subscription-based replenishment models harden into a core revenue layer for direct-to-consumer brands.
- Health Food Stores:Specialty retailers emphasize organic certification and non-GMO verification. USDA organic requirements constrain supply base flexibility during volume ramp phases.
- Specialty Stores:Ethnic grocers and gourmet outlets serve niche taste preferences and imported formats. Limited scale restricts national brand presence.
Supermarkets retain the majority of physical infrastructure investment; online retailers are climbing the fastest with asset-light expansion models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The San Francisco Bay Area anchors precision fermentation infrastructure development, with contract manufacturers retrofitting idled bioethanol capacity to produce recombinant proteins at sub-$10 per kilogram cost structures.
United States
Fitness enthusiasts drive isolate-based powder demand through subscription replenishment models. FDA GRAS notifications clear regulatory pathways for high-concentration pea protein applications. Chicago and Austin host dedicated extrusion R&D facilities where foodservice chains test whole-muscle analog formulations.
Germany
Health-conscious consumers prioritize clean-label positioning with minimal ingredient lists. EFSA novel food authorization accelerates fermented protein ingredient market access. The Rhine-Ruhr corridor concentrates wet-fractionation processing capacity for allergen-friendly raw material flows.
United Kingdom
Contract caterers and pub chains issue separate sustainability-weighted tenders for plant-based proteins. EU Green Deal agricultural standards bind farm-level carbon accounting to finished product labeling. London foodservice procurement teams unbundle protein specifications from bundled meat-category purchasing.
Canada
Yellow pea and fava bean processing capacity concentrates in prairie provinces, securing raw material flows for formulation houses. USDA organic certification requirements constrain supply base flexibility during volume ramp phases. Manitoba and Saskatchewan face margin pressure from drought cycle input cost volatility.
Brazil
Supermarket chains in São Paulo and Rio de Janeiro lack dedicated plant-based protein sections, creating first-mover shelf space advantages. The country's national food safety regulator evaluates novel protein authorization frameworks. Southeast metropolitan retail corridors show earliest foodservice menu embedding of permanent core offerings.
Plant-Based Protein Food Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the plant-based protein food market. The structure fragments between integrated ingredient suppliers owning extraction infrastructure and brand marketers outsourcing manufacturing to contract facilities. Three archetypes dominate: precision fermentation technology licensors, legacy food conglomerates extending into dairy alternatives, and direct-to-consumer pure-plays capturing subscription revenue. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with extrusion equipment lead times extending 14-18 months.
Among US-based innovators, Beyond Meat Inc. and Impossible Foods Inc. occupy positions as category-defining anchors, while Danone SA represents the European conglomerate archetype extending fermented protein expertise into adjacent categories. These three exemplify divergent strategic postures: pure-play brand building, foodservice partnership anchoring, and dairy-alternative portfolio extension.
| Leading Market Players |
|---|
| Beyond Meat Inc. |
| Impossible Foods Inc. |
| Garden Protein International Inc. |
| Lightlife Foods Inc. |
| Danone SA |
| Nestlé S.A. |
| Conagra Brands |
| Monde Nissin Corporation |
| Tyson Foods Inc. |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up pea protein specialists concentrate extraction capacity in Canadian prairie provinces and northern France, creating disciplined pricing power through multi-year offtake agreements tied to regenerative agriculture verification while constraining spot-market flexibility for smaller formulation houses.
Pricing Analysis
Protein-per-serving value metrics anchor pricing tiers across sports nutrition and foodservice channels. Three-tier pricing structure across premium isolate grades, standard concentrates, and economy blended flours differentiates on EFSA novel food authorization status and leucine content verification. Pricing pressure stems from yellow pea input cost volatility during Canadian drought cycles. Fitness enthusiasts show lowest price sensitivity for performance-verified isolates; foodservice procurement teams drive hardest bargain on volume commitments.
Supply Chain Analysis
USDA organic certification and EU Green Deal regenerative agriculture standards gate supplier qualification, forcing multi-year verification investments before volume allocation. Wet-fractionation capacity concentrates in Canada, France, and the Netherlands. Yellow pea, fava bean, and precision-fermented heme protein constitute critical input dependencies. Single-source vulnerability runs through Canadian prairie drought exposure. Distribution runs through foodservice dedicated supplier tiers and supermarket dedicated shelf-space negotiations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Extrusion equipment lead times extending fourteen to eighteen months constrain capacity expansion velocity, propping pricing discipline for incumbent isolate producers with installed wet-fractionation infrastructure.
For Market Incumbents: Anchor foodservice partnerships through permanent core menu placements rather than limited-time promotions, locking volume commitments ahead of new entrant scale. Secure backward integration into regenerative agriculture supply bases to defend margin structures against input cost volatility from Canadian drought cycles. Prioritize R&D investment in high-moisture extrusion texture systems to maintain chew parity advantages over emerging precision-fermented alternatives. For New Entrants and Emerging Players: Contract manufacturers with idled bioethanol infrastructure offer asset-light fermentation capacity without greenfield construction timelines. Brazilian supermarket chains in São Paulo and Rio de Janeiro present first-mover shelf space advantages with minimal incumbent presence. Direct-to-consumer subscription replenishment models bypass supermarket slotting fees while capturing recurring revenue and consumption data. For Investors and Strategic Acquirers: Distressed-cycle entries favor precision fermentation technology licensors with sub-ten-dollar-per-kilogram cost structures and existing GRAS notifications or novel food approvals. Long-term viability hinges on regulatory pathway clarity and carbon accounting methodology convergence across ISO and EU Green Deal standards. Watch EFSA authorization timelines and USDA organic certification backlogs as inflection indicators for formulation preference shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Retrofitting idled bioethanol capacity in the Netherlands and United States compresses capital barriers for recombinant protein production. |
| Regenerative Agriculture Supply Agreements | Multi-year offtake contracts tied to EU Green Deal verification secure allergen-friendly raw material flows against drought volatility. |
| Foodservice Menu Embedding | Permanent core offerings at national United States and United Kingdom chains decouple volume from legacy meat procurement bundles. |
| Direct-to-Consumer Subscription Launch | Replenishment models capture recurring revenue and consumption data while bypassing supermarket trade marketing budgets. |
| High-Moisture Extrusion R&D Investment | Texture science advances in Chicago and Austin facilities improve whole-muscle analog chew above twenty percent protein concentration thresholds. |
Research Methodology
SEC filings, EFSA novel food authorization databases, and USDA organic certification registries formed the secondary backbone, cross-referenced against primary interviews with extraction facility plant managers, foodservice procurement directors at national restaurant chains, formulation house R&D leads, and contract manufacturing executives. Bottom-up and top-down triangulation validated volume estimates across wet-fractionation capacity installations and retail scan data.
Bottom-up modeling segmented the analysis by product type, end-user motivation profile, application complexity, and distribution channel infrastructure intensity. CAGRs derived from installed capacity expansion schedules, regulatory approval timelines, and foodservice menu penetration curves. Forecast inputs incorporated precision fermentation cost compression trajectories and EU Farm to Fork organic coverage mandates.
Caveats apply where EFSA authorization delays, Canadian prairie drought severity, or carbon accounting standard divergence could materially shift the outlook. A model refresh is warranted upon material change in extrusion equipment delivery schedules or novel protein regulatory pathway clarity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
North America Textured Vegetable Protein Market
Plant Based Food
Plant-Based Natural Flavor Market
Plant Based Food
Plant-Based Fish Market
Plant Based Food
Plant-Based Tzatziki and Labneh Ferment Bases Market
Plant Based Food
Meat Substitutes Market
Plant Based Food
Tempeh Market
Plant Based Food
Plant-Based Burger Market
Plant Based Food
Plant-Based Meatballs Market
Plant Based Food
Europe Plant-Based Seafood Market
Plant Based Food
Vegan Chocolate Market
Plant Based Food
North America Rice Protein Market
Plant Based Food
Plant-Based Yogurt Market
Plant Based Food
Plant Chocolate Protein Powder Market
Plant Based Food
Singapore Plant-Based Food and Beverages Market
Plant Based Food
France Plant Protein Market
Plant Based Food
New Jersey Vegan Products Market