
 Plant Based Ice Cream Market | 2026-2036
Plant Based Ice Cream Market Size, Share, and Industry Trends Forecast 2026-2036
Plant Based Ice Cream Market Analysis
The capital-intensity gap between multinational CPG infrastructure and artisan plant-based startups is collapsing. Unilever leverages global cold-chain logistics to stock plant-based SKUs in conventional supermarkets across multiple continents. NadaMoo! competes through small-batch positioning and allergen-free formulations that command premium shelf placement. Danone anchors its portfolio with fermented oat bases that reduce reliance on commodity coconut supply.
Plant based ice cream comprises frozen desserts formulated without mammalian dairy proteins, typically employing emulsified plant lipid systems from coconut, almond, soy, or cashew bases with overrun controlled between 80% and 120% for texture parity. Its primary commercial purpose is to serve lactose-intolerant consumers, vegan households, and flexitarian buyers seeking indulgence without animal-derived ingredients. Coconut-derived variants dominate volume due to fat-structure similarity to cream, while oat-based formulations represent the fastest-growing sub-category as neutral flavor profiles improve mix-in compatibility. Carton and tub packaging formats capture the majority of retail margin pools, though single-serve cups are expanding in convenience channels.
FDA labeling requirements for dairy-alternative products, EU REACH frameworks governing food-contact materials in packaging, and EFSA novel-food assessments for emerging protein sources all shape formulation choices and market access timelines. These regulatory layers elevate compliance costs for new entrants while rewarding incumbents with established regulatory affairs capabilities. Stakeholders must monitor evolving protein-source approval pathways and front-of-pack labeling mandates that could recalibrate competitive positioning.
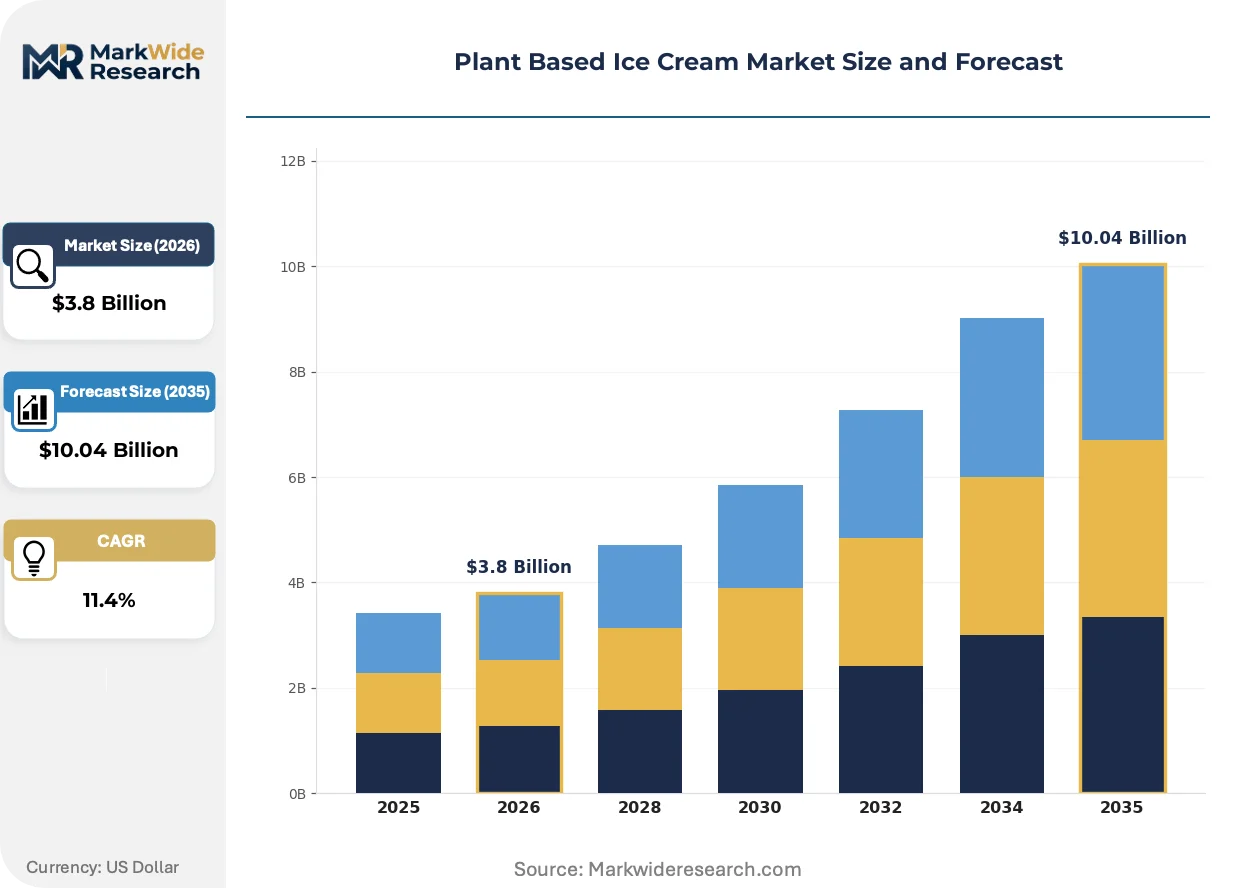
Market Dynamics
Oat protein extraction breakthroughs are collapsing the cost premium against dairy bases while EFSA novel-food pathways for emerging proteins compress formulation timelines for new entrants.
Growth Catalysts
- EFSA novel-food assessments:Accelerated approval timelines for fava bean and pea protein isolates enable faster SKU rotation in European retail channels.
- Flexitarian household penetration:German and UK supermarkets now dedicate 15-20% of frozen dessert facings to plant-based alternatives, up from single-digit allocations three years ago.
- Cold-chain infrastructure expansion:Third-party logistics providers in the United States have added dedicated dairy-alternative freezer capacity across distribution hubs serving conventional grocery.
Market Restraints
- Coconut lipid price volatility:Southeast Asian supply concentration exposes margins to weather-driven harvest disruptions and freight cost spikes.
- Protein functionality gaps:Current oat and almond bases fail to replicate the aeration stability of dairy cream above 100% overrun, limiting texture parity in premium tiers.
- FDA labeling uncertainty:Pending enforcement discretion on "milk" terminology creates retail hesitation and reformulation risk for US-focused portfolios.
Strategic Opportunities
- Precision fermentation proteins:Whey-identical proteins from microbial fermentation promise to eliminate the taste-compromise barrier currently limiting repeat purchase rates.
- Convenience channel single-serve:Petrol stations and transit hubs in the United Kingdom represent untapped impulse-purchase occasions with minimal dairy-alternative presence.
- EU Green Deal procurement mandates:Public sector catering contracts in Germany and France increasingly specify carbon-footprint thresholds that favor domestic oat-based supply chains.
Industry Challenges
- Flavor chemist scarcity:Formulation teams with expertise in masking legume off-notes command premium compensation and extended search timelines.
- Freezer burn rate management:Plant lipid oxidation kinetics differ from dairy, requiring recalibrated packaging film specifications and accelerated shelf-life testing protocols.
- Legacy dairy co-packer conversion:Shared production lines demand complete sanitation cycles between dairy and plant-based runs, compressing effective capacity and complicating scheduling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant Based Ice Cream Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coconut, Almond, Soy, Cashew Flavor Profile: Vanilla, Chocolate, Strawberry, Mint Chip Packaging Type: Carton, Cup, Cone, Tub Distribution Channel: Online, Supermarkets, Health Food Stores, Restaurants |
| Companies Covered | General Mills, NadaMoo!, Unilever, Bliss Unlimited, The Urgent Company, Nestlé, Oatly, Booja-Booja, Danone, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant Based Ice Cream Market Emerging Trajectories
Formulation science is pivoting from base-ingredient substitution toward structural replication of dairy microstructure, while regulatory clarity and procurement centralization reshape competitive access.
High-pressure processing of oat bases is supplanting traditional heat treatment in premium manufacturing lines. Artisan producers in Denmark and Sweden have adopted this technology to preserve volatile flavor compounds and extend clean-label positioning. The structural consequence is a compression of the quality gap between small-batch and scaled production, forcing multinationals to accelerate equipment upgrades or cede the super-premium tier.
EU REACH frameworks governing food-contact materials now mandate comprehensive migration testing for recycled content in frozen dessert packaging. This elevates compliance costs for carton and tub suppliers while creating first-mover advantage for firms with established testing protocols. German retailers are responding by consolidating supplier lists around packaging partners with pre-validated substrate portfolios.
Direct-to-subscription models are capturing trial-resistant consumers through curated flavor rotations and loyalty-driven replenishment cycles. UK-based specialists have built recurring revenue streams exceeding 40% of total sales, displacing conventional promotional reliance on retail slotting fees. This shift is most visible in urban households with above-median disposable income and established vegan or flexitarian dietary patterns.
Plant Based Ice Cream Market Segmentation
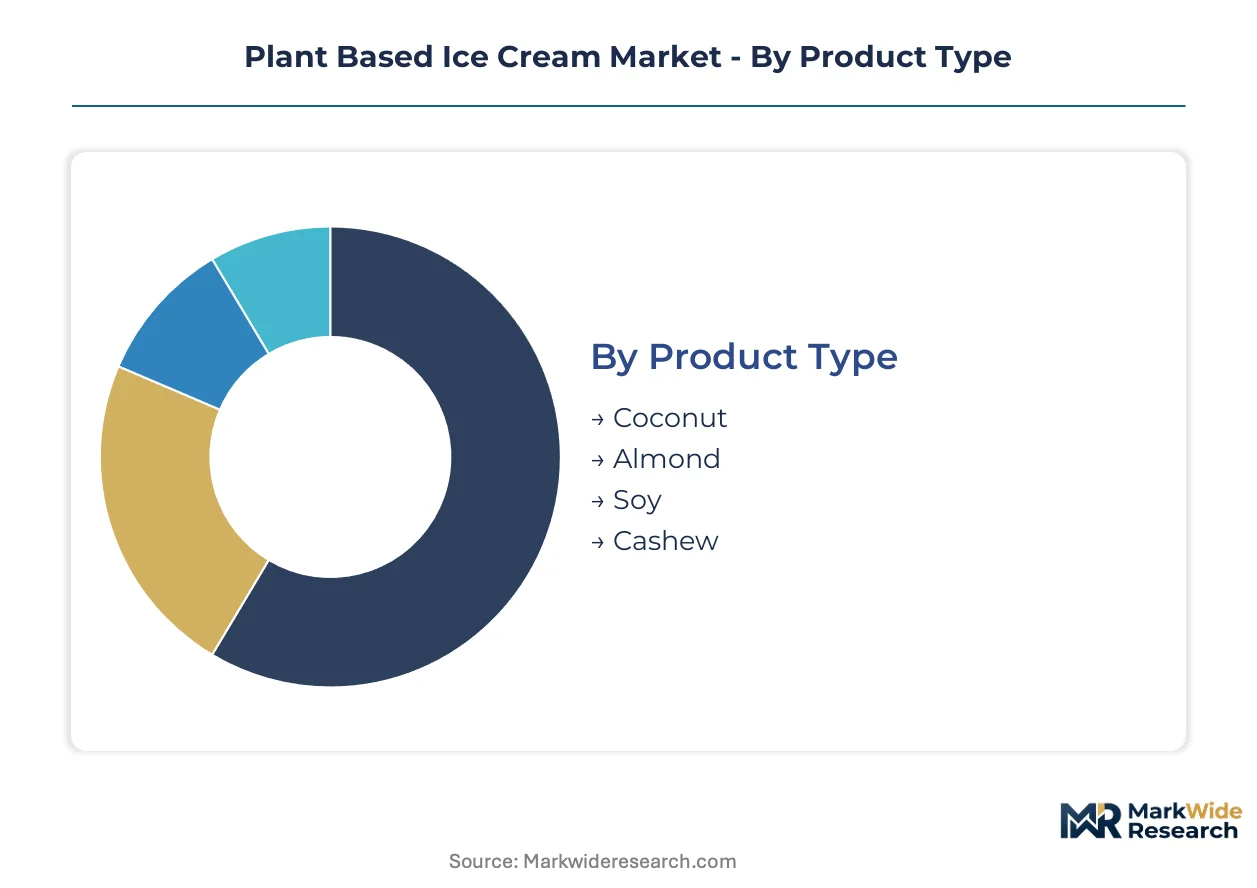
Plant based ice cream segmentation reveals divergent margin architectures across base ingredients, flavor positioning, and channel access. Manufacturers optimize formulations around fat-structure replication and freezer-space economics rather than uniform substitution strategies.
Product Type:
Margin pools concentrate in bases that minimize reformulation costs while maximizing texture parity with dairy cream systems.
- Coconut:High saturated fat content (24-30%) enables aeration stability above 100% overrun with minimal emulsifier addition. German and UK retail chains allocate premium freezer positioning to coconut-derived SKUs due to established consumer acceptance and clean-label compatibility.
- Oat:Neutral flavor profiles improve mix-in compatibility while protein extraction cost curves collapse against legacy bases. Flexitarian households in urban United States markets demonstrate repeat purchase rates exceeding other plant bases in blind taste panels.
- Almond:Lower fat content (3-4%) demands higher emulsifier loads and stabilizer packages, compressing gross margins relative to coconut alternatives.
- Soy:Mature supply chains and commodity pricing provide cost floor protection, though allergen labeling requirements limit placement in school and healthcare channels.
- Cashew:Creamy mouthfeel without coconut flavor intrusion commands super-premium pricing tiers, constrained by African and Southeast Asian supply concentration.
Coconut holds installed capacity. Oat is rotating up the share rankings.
Flavor Profile:
Volume distribution follows indulgence-occasion mapping rather than health-positioning, with classic profiles dominating trial conversion.
- Vanilla:Base formulation standard for mix-in customization and private-label manufacturing, capturing economies of scale in co-packing arrangements across multiple brands.
- Chocolate:Cocoa butter compatibility with coconut lipid systems creates structural advantages in texture replication without dairy cocoa butter equivalents.
- Strawberry:Fruit particulate suspension challenges in oat and almond bases limit overrun tolerance, constraining distribution to artisan and premium tiers.
- Mint Chip:Chocolate fragment dispersion and flavor oil stability requirements elevate technical complexity, filtering production to specialized manufacturing lines with controlled-temperature mixing capabilities.
Vanilla anchors manufacturing throughput. Chocolate is climbing the fastest in absolute volume contribution.
Packaging Type:
Retail margin capture diverges sharply between household stock-up formats and impulse-convenience units with divergent cold-chain requirements.
- Carton:Multi-serve rectangular formats optimize pallet density and freezer shelf utilization in conventional grocery, dominating German and UK supermarket replenishment cycles.
- Tub:Wide-mouth cylindrical containers support scoop-shop aesthetics in retail and foodservice crossover applications, particularly in United States club store channels.
- Cup:Single-serve portions with attached spoons capture petrol station and transit hub occasions with minimal competitive plant-based presence in the United Kingdom.
- Cone:Pre-filled waffle and sugar cone formats demand specialized filling equipment and moisture-barrier packaging, limiting viable production to dedicated frozen dessert facilities.
Carton commands shelf space allocation. Cup is gaining share fastest in convenience channel expansion.
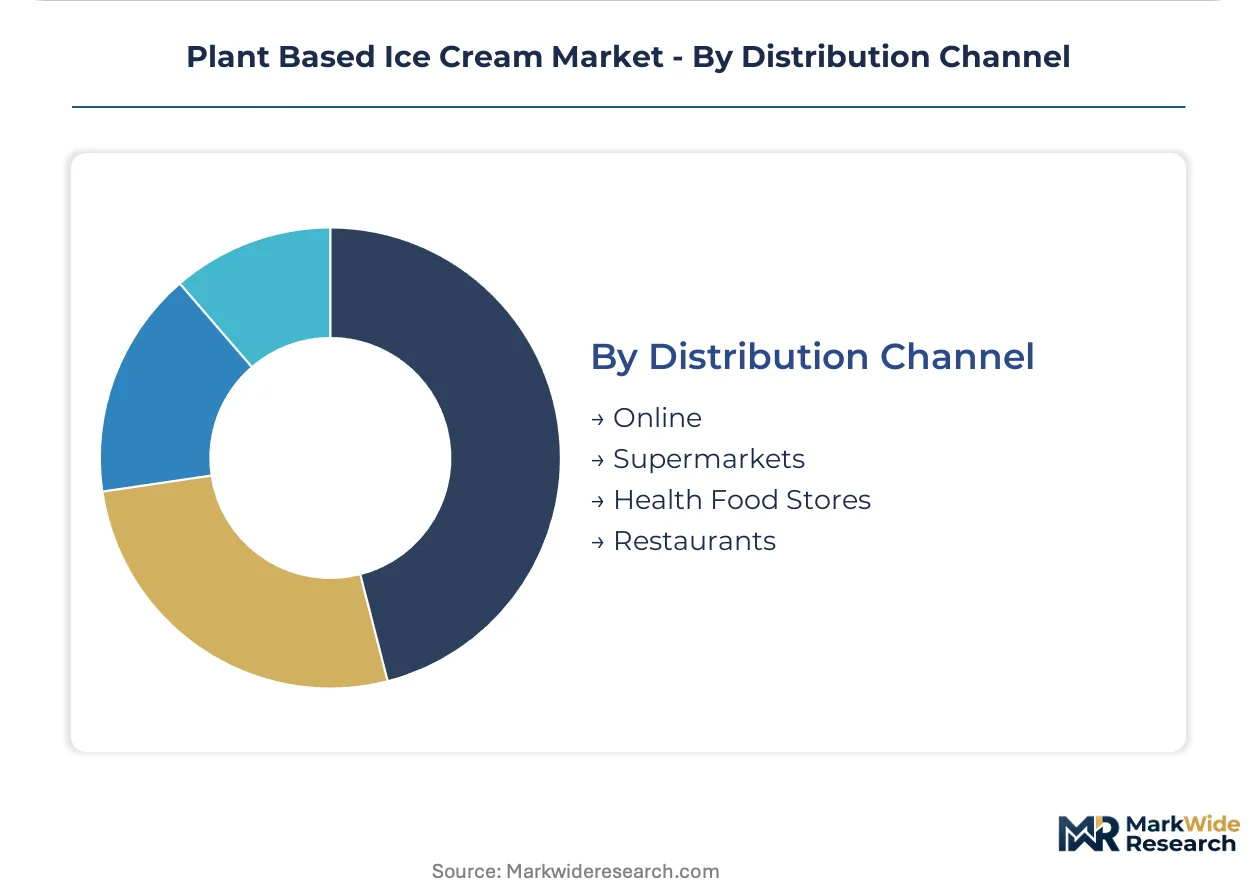
Distribution Channel:
Customer acquisition economics vary by channel maturity, with online subscription models displacing conventional slotting-fee dependence in urban flexitarian segments.
- Supermarkets:Conventional grocery freezer reset programs in Germany and the United States now dedicate 15-20% of frozen dessert facings to plant-based alternatives, up from single-digit allocations.
- Online:Direct-to-subscription models with curated flavor rotations capture trial-resistant consumers, with UK-based specialists building recurring revenue streams exceeding 40% of total sales.
- Health Food Stores:Narrower SKU assortments and educated staff enable premium pricing for allergen-free and organic-certified formulations with higher gross margins.
- Restaurants:Foodservice dessert menu integration remains underdeveloped, constrained by portion-control consistency and dairy-cross-contamination liability protocols.
Supermarkets hold volume infrastructure. Online is rotating up the share rankings in above-median income households.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in plant-based frozen desserts favor net-importing developed markets with established cold-chain infrastructure. Germany, the United Kingdom, and the United States absorb the majority of internationally sourced oat and coconut base materials. Southeast Asian supply regions dominate raw ingredient exports while European and North American markets capture value-added formulation margins.
United States
Flexitarian household penetration drives freezer-space expansion in conventional grocery, with dedicated plant-based dessert sections now standard in major retail chains. FDA enforcement discretion on "milk" terminology creates labeling uncertainty that constrains new product launches. California-based formulation labs and Colorado manufacturing clusters concentrate precision-fermentation protein development for next-generation dairy replication.
Germany
Supermarket chains allocate 15-20% of frozen dessert facings to plant-based alternatives, the highest retail penetration rate in Europe. EU Green Deal procurement mandates in public sector catering specify carbon-footprint thresholds favoring domestic oat supply chains. Berlin and Hamburg anchor brand headquarters and cold-chain distribution hubs serving Central European markets.
United Kingdom
Direct-to-subscription models capture trial-resistant consumers, with recurring revenue streams exceeding 40% of total sales for specialist operators. EFSA novel-food assessments for emerging protein isolates accelerate SKU rotation timelines relative to other European markets. London and Manchester concentrate e-commerce fulfillment infrastructure and artisan production facilities.
Sweden
High-pressure processing adoption in oat-base manufacturing preserves volatile flavor compounds for premium positioning. REACH framework compliance for recycled packaging content elevates supplier qualification barriers. Stockholm and Malmö clusters pioneer equipment upgrades that compress quality gaps between small-batch and scaled production.
Canada
Health Canada regulatory pathways for novel proteins provide market access certainty absent from US enforcement discretion. Third-party logistics providers have added dedicated dairy-alternative freezer capacity across distribution hubs serving conventional grocery. Toronto and Vancouver concentrate retail innovation testing and regional brand headquarters.
Plant Based Ice Cream Market Vendor Landscape
Concentration sits with multinational CPG conglomerates leveraging global cold-chain infrastructure against artisan specialists commanding premium positioning. The market structure tiers between scale-driven volume players and small-batch differentiation specialists. Three archetypes dominate: diversified food conglomerates with cross-category leverage, oat-native challengers with ingredient-origin credibility, and allergen-free pure-plays with clean-label positioning. Competitive moves center on co-packer capacity capture and precision-fermentation protein licensing.
Among diversified conglomerates, Unilever and Nestlé occupy positions defined by freezer-space negotiation power and multi-continental distribution density. Oatly exemplifies the ingredient-origin archetype with supply chain credibility extending into captive base-material production. NadaMoo! represents the allergen-free specialist tier where small-batch positioning commands shelf-placement premiums. Danone anchors the fermented-base segment with oat-centric portfolios reducing commodity coconut exposure. These entities collectively illustrate the competitive tension between scale efficiency and formulation differentiation.
| Leading Market Players |
|---|
| General Mills |
| NadaMoo! |
| Unilever |
| Bliss Unlimited |
| The Urgent Company |
| Nestlé |
| Oatly |
| Booja-Booja |
| Danone |
| Others |
Supply Flow & Price Mechanics
Co-packer capacity utilization above 85% in Germany and the United States compresses margin floors for artisan brands while rewarding multinationals with captive manufacturing. Scale asymmetries in cold-chain infrastructure concentrate pricing power among freezer-space gatekeepers in conventional grocery, forcing smaller entrants toward subscription models or premium health-food channels.
Pricing Analysis
Industrial OEM buyers anchor contract manufacturing pricing through volume commitments that secure dedicated production windows. Three-tier pricing structure across premium, standard, and economy levels reflects base-ingredient cost differentials between coconut, oat, and soy formulations. Cost compression in the standard tier intensifies because oat protein extraction yields are improving faster than formulation complexity. Price-sensitive flexitarian households in conventional grocery drive promotional intensity, while allergen-free positioning commands least sensitivity among pediatric and healthcare channels.
Supply Chain Analysis
Strait of Malacca transit vulnerability exposes coconut lipid shipments from Indonesia and the Philippines to weather-related delays that ripple through European manufacturing schedules. Raw material sourcing draws from Southeast Asian coconut plantations, North American oat processing clusters, and West African cashew cooperatives. Single-source vulnerability concentrates in Indonesian coconut cream suppliers serving premium texture-replication formulations. Distribution runs through third-party cold-chain operators with dedicated dairy-alternative freezer capacity across conventional grocery replenishment networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Retailer consolidation in Germany and the United Kingdom has shifted buyer power toward category managers who dictate freezer-space allocation terms, compressing supplier negotiation leverage.
For Market Incumbents: Shield margin position by securing exclusive co-packer capacity in high-pressure processing oat-base facilities before equipment lead times extend. Accelerate precision-fermentation protein licensing to neutralize taste-compromise barriers that emerging oat-native challengers exploit. Lock in multi-year coconut supply contracts with Indonesian processors to insulate against lipid price volatility from climate-driven harvest disruptions. For New Entrants and Emerging Players: Anchor in United Kingdom petrol station and transit hub convenience channels where plant-based single-serve presence remains minimal and slotting-fee resistance is lowest. Exploit EFSA novel-food approval acceleration for fava bean protein isolates to rotate SKUs faster than legacy coconut-dependent incumbents. Build direct-to-subscription recurring revenue before conventional grocery buyer power consolidates further. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among oat-native specialists with captive base-material production and established UK subscription infrastructure. Five-to-ten year viability favors acquisition targets with pre-validated EU REACH packaging compliance and health-food channel relationships that survive conventional grocery margin compression. Monitor FDA enforcement discretion resolution on "milk" terminology as the signal indicating US market access timing for precision-fermentation protein launches.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Protein Licensing | Eliminates taste-compromise barrier currently limiting repeat purchase rates in oat-based formulations. |
| High-Pressure Processing Equipment Upgrade | Preserves volatile flavor compounds in Swedish and Danish manufacturing clusters for premium positioning. |
| Direct-to-Subscription Channel Launch | Captures trial-resistant UK urban households with recurring revenue exceeding conventional slotting-fee dependence. |
| EFSA Novel-Food Approval Acceleration | Compresses SKU rotation timelines for fava bean and pea protein isolates in European retail channels. |
| Recycled Content Packaging Validation | Creates first-mover advantage under EU REACH migration testing mandates elevating supplier qualification barriers. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA enforcement discretion filings, EFSA novel-food assessment registers, Nielsen retail audit data, and EU Green Deal procurement contract disclosures. Interviews with frozen dessert category buyers at German and UK supermarket chains, formulation scientists at oat processing facilities, cold-chain logistics operators, and packaging compliance specialists informed demand-side and supply-side validation. Bottom-up SKU-level volume builds triangulate against top-down category expenditure estimates from customs trade records.
Segmentation dimensions modeled span base-ingredient type, flavor profile, packaging format, and distribution channel across the projection horizon. CAGRs derive from regression analysis of historical freezer-space allocation trends, protein extraction cost curves, and flexitarian household penetration rates. Precision-fermentation protein commercialization timelines and EFSA approval velocity for emerging isolates constitute industry-specific forecast inputs.
Material uncertainties — regulatory enforcement discretion shifts, coconut harvest disruptions from Southeast Asian weather patterns, and co-packer capacity constraints — sit outside the modeled envelope. Forecasts reflect assumptions about oat protein yield improvement trajectories and cold-chain infrastructure expansion cadence. Practitioners should keep alternative scenarios live as FDA labeling clarity and EU REACH packaging compliance deadlines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
China Plant Protein Market
Plant Based Food
South America Meat Substitute Market
Plant Based Food
Europe Meat Substitutes Market
Plant Based Food
Plant-Based Milk Alternatives Market
Plant Based Food
Plant Based Protein Market
Plant Based Food
Plant-Based Vegan Eggs Market
Plant Based Food
Global Tofu Market
Plant Based Food
United Kingdom Tofu Market
Plant Based Food
Vegan Dips Market
Plant Based Food
Global Textured Vegetable Protein Market
Plant Based Food
India Meat Substitutes Market
Plant Based Food
Plant Based Cheese Market
Plant Based Food
Plant Derived Proteins Market
Plant Based Food
Plant-Based Ham Market
Plant Based Food
Soy Food Products Market
Plant Based Food
Plant Based Meal Kit Market