
 USA Plant-Based Creamers Market | 2026-2036
USA Plant-Based Creamers Market Size, Share, and Industry Trends Forecast 2026-2036
USA Plant-Based Creamers Market Analytics
Specialty coffee chain procurement consolidation is repositioning volume concentration toward food service buyers with national scale requirements. Califia Farms LLC leverages its West Coast manufacturing footprint to anchor supply contracts with multi-location cafe operators. Oatly competes through dedicated barista-format production lines that sustain premium positioning in high-velocity urban markets. Nutpods differentiates via unsweetened coconut-almond blends that occupy the clean-label perimeter of conventional grocery sets.
USA plant-based creamers are emulsified, shelf-stable or refrigerated fluid products formulated from milled oilseeds, grains, or nuts, typically containing two to twelve percent fat content, homogenized for thermal stability in hot beverages, and designed to replicate the mouthfeel and whitening function of dairy cream in coffee and tea applications. Oat-based formulations now lead retail velocity due to neutral flavor compatibility with roasted coffee profiles, while almond-derived variants remain the most mature segment with established household penetration but flattening growth curves. Barista-specific formulations command the strongest margin pools as food service buyers prioritize foam stability and latte art performance over unit cost.
The FDA's plant-based dairy labeling framework and USDA organic certification requirements jointly shape product nomenclature, ingredient disclosure standards, and market access for interstate commerce. California's Proposition 65 enforcement and state-level clean-label legislation further constrain additive portfolios and processing aid selections for manufacturers distributing nationwide. Stakeholders must monitor evolving enforcement patterns at the FDA and state agriculture departments to anticipate reformulation timelines and label refresh investments.
Market Dynamics
Specialty coffee chain procurement consolidation is compressing supplier margins while simultaneously rewarding manufacturers with dedicated barista-format production capabilities and West Coast distribution infrastructure.
Growth Catalysts
- Food service buyer concentration:National cafe operators now consolidate volume through multi-year supply agreements, creating predictable offtake for manufacturers with scalable oat and almond processing lines.
- California Proposition 65 enforcement:Clean-label mandates accelerate reformulation away from synthetic emulsifiers, pulling consumer preference toward minimally processed coconut and oat bases in retail sets.
- Barista-format functionality:Foam stability specifications for latte art performance create premium pricing tiers that sustain margin pools unavailable in conventional retail creamer segments.
Market Restraints
- Input cost volatility:Organic oat and almond commodity prices fluctuate with California drought cycles and water allocation disputes, compressing gross margins for non-vertically integrated processors.
- Supply concentration risk:Domestic manufacturing clusters heavily in California's Central Valley, exposing national distribution networks to single-state climate and logistics disruptions.
- Technical limitation:Current enzymatic processing methods struggle to achieve dairy-comparable mouthfeel in unsweetened formulations below 3% fat content without clean-label compromises.
Strategic Opportunities
- Underpenetrated food service verticals:Independent diner chains and university food service systems in the Midwest and Southeast remain largely unserved by dedicated barista-format distribution.
- USDA organic certification tailwind:Federal organic standards expansion creates shelf-space advantages in conventional grocery perimeter sets where conventional creamers face displacement pressure.
- Direct-to-cafe channel innovation:Micro-roaster subscription models and regional coffee equipment distributors offer bypass routes around consolidated national chain procurement gatekeepers.
Industry Challenges
- Emulsifier chemistry expertise gap:Formulation teams with dual competency in plant protein stabilization and thermal processing for hot-beverage applications command premium salaries that strain mid-cap R&D budgets.
- Clean-label certification timeline:Non-GMO Project verification and USDA organic audits require 12-18 month lead times that delay product launches in fast-moving seasonal flavor cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | USA Plant-Based Creamers Market |
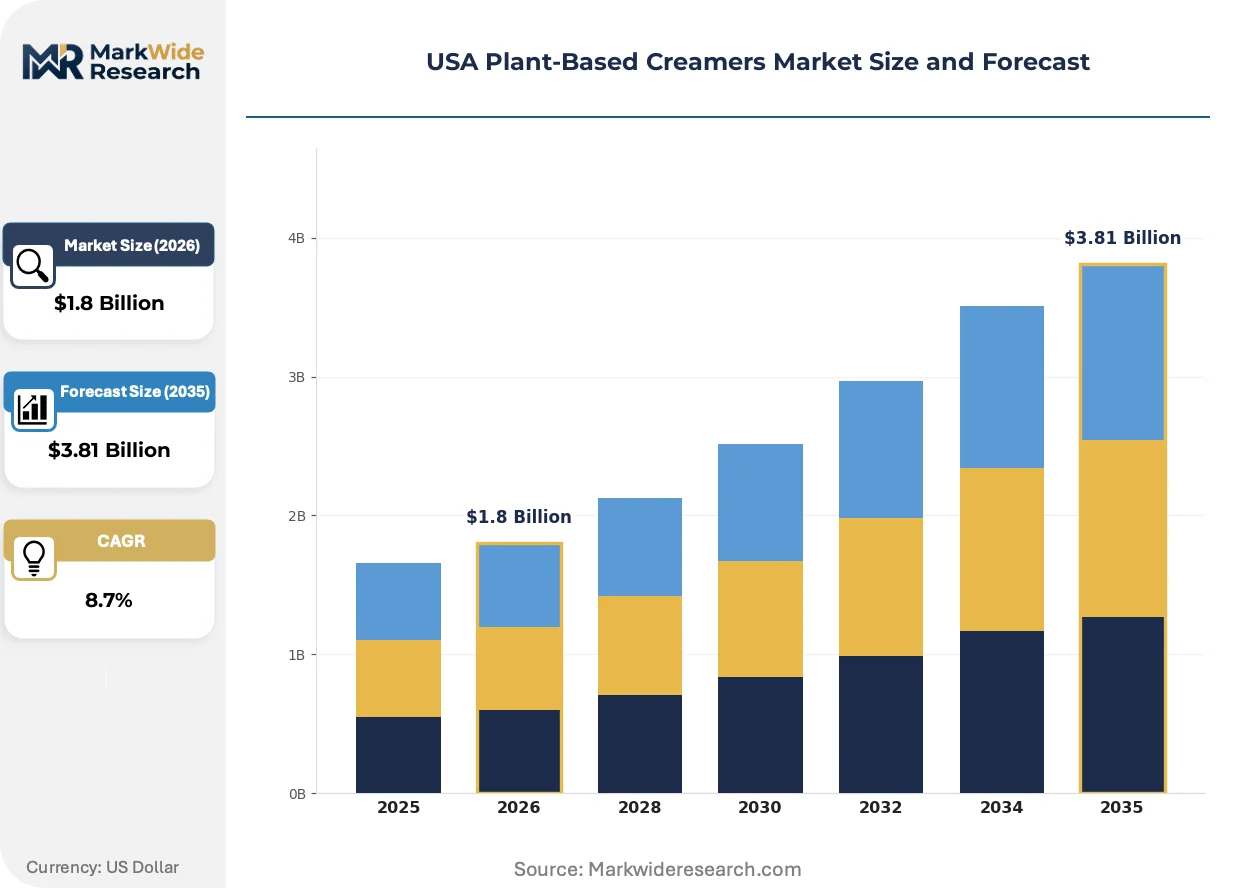
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
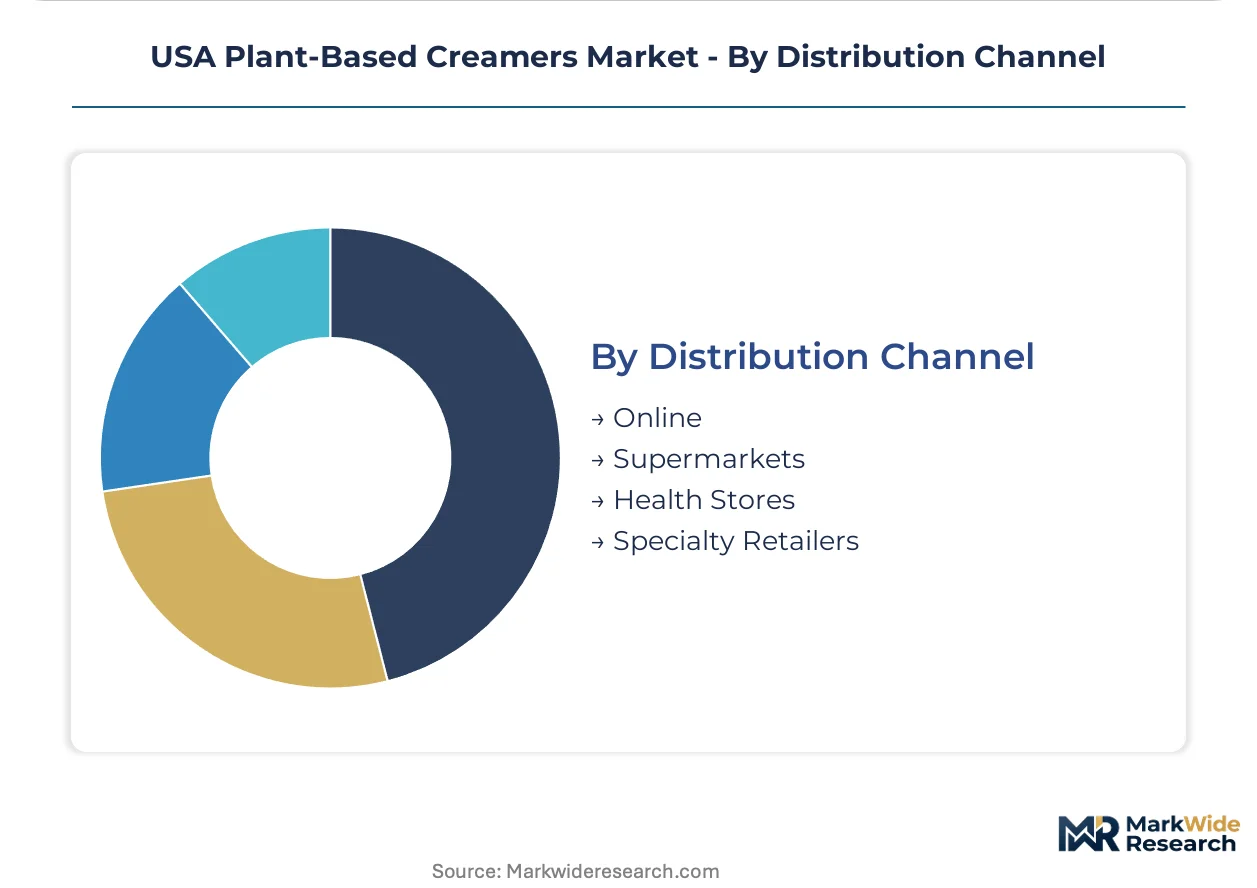
| Segmentation | Product Type: Almond, Soy, Oat, Coconut Formulation: Unsweetened, Flavored, Sweetened, Barista End User: Household, Food Service, Cafes, Restaurants Distribution Channel: Online, Supermarkets, Health Stores, Specialty Retailers |
| Companies Covered | Califia Farms LLC, Oatly, Nutpods, Laird Superfood, Chobani LLC, Elmhurst Milked Direct LLC, Ripple Foods, Organic Valley, Danone North America, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
USA Plant-Based Creamers Market Evolving Landscape
Enzymatic lipid restructuring and precision fermentation are actively reconfiguring how manufacturers achieve functional performance without synthetic additive portfolios, while regulatory clarity on nomenclature accelerates investment in transparent supply chain infrastructure.
High-pressure homogenization combined with oat lipid fractionation is absorbing the functional role previously filled by mono- and diglycerides in conventional barista formulations. Multi-location cafe operators in the Pacific Northwest and Northeast corridors are adopting these enzymatically stabilized oat bases at contract renewal cycles. The technology is absorbing margin pressure from synthetic emulsifier price volatility while enabling shorter ingredient declarations that satisfy California retail distribution requirements.
FDA's updated labeling guidance for plant-based dairy alternatives is compressing permissible claim language and accelerating investment in supply chain documentation systems. Domestic manufacturers must now substantiate nutritional equivalence statements through analytical testing protocols that add 8-12 weeks to product launch timelines. Barista-format SKUs face the steepest compliance burden given their positioning at the premium tier where label transparency commands highest consumer scrutiny.
Specialty coffee chains are consolidating procurement decisions at the regional operator level rather than individual store discretion, compressing supplier negotiation cycles and favoring manufacturers with national distribution infrastructure. This concentration displaces fragmented local distributor relationships that historically sustained smaller regional creamer brands. The shift is most visible in California's Los Angeles and San Francisco metro areas where multi-roaster cafe collectives now negotiate collective purchasing agreements.
USA Plant-Based Creamers Market Segmentation
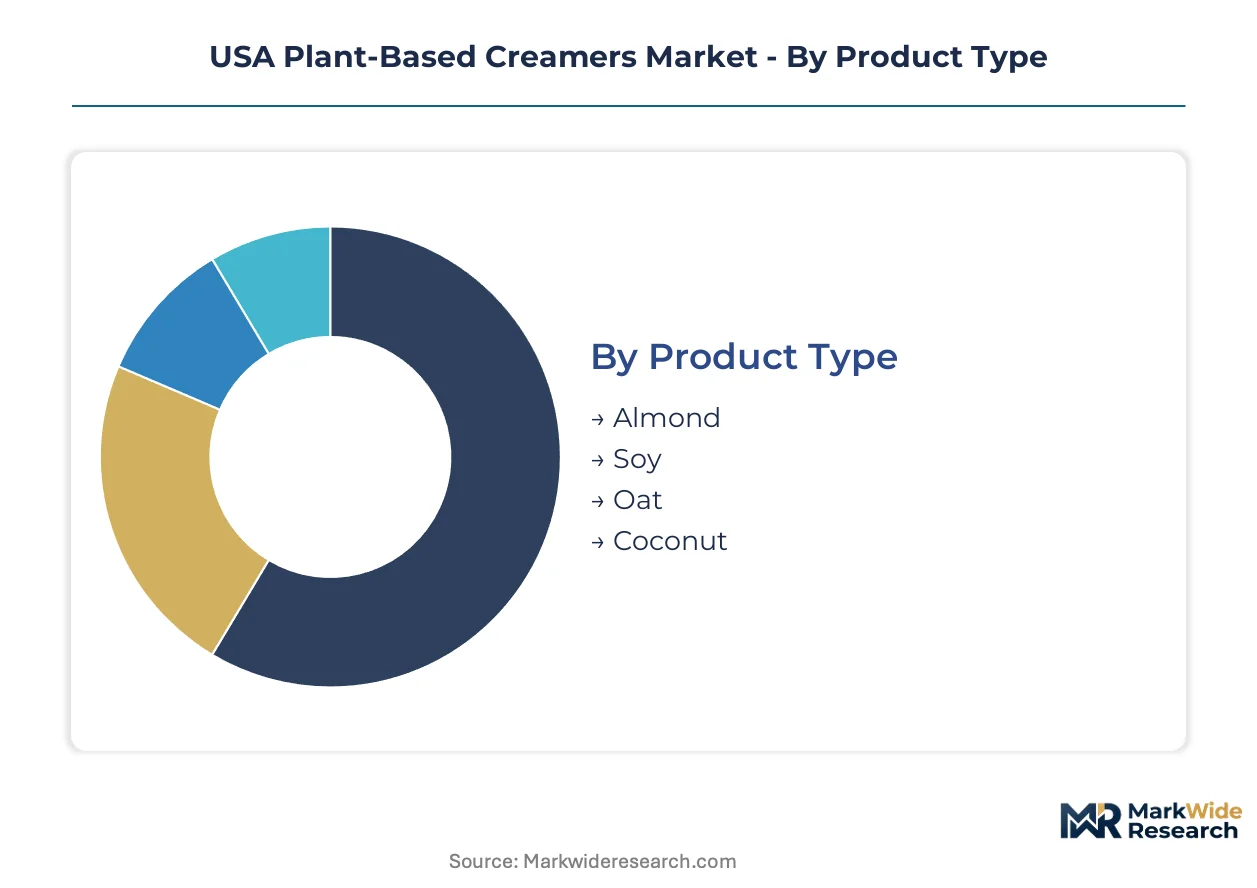
Plant-based creamer procurement decisions hinge on functional performance specifications that vary sharply between home brewing and commercial espresso applications. Manufacturers configure production lines around these divergent requirements, with formulation chemistry and thermal stability specifications driving category-level investment priorities.
Product Type:
Flavor neutrality and foam architecture determine which base ingredient commands shelf space and food service contracts.
- Oat:Neutral flavor profile and superior lipid emulsion stability make oat the preferred substrate for barista-format formulations. Los Angeles and San Francisco metro-area cafes drive premium adoption where latte art performance commands contract specifications.
- Almond:The most mature segment with established household penetration across conventional grocery sets. California Central Valley processing clusters anchor supply, though growth curves flatten as oat displaces almond in food service procurement.
- Soy:Legacy base with cost advantages in conventional retail but declining relevance in premium positioning due to allergen labeling constraints and flavor compatibility limitations with dark roast profiles.
- Coconut:High-fat content enables rich mouthfeel in unsweetened formulations. Clean-label perimeter placement in health stores and specialty retailers supports niche positioning outside mainstream food service channels.
Oat leads on scale; coconut leads on momentum in clean-label premium tiers.
Formulation:
Calorie positioning and additive transparency split procurement between mass retail and perimeter health channels.
- Barista:Engineered for thermal stability and microfoam formation at steam wand temperatures. Dedicated production lines command premium pricing tiers as national cafe chains consolidate volume through multi-year supply agreements.
- Unsweetened:Zero-calorie positioning aligns with California Proposition 65 enforcement trends and USDA organic certification requirements. Enzymatic processing challenges below 3% fat content constrain clean-label formulation options.
- Flavored:Seasonal rotation cycles drive velocity in conventional retail sets. Vanilla and hazelnut variants anchor core SKUs with shorter innovation timelines than certification-dependent organic launches.
- Sweetened:Mass-market positioning with established distribution through supermarket dairy cases. Price compression from private label competition limits margin expansion in conventional retail channels.
Barista formulations concentrate margin pools; unsweetened variants gain share fastest in California retail distribution.
End User:
Volume scale and specification complexity separate fragmented household demand from consolidated food service procurement.
- Food Service:National cafe operators and university systems consolidate purchasing through centralized procurement functions. Predictable offtake volumes reward manufacturers with scalable oat processing lines and West Coast distribution infrastructure.
- Cafes:Independent and multi-roaster collectives in Pacific Northwest and Northeast corridors prioritize foam stability specifications over unit cost. Regional operator-level consolidation compresses supplier negotiation cycles.
- Restaurants:Diner chains and casual dining operators in Midwest and Southeast remain underpenetrated by dedicated barista-format distribution. Equipment compatibility requirements slow adoption outside espresso-focused concepts.
- Household:Fragmented demand across conventional grocery and online channels with price sensitivity driving private label substitution. Almond-based SKUs retain penetration advantage from early-mover positioning.
Food service leads on scale; cafes lead on specification premiumization.
Distribution Channel:
Certification requirements and velocity expectations shape channel-specific SKU configurations.
- Supermarkets:Conventional dairy case placement demands refrigerated supply chain compliance and high-velocity turnover. Barista-format SKUs face shelf-space competition from established dairy creamer incumbents.
- Specialty Retailers:Clean-label and organic certification command perimeter positioning with margin structures supporting slower inventory turns. California health store chains anchor regional distribution for coconut and oat variants.
- Online:Direct-to-consumer subscription models and micro-roaster partnerships bypass consolidated national chain procurement gatekeepers. Fulfillment economics favor shelf-stable formulations over refrigerated SKUs.
- Health Stores:Non-GMO Project verification and USDA organic audits dominate entry requirements with 12-18 month certification timelines. Unsweetened formulations align with consumer demographics in this channel.
Supermarkets lead on scale; specialty retailers lead on margin structure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's regulatory environment diverges from the United States on plant-based dairy nomenclature, while Mexico's food service sector adopts barista-format products at a slower velocity than its northern neighbors. The North American landscape reflects distinct state-level enforcement patterns and metropolitan demand concentrations.
California
Los Angeles and San Francisco metro-area cafes drive premium barista-format adoption through multi-roaster collective purchasing agreements. Proposition 65 enforcement accelerates reformulation away from synthetic emulsifiers, pulling consumer preference toward minimally processed oat bases. Central Valley processing clusters anchor national supply for organic oat and almond inputs.
Texas
Austin and Dallas-Fort Worth independent coffee shops expand procurement of shelf-stable oat formulations for high-velocity urban markets. State agriculture department inspections align with FDA labeling guidance for interstate distribution compliance. Houston's food service distribution hubs connect Gulf Coast logistics to Midwest cafe supply chains.
New York Metro
Brooklyn and Manhattan specialty roasters prioritize foam stability specifications in contract negotiations with West Coast manufacturers. State-level clean-label legislation complements federal organic certification requirements for perimeter retail placement. Albany's regulatory oversight coordinates with FDA on plant-based dairy alternative enforcement.
Pacific Northwest
Seattle and Portland cafe operators adopt enzymatically stabilized oat bases at contract renewal cycles, favoring high-pressure homogenization technologies. Washington State Department of Agriculture audits enforce ingredient disclosure standards for organic claims. Portland's micro-roaster subscription models bypass consolidated national chain procurement gatekeepers.
Midwest
Chicago and Detroit diner chains remain underpenetrated by dedicated barista-format distribution, presenting whitespace for regional equipment compatibility programs. Illinois Department of Agriculture inspections focus on refrigerated supply chain compliance for conventional retail placement. Cleveland's university food service systems consolidate purchasing through centralized procurement functions.
USA Plant-Based Creamers Market Competitive Landscape
California producers anchor the premium tier; Midwest specialists hold conventional retail positioning through established dairy case relationships. The vendor base stratifies across three functional layers: vertically integrated oat processors with captive supply chains, contract manufacturers serving private label programs, and ingredient technology licensors enabling enzymatic stabilization. Competitive moves concentrate on multi-year supply agreements with national cafe operators and USDA organic certification expansion for perimeter shelf access.
Within the West Coast manufacturing tier, Califia Farms LLC and Oatly exemplify dedicated barista-format production capabilities, while Nutpods occupies a position in the clean-label perimeter of conventional grocery sets. These entities represent distinct archetypes: the multi-location supply contract anchor, the premium urban market specialist, and the unsweetened formulation innovator. Their collective positioning illustrates how geographic concentration in California's Central Valley interacts with FDA labeling timelines and state-level enforcement to shape competitive differentiation.
| Leading Market Players |
|---|
| Califia Farms LLC |
| Oatly |
| Nutpods |
| Laird Superfood |
| Chobani LLC |
| Elmhurst Milked Direct LLC |
| Ripple Foods |
| Organic Valley |
| Danone North America |
| Others |
Value Network & Pricing Analysis
National cafe operators consolidating volume through multi-year supply agreements have compressed supplier margins while elevating contract-based pricing structures that reward scale and barista-format specialization. This buyer concentration shifts pricing power toward food service procurement functions with predictable offtake requirements, forcing manufacturers to absorb input volatility through long-term contract terms rather than spot-market adjustments.
Pricing Analysis
Capacity additions in California's Central Valley are reshaping price floors for organic oat and almond inputs as drought cycles and water allocation disputes introduce commodity volatility that processors must hedge through forward contracting. Three-tier pricing structure across premium barista, standard retail, and economy private-label levels separates formulations by foam stability certification and organic claim substantiation. Pricing pressure stems from synthetic emulsifier cost spikes and clean-label reformulation investments. Household consumers in conventional grocery channels exhibit highest price sensitivity, while Pacific Northwest cafe collectives prioritize performance specifications over unit cost.
Supply Chain Analysis
Workforce availability constraints in California's Central Valley processing clusters and emerging Texas manufacturing corridors are tightening operational flexibility for enzymatic processing lines requiring specialized protein stabilization expertise. Domestic supply concentrates in California with secondary nodes in Texas and Oregon, drawing from organic oat cultivation in the northern plains and almond orchards in drought-exposed Central Valley regions. Raw material dependencies center on organic grain inputs, plant protein isolates, and high-pressure homogenization equipment. Single-state climate exposure creates structural vulnerability to irrigation restrictions and wildfire logistics disruptions. Distribution runs through refrigerated food service networks anchored in Los Angeles, San Francisco, and Seattle metro hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The USA plant-based creamers market functions as a regulatory compounder where FDA's updated labeling guidance for plant-based dairy alternatives accelerates formulation transparency investments and compresses permissible claim language, directly expanding demand for supply chain documentation systems and analytical testing capabilities.
For Market Incumbents: Anchor multi-year supply agreements with national cafe operators before contract renewal cycles consolidate procurement decisions at regional operator levels. Invest in captive organic oat processing capabilities to hedge against California drought-driven input volatility. Prioritize USDA organic certification expansion for perimeter shelf access in conventional grocery sets where conventional creamers face displacement pressure from clean-label mandates.
For New Entrants and Emerging Players: Regional coffee equipment distributors offer bypass routes around consolidated national chain procurement gatekeepers for micro-roaster subscription models. Midwest diner chains and university food service systems remain underpenetrated by dedicated barista-format distribution, presenting whitespace for equipment compatibility programs. Target direct-to-cafe channel innovation through enzymatic stabilization technology licensing rather than capital-intensive manufacturing scale-up.
For Investors and Strategic Acquirers: Vertically integrated beverage conglomerates with existing cafe supply relationships are the most active acquirer in this space, seeking barista-format production capabilities and West Coast distribution infrastructure. Mid-cap specialists with captive organic supply chains and FDA compliance documentation systems represent prime acquisition targets over the medium-term horizon. Monitor California Proposition 65 enforcement patterns as the inflection indicator for accelerated clean-label reformulation timelines and label refresh investment cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Barista-Format Production Line Expansion | Dedicated foam stability capabilities capture premium pricing tiers in Los Angeles and San Francisco metro-area cafe contracts. |
| USDA Organic Certification Acceleration | Federal organic standards expansion unlocks perimeter shelf positioning in California health store chains and conventional grocery sets. |
| Enzymatic Stabilization Technology Licensing | High-pressure homogenization and oat lipid fractionation replace synthetic emulsifiers for California Proposition 65 compliance. |
| West Coast Distribution Infrastructure Investment | Central Valley and Pacific Northwest logistics nodes reduce lead times for national cafe operator multi-year supply agreements. |
| Direct-to-Cafe Subscription Channel Development | Micro-roaster partnerships bypass consolidated procurement gatekeepers in Brooklyn and Manhattan specialty coffee corridors. |
Research Methodology
Bottom-up food service procurement modeling reconciled against top-down oat and almond processing capacity tracking forms the analytical core of this study. Primary interviews with barista-format production managers, national cafe chain procurement directors, organic certification auditors, enzymatic processing engineers, and Central Valley agricultural cooperative representatives combined with secondary validation from FDA labeling guidance documents, USDA organic certification databases, California Department of Public Health enforcement records, and Nielsen retail velocity data. Triangulation across stakeholder inputs and regulatory filings ensures segmentation integrity.
Input-output matrices mapping organic oat and almond cultivation through enzymatic processing to barista-format finished goods distribution generate volume and value trajectories across the projection horizon. Segmentation dimensions modeled include base ingredient type, formulation functionality, end-user procurement scale, and distribution channel certification requirements. CAGRs derive from contract renewal cycle analysis and organic acreage expansion patterns. Forecast inputs incorporate California drought severity indices and FDA enforcement timeline assumptions.
Revisions become necessary when California water allocation disputes intensify, FDA labeling guidance enforcement accelerates, or enzymatic processing breakthroughs achieve dairy-comparable mouthfeel below 3% fat content. Forecasts reflect documented assumptions regarding organic certification audit timelines and national cafe operator consolidation trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Plant Based Breads Market
Plant Based Food
Plant-Based Spreads Market
Plant Based Food
Vegan Pastry Market
Plant Based Food
Soy- Based Food Market
Plant Based Food
Europe Rice Protein Market
Plant Based Food
China Plant-Based Food and Beverages Market
Plant Based Food
Oat-Based Cereals Market
Plant Based Food
Plant-Based Ham Market
Plant Based Food
Europe Tofu Market
Plant Based Food
Organic Rice Protein Market
Plant Based Food
Plant-Based Bacon Market
Plant Based Food
Lentil Protein Market
Plant Based Food
United Kingdom Plant Protein Market
Plant Based Food
Soy Protein Market
Plant Based Food
Vegan Noodles Market
Plant Based Food
Meat Substitutes Market