
 Plant Based Collagen Market | 2026-2036
Plant Based Collagen Market Size, Share, and Industry Trends Forecast 2026-2036
Plant Based Collagen Market Analytics
Asset-light contract manufacturing and white-label leasing is narrowing the capital barrier for new entrants in functional nutrition. Sunwarrior LLC leverages its Utah-based vertical supply chain to control raw pea and rice protein sourcing. Evonik Industries AG sustains technology leadership through precision fermentation platforms for recombinant collagen building blocks. Garden of Life LLC anchors shelf presence via Whole Foods and natural channel exclusivity that smaller brands struggle to replicate.
Plant based collagen denotes protein hydrolysates and peptide fractions derived from legume, cereal, or nut sources, engineered to mimic the glycine-proline-hydroxyproline amino acid signature of animal collagen through enzymatic hydrolysis at controlled temperature and pH. These ingredients serve primarily as functional inputs for skin elasticity claims, joint support formulations, and clean-label protein fortification in beverages and powders. Hydrolyzed collagen and collagen peptides capture the dominant share of current volume, with liquid collagen formats gaining fastest in ready-to-drink wellness applications where convenience drives repeat purchase. Source segmentation tilts toward pea and rice combinations, as these deliver complete amino acid profiles without major allergen labeling burdens that constrain soy and almond alternatives in European and North American retail.
The FDA exercises oversight through structure-function claim substantiation under DSHEA, while EFSA enforces health claim authorization under the EU Nutrition and Health Claims Regulation, compelling brands to invest in human clinical validation. BIS standards in India and GB standards in China add further compliance layers for cross-border nutraceutical trade. Stakeholders must monitor evolving peptide characterization methodologies and jurisdiction-specific substantiation thresholds before committing to regional formulation and positioning strategies.
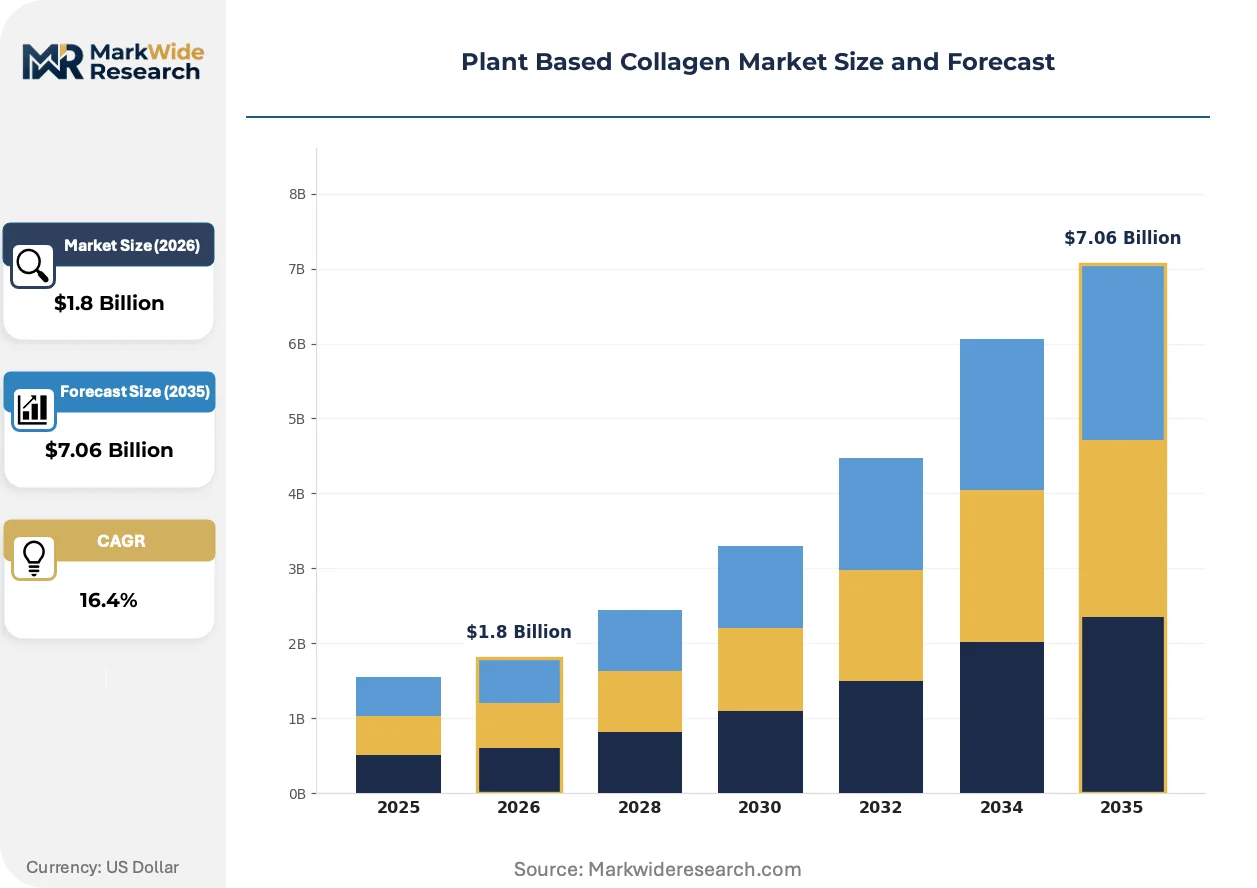
Market Dynamics
Precision fermentation platforms are compressing the cost curve for recombinant collagen peptides while FDA and EFSA substantiation rules force brands to fund human clinical trials before making structure-function claims.
Growth Catalysts
- DSHEA structure-function pathway:The FDA's existing framework allows faster time-to-market for skin elasticity and joint support claims compared to pharmaceutical pathways, drawing functional food investment.
- Peptide bioavailability research:Advances in enzymatic hydrolysis at controlled temperature and pH are improving glycine-proline-hydroxyproline signature matching to animal collagen benchmarks.
- Wellness retail infrastructure:Mature beauty-from-within positioning in the United States, Germany, and South Korea creates pull-through for clean-label protein fortification applications.
Market Restraints
- Input cost volatility:Organic pea and rice protein concentrates face price pressure from competing plant-based meat demand and climate-driven yield variability in North American and European sourcing regions.
- Supply concentration risk:Precision fermentation capacity for recombinant collagen building blocks clusters with a limited set of contract manufacturing organizations, creating bottleneck exposure.
- Technical limitation:Current plant-based hydrolysates cannot replicate the full triple-helix structure of native animal collagen, constraining claims in wound healing and orthopedic applications.
Strategic Opportunities
- Underpenetrated geography:India's BIS standards and FSSAI framework for nutraceuticals remain less stringent than EFSA thresholds, offering first-mover positioning for peptide characterization methodologies.
- Regulatory tailwind:The EU Green Deal's push toward sustainable protein systems creates procurement preference for fermentation-derived ingredients in public sector and institutional foodservice channels.
- Distribution innovation:Direct-to-consumer subscription models for liquid collagen formats bypass traditional natural channel slotting fees that constrain smaller brands at Whole Foods and comparable retailers.
Industry Challenges
- Peptide characterization expertise gap:Analytical chemists capable of validating amino acid signatures and molecular weight distributions for clean-label substantiation remain scarce across contract research organizations.
- Cross-border compliance timeline:Dual carbon goals in China and evolving GB standards for protein hydrolysates create unpredictable registration timelines for brands seeking MIIT and SAMR approvals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant Based Collagen Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.06 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrolyzed Collagen, Collagen Peptides, Liquid Collagen, Gelatin Source: Pea, Rice, Soy, Almond Application: Skincare, Nutraceuticals, Food & Beverage, Supplements End User: Healthcare, Beauty, Fitness, Wellness |
| Companies Covered | Plantigo, Evonik Industries AG, Sunwarrior LLC, Garden of Life LLC, Unived, SMPNutra, Nitta Gelatin Inc., Ancient+Brave, OZiva, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant Based Collagen Market Evolving Landscape
Active ingredient sourcing is bifurcating between legacy extraction methods and biotechnology-derived alternatives, with formulation science racing to validate functional equivalence before regulatory windows narrow.
Fermentation-derived collagen building blocks are hybridizing with traditional enzymatic hydrolysis outputs to create blended peptide profiles that satisfy both cost targets and clean-label positioning. Nutraceutical brands in South Korea and Germany are adopting these hybrid inputs at pilot scale, seeking to preempt EFSA health claim authorization requirements. The technology is hybridizing supply chain structures by enabling brands to source recombinant precursors from precision fermentation specialists while maintaining downstream control over final hydrolysis and formulation.
EFSA's tightening enforcement under the EU Nutrition and Health Claims Regulation is forcing brands to commission human clinical studies for skin elasticity and joint support claims before market entry. This industrial consequence is compressing marketing timelines and raising capital requirements for substantiation. Beauty-from-within positioned products targeting German and French consumers face the steepest compliance burden, with several brands reformulating toward generic protein fortification claims to avoid authorization delays.
Buyer concentration among wellness retail chains is compressing supplier margins and demanding exclusive formulation partnerships that lock out competing brands. Direct-to-consumer channels are displacing natural retail dependency for mid-sized nutraceutical companies seeking to escape slotting fee structures. This pattern is most visible in the United States, where Shopify-enabled subscription models for liquid collagen formats are capturing repeat purchase cohorts that traditional powder SKUs struggle to retain.
Plant Based Collagen Market Segmentation
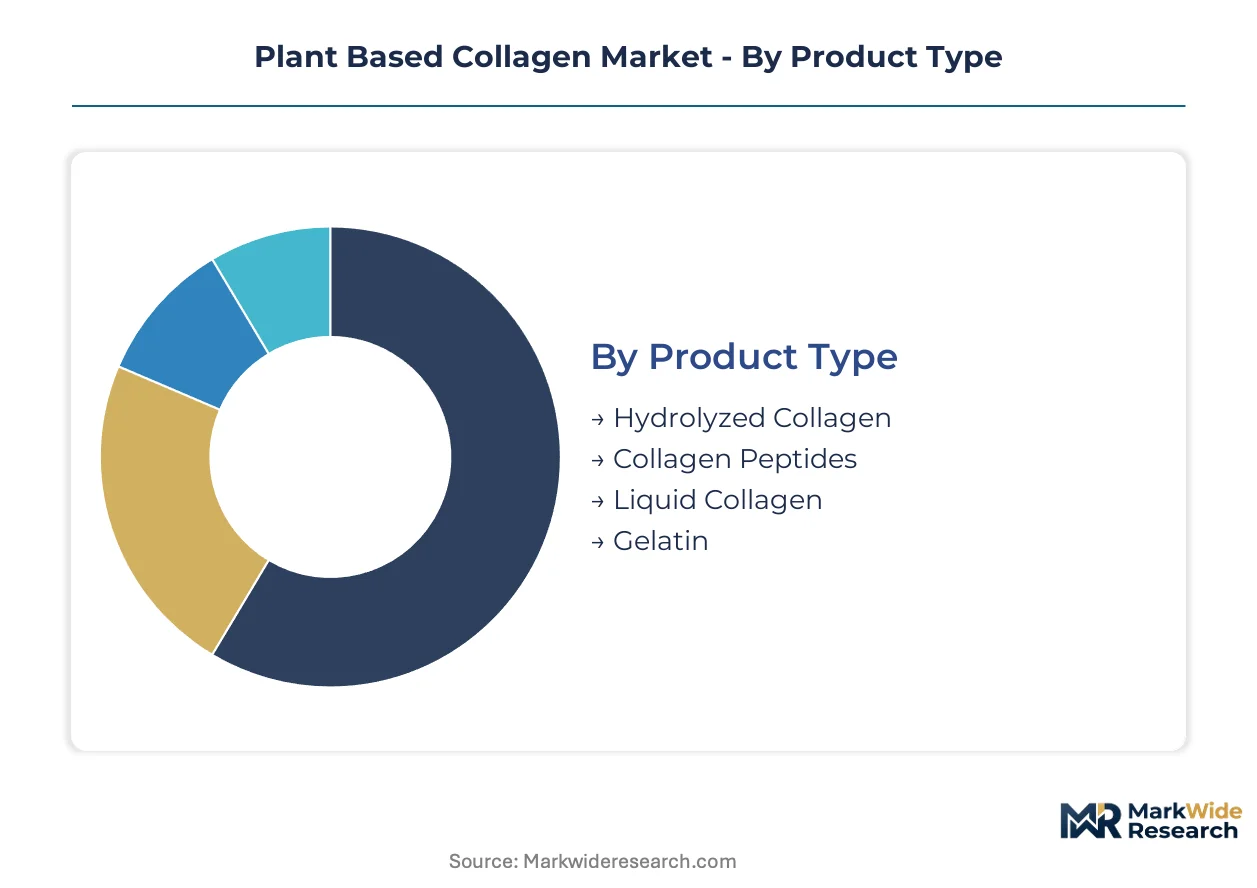
Plant based collagen suppliers configure their ingredient portfolios around peptide molecular weight, amino acid completeness, and format stability. Segmentation choices directly determine which regulatory substantiation pathways and retail channels remain accessible.
Product Type:
Cost tier stratification separates commodity hydrolysates from premium-positioned liquid formats requiring cold-chain investment.
- Hydrolyzed Collagen:Enzymatically cleaved protein fractions with molecular weights between 3,000 and 10,000 Daltons dominate powder applications. United States nutraceutical brands source these for bulk protein fortification where cost-per-serving constraints dominate procurement.
- Collagen Peptides:Smaller di- and tri-peptide fractions below 2,000 Daltons demonstrate superior bioavailability in human clinical trials. German manufacturers prioritize these for EFSA health claim substantiation in beauty-from-within formulations.
- Liquid Collagen:Ready-to-drink concentrates with flavor masking and suspension stability for convenience positioning.
- Gelatin:Partially hydrolyzed collagen with gelling functionality for food texture applications.
Hydrolyzed Collagen holds installed capacity. Liquid Collagen is rotating up the share rankings.
Source:
Application requirements for complete amino acid profiles and allergen labeling burdens shape sourcing decisions across formulation categories.
- Pea:High lysine content complements rice protein to achieve PDCAAS scores matching animal collagen benchmarks. South Korean beauty brands specify pea-rice blends for skin elasticity claims in MFDS-registered products.
- Rice:Hypoallergenic positioning and neutral flavor profile suit pediatric and sensitive-skin formulations. United States clean-label startups source organic rice concentrates to avoid soy allergen warnings.
- Soy:Established supply infrastructure and cost position constrained by GMO labeling requirements in European retail.
- Almond:Premium positioning in nut-allergen-managed formulations with limited volume scale.
Pea and Rice combinations capture formulation preference. Almond is gaining fastest in premium positioning.
Application:
Volume concentration in mature categories creates margin pressure while emerging segments command substantiation premiums.
- Skincare:Topical and ingestible formats targeting dermal collagen density claims require clinical validation under FDA structure-function guidelines. German and French brands face EFSA authorization timelines for beauty-from-within positioning.
- Nutraceuticals:Capsule and tablet delivery systems for joint support and protein fortification dominate pharmacy channel distribution. United States DSHEA framework permits faster claim deployment than pharmaceutical pathways.
- Food & Beverage:Protein enrichment in dairy alternatives and functional beverages with clean-label positioning.
- Supplements:Powder and liquid formats for direct-to-consumer subscription models bypassing retail slotting fees.
Skincare holds installed capacity. Supplements is climbing the fastest in share rankings.
End User:
Customer type differentiation separates institutional procurement from premium direct-to-consumer positioning.
- Healthcare:Clinical nutrition and wound support applications requiring medical-grade peptide characterization. FDA oversight through food additive and GRAS pathways constrains supplier qualification.
- Beauty:Beauty-from-within and topical collagen claims driving repeat purchase in South Korean and German wellness retail. EFSA health claim authorization creates compliance hierarchy among competing brands.
- Fitness:Protein recovery and joint protection positioning in sports nutrition channels.
- Wellness:Holistic health and longevity positioning in subscription and natural retail channels.
Healthcare holds installed capacity. Wellness is expanding most quickly in share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics favor the United States and Germany as net importers of precision fermentation-derived collagen building blocks, while South Korea and China balance domestic production with selective ingredient sourcing. Trade flows concentrate where wellness retail infrastructure and regulatory substantiation frameworks have matured.
United States
DSHEA structure-function claims accelerate nutraceutical deployment for skin elasticity and joint support formulations. FDA oversight through GRAS and food additive pathways constrains supplier qualification timelines. Utah-based vertical supply chains for pea and rice protein concentrates serve domestic powder and liquid collagen manufacturers.
Germany
EFSA health claim authorization under the EU Nutrition and Health Claims Regulation compresses marketing timelines for beauty-from-within positioning. The EU Green Deal procurement preference directs institutional foodservice toward sustainable protein systems. Bavarian and North Rhine-Westphalian wellness retail chains demand exclusive formulation partnerships that lock out competing brands.
South Korea
MFDS-registered beauty-from-within products drive peptide bioavailability research for skin elasticity claims. K-beauty export demand pulls through domestic fermentation capacity for recombinant collagen precursors. Seoul Capital Area concentration of contract manufacturing organizations supplies both local brands and regional export markets.
China
Dual carbon goals and evolving GB standards for protein hydrolysates create unpredictable registration timelines for MIIT and SAMR approvals. Domestic precision fermentation capacity expands for recombinant collagen building blocks. Yangtze River Delta and Pearl River Delta clusters host pilot-scale hybrid peptide production for nutraceutical export.
India
BIS standards and FSSAI framework for nutraceuticals remain less stringent than EFSA thresholds, offering first-mover positioning for peptide characterization methodologies. Import dependency for organic pea protein concentrates persists due to competing plant-based meat demand. Maharashtra and Gujarat contract manufacturers serve both domestic pharmacy channels and cross-border nutraceutical trade.
Plant Based Collagen Market Competitive Landscape
On the supply side, the industry is bifurcating between asset-light contract manufacturers and vertically integrated ingredient specialists. Tiered competitive positioning separates precision fermentation platform operators from enzymatic hydrolysis processors and white-label formulators. Strategic archetypes include biotechnology-derived building block suppliers, legacy extraction method operators, and direct-to-consumer subscription brands. Capacity expansion and strategic partnerships constitute the dominant competitive moves as firms seek to secure fermentation capacity and bypass retail slotting fees.
Within the biotechnology platform tier, Evonik Industries AG exemplifies precision fermentation leadership for recombinant collagen building blocks. Among vertically integrated specialists, Sunwarrior LLC anchors the pea-rice protein supply chain archetype with captive sourcing infrastructure. Garden of Life LLC occupies a position representing natural channel exclusivity and shelf presence concentration that smaller brands struggle to replicate.
| Leading Market Players |
|---|
| Plantigo |
| Evonik Industries AG |
| Sunwarrior LLC |
| Garden of Life LLC |
| Unived |
| SMPNutra |
| Nitta Gelatin Inc. |
| Ancient+Brave |
| OZiva |
| Others |
Value Network & Pricing Analysis
Organic pea protein concentrate volatility from competing plant-based meat demand compresses both premium tier spreads and contract manufacturer margin structures across North American and European sourcing corridors. This feedstock instability forces brands toward hybrid fermentation-derived inputs or captive rice protein cultivation to escape spot market exposure.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on EFSA health claim authorization status and cold-chain liquid format stability versus ambient powder SKUs. Pricing pressure stems from wellness retail chain slotting fee escalation that transfers downstream to ingredient suppliers. Contract manufacturers exhibit highest price sensitivity due to fixed-price white-label agreements, while direct-to-consumer subscription brands absorb premium positioning through recurring revenue models.
Supply Chain Analysis
Upstream organic pea and rice protein cultivation concentrates in the United States, Canada, and France where climate-driven yield variability threatens input security. Precision fermentation capacity for recombinant collagen building blocks clusters with contract manufacturing organizations in Germany and South Korea. Single-source vulnerability runs through limited enzymatic hydrolysis specialists capable of glycine-proline-hydroxyproline signature validation. Distribution runs through natural channel retail chains in the United States and Germany, with direct-to-consumer subscription models displacing traditional slotting-dependent pathways.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is emerging from a cyclical trough driven by EFSA health claim authorization delays that compressed marketing timelines and capital deployment. Recovery momentum builds as peptide bioavailability research validates structure-function substantiation pathways.
For Market Incumbents: Pre-empt precision fermentation capacity constraints by securing long-term offtake agreements with recombinant collagen building block specialists in Germany and South Korea. Anchor backward integration into organic rice protein cultivation in Utah and North Dakota to escape pea concentrate spot volatility. Fortify EFSA health claim dossiers before regulatory windows narrow for beauty-from-within positioning. For New Entrants and Emerging Players: Establish a beachhead in India's BIS-regulated nutraceutical channel where peptide characterization thresholds remain below EFSA stringency. Target direct-to-consumer liquid collagen subscriptions in the United States to bypass Whole Foods slotting fee structures that lock out smaller brands. Deploy hybrid fermentation-extraction peptide blends to satisfy both cost targets and clean-label positioning. For Investors and Strategic Acquirers: EFSA's tightening enforcement under the EU Nutrition and Health Claims Regulation reshapes the acquisition landscape toward clinical-stage peptide validation capabilities. Long-term viability centers on brands with human trial infrastructure and multi-jurisdiction regulatory dossiers. Target vertically integrated specialists with captive organic sourcing and fermentation partnerships. Monitor FDA GRAS notification velocity for novel recombinant building blocks as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Capacity Expansion | Recombinant collagen building block supply from Evonik platforms reduces dependency on agricultural commodity cycles. |
| EFSA Health Claim Dossier Investment | Human clinical validation for skin elasticity claims secures beauty-from-within positioning in German and French retail. |
| Direct-to-Consumer Subscription Launch | Liquid collagen formats via Shopify-enabled models capture repeat purchase cohorts outside natural channel slotting structures. |
| Backward Integration into Organic Sourcing | Captive pea and rice protein cultivation in Utah and North Dakota insulates margin from plant-based meat demand competition. |
| Hybrid Peptide Formulation Development | Fermentation-derived precursors blended with enzymatic hydrolysates balance cost targets and clean-label substantiation requirements. |
Research Methodology
Operator-level perspectives from peptide characterization chemists, nutraceutical brand managers, contract manufacturing procurement leads, and natural channel category buyers anchored the qualitative base. Secondary validation drew from FDA GRAS notifications, EFSA health claim authorization registers, MFDS product registrations, and customs trade data for organic protein concentrate flows. Bottom-up volume builds across hydrolyzed collagen, collagen peptides, liquid collagen, and gelatin formats triangulated against top-down expenditure estimates from wellness retail audit data.
Scenario-bracketing framed analytical outputs across the projection horizon, with segmentation dimensions spanning product type molecular weight tiers, pea-rice-soy-almond source combinations, skincare-nutraceutical-food-beverage-supplements applications, and healthcare-beauty-fitness-wellness end users. CAGRs derived from elasticity modeling against protein fortification expenditure trends and peptide bioavailability research investment cycles. Forecast inputs incorporated precision fermentation capacity expansion timelines and EFSA authorization pipeline velocity.
Macroeconomic conditions sit as an overlay; deviation in organic commodity prices, climate-induced agricultural yields, or cross-border nutraceutical tariff regimes would shift the trajectory. Forecasts reflect documented assumptions on peptide characterization methodology standardization and regulatory substantiation threshold evolution. Quarterly review of FDA GRAS notification cadence, EFSA opinion publication velocity, and precision fermentation capacity utilization rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Plant-Based Milk Alternatives Market
Plant Based Food
Hemp-Based Food Market
Plant Based Food
Vegan Protein Blend Market
Plant Based Food
Vegan Chocolate Market
Plant Based Food
Fermented Plant-Based Ingredient Market
Plant Based Food
Faba Bean Protein Market
Plant Based Food
China Plant Protein Market
Plant Based Food
Europe Plant-Based Meal Kit Market
Plant Based Food
Vegan Pasta Market
Plant Based Food
China Pea Protein Market
Plant Based Food
United States Plant Protein Market
Plant Based Food
Plant-Based Tzatziki and Labneh Ferment Bases Market
Plant Based Food
Vegan Diet Market
Plant Based Food
Middle East and Africa Plant-Based Egg Market
Plant Based Food
United Kingdom Soy Protein Market
Plant Based Food
Plant-Based Flour Market