
 Mexico Plant-Based Food and Beverages Market | 2026-2036
Mexico Plant-Based Food and Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Plant-Based Food and Beverages Market Foresight
Premium clean-label certification is bifurcating the Mexico plant-based landscape into mass-market and specialty tiers. NotCo leverages its AI-driven formulation platform to sustain rapid product iteration across multiple categories. Danone SA anchors its position through deep refrigerated distribution networks spanning modern trade and traditional tiendas. Sigma Alimentos competes by extending its protein processing expertise from animal into plant-based meat alternatives.
Plant-based food and beverages comprise formulated products using proteins, oils, and fibers derived from legumes, grains, nuts, or seeds, typically processed through extrusion, fermentation, or enzymatic treatment to replicate the sensory and nutritional profiles of animal-derived foods. These products serve retail and foodservice channels seeking alternatives with lower saturated fat and reduced environmental footprint. Dairy alternatives lead current revenue pools given established consumer familiarity and versatile applications, while meat alternatives represent the fastest-growing structural segment as extrusion technology improves texture fidelity. Ingredient sourcing from pea protein commands particular attention due to its functional advantages in emulsification and allergen positioning relative to soy.
COFEPRIS oversees novel food ingredient approvals and labeling compliance, while NOM-051 front-of-pack warning regulations directly shape formulation decisions and marketing claims for plant-based products. PROFECO monitors pricing and consumer protection standards that influence competitive positioning across retail channels. Stakeholders must track evolving protein import tariffs and local cultivation incentives as determinants of cost structure and supply security.
Market Dynamics
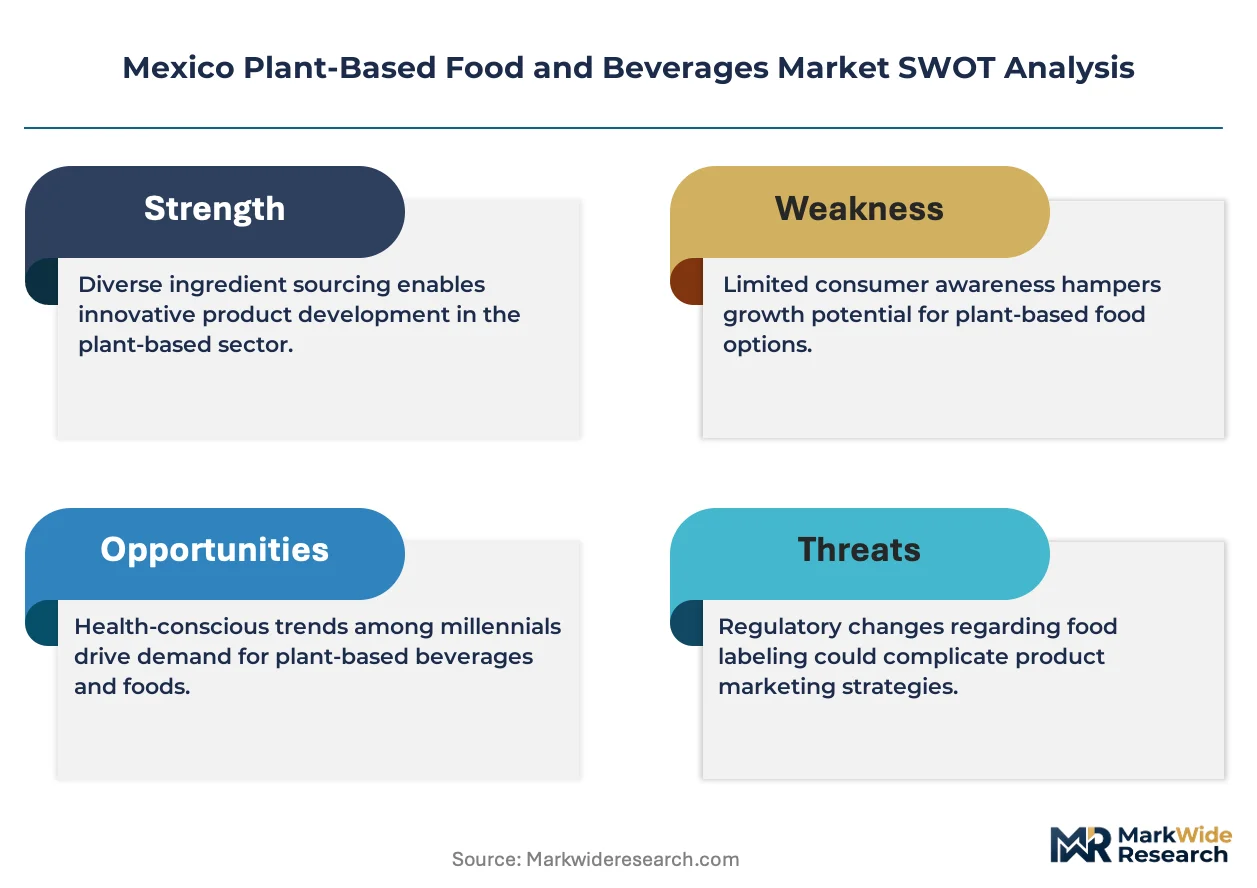
NOM-051 front-of-pack warning labels are forcing manufacturers to reformulate high-sugar dairy alternatives, compressing margins while accelerating clean-label migration across Mexico's retail and foodservice channels.
Growth Catalysts
- Oat protein extrusion:Advanced extrusion systems now replicate dairy mouthfeel in oat-based beverages, driving adoption across Mexico City's specialty coffee chains and premium grocers.
- PROFECO price transparency mandates:Standardized unit pricing regulations enable direct comparison between plant-based and conventional dairy, reducing consumer hesitation at shelf.
- Guadalajara foodservice cluster:Concentrated restaurant development in Jalisco's capital creates demonstration effects that diffuse plant-based menu integration into secondary cities.
Market Restraints
- Pea protein import dependency:Mexico lacks domestic pea cultivation at commercial scale, exposing processors to USD-denominated input volatility and tariff uncertainty.
- Almond water intensity:Almond cultivation requires approximately 5 liters of water per kernel, creating sustainability credibility gaps as drought conditions persist in northern growing regions.
- NOM-051 compliance costs:Reformulation to avoid octagonal warning labels demands R&D investment and sensory retesting that disadvantages smaller regional brands.
Strategic Opportunities
- Yucatán Peninsula tourism corridor:Cancún and Mérida hospitality operators seek differentiated plant-based offerings for international visitors, creating premium positioning opportunities outside Mexico City saturation.
- COFEPRIS novel ingredient pathway:Accelerated approval frameworks for fermentation-derived proteins enable first-mover advantage in precision fermentation dairy alternatives.
- Traditional tienda digitization:B2B ordering platforms now reach 400,000+ small-format retailers, bypassing modern trade gatekeepers for direct distribution.
Industry Challenges
- Food technologist scarcity:Mexico produces fewer than 200 graduates annually with plant protein formulation expertise, constraining product development velocity for mid-tier manufacturers.
- Refrigerated last-mile gaps:Cold chain infrastructure in southern states fails to maintain 4°C thresholds required for cultured dairy alternatives, limiting geographic expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Plant-Based Food and Beverages Market |
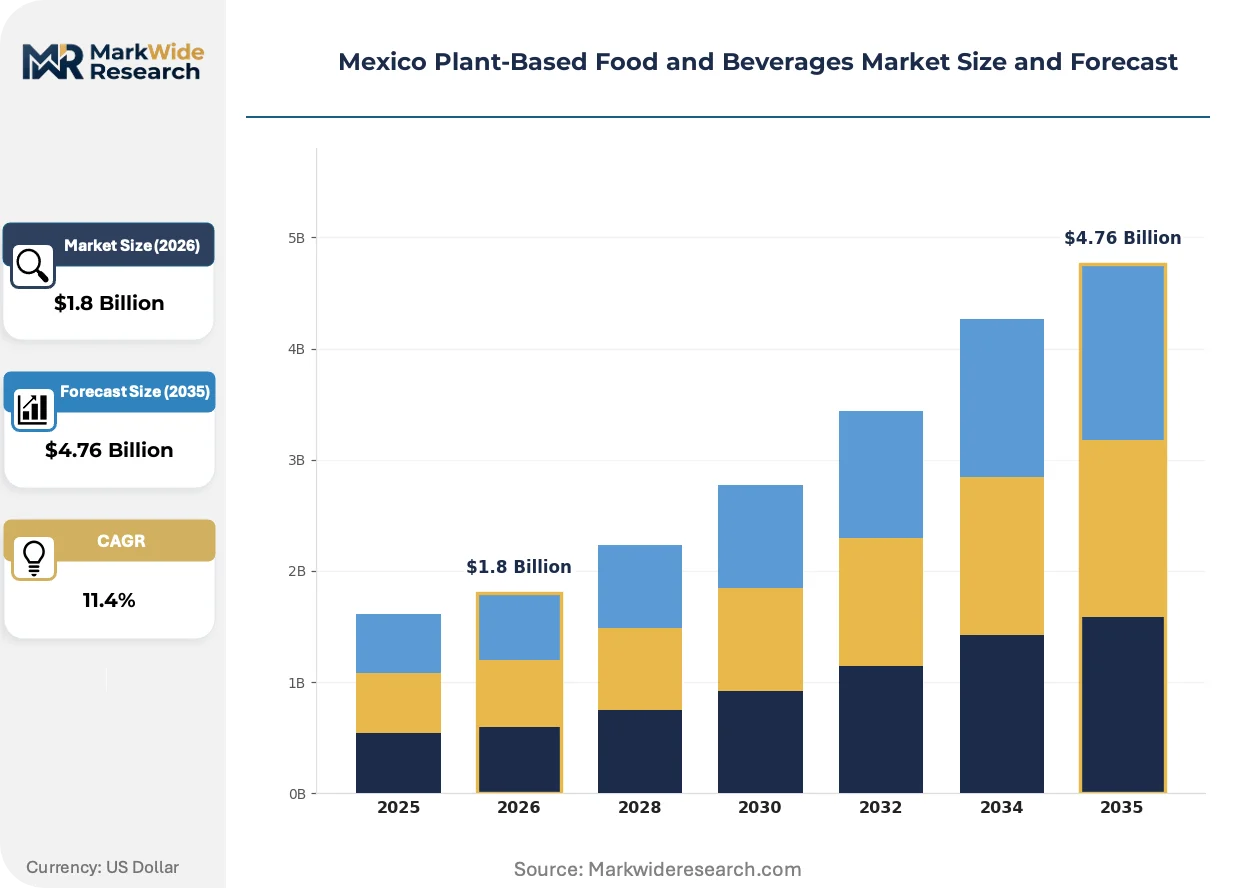
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Meat Alternatives, Dairy Alternatives, Snacks, Beverages End User: Retail Customers, Food Service, Health Enthusiasts, Vegan Consumers Ingredient Source: Pea Protein, Soy Protein, Almond, Coconut Packaging Type: Cartons, Bottles, Pouches, Flexible Packaging |
| Companies Covered | NotCo, Unilever Plc, Danone SA, Sigma Alimentos, JBS Foods, Nestle SA, Heartbest Foods, Oatly Group AB, Grupo Bimbo SAB de CV, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Plant-Based Food and Beverages Market Shifts & Advancements
Clean-label certification systems are fragmenting competitive positioning across Mexico's plant-based landscape, separating mass-market formulations from premium specialty tiers with distinct ingredient sourcing and processing claims.
Precision fermentation for dairy protein replication is bifurcating the alternative dairy segment. Biotechnology startups deploy microbial hosts to produce casein and whey without animal agriculture. Major retailers in Polanco and Santa Fe districts now allocate separate chilled sections for fermentation-derived versus conventional plant-based milks. This separation is compressing price parity timelines while enabling premium positioning for precision fermentation products that carry novel food approvals from COFEPRIS.
NOM-051 warning label implementation continues reshaping formulation priorities across Mexican manufacturing. The regulation mandates black octagonal seals for products exceeding sugar, sodium, or saturated fat thresholds. Dairy alternative producers reformulate with enzymatic sugar reduction and alternative sweeteners to avoid shelf stigma. Oat and almond beverages with sub-threshold formulations command expanded facings in Chedraui and Soriana chains.
Consumer verification behavior now extends to ingredient provenance claims. Mexican buyers scan QR codes linking to sourcing documentation for pea protein and coconut oil inputs. This pattern concentrates among households in Monterrey and Querétaro metropolitan zones where disposable income supports premium verification. Retailers respond by demanding batch-level traceability from suppliers as a listing condition.
Mexico Plant-Based Food and Beverages Market Segmentation
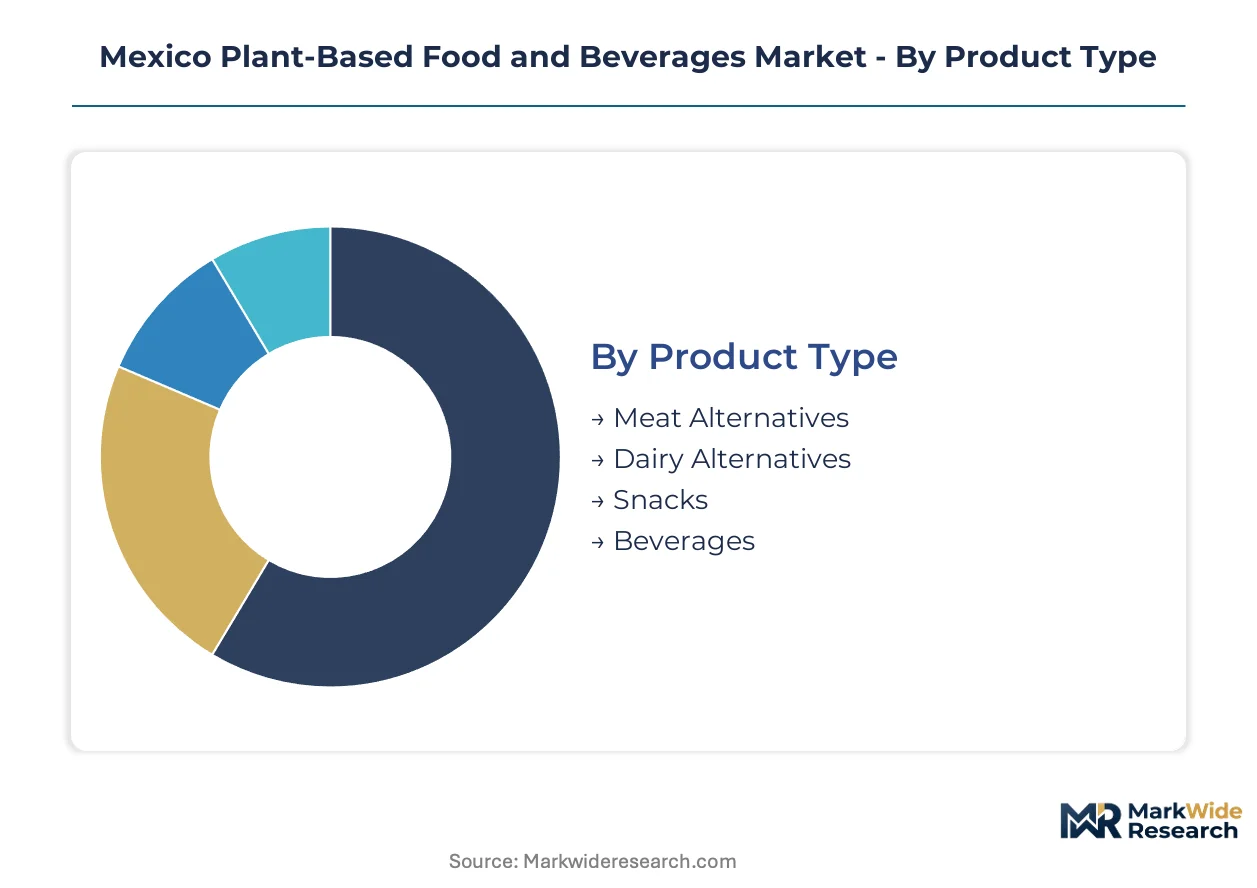
Segmentation in Mexico's plant-based market reveals how NOM-051 compliance costs and ingredient sourcing constraints concentrate competitive advantage across specific product tiers and channel configurations. Understanding these divisions exposes where substitution pressure from conventional alternatives remains strongest.
Product Type:
Dairy alternatives face the most acute substitution pressure from conventional products given entrenched consumer habits and price sensitivity in Mexico's traditional retail channels.
- Dairy Alternatives:Oat and almond-based beverages dominate refrigerated sections through enzymatic processing that replicates dairy mouthfeel. Demand concentrates in Mexico City and Guadalajara specialty coffee chains where barista-grade foam stability commands premium positioning.
- Meat Alternatives:Extruded pea and soy protein formulations replicate ground meat textures through high-moisture extrusion systems. Foodservice operators in Jalisco's restaurant cluster drive adoption as menu differentiation tools against conventional protein options.
- Snacks:Roasted chickpea and lentil-based formats target convenience positioning in OXXO and 7-Eleven chains.
- Beverages:Ready-to-drink protein shakes and functional blends serve post-workout consumption occasions in Monterrey fitness channels.
Dairy alternatives retain volume leadership; meat alternatives hold the steepest expansion curve.
End User:
Margin structures diverge sharply across customer types, with foodservice commanding formulation customization premiums unavailable in standardized retail channels.
- Food Service:Restaurant and café operators demand bulk formats with consistent performance across batch preparations. Guadalajara's concentrated hospitality development creates demonstration effects that diffuse menu integration into secondary Mexican cities.
- Retail Customers:Mainstream shoppers purchasing through Chedraui and Soriana chains prioritize unit price competitiveness and NOM-051 warning label avoidance.
- Health Enthusiasts:Protein-conscious consumers in Querétaro and Monterrey metropolitan zones verify ingredient provenance through QR-coded sourcing documentation.
- Vegan Consumers:Ethically motivated buyers sustain specialty tier demand for certified clean-label products in Polanco and Santa Fe districts.
Retail customers anchor volume absorption; foodservice generates the highest per-unit margin realization.
Ingredient Source:
Supply security concerns reshape procurement priorities as import dependency exposes processors to currency volatility and tariff uncertainty.
- Pea Protein:Functional advantages in emulsification and allergen positioning relative to soy support premium applications. Mexico lacks domestic cultivation at commercial scale, forcing reliance on North American and European import channels.
- Almond:Water intensity of approximately five liters per kernel creates sustainability credibility gaps as drought conditions persist in northern growing regions.
- Soy Protein:Established processing infrastructure and lower input costs sustain mass-market positioning despite allergen labeling requirements.
- Coconut:Southeast Asian sourcing supports clean-label positioning for premium dairy alternatives targeting tropical flavor profiles.
Soy protein maintains cost leadership; pea protein climbs the fastest on functional premiumization.
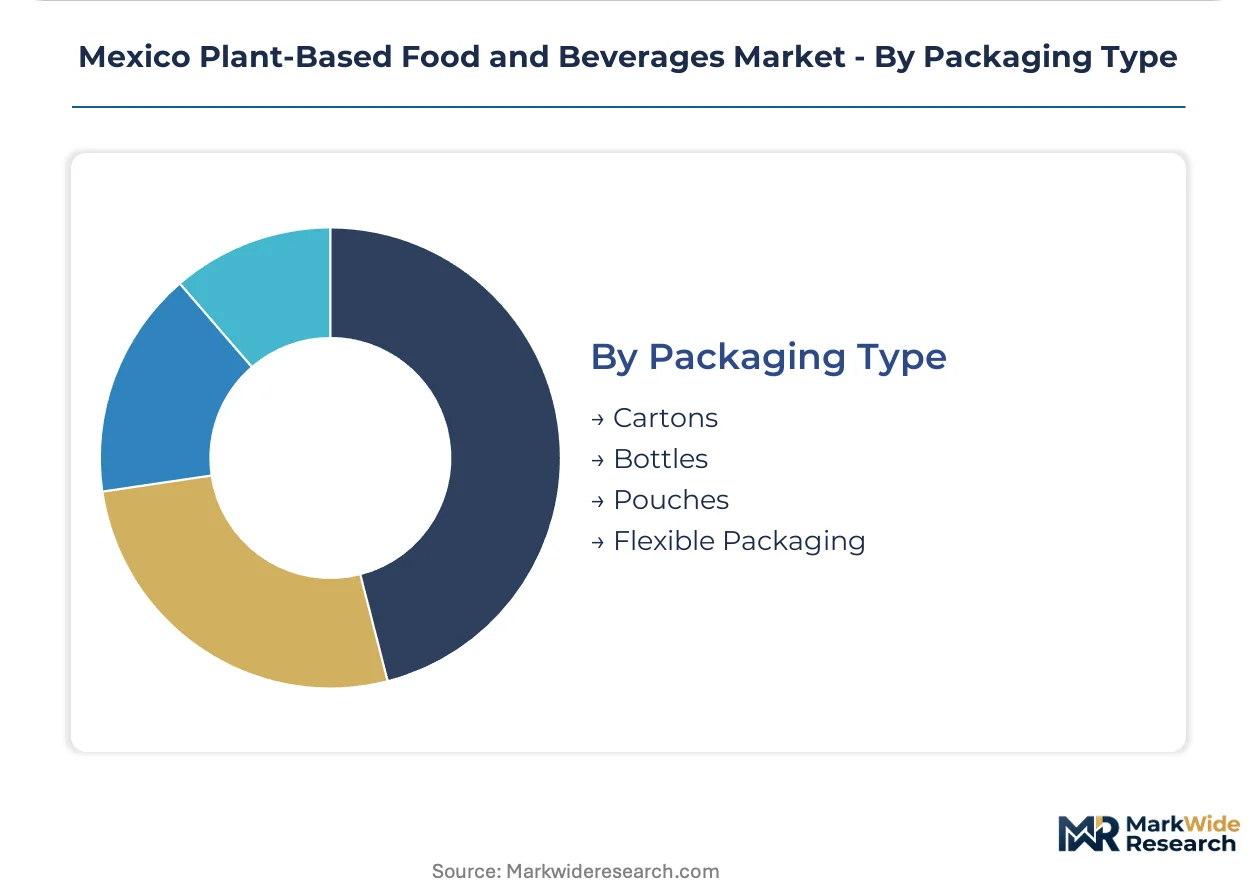
Packaging Type:
Cold chain capabilities constrain format selection as refrigerated distribution gaps in southern states limit geographic expansion for temperature-sensitive products.
- Cartons:Aseptic brick formats enable ambient distribution through traditional tiendas lacking refrigeration infrastructure. Shelf-stable oat and soy beverages reach 400,000+ small-format retailers via B2B ordering platforms.
- Bottles:PET and HDPE containers serve ready-to-drink beverages requiring resealability for on-the-go consumption in urban transit corridors.
- Pouches:Flexible stand-up formats reduce shipping cube for e-commerce fulfillment and subscription box services targeting health enthusiasts.
- Flexible Packaging:Vacuum-sealed films preserve freshness for extruded meat alternatives distributed through modern trade refrigerated cases.
Cartons dominate volume throughput; bottles capture the highest value-per-liter realization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexico's plant-based sector operates with a structural trade deficit in protein inputs, importing pea and soy concentrates while exporting finished beverages and meat alternatives to Central American markets. Regional demand concentrates in metropolitan corridors where cold chain infrastructure supports refrigerated distribution.
Mexico City Metro
Specialty coffee chains and premium grocers in Polanco and Santa Fe districts drive barista-grade oat beverage adoption. NOM-051 warning label compliance shapes shelf placement decisions across Chedraui and Soriana headquarters operations. The concentration of foodservice operators creates formulation feedback loops that diffuse into national menu standards.
Nuevo León
Monterrey's fitness-conscious households sustain demand for protein shakes and functional beverages with QR-code verification of ingredient provenance. PROFECO price transparency mandates enable direct unit-price comparison between plant-based and conventional dairy in modern trade channels. Industrial parks in Apodaca host extrusion equipment for meat alternative production serving northern markets.
Jalisco
Guadalajara's restaurant cluster generates demonstration effects that diffuse plant-based menu integration into secondary cities across western Mexico. Local food technologists collaborate with extrusion specialists to refine high-moisture protein textures. The metropolitan area anchors regional distribution for refrigerated dairy alternatives reaching Colima and Michoacán.
Bajío Region
Querétaro's health enthusiast segment verifies sourcing documentation through batch-level traceability systems demanded by specialty retailers. COFEPRIS novel ingredient approvals attract fermentation-derived protein pilots seeking accelerated regulatory pathways. The region's logistics connectivity supports ambient carton distribution to traditional tiendas lacking refrigeration.
Yucatán Peninsula
Cancún and Mérida hospitality operators seek differentiated plant-based offerings for international tourism corridors. B2B ordering platforms bypass modern trade gatekeepers to reach small-format retailers across Campeche and Yucatán states. Clean-label certification commands premium positioning in hotel and resort channels.
Mexico Plant-Based Food and Beverages Market Competitive Landscape
Concentration sits with multinational food conglomerates holding deep refrigerated distribution networks and established brand equity in Mexican retail channels. The competitive structure spans three tiers: global CPG giants with portfolio diversification strategies, regional specialists leveraging local protein processing expertise, and AI-native entrants with rapid formulation iteration capabilities. Dominant competitive moves include strategic partnerships with foodservice operators and technology licensing agreements for extrusion and enzymatic processing systems.
Within the multinational tier, Danone SA and Unilever Plc occupy positions anchored by decades of refrigerated route-to-market infrastructure. Nestle SA exemplifies portfolio diversification across beverage and meat alternative categories. Among regional specialists, Sigma Alimentos represents the protein processing expertise extension from animal into plant-based applications. NotCo sits within the technology-native archetype, with its AI-driven formulation platform enabling cross-category product development velocity that compresses traditional R&D timelines.
| Leading Market Players |
|---|
| NotCo |
| Unilever Plc |
| Danone SA |
| Sigma Alimentos |
| JBS Foods |
| Nestle SA |
| Heartbest Foods |
| Oatly Group AB |
| Grupo Bimbo SAB de CV |
| Others |
Supply & Pricing Matrix
NOM-051 certification compliance gates both supplier qualification and shelf-price positioning across Mexico's plant-based retail channels. Manufacturers that achieve clean-label formulations without octagonal warning seals command expanded facings in Soriana and Chedraui chains, while reformulation costs compress margins for mid-tier brands unable to absorb R&D investments.
Pricing Analysis
Retail customers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation separates fermentation-derived dairy alternatives in Polanco specialty grocers from mass-market soy beverages in traditional tiendas. Pricing pressure stems from PROFECO-mandated unit transparency enabling direct comparison with conventional dairy. Health enthusiasts in Monterrey show lowest price sensitivity, while budget-conscious households in southern states drive volume through economy tiers.
Supply Chain Analysis
Strategic stockpiling of pea protein concentrates characterizes procurement behavior as processors buffer against USD-denominated import volatility. Supply concentrates in Canada and the United States for pea cultivation, with Southeast Asian sources for coconut oil inputs. Raw material dependencies include North American pea protein isolates, enzymatic processing aids, and aseptic packaging films. Tariff exposure on protein imports creates margin vulnerability for domestic extrusion operations. Distribution runs through refrigerated networks anchored by Mexico City and Guadalajara distribution hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation technology represents a high-growth disruption trajectory for Mexico's plant-based sector, with COFEPRIS novel ingredient approvals compressing commercialization timelines for casein and whey alternatives.
For Market Incumbents: Compound refrigerated distribution advantages through exclusive channel partnerships with Guadalajara's restaurant cluster. Invest in enzymatic sugar reduction capabilities to maintain NOM-051 compliance without sensory degradation. Vertical integration into oat protein processing mitigates exposure to North American import volatility. For New Entrants and Emerging Players: B2B ordering platform penetration gaps in Yucatán Peninsula tiendas offer white-space access to 400,000+ small-format retailers bypassing modern trade gatekeepers. Target Cancún hospitality operators seeking differentiated clean-label offerings for international tourism corridors. Launch through direct-to-chef sampling programs that demonstrate extruded meat alternative performance in high-volume kitchen environments. For Investors and Strategic Acquirers: COFEPRIS accelerated approval frameworks reshape the acquisition landscape toward fermentation-derived protein assets with novel food clearances. Five-to-ten year viability favors precision fermentation specialists with demonstrated regulatory pathway execution. Monitor pea protein tariff negotiation outcomes as inflection indicator for domestic processing cost structures.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Sugar Reduction Investment | NOM-051 compliance without octagonal warnings secures shelf positioning in Soriana and Chedraui chains. |
| Precision Fermentation Scale-Up | COFEPRIS novel ingredient approvals enable premium dairy alternatives in Polanco and Santa Fe districts. |
| B2B Platform Distribution Expansion | Direct tienda reach bypasses modern trade concentration and unlocks southern state penetration. |
| Guadalajara Foodservice Partnership | Restaurant cluster demonstration effects diffuse menu integration into western Mexico secondary cities. |
| Pea Protein Import Diversification | Multi-origin sourcing hedges USD currency exposure and tariff uncertainty for extrusion operations. |
Research Methodology
The analysis maps dairy alternatives, meat alternatives, and precision fermentation platforms, each validated through food technologists, category buyers at Chedraui and Soriana, COFEPRIS regulatory affairs specialists, and extrusion equipment operators. Primary interviews with supply chain managers and R&D directors combined with secondary validation against COFEPRIS novel food registries, PROFECO pricing databases, and customs import records. Bottom-up volume modeling triangulated against top-down category spend estimates.
Consistency checks validated projections against external benchmarks including refrigerated beverage consumption patterns and foodservice menu integration rates. Segmentation dimensions modeled include product type, ingredient source, packaging format, and end-user channel across the projection horizon. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection timing and technology adoption curves. Forecast inputs incorporated NOM-051 compliance cost assumptions and pea protein import price elasticity.
Underlying assumptions cover sustained drought conditions in northern almond-growing regions and stable COFEPRIS approval timelines, with deviation risk concentrated in tariff renegotiation outcomes and cold chain infrastructure expansion in southern states. Revision becomes warranted when fermentation-derived product penetration in Mexico City metro crosses mass-market adoption thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Vegan Spaghetti Market
Plant Based Food
Vegan Dessert Market
Plant Based Food
Global Organic Soy Protein Market
Plant Based Food
Fermented Plant Protein Market
Plant Based Food
Vegan Chocolate Market
Plant Based Food
United States Pea Protein Market
Plant Based Food
Fermented Plant-Based Food Market
Plant Based Food
Europe Plant-Based Seafood Market
Plant Based Food
Plant-Based Wellness Foods Market
Plant Based Food
Vegan Bacon Market
Plant Based Food
Africa Soy Beverages Market
Plant Based Food
Middle East and Africa Plant-Based Egg Market
Plant Based Food
Pea Protein Market
Plant Based Food
Plant-Based Burger Market
Plant Based Food
Indonesia Plant-Based Food and Beverages Market
Plant Based Food
Smart Plant Based Food Packaging Market