
 Global Vegan Fast Foods Market | 2026-2036
Global Vegan Fast Foods Market Size, Share, and Industry Trends Forecast 2026-2036
Global Vegan Fast Foods Market Outlook
Menu engineering and limited-time plant-based offerings is rewriting where fast-food chains capture margin across dayparts. Beyond Meat leverages pea-protein extrusion technology to anchor supply relationships with major quick-service operators. Impossible Foods sustains heme-based formulation leadership that differentiates its patty chemistry from commodity soy isolates. McDonald's Corporation controls the largest single-brand distribution footprint for vegan items across its U.S., German, and British locations.
Global vegan fast foods encompass plant-protein formulations, vegetable-based patties, and dairy-free condiments engineered to replicate the sensory profile of conventional quick-service items through extrusion, fermentation-derived flavoring, and lipid structuring. These products serve commercial foodservice and retail channels seeking to reduce animal-derived inputs without sacrificing throughput speed or menu familiarity. Burgers occupy the dominant volume position within product type segmentation, while wraps and salads represent faster-growing formats as grab-and-go occasions expand. Online retail and food trucks capture disproportionate growth velocity among distribution channels, whereas supermarkets retain the largest absolute transaction base through frozen and chilled ready-meal placement.
The FDA enforces allergen labeling and GRAS notification requirements for novel plant proteins entering U.S. interstate commerce, while the EU Green Deal's Farm to Fork strategy pressures member states to reduce livestock-derived foodsystem emissions. EFSA novel food assessments create a gatekeeping function for fermented or cell-cultured ingredients seeking European market access. Stakeholders must monitor how national protein-transition policies in Germany, the Netherlands, and the United Kingdom reshape procurement specifications and public-sector catering contracts.
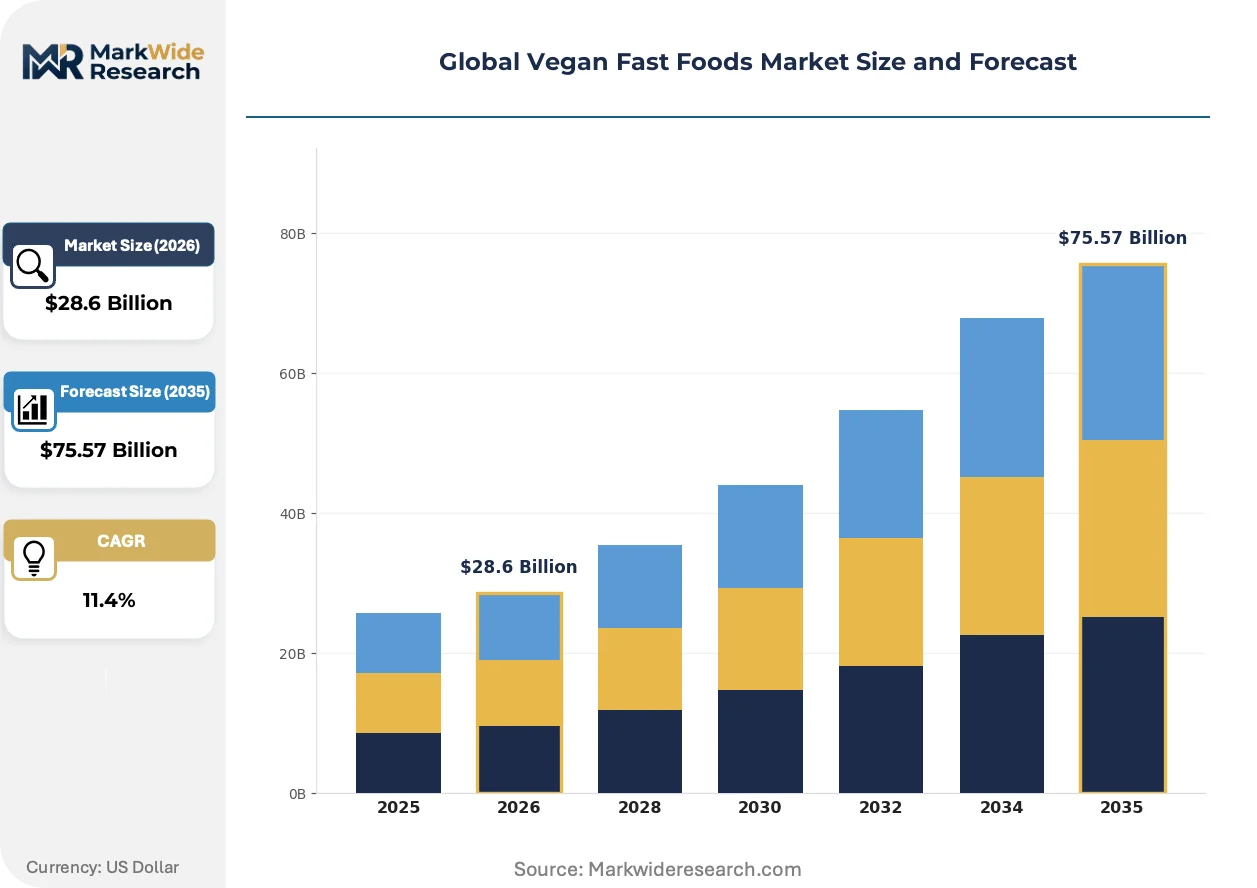
Market Dynamics
Quick-service restaurant chains are reconfiguring kitchen workflows around pea-protein extrusion and fermentation-derived fat systems, compressing cook times while meeting EU Green Deal emission thresholds. This operational pivot is redrawing supplier relationships and capital allocation across the value chain.
Growth Catalysts
- EU Green Deal procurement mandates:Public-sector catering contracts across Germany and the Netherlands now require minimum plant-based meal ratios, creating guaranteed offtake volumes for certified suppliers.
- Heme-based formulation chemistry:Fermentation-derived leghemoglobin is replicating the Maillard reaction profile of beef, allowing chains to retain core menu items without animal inputs.
- Urban density in the United Kingdom:London and Manchester foodservice clusters are piloting dedicated vegan production lines, generating operational templates for rapid replication.
Market Restraints
- Pea protein supply concentration:North American and Canadian pulse processors control 70% of food-grade isolate capacity, exposing formulators to crop yield volatility and tariff friction.
- EFSA novel food assessment timelines:Fermented or cell-cultured ingredients face 18-24 month authorization windows, delaying European commercialization for innovators.
- Price elasticity in quick-service value tiers:Plant-based patties carry 15-40% ingredient cost premiums over commodity beef, constraining penetration in price-sensitive dayparts.
Strategic Opportunities
- Food truck and ghost kitchen channels:Low-capex mobile formats in Berlin and Los Angeles are testing limited-time vegan offerings without retrofitting legacy restaurant infrastructure.
- Dual carbon goals in China:Provincial governments are subsidizing plant-protein R&D, creating joint-venture entry points for extrusion technology licensors.
- FDA GRAS self-determination pathway:Streamlined notification for soy and wheat proteins is accelerating U.S. market entry relative to European novel food regimes.
Industry Challenges
- Extrusion technician scarcity:High-moisture extrusion operation requires specialized protein chemistry knowledge that outpaces vocational training pipeline output in food manufacturing hubs.
- Cross-contamination certification:Vegan Society and Plant Based Foods Association standards demand segregated production lines, complicating co-manufacturing arrangements for mid-scale brands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Vegan Fast Foods Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $75.57 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Burgers, Sandwiches, Wraps, Salads End User: Individuals, Families, Restaurants, Cafés Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Food Trucks Price Tier: Economy, Mid-Range, Premium, Luxury |
| Companies Covered | McDonald's Corporation, Burger King Corporation, KFC Corporation, Subway, Taco Bell, Domino's Pizza, Inc., Beyond Meat, Impossible Foods, Veggie Grill, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Vegan Fast Foods Market Strategic Shifts
Digital twin modeling of extrusion parameters is compressing product development cycles, while regulatory divergence between FDA self-certification and EFSA gatekeeping is fragmenting go-to-market strategies. These forces are simultaneously accelerating formulation precision and complicating geographic expansion.
High-moisture extrusion technology is virtualizing the texture engineering process for plant-based patties. Quick-service chains in Germany and the United States are deploying these systems to achieve fibrous mouthfeel without batch-to-batch sensory variation. The technology is virtualizing quality control overhead, allowing smaller operators to match multinational consistency benchmarks without captive R&D facilities.
The EU Green Deal's Farm to Fork strategy is mandating lifecycle emission disclosures for foodservice procurement by 2030. This is forcing reformulation priorities toward locally sourced legumes and reduced processing energy intensity. German and Dutch contract caterers are responding by pre-qualifying suppliers against ISO 14064 carbon accounting standards ahead of enforcement deadlines.
Grab-and-go occasions are displacing seated dining as the dominant vegan fast-food consumption context. Airport terminals, university campuses, and hospital food courts in the United Kingdom and United States are expanding chilled ready-meal placement. This rotation is compressing holding-time requirements and favoring lipid-structured emulsions that maintain sensory stability across extended distribution windows.
Global Vegan Fast Foods Market Segmentation
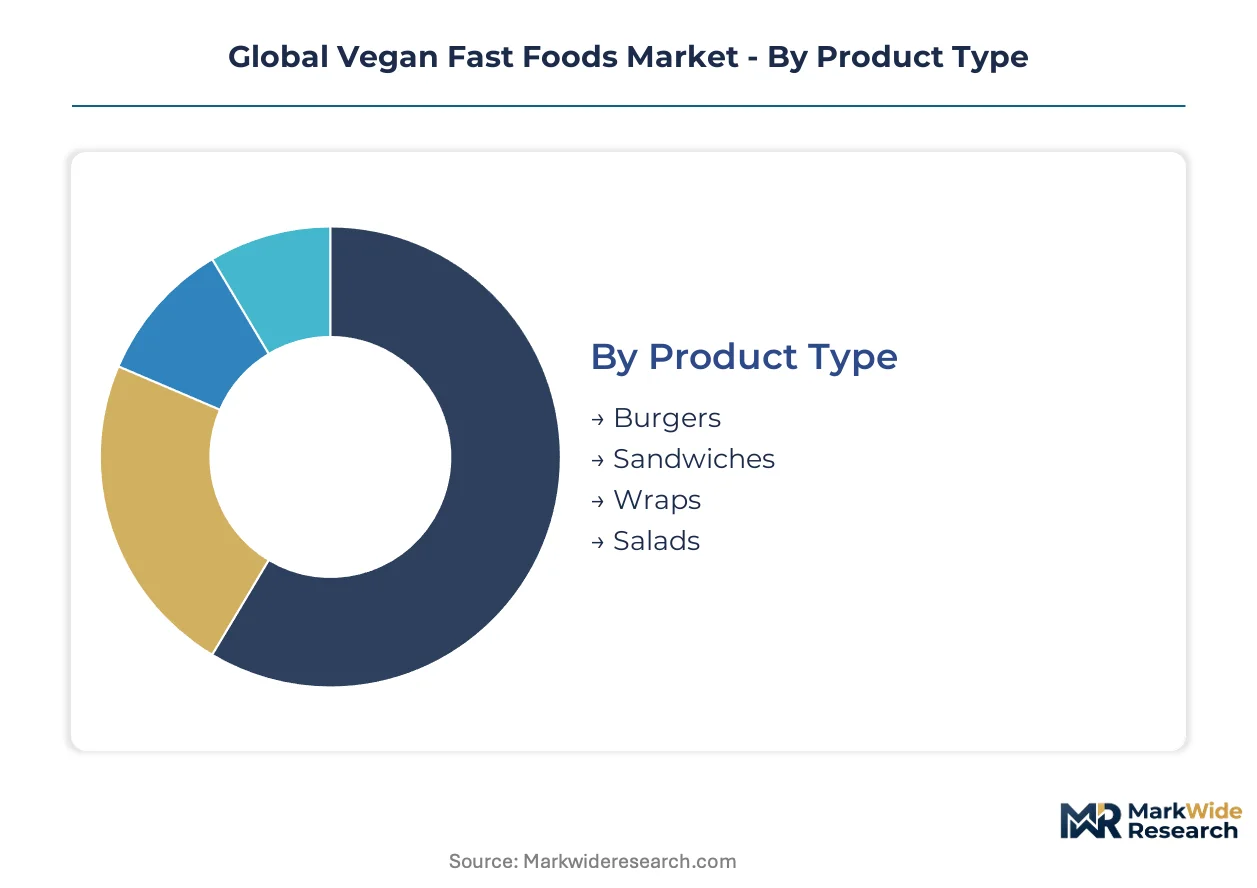
Segmentation in vegan fast foods determines equipment compatibility, procurement specifications, and margin architecture across distinct consumption contexts. Each dimension carries unique supply chain and operational implications for manufacturers and foodservice operators.
Product Type:
After-sales service intensity varies sharply across formats, with extruded protein systems requiring specialized maintenance versus fresh-assembly items.
- Burgers:High-moisture extrusion technology replicates fibrous beef texture through controlled shear and thermal processing. Demand concentrates in German and U.S. quick-service chains where kitchen retrofit costs favor patty-based menu integration over equipment-intensive alternatives. The format benefits from established supplier relationships with pea-protein processors.
- Wraps:Flatbread assembly lines accommodate diverse vegetable fillings and fermented protein strips with lower capital expenditure than patty extrusion. United Kingdom grab-and-go channels and airport terminals are expanding chilled wrap placement, driven by compressed holding-time requirements and extended distribution windows.
- Sandwiches:Sliced protein formats leverage existing deli infrastructure with minimal workflow reconfiguration.
- Salads:Fresh-assembly items carry minimal equipment dependency and rapid menu rotation capability.
Burgers hold the largest share; momentum sits with wraps.
End User:
Volume concentration and purchasing behavior diverge significantly between institutional procurement and individual consumption patterns.
- Individuals:Single-serve occasions dominate mobile and digital-native channels, with app-based ordering compressing decision windows and favoring familiar formats. Urban density in London and Los Angeles sustains dedicated vegan production lines optimized for throughput speed.
- Families:Multi-portion occasions concentrate in suburban supermarket frozen aisles and drive-thru formats where price elasticity constrains premium positioning. German and Dutch public-sector catering mandates are expanding guaranteed offtake volumes for certified family-meal suppliers.
- Restaurants:Full-service integration requires segregated prep lines and cross-contamination certification under Vegan Society standards.
- Cafés:Limited kitchen footprints favor pre-assembled components and reduced holding equipment.
Individuals command current volume; families are expanding most quickly.
Distribution Channel:
Capital requirements and margin capture potential structure competitive positioning across physical and digital pathways.
- Supermarkets:Frozen and chilled ready-meal placement retains the largest absolute transaction base through established cold-chain infrastructure. United Kingdom and United States retailers are pre-qualifying suppliers against ISO 14064 carbon accounting standards ahead of EU Green Deal enforcement deadlines.
- Online Retail:Direct-to-consumer subscription models and rapid-delivery platforms capture disproportionate growth velocity among urban professionals. Berlin and Los Angeles ghost kitchen clusters test limited-time offerings without legacy restaurant retrofit costs.
- Convenience Stores:Extended-hour access points favor shelf-stable and refrigerated grab-and-go formats with minimal preparation.
- Food Trucks:Low-capex mobile formats enable geographic flexibility and menu experimentation with reduced regulatory compliance burden relative to fixed establishments.
Supermarkets dominate absolute transactions; online retail gains share fastest.
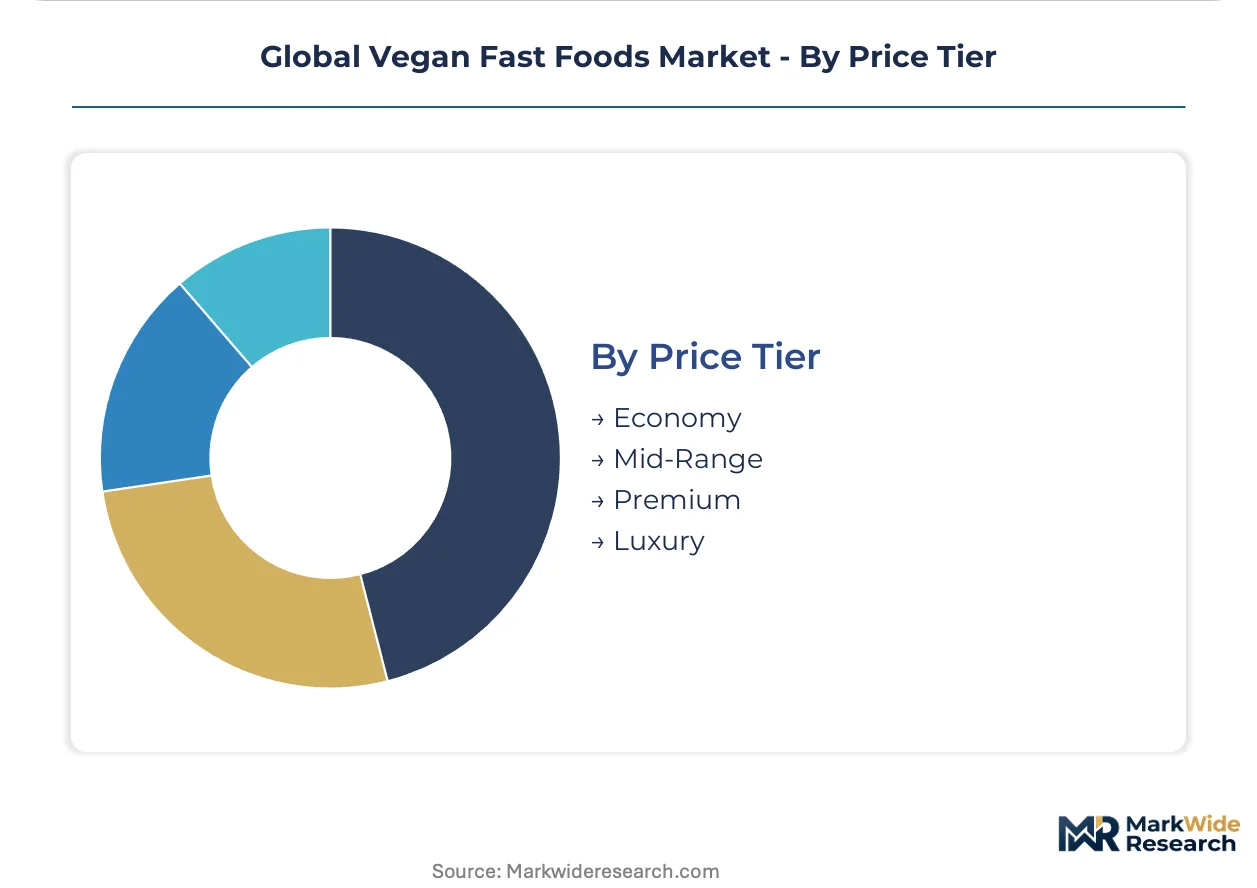
Price Tier:
Ingredient cost premiums and certification requirements stratify positioning across value and premium positioning.
- Economy:Commodity soy and wheat protein bases serve price-sensitive dayparts where 15-40% plant-based cost premiums constrain penetration. Value-tier procurement concentrates in U.S. and German quick-service value menus with high volume and low margin tolerance.
- Premium:Pea-protein isolates and fermentation-derived flavoring command ingredient cost premiums offset by heme-based formulation differentiation. McDonald's Corporation and major quick-service operators anchor this tier through supply relationships with Beyond Meat and Impossible Foods.
- Mid-Range:Blended protein formulations balance cost and sensory performance for mainstream adoption.
- Luxury:Small-batch fermentation and cell-cultured ingredients face 18-24 month EFSA novel food assessment timelines, delaying European commercialization.
Premium commands revenue concentration; economy shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across national markets. German and Dutch institutional buyers absorb premium plant-based costs through public-sector mandates, while U.S. value-tier consumers resist ingredient premiums above 20%. United Kingdom urban professionals show intermediate elasticity, accepting modest premiums for convenience.
Germany
Public catering contracts under the EU Green Deal guarantee minimum plant-based meal ratios, creating institutional demand floors. EFSA novel food assessments regulate fermented ingredient entry, though domestic pea-protein processors expedite GRAS-equivalent pathways. Berlin foodservice clusters pilot dedicated vegan production lines for rapid operational template replication.
United States
FDA GRAS self-determination accelerates soy and wheat protein market entry versus European timelines. Quick-service chains retrofit kitchens around high-moisture extrusion systems to compress cook times. Los Angeles ghost kitchen clusters test limited-time vegan offerings without legacy restaurant infrastructure investment.
United Kingdom
London and Manchester foodservice density supports dedicated vegan production line economics. ISO 14064 carbon accounting standards pre-qualify suppliers ahead of EU Green Deal enforcement alignment. Airport terminals and university campuses expand chilled ready-meal placement for grab-and-go occasions.
Netherlands
Provincial protein-transition policies reshape procurement specifications for contract caterers. Farm to Fork lifecycle emission disclosure mandates force reformulation toward locally sourced legumes. Rotterdam port logistics clusters concentrate plant-protein import and extrusion equipment distribution.
China
Provincial dual carbon goals subsidize plant-protein R&D and extrusion technology joint ventures. National regulators align novel protein oversight with evolving GB standards for food safety. Yangtze River Delta manufacturing hubs scale pea-protein isolate capacity for domestic quick-service integration.
Global Vegan Fast Foods Market Competitive Environment
Capability concentration sits with extrusion technology licensors and fermentation-derived flavoring specialists; scale advantage sits with quick-service chains controlling distribution footprints. The market structures around three tiers: multinational restaurant operators with captive menu placement, specialized protein formulators with patented chemistry, and regional foodservice contractors with public-sector certification. Dominant competitive moves include strategic partnerships between protein suppliers and restaurant chains, plus geographic licensing of extrusion technology to compress competitor R&D cycles.
Within the multinational quick-service tier, McDonald's Corporation and Burger King Corporation anchor global distribution capacity for plant-based menu integration. Among specialized formulators, Beyond Meat and Impossible Foods exemplify divergent protein chemistry approaches—pea-protein extrusion versus heme-based fermentation—each representing distinct paths to sensory replication of conventional fast-food items.
| Leading Market Players |
|---|
| McDonald's Corporation |
| Burger King Corporation |
| KFC Corporation |
| Subway |
| Taco Bell |
| Domino's Pizza, Inc. |
| Beyond Meat |
| Impossible Foods |
| Veggie Grill |
| Others |
Value Chain & Pricing Dynamics
Rotterdam port logistics clusters concentrate pea-protein isolate import and extrusion equipment distribution, anchoring European formulators' ingredient cost structures and compressing margin flexibility for downstream quick-service operators. This geographic chokepoint amplifies pricing power for North American pulse processors while exposing EU buyers to tariff friction and crop yield volatility.
Pricing Analysis
After-sales service contracts for high-moisture extrusion systems drive lifetime value capture for equipment licensors. Three-tier pricing structure across premium, standard, and economy levels segments buyers by certification grade and volume commitment. Pricing pressure stems from commodity beef cost benchmarks constraining plant-based patty premiums in U.S. value-tier dayparts. Quick-service chains show highest price sensitivity; premium positioned operators absorb ingredient premiums through heme-based formulation differentiation.
Supply Chain Analysis
Export-control restrictions on extrusion technology licensing limit equipment flow to Chinese manufacturing hubs seeking domestic capacity buildout. Canada and the United States anchor food-grade pea-protein isolate supply. Raw material dependencies center on yellow pea cultivation, fermentation-derived leghemoglobin, and lipid structuring agents. Single-source vulnerability concentrates in North American pulse processing. Distribution runs through Rotterdam logistics clusters into German and Dutch quick-service production networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among multinational quick-service chains controlling captive menu placement, fragmenting supplier negotiating leverage across mid-scale protein formulators.
For Market Incumbents: Pre-empt emerging entrants by securing exclusive supply relationships with fermentation-derived flavoring specialists before EFSA novel food assessments unlock European capacity. Invest in ISO 14064 carbon accounting certification ahead of EU Green Deal enforcement deadlines. Capacity addition in Yangtze River Delta manufacturing hubs hedges against North American pulse supply concentration. For New Entrants and Emerging Players: Establish a beachhead in United Kingdom airport terminal and university campus grab-and-go channels where chilled wrap placement outpaces patty-format saturation. Food truck and ghost kitchen formats in Berlin and Los Angeles offer lowest-capex entry with limited legacy infrastructure retrofit requirements. Direct-to-consumer subscription models bypass incumbent quick-service gatekeepers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among extrusion technology licensors with equipment-plus-service bundling. Five-to-ten year viability favors specialists with patented heme-based or pea-protein chemistry protected from commodity substitution. Acquisition targets should demonstrate EFSA pre-submission progress or FDA GRAS self-determination completion. Monitor provincial protein-transition policy announcements in Germany and the Netherlands as demand inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| High-Moisture Extrusion Licensing | Equipment licensors capture recurring service revenue from quick-service kitchen retrofits across German and U.S. chains. |
| Fermentation-Derived Flavoring Partnership | Heme-based formulation specialists anchor premium tier positioning through Maillard reaction chemistry differentiation. |
| Carbon Accounting Certification | ISO 14064 pre-qualification secures procurement eligibility under EU Green Deal Farm to Fork mandates. |
| Ghost Kitchen Channel Expansion | Low-capex mobile formats in Los Angeles and Berlin test limited-time offerings without fixed infrastructure investment. |
| Provincial R&D Joint Ventures | Dual carbon goal subsidies in Chinese manufacturing hubs localize extrusion capacity away from import dependency. |
Study Parameters
Operator-level perspectives from quick-service procurement directors, extrusion equipment technicians, plant-based R&D formulators, and contract catering managers anchored the qualitative base. Primary interviews combined with secondary validation against FDA GRAS notifications, EFSA novel food registers, EU Green Deal policy documents, and ISO 14064 certification databases. Bottom-up volume modeling triangulated against top-down expenditure estimates across product type, end user, distribution channel, and price tier segmentation.
Scenario-bracketing around regulatory approval timelines and protein-transition policy intensity shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product format, buyer archetype, channel format, and certification tier. CAGRs derived from elasticity-adjusted volume projections incorporating pea-protein supply constraints and quick-service menu penetration curves. Industry-specific inputs encompassed extrusion equipment deployment rates and EFSA assessment queue dynamics.
Sensitivities concentrate around EFSA novel food authorization delays, North American pulse crop yields, and EU Green Deal enforcement calibration. Forecasts reflect documented assumptions on regulatory timelines and supply chain configuration. Material shifts in public-sector procurement mandate timing or export-control restrictions on extrusion technology would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Plant-Based Food Ingredients Market
Plant Based Food
Plant-Based Ham Market
Plant Based Food
Vegan Noodles Market
Plant Based Food
Vegan Flavor Market
Plant Based Food
China Pea Protein Market
Plant Based Food
India Plant Based Milk Market
Plant Based Food
Fermented Plant-Based Ingredient Market
Plant Based Food
Plant-Based Burger Market
Plant Based Food
France Plant Protein Market
Plant Based Food
Meatless Meat Market
Plant Based Food
Rhubarb Root Extract Market
Plant Based Food
Vegan Gelatin Market
Plant Based Food
Europe Plant-Based Meal Kit Market
Plant Based Food
China Plant-Based Food and Beverages Market
Plant Based Food
Plant-Based Shrimp Market
Plant Based Food
Plant Based Eggs Market