
 Plant Based Cheese Market | 2026-2036
Plant Based Cheese Market Size, Share, and Industry Trends Forecast 2026-2036
Plant Based Cheese Market Analysis
Precision fermentation and enzymatic modification of plant proteins is reconfiguring how manufacturers replicate the stretch, melt, and mouthfeel of conventional dairy cheese. Miyoko's Creamery leverages traditional creamery techniques adapted to cashew and oat bases to sustain premium positioning. Flora Food Group anchors European retail penetration through Violife's coconut-oil formulations. Daiya Foods Inc. dominates North American foodservice channels with its tapioca-starch cheddar platforms.
Plant based cheese comprises protein isolates, plant oils, and stabilizers fermented or processed to mimic the functional properties of animal-derived cheese, typically achieving 15-30% protein content and melt points between 50°C and 70°C for pizza and sandwich applications. Cheddar and mozzarella variants lead volume because they satisfy the formulation requirements of quick-service restaurants and frozen pizza manufacturers. Coconut-based sources occupy the largest share of commercial production due to fat-structure compatibility, though cashew and almond bases command premium shelf positioning in specialty shops. Foodservice and retail chains together represent the dominant end-user channel, with households growing fastest through online subscription and direct-to-consumer platforms.
FDA labeling requirements for dairy terms and USDA organic certification shape product nomenclature and ingredient sourcing in the United States, while EFSA novel food assessments and EU Green Deal sustainability benchmarks govern market entry and clean-label claims across Europe. REACH compliance for processing aids and packaging migration limits adds compliance layers for exporters. Stakeholders must monitor evolving enzyme approval pathways and carbon-footprint disclosure mandates to secure formulation flexibility and geographic expansion options.
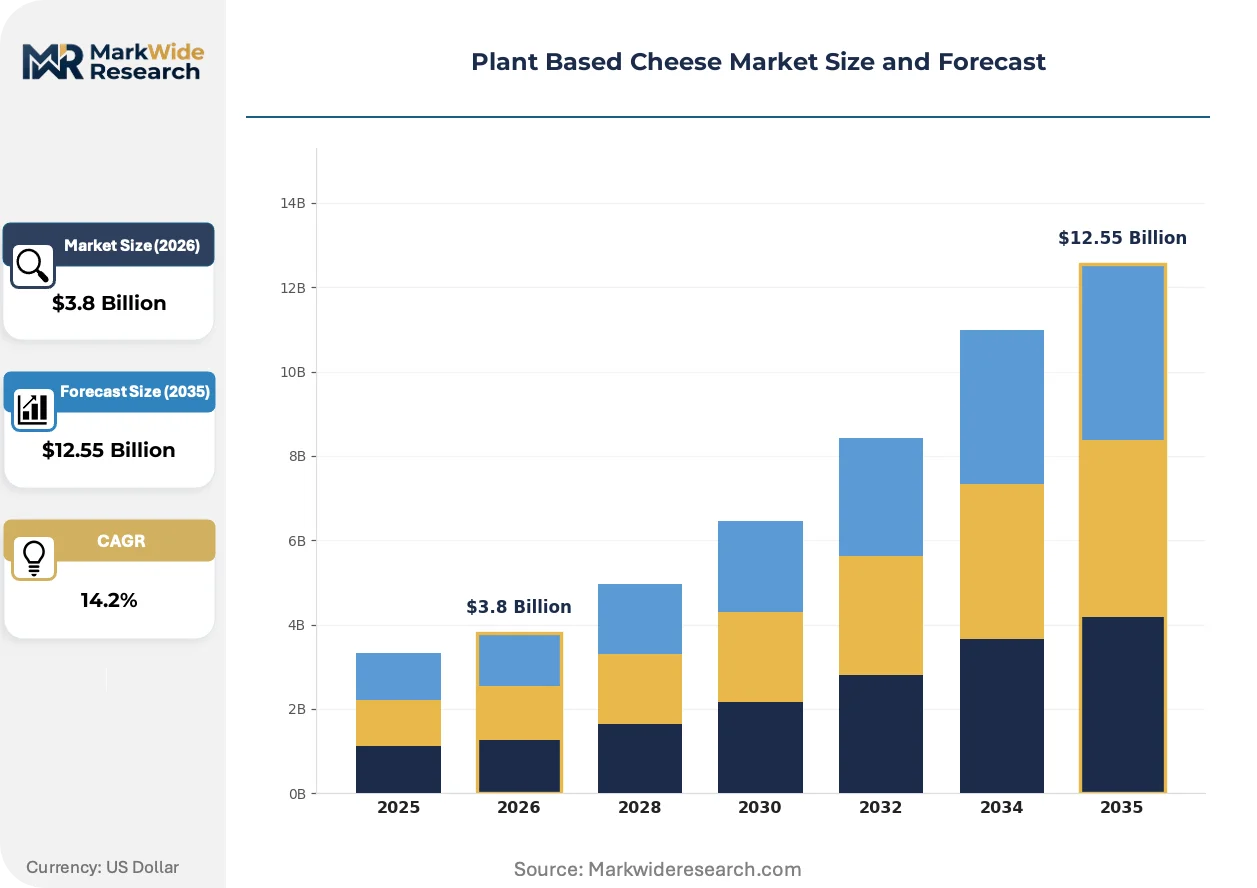
Market Dynamics
Precision fermentation is virtualizing traditional dairy biochemistry, enabling manufacturers to replicate casein micelle structures without livestock inputs. This technological inflection compresses the functional gap between plant-derived and animal-derived cheese, forcing incumbents to reformulate or cede premium positioning.
Growth Catalysts
- EU Green Deal carbon-footprint mandates:The EU Green Deal's Farm to Fork strategy imposes binding sustainability disclosures on food manufacturers, creating procurement preference for plant-based alternatives in German and French retail chains.
- Quick-service restaurant menu expansion:North American fast-casual chains now standardize dairy-free cheese slots across sandwich and pizza lines, normalizing plant-based options for mainstream consumers.
- F-Gas Regulation processing bans:The EU F-Gas Regulation phases out hydrofluorocarbon cooling in food manufacturing, accelerating adoption of enzymatic and fermentation-based thermal processes that align with plant cheese production.
Market Restraints
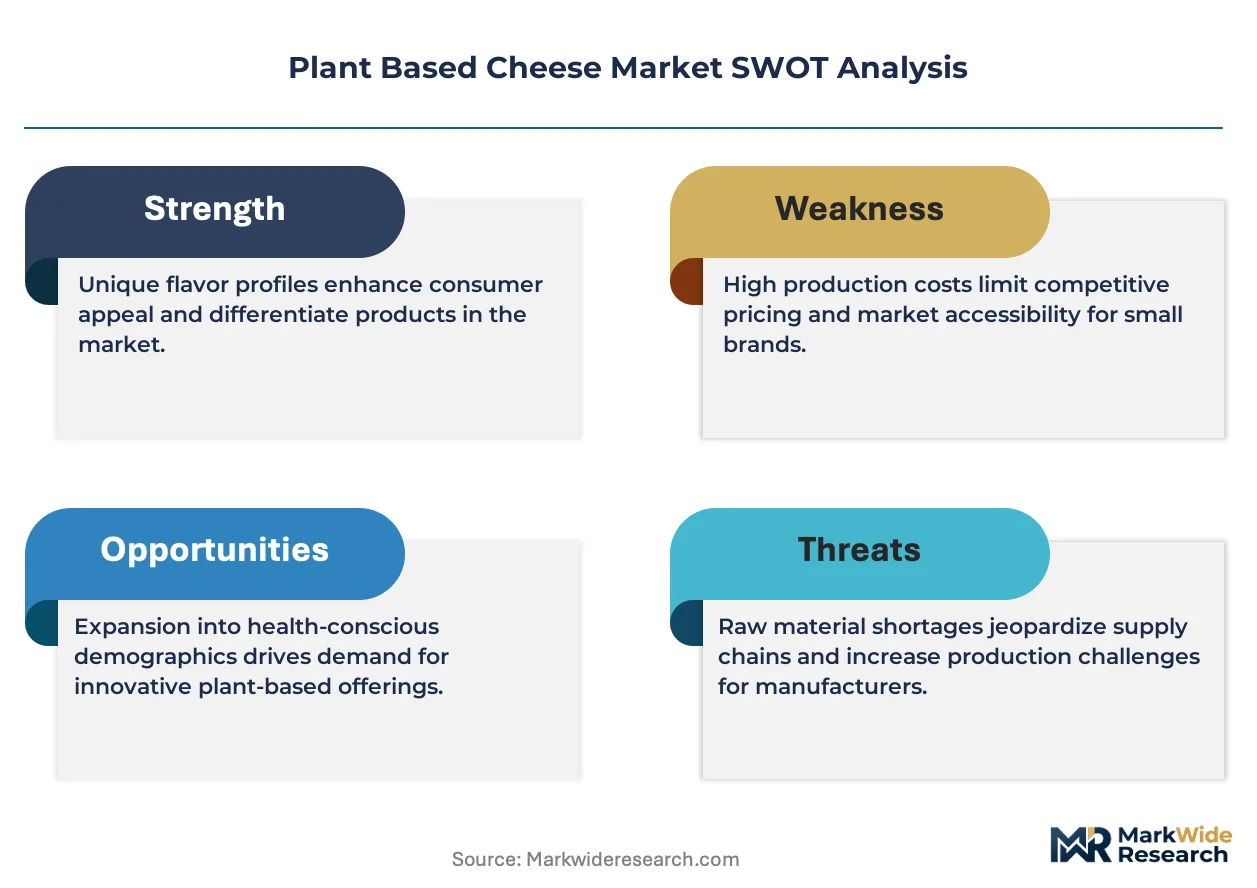
- Coconut oil price volatility:Coconut fat constitutes the dominant lipid base for commercial plant cheese, leaving formulations exposed to Philippine and Indonesian weather-driven supply shocks.
- FDA dairy term restrictions:The FDA's enforcement discretion on "cheese" labeling creates nomenclature fragmentation, forcing costly dual-SKU strategies for US market entry.
- Protein isolate supply concentration:Pea and fava protein isolates concentrate among a handful of North American and European processors, creating input bottlenecks for mid-tier manufacturers.
Strategic Opportunities
- Pizza manufacturer white-label partnerships:Frozen pizza producers in Italy and Spain seek dedicated plant-cheese supply agreements, offering volume commitments for customized melt-profile formulations.
- EFSA novel enzyme approvals:Pending EFSA assessments for microbial transglutaminase variants could unlock texture improvements for European manufacturers ahead of competitors.
- Direct-to-consumer subscription channels:Specialty cashew-based and almond-based variants bypass retail slotting fees through Shopify-integrated subscription models targeting UK and US coastal households.
Industry Challenges
- Fermentation bioprocess talent scarcity:Precision fermentation operations require hybrid skill sets spanning food science and bioreactor engineering, with limited training pipelines in traditional dairy regions.
- USDA organic certification timelines:Multi-year transition periods for organic oil sourcing delay clean-label claims, compressing margin windows for brands targeting premium positioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant Based Cheese Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cheddar, Mozzarella, Cream Cheese, Parmesan Source: Coconut, Almond, Cashew, Soy End User: Restaurants, Retail Chains, Foodservice, Households Distribution Channel: Online, Grocery Stores, Specialty Shops, Food Distributors |
| Companies Covered | Daiya Foods Inc., Kite Hill, Miyoko’s Creamery, Follow Your Heart, Tofutti Brands, Inc., Flora Food Group (Violife), Bute Island Foods Ltd., GreenSpace Brands, Danone S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant Based Cheese Market Emerging Trajectories
Bioprocess engineering is collapsing the functional performance gap between plant-derived and animal-derived cheese. Three converging developments are restructuring how manufacturers formulate, label, and distribute across retail and foodservice channels.
Precision fermentation-derived casein is virtualizing the structural foundation of conventional cheese. Startups and established ingredient suppliers now cultivate dairy-identical proteins in bioreactors, supplying B2B customers with functional bases that melt and stretch indistinguishably from animal-derived equivalents. Quick-service restaurants in California and New York pilot these inputs for pizza applications, compressing the timeline for mainstream acceptance of next-generation plant cheese.
REACH compliance for processing aids is tightening migration limits on packaging and enzyme carriers. The European Chemicals Agency's updated substance restrictions force reformulation of stabilizer systems and printing inks used in cheese analog packaging. German and Dutch manufacturers face the steepest adaptation costs, accelerating consolidation among suppliers capable of certifying full supply chain compliance.
Retail buyers now unbundle cheese procurement from legacy dairy category management. UK and French supermarket chains establish dedicated plant-based buying functions with separate margin targets and shelf-space allocation rules. This organizational split enables faster listing decisions for innovative formats but demands that suppliers maintain distinct sales teams and trade marketing budgets for conventional and alternative cheese lines.
Plant Based Cheese Market Segmentation
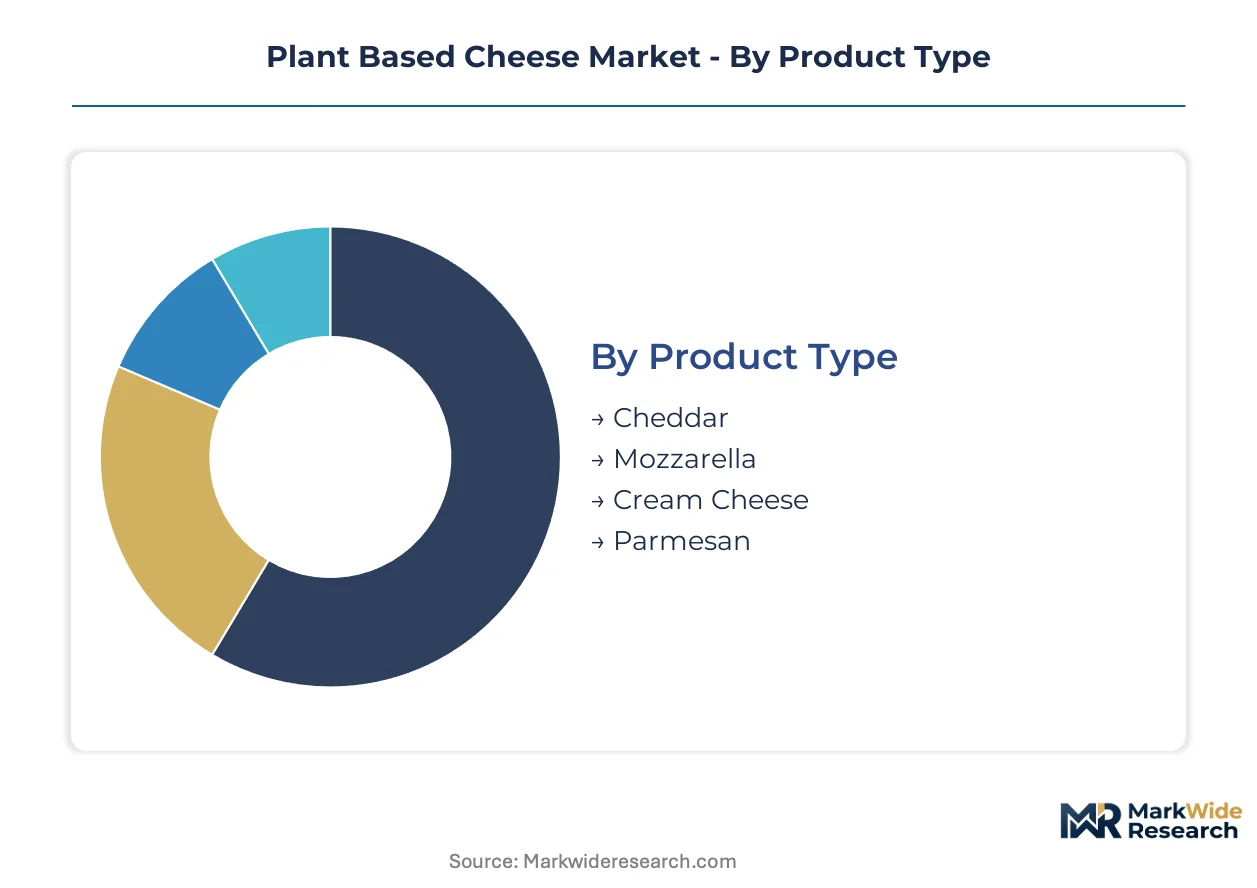
Plant-based cheese manufacturers configure production lines and ingredient sourcing around distinct functional requirements. Segment-specific melt profiles, fat structures, and certification demands create divergent margin architectures across product types and distribution channels.
Product Type:
Cheddar and mozzarella variants turn inventory fastest through quick-service restaurant contracts, while cream cheese and parmesan rotate more slowly through specialty retail.
- Cheddar:Tapioca-starch and coconut-oil formulations achieve 50°C–60°C melt points for sandwich applications. Frozen pizza manufacturers in Italy and Spain concentrate procurement here, driven by quick-service restaurant menu standardization.
- Mozzarella:Stretch-optimized protein networks using enzymatic modification replicate casein micelle behavior. California and New York pizza chains drive demand, constrained by fermentation bioprocess capacity bottlenecks.
- Cream Cheese:Higher moisture content (45-55%) requires modified stabilizer systems for spreadability.
- Parmesan:Aged flavor profiles depend on precision fermentation-derived lipase enzymes for umami replication.
Cheddar dominates installed base. Mozzarella is where expansion concentrates.
Source:
Cost tiers separate commodity-scale coconut bases from premium-positioned cashew and almond alternatives.
- Coconut:Dominates commercial production due to fat-structure compatibility with analog cheese matrices. German and French retail chains source here for price-accessible private label lines, though Philippine weather volatility creates supply risk.
- Cashew:Premium shelf positioning in UK and US coastal specialty shops. Shopify-integrated subscription models bypass retail slotting fees for this segment.
- Almond:Clean-label appeal aligns with USDA organic certification timelines, compressing margin windows.
- Soy:Lowest input cost but declining share due to allergen labeling requirements and consumer preference shifts.
Coconut anchors volume scale. Cashew commands the steepest expansion trajectory.
End User:
Foodservice channels move bulk volumes through annual contracts, while household demand fragments across direct-to-consumer subscriptions.
- Restaurants:Quick-service chains in North America standardize dairy-free slots across sandwich and pizza lines. Procurement runs through centralized distribution agreements with melt-profile specifications.
- Retail Chains:UK and French supermarkets now maintain separate plant-based buying functions with distinct margin targets and shelf-space rules.
- Foodservice:Institutional caterers and contract food operators represent stable mid-volume demand.
- Households:Fastest-climbing segment through online subscription platforms targeting specialty format preferences.
Restaurants lock in contracted volumes. Households are expanding most quickly.
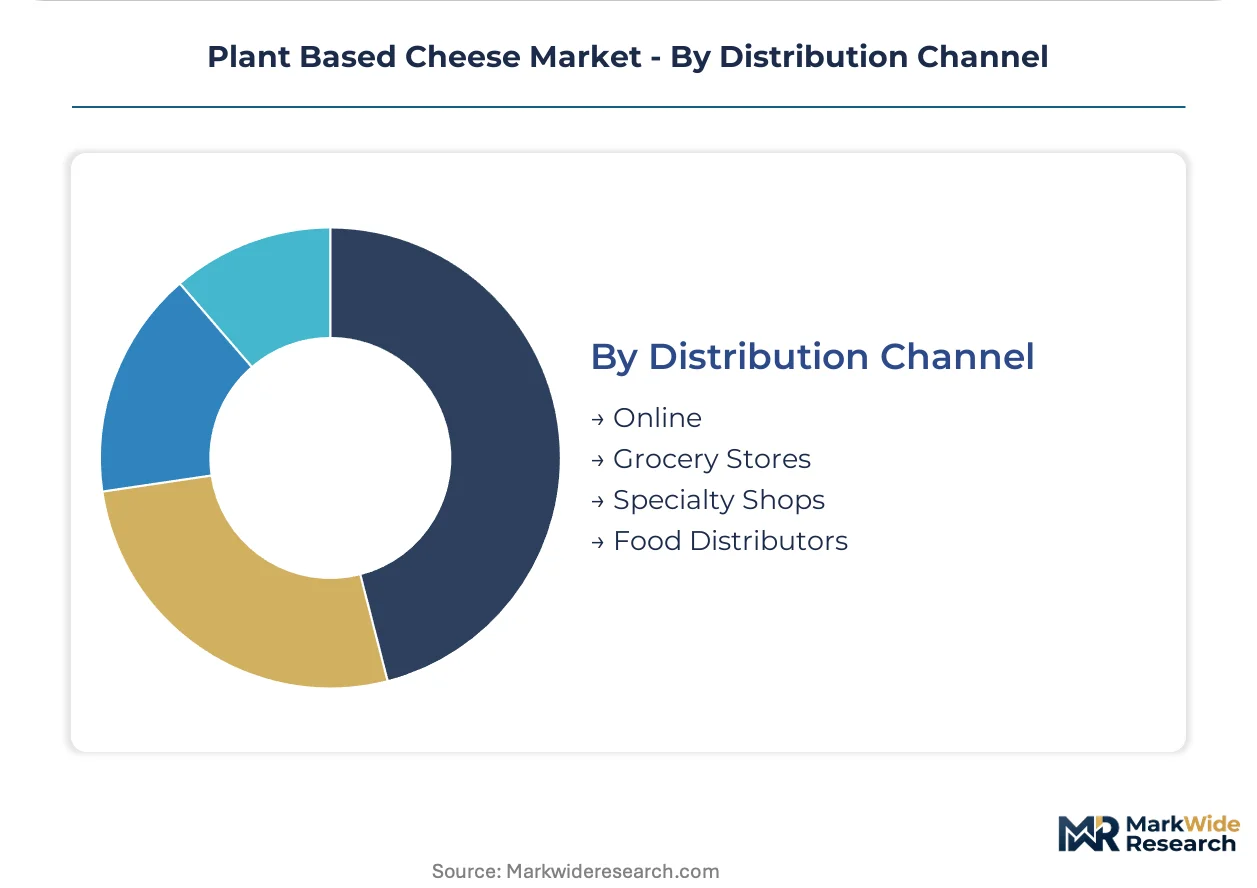
Distribution Channel:
Geographic reach and customer touchpoint intensity vary sharply across channel structures.
- Online:Direct-to-consumer models capture UK and US coastal households for cashew-based and almond-based premium variants. Subscription economics bypass retail margin stacking.
- Grocery Stores:Mass-market penetration for coconut-based cheddar and mozzarella formats. German retail chains prioritize EU Green Deal compliance disclosures here.
- Specialty Shops:Curated selection of fermented and enzymatically modified premium lines.
- Food Distributors:B2B logistics for restaurant and foodservice procurement with temperature-controlled handling requirements.
Grocery stores dominate installed base. Online channels concentrate expansion investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Quick-service restaurant chains and retail buyers concentrate procurement authority in four national markets, each imposing distinct formulation and compliance requirements on suppliers.
United States
California and New York pizza chains pilot precision fermentation-derived casein for melt-profile standardization. FDA enforcement discretion on "cheese" labeling forces dual-SKU strategies for national distribution. Chicago and Los Angeles anchor foodservice procurement concentration for tapioca-starch cheddar platforms.
Germany
Retail chains prioritize EU Green Deal carbon-footprint disclosures for private-label coconut-oil lines. ECHA REACH compliance tightens migration limits on packaging stabilizers and enzyme carriers. Berlin and Hamburg concentrate reformulation investment for enzymatic processing adaptations.
United Kingdom
Supermarket chains maintain dedicated plant-based buying functions with separate margin targets and shelf-space rules. EFSA novel food assessments govern enzyme approval pathways for texture optimization. London and Manchester drive subscription-model adoption for cashew-based premium variants.
France
Frozen pizza manufacturers in the Italian and Spanish border regions seek white-label supply agreements for customized melt profiles. EU F-Gas Regulation phases out hydrofluorocarbon cooling in manufacturing facilities. Lyon and Paris cluster clean-label formulation development for organic certification timelines.
Canada
Health Canada and PMRA govern processing aid approvals and organic certification for cross-border suppliers. Quick-service restaurant menu standardization mirrors US dairy-free slot expansion. Toronto and Vancouver concentrate direct-to-consumer platform development for coastal household penetration.
Plant Based Cheese Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented tier structures. The vendor base separates into foodservice-dominant suppliers with centralized distribution agreements and retail-focused specialists with premium positioning. Three archetypes define competitive positioning: precision fermentation technology licensors, traditional creamery-technique adaptors, and coconut-oil commodity formulators. Capacity expansion and strategic partnerships constitute the dominant competitive moves as firms secure bioreactor capacity and enzyme supply agreements.
Within the precision fermentation tier, Miyoko's Creamery and Daiya Foods Inc. exemplify contrasting positioning strategies. Miyoko's Creamery occupies the traditional creamery-technique adaptor archetype, leveraging cashew and oat bases for premium shelf positioning. Daiya Foods Inc. anchors the foodservice-dominant archetype through tapioca-starch cheddar platforms. Flora Food Group (Violife) sits within the retail-penetration archetype, supplying coconut-oil formulations to European chains with EU Green Deal compliance positioning.
| Leading Market Players |
|---|
| Daiya Foods Inc. |
| Kite Hill |
| Miyoko's Creamery |
| Follow Your Heart |
| Tofutti Brands, Inc. |
| Flora Food Group (Violife) |
| Bute Island Foods Ltd. |
| GreenSpace Brands |
| Danone S.A. |
| Others |
Supply Flow & Price Mechanics
Bioreactor capacity underutilization in European precision fermentation facilities is compressing contract manufacturing rates and shifting supplier bargaining power toward ingredient buyers seeking casein micelle alternatives. This utilization slack feeds directly into pricing softness for enzymatically modified protein bases while coconut-oil formulators absorb Philippine weather-driven cost volatility.
Pricing Analysis
Annual cost-plus contracts with coconut oil indexation dominate procurement between German retail chains and Southeast Asian suppliers. Three-tier pricing structure across premium cashew-based, standard coconut-oil, and economy soy-based variants separates USDA organic certification tiers from conventional formulations. Pricing pressure stems from REACH compliance migration limits forcing stabilizer reformulation. Quick-service restaurant chains exhibit highest price sensitivity due to centralized volume procurement, while direct-to-consumer subscription buyers accept premium positioning.
Supply Chain Analysis
Tariff exposure between the Philippines and Germany dominates supply chain risk planning for coconut-fat-dependent formulators. Philippine and Indonesian coconut processing clusters feed European and North American manufacturing, drawing from pea protein isolates concentrated in Canada and France. Single-source vulnerability concentrates in microbial transglutaminase enzyme suppliers awaiting EFSA novel food assessments. Distribution runs through temperature-controlled food distributors serving quick-service restaurant networks and retail chain consolidation centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation casein commercialization constitutes a technological inflection disrupting traditional plant-protein formulation economics and compressing incumbent repositioning timelines.
For Market Incumbents: Entrench fermentation bioprocess capacity through backward integration into bioreactor operations or captive enzyme supply agreements. Secure EFSA novel food approval pathways ahead of competitors to defend margin position against precision fermentation entrants. Prioritize EU Green Deal carbon-footprint certification to maintain German and French retail shelf access. For New Entrants and Emerging Players: Establish a beachhead in white-label frozen pizza supply agreements with Italian and Spanish manufacturers seeking customized melt-profile formulations. Target direct-to-consumer subscription channels for cashew-based premium variants where retail slotting fees do not apply. Leverage Shopify-integrated logistics to bypass grocery store margin stacking. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across precision fermentation infrastructure, favoring early-stage equipment financing over late-stage brand acquisitions. Five-to-ten year viability hinges on enzyme approval pathway execution and bioprocess talent pipeline development. Monitor EFSA microbial transglutaminase assessment timelines as the critical signal for European manufacturing competitiveness inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Capacity Buildout | Bioreactor scale-up unlocks casein-identical protein supply for pizza chain melt-profile standardization. |
| EFSA Novel Enzyme Approval Pathway | Microbial transglutaminase clearance enables texture optimization ahead of REACH-compliant competitors. |
| Backward Integration into Coconut Processing | Upstream control over Philippine supply mitigates weather-driven lipid base price volatility. |
| Direct-to-Consumer Platform Launch | Subscription economics bypass UK and US coastal retail slotting fees for premium cashew variants. |
| EU Green Deal Certification Program | Carbon-footprint disclosure compliance secures German and French private-label procurement preference. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA enforcement discretion records, EFSA novel food assessment databases, EU Green Deal Farm to Fork strategy documents, and REACH compliance guidance. Primary interviews engaged plant-based cheese R&D directors, quick-service restaurant procurement managers, European retail category buyers, and precision fermentation bioprocess engineers. Secondary validation drew from customs trade data, SEC 10-K filings of publicly traded food manufacturers, and Nielsen retail audit records. Bottom-up volume modeling triangulated against top-down market sizing across ingredient input flows.
Forecast inputs incorporate enzymatic modification adoption curves, precision fermentation capacity expansion pipelines, and EU F-Gas Regulation phase-out timelines. Segmentation modeling spans product type, protein source, end-user channel, and distribution format across the projection horizon. CAGR derivation rests on historical volume trajectory analysis adjusted for technology substitution elasticity and regulatory approval pathway probability weighting. Pizza manufacturer procurement contract visibility and bioreactor utilization surveys inform near-term capacity assumptions.
Sensitivities concentrate around EFSA enzyme approval delays, Philippine coconut harvest volatility, and FDA labeling enforcement shifts. Forecasts embed assumptions regarding quick-service restaurant menu standardization velocity and carbon-footprint disclosure mandate implementation timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Africa Soy Beverages Market
Plant Based Food
Vegan Noodles Market
Plant Based Food
Yucca Extract Market
Plant Based Food
Europe Textured Vegetable Protein Market
Plant Based Food
Plant-Based Flour Market
Plant Based Food
South America Meat Substitute Market
Plant Based Food
Vegan Margarine Market
Plant Based Food
New Jersey Vegan Products Market
Plant Based Food
Dandelion Root Extract Market
Plant Based Food
Australia Plant Protein Market
Plant Based Food
Veggie Meals Market
Plant Based Food
Plant-Based Wellness Foods Market
Plant Based Food
Pea Protein Market
Plant Based Food
Vegan Flavor Market
Plant Based Food
United States Rice Protein Market
Plant Based Food
India Plant Based Milk Market