
 Varicose Vein Treatment Devices Market | 2026-2036
Varicose Vein Treatment Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Varicose Vein Treatment Devices Market Intelligence
The integration of real-time ultrasound guidance into catheter-based systems is rewriting the standard of care for minimally invasive procedures. Medtronic leverages its extensive R&D in cardiovascular devices to lead in radiofrequency ablation technologies. AngioDynamics specializes in endovenous laser therapy systems, competing on procedural efficiency. Boston Scientific Corporation extends its broad interventional portfolio to include solutions for venous insufficiency.
Varicose vein treatment devices encompass a range of medical instruments designed for the occlusion or removal of dilated, tortuous veins. These devices often operate on principles of thermal ablation, using laser fibers emitting at wavelengths like 1470 nm, or radiofrequency energy to collapse the vessel wall. Radiofrequency Ablation Devices and Endovenous Laser Therapy Systems represent the core of the market, offering high efficacy and shorter recovery times. Vascular Clinics and Specialized Surgical Centers are the primary end-user segments, driven by the shift from inpatient hospital procedures to outpatient settings.
Market access is governed by stringent regulatory approvals, including the FDA's 510(k) clearance process in the United States and CE marking under the MDR in Europe. In Japan, the PMDA imposes its own rigorous evaluation for device safety and efficacy, influencing product design for market entry. Device manufacturers must navigate the evolving reimbursement landscapes, which directly impacts technology adoption rates in different healthcare systems.
Market Dynamics
The structural shift from hospital-based surgeries to procedures in outpatient Vascular Clinics is the central force shaping the market. This transition prioritizes devices offering minimal invasiveness, faster recovery, and greater procedural efficiency for high-volume settings.
Growth Catalysts
- Non-Thermal Technologies:Cyanoacrylate embolization devices eliminate tumescent anesthesia needs, simplifying procedures in specialized clinics and expanding patient access.
- Aging Demographics in Europe:Germany's aging populace and high healthcare standards create concentrated, sustained demand for advanced varicose vein treatments.
- Reimbursement Shifts:Favorable reimbursement codes in the United States for minimally invasive endovenous procedures accelerate their adoption over traditional surgery.
Market Restraints
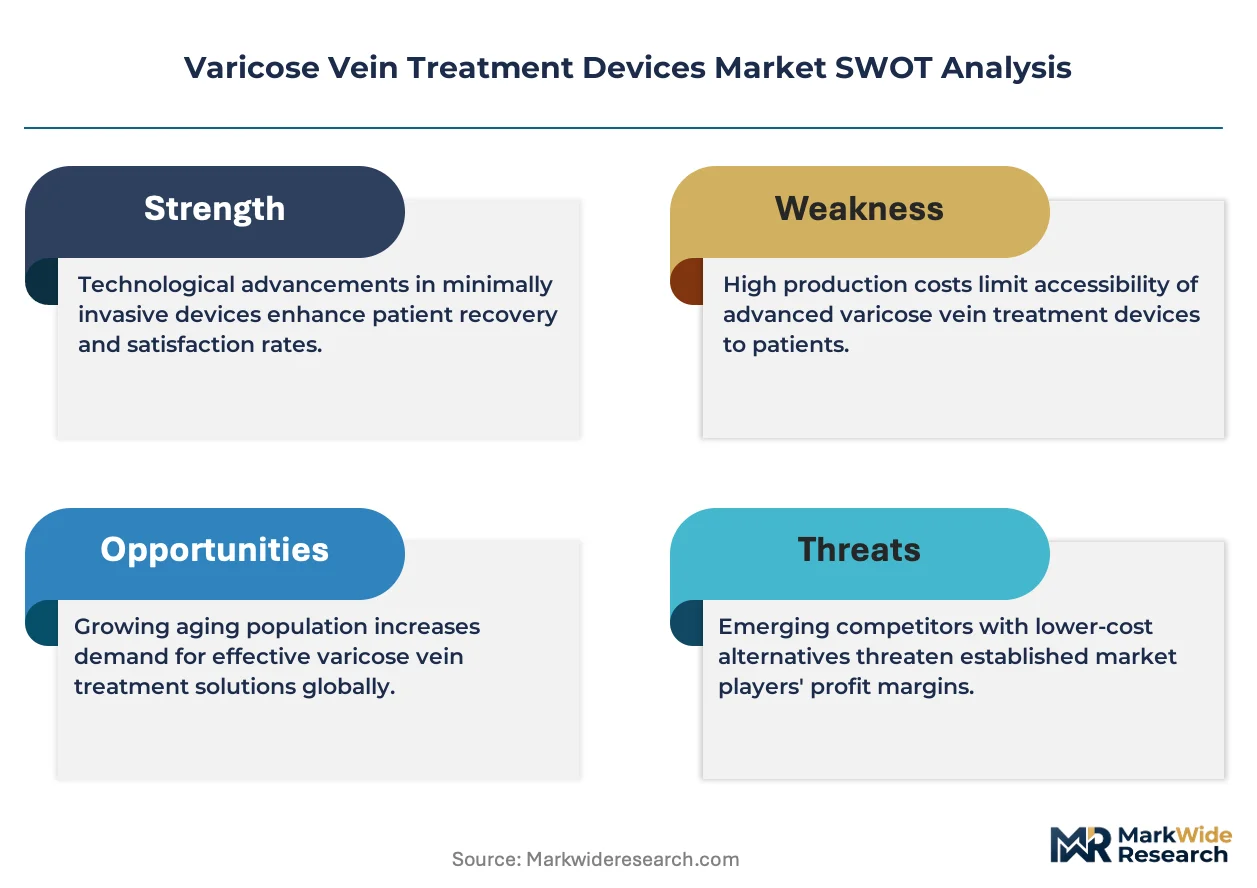
- High Capital Investment:The initial cost of radiofrequency and laser ablation systems is a significant barrier for smaller, independent Vascular Clinics.
- Regulatory Friction:The EU's Medical Device Regulation (MDR) imposes extensive clinical data requirements, delaying new device approvals and increasing costs.
- Alternative Treatments:Sclerotherapy remains a lower-cost, effective alternative for smaller veins, competing directly with more advanced device-based procedures.
Strategic Opportunities
- Emerging Market Penetration:Southeast Asian nations with improving healthcare infrastructure represent a key expansion target beyond saturated Western markets.
- Integrated Guidance Systems:Combining catheters with real-time ultrasound guidance offers a pathway to create more precise and automated treatment solutions.
- Broader Venous Applications:Developing device solutions specifically for complex Chronic Venous Insufficiency (CVI) opens a larger, underserved patient population.
Industry Challenges
- Specialized Physician Training:The effective and safe use of advanced ablation technologies requires specific training and credentialing, creating a bottleneck for rapid adoption.
- Reimbursement Variability:Manufacturers face operational complexity in navigating disparate and evolving reimbursement policies across different national and private payer systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Varicose Vein Treatment Devices Market |
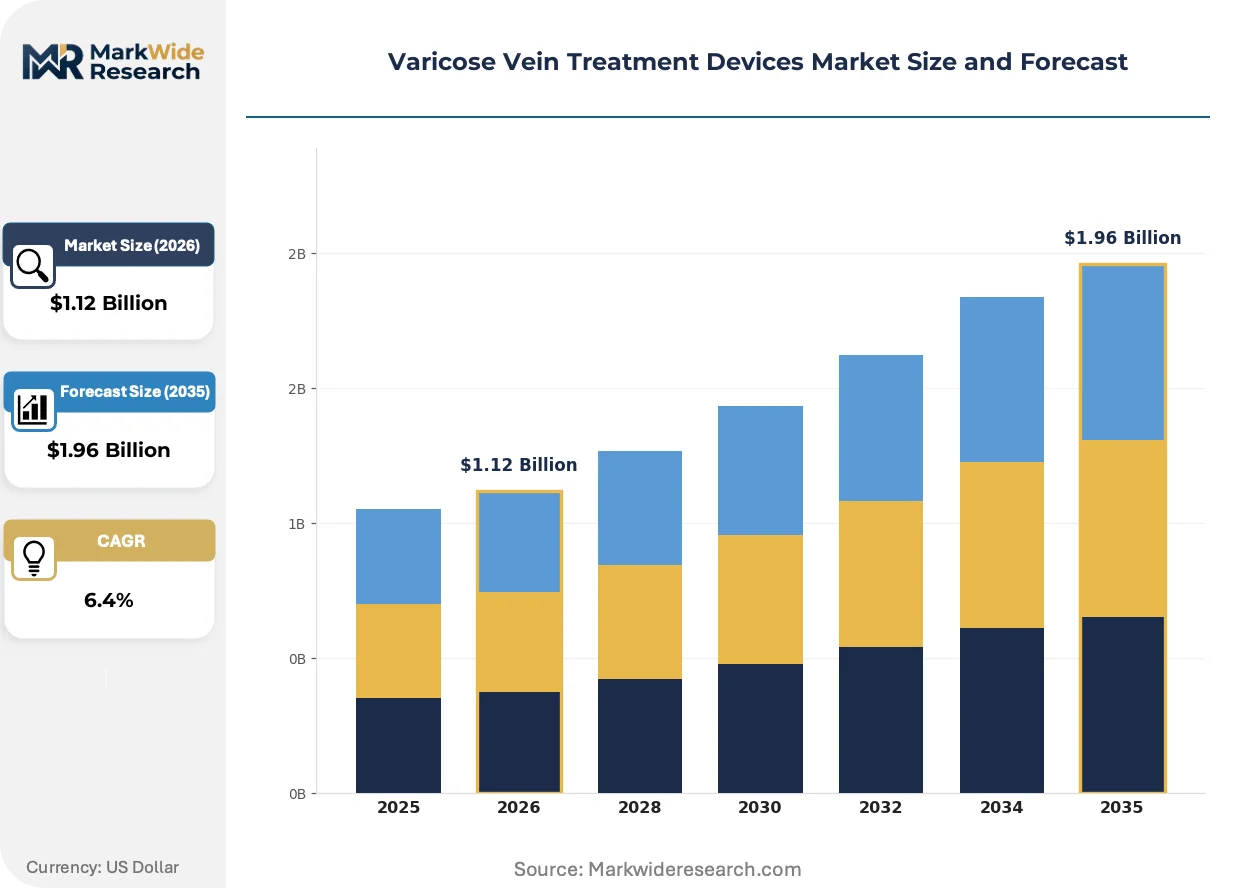
| Market Size in 2026 | $1.12 Billion |
| Market Size in 2035 | $1.96 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
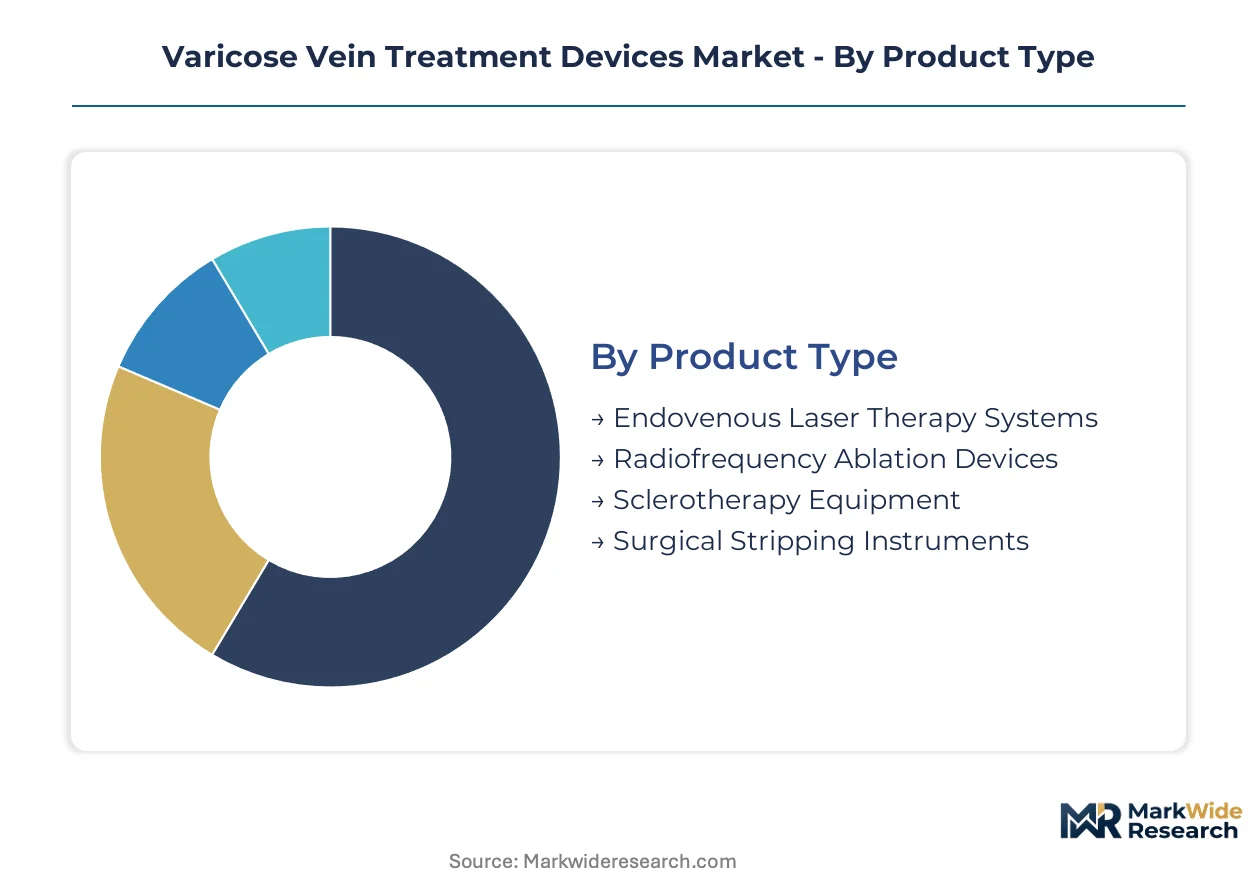
| Segmentation | Product Type: Endovenous Laser Therapy Systems, Radiofrequency Ablation Devices, Sclerotherapy Equipment, Surgical Stripping Instruments Therapy Area: Chronic Venous Insufficiency, Superficial Venous Reflux, Venous Ulcers, Telangiectasia End User: Vascular Clinics, Specialized Surgical Centers, Dermatology Clinics, Ambulatory Surgery Centers Delivery Technology: Minimally Invasive Devices, Catheter-Based Systems, Ultrasound-Guided Devices, Thermal Ablation Tools |
| Companies Covered | AngioDynamics, Medtronic, Boston Scientific Corporation, Teleflex Incorporated, Dornier MedTech, Alma Lasers, Biolitec AG, Merit Medical Systems, Sciton, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Varicose Vein Treatment Devices Market Strategic Shifts & Innovations
The evolution of varicose vein treatment is driven by a dual focus on improving the patient experience and enhancing procedural efficiency for clinicians. This dynamic pushes innovation beyond simple efficacy toward less invasive and more economically viable solutions.
Non-thermal, non-tumescent technologies like cyanoacrylate embolization use medical adhesives to close diseased veins without heat. Vascular Clinics adopt these methods to eliminate the need for tumescent anesthesia and shorten procedure times. The standard of care is migrating from purely thermal-based ablation toward these simpler, adhesive-based closure techniques.
The European Union's Medical Device Regulation (MDR) now mandates more rigorous clinical evidence and post-market surveillance for all devices. This regulatory shift increases development timelines and costs, particularly for new entrants. Consequently, manufacturers are embedding clinical data collection earlier into their product design cycles to meet the EU's stringent requirements.
Purchasing decisions in high-volume Vascular Clinics are shifting focus from upfront device cost to total procedural value. This change favors integrated systems that demonstrably reduce procedure times and minimize post-operative care over simpler, single-use disposables. This trend is most visible in competitive outpatient markets like the United States and Germany.
Varicose Vein Treatment Devices Market Segmentation
Understanding the segmentation within the varicose vein treatment devices market is crucial for device manufacturers and healthcare providers to align product development with evolving clinical needs and patient demographics. This detailed breakdown highlights how different product types, therapy areas, end-user settings, and delivery technologies shape competitive dynamics and investment priorities.
Product Type:
The cycle-time for device adoption varies significantly across product types, with newer, less invasive technologies seeing faster uptake in specialized clinics compared to established surgical methods.
- Endovenous Laser Therapy Systems:These systems utilize laser fibers, often emitting at 1470 nm, to deliver thermal energy directly into the diseased vein, causing its collapse. Demand concentrates in outpatient Vascular Clinics across Germany, driven by patient preference for minimally invasive procedures and shorter recovery times.
- Radiofrequency Ablation Devices:These devices employ radiofrequency energy to heat and ablate the vein wall, achieving permanent closure. Their adoption is particularly strong in the United States, where favorable reimbursement codes for endovenous procedures accelerate their use over traditional surgery.
- Sclerotherapy Equipment:This category includes syringes, needles, and catheters used to inject sclerosant solutions, chemically irritating and closing smaller veins. Sclerotherapy remains a cost-effective option for telangiectasia and reticular veins.
- Surgical Stripping Instruments:These traditional tools are used for the physical removal of varicose veins, typically reserved for complex cases or when other methods are contraindicated. Surgical stripping instruments offer a definitive solution for severe venous disease.
Radiofrequency Ablation Devices anchors the volume base while Endovenous Laser Therapy Systems gains share at the steepest rate.
Therapy Area:
The application of varicose vein treatment devices is directly tied to specific patient conditions, ranging from widespread chronic issues to more cosmetic concerns.
- Chronic Venous Insufficiency:This widespread condition involves impaired venous return, leading to symptoms like pain, swelling, and skin changes. Device solutions for CVI are a primary focus for research and development, particularly for complex cases.
- Superficial Venous Reflux:Characterized by faulty valves in superficial veins, this condition is a common cause of varicose veins and is a significant target for endovenous ablation techniques. Treatment aims to restore proper blood flow.
- Venous Ulcers:These severe skin lesions result from prolonged venous hypertension and require comprehensive management, often including device-based interventions to address underlying venous insufficiency. Effective treatment reduces recurrence rates.
- Telangiectasia:These are small, dilated blood vessels near the skin surface, often treated with sclerotherapy or micro-laser procedures for cosmetic improvement. Patient demand for aesthetic outcomes drives this segment.
Addressing Chronic Venous Insufficiency represents the largest patient population, while solutions for Venous Ulcers are demonstrating a rapid expansion in clinical focus.
End User:
The operational model and patient flow within different healthcare settings heavily influence the selection and utilization of varicose vein treatment devices.
- Vascular Clinics:These specialized outpatient facilities are increasingly performing minimally invasive varicose vein procedures, benefiting from faster patient turnover and lower overhead compared to hospitals. Their focus on efficiency drives demand for advanced systems.
- Specialized Surgical Centers:These centers handle a mix of complex cases and routine procedures, often equipped with a broader range of surgical and interventional tools. They serve as a key setting for advanced device utilization.
- Dermatology Clinics:These clinics primarily address smaller, cosmetic venous issues such as spider veins, relying on less invasive treatments like sclerotherapy and certain laser therapies. Patient self-referral is common in this segment.
- Ambulatory Surgery Centers:ASCs offer a cost-effective alternative to hospital-based surgeries for various procedures, including varicose vein treatments. These centers prioritize devices that offer quick recovery and high procedural efficiency.
The shift from inpatient hospital procedures to outpatient settings drives device purchasing decisions for Vascular Clinics, while Dermatology Clinics maintain consistent demand for cosmetic solutions.
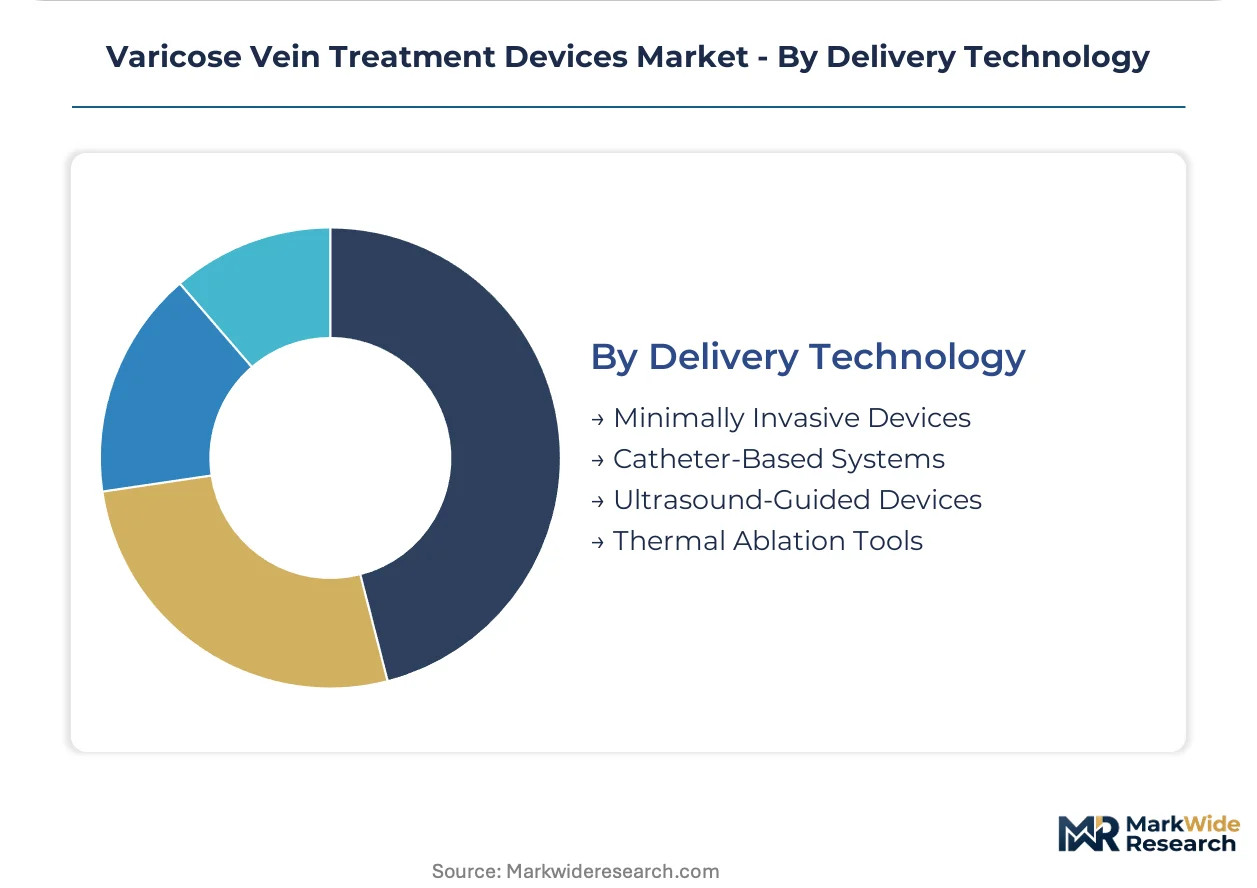
Delivery Technology:
The underlying technical principles and methods for applying treatment define this segment, with a strong emphasis on precision and reduced invasiveness.
- Minimally Invasive Devices:This broad category includes all devices designed to treat varicose veins with small incisions or percutaneous access, reducing patient trauma and recovery time. Innovation focuses on further reducing procedural footprint.
- Catheter-Based Systems:These systems involve the insertion of a thin tube into the vein to deliver energy (thermal or non-thermal) or adhesive agents directly to the diseased vessel. Real-time ultrasound guidance often accompanies these procedures.
- Ultrasound-Guided Devices:The integration of ultrasound technology allows clinicians to visualize veins and guide device placement with precision, enhancing safety and efficacy. This technology improves procedural accuracy.
- Thermal Ablation Tools:This segment encompasses devices that use heat, generated by laser or radiofrequency energy, to close off varicose veins. These tools represent a mature and highly effective treatment modality.
Minimally Invasive Devices command the largest share of innovation, as Catheter-Based Systems continue to see expanding application for improved precision.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Device manufacturers from the United States increasingly export advanced varicose vein treatment systems to European markets. This cross-border flow supports market expansion and technology adoption across different healthcare systems. Regulatory harmonization efforts also influence product design for broader market access.
United States
The United States market benefits from favorable reimbursement codes for endovenous procedures, driving demand for minimally invasive devices. FDA's 510(k) clearance process guides product development and market entry for new technologies. Medical device clusters in Minnesota continue to innovate in catheter-based systems.
Germany
Germany exhibits concentrated demand for advanced varicose vein treatments due to its aging populace and high healthcare standards. CE marking under the MDR imposes stringent clinical data requirements, influencing product innovation. The MedTech cluster in Bavaria focuses on developing integrated guidance systems.
Japan
Japanese demand reflects a strong emphasis on device safety and efficacy, influencing product specifications for market entry. The PMDA imposes rigorous evaluation standards for new medical devices. Healthcare technology development in Tokyo drives advancements in endovenous laser therapy systems.
France
French healthcare providers seek advanced solutions for venous insufficiency, prioritizing patient outcomes and procedural efficiency. The ANSM regulates medical device approvals, ensuring compliance with European standards. Research institutions in Lyon contribute to developing novel non-thermal ablation techniques.
Singapore
Singapore's improving healthcare infrastructure and growing medical tourism sector drive demand for specialized varicose vein treatment devices. The Health Sciences Authority (HSA) oversees medical device registration and post-market surveillance. Biopolis serves as a hub for biomedical research and device manufacturing.
Varicose Vein Treatment Devices Market Key Industry Players
On the supply side, the industry is moderately concentrated, with a mix of established global players and specialized technology providers. This structure supports both large-scale market penetration and niche innovation. Strategic archetypes include broad interventional device manufacturers, focused endovenous therapy specialists, and innovators in non-thermal ablation techniques. Companies pursue portfolio diversification, technology licensing, and strategic partnerships to expand their market reach and adapt to evolving clinical standards.
Within the leading innovator archetype, Medtronic, a US-based corporation, exemplifies a company with extensive R&D capabilities in cardiovascular devices. Boston Scientific Corporation, also from the United States, extends its broad interventional portfolio to include solutions for venous insufficiency. AngioDynamics, another US-based entity, occupies a position as a specialist in endovenous laser therapy systems. These companies represent key strategic approaches, ranging from comprehensive device offerings to focused therapeutic solutions. Their presence anchors the market by driving technological advancements and expanding treatment options across various end-user settings.
| Leading Market Players |
|---|
| AngioDynamics |
| Medtronic |
| Boston Scientific Corporation |
| Teleflex Incorporated |
| Dornier MedTech |
| Alma Lasers |
| Biolitec AG |
| Merit Medical Systems |
| Sciton, Inc. |
| Others |
Cost & Logistics Intelligence
United States-based R&D and advanced manufacturing for varicose vein treatment devices concentrate upstream value capture. This concentration influences pricing power for complex systems across global markets.
Pricing Analysis
The pricing gap between established thermal ablation systems and newer non-thermal technologies creates market tension. Pricing operates on a hybrid model, combining per-unit transactional costs for disposables with value-based contracts for integrated systems. Procedural efficiency and the integration of real-time ultrasound guidance drive significant price differentiation. Pricing softness stems from the availability of lower-cost alternatives like sclerotherapy. Smaller, independent Vascular Clinics exhibit higher price sensitivity compared to larger specialized surgical centers.
Supply Chain Analysis
Specialized polymers and microelectronics form critical upstream feedstocks for advanced varicose vein treatment devices. Supply concentration primarily resides in the United States, Germany, and Japan, reflecting R&D and manufacturing hubs. Regulatory friction, particularly the EU's MDR requirements, presents a structural supply chain risk by delaying new device approvals. Distribution runs through a network of specialized medical device distributors and direct sales channels targeting vascular clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The varicose vein treatment devices market is experiencing a cyclical recovery, driven by the renewed prioritization of elective procedures in outpatient settings. This shift accelerates demand for minimally invasive solutions.
For Market Incumbents: Entrench market position by aggressively investing in non-thermal ablation technologies and integrated guidance systems. This strategy mitigates the threat from lower-cost alternative treatments and regulatory friction, particularly the EU's MDR. Deepen R&D in cardiovascular devices to maintain technological leadership. Pursue strategic partnerships with specialized Vascular Clinics to secure long-term adoption.
For New Entrants and Emerging Players: Build out solutions for emerging markets, specifically targeting Southeast Asian nations with improving healthcare infrastructure. Focus on developing cost-effective, non-thermal, non-tumescent devices that simplify procedures in outpatient Vascular Clinics. Penetrate the underserved patient population suffering from complex Chronic Venous Insufficiency. Strategic alliances with local distributors can accelerate market entry and adoption.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with specialized device manufacturers focused on non-thermal or integrated guidance systems. The market offers long-term viability fueled by aging demographics and the outpatient care shift. Target acquisition archetypes include innovators in cyanoacrylate embolization or advanced catheter-based systems. The signal to watch is the expansion of favorable reimbursement codes for non-thermal procedures in new geographies.
| Strategic Initiative | Industry Significance |
|---|---|
| Non-Thermal Technology Development | Developing advanced cyanoacrylate embolization devices expands patient access by eliminating tumescent anesthesia. |
| Integrated Ultrasound Guidance | Combining catheters with real-time ultrasound guidance enhances procedural precision for clinicians. |
| CE Marking Pathway Acceleration | Streamlining CE marking under the MDR enables faster market entry for new devices in Europe. |
| Southeast Asia Market Penetration | Expanding into Southeast Asian nations capitalizes on improving healthcare infrastructure and unmet demand. |
| Chronic Venous Insufficiency Solutions | Addressing complex CVI opens a larger, underserved patient population for device manufacturers. |
Research Approach
Two parallel data streams informed the analysis: primary interviews and extensive secondary research. Primary insights were gathered from vascular surgeons, clinic administrators, MedTech R&D leads, and regulatory affairs specialists. Secondary validation drew from FDA's 510(k) clearance data, EU MDR compliance reports, and healthcare provider procurement databases. Bottom-up and top-down triangulation ensured data integrity and market sizing accuracy.
Forecast inputs considered historical market performance, technological innovation, and patient demographics across the analysis window. The quantitative model segmented the market by product type, therapy area, end-user, delivery technology, and regional regulatory landscape. Compound Annual Growth Rates derived from historical growth and projected adoption rates incorporated aging demographics in Europe and evolving reimbursement policies.
The forecast holds incumbent behavior within observed patterns; aggressive moves by specialized technology providers would shift outcomes. Forecasts reflect assumptions regarding regulatory stability and sustained healthcare expenditure. Cross-checking against national health authority reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Digital X-Ray Devices Market
Medical Devices
Spain Diabetes Devices Market
Medical Devices
Electroencephalography Systems/Devices Market
Medical Devices
Implantable Pulse Generator Market
Medical Devices
Occlusion Balloon Catheter Market
Medical Devices
Life Science and Chemical Instruments Market
Medical Devices
Global Electrotherapy Devices Market
Medical Devices
Global Robotic Assisted Surgery Systems Market
Medical Devices
Photorejuvenation Devices Market
Medical Devices
China Intrauterine Devices Market
Medical Devices
Medical Bionic Implants and Exoskeletons Market
Medical Devices
Global Anastomosis Devices Market
Medical Devices
Laser BPH Devices Market
Medical Devices
Global Stereotactic Surgery Devices Market
Medical Devices
Airway Clearance Devices System Market
Medical Devices
Surgical Robotic Services Market