
 Implantable Pulse Generator Market | 2026-2036
Implantable Pulse Generator Market Size, Share, and Industry Trends Forecast 2026-2036
Implantable Pulse Generator Market Outlook
Closed-loop sensing with adaptive stimulation algorithms is reshaping how implantable pulse generators modulate therapy delivery in real time. Medtronic leverages its integrated hardware-software ecosystem to sustain leadership in cardiac neuromodulation systems. Boston Scientific Corporation anchors its competitive position through deep specialization in spinal cord stimulation platforms for chronic pain. Abbott differentiates via rechargeable battery architectures that extend device longevity and reduce surgical replacement frequency.
An implantable pulse generator is a sealed electronic device containing a battery, microprocessor, and electrode leads that delivers precisely timed electrical impulses to targeted neural or cardiac tissue to regulate abnormal physiological activity. Manufacturing requires hermetic titanium enclosures, biocompatible polymers for lead insulation, and cleanroom assembly to ensure decades-long implant reliability. Neuromodulators now command the fastest expansion as chronic pain management protocols broaden across hospital and ambulatory surgery center settings. Rechargeable technology platforms concentrate margin pools where battery chemistry innovations reduce replacement surgeries and lower lifetime care costs. Wireless connectivity capabilities are maturing rapidly as remote patient monitoring integrates with existing cardiac rhythm management workflows.
The FDA premarket approval process and EU MDR conformity assessments govern device safety, clinical evidence requirements, and post-market surveillance obligations across major commercial jurisdictions. ISO 14708 active implantable medical device standards establish baseline electrical safety and electromagnetic compatibility benchmarks that manufacturers must satisfy for market access. Stakeholders must monitor evolving cybersecurity guidance from regulators as wireless-enabled generators become standard care, since data integrity vulnerabilities could trigger new premarket testing requirements or delay clearances.
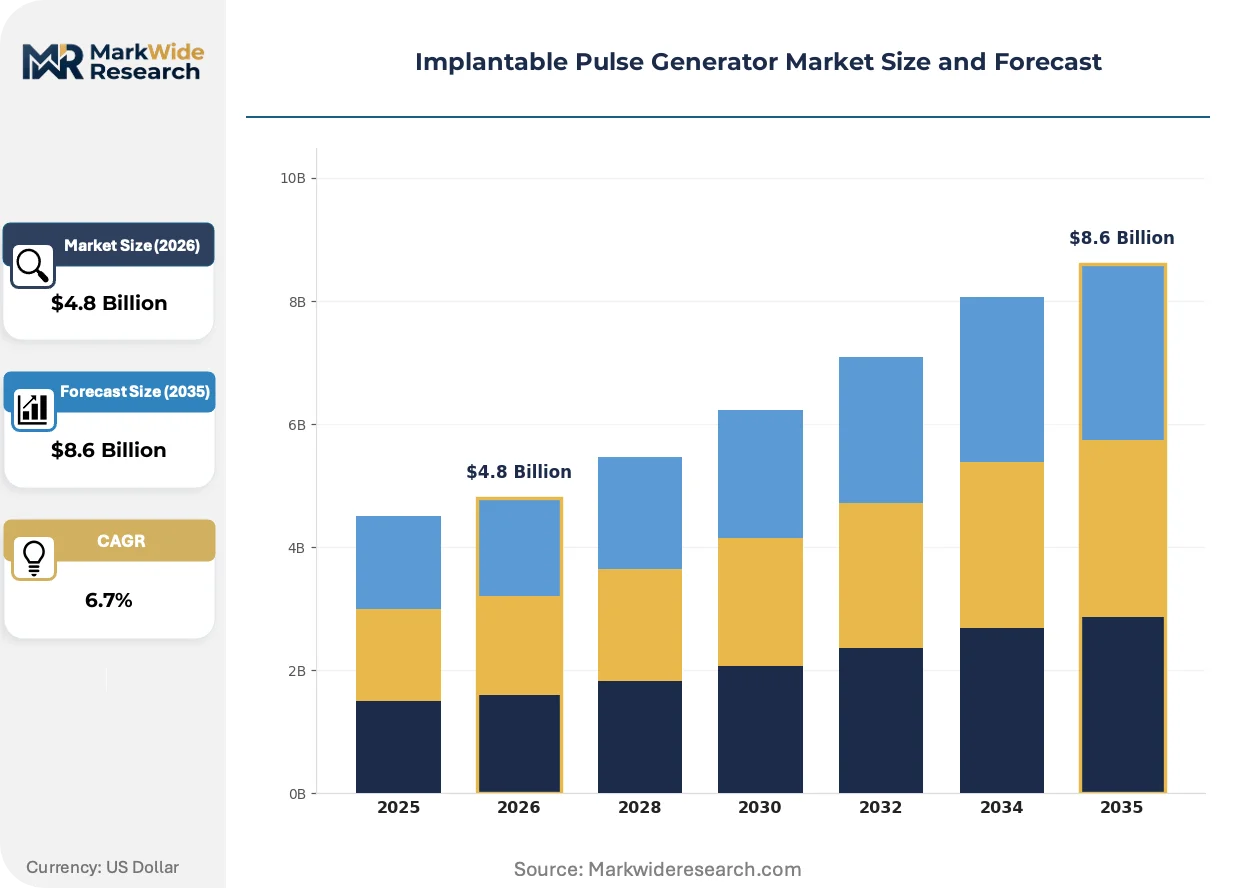
Market Dynamics
Closed-loop adaptive algorithms are compressing replacement cycles as rechargeable platforms extend functional longevity and reduce surgical burden on healthcare systems.
Growth Catalysts
- EU MDR conformity pathways:Streamlined post-market surveillance obligations for breakthrough neuromodulation devices accelerate commercialization timelines across European hospital networks.
- Ambulatory surgery centers:Chronic pain protocols now integrate spinal cord stimulation procedures outside traditional hospital settings, expanding addressable procedure volumes.
- Lithium-ion battery chemistry:Energy density improvements enable smaller form factors and extended recharge intervals, reducing patient compliance friction.
Market Restraints
- Titanium enclosure supply:Hermetic sealing requirements concentrate qualified suppliers in German and Swiss precision metalworking clusters, creating input bottlenecks.
- FDA premarket approval timelines:Breakthrough device designation does not compress clinical evidence requirements for novel stimulation algorithms, extending development costs.
- Non-invasive neuromodulation:Transcutaneous electrical nerve stimulation systems compete for chronic pain indications without surgical implantation risks.
Strategic Opportunities
- Japan's aging demographic:METI reimbursement frameworks for cardiac rhythm management create expansion pathways for neuromodulator crossover applications.
- Remote patient monitoring integration:Wireless connectivity convergence with existing cardiac telemetry infrastructure enables real-time therapy adjustment without clinic visits.
- India's PLI scheme for medical devices:Domestic manufacturing incentives reduce import dependency for electrode leads and battery components serving South Asian markets.
Industry Challenges
- Cybersecurity validation:FDA guidance on wireless-enabled active implants demands premarket penetration testing that extends certification timelines by 8-14 months.
- Cleanroom assembly capacity:ISO 14644 Class 7 fabrication requirements for microprocessor encapsulation constrain contract manufacturer availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Implantable Pulse Generator Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pacemakers, Neuromodulators, Defibrillators, Neurostimulators End User: Hospitals, Clinics, Ambulatory Surgery Centers, Specialty Clinics Application: Chronic Pain Management, Cardiac Rhythm Disorders, Movement Disorders, Neurological Disorders Technology: Wireless, Rechargeable, Miniaturized, Biocompatible |
| Companies Covered | Medtronic, Boston Scientific Corporation, Abbott, Biotronik, Nevro Corp, Synapse Biomedical, NeuroPace, LivaNova, CVRx, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Implantable Pulse Generator Market Strategic Shifts
Hardware-software integration is redefining competitive moats as sensing capabilities transform pulse generators from open-loop stimulators into responsive therapeutic systems.
Artificial intelligence-driven pattern recognition is collapsing the latency between physiological signal detection and therapeutic response. Cardiac electrophysiology departments at tertiary hospitals in Germany and the United States are piloting these platforms for arrhythmia prediction. The compression of algorithmic decision cycles is eliminating the need for separate diagnostic implants and consolidating device categories.
REACH restrictions on persistent organic pollutants in medical device polymers are forcing reformulation of lead insulation materials. European manufacturers must validate alternative biocompatible elastomers by 2026 to maintain CE marking. Spinal cord stimulation platforms with extended implant lifespans face the steepest requalification burden given polymer degradation risks over multi-decade service periods.
Hospital procurement committees now mandate total cost-of-ownership models that weight battery longevity against initial device price. United States integrated delivery networks are consolidating vendor contracts around rechargeable platforms that reduce revision surgery frequency. This behavioral shift concentrates purchasing power among health systems with sophisticated lifecycle accounting capabilities.
Implantable Pulse Generator Market Segmentation
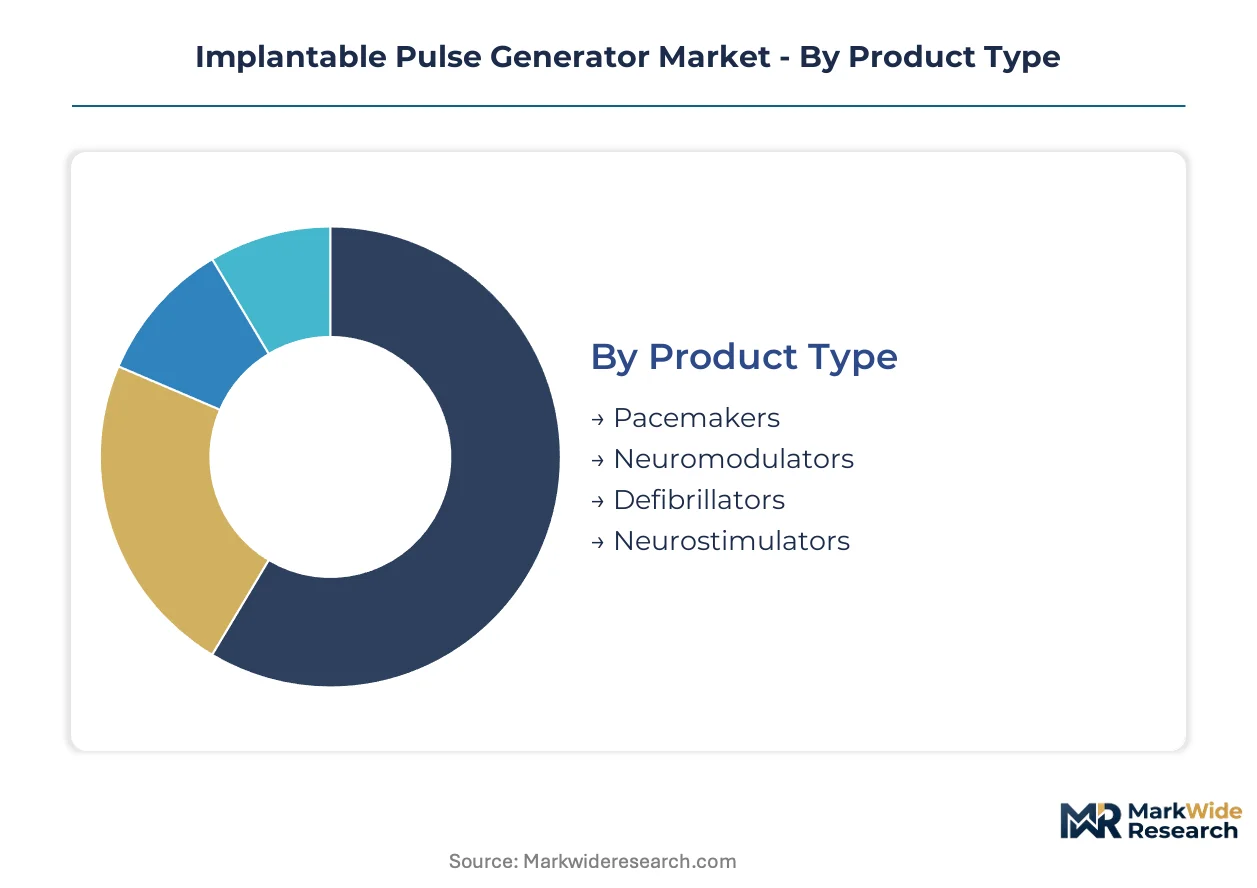
Segmentation in implantable pulse generators reveals distinct service intensity profiles across product categories. After-sales requirements vary dramatically between cardiac devices requiring remote monitoring infrastructure and pain management systems demanding frequent reprogramming protocols.
Product Type:
After-sales-service intensity diverges sharply across product categories, with neuromodulation platforms requiring sustained clinical support versus cardiac devices emphasizing remote telemetry maintenance.
- Pacemakers:These cardiac rhythm management devices incorporate lithium-iodine or lithium-carbon monofluoride batteries delivering 5-15 year lifespans. Demand concentrates in tertiary hospital electrophysiology departments across Germany and the United States, driven by aging demographics and established reimbursement pathways for bradycardia treatment.
- Neuromodulators:Closed-loop adaptive systems for chronic pain and movement disorders feature rechargeable lithium-ion architectures with 10-25 year functional longevity. Ambulatory surgery centers in Japan and the United States are expanding implant volumes as spinal cord stimulation protocols migrate outside traditional hospital settings.
- Defibrillators:Implantable cardioverter-defibrillators combine pacing and high-voltage shock delivery for sudden cardiac arrest prevention.
- Neurostimulators:Deep brain stimulation platforms target Parkinson's disease and essential tremor through subthalamic nucleus targeting.
Neuromodulators hold the largest share; momentum sits with neurostimulators as movement disorder indications broaden.
End User:
Procurement authority is shifting toward integrated delivery networks that consolidate purchasing across hospital and outpatient settings under unified vendor contracts.
- Hospitals:Tertiary medical centers maintain comprehensive cardiac electrophysiology and neuromodulation surgical programs with dedicated device management clinics. United States academic medical centers anchor volume through complex arrhythmia and movement disorder case referrals.
- Ambulatory Surgery Centers:Freestanding surgical facilities now perform spinal cord stimulator trials and permanent implants under streamlined protocols. Germany's outpatient reimbursement frameworks enable same-day discharge for select neuromodulation procedures.
- Clinics:Cardiac device follow-up and programming adjustments occur in specialized electrophysiology clinics.
- Specialty Clinics:Pain management and movement disorder centers focus exclusively on neuromodulator optimization.
Hospitals dominate current volume; ambulatory surgery centers are climbing the fastest as site-of-care migration accelerates.
Application:
Clinical evidence requirements vary by therapeutic area, with cardiac applications commanding the most mature regulatory pathways and chronic pain facing evolving payer scrutiny.
- Chronic Pain Management:Spinal cord stimulation and dorsal root ganglion targeting address failed back surgery syndrome and complex regional pain syndrome. United States integrated delivery networks are consolidating vendor selection around rechargeable platforms that reduce revision surgery frequency.
- Cardiac Rhythm Disorders:Bradycardia pacing and tachycardia termination encompass the most established implantable pulse generator category. Japan's METI reimbursement frameworks sustain expansion through aging population screening programs.
- Movement Disorders:Deep brain stimulation for Parkinson's disease and dystonia requires specialized neurosurgical expertise.
- Neurological Disorders:Epilepsy responsive neurostimulation and obsessive-compulsive disorder applications represent emerging indications.
Cardiac rhythm disorders command the largest installed base; chronic pain management is gaining share fastest as indication expansion outpaces cardiac saturation.
Technology:
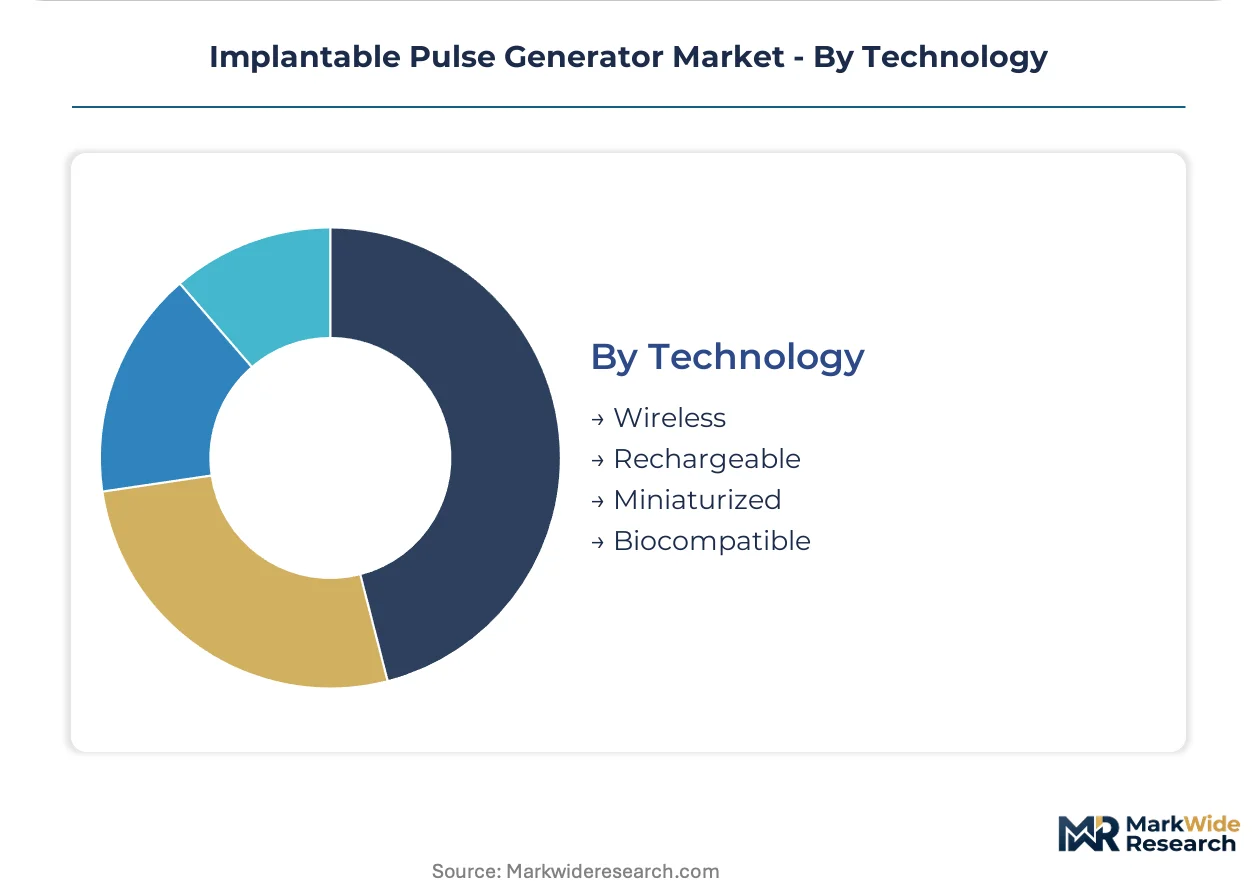
Platform differentiation increasingly centers on energy management architectures that determine replacement intervals and lifetime cost profiles.
- Rechargeable:Lithium-ion battery systems enable compact form factors and 10-25 year functional lifespans through inductive or RF charging protocols. Hospital procurement committees in the United States now mandate total cost-of-ownership models that weight battery longevity against initial device price.
- Wireless:Bluetooth Low Energy and proprietary RF connectivity enable remote monitoring and automated alerts without patient-initiated transmission. FDA cybersecurity guidance for wireless-enabled active implants demands premarket penetration testing that extends certification timelines.
- Miniaturized:Reduced device volume through advanced packaging and leadless architectures decreases surgical implant burden.
- Biocompatible:Titanium hermetic enclosures and silicone or polyurethane lead insulation materials ensure decades-long implant reliability.
Rechargeable technology holds the largest share; wireless capabilities are expanding most quickly as remote patient monitoring integrates with existing cardiac telemetry infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision metalworking clusters supply hermetic titanium enclosures to device manufacturers across the United States and Japan, establishing a critical trade-flow corridor for implantable pulse generator componentry.
United States
FDA premarket approval pathways and breakthrough device designations shape product development timelines for cardiac neuromodulation systems. Integrated delivery networks in tertiary hospital systems consolidate vendor contracts around rechargeable platforms. The Minneapolis medical device corridor anchors manufacturing concentration for active implantable technologies.
Germany
EU MDR conformity assessments and REACH restrictions on medical device polymers drive reformulation of lead insulation materials. Tertiary hospital electrophysiology departments in Bavaria and Baden-Württemberg pilot closed-loop adaptive algorithms for arrhythmia prediction. Stuttgart precision metalworking clusters specialize in hermetic titanium enclosure fabrication.
Japan
METI reimbursement frameworks for cardiac rhythm management sustain expansion through aging population screening programs. PMDA regulatory harmonization with FDA standards accelerates approval timelines for neuromodulator crossover applications. The Kanto region around Tokyo concentrates implant volumes at academic medical centers.
India
PLI scheme incentives for medical device manufacturing reduce import dependency for electrode leads and battery components serving South Asian markets. CDSCO regulatory pathways for active implantables mature as domestic production scales. Gujarat and Maharashtra industrial corridors attract contract manufacturing for cleanroom assembly operations.
Switzerland
Swissmedic regulatory frameworks align with EU MDR standards while maintaining distinct post-market surveillance protocols. Precision metalworking expertise in the Jura region supports hermetic sealing requirements for titanium enclosures. Geneva and Basel clusters specialize in microprocessor encapsulation for extended implant reliability.
Implantable Pulse Generator Market Competitive Environment
Channel-controlling players compete with product-specialist players across differentiated technology vectors in implantable pulse generators. The market structure consolidates around integrated hardware-software ecosystems and deep specialization in specific therapeutic domains. Three strategic archetypes dominate: diversified medical technology conglomerates with cardiac-neuromodulation breadth, pure-play neuromodulation specialists with spinal cord stimulation focus, and emerging platform developers with rechargeable battery architectures. Competitive moves concentrate on strategic partnerships for remote patient monitoring integration and portfolio diversification into closed-loop adaptive systems.
Within the diversified conglomerate tier, Medtronic and Boston Scientific Corporation represent channel-controlling positions spanning cardiac rhythm management and neuromodulation applications. Abbott exemplifies the rechargeable battery architecture specialist archetype, while Nevro Corp occupies a position among pure-play neuromodulation developers focused on spinal cord stimulation platforms.
| Leading Market Players |
|---|
| Medtronic |
| Boston Scientific Corporation |
| Abbott |
| Biotronik |
| Nevro Corp |
| Synapse Biomedical |
| NeuroPace |
| LivaNova |
| CVRx |
| Others |
Value Chain & Pricing Dynamics
The Frankfurt-Minneapolis air freight corridor channels precision-machined titanium enclosures from German metalworking clusters to United States device assemblers, with transport cost volatility amplifying margin compression for rechargeable neuromodulator platforms while reinforcing price premiums for hermetic sealing capabilities.
Pricing Analysis
Generational pricing gaps separate first-generation primary-cell pacemakers from current rechargeable neuromodulators and emerging closed-loop adaptive systems. Three-tier pricing structure across premium adaptive platforms, standard rechargeable devices, and economy primary-cell alternatives reflects battery chemistry sophistication and FDA breakthrough designation status. Price differentiation centers on ISO 14708 certification tier and total cost-of-ownership accounting by United States integrated delivery networks. Pricing pressure stems from hospital procurement committees mandating lifecycle cost models that discount upfront device premiums against revision surgery avoidance.
Supply Chain Analysis
Upstream feedstock flows for hermetic titanium enclosures draw from German and Swiss precision metalworking clusters, while lithium-ion battery cells source primarily from South Korean and Japanese chemical manufacturers. Cleanroom-grade silicone and polyurethane lead insulation materials hinge on European polymer suppliers navigating REACH reformulation deadlines. Single-source vulnerability concentrates in Class 7 cleanroom assembly capacity for microprocessor encapsulation. Distribution runs through authorized device distributors serving hospital electrophysiology departments and ambulatory surgery center networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The implantable pulse generator market is emerging from a cyclical trough driven by deferred elective procedures during hospital capacity constraints, with replacement cycle compression now accelerating as rechargeable platforms extend functional longevity.
For Market Incumbents: Insulate core cardiac rhythm management franchises by deepening backward integration into titanium enclosure supply through captive agreements with Stuttgart-area metalworking specialists. Prioritize cybersecurity certification investment ahead of FDA wireless-enabled implant guidance to preempt 8-14 month clearance delays that emerging entrants will face.
For New Entrants and Emerging Players: Pursue white-space expansion in India's domestic manufacturing corridor under PLI scheme incentives, targeting electrode lead and battery component production for South Asian hospital networks. Ambulatory surgery center spinal cord stimulation protocols offer the most penetrable entry vector, with remote patient monitoring software companions as the differentiated go-to-market anchor.
For Investors and Strategic Acquirers: EU MDR conformity pathway streamlining reshapes the acquisition landscape by compressing commercialization timelines for breakthrough neuromodulation assets relative to FDA premarket approval trajectories. Five-to-ten year viability favors pure-play neuromodulation developers with closed-loop adaptive algorithm pipelines over diversified cardiac conglomerates facing cardiac saturation. The signal to watch is Japan METI reimbursement framework expansion for movement disorder indications beyond Parkinson's disease.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Accelerates premarket review timelines for adaptive stimulation algorithms competing against Medtronic's integrated ecosystem. |
| CE Marking Pathway under EU MDR | Enables European hospital network access contingent on REACH-compliant polymer reformulation for lead insulation materials. |
| Hospital System Partnership | Locks in integrated delivery network vendor consolidation around rechargeable platforms with total cost-of-ownership contracting. |
| Software Companion Development | Integrates remote patient monitoring with existing cardiac telemetry infrastructure at United States academic medical centers. |
| Reimbursement Strategy | Secures CMS Medicare coverage determination for spinal cord stimulation in failed back surgery syndrome indications. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with implantable device executives, hospital purchasing committee members, biomedical engineers, and GPO contracts managers; and secondary validation against FDA premarket approval databases, EU MDR conformity assessment records, hospital procurement contract repositories, and ISO 14708 certification registries. Bottom-up procedure volume modeling triangulated against top-down manufacturer revenue segmentation.
Forecast inputs encompassed product type evolution across pacemakers, neuromodulators, defibrillators, and neurostimulators; technology platform penetration for rechargeable versus primary-cell architectures; and end-user migration from tertiary hospitals toward ambulatory surgery centers. CAGRs were derived from segmented growth rate reconciliation across the analysis window, with inputs including battery chemistry energy density improvement curves and regulatory approval timeline distributions by jurisdiction.
Sensitivities concentrate around FDA cybersecurity guidance implementation delays, EU MDR polymer reformulation deadline compliance, and titanium enclosure supply concentration in German-Swiss clusters. Cross-checking against CMS Medicare procedure volume benchmarks and PMDA approval timeline harmonization metrics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Medical Suction Devices Market
Medical Devices
Mexico Contraceptive Devices Market
Medical Devices
Insulin Delivery Devices (Idd) Market
Medical Devices
Surgical Display Market
Medical Devices
Medical Coatings Market
Medical Devices
Endometrial Ablation Devices Market
Medical Devices
Disposable EEG Electrode Market
Medical Devices
Neurotech Devices Market
Medical Devices
North America Wearable Medical Devices Market
Medical Devices
Muscle Stimulator Market
Medical Devices
Dry Eye Treatment Devices Market
Medical Devices
Digital Blood Pressure Monitors Market
Medical Devices
Middle East and Africa Refractive Surgery Devices Market
Medical Devices
Endocavity Transducer Market
Medical Devices
Tumour Ablation Devices Market
Medical Devices
Cast Removal Devices Market