
 Medical Bionic Implants and Exoskeletons Market | 2026-2036
Medical Bionic Implants and Exoskeletons Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Bionic Implants and Exoskeletons Market Foresight
The EU Green Deal is broadening sustainability requirements across medical device supply chains, pressuring manufacturers to reduce rare-earth dependence in actuator systems. Ottobock SE & Co. KGaA leverages its vertically integrated component foundry to control magnet sourcing for powered prosthetic joints. Ekso Bionics Holdings, Inc. anchors its competitive position through FDA-cleared rehabilitation protocols that dominate hospital purchasing criteria in the United States.
Medical bionic implants and exoskeletons comprise electromechanical systems that restore or augment human motor function through servo-actuated joints, myoelectric signal processing, and closed-loop neural interfaces with response latencies below 50 milliseconds. These devices serve commercial purposes ranging from paraplegic ambulation in clinical settings to stroke neurorehabilitation that reduces long-term care costs. Bionic limbs command the largest revenue pool due to established reimbursement codes and mature socket-interface technology, while neural prosthetics represent the fastest-expanding segment as brain-computer interface startups achieve regulatory milestones. Exoskeletons for home care applications remain nascent, with margin concentration currently residing in rehabilitation center deployments where bundled service contracts extend hardware economics.
FDA premarket approval pathways and the EU Medical Device Regulation shape demand by mandating longitudinal clinical data for active implantable devices, effectively filtering market access to well-capitalized developers. Japan's PMDA has accelerated review timelines for regenerative medicine devices incorporating bionic interfaces, redirecting some R&D investment toward Tokyo-Osaka clinical corridors. Stakeholders must monitor evolving reimbursement decisions by Germany's Federal Joint Committee and comparable health technology assessment bodies, as these determinations will dictate whether home-use exoskeletons transition from niche disability aids to mainstream mobility solutions.
Market Dynamics
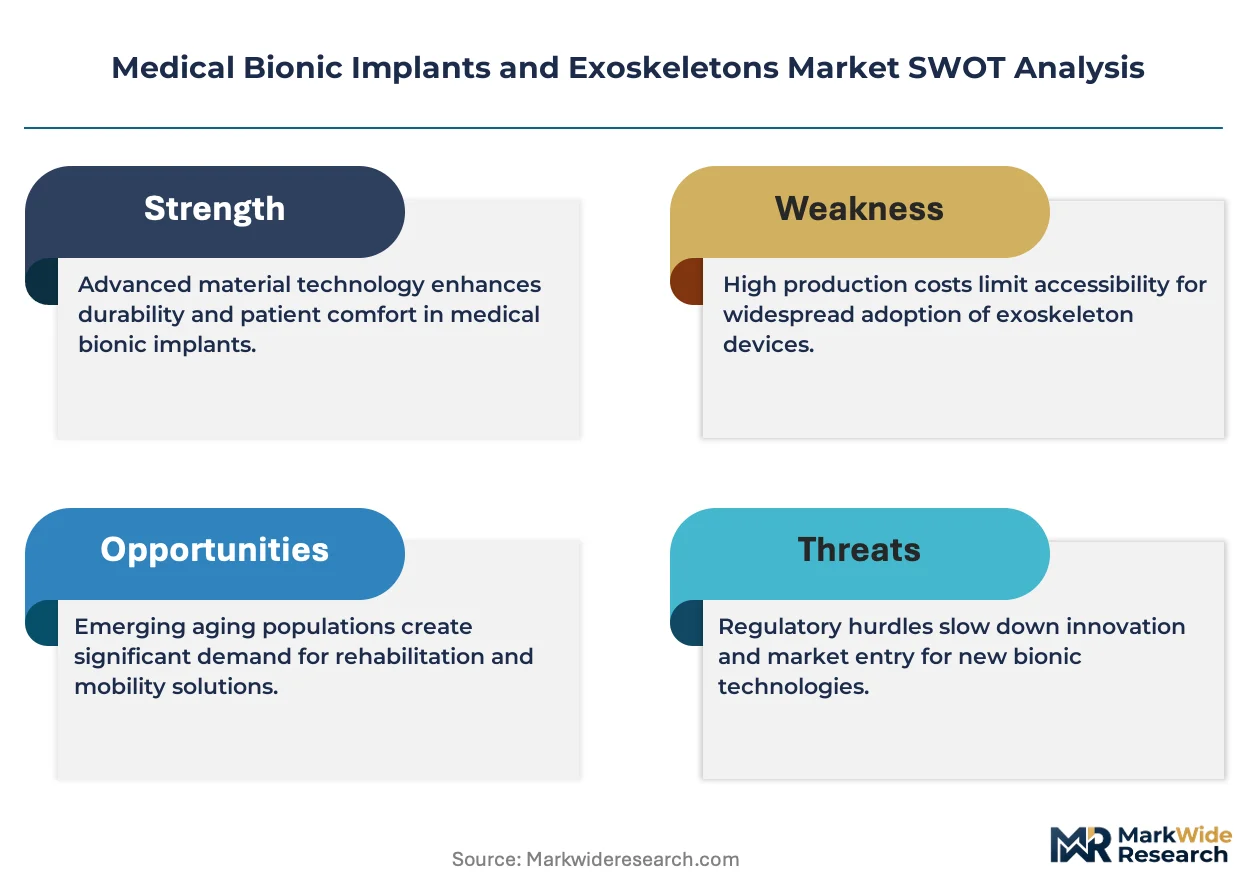
EU Medical Device Regulation tightening clinical evidence requirements for active implantable devices is filtering market access toward well-capitalized developers capable of funding longitudinal trials.
Growth Catalysts
- Statutory Reimbursement Expansion:Germany's Federal Joint Committee has broadened health insurance coverage for exoskeleton-assisted gait training, accelerating rehabilitation center procurement cycles.
- Neural Interface Maturation:Brain-computer interface response latencies below 50 milliseconds are enabling closed-loop control for prosthetic limbs and expanding addressable patient populations.
- REACH Compliance Incentives:EU Green Deal sustainability mandates are pressuring manufacturers to redesign actuator systems with reduced rare-earth dependence, favoring suppliers with vertically integrated magnet sourcing.
Market Restraints
- Neodymium Supply Concentration:China controls approximately 85% of global rare-earth processing, creating input cost volatility for servo-actuated joint manufacturers dependent on permanent magnet motors.
- Long-Term Clinical Data Burden:FDA premarket approval pathways mandate multi-year safety studies for active implantable devices, extending development timelines beyond typical venture capital fund lifecycles.
- Socket Interface Limitations:Mature but imperfect prosthetic socket technology creates fitting complexity that limits patient adherence and constrains market penetration in lower-limb segments.
Strategic Opportunities
- Home-Use Exoskeleton White Space:Bundled service contracts currently dominate rehabilitation center economics, but Germany's reimbursement precedent creates regulatory template for residential mobility solutions.
- Regenerative Medicine Convergence:Japan's PMDA accelerated review timelines for devices combining bionic interfaces with tissue engineering are redirecting R&D investment toward Tokyo-Osaka clinical corridors.
- Myoelectric Signal Processing Advancement:Machine learning-enabled pattern recognition is converging with implantable electrode arrays to enable intuitive multi-joint control previously requiring invasive nerve reinnervation surgery.
Industry Challenges
- Cross-Disciplinary Talent Scarcity:Development teams require simultaneous expertise in neuromuscular physiology, embedded systems engineering, and regulatory science, creating recruitment bottlenecks.
- Certification Timeline Compression:Health technology assessment bodies including Germany's IQWiG demand real-world evidence generation alongside controlled trials, straining quality management system resources.
- Interoperability Standardization Gaps:Absence of unified communication protocols between neural implants and external processing units forces proprietary system architectures that lock rehabilitation centers into single-vendor ecosystems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Bionic Implants and Exoskeletons Market |
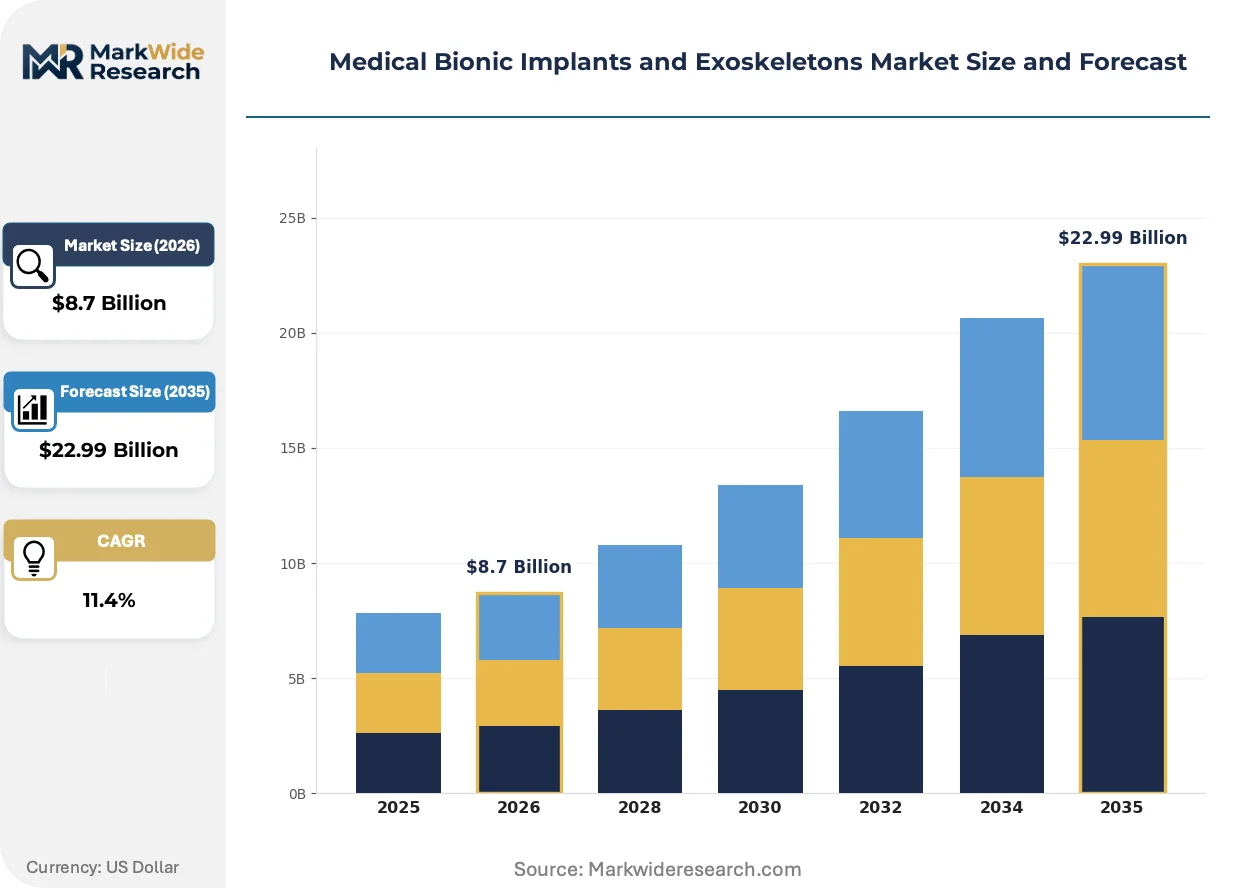
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bionic Limbs, Exoskeletons, Neural Prosthetics, Wearable Therapies Technology: Robotic Systems, AI Algorithms, Sensor Integration, Control Interfaces End User: Rehabilitation Centers, Hospitals, Research Institutions, Home Care Application: Physical Rehabilitation, Mobility Assistance, Chronic Pain Management, Post-Surgery Recovery |
| Companies Covered | Lifeward Ltd., B-Temia Inc., Ekso Bionics Holdings, Inc., Hocoma AG, Rex Bionics Ltd., Ottobock SE & Co. KGaA, ReWalk Robotics Ltd., Myomo Inc., CYBERDYNE Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Bionic Implants and Exoskeletons Market Shifts & Advancements
Neural signal processing architectures are consolidating around embedded machine learning inference, while regulatory frameworks bifurcate between accelerated regenerative medicine pathways and stricter active implantable oversight.
Implantable myoelectric sensors with onboard edge computing are consolidating peripheral signal acquisition and processing into single-package devices. Rehabilitation centers in Germany and the United States are adopting these systems for stroke neurorehabilitation protocols. The technology is consolidating previously separate hardware layers, compressing system complexity and reducing per-patient setup time.
EU Medical Device Regulation post-market surveillance requirements are mandating systematic implant registries and long-term follow-up studies for active devices. Manufacturers must now fund decade-long safety monitoring programs as a condition of CE marking renewal. Neural prosthetic developers targeting European commercialization are responding by structuring clinical affairs departments around proactive vigilance systems rather than reactive complaint handling.
Hospital procurement committees are unbundling hardware acquisition from rehabilitation service contracts, forcing exoskeleton vendors to compete on capital equipment margins rather than bundled lifetime value. United States academic medical centers are leading this transition, separating device purchasing decisions from therapy protocol licensing. The shift is most visible in spinal cord injury programs where third-party physical therapy operators now source hardware independently from software-enabled training curricula.
Medical Bionic Implants and Exoskeletons Market Segmentation
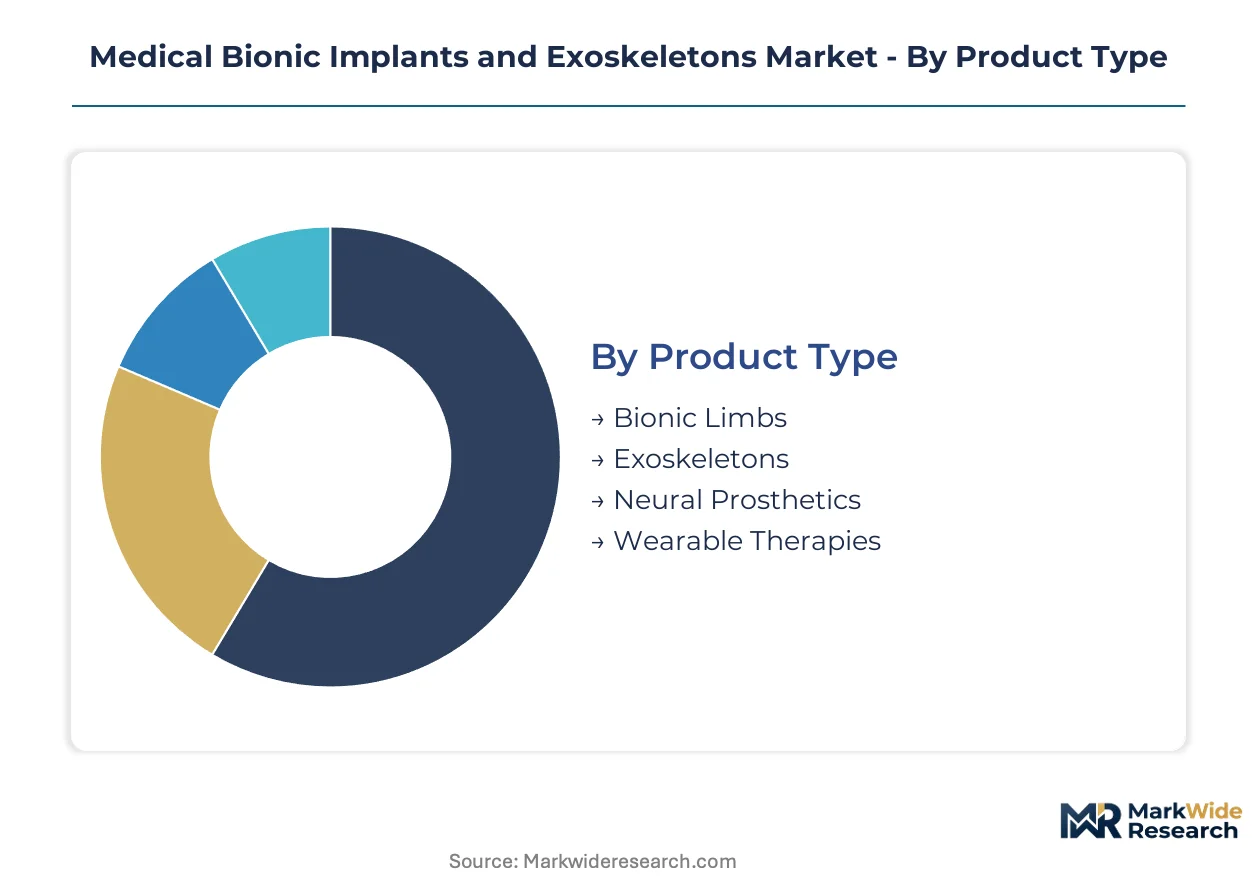
Segmentation in medical bionic implants and exoskeletons reveals divergent commercial models across product architectures and care settings. Technology choices determine regulatory pathways, while end-user concentration shapes pricing power and service bundling strategies.
Product Type:
Customization intensity spans from standardized socket-fitted prosthetics to patient-specific neural implants requiring surgical planning.
- Bionic Limbs:Myoelectric-controlled prosthetic arms and legs with silicone socket interfaces and carbon-fiber structural components. Demand concentrates in German rehabilitation centers where statutory insurance covers microprocessor knee joints. Socket fitting complexity limits patient adherence despite established reimbursement codes.
- Exoskeletons:Powered wearable frames with servo-actuated hip and knee joints enabling paraplegic ambulation. Hospital procurement committees in the United States unbundle hardware from service contracts, pressuring capital equipment margins. FDA-cleared rehabilitation protocols dominate purchasing criteria.
- Neural Prosthetics:Brain-computer interfaces with sub-50 millisecond response latencies for direct neural control of external devices.
- Wearable Therapies:Soft robotic garments providing assistive force for movement disorders without rigid skeletal frames.
Leading the category by volume: Bionic Limbs. Growing fastest: Neural Prosthetics.
Technology:
Cost tiers separate premium closed-loop systems from standard open-loop actuators with basic sensor feedback.
- Robotic Systems:Electromechanical joint actuators with rare-earth permanent magnet motors and harmonic drive gearboxes. Manufacturers face EU Green Deal pressure to reduce neodymium dependence through alternative magnet materials or switched reluctance designs. Ottobock's vertically integrated foundry controls upstream magnet sourcing.
- AI Algorithms:Machine learning models for pattern recognition in myoelectric signal processing, enabling intuitive multi-joint control without nerve reinnervation surgery. Embedded inference engines consolidate previously separate hardware layers in stroke rehabilitation protocols.
- Sensor Integration:Fusion of inertial measurement units, force-sensitive resistors, and surface electromyography electrodes.
- Control Interfaces:Joystick, sip-and-puff, or switch-based alternatives for patients lacking sufficient neuromuscular signal quality.
Generating highest margins: AI Algorithms. Expanding most quickly: Robotic Systems.
End User:
Customer type determines contract structure, from bundled lifetime service agreements to discrete capital purchases.
- Rehabilitation Centers:Specialized facilities combining exoskeleton hardware with licensed gait training protocols. Germany's Federal Joint Committee reimbursement decisions dictate procurement cycles, with statutory coverage expansion accelerating adoption. Third-party physical therapy operators increasingly source hardware independently from curricula.
- Hospitals:Academic medical centers leading unbundling of device purchasing from therapy services. Spinal cord injury programs separate capital equipment decisions from software-enabled training programs, compressing vendor margins.
- Research Institutions:Clinical trial sites generating longitudinal safety data for regulatory submissions.
- Home Care:Residential mobility solutions constrained by reimbursement gaps and caregiver training requirements.
Commanding current revenue concentration: Rehabilitation Centers. Poised for structural expansion: Home Care.
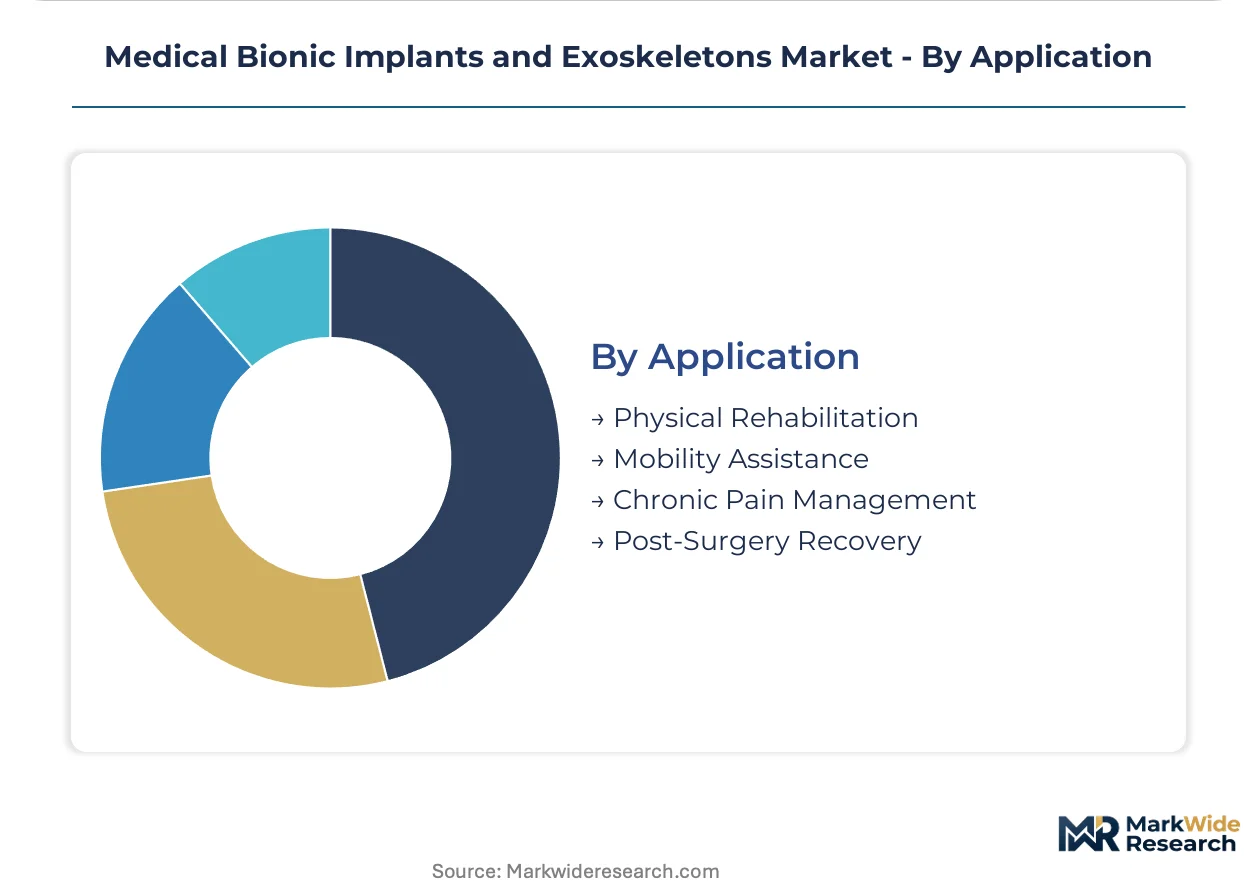
Application:
Maturity gradients separate established physical therapy protocols from emerging chronic condition management.
- Physical Rehabilitation:Stroke neurorehabilitation protocols reducing long-term care costs through accelerated motor recovery. Implantable myoelectric sensors with onboard edge computing compress per-patient setup time in German and United States facilities.
- Mobility Assistance:Paraplegic ambulation in clinical settings using powered exoskeletons with fall-prevention balance algorithms. Patient selection criteria limit addressable population to specific injury levels and residual function profiles.
- Chronic Pain Management:Spinal cord stimulation and peripheral nerve interfaces for neuropathic conditions.
- Post-Surgery Recovery:Temporary assistive devices bridging acute care discharge and functional independence.
Dominating installed base: Physical Rehabilitation. Gaining share fastest: Mobility Assistance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston anchors North American exoskeleton development through its concentration of academic medical centers and FDA-cleared rehabilitation protocols. The United States, Germany, Japan, and China concentrate distinct competitive advantages across regulatory pathways, reimbursement systems, and manufacturing scale.
United States
Academic medical centers in Boston and the San Francisco Bay Area drive clinical trial recruitment for neural prosthetic devices. FDA premarket approval pathways mandate multi-year safety studies that filter market access toward well-capitalized developers. The Baltimore-Washington corridor concentrates federal research funding through NIH and DARPA programs advancing brain-computer interface technology.
Germany
Statutory health insurance reimbursement for exoskeleton-assisted gait training has expanded through Federal Joint Committee decisions, accelerating rehabilitation center procurement in Berlin and Munich. The EU Medical Device Regulation tightens clinical evidence requirements for active implantable devices. Duderstadt hosts Ottobock's vertically integrated component foundry controlling magnet sourcing for powered prosthetic joints.
Japan
PMDA accelerated review timelines for regenerative medicine devices incorporating bionic interfaces redirect R&D investment toward the Tokyo-Osaka clinical corridor. Government funding programs support brain-computer interface startups achieving regulatory milestones. Tsukuba Science City concentrates neural signal processing research with embedded machine learning inference capabilities.
China
Domestic manufacturers face input cost volatility from rare-earth processing concentration, with neodymium supply chains creating vulnerability for servo-actuated joint production. The national medical device regulator tightens clinical data requirements for active implantable devices. Shenzhen's hardware manufacturing ecosystem produces cost-competitive actuator components for export markets.
Switzerland
Swissmedic maintains stringent oversight of active implantable devices while supporting precision manufacturing clusters in the Lake Geneva region. Reimbursement negotiations with health insurers determine market access for premium prosthetic technologies. Zurich concentrates research institutions generating longitudinal safety data for European regulatory submissions.
Medical Bionic Implants and Exoskeletons Market Competitive Landscape
Premium-margin players sit above commodity-margin players across regulatory sophistication and clinical evidence depth. The vendor base stratifies into three tiers: vertically integrated component manufacturers controlling upstream magnet supply, FDA-cleared protocol developers dominating hospital purchasing criteria, and emerging brain-computer interface specialists pursuing accelerated regulatory pathways. Consolidation pressure favors well-capitalized developers capable of funding decade-long safety monitoring programs. Dominant competitive moves include strategic partnerships with rehabilitation center networks and backward integration into rare-earth magnet sourcing.
Within the vertically integrated tier, Ottobock SE & Co. KGaA exemplifies upstream control over critical actuator components. Among FDA-cleared rehabilitation specialists, Ekso Bionics Holdings, Inc. and ReWalk Robotics Ltd. occupy positions shaped by bundled service contract economics. Hocoma AG represents the Swiss precision manufacturing archetype with established European regulatory track records. CYBERDYNE Inc. and Myomo Inc. sit within the neural interface development cluster targeting response latency breakthroughs below 50 milliseconds.
| Leading Market Players |
|---|
| Lifeward Ltd. |
| B-Temia Inc. |
| Ekso Bionics Holdings, Inc. |
| Hocoma AG |
| Rex Bionics Ltd. |
| Ottobock SE & Co. KGaA |
| ReWalk Robotics Ltd. |
| Myomo Inc. |
| CYBERDYNE Inc. |
| Others |
Supply & Pricing Matrix
Neodymium oxide price volatility cascades through servo-actuated joint manufacturing into three-tier pricing structures across premium, standard, and economy levels. Magnet sourcing costs differentiate rehabilitation center contracts from home-use device quotations.
Pricing Analysis
Value-based pricing anchored to gait training session throughput dominates rehabilitation center procurement. Pricing stratifies across premium, standard, and economy tiers based on FDA clearance tier and myoelectric sensor channel count. Cost compression in standard-tier exoskeletons is intensifying because hospital procurement committees unbundle hardware from service contracts. Academic medical centers exhibit highest price sensitivity; German statutory insurers show lowest sensitivity due to reimbursement coverage expansion.
Supply Chain Analysis
Direct-to-rehabilitation-center channels handle institutional buyer demand with bundled service agreements. Rare-earth magnet supply concentrates in China, Germany, and Japan for neodymium processing and alternative magnet R&D. Permanent magnet motors and harmonic drive gearboxes draw from concentrated upstream foundries. Single-source vulnerability in Chinese rare-earth processing creates input cost instability. Distribution runs through OEM-direct hospital contracts and third-party physical therapy operator procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Medical bionic implants occupy a technology-transition phase where embedded machine learning inference replaces discrete hardware signal processing layers.
For Market Incumbents: Deepen backward integration into magnet sourcing to offset Chinese supply concentration risk. Expand FDA-cleared protocol libraries to defend against emerging brain-computer interface specialists. Prioritize certification investment in EU Medical Device Regulation post-market surveillance systems. For New Entrants and Emerging Players: Launch via home-use exoskeleton direct-to-consumer channels where reimbursement gaps create white-space opportunity. Target residential mobility segments in German-speaking markets leveraging statutory insurance precedent. Pursue software-enabled training curriculum licensing as go-to-market angle. For Investors and Strategic Acquirers: Distressed-cycle entries favor vertically integrated component manufacturers with captive magnet supply in Central Europe. Five-to-ten year viability hinges on longitudinal clinical data generation capacity. Watch Germany's Federal Joint Committee reimbursement decisions for home-use devices as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU Medical Device Regulation compliance opens statutory reimbursement access in German rehabilitation centers. |
| Backward Integration | Captive rare-earth magnet sourcing insulates servo-actuated joint margins from Chinese processing volatility. |
| Hospital System Partnership | Academic medical center alliances secure FDA-cleared rehabilitation protocol adoption. |
| Software Companion Development | Machine learning-enabled pattern recognition differentiates myoelectric control systems. |
| Reimbursement Strategy | Federal Joint Committee engagement determines home-use exoskeleton market expansion feasibility. |
Research Methodology
Independent corroboration across rehabilitation center procurement managers, biomedical engineers, GPO contracts managers, and regulatory affairs leads underwrites the qualitative findings. Secondary validation draws from FDA 510(k) filings, EU Medical Device Regulation submissions, hospital procurement databases, and CMS Medicare reimbursement data. Bottom-up patient population modeling and top-down equipment shipment triangulation converge on segment estimates.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions span product architecture, technology tier, end-user contract structure, and regional regulatory cluster. CAGRs derive from fitted trend extrapolation against policy inflection points. Forecast inputs include German statutory insurance coverage decisions and PMDA accelerated review pathway utilization rates.
The model assumes a particular technology adoption path; alternative pathways for non-invasive neural interfaces would alter the outlook. Forecasts reflect assumptions around reimbursement expansion timelines and rare-earth supply stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Hydrogel Contact Lenses Market
Medical Devices
Genitourinary Prosthetics Market
Medical Devices
Medical Machine Battery Market
Medical Devices
Orthokeratology Lens Market
Medical Devices
Global Artificial Organs and Bionics Market
Medical Devices
Treatment Pumps Market
Medical Devices
United States Respiratory Devices Market
Medical Devices
Intelligent Prosthetics Market
Medical Devices
Arteriovenous Fistula Devices Market
Medical Devices
Global Surgical Navigation System Market
Medical Devices
Global Gastrointestinal Devices Market
Medical Devices
Smart Infusion Pump Market
Medical Devices
Skin Rejuvenation Devices Market
Medical Devices
Global Gynecological Dilators Market
Medical Devices
North America Oxygen Concentrators Market
Medical Devices
Ultrasonic Dissection Devices Market