
 Electroencephalography Systems/Devices Market | 2026-2036
Electroencephalography Systems/Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Electroencephalography Systems/Devices Market Analysis
Buyer concentration across hospital neurology departments is rebalancing toward larger integrated delivery networks that centralize neurodiagnostic procurement. Natus Medical leverages its installed base in hospital sleep labs to sustain recurring revenue from disposables and service contracts. Nihon Kohden Corporation anchors its position through deep channel control in Japanese and North American acute care settings. Compumedics differentiates via specialized long-term epilepsy monitoring systems that occupy premium tier placements in tertiary neurology centers.
Electroencephalography systems measure electrical activity through scalp electrodes, typically capturing signals across 19-256 channels with sampling rates from 256 Hz to 20 kHz depending on clinical or research requirements. These devices serve primary commercial purposes in epilepsy diagnosis, sleep disorder assessment, and neurofeedback applications where real-time cortical signal visualization guides therapeutic decisions. Wireless EEG product configurations are capturing expanding share in ambulatory and home-based monitoring settings where patient mobility constraints limit wired deployments. Brain-computer interface applications represent the fastest-growing demand segment, though sleep studies and seizure detection still dominate absolute revenue contribution across hospital and clinic end users.
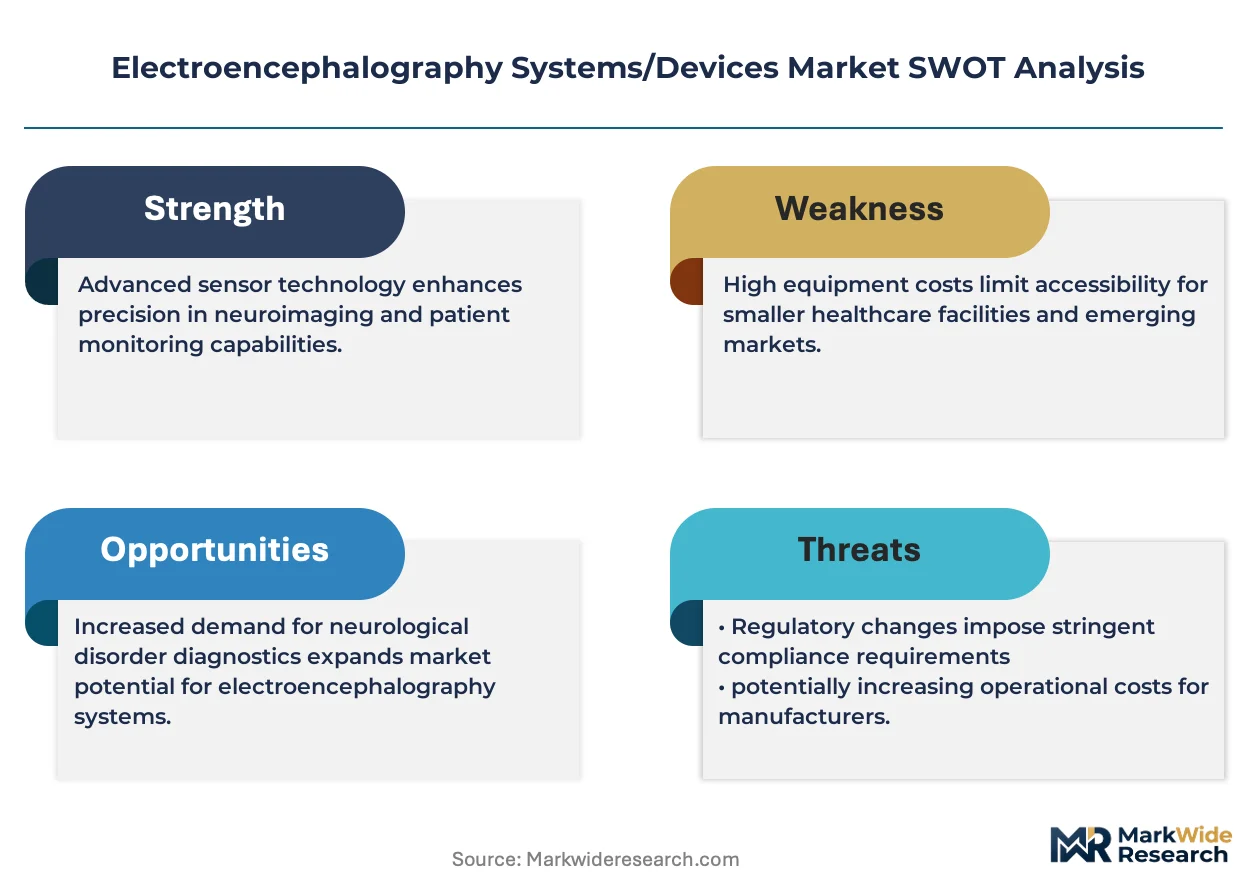
FDA 510(k) clearance requirements shape product development timelines and clinical validation burdens for manufacturers targeting the United States, while CE marking under the EU Medical Device Regulation governs European market access with stricter post-market surveillance obligations. ISO 13485 quality management certification operates as a baseline procurement filter for institutional buyers evaluating vendor qualification. Stakeholders must monitor evolving reimbursement codes for remote EEG monitoring and ambulatory brain-computer interface applications as payor policy will determine commercial scalability beyond traditional hospital settings.
Market Dynamics
Wireless EEG hardware is modularizing rapidly, collapsing the traditional separation between hospital-grade diagnostics and consumer-accessible brain-sensing platforms. This structural shift compresses validation timelines while expanding addressable use cases beyond clinical settings.
Growth Catalysts
- FDA 510(k) pathway streamlining:Accelerated clearance protocols for wearable brain-sensing devices reduce commercialization barriers for manufacturers targeting ambulatory monitoring segments.
- Epilepsy monitoring protocols:Hospital neurology departments are expanding continuous EEG adoption for seizure detection, driving replacement cycles for legacy 32-channel systems.
- Boston-San Francisco neurotechnology clusters:Geographic concentration of academic medical centers and venture funding creates specialized demand pipelines for high-density research-grade systems.
Market Restraints
- Silver-silver chloride electrode cost volatility:Raw material price swings for specialized biocompatible sensors compress margins on disposable consumables.
- Japanese component supply concentration:Precision analog-to-digital converter modules face single-source dependencies from specialized semiconductor foundries.
- EU MDR post-market surveillance:Stricter clinical follow-up obligations under the Medical Device Regulation extend total cost of ownership for European deployments.
Strategic Opportunities
- Home-based neurofeedback therapy:Underpenetrated consumer wellness applications in sleep optimization and attention training await validated hardware-software bundles.
- Brain-computer interface gaming:Convergence of EEG signal processing with real-time rendering engines opens entertainment and accessibility verticals.
- IRA neurotechnology research credits:US federal incentives for neurological disorder research accelerate institutional procurement of high-channel-count research systems.
Industry Challenges
- Clinical neurophysiologist training pipelines:Specialized interpretation skills for complex epileptiform patterns face generational workforce gaps.
- ISO 13485 certification timelines:Quality management system audits create 12-18 month delays for new market entrants seeking institutional procurement eligibility.
- Legacy EMR integration complexity:Hospital information system interoperability requirements force costly custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electroencephalography Systems/Devices Market |
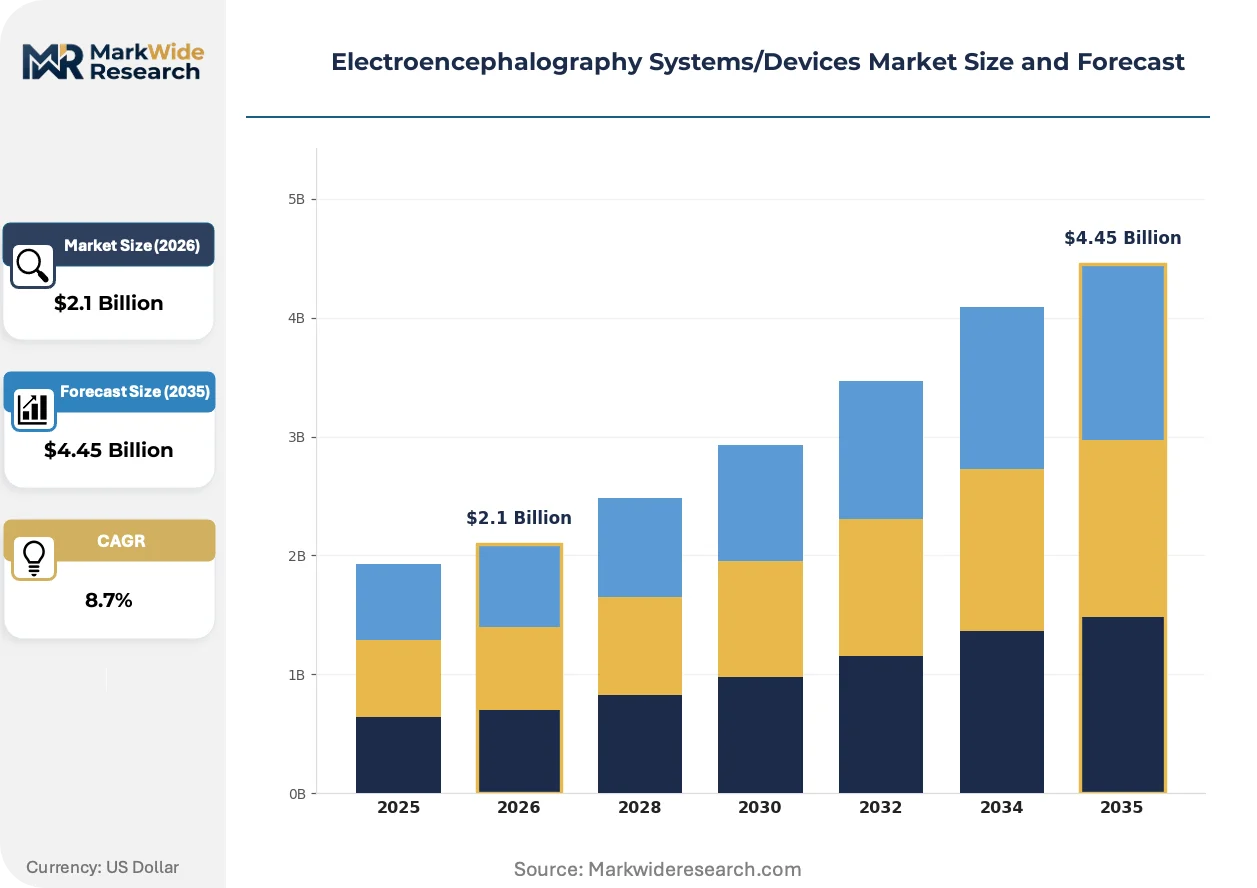
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable EEG, Wired EEG, Wireless EEG, Wearable EEG Technology: Long-Term Monitoring, Real-Time Feedback, Signal Processing, Data Analytics End User: Clinics, Research Institutions, Hospitals, Neurology Centers Application: Sleep Studies, Seizure Detection, Cognitive Research, Brain-Computer Interfaces |
| Companies Covered | Natus Medical, Nihon Kohden Corporation, Compumedics, Cadwell Laboratories, Neurosoft, Brain Products GmbH, Micromed, Electrical Geodesics, NeuroWave Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electroencephalography Systems/Devices Market Emerging Trajectories
Signal processing architectures are fragmenting across edge-computing and cloud-dependent models, creating divergent hardware design philosophies. This bifurcation reshapes vendor specialization and buyer evaluation criteria.
Dry-electrode arrays with active impedance compensation are modularizing rapidly, enabling rapid deployment without conductive gel preparation. Tertiary epilepsy centers are adopting these systems for emergency department triage. The technology is compressing setup times from 45 minutes to under 10 minutes while maintaining clinical-grade signal fidelity.
EU MDR Article 10 technical documentation requirements are forcing manufacturers to restructure quality management systems. Small-to-mid sized device firms face disproportionate compliance burdens relative to their revenue bases. The regulation is accelerating consolidation as specialized EEG vendors seek regulatory infrastructure through acquisition.
Hospital procurement committees are unbundling hardware from software service contracts, forcing vendors to price discretely. Integrated delivery networks in the United States are driving this shift through centralized neurodiagnostic capital planning. The pattern concentrates negotiating leverage with buyers who can aggregate multi-site deployments.
Electroencephalography Systems/Devices Market Segmentation
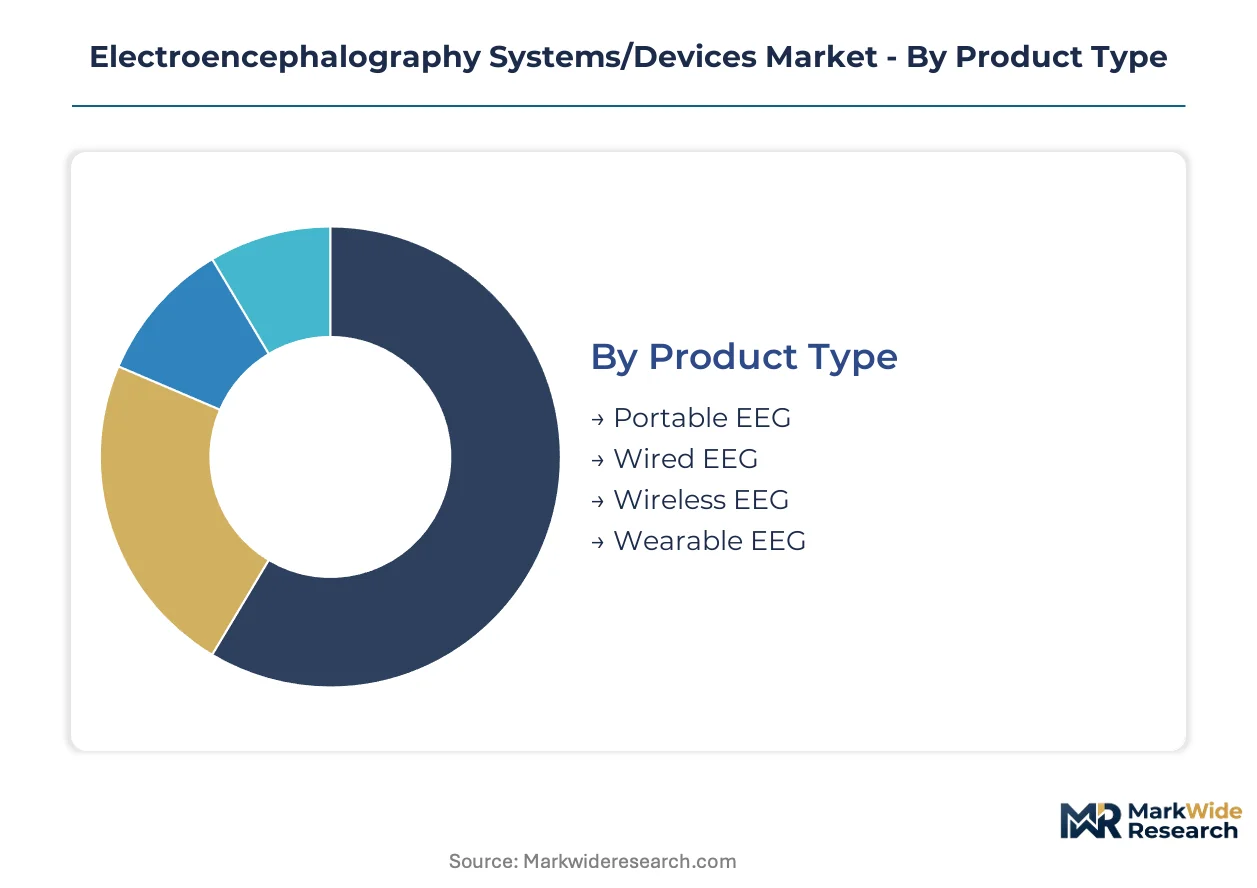
Electroencephalography systems fragment across hardware configurations, signal processing architectures, and clinical deployment settings. Each segment carries distinct validation requirements, reimbursement pathways, and buyer procurement behaviors that shape vendor strategy and pricing power.
Product Type:
Customization versus standardization tension runs deepest here, with modular wireless designs disrupting legacy wired installations while portable formats bridge institutional and ambulatory use cases.
- Portable EEG:Battery-powered units with 16-64 channel configurations enable point-of-care deployment in emergency departments and intensive care settings. Demand concentrates in United States academic medical centers where rapid seizure triage protocols require bedside availability. FDA 510(k) clearance timelines for portable hardware run 6-9 months shorter than full stationary systems, accelerating commercialization for mid-tier manufacturers.
- Wired EEG:Traditional tethered configurations with 128-256 channels deliver research-grade sampling rates up to 20 kHz for epilepsy monitoring suites. Tertiary neurology centers in Boston and San Francisco sustain replacement demand as legacy 32-channel systems reach end-of-life. High-density wired arrays remain mandatory for pre-surgical epilepsy localization procedures.
- Wireless EEG:Radio-frequency or Bluetooth-enabled headsets eliminate patient mobility constraints during long-term monitoring. Home-based sleep studies and ambulatory seizure detection drive fastest expansion.
- Wearable EEG:Consumer-accessible form factors with dry electrodes target wellness and neurofeedback applications. CE marking under EU MDR governs European commercialization with stricter biocompatibility testing than FDA pathways.
Leading the category by volume: Wired EEG. Growing fastest: Wireless EEG.
Technology:
Cost tier stratification separates capital-intensive hardware-integrated systems from software-layer monetization models with recurring revenue potential.
- Long-Term Monitoring:Continuous recording architectures with cloud storage integration support 24-72 hour epilepsy surveillance protocols. Hospital neurology departments in Japan and Germany drive premium placements for video-EEG correlation systems. PMDA and BfArM regulatory requirements extend validation timelines but lock in multi-year service contracts.
- Real-Time Feedback:Closed-loop neurofeedback engines with sub-100ms latency enable therapeutic interventions for ADHD and anxiety disorders. Neurotechnology startups in San Francisco cluster around this modality for brain-computer interface development.
- Signal Processing:Analog-to-digital conversion and artifact rejection algorithms differentiate hardware performance. Japanese semiconductor supply concentration creates single-source dependencies for precision ADC modules.
- Data Analytics:Machine learning classification of epileptiform patterns reduces interpretation burden on clinical neurophysiologists. ISO 13485 certification requirements filter vendor qualification for institutional procurement.
Highest margin capture: Data Analytics. Steepest expansion trajectory: Real-Time Feedback.
End User:
Customer type determines pricing elasticity, with consolidated integrated delivery networks extracting volume discounts unavailable to fragmented clinic buyers.
- Hospitals:Inpatient neurology departments and intensive care units represent the revenue anchor for 256-channel diagnostic systems. United States hospital procurement committees unbundle hardware from software contracts, compressing vendor margins.
- Neurology Centers:Specialized epilepsy monitoring units command premium placements for long-term video-EEG suites. Medicare reimbursement codes for continuous EEG monitoring sustain capital investment cycles.
- Research Institutions:Academic medical centers in Boston and San Francisco drive demand for high-channel-count research-grade systems. IRA neurotechnology research credits accelerate federal funding flows.
- Clinics:Outpatient neurology practices favor portable and wireless configurations for routine diagnostic workups. Smaller buyers face ISO 13485 certification barriers that favor established vendors.
Concentrating negotiating leverage: Hospitals. Gaining share fastest: Research Institutions.
Application:
Maturity gradient spans decades-old sleep medicine protocols to emerging brain-computer interface verticals with unproven reimbursement pathways.
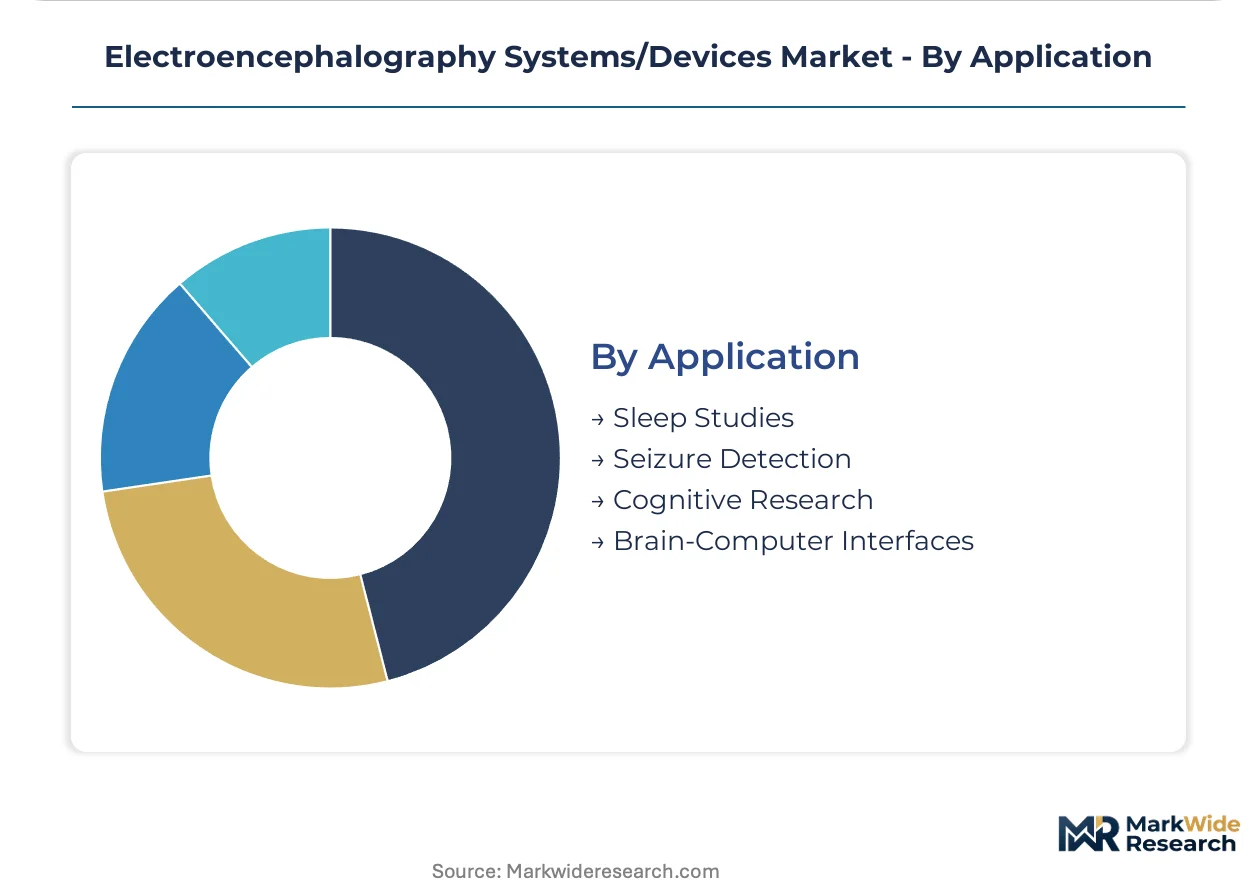
- Sleep Studies:Polysomnography-integrated EEG channels remain the clinical standard for apnea and narcolepsy diagnosis. Natus Medical sustains recurring revenue from disposable electrodes and service contracts across United States sleep lab networks.
- Seizure Detection:Continuous monitoring for epilepsy represents the largest absolute revenue pool across institutional end users. Compumedics occupies premium tier placements in tertiary centers with specialized long-term monitoring systems.
- Brain-Computer Interfaces:Signal translation for prosthetic control and accessibility applications climbs fastest despite reimbursement uncertainty. Venture funding concentrates in San Francisco neurotechnology clusters.
- Cognitive Research:Experimental protocols for attention, memory, and decision-making studies utilize research-grade sampling rates. University procurement cycles follow federal grant award timelines.
Dominating absolute revenue: Seizure Detection. Expanding most quickly: Brain-Computer Interfaces.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital neurology departments in the United States concentrate the highest absolute demand for high-channel-count diagnostic systems. Academic medical centers and venture-funded neurotechnology clusters generate specialized procurement pipelines for research-grade hardware.
United States
Integrated delivery networks in Boston and San Francisco aggregate multi-site procurement leverage for neurodiagnostic capital planning. FDA 510(k) clearance pathways accelerate commercialization timelines for wearable brain-sensing devices targeting ambulatory monitoring. Medicare reimbursement codes for continuous EEG monitoring sustain hospital investment cycles across tertiary epilepsy centers.
Germany
BfArM regulatory requirements extend validation timelines for long-term video-EEG correlation systems but lock in multi-year service contracts. The country's precision engineering base supplies specialized analog-to-digital converter modules to global device manufacturers. Tertiary neurology centers in Munich and Heidelberg drive replacement demand for legacy 32-channel monitoring installations.
Japan
PMDA approval processes filter market entry for foreign manufacturers while METI industrial policy supports domestic semiconductor foundry capacity for precision ADC components. Nihon Kohden Corporation anchors channel control in acute care settings through deep hospital relationships. Tokyo and Osaka medical districts concentrate demand for sleep disorder assessment hardware.
United Kingdom
NHS England procurement frameworks centralize neurodiagnostic purchasing across integrated care systems, compressing vendor margins through volume aggregation. MHRA post-market surveillance aligns with EU MDR technical documentation requirements for CE-marked devices. London academic medical centers and the Cambridge neurotechnology corridor sustain research-grade system demand.
Australia
TGA regulatory pathways for software-as-medical-device classifications shape data analytics vendor market access strategies. Compumedics occupies premium tier placements through specialized long-term epilepsy monitoring systems. Melbourne and Sydney tertiary neurology centers drive adoption of dry-electrode arrays for emergency department triage protocols.
Electroencephalography Systems/Devices Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue brain-computer interface and consumer wellness applications outside traditional clinical validation frameworks. The vendor base stratifies across three tiers: diversified medical device conglomerates with sleep lab installed bases, specialized neurodiagnostic pure-plays with epilepsy monitoring expertise, and venture-backed neurotechnology startups targeting ambulatory and research applications. Dominant competitive moves include regulatory infrastructure acquisition to compress EU MDR compliance timelines and unbundling of hardware from software service contracts to meet integrated delivery network procurement requirements.
Among diversified medical device conglomerates, Natus Medical leverages its installed base across United States sleep lab networks to sustain recurring revenue from disposables and service contracts. Nihon Kohden Corporation represents the acute care channel control archetype through deep relationships in Japanese and North American hospital settings. Compumedics exemplifies the specialized premium-tier positioning strategy, occupying placements in tertiary neurology centers with dedicated long-term monitoring expertise.
| Leading Market Players |
|---|
| Natus Medical |
| Nihon Kohden Corporation |
| Compumedics |
| Cadwell Laboratories |
| Neurosoft |
| Brain Products GmbH |
| Micromed |
| Electrical Geodesics |
| NeuroWave Systems |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap specialists in precision analog-to-digital converter manufacturing anchor supply discipline through captive semiconductor foundry relationships, while their pricing power in Japanese and German acute care channels resists commoditization pressure from modular wireless entrants.
Pricing Analysis
Volume concentrates in portable 16-64 channel configurations where per-unit transactional pricing dominates hospital procurement, while margin capture clusters in long-term monitoring systems with multi-year service bundling. Price differentiation hinges on FDA 510(k) clearance tier and ISO 13485 certification status, with uncertified vendors excluded from integrated delivery network tenders. Cost compression in disposable silver-silver chloride electrodes is intensifying because raw material volatility transfers downstream, squeezing consumables margins. Smaller outpatient neurology clinics exhibit highest price sensitivity, whereas tertiary epilepsy centers prioritize signal fidelity over acquisition cost.
Supply Chain Analysis
Japan's METI industrial policy and local-content mandates for medical device components are reshaping sourcing patterns, pressuring foreign manufacturers to qualify domestic semiconductor foundries. Precision analog-to-digital converter modules draw from Japan, Taiwan, and the United States, while biocompatible electrode materials rest on German and Japanese chemical suppliers. Single-source vulnerability in specialized ADC fabrication creates chokepoint exposure when foundry capacity tightens. Distribution runs through hospital procurement committees and group purchasing organizations that aggregate multi-site neurodiagnostic capital planning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply constraints in clinical neurophysiologist training pipelines prop pricing discipline for interpretation-intensive long-term monitoring systems, insulating premium-tier vendors from wireless commoditization.
For Market Incumbents: To counter modular wireless entrants collapsing hospital-consumer boundaries, deepen backward integration into precision ADC component supply and accelerate FDA 510(k) pathway expertise acquisition to compress rival clearance timelines. Lock in integrated delivery network procurement committees through unbundled software service contracts that aggregate multi-site deployment leverage. For New Entrants and Emerging Players: Neurotechnology venture capital clusters in San Francisco offer channel partner density for brain-computer interface applications, the most penetrable segment given reimbursement uncertainty blocking incumbent resource allocation. Target home-based neurofeedback therapy white space with validated hardware-software bundles bypassing institutional ISO 13485 certification barriers through direct-to-consumer CE marking pathways. For Investors and Strategic Acquirers: FDA 510(k) clearance acceleration for wearable brain-sensing devices is the leading indicator that ambulatory monitoring segments will consolidate around regulatory infrastructure owners. Five-to-ten year viability favors specialized neurodiagnostic pure-plays with epilepsy monitoring expertise over diversified conglomerates facing sleep lab revenue erosion. Watch PMDA and BfArM approval timeline compression as the signal that Japanese and German channel control premiums are eroding.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Infrastructure Acquisition | EU MDR Article 10 compliance capabilities compress market entry timelines for specialized EEG vendors. |
| Dry-Electrode Array Development | Active impedance compensation technology collapses emergency department setup times from 45 minutes to under 10 minutes. |
| Software Service Unbundling | Discrete pricing meets integrated delivery network procurement requirements while protecting recurring revenue streams. |
| Brain-Computer Interface Platform Integration | Real-time signal processing convergence with rendering engines opens entertainment and accessibility verticals. |
| Reimbursement Strategy Development | Medicare code expansion for remote EEG monitoring determines commercial scalability beyond hospital settings. |
Methodological Framework
Multi-period observation of FDA 510(k) clearance timelines, PMDA approval patterns, and hospital procurement contract structures anchored the trend analysis, supplemented by interviews with clinical neurophysiologists, biomedical engineers, hospital purchasing committee members, and neurotechnology venture capitalists. Secondary validation drew from FDA 510(k) filings, PMDA approval databases, CMS Medicare reimbursement code updates, and hospital GPO contract disclosures. Bottom-up channel checks across Boston and San Francisco neurotechnology clusters triangulated against top-down market sizing from equipment manufacturer revenue disclosures.
Input-output matrices modeled hardware configurations against signal processing architectures and clinical deployment settings across the projection horizon. Segmentation dimensions spanned product type, technology layer, end-user concentration, and application maturity. CAGRs derived from replacement cycle analysis for legacy 32-channel systems and penetration curves for wireless ambulatory formats. Forecast inputs incorporated IRA neurotechnology research credit allocation flows and EU MDR compliance cost burdens.
Caveats apply where FDA 510(k) pathway streamlining reverses or silver-silver chloride electrode supply disruptions materially shift the outlook for disposable consumables economics. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Depression Devices Market
Medical Devices
Nonablative Laser Resurfacing Devices Market
Medical Devices
Human Augmentation in Healthcare Market
Medical Devices
Oxygen Therapy Devices Market
Medical Devices
Digital Radiology Devices Market
Medical Devices
Removable Partial Dentures Market
Medical Devices
Glass Syringe Market
Medical Devices
Breast Localization System Market
Medical Devices
PDA Closure Devices Market
Medical Devices
Global Veress Needle Market
Medical Devices
North America Renal Denervation Devices Market
Medical Devices
Single Lead ECG Equipment Market
Medical Devices
Liver-On-Chip Market
Medical Devices
Cranial Perforator Market
Medical Devices
Abdominal Closure Systems Market
Medical Devices
Global Gynecological Devices Market