
 Airway Clearance Devices System Market | 2026-2036
Airway Clearance Devices System Market Size, Share, and Industry Trends Forecast 2026-2036
Airway Clearance Devices System Market Outlook
Germany is tilting toward expanded airway clearance device manufacturing as European respiratory care infrastructure modernizes. Medtronic leverages its cardiac and respiratory portfolio to sustain integrated device ecosystems across acute and post-acute channels. Koninklijke Philips N.V. anchors its position through connected care platforms that extend from hospital to home ventilation and secretion management. Hill-Rom competes on clinical workflow integration, occupying premium installed-base positions in North American intensive care units.
An airway clearance device system encompasses mechanical, electronic, and smart technologies designed to mobilize pulmonary secretions through oscillatory pressure, positive expiratory force, or suction-assisted extraction, typically operating at frequencies between 5 and 25 Hz and pressure thresholds calibrated to patient tolerance. These systems serve cystic fibrosis, chronic obstructive pulmonary disease, asthma, and pneumonia management by reducing mucus retention and infection risk. High-frequency chest wall oscillation leads product type revenue due to reimbursement anchoring in hospital settings, while smart technologies represent the fastest-expanding technology dimension as remote patient monitoring integrates with home care workflows. Home care end users concentrate margin pools through recurring consumable attachment and reduced clinical labor dependency.
FDA 510(k) clearance pathways and ISO 13485 quality management standards govern device commercialization in the United States, while the EU Medical Device Regulation imposes enhanced clinical evidence requirements for mechanical and electronic airway systems entering European markets. These frameworks elevate barriers for novel entrants and reward established manufacturers with predicate device libraries and notified body relationships. Stakeholders must monitor reimbursement recalibration for home-based oscillation therapy as payors weigh hospitalization avoidance against device acquisition costs.
Market Dynamics
Home care migration is collapsing the traditional hospital-centric revenue model for airway clearance systems, forcing manufacturers to reconfigure device portfolios around portability, connectivity, and patient self-management capabilities.
Growth Catalysts
- FDA 510(k) predicate pathways:Established manufacturers leverage extensive clearance histories to accelerate new device introductions while newcomers face extended review timelines.
- High-frequency chest wall oscillation:Hospital reimbursement anchoring sustains installed-base expansion and consumable recurring revenue streams across acute care networks.
- Germany:European respiratory infrastructure modernization drives manufacturing capacity expansion and regional supply chain clustering.
Market Restraints
- EU Medical Device Regulation clinical evidence requirements:Enhanced documentation burdens extend commercialization timelines and elevate compliance costs for mechanical and electronic systems.
- Semiconductor component concentration:Sourcing dependencies for sensor and microcontroller inputs create vulnerability to allocation constraints and price volatility.
- Positive expiratory pressure devices:Lower-cost alternatives limit pricing power for premium oscillation systems in price-sensitive segments.
Strategic Opportunities
- Japan:Aging demographics and chronic respiratory disease prevalence create underpenetrated demand for home-based secretion management solutions.
- Remote patient monitoring convergence:Integration of oscillation therapy data with telehealth platforms enables outcome-based contracting with payors.
- United States Medicare Advantage:Risk-based reimbursement models incentivize hospitalization avoidance through preventive device deployment.
Industry Challenges
- Biomedical engineering talent scarcity:Specialized expertise in respiratory mechanics and embedded systems development constrains R&D throughput.
- ISO 13485 quality management certification:Multi-year implementation timelines delay market entry for emerging manufacturers.
- Legacy hospital IT integration:Proprietary data protocols complicate connectivity with existing electronic health record infrastructures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airway Clearance Devices System Market |
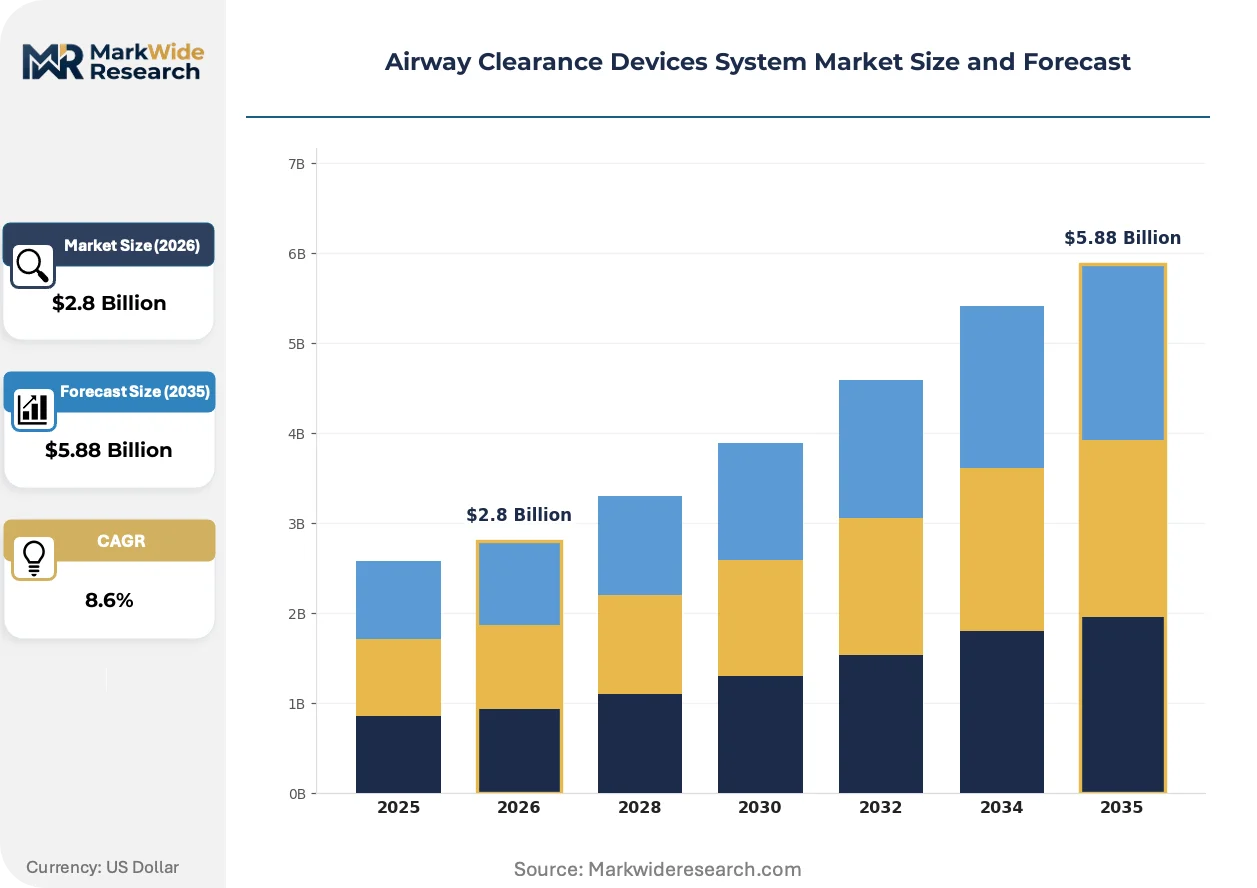
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.88 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Frequency Chest Wall Oscillation, Positive Expiratory Pressure, Manual Techniques, Airway Suction End User: Hospitals, Home Care, Rehabilitation Centers, Long-Term Care Facilities Technology: Mechanical Devices, Electronic Devices, Smart Technologies, Handheld Devices Application: Cystic Fibrosis, Chronic Obstructive Pulmonary Disease, Asthma, Pneumonia |
| Companies Covered | Hill-Rom, Medtronic, Koninklijke Philips N.V., Electromed, Vyaire Medical, Smiths Medical, Baxter, PARI GmbH, ResMed, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airway Clearance Devices System Market Strategic Shifts
Smart connectivity and algorithm-driven therapy personalization are redefining competitive differentiation, shifting value capture from hardware margins toward software-enabled service ecosystems and longitudinal patient data monetization.
High-frequency chest wall oscillation technology is collapsing the boundary between acute and post-acute care settings. Home care agencies and durable medical equipment suppliers are adopting hospital-caliber devices at accelerating rates. This convergence compresses the traditional acute-to-home device tiering structure and forces single-platform strategies.
The EU Medical Device Regulation imposes strengthened clinical evidence requirements for airway clearance systems entering European markets. Manufacturers must generate prospective data or leverage substantial equivalence arguments with robust predicate histories. Class IIa and IIb device categories face the steepest compliance burden, driving consolidation among notified body relationships.
Patient self-management preferences are reshaping procurement authority toward individual buyers and family caregivers. Retail pharmacy and direct-to-consumer channels are displacing traditional durable medical equipment distribution in United States and Western European markets. Cystic fibrosis patient advocacy networks in Germany and the United States accelerate this behavioral shift through peer education and reimbursement navigation support.
Airway Clearance Devices System Market Segmentation
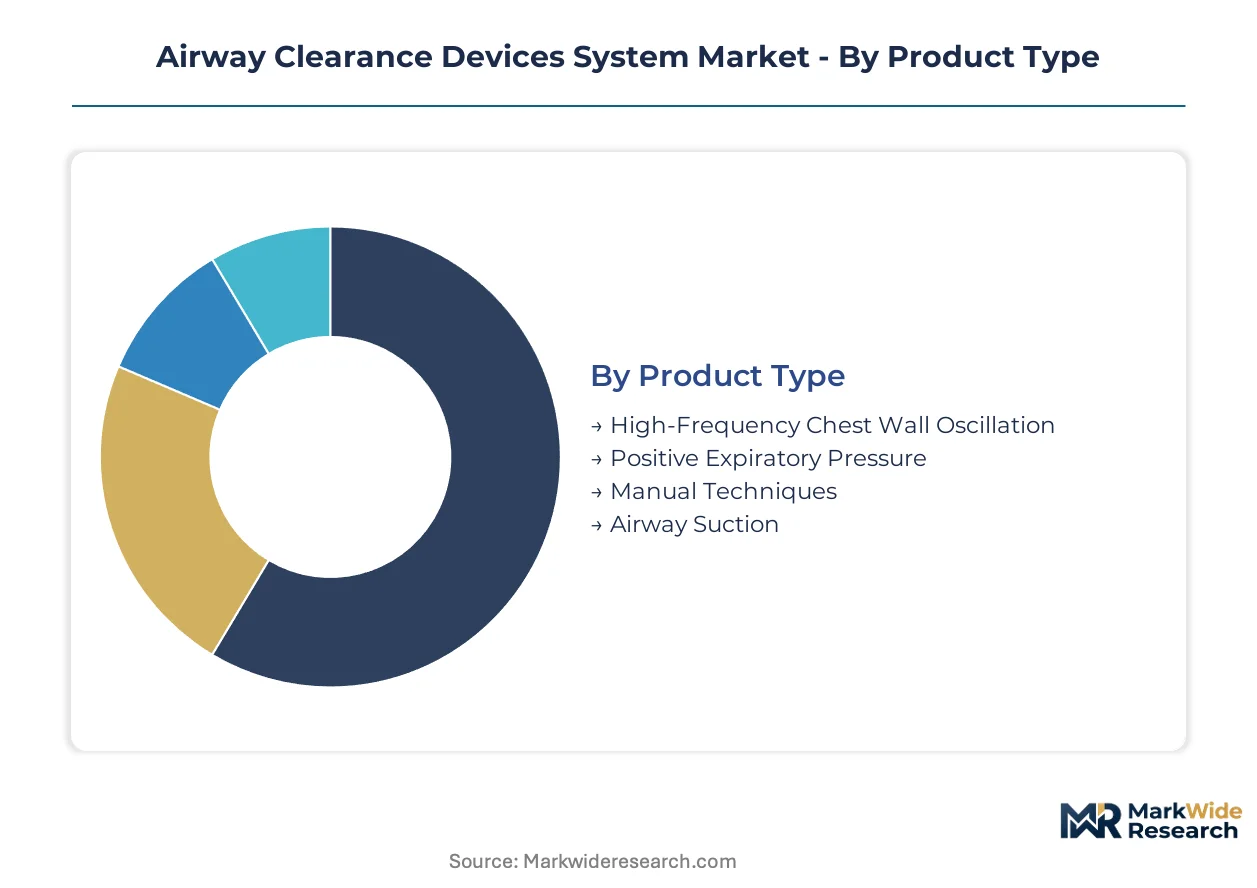
Airway clearance device manufacturers configure product portfolios around four intersecting dimensions that determine reimbursement pathways, regulatory classification, and channel economics. Each segmentation layer carries distinct margin profiles and competitive intensity.
Product Type:
Clinical indication severity and reimbursement anchoring shape the use-case spectrum across mechanical and powered modalities.
- High-Frequency Chest Wall Oscillation:Vest-based systems deliver oscillatory pressures at calibrated frequencies to mobilize secretions in non-ambulatory patients. Hospital procurement in the United States and Germany sustains premium pricing through durable medical equipment reimbursement codes.
- Positive Expiratory Pressure:Mask or mouthpiece devices generate back-pressure during exhalation to splint airways and enhance mucus clearance. Home care channels in Japan concentrate demand as patients self-manage chronic obstructive pulmonary disease outside acute settings.
- Manual Techniques:Chest physiotherapy performed by trained caregivers without mechanical assistance. Long-term care facilities deploy these methods where capital equipment budgets constrain device acquisition.
- Airway Suction:Catheter-based systems extract secretions through applied negative pressure. Intensive care units require these devices for patients with compromised cough reflexes.
Established volume favors High-Frequency Chest Wall Oscillation; emerging adoption favors Positive Expiratory Pressure.
End User:
Care setting migration from acute facilities to domestic environments restructures procurement authority and recurring revenue potential.
- Hospitals:Acute care networks purchase capital equipment with institutional procurement processes. FDA 510(k) predicate device histories accelerate vendor qualification.
- Home Care:Patients and family caregivers acquire portable systems through durable medical equipment suppliers. Germany's respiratory infrastructure modernization expands regional distribution capacity.
- Rehabilitation Centers:Post-acute facilities bridge hospital discharge and home management with supervised therapy protocols.
- Long-Term Care Facilities:Skilled nursing operations balance labor costs against device automation for resident respiratory maintenance.
Reimbursement density concentrates in Hospitals; margin expansion concentrates in Home Care.
Technology:
Component sophistication tiers separate price-accessible entry points from integrated care platforms.
- Mechanical Devices:Pneumatic or spring-actuated systems without electronic control modules. Price-sensitive procurement in emerging markets sustains manufacturing volume.
- Electronic Devices:Microprocessor-controlled pressure modulation with patient feedback displays. ISO 13485 certification requirements elevate compliance costs for new entrants.
- Smart Technologies:Connected platforms transmit therapy adherence data to clinical dashboards. Remote patient monitoring convergence in the United States enables outcome-based contracting.
- Handheld Devices:Battery-operated portable units for ambulatory secretion management. Cystic fibrosis patient advocacy networks accelerate direct-to-consumer channel development.
Hardware margins concentrate in Electronic Devices; software-enabled services concentrate in Smart Technologies.
Application:
Disease prevalence and progression trajectory determine device specification requirements and replacement frequency.
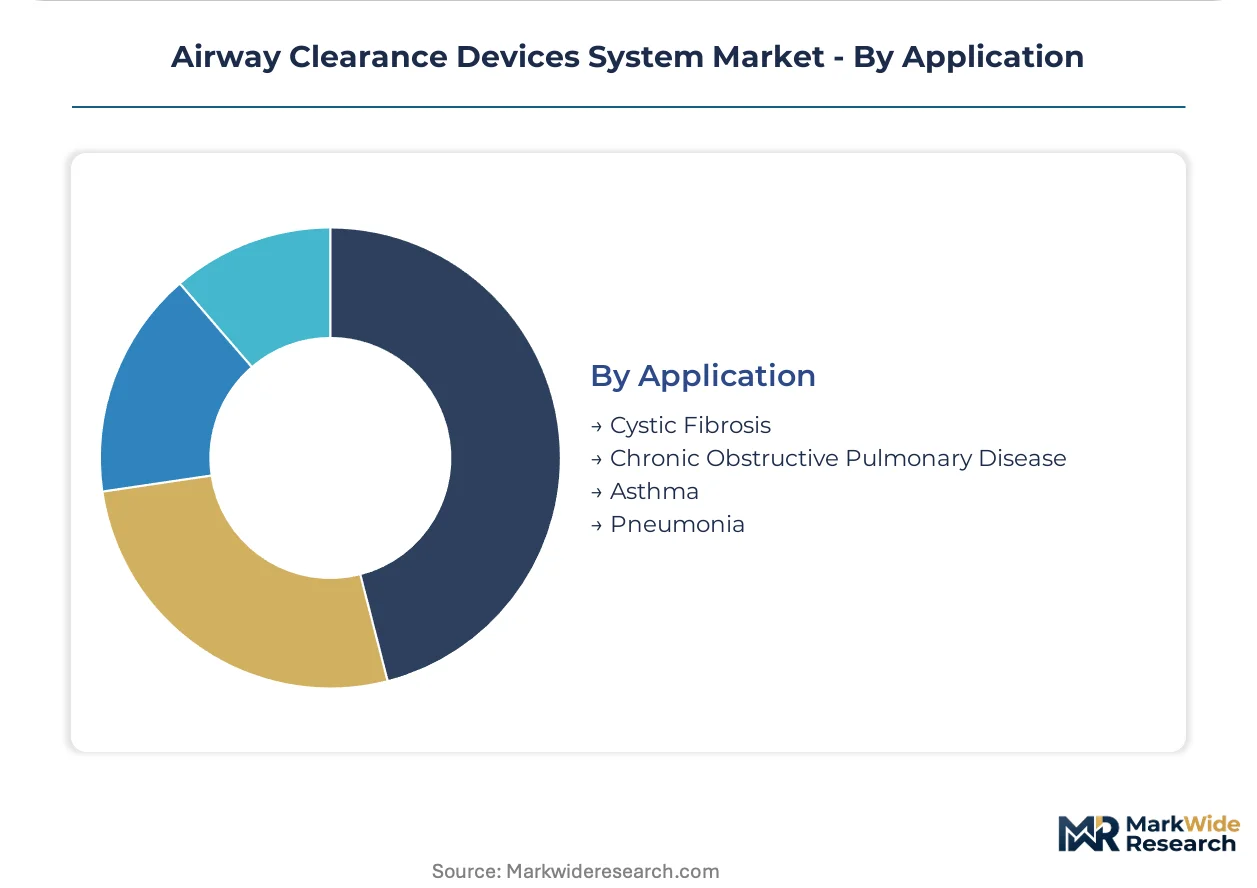
- Cystic Fibrosis:Genetic condition requiring lifelong daily airway clearance from diagnosis through adulthood. Specialized cystic fibrosis centers in the United States and Germany coordinate prescription and training.
- Chronic Obstructive Pulmonary Disease:Progressive airflow limitation driving secretion retention and infection risk. Japan's aging demographics expand the addressable patient pool for home-based management.
- Asthma:Reversible airway obstruction with intermittent clearance needs during exacerbation periods.
- Pneumonia:Acute infection requiring short-term intensive secretion management in hospital settings.
Therapy intensity concentrates in Cystic Fibrosis; volume scaling concentrates in Chronic Obstructive Pulmonary Disease.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) predicate pathways anchor commercialization velocity in the United States, while EU Medical Device Regulation compliance costs reshape competitive positioning across European markets. Germany, Japan, and the United States concentrate manufacturing capacity and procurement density.
United States
Medicare Advantage risk-based reimbursement models incentivize hospitalization avoidance through preventive device deployment. FDA maintains 510(k) clearance pathways for mechanical oscillation systems with established predicate libraries. Minneapolis and Boston medical device clusters host integrated respiratory care R&D operations.
Germany
Respiratory infrastructure modernization drives expanded manufacturing capacity for high-frequency chest wall oscillation systems. EU Medical Device Regulation imposes enhanced clinical evidence requirements for Class IIa and IIb mechanical devices. Stuttgart and Munich anchor precision engineering supply chains for electronic control modules.
Japan
Aging demographics and chronic obstructive pulmonary disease prevalence create underpenetrated demand for home-based secretion management. PMDA oversees device registration with convergence toward international harmonization standards. Osaka and Tokyo metropolitan areas concentrate durable medical equipment distribution networks.
United Kingdom
NHS procurement frameworks prioritize cost-effectiveness in respiratory care device selection for cystic fibrosis centers. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR technical standards. London and Cambridge host connected care platform development for remote patient monitoring integration.
China
Domestic production capacity expansion targets import substitution for electronic airway clearance systems. NMPA medical device registration requirements intensify for foreign manufacturers seeking market access. Shenzhen and Shanghai clusters advance microcontroller and sensor component manufacturing.
Airway Clearance Devices System Market Competitive Environment
Diversified medical technology conglomerates and specialized respiratory device manufacturers split the market into distinct capability tiers. Hospital procurement consolidation favors vendors with established FDA predicate histories and integrated care platform architectures. Three archetypes dominate: cardiac-respiratory portfolio integrators, connected care platform specialists, and standalone oscillation technology pure-plays. Competitive moves concentrate on strategic partnerships for remote monitoring integration and backward integration into sensor supply chains.
Among diversified medical technology conglomerates, Medtronic and Koninklijke Philips N.V. exemplify portfolio breadth spanning acute and post-acute respiratory channels. Hill-Rom occupies a position within the clinical workflow integration archetype, reflecting premium installed-base positioning in North American intensive care settings. PARI GmbH represents specialized European manufacturing heritage in aerosol and secretion management technologies.
| Leading Market Players |
|---|
| Hill-Rom |
| Medtronic |
| Koninklijke Philips N.V. |
| Electromed |
| Vyaire Medical |
| Smiths Medical |
| Baxter |
| PARI GmbH |
| ResMed |
| Others |
Value Chain & Pricing Dynamics
Trans-Pacific container freight corridors linking Shenzhen and Los Angeles transmit semiconductor cost volatility directly into electronic airway clearance device pricing, while concentration of microcontroller sourcing in Taiwan and South Korea amplifies tiered price differentiation between smart-connected and mechanical-only systems.
Pricing Analysis
United States-Germany price spreads of 15-25% separate premium oscillation vests from basic positive expiratory pressure devices, with FDA 510(k) certification tier and embedded sensor density driving differentiation. Cost compression in the mechanical device segment intensifies as Chinese manufacturers expand export capacity. Home care buyers exhibit acute price sensitivity, while hospital procurement committees prioritize clinical workflow integration over unit cost.
Supply Chain Analysis
Medical-grade silicone and precision pressure sensors feed from concentrated manufacturing bases in Germany, Japan, and the United States, with microcontroller fabrication anchored in Taiwan and South Korea. Single-source vulnerability for Bluetooth Low Energy chipsets creates allocation risk during demand surges. Distribution runs through durable medical equipment suppliers in North America and specialized respiratory equipment distributors in Western Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Embedded systems engineering talent scarcity constrains product development velocity, creating acquisition premiums for firms with captive firmware capabilities and ISO 13485 certification histories.
For Market Incumbents: Harden predicate device libraries against emerging competitors by accelerating FDA 510(k) supplement filings for connectivity modules. Secure backward integration into pressure sensor supply through partnerships with Stuttgart-based precision engineering clusters. Channel control through exclusive durable medical equipment distribution agreements defends margin position against direct-to-consumer disintermediation. For New Entrants and Emerging Players: Pursue Japan's underpenetrated home care segment where aging demographics and chronic obstructive pulmonary disease prevalence outpace local manufacturing capacity. Target positive expiratory pressure device categories with simplified regulatory pathways and lower capital requirements. Partner with cystic fibrosis patient advocacy networks for peer-to-peer reimbursement navigation and prescription access. For Investors and Strategic Acquirers: Connected care platform specialists with FDA-cleared remote monitoring integrations and established hospital system partnerships represent priority acquisition targets. Long-term viability hinges on software-enabled service revenue streams displacing hardware margins across the projection horizon. Watch Medicare Advantage risk-based contracting penetration as the inflection signal for outcome-based reimbursement adoption.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Predicate Expansion | Accelerates clearance timelines for oscillation device connectivity modules in United States markets. |
| CE Marking Pathway Investment | EU MDR compliance for Class IIa devices opens German hospital procurement channels. |
| Hospital System Partnership | Integrated clinical workflow positioning secures premium installed-base contracts in intensive care. |
| Software Companion Development | Therapy adherence dashboards enable outcome-based contracting with Medicare Advantage plans. |
| Reimbursement Strategy | Durable medical equipment code anchoring sustains recurring consumable revenue in home care. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA 510(k) databases, EU MDR notified body filings, and hospital procurement contract registries. Primary interviews spanned biomedical engineers at cystic fibrosis centers, GPO contracts managers, and regulatory affairs leads at oscillation device manufacturers. Secondary sources included ISO 13485 certification records, CMS Medicare reimbursement schedules, and customs trade data for respiratory equipment components. Bottom-up patient population modeling triangulates against top-down manufacturer revenue aggregation.
Forecast inputs incorporate disease prevalence trajectories, reimbursement recalibration schedules, and technology substitution elasticities across the analysis window. Segmentation dimensions span product type, end user setting, technology tier, and application indication. CAGRs derive from fitted growth curves calibrated to historical adoption patterns in connected medical devices. Semiconductor allocation constraints and EU MDR implementation timelines feed as scenario variables.
Macroeconomic conditions sit as an overlay; deviation in durable medical equipment reimbursement rates or trans-Pacific logistics costs would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory harmonization and patient self-management behavioral trends. Cross-checking against CMS Medicare Advantage enrollment data and FDA 510(k) clearance velocity metrics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
At-Home Vaginal Ph Test Kit Market
Medical Devices
Saudi Arabia Aesthetic Devices Market
Medical Devices
Medical Connector Market
Medical Devices
Global Foot Orthotic Insoles Market
Medical Devices
North America Intraocular Lens Market
Medical Devices
Global Venous Stents Market
Medical Devices
Ostomy Drainage Systems Market
Medical Devices
North America Surgical Visualization Products Market
Medical Devices
India Respiratory Devices Market
Medical Devices
Europe Ventilator Market
Medical Devices
South America C-Arms Market
Medical Devices
North America Neurostimulation Devices Market
Medical Devices
US Neurothrombectomy Devices Market
Medical Devices
Vascular Screening Devices Market
Medical Devices
Nerve Locator Stimulator Market
Medical Devices
Brain Base Knife Package Market