
 Laser BPH Devices Market | 2026-2036
Laser BPH Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Laser BPH Devices Market Analysis
Buyer concentration is repositioning as ambulatory surgery centers fragment demand away from traditional hospital procurement. Boston Scientific leverages its integrated urology portfolio to control catheter and laser system bundling. Lumenis sustains technology leadership in photoselective vaporization platforms. Olympus anchors hospital sales through endoscope-laser compatibility.
Laser BPH devices deliver precise tissue ablation via fiber-delivered energy at wavelengths between 532 nm and 2013 nm, enabling bloodless prostate resection with minimal thermal spread to adjacent structures. Holmium laser systems occupy the mature core of installed bases with predictable replacement cycles. Thulium laser segments attract fastest-growing interest due to continuous-wave tissue cutting efficiency and reduced operative times. Fiber laser technology dominates new system architecture as solid-state platforms face component sourcing constraints.
FDA 510(k) pathways and EU MDR conformity assessments govern market access timelines for laser BPH systems in the United States and Europe. Japan's PMDA enforces stringent electrical safety and clinical efficacy standards that filter non-specialized entrants. Stakeholders must monitor reimbursement coding shifts for outpatient laser prostate procedures and evolving sterilization validation requirements under updated ISO 13485 frameworks.
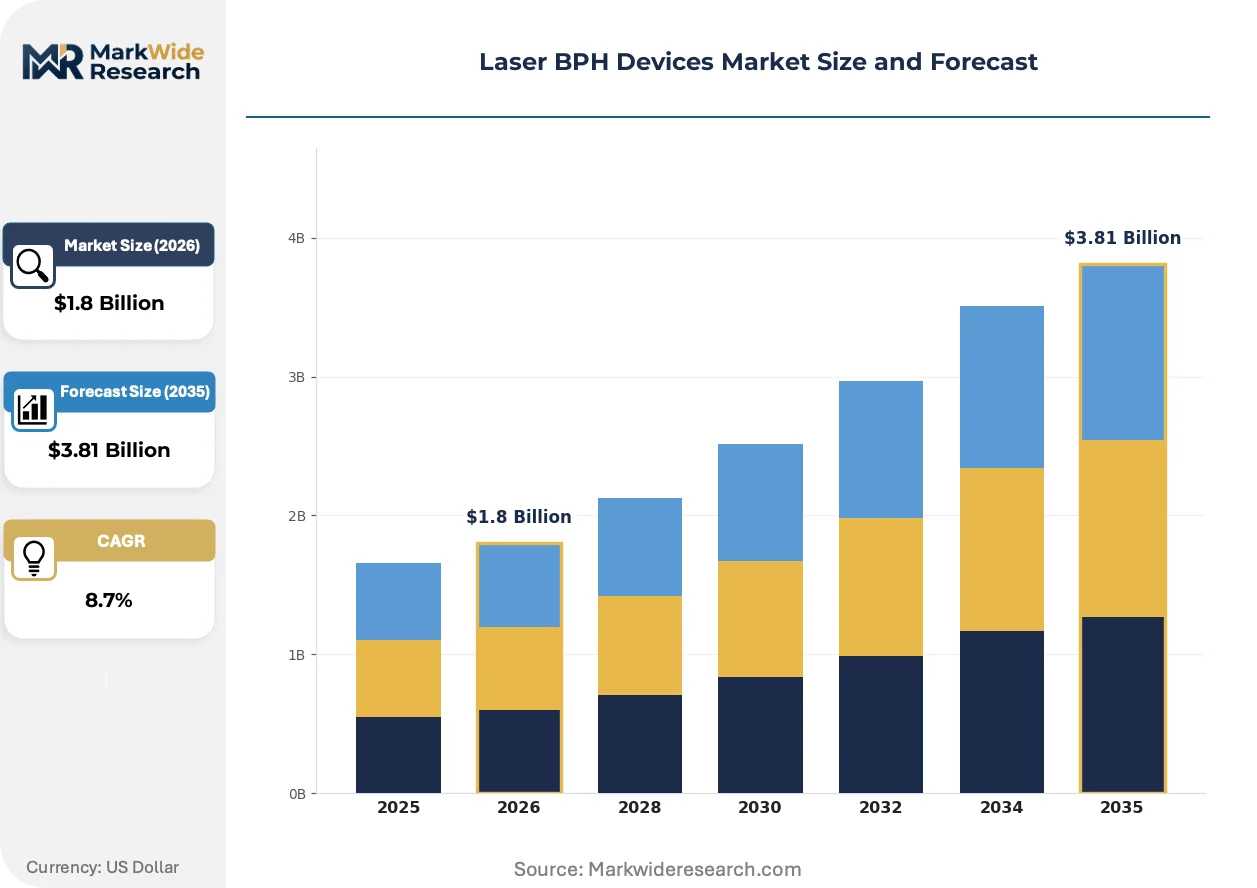
Market Dynamics
Thulium fiber laser systems are compressing procedure times and displacing holmium platforms in ambulatory settings, while EU MDR recertification timelines reshape competitive entry barriers for device manufacturers.
Growth Catalysts
- Aging demographics:Benign prostatic hyperplasia prevalence rises sharply in men over 60 across Japan, Germany, and the United States, expanding addressable patient pools for outpatient laser procedures.
- EU MDR pathway clarity:Streamlined conformity assessment routes for Class IIa laser surgical equipment accelerate CE marking timelines for established manufacturers with robust quality management systems.
- Fiber laser efficiency:Continuous-wave thulium platforms reduce vaporization times by half compared to pulsed holmium systems, enabling higher surgical throughput in clinic-based settings.
Market Restraints
- Input cost volatility:Rare-earth elements for thulium-doped fiber lasers concentrate in Chinese processing facilities, exposing manufacturers to supply disruption and price swings.
- Technical limitation:Tissue penetration depth variability across prostate anatomies limits standardization of energy delivery protocols, complicating training curves for new adopters.
- Regulatory friction:Japan's PMDA electrical safety testing requirements add 18-24 months to market entry timelines compared to FDA 510(k) pathways, filtering smaller competitors.
Strategic Opportunities
- Underpenetrated ambulatory surgery centers:United States freestanding ASCs currently account for under 30 percent of laser BPH volumes, presenting expansion potential as reimbursement codes shift toward outpatient settings.
- Technology convergence:Integration of real-time endoscopic imaging with laser energy delivery systems enables tissue feedback loops that reduce operator dependence and standardize outcomes.
- Distribution innovation:Direct-to-facility leasing models with bundled maintenance contracts lower capital barriers for mid-size urology practices in Germany and Japan.
Industry Challenges
- Specialized technician scarcity:Fiber optic alignment and laser cavity calibration require certified biomedical engineers, with training programs lagging installed base expansion in the United States.
- ISO 13485 sterilization validation:Updated guidance on reusable fiber reprocessing demands extended bioburden testing cycles, compressing gross margins on disposable fiber sales.
- Legacy system interoperability:Hospital IT infrastructure for surgical documentation often lacks HL7 connectivity with laser system data outputs, forcing manual entry workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laser BPH Devices Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Holmium Laser, Photoselective Vaporization Laser, Thulium Laser, Diode Laser End User: Urology Clinics, Hospitals, Ambulatory Surgery Centers, Research Institutions Technology: Fiber Laser, Solid-State Laser, Pulsed Laser, Continuous Wave Laser Application: Prostate Surgery, Tissue Ablation, Laser Lithotripsy, Hemostasis |
| Companies Covered | Boston Scientific, Lumenis, Olympus, Medtronic, Biolitec, Richard Wolf, Stryker, Teleflex, Convergent Laser Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laser BPH Devices Market Emerging Trajectories
Real-time tissue feedback systems and disposable fiber economics are compressing the technology refresh cycle, while regulatory harmonization efforts across North America and Europe reshape competitive positioning.
Thulium fiber laser technology is integrating photoselective vaporization with continuous-wave cutting modes, enabling single-device versatility across ablation and enucleation procedures. Ambulatory surgery centers in the United States and Germany are adopting these platforms at twice the pace of hospital systems due to capital efficiency and space constraints. The technology is integrating surgical workflow standardization by reducing equipment footprint and eliminating the need for separate holmium and greenlight laser systems.
EU MDR Article 10 technical documentation requirements for Class IIa active surgical devices now mandate clinical evaluation reports with post-market surveillance data, extending preparation timelines for new market entrants. Manufacturers with legacy CE certificates under the Medical Devices Directive face compressed transition windows through 2028. European urology clinics are responding by consolidating procurement around established suppliers with notified body relationships and robust quality management systems.
Service unbundling from capital equipment sales is disrupting traditional hospital procurement patterns for laser BPH systems. United States ambulatory surgery centers now favor per-procedure leasing arrangements with maintenance inclusion over outright purchase, compressing vendor cash conversion cycles. This shift is most visible in Texas and Florida metropolitan markets where ASC chains compete aggressively on procedure throughput metrics.
Laser BPH Devices Market Segmentation
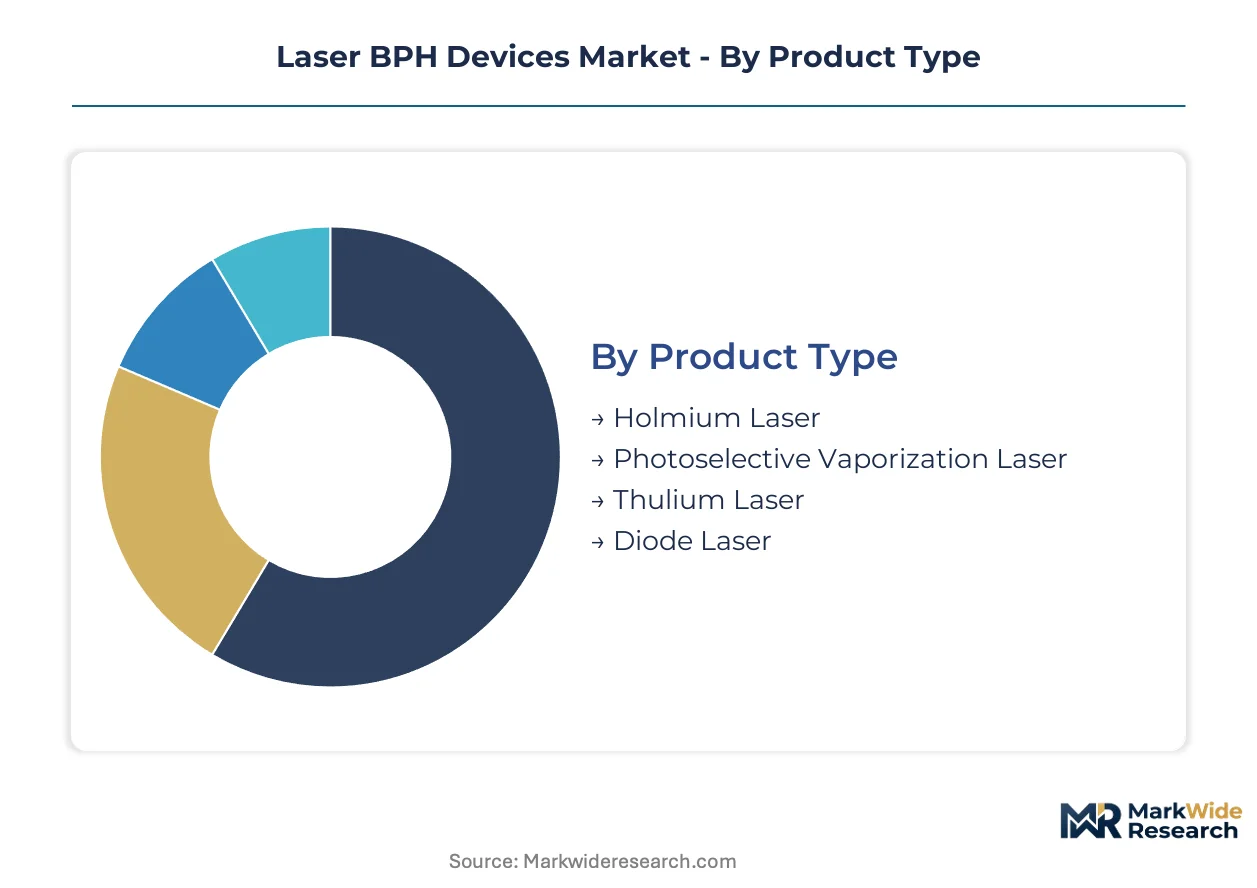
Laser BPH device segmentation reveals distinct procurement patterns across technology platforms and care settings. Product architecture and end-user workflow requirements determine integration depth and capital deployment strategies for manufacturers.
Product Type:
Holmium and thulium platforms anchor hospital installations as standalone capital equipment, while diode and photoselective vaporization systems increasingly embed into compact clinic-based workstations.
- Holmium Laser:Pulsed solid-state systems operating at 2100 nm wavelength deliver precise tissue cutting with minimal thermal spread. Demand concentrates in United States academic medical centers where enucleation training programs require predictable energy delivery. Replacement cycles follow 7-10 year intervals as fiber optic components degrade.
- Thulium Laser:Continuous-wave fiber platforms at 1940 nm enable simultaneous vaporization and cutting without switching devices. German ambulatory surgery centers favor these systems for reduced operative times and single-fiber versatility. Supply constraints in thulium-doped fiber amplifiers limit manufacturing scale-up.
- Photoselective Vaporization Laser:532 nm greenlight systems target high-vascularity tissue with minimal bleeding. Compact diode-pumped configurations suit Japanese urology clinics with space constraints.
- Diode Laser:Lower-cost semiconductor platforms serve secondary procedures and hemostasis applications. Budget-conscious hospital systems in Texas and Florida deploy these for basic vaporization cases.
Volume placements concentrate in holmium platforms; the faster expansion belongs to thulium fiber configurations.
End User:
Procurement authority and reimbursement coding shape demand fragmentation across institutional settings, with capital efficiency driving clinic-level technology choices.
- Urology Clinics:Independent specialty practices in Germany and Japan prioritize compact, multi-modality systems with reduced maintenance requirements. Leasing arrangements with per-procedure billing dominate procurement.
- Hospitals:Integrated delivery networks in the United States bundle laser systems with endoscope service contracts. Operating room scheduling constraints favor faster procedure platforms.
- Ambulatory Surgery Centers:Freestanding facilities in Texas metropolitan markets exploit outpatient reimbursement differentials. Space optimization demands smaller equipment footprints.
- Research Institutions:Academic medical centers in Japan pursue experimental wavelength combinations for tissue interaction studies. Funding cycles align with grant award timelines.
Hospital systems retain the largest installed base; ambulatory surgery centers are climbing the fastest in annual procurement growth.
Technology:
Beam delivery architecture determines thermal precision, maintenance burden, and compatibility with existing surgical visualization systems.
- Fiber Laser:Doped silica fiber configurations enable flexible beam delivery through reusable or disposable handpieces. Thulium-doped variants dominate new system development for prostate applications.
- Solid-State Laser:Crystalline gain media in holmium and Nd:YAG platforms deliver high pulse energies for enucleation. Component sourcing constraints affect replacement part availability.
- Pulsed Laser:Q-switched or mode-locked operation creates discrete energy packets for controlled tissue ablation. Peak power requirements stress fiber optic connectors.
- Continuous Wave Laser:Uninterrupted emission enables smooth cutting with reduced charring. Thulium platforms exploit this mode for faster vaporization speeds.
Continuous wave configurations gain share fastest in new installations; pulsed systems defend position in established hospital bases.
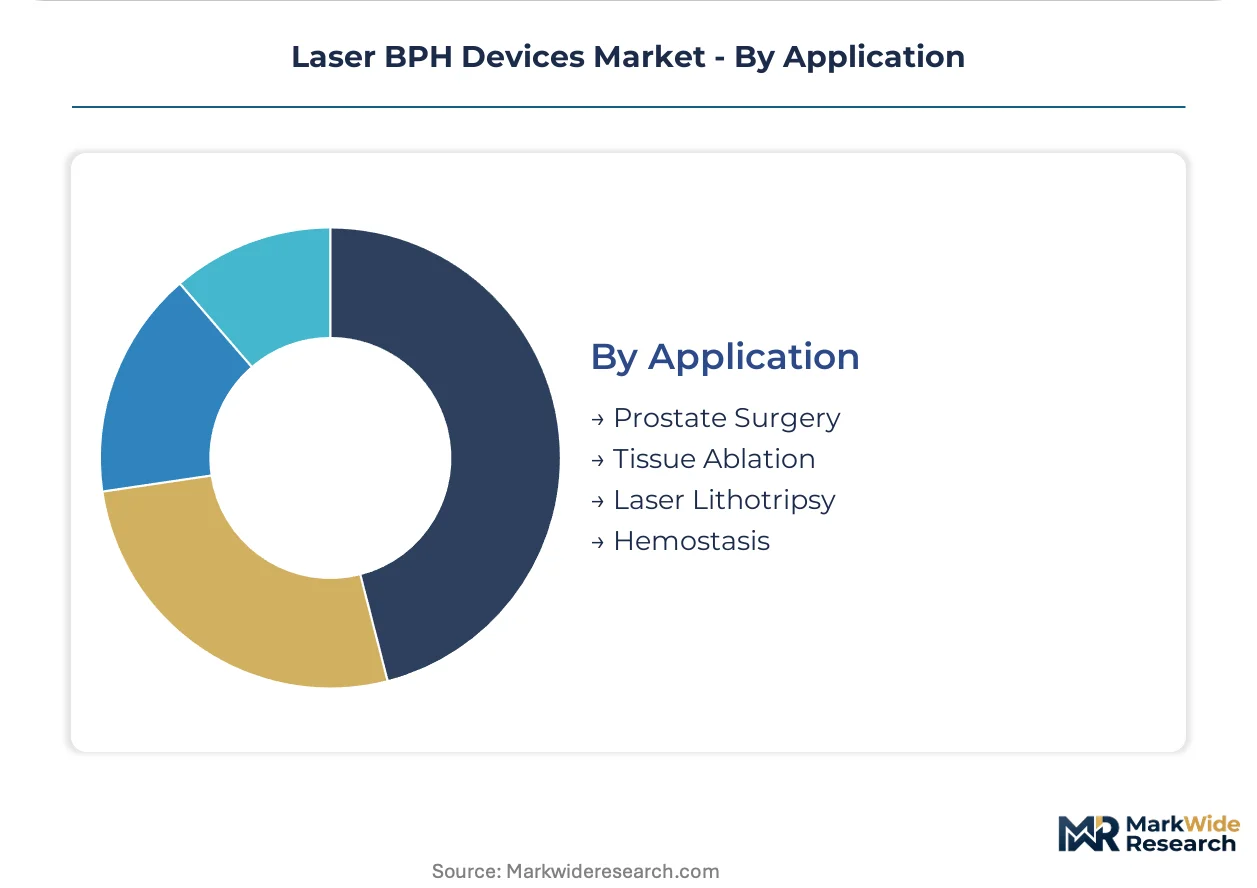
Application:
Clinical indication determines energy parameter selection, fiber choice, and postoperative monitoring protocols across procedural categories.
- Prostate Surgery:Transurethral vaporization and enucleation procedures constitute the core revenue driver for laser BPH manufacturers. United States urology clinics report higher patient throughput with thulium platforms.
- Tissue Ablation:Precise thermal destruction targets obstructive prostate tissue while preserving continence mechanisms. German hospitals emphasize nerve-sparing techniques.
- Laser Lithotripsy:Holmium systems fragment urinary calculi during combined procedures. Dual-application utilization improves capital equipment ROI.
- Hemostasis:Coagulation modes manage bleeding during open or endoscopic surgery. Lower-power diode configurations suffice for this indication.
Prostate surgery commands the dominant procedure volume; tissue ablation applications show steepest expansion trajectory in ambulatory settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for laser BPH devices concentrates in three specific countries where aging male populations and established reimbursement pathways for outpatient urology procedures intersect. Germany, Japan, and the United States collectively absorb the majority of thulium and holmium laser system placements, with ambulatory surgery centers in Texas and Bavaria driving fastest procurement growth.
United States
Freestanding ambulatory surgery centers in Texas and Florida metropolitan markets exploit favorable outpatient reimbursement coding for laser prostate procedures. FDA 510(k) clearance pathways enable faster commercialization timelines than Japanese or European equivalents, attracting initial product launches. Hospital systems in the Northeast corridor bundle laser acquisitions with endoscope service contracts, consolidating vendor relationships around integrated urology portfolios.
Germany
Bavarian and North Rhine-Westphalian urology clinics prioritize thulium fiber laser platforms for reduced operative times and single-device versatility across vaporization and enucleation. EU MDR conformity assessment requirements under Article 10 extend preparation timelines for new market entrants, favoring established manufacturers with notified body relationships. Stuttgart and Munich medical device clusters host service infrastructure supporting rapid technician deployment for laser cavity calibration.
Japan
PMDA electrical safety and clinical efficacy standards add 18-24 months to market entry timelines compared to FDA pathways, filtering non-specialized competitors from the Japanese market. Tokyo and Osaka metropolitan urology clinics favor compact greenlight laser configurations addressing space constraints in high-density clinical settings. METI industrial policy supports domestic manufacturing of fiber optic components for surgical laser systems.
United Kingdom
NHS England specialized commissioning frameworks for benign prostatic hyperplasia procedures concentrate laser system procurement within designated urology centers of excellence. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR technical standards while streamlining conformity assessment for devices with existing CE marking. London and Manchester academic medical centers pursue experimental wavelength combinations for tissue interaction studies.
Laser BPH Devices Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue ambulatory-focused platform miniaturization and service unbundling. The vendor base stratifies across three maturity tiers: integrated medical technology conglomerates with urology portfolios, specialized laser surgical equipment manufacturers, and regional distributors with technical service capabilities. Competitive dynamics center on fiber laser technology licensing, per-procedure leasing model expansion, and M&A targeting ambulatory surgery center channel access.
Within the integrated conglomerate tier, Boston Scientific and Olympus occupy positions exemplifying endoscope-laser bundling strategies and hospital procurement consolidation. Lumenis represents specialized laser surgical equipment manufacturers sustaining technology leadership in photoselective vaporization platforms. These three companies anchor competitive positioning through differentiated approaches to fiber delivery architecture and ambulatory workflow integration.
| Leading Market Players |
|---|
| Boston Scientific |
| Lumenis |
| Olympus |
| Medtronic |
| Biolitec |
| Richard Wolf |
| Stryker |
| Teleflex |
| Convergent Laser Technologies |
| Others |
Supply Flow & Price Mechanics
Certified biomedical engineers concentrated in Stuttgart and Munich medical device clusters command wage premiums that compress pricing spreads between premium thulium fiber systems and standard holmium platforms. Labor-cost differentials across German service hubs versus Asian manufacturing centers feed directly into tiered equipment pricing, with thulium-doped fiber amplifier scarcity amplifying margin pressure on mid-range configurations.
Pricing Analysis
High-volume placements of holmium systems in United States academic medical centers trade margin for installed base retention, while thulium fiber platforms in German ambulatory surgery centers capture premium pricing through reduced operative time value propositions. Price differentiation hinges on FDA 510(k) clearance tier versus EU MDR Class IIa certification level, with after-sales service bundling widening spreads. Pricing pressure stems from rare-earth element cost volatility in Chinese processing facilities. Budget-conscious hospital systems in Texas and Florida exhibit highest price sensitivity; integrated delivery networks in the Northeast corridor show lowest.
Supply Chain Analysis
ISO 13485 sterilization validation requirements and EU MDR Article 10 technical documentation gating filter component suppliers, concentrating qualified fiber optic manufacturers in Germany, Japan, and the United States. Thulium-doped fiber amplifiers, precision laser diodes, and reusable fiber handpieces constitute critical input dependencies. Single-source vulnerability in Chinese rare-earth element processing exposes manufacturers to disruption. Distribution runs through authorized dealer networks with biomedical engineer certification requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thulium-doped fiber amplifier manufacturing capacity constraints prop pricing power for qualified suppliers, positioning this market as supply-constrained rather than demand-limited.
For Market Incumbents: To counter displacement by ambulatory-focused platform miniaturization, Boston Scientific and Lumenis should deepen backward integration into fiber laser component supply and secure exclusive thulium fiber sourcing agreements with German and Japanese specialty manufacturers. Hospital procurement consolidation demands integrated endoscope-laser service contracts with GPOs. For New Entrants and Emerging Players: Enter via per-procedure leasing arrangements targeting United States freestanding ambulatory surgery centers in Texas and Florida, where outpatient reimbursement differentials create white-space demand for compact multi-modality systems. White-space concentration sits with mid-size urology practices seeking capital efficiency. For Investors and Strategic Acquirers: Re-rating potential sits with specialized laser surgical equipment manufacturers possessing EU MDR notified body relationships and thulium fiber technology licenses, given regulatory harmonization catalysts compressing competitive entry timelines. Long-term viability favors targets with ambulatory surgery center channel access and disposable fiber economics. Signal to monitor: shifts in CMS reimbursement coding for outpatient laser prostate procedures.| Strategic Initiative | Industry Significance |
|---|---|
| Thulium Fiber Technology Licensing | Secures continuous-wave platform advantages for German ambulatory surgery center penetration. |
| EU MDR Class IIa Certification Pathway | Accelerates CE marking timelines through notified body relationships in Stuttgart clusters. |
| Ambulatory Surgery Center Partnership | Locks per-procedure leasing demand in Texas and Florida metropolitan markets. |
| Disposable Fiber Economics Development | Compresses technology refresh cycles while navigating ISO 13485 sterilization validation. |
| Reimbursement Strategy Alignment | Captures CMS outpatient coding shifts favoring clinic-based laser prostate procedures. |
Methodological Framework
Multi-period observation of thulium fiber laser adoption rates, ambulatory surgery center procurement patterns, and EU MDR certification timelines anchored the trend analysis, supplemented by interviews with urology clinic directors, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Secondary validation drew from FDA 510(k) filings, EU MDR Article 10 technical documentation, hospital procurement databases, and CMS reimbursement coding updates. Bottom-up equipment placement estimates triangulated against top-down market sizing.
Input-output matrices mapped laser system shipments to end-user segments across the projection horizon, modeling technology platform, care setting, and geographic regulatory cluster dimensions. CAGRs derived from fitted growth curves applied to installed base replacement cycles and ambulatory expansion trajectories. Forecast inputs incorporated thulium-doped fiber amplifier supply constraints and PMDA electrical safety testing duration differentials.
Revisions become necessary when rare-earth element supply disruptions, EU MDR recertification deadline extensions, or CMS reimbursement coding eliminations materialize. Forecasts reflect documented assumptions on ambulatory surgery center penetration rates and fiber laser efficiency improvements. A model refresh is warranted upon material change in Japanese PMDA regulatory timelines or thulium fiber manufacturing capacity expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
North America Portable Medical and Healthcare Devices Market
Medical Devices
Global Large Volume Wearable Injectors Market
Medical Devices
Global Metal Implants and Medical Alloys Market
Medical Devices
Global Ultrasound Devices Market
Medical Devices
Dosing Units Market
Medical Devices
US Thrombectomy Devices Market
Medical Devices
Capnography Devices Market
Medical Devices
Neonatal & Preterm Infant Enteral Feeding Devices Market
Medical Devices
Nasal Implant Market
Medical Devices
Tissue Embedding Center Market
Medical Devices
Global Patient-Controlled Analgesic Pumps Market
Medical Devices
Transplant Monitoring Kits Market
Medical Devices
Europe Ablation Technologies Market
Medical Devices
Infant Radiant Warmer Market
Medical Devices
Oxygen Concentrators Market
Medical Devices
Photopheresis Products Market