
 Life Science and Chemical Instruments Market | 2026-2036
Life Science and Chemical Instruments Market Size, Share, and Industry Trends Forecast 2026-2036
Life Science and Chemical Instruments Market Foresight
A widening capability gap between full-platform conglomerates and point-solution specialists is reorganizing competitive dynamics in analytical instrumentation. Thermo Fisher Scientific leverages its captive consumables stream to lock in multi-year service contracts across proteomics workflows. Danaher Corporation anchors its position through diagnostic-leaning automation that reduces wet-lab headcount for pharmaceutical clients. Bruker Corporation differentiates via high-field NMR systems that command premium placement at structural biology core facilities.
Life science and chemical instruments encompass precision measurement systems designed to identify, quantify, and characterize molecular and cellular structures, typically operating at detection thresholds of parts-per-billion or single-molecule resolution for regulatory-compliant decision-making. Chromatography systems constitute the largest installed base, though mass spectrometers capture disproportionate margin pools due to software-locked consumables and qualification-dependent service revenue. Spectrophotometry maintains steady replacement demand from quality assurance laboratories, while microscopy accelerates fastest as cryo-EM and super-resolution modalities displace electron microscopy in structural drug discovery pipelines.
FDA 21 CFR Part 11 and EU MDR frame data integrity and traceability requirements that render pre-2015 software architectures commercially obsolete. EPA methods and REACH compliance specifications dictate detector sensitivity thresholds and validation protocols for environmental and materials testing applications. Stakeholders must weigh captive platform economics against modular best-of-breed architectures as artificial intelligence reshapes instrument control and autonomous method optimization.
Market Dynamics
Artificial intelligence is fragmenting analytical instrument architectures, forcing vendors to choose between monolithic software stacks and modular API-first platforms that accommodate third-party algorithmic workflows.
Growth Catalysts
- Biologics manufacturing expansion:Cell and gene therapy production lines in Massachusetts and North Rhine-Westphalia require real-time mass spectrometry monitoring for critical quality attributes. FDA process analytical technology guidance accelerates inline sensor deployment.
- EU MDR data integrity mandates:Medical device manufacturers must replace legacy chromatography data systems with compliant electronic records. Replacement cycles compress from seven years to four years for qualifying laboratories.
- Precision medicine infrastructure:Proteomics and metabolomics core facilities at academic medical centers in Singapore, Switzerland, and the United States deploy high-resolution mass spectrometry for patient stratification biomarker discovery.
Market Restraints
- Helium supply concentration:Gas chromatography-mass spectrometry systems depend on helium sourced primarily from Qatar and the United States federal reserve. Price volatility and allocation restrictions constrain field deployment.
- High-field magnet manufacturing bottleneck:Superconducting niobium-titanium wire production concentrates at a single Japanese supplier. NMR system lead times extend to eighteen months.
- Qualified personnel scarcity:Mass spectrometry method development requires hybrid analytical chemistry and software engineering skills. University programs produce insufficient graduates for industrial demand.
Strategic Opportunities
- India's pharmaceutical quality upgrade:CDSCO's revised schedule M guidelines and export-oriented unit certification drive replacement of aging UV-Vis and HPLC systems in Hyderabad and Ahmedabad manufacturing clusters.
- AI-native instrument control convergence:Machine learning method optimization combines with cloud-based data lakes to enable autonomous method development. Early deployments appear at agricultural chemistry screening laboratories.
- Service contract unbundling:Third-party qualification and calibration providers capture maintenance revenue from pharmaceutical quality assurance departments seeking cost transparency.
Industry Challenges
- 21 CFR Part 11 software validation timelines:Pharmaceutical buyers require six to twelve months for computerized system validation. Vendor release cycles compress faster than customer qualification capacity.
- Multi-vendor data format interoperability:Chromatography data systems from different suppliers use proprietary file structures. Laboratory information management system integration demands custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Life Science and Chemical Instruments Market |
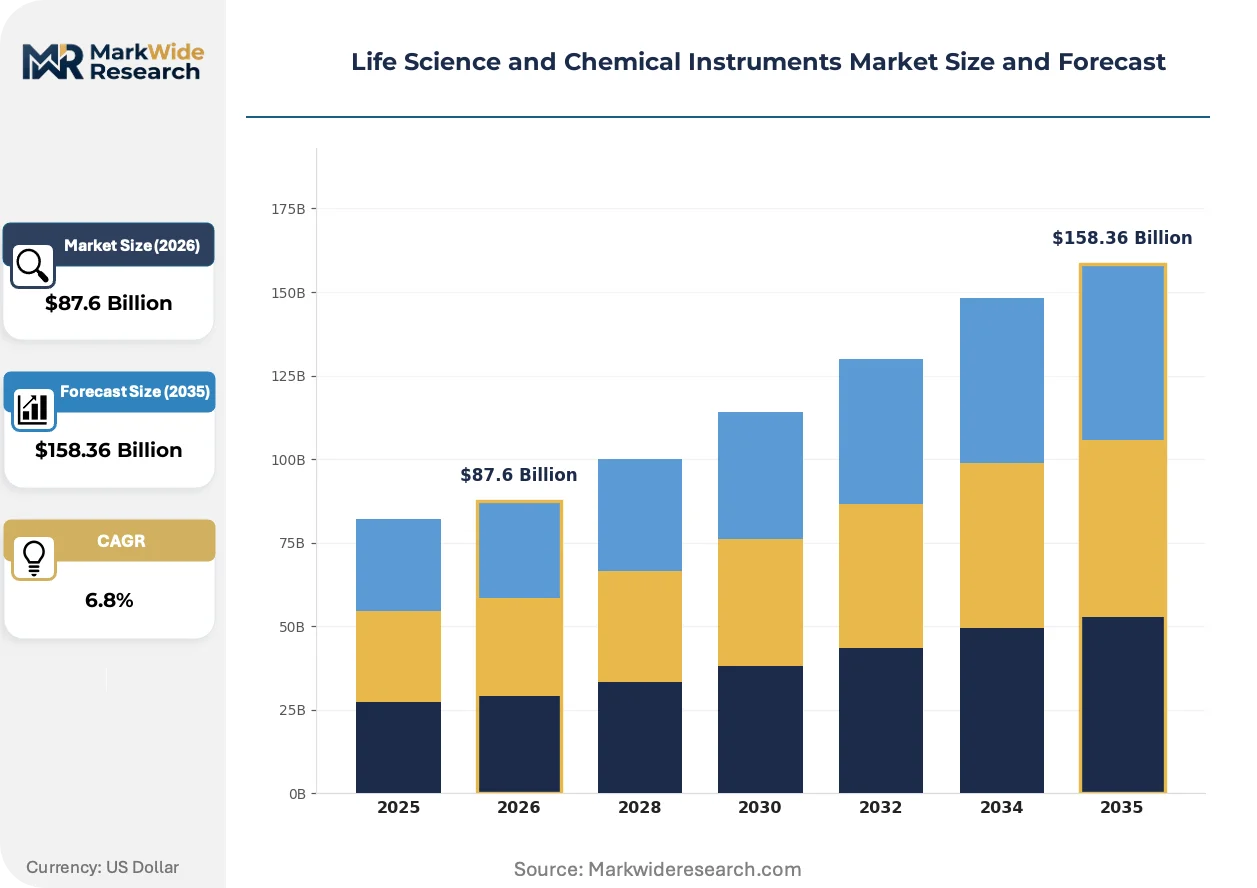
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $158.36 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chromatography Systems, Mass Spectrometers, Spectrophotometers, Microscopes Application: Biotechnology, Pharmaceutical Development, Quality Control, Environmental Testing Technology: Liquid Chromatography, Gas Chromatography, Fluorescence, Nuclear Magnetic Resonance End User: Research Laboratories, Pharmaceutical Companies, Educational Institutions, Quality Assurance Laboratories |
| Companies Covered | Thermo Fisher Scientific, Danaher Corporation, Agilent Technologies, Shimadzu Corporation, Waters Corporation, Bruker Corporation, PerkinElmer, Bio-Rad Laboratories, Becton Dickinson and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Life Science and Chemical Instruments Market Shifts & Advancements
Computational methods are redistributing value from hardware performance specifications to software-enabled analytical decision-making, compressing traditional instrument replacement cycles and elevating data infrastructure investments.
Cryogenic electron microscopy is fragmenting structural biology workflows. Academic drug discovery centers and contract research organizations in Boston and Cambridge, United Kingdom adopt single-particle analysis for membrane protein target validation. The technology is fragmenting demand between dedicated core facilities and distributed benchtop installations, eroding the centralized service model that dominated electron microscopy for decades.
REACH substance restriction amendments tighten detection thresholds for persistent organic pollutants in environmental testing laboratories. Germany's Federal Environment Agency and France's ANSES coordinate reference method updates that mandate tandem mass spectrometry for regulatory compliance. Contract environmental laboratories in the Rhine-Ruhr and Paris regions accelerate quadrupole-time-of-flight system procurement to maintain accreditation.
Pharmaceutical procurement departments now unbundle instrument capital expenditure from multi-year service and consumables commitments. Large molecule manufacturers in Research Triangle Park and Basel negotiate platform-agnostic reagent supply contracts separately from hardware acquisition. The unbundling trend concentrates in North American and European biopharma clusters where procurement organizations have matured category management functions.
Life Science and Chemical Instruments Market Segmentation
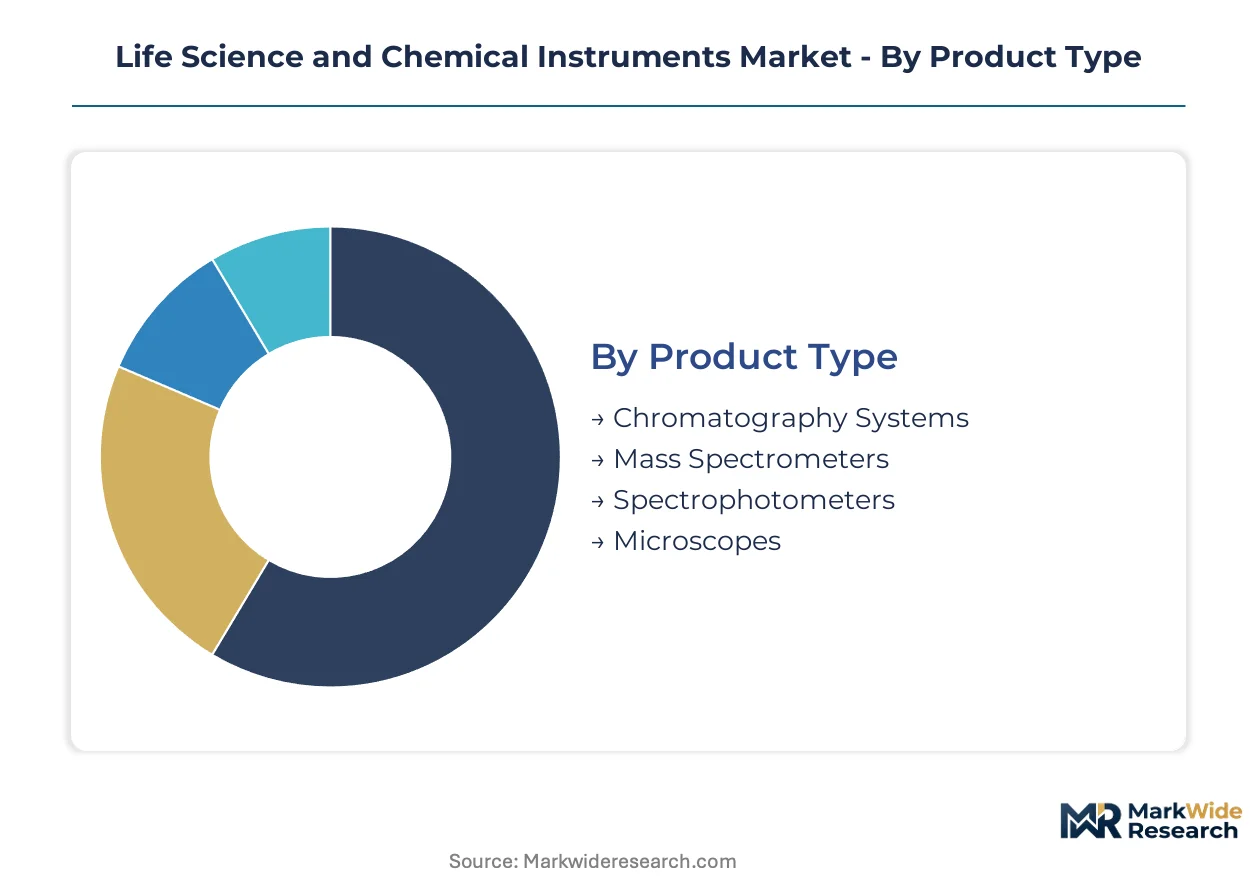
Life science and chemical instruments serve heterogeneous decision-makers with divergent technical specifications and procurement workflows. Segmentation reveals how channel strategies must adapt to the validation rigor of pharmaceutical quality control versus the experimental flexibility demanded by academic research laboratories.
Product Type:
Direct sales teams handle high-attachment-rate platforms while distribution partners manage standardized benchtop systems for smaller laboratories.
- Chromatography Systems:These separation platforms employ stationary and mobile phases to isolate complex mixtures with parts-per-billion resolution. Pharmaceutical quality control departments in Basel and Research Triangle Park deploy ultra-high-performance liquid chromatography for impurity profiling under FDA 21 CFR Part 11 mandates.
- Mass Spectrometers:Ionization and mass-to-charge detection systems enable molecular identification through fragmentation pattern analysis. Proteomics core facilities at Singapore's academic medical centers and Swiss precision medicine initiatives drive demand for high-resolution Orbitrap configurations.
- Spectrophotometers:UV-Vis and infrared absorption instruments support routine quantitative analysis in quality assurance settings.
- Microscopes:Optical and electron beam imaging systems span basic cellular visualization through cryo-EM structural biology.
Chromatography systems dominate installed base. Mass spectrometers are where expansion concentrates.
Application:
Cost tiers separate validated GMP environments from exploratory R&D settings with lower compliance overhead.
- Biotechnology:Cell and gene therapy manufacturing workflows demand real-time analytical monitoring for critical quality attributes. Massachusetts biologics clusters deploy inline mass spectrometry sensors under FDA process analytical technology guidance to accelerate batch release decisions.
- Pharmaceutical Development:Small molecule and biologic candidate characterization requires multi-modal analytical confirmation. Large molecule manufacturers in North Rhine-Westphalia integrate chromatography-mass spectrometry platforms for forced degradation studies and stability protocol design.
- Quality Control:Release testing and raw material verification laboratories operate under strict method transfer and qualification requirements.
- Environmental Testing:Contract laboratories monitor persistent organic pollutants under REACH substance restriction amendments.
Pharmaceutical development commands premium pricing. Biotechnology is climbing the fastest.
Technology:
Volume concentration favors established separation methods while emerging detection modalities capture disproportionate margin expansion.
- Liquid Chromatography:Reverse-phase and size-exclusion separations resolve biomolecules and small molecule APIs with reproducible retention time precision. Hyderabad and Ahmedabad pharmaceutical manufacturing clusters in India upgrade aging HPLC systems under CDSCO revised Schedule M guidelines for export-oriented unit certification.
- Gas Chromatography:Volatile and semi-volatile compound analysis depends on helium carrier gas supply chains concentrated in Qatar and United States federal reserves.
- Fluorescence:Excitation-emission detection enables high-sensitivity quantification of labeled biomolecules in screening applications.
- Nuclear Magnetic Resonance:Superconducting magnet systems require niobium-titanium wire from concentrated Japanese supply sources.
Liquid chromatography dominates installed base. Mass spectrometry detection is gaining share fastest.
End User:
Customer type determines service contract structure and software validation support intensity.
- Research Laboratories:Academic and government facilities prioritize methodological flexibility and grant-funded capital acquisition. Structural biology core facilities at Boston and Cambridge, United Kingdom drug discovery centers deploy cryo-EM for membrane protein target validation.
- Pharmaceutical Companies:Commercial manufacturing organizations require qualified systems with documented computerized system validation. European medical device manufacturers replace legacy chromatography data systems under EU MDR electronic records mandates.
- Educational Institutions:Undergraduate training programs demand robust, low-maintenance instrumentation for teaching laboratories.
- Quality Assurance Laboratories:Third-party testing providers seek unbundled service contracts for cost transparency.
Pharmaceutical companies anchor revenue concentration. Research laboratories are where technology adoption accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German precision manufacturing clusters while Indian pharmaceutical hubs compete on volume throughput. The United States captures premium margins through biologics manufacturing density. Japan maintains technological leadership in superconducting magnet fabrication.
United States
Massachusetts biologics clusters and Research Triangle Park pharmaceutical corridors drive demand for inline mass spectrometry sensors. FDA process analytical technology guidance accelerates real-time monitoring deployment for cell and gene therapy production. Boston-area structural biology core facilities adopt cryo-EM systems for membrane protein target validation.
Germany
North Rhine-Westphalia pharmaceutical manufacturing and Rhine-Ruhr environmental testing laboratories anchor European instrument demand. REACH substance restriction amendments and EU MDR data integrity mandates force replacement of legacy chromatography systems. Heidelberg and Munich precision medicine initiatives deploy high-resolution mass spectrometry for patient stratification biomarker discovery.
India
Hyderabad and Ahmedabad pharmaceutical manufacturing clusters upgrade aging analytical infrastructure under CDSCO revised Schedule M guidelines. Export-oriented unit certification drives replacement of UV-Vis and HPLC systems for European and North American market access. Domestic biologics manufacturing expansion creates demand for compliant electronic records systems.
Japan
Superconducting niobium-titanium wire production concentrates at Japanese suppliers, creating eighteen-month lead times for high-field NMR systems. METI industrial policy supports domestic analytical instrument manufacturing for semiconductor and materials science applications. Osaka and Nagoya pharmaceutical corridors maintain steady replacement demand for spectrophotometry and chromatography platforms.
Switzerland
Basel large molecule manufacturers negotiate platform-agnostic reagent supply contracts separately from hardware acquisition. Swissmedic regulatory requirements and precision medicine infrastructure investments drive proteomics core facility expansion. Zurich and Geneva academic medical centers deploy Orbitrap configurations for metabolomics research.
Life Science and Chemical Instruments Market Competitive Landscape
Concentration sits with full-platform conglomerates that bundle hardware, consumables, and multi-year service contracts. Three to five integrated players capture the majority of pharmaceutical quality control spending. Strategic archetypes include captive consumables stream operators, diagnostic-leaning automation specialists, and high-field magnetic resonance premium vendors. Competitive moves center on software-locked consumables ecosystems and autonomous method optimization capabilities.
Within the integrated conglomerate tier, Thermo Fisher Scientific and Danaher Corporation exemplify platform bundling strategies that lock in pharmaceutical manufacturing clients. Bruker Corporation occupies a position among high-field system specialists commanding premium placement at structural biology core facilities. These three anchors demonstrate how competitive positioning fragments between consumables-captive economics and best-of-breed performance specifications.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Danaher Corporation |
| Agilent Technologies |
| Shimadzu Corporation |
| Waters Corporation |
| Bruker Corporation |
| PerkinElmer |
| Bio-Rad Laboratories |
| Becton Dickinson and Company |
| Others |
Supply & Pricing Matrix
Eighteen-month lead times for superconducting niobium-titanium wire concentrate pricing power at Japanese magnet manufacturers while helium allocation restrictions from Qatar and United States federal reserves compress margins for gas chromatography system vendors. Pharmaceutical procurement departments exploit this supply rigidity by unbundling hardware capital expenditure from multi-year consumables and service commitments.
Pricing Analysis
Configured-to-order pricing for high-field NMR systems commands a 40-60% premium over standard liquid chromatography platforms due to superconducting magnet customization and site-specific installation requirements. Pricing stratifies across premium, standard, and economy tiers based on software validation tier (FDA 21 CFR Part 11 compliant vs. research-grade) and consumables lock-in intensity. Cost compression in mid-tier chromatography is intensifying because Indian pharmaceutical clusters negotiate platform-agnostic reagent supply contracts separately from hardware acquisition. Academic research laboratories exhibit the highest price sensitivity, while commercial biologics manufacturers prioritize qualification speed over capital cost.
Supply Chain Analysis
Superconducting niobium-titanium wire production concentrates at a single Japanese supplier, creating eighteen-month lead times that constrain high-field NMR system deployment. Helium for gas chromatography-mass spectrometry draws from Qatar extraction and United States federal reserve allocation, while precision optical components for mass spectrometry ionization sources rest on German and Swiss manufacturing clusters. Single-source vulnerability in superconducting magnet feedstock exposes vendors to production bottlenecks. Distribution runs through direct sales teams for high-attachment-rate platforms and authorized distribution partners for standardized benchtop systems serving smaller laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
AI-native method optimization is fragmenting analytical instrument architectures, creating white-space opportunities for modular platform specialists between full-conglomerate bundlers and point-solution vendors.
For Market Incumbents: Fortify consumables-captive economics by deepening software-locked reagent ecosystems around proteomics and metabolomics workflows. Expand qualification and validation service capacity to match compressed EU MDR replacement cycles, as pharmaceutical buyers now unbundle hardware from multi-year support commitments. Prioritize backward integration into superconducting wire supply through long-term offtake agreements with Japanese magnet manufacturers. For New Entrants and Emerging Players: Cloud-native laboratory information management system integration addresses a service-layer gap where legacy chromatography data systems impose proprietary file format lock-in. Target Indian pharmaceutical manufacturing clusters in Hyderabad and Ahmedabad where CDSCO Schedule M compliance upgrades drive replacement demand for aging UV-Vis and HPLC infrastructure. Lead with API-first instrument control platforms that accommodate third-party AI algorithmic workflows. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-connected instrument segments as software subscriptions displace capital-heavy hardware refresh cycles. Long-term viability favors acquisition targets with recurring revenue density above 60% of total sales and established FDA 21 CFR Part 11 validation documentation. Watch for inflection when pharmaceutical procurement departments achieve mature category management functions capable of enforcing platform-agnostic reagent sourcing.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Native Instrument Control Development | Machine learning method optimization enables autonomous analytical workflows at agricultural chemistry screening laboratories. |
| Consumables Ecosystem Lock-In | Software-locked reagent streams secure multi-year service contracts across proteomics core facilities at Singapore academic medical centers. |
| Third-Party Qualification Service Expansion | Unbundled calibration and validation providers capture maintenance revenue from pharmaceutical quality assurance departments seeking cost transparency. |
| Superconducting Magnet Supply Securement | Long-term niobium-titanium wire offtake agreements reduce eighteen-month lead times for high-field NMR system delivery. |
| Cloud-Connected Data Infrastructure Investment | Cloud-based data lakes enable autonomous method development and remote instrument diagnostics for distributed laboratory networks. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with analytical instrumentation product managers, pharmaceutical quality control directors, proteomics core facility heads, regulatory affairs specialists at CDSCO and FDA, and third-party instrument qualification service providers. Secondary validation drew from FDA 21 CFR Part 11 guidance documents, EU MDR implementation notices, ECHA REACH substance restriction amendments, SEC 10-K instrument manufacturer filings, and academic medical center procurement records. Bottom-up segment sizing triangulated against top-down market aggregation across chromatography, mass spectrometry, spectrophotometry, and microscopy product categories.
Across the analysis window, the forecasting framework modeled demand trajectories by technology type (liquid chromatography, gas chromatography, mass spectrometry detection, NMR, microscopy), application segment (biotechnology manufacturing, pharmaceutical development, quality control, environmental testing), and end-user archetype (research laboratories, commercial manufacturers, contract testing organizations). CAGRs were derived from regression analysis of historical replacement cycle compression and regulatory mandate acceleration, incorporating helium supply volatility indices and superconducting magnet production capacity constraints as industry-specific inputs.
Forecasts assume regulatory continuity in FDA 21 CFR Part 11 and EU MDR data integrity regimes; material policy shifts in electronic records validation requirements or REACH detection threshold amendments would require re-modeling. Scenario readiness is essential as AI-native instrument control standards and cloud data residency regulations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Non- Resorbable Cranial Fixation System Market
Medical Devices
Electronic Pediatric Nebulizer Market
Medical Devices
Sacroiliac Joint Fusion Market
Medical Devices
Global Non-Surgical Skin Tightening Devices Market
Medical Devices
Anti-Snore Device Market
Medical Devices
Global Patient Warming Systems Market
Medical Devices
Global External Fixators Market
Medical Devices
Intraocular Lens (IOL) Market
Medical Devices
Continuous Passive Motion Devices Market
Medical Devices
Surgical Robot Accessories Market
Medical Devices
Posture Correction Market
Medical Devices
Ultrasonic Medical Nebulizer Market
Medical Devices
Insulin Storage Devices Market
Medical Devices
Ophthalmic Ultrasound Devices Market
Medical Devices
Engine-Driven Endodontic File Market
Medical Devices
Micro Syringes Market