
 China Laser Hair Removal Market | 2026-2036
China Laser Hair Removal Market Size, Share, and Industry Trends Forecast 2026-2036
China Laser Hair Removal Market Insights
Medical aesthetic clinics is restructuring the China laser hair removal landscape as dermatology centers and upscale spas reduce capital expenditure on multi-platform systems. Alma Lasers dominates the professional channel with its integrated platform strategy. Cutera navigates regulatory complexity through dedicated NMPA liaison operations. Lumenis sustains its installed base by extending service contracts across tier-one hospital affiliates.
Laser hair removal employs selective photothermolysis, targeting melanin in hair follicles with wavelengths between 755 nm and 1064 nm to disable regrowth without damaging surrounding tissue. Diode laser systems occupy the highest volume tier due to their efficacy across Fitzpatrick skin types III through V prevalent in the Chinese population. Nd:YAG laser technology represents the fastest-growing product category as clinics serving darker skin tones demand safer long-pulse parameters. Dermatology centers command the most concentrated margin pool among end users, given their capacity to bundle hair removal with photorejuvenation protocols.
NMPA Class III medical device registration and GB standards for laser safety equipment govern product entry and clinical use in China. The national regulator's emphasis on adverse event reporting is forcing distributors to maintain localized technical service teams. Stakeholders must monitor how provincial health commissions interpret aesthetic procedure licensing, as municipal enforcement variation in Shenzhen versus Chengdu directly shapes clinic expansion feasibility.
Market Dynamics
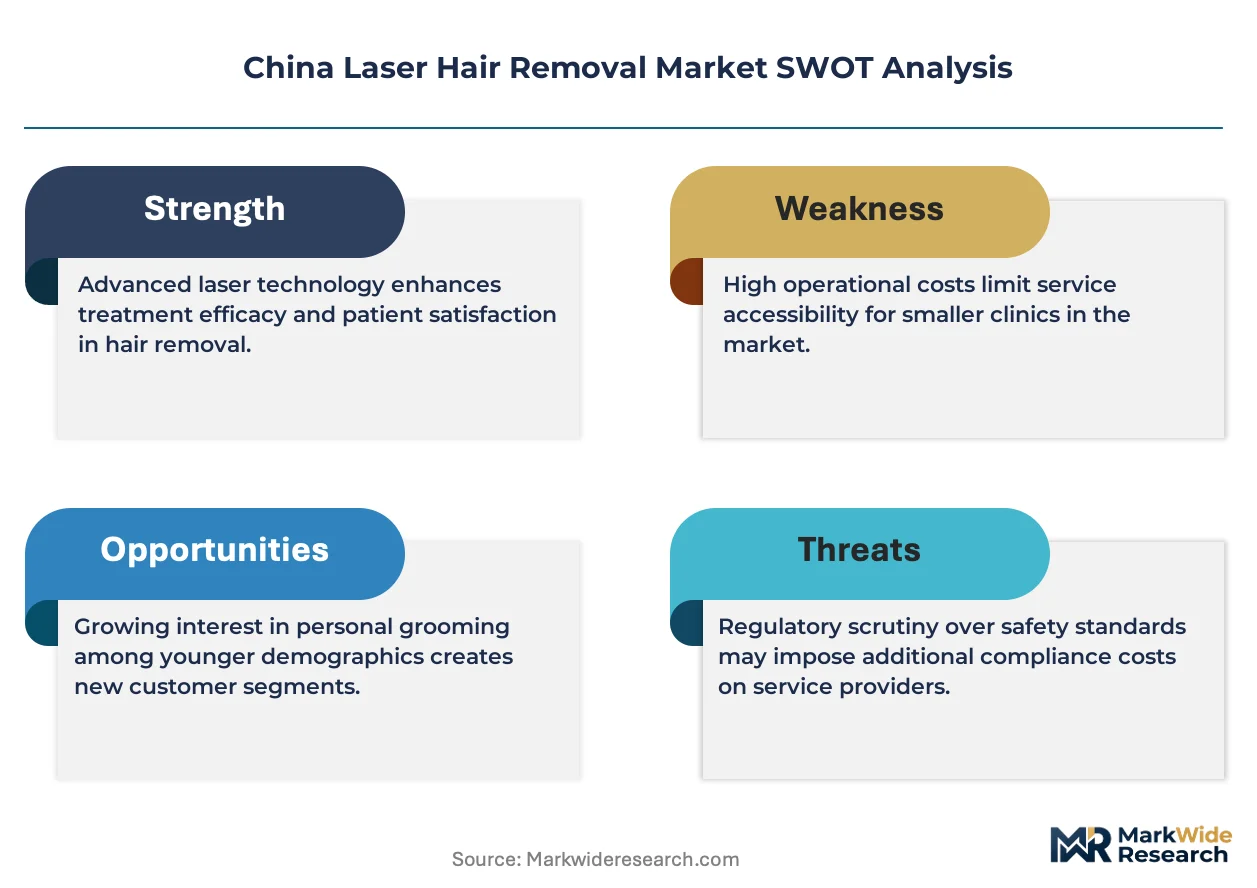
NMPA Class III medical device registration timelines are compressing competitive entry windows while diode laser platforms consolidate procurement decisions among tier-one dermatology centers.
Growth Catalysts
- Dual carbon goals:MIIT energy-efficiency mandates accelerate clinic adoption of solid-state laser systems over legacy IPL devices in Beijing and Shanghai.
- Medical aesthetic clinics:Dermatology centers bundle hair removal with photorejuvenation protocols, expanding device utilization rates across installed diode platforms.
- GB standards for laser safety equipment:Harmonized technical requirements reduce manufacturer certification duplication, shortening product launch cycles for domestic distributors.
Market Restraints
- Optical component concentration:German and Japanese suppliers control high-power diode bar supply, exposing Chinese OEMs to euro-yen volatility and extended lead times.
- Nd:YAG crystal sourcing:Synthetic YAG rod production concentrates among three specialized foundries, creating single-source vulnerability for long-pulse system manufacturers.
- Fitzpatrick skin type limitation:Alexandrite wavelength platforms face restricted addressable population in southern provinces where Type VI pigmentation prevalence exceeds device safety parameters.
Strategic Opportunities
- Chengdu and Xi'an corridor:Tier-two city disposable income growth outpaces Beijing saturation, creating whitespace for mid-range diode system deployment.
- Home-use device channel:Cross-border e-commerce platforms enable direct-to-consumer distribution of FDA-cleared handheld IPL units, bypassing clinic channel congestion.
- AI-assisted treatment planning:Integration of skin analysis algorithms with laser parameter selection creates premium service tier differentiation for high-end medical spas.
Industry Challenges
- NMPA clinical trial staffing:Qualified principal investigators for Class III device studies cluster in Shanghai and Guangzhou, delaying trial initiation for applicants in northern provinces.
- Service engineer certification:GB-standard laser safety officer credentials require annual renewal, constraining technical team scaling for multi-province distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Laser Hair Removal Market |
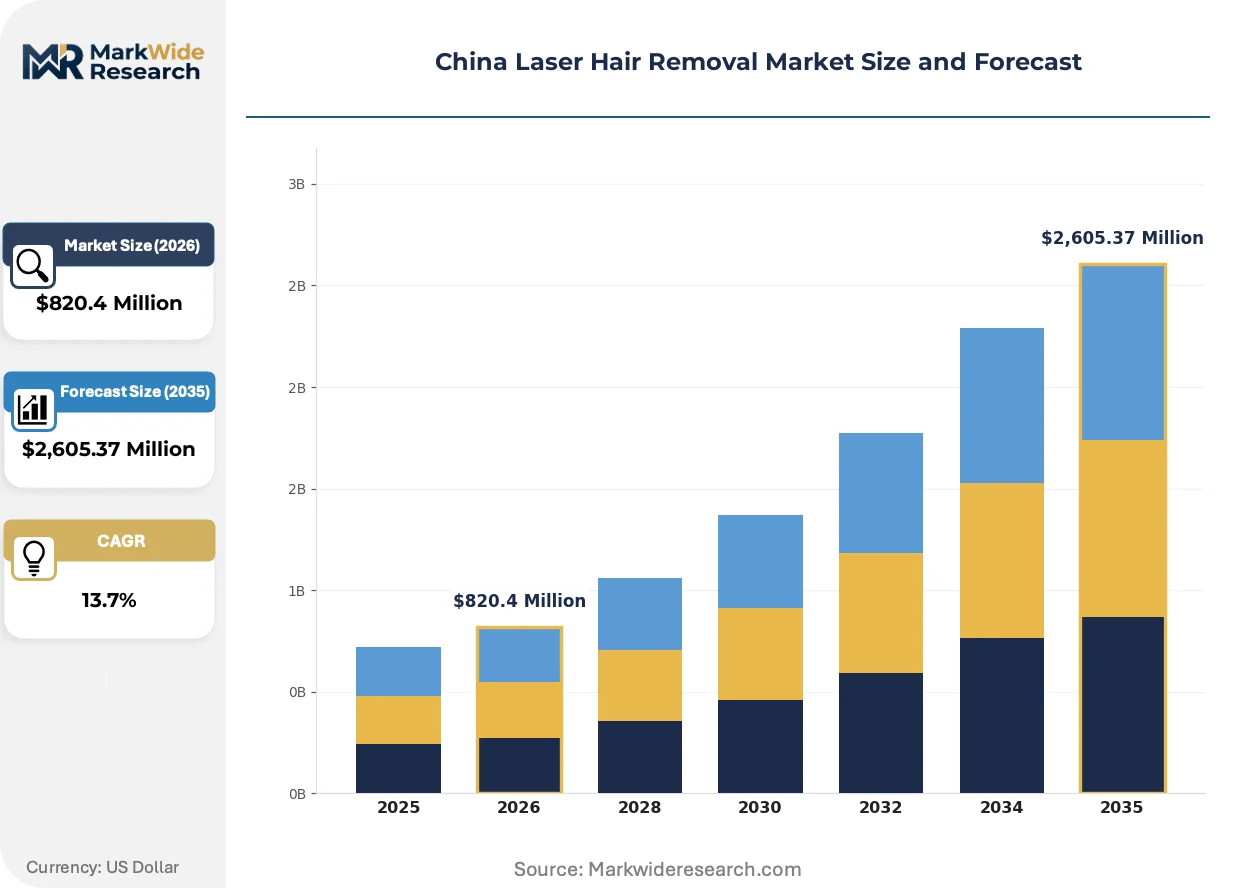
| Market Size in 2026 | $820.4 Million |
| Market Size in 2035 | $2,605.37 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diode Laser, Alexandrite Laser, Nd:YAG Laser, IPL System Application: Facial Hair Removal, Body Hair Removal, Permanent Hair Reduction, Touch-Up Treatments End User: Clinics, Home Users, Spas, Dermatology Centers Technology: Ruby Laser, Pulsed Light Technology, CO2 Laser, Hybrid Systems |
| Companies Covered | Cutera, Alma Lasers, Homi Laser, Venus Concept, Cynosure, Lumenis, Lutronic, Sciton, Synergy Candela, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Laser Hair Removal Market Trends and Innovations
Photorejuvenation bundling and AI-assisted skin analysis are redefining service delivery economics while regulatory data requirements reshape competitive entry barriers.
Triple-wavelength diode platforms combining 755 nm, 808 nm, and 1064 nm outputs are overtaking single-source systems in tier-one clinic procurement. Dermatology centers serving diverse patient phenotypes prioritize flexible parameter adjustment over peak power specifications. This capability compression is forcing standalone alexandrite manufacturers toward platform integration or exit.
SAMR adverse event reporting mandates now require real-time device connectivity for Class III laser systems. Manufacturers must embed cellular telemetry modules to satisfy post-market surveillance obligations. Tier-one hospital affiliates are selecting vendors based on cloud infrastructure readiness rather than hardware specifications alone.
Subscription-based device access is displacing capital purchase models among emerging clinic chains in Shenzhen and Hangzhou. Equipment-as-a-service contracts bundle maintenance, consumables, and software updates into per-treatment fees. This financing innovation is most visible among venture-backed aesthetic groups seeking to preserve working capital for location expansion.
China Laser Hair Removal Market Segmentation
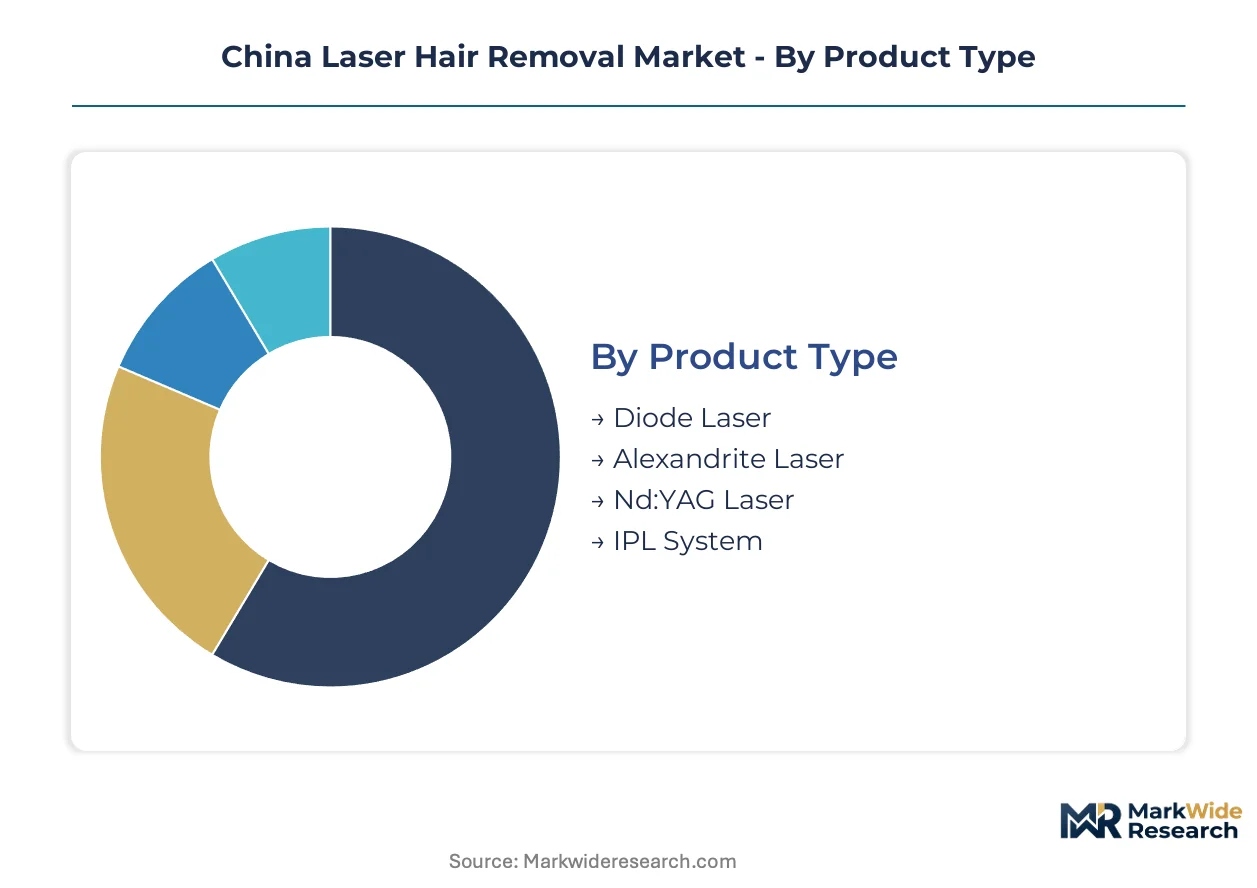
Technology selection in China's laser hair removal market determines treatment safety across Fitzpatrick skin types prevalent in the population. Device specifications directly influence NMPA registration pathways and clinic procurement decisions in tier-one cities.
Product Type:
Wavelength engineering defines clinical efficacy and safety margins across Chinese patient demographics.
- Diode Laser:Operating at 808 nm with semiconductor-pumped solid-state architecture, these systems deliver consistent fluence across large treatment areas. Beijing and Shanghai dermatology centers prioritize 808 nm platforms for their versatility across skin types III through V, which dominate northern and eastern Chinese populations. Dual carbon goals under MIIT directives accelerate replacement of legacy IPL devices with energy-efficient diode systems.
- Nd:YAG Laser:Long-pulse 1064 nm emission penetrates deeply with minimal epidermal absorption, enabling safe treatment of darker skin tones. Guangzhou clinics serving Type VI patients in southern provinces specify Nd:YAG platforms to avoid post-inflammatory hyperpigmentation risks that shorter wavelengths present.
- Alexandrite Laser:755 nm chromium-doped alexandrite crystals produce high melanin absorption for rapid treatment of lighter skin types.
- IPL System:Broadband filtered flashlamps offer multi-application flexibility but sacrifice specificity compared to monochromatic lasers.
Diode laser leads on scale; Nd:YAG laser leads on momentum.
Application:
Procedure location and permanence expectations segment device utilization patterns and pricing power.
- Facial Hair Removal:Precision requirements around periorbital and perioral zones demand small spot sizes with integrated cooling. Shanghai medical aesthetic clinics bundle facial hair removal with photorejuvenation protocols, elevating per-session revenue above standalone body treatments.
- Permanent Hair Reduction:Multiple-session protocols requiring 6-8 treatments generate predictable recurring revenue streams. Tier-one hospital affiliates structure package pricing around permanent reduction guarantees, differentiating from touch-up dependent competitors.
- Body Hair Removal:Large surface area treatments prioritize speed and patient comfort over absolute precision.
- Touch-Up Treatments:Maintenance sessions address hormonal regrowth patterns common in polycystic ovary syndrome patients.
Permanent hair reduction commands the margin pool; facial hair removal expands most quickly.
End User:
Capital intensity and regulatory compliance requirements stratify the customer base across channel types.
- Dermatology Centers:Physician-supervised facilities with Class III medical device operating licenses command premium pricing through clinical credibility. These centers in Beijing, Shanghai, and Guangzhou concentrate procurement of multi-wavelength platforms capable of addressing complex patient presentations.
- Clinics:Mid-scale aesthetic operators balance equipment versatility against per-treatment economics.
- Spas:Non-medical wellness venues face stricter provincial licensing interpretations in Shenzhen versus Chengdu.
- Home Users:Cross-border e-commerce channels enable direct acquisition of FDA-cleared handheld devices, bypassing clinical channel congestion entirely.
Dermatology centers lead on scale; home users lead on momentum.
Technology:
Platform architecture choices reflect trade-offs between specificity, versatility, and regulatory burden.
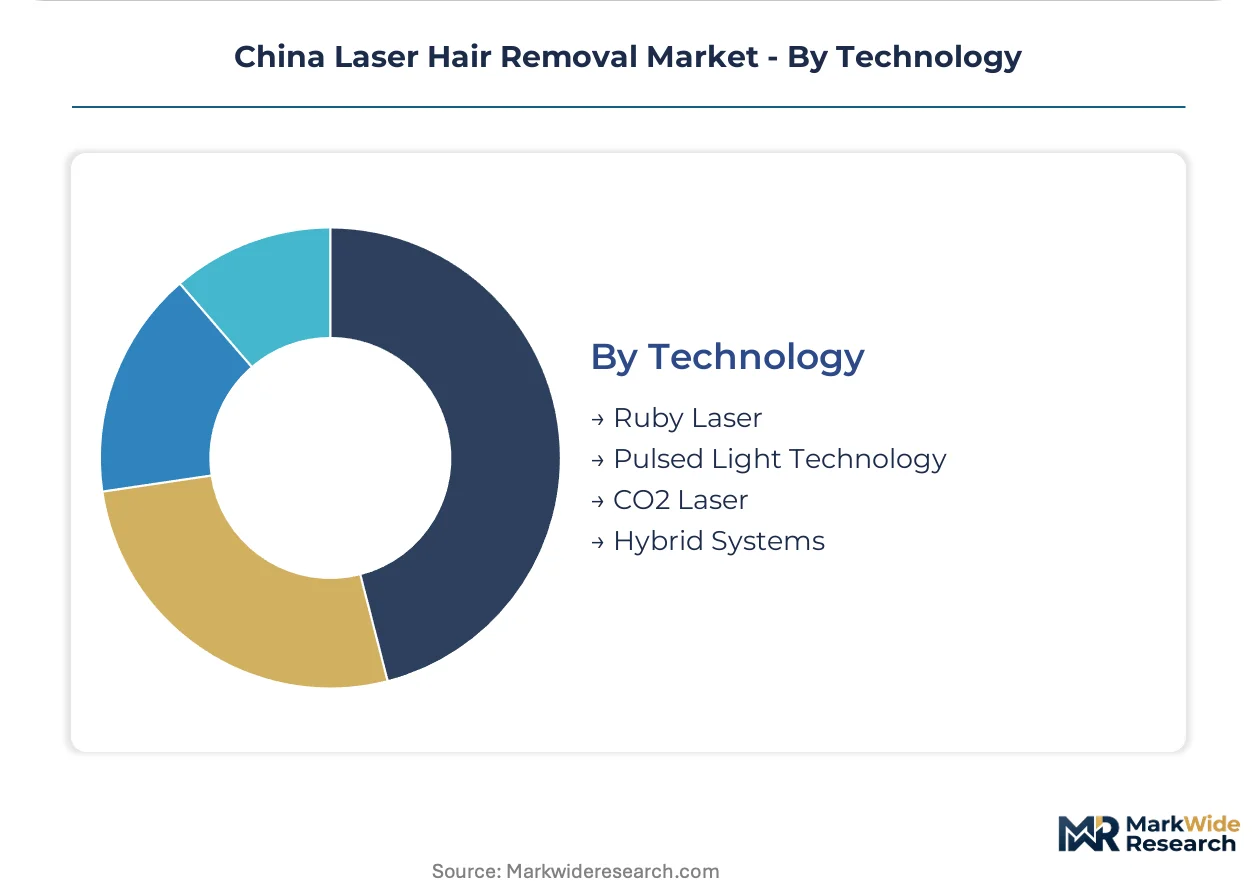
- Pulsed Light Technology:Filtered broadband emission enables simultaneous treatment of multiple chromophores. Hangzhou aesthetic groups deploy IPL platforms for hair removal combined with vascular and pigmented lesion indications, maximizing device utilization rates.
- Hybrid Systems:Integrated platforms combining multiple laser sources with IPL capability consolidate treatment room footprint. Tier-one clinic chains in Shenzhen prefer hybrid configurations to reduce capital expenditure per service line while maintaining clinical flexibility.
- Ruby Laser:694 nm chromium-doped aluminum oxide emission targets fine, light-colored hair with high melanin specificity.
- CO2 Laser:Ablative 10,600 nm systems see limited hair removal application due to epidermal damage risk.
Pulsed light technology leads on scale; hybrid systems lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Beijing anchors the China laser hair removal market through concentrated dermatology center procurement and stringent NMPA regulatory enforcement. Shanghai and Guangzhou follow as secondary demand poles, while tier-two corridors in western China emerge as expansion targets.
Beijing-Tianjin-Hebei
Capital region dermatology centers drive multi-wavelength platform adoption among affluent patient populations. MIIT dual carbon goals accelerate clinic replacement of legacy IPL systems with solid-state diode lasers. Chaoyang District medical aesthetic clusters concentrate procurement decisions for northern China.
Yangtze River Delta
Shanghai's medical aesthetic chains bundle hair removal with photorejuvenation protocols, elevating per-session revenue benchmarks. SAMR adverse event reporting mandates require real-time device connectivity for Class III laser systems. Hangzhou venture-backed clinic groups pioneer subscription-based equipment access models.
Pearl River Delta
Guangzhou clinics serving Type VI skin tone patients specify Nd:YAG platforms to avoid post-inflammatory hyperpigmentation. NMPA clinical trial investigators cluster in Guangzhou, accelerating device approval timelines for southern applicants. Shenzhen municipal enforcement of aesthetic procedure licensing varies from Chengdu interpretations.
Sichuan-Chongqing Corridor
Chengdu disposable income growth outpaces Beijing saturation, creating whitespace for mid-range diode system deployment. Provincial health commissions interpret aesthetic licensing with greater flexibility than coastal regulators. Western China clinic chains expand device procurement budgets ahead of tier-one saturation.
China Laser Hair Removal Market Competitive Landscape
Platform integration dominates the current landscape as manufacturers consolidate multiple wavelength sources into single systems. The vendor base stratifies across three tiers: multinational platform specialists, regional diode laser fabricators, and emerging hybrid system developers. Two strategic archetypes prevail: integrated platform providers serving tier-one dermatology centers, and specialized Nd:YAG manufacturers targeting darker skin tone applications. Competitive moves center on NMPA registration acceleration and service contract extensions across hospital affiliates.
Within the multinational tier, Alma Lasers, Cutera, and Lumenis anchor professional channel positioning through distinct regulatory and service strategies. Alma Lasers exemplifies integrated platform dominance in tier-one clinic procurement. Cutera occupies a position defined by dedicated NMPA liaison operations navigating approval complexity. Lumenis represents the installed base defense archetype, extending service contracts across Beijing and Shanghai hospital affiliates to sustain recurring revenue streams.
| Leading Market Players |
|---|
| Cutera |
| Alma Lasers |
| Homi Laser |
| Venus Concept |
| Cynosure |
| Lumenis |
| Lutronic |
| Sciton |
| Synergy Candela |
| Others |
Pricing and Supply Chain Analysis
Captive integration into high-power diode bar fabrication anchors both supply security and premium pricing power for tier-one equipment manufacturers serving Beijing and Shanghai dermatology centers. This vertical control over semiconductor-pumped solid-state architecture insulates against euro-yen volatility while enabling sustained margin capture across multi-wavelength platform sales.
Pricing Analysis
Input-cost pass-through from German and Japanese optical component suppliers shapes tiered pricing across premium, standard, and economy equipment levels. Certification grade under NMPA Class III medical device registration and after-sales service bundling drive price differentiation between multinational platform specialists and domestic OEMs. Cost compression in mid-range diode systems is intensifying because tier-two city clinics demand lower per-treatment economics. Home users exhibit highest price sensitivity, while dermatology centers prioritize clinical flexibility over absolute cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale procurement demand from tier-one clinic chains, while authorized distributors serve fragmented spa and clinic networks in western provinces. German, Japanese, and domestic Chinese suppliers concentrate production of high-power diode bars, synthetic YAG rods, and integrated cooling modules. Supply chain risk centers on single-source vulnerability for Nd:YAG crystal sourcing from three specialized foundries. Distribution runs through hospital procurement committees, regional medical device distributors, and emerging cross-border e-commerce platforms for home-use segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's laser hair removal market operates as a stable compounder, with medical aesthetic clinic expansion in tier-two corridors delivering sustained device procurement growth across the analysis window.
For Market Incumbents: Extend service contract coverage across Beijing and Shanghai hospital affiliates to defend recurring revenue streams against subscription-based equipment access models emerging in Shenzhen and Hangzhou. Deepen backward integration into diode bar fabrication to reduce exposure to euro-denominated component volatility and secure supply priority during allocation periods. For New Entrants and Emerging Players: Tier-two city distributors in the Chengdu and Xi'an corridor represent the most penetrable channel entry point, given whitespace for mid-range diode deployment and flexible provincial licensing interpretations. Target AI-assisted treatment planning integration as a differentiated service tier for high-end medical spas seeking premium positioning. For Investors and Strategic Acquirers: Roll-up economics work for regional hybrid system developers because NMPA registration timelines compress competitive entry windows and concentrate procurement decisions among established platform vendors. Monitor SAMR adverse event reporting mandate compliance as the signal indicating which manufacturers possess cloud infrastructure readiness for tier-one hospital affiliate selection.| Strategic Initiative | Industry Significance |
|---|---|
| NMPA Class III Registration Acceleration | Shortened approval timelines compress competitive entry windows for multinational entrants. |
| Multi-Wavelength Platform Integration | Consolidated treatment room footprint reduces capital expenditure per service line for clinic chains. |
| Cloud Infrastructure Development | Real-time device connectivity satisfies SAMR post-market surveillance obligations for hospital affiliates. |
| Subscription-Based Equipment Access | Per-treatment financing preserves working capital for venture-backed aesthetic group expansion. |
| AI-Assisted Treatment Planning | Skin analysis algorithm integration creates premium service tier differentiation for medical spas. |
Research Methodology
Multiple input streams — dermatology center procurement directors, NMPA regulatory affairs specialists, medical device distributor technical service heads, and hospital biomedical engineering committees — were reconciled against secondary validation from NMPA registration databases, MIIT energy-efficiency directive filings, and provincial health commission licensing records. Bottom-up installation data across tier-one and tier-two cities was triangulated with top-down revenue estimates from equipment manufacturer disclosures.
Data-stream reconciliation across technology type, end-user channel, and regional regulatory cluster dimensions anchored the analytical framework over the projection horizon. CAGRs were derived from modeled adoption curves for diode and Nd:YAG platforms, incorporating Fitzpatrick skin type demographics, disposable income trajectories, and clinic expansion pipelines as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to NMPA registration timeline variability, euro-yen exchange rate volatility affecting optical component costs, and provincial health commission licensing interpretation shifts. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Aesthetics
France Hair Transplant Market
Medical Aesthetics
Non-Hyaluronic Acid Dermal Filler Market
Medical Aesthetics
UK Hair Transplant Market
Medical Aesthetics
Cosmetic Threads Market
Medical Aesthetics
South Korea Hair Transplant Market
Medical Aesthetics
Chin Augmentation Market
Medical Aesthetics
Laser Scar Removal Market
Medical Aesthetics
Europe Facial Injectable Market
Medical Aesthetics
Oculoplastic Surgery Market
Medical Aesthetics
Europe Medical Aesthetic Devices Market
Medical Aesthetics
Injectable Anti-Wrinkle Treatment Market
Medical Aesthetics
Hair Transplant Market
Medical Aesthetics
Global Medical Aesthetic Devices Market
Medical Aesthetics
China Hair Transplant Market
Medical Aesthetics
Tattoo Removal Market
Medical Aesthetics
Facial Aesthetics Market