
 Asia-Pacific Interventional Cardiology and Peripheral Vascular Devices Market | 2026-2036
Asia-Pacific Interventional Cardiology and Peripheral Vascular Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Interventional Cardiology and Peripheral Vascular Devices Market Analytics
Japanese catheter production is decoupling from legacy nitinol supply chains as domestic alloy processors expand capacity. Terumo Corporation leverages vertical integration across guidewire manufacturing to anchor its position in minimally invasive delivery systems. Abbott Laboratories sustains technology leadership in drug-eluting platforms through dedicated R&D facilities in Singapore. Boston Scientific Corporation competes on balloon-expandable stent specialization across Australia's cardiac care networks.
Interventional cardiology and peripheral vascular devices encompass stents, balloons, catheters, and guidewires engineered from nitinol, cobalt-chromium, or bioresorbable polymers with strut thicknesses below 100 micrometers, designed to restore luminal patency in coronary and peripheral arteries through percutaneous transluminal intervention. Drug-eluting stent platforms command premium positioning due to sustained antiproliferative coating requirements, while bioabsorbable technology segments attract focused investment despite extended regulatory pathways. Ambulatory surgery centers represent the fastest-growing end user channel as same-day PCI protocols expand across South Korea and Taiwan.
Japan's PMDA enforces stringent Good Manufacturing Practice audits on imported coronary stents, while Australia's TGA mandates ISO 14155-compliant clinical evidence for novel device registration. India's CDSCO accelerates market access through priority review pathways for indigenously manufactured catheters under its PLI scheme. Stakeholders must monitor divergent biocompatibility testing requirements across national regulators when harmonizing regional product portfolios.
Market Dynamics
Japan's PMDA biocompatibility audits and China's hospital procurement centralization are compressing margins while accelerating technology turnover across the Asia-Pacific interventional cardiology landscape.
Growth Catalysts
- PLI scheme acceleration:India's CDSCO priority review pathways slash registration timelines for domestically manufactured catheters, channeling capital toward indigenization.
- Same-day PCI protocols:Ambulatory surgery centers across South Korea and Taiwan are absorbing volume from tertiary hospitals, expanding addressable procedure volume.
- Bioresorbable polymer platforms:Sustained antiproliferative coating requirements on drug-eluting stents command premium positioning and repeat purchase cycles.
Market Restraints
- Nitinol supply concentration:Japanese catheter producers face input volatility as legacy alloy supply chains consolidate around a limited processor base.
- ISO 14155 evidentiary burden:Australia's TGA mandates full clinical trial compliance for novel device registration, extending time-to-revenue for innovators.
- Bioresorbable technical limitations:Extended degradation timelines and mechanical performance gaps constrain adoption in complex lesion subsets.
Strategic Opportunities
- Central and western China hospital clusters:Underpenetrated provinces beyond the eastern seaboard present expansion vectors for catheter and guidewire distributors.
- Dual antiplatelet therapy reduction:Polymer-free drug-eluting platforms enable shorter DAPT protocols, opening ambulatory and elderly patient segments.
- Vertical manufacturing integration:Captive nitinol melting and wire-drawing capabilities insulate producers from alloy spot price volatility.
Industry Challenges
- Microfabrication talent scarcity:Strut thickness targets below 100 micrometers demand specialized laser machining expertise concentrated in Japan and Singapore.
- Multi-jurisdiction dossier harmonization:Divergent biocompatibility testing requirements across PMDA, TGA, and CDSCO force redundant regulatory expenditure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Interventional Cardiology and Peripheral Vascular Devices Market |
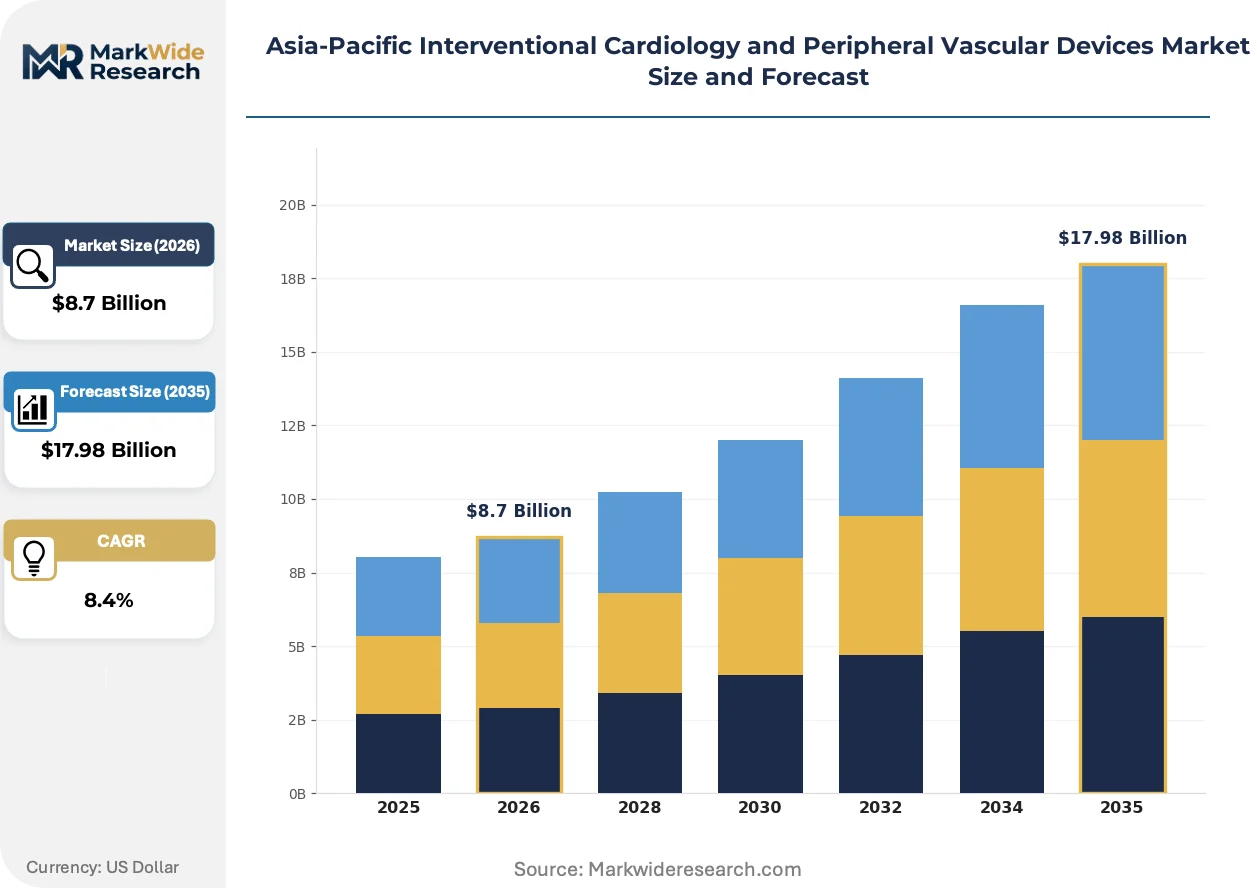
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stents, Balloons, Catheters, Guidewires End User: Hospitals, Ambulatory Surgery Centers, Cardiac Care Units, Specialty Clinics Technology: Bioabsorbable, Drug-Eluting, Non-Drug-Eluting, Balloon-Expandable Delivery Mode: Minimally Invasive, Open Surgery, Transcatheter, Hybrid Techniques |
| Companies Covered | Terumo Corporation, Johnson & Johnson, Medtronic, Cook Medical, BD, Boston Scientific Corporation, Edwards Lifesciences Corporation, Meril Life Sciences, Abbott Laboratories, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Interventional Cardiology and Peripheral Vascular Devices Market Evolving Landscape
Device miniaturization and polymer science advances are collapsing the performance gap between permanent metallic scaffolds and bioresorbable alternatives across Asia-Pacific cardiac centers.
Bioresorbable vascular scaffolds engineered from poly-L-lactide and tyrosine-derived polycarbonate restore acute luminal support before complete metabolic absorption. Tertiary hospitals in Japan and Australia are piloting these platforms for younger patient cohorts with discrete de novo lesions. The technology is overtaking cobalt-chromium bare metal stents in elective PCI cases where long-term endothelial function preservation matters.
Japan's PMDA tightened Good Manufacturing Practice audit protocols for imported coronary stents in 2023, requiring real-time manufacturing data submission. Foreign manufacturers now face facility inspection backlogs stretching eighteen months. Singapore-registered production sites are absorbing disproportionate audit capacity as regional headquarters relocate quality functions.
Hospital procurement consortiums in China's eastern provinces are consolidating catheter and guidewire purchasing through centralized tender platforms. Volume commitments now dominate supplier selection over unit pricing. Zhejiang and Jiangsu province health commissions are piloting two-year framework agreements that lock out non-participating distributors.
Asia-Pacific Interventional Cardiology and Peripheral Vascular Devices Market Segmentation
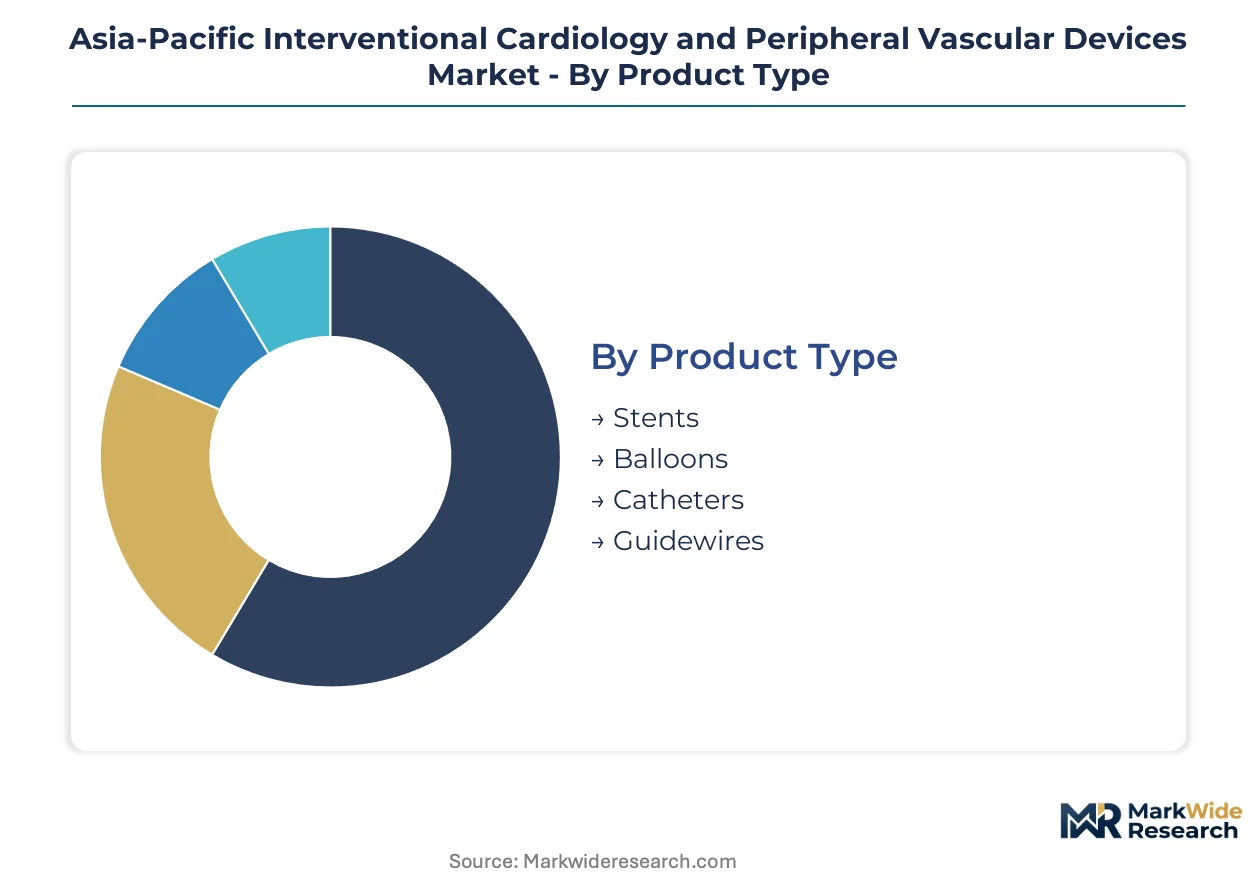
Segmentation in this market traces regulatory pathways as much as clinical applications. PMDA, TGA, and CDSCO each impose distinct dossier requirements that reshape commercial viability across product categories and end-use settings.
Product Type:
Stent and balloon segments carry heavier biocompatibility audit burdens under Japan's PMDA than catheter or guidewire lines, while China's centralized procurement applies uniform pressure across all four categories.
- Stents:Drug-eluting and bioabsorbable platforms engineered from cobalt-chromium alloys or poly-L-lactide polymers with sub-100 micrometer strut thicknesses. Tertiary hospitals in Japan's Kanto region and China's Zhejiang province drive demand as these facilities handle complex multivessel interventions requiring durable antiproliferative coatings.
- Balloons:Semi-compliant and non-compliant dilation catheters deployed for lesion preparation and post-stent optimization. Australia's cardiac care networks absorb significant volume as TGA-mandated ISO 14155 trials favor established balloon platforms with proven safety profiles over novel alternatives.
- Catheters:Diagnostic and interventional sheaths manufactured through nitinol hypotube processing. India's CDSCO priority review under PLI schemes accelerates domestic catheter registration timelines.
- Guidewires:Hydrophilic and hydrophobic torque-responsive wires for lesion crossing. Terumo Corporation's vertical manufacturing integration anchors Japanese supply security for this segment.
Leading the category by volume: Stents. Growing fastest: Catheters under India's PLI acceleration.
End User:
Procedure site selection determines reimbursement codes and device specification tiers, with ambulatory settings demanding simplified inventory and faster turnover formats than tertiary institutions.
- Hospitals:General acute care facilities performing both emergency and elective PCI procedures. China's eastern province hospital clusters concentrate procurement volume through centralized tender platforms that lock in two-year framework agreements.
- Ambulatory Surgery Centers:Same-day discharge facilities expanding across South Korea and Taiwan. These centers absorb PCI volume from tertiary hospitals as protocols shorten observation windows.
- Cardiac Care Units:Dedicated coronary intervention suites within tertiary institutions. Japan's PMDA facility inspections target these high-volume sites for real-time manufacturing data verification.
- Specialty Clinics:Peripheral vascular-focused outpatient practices managing chronic limb ischemia. Australia's TGA registration pathways limit novel device adoption in these lower-acuity settings.
Dominant by procedure value: Cardiac Care Units. Expanding most quickly: Ambulatory Surgery Centers.
Technology:
Platform selection hinges on degradation kinetics versus mechanical performance tradeoffs, with polymer science advances collapsing historical gaps between permanent and resorbable scaffolds.
- Bioabsorbable:Tyrosine-derived polycarbonate and poly-L-lactide scaffolds metabolizing to lactic acid and carbon dioxide. Tertiary hospitals in Japan and Australia pilot these for younger patients with discrete de novo lesions where endothelial function preservation matters long-term.
- Drug-Eluting:Antiproliferative agent coatings on metallic platforms requiring sustained release kinetics. Abbott Laboratories' Singapore R&D facilities anchor technology leadership for this premium-positioned segment.
- Non-Drug-Eluting:Bare metal and polymer-free cobalt-chromium scaffolds. Cost-sensitive procurement in India's government hospitals sustains residual demand.
- Balloon-Expandable:Deployment systems relying on controlled inflation pressure rather than self-expanding mechanics. Boston Scientific Corporation specializes across Australia's cardiac care networks.
Revenue concentration: Drug-Eluting. Steepest expansion trajectory: Bioabsorbable despite extended regulatory pathways.
Delivery Mode:
Access strategy selection shapes device design specifications, with transcatheter approaches demanding lower-profile delivery systems than open surgical alternatives.
- Minimally Invasive:Percutaneous femoral or radial access techniques dominating coronary intervention. South Korea's same-day PCI protocols standardize this approach across ambulatory and hospital settings.
- Open Surgery:Direct arterial exposure for complex peripheral bypass or endarterectomy. Declining share as endovascular techniques advance.
- Transcatheter:Valve and structural heart interventions requiring specialized delivery catheters. Singapore-registered production sites absorb disproportionate PMDA audit capacity for these high-risk devices.
- Hybrid Techniques:Combined surgical and endovascular approaches for multilevel peripheral disease. Taiwan's tertiary centers pioneer these protocols for critical limb ischemia.
Procedure volume leader: Minimally Invasive. Gaining share fastest: Transcatheter as structural heart applications expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nitinol alloy processing clusters in Japan's Niigata prefecture anchor catheter manufacturing supply security for the broader Asia-Pacific region. Raw material localization is reshaping procurement patterns as domestic Japanese processors expand melting capacity.
Japan
PMDA facility inspections and real-time manufacturing data requirements compress registration timelines for foreign stent manufacturers. Kanto region tertiary hospitals absorb disproportionate audit capacity as Singapore-registered production sites relocate quality functions. Tokyo-Osaka cardiac care networks pilot bioresorbable scaffolds for younger elective PCI patients.
China
Eastern province hospital clusters in Zhejiang and Jiangsu consolidate catheter purchasing through centralized two-year framework agreements. NMPA-aligned procurement centralization locks out non-participating distributors. Shanghai-Suzhou manufacturing corridors concentrate domestic guidewire assembly capacity.
India
CDSCO priority review pathways under PLI schemes accelerate domestic catheter registration timelines. Government hospital procurement sustains residual demand for non-drug-eluting platforms. Maharashtra and Karnataka medical device parks channel capital toward indigenization of interventional delivery systems.
Australia
TGA-mandated ISO 14155 clinical evidence requirements extend time-to-revenue for novel device innovators. Cardiac care networks favor established balloon platforms with proven safety profiles. Sydney-Melbourne metropolitan hospital systems concentrate peripheral vascular procedure volume.
South Korea
Same-day PCI protocols standardize minimally invasive approaches across ambulatory surgery centers. MFDS regulatory alignment with international standards streamlines multinational dossier submission. Seoul capital area facilities absorb volume migration from tertiary hospitals as observation windows shorten.
Asia-Pacific Interventional Cardiology and Peripheral Vascular Devices Market Competitive Landscape
Global majors compete with regional champions across technology licensing and manufacturing scale. The vendor base organizes into three tiers: integrated alloy-to-device producers, specialized catheter fabricators, and diversified medical technology conglomerates. Strategic archetypes include captive nitinol processors, polymer science specialists, and procurement-integrated distributors. Dominant competitive moves span backward integration into alloy supply and geographic relocation of quality functions to Singapore-registered sites.
Among Japan-based integrated manufacturers, Terumo Corporation exemplifies captive supply chain control from nitinol melting through finished guidewire delivery. Abbott Laboratories and Boston Scientific Corporation occupy positions representing global technology leadership archetypes, with Singapore-registered production facilities absorbing disproportionate PMDA audit capacity for high-risk device categories. These three anchors illustrate divergent strategic postures: regional vertical integration versus multinational R&D concentration versus balloon-expandable specialization.
| Leading Market Players |
|---|
| Terumo Corporation |
| Johnson & Johnson |
| Medtronic |
| Cook Medical |
| BD |
| Boston Scientific Corporation |
| Edwards Lifesciences Corporation |
| Meril Life Sciences |
| Abbott Laboratories |
| Others |
Value Network & Pricing Analysis
China's centralized hospital procurement consortiums in Zhejiang and Jiangsu provinces are locking suppliers into two-year volume framework agreements that prioritize commitment scale over unit economics, forcing manufacturers to absorb margin compression while securing alloy supply through captive melting arrangements or long-term offtake contracts with Japanese processors.
Pricing Analysis
Service bundling separates premium-tier device suppliers offering real-time manufacturing data submission and PMDA audit support from economy-tier competitors stripped to bare product-only transactions. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and vertical integration depth, with PMDA-audit-ready platforms commanding substantial premiums over CDSCO-registered alternatives. Cost compression in the standard tier is intensifying as India's PLI scheme floods domestic channels with indigenously manufactured catheters. Government hospital procurement committees in India exhibit highest price sensitivity, while Japan's Kanto region cardiac care units prioritize compliance assurance over unit cost.
Supply Chain Analysis
Regional distribution centers in Singapore and Shanghai coordinate hub-and-spoke patterns radiating toward hospital clusters across the Asia-Pacific region. Nitinol alloy supply concentrates in Japan's Niigata prefecture and select Chinese melting facilities, with catheter manufacturing drawing from cobalt-chromium feedstock processed in South Korean and Taiwanese facilities. Single-source vulnerability around Japanese alloy processors creates structural exposure as PMDA facility inspection backlogs stretch capacity. Distribution runs through procurement-integrated distributors holding framework agreements with China's eastern province health commissions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over nitinol melting and wire-drawing capabilities determines margin defense against procurement centralization.
For Market Incumbents: Anticipate further margin compression from China's tender consolidation by securing captive alloy supply through backward integration into Japanese or domestic Chinese melting capacity, while accelerating PMDA audit-ready quality function relocation to Singapore-registered production sites ahead of foreign manufacturer facility inspection backlogs. For New Entrants and Emerging Players: Enter via India's CDSCO priority review pathways for domestically manufactured catheters, exploiting PLI scheme acceleration to bypass entrenched import-dependent competitors, while targeting central and western China hospital clusters where procurement centralization has not yet penetrated as deeply as eastern provinces. For Investors and Strategic Acquirers: The window for entry favors polymer science specialists with bioabsorbable scaffold platforms navigating extended regulatory pathways, as sustained R&D investment requirements and PMDA evidentiary burdens filter out undercapitalized competitors; watch for MFDS regulatory alignment announcements as inflection indicators for South Korean market access simplification.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Audit Readiness Investment | Singapore-registered production sites absorb disproportionate inspection capacity for high-risk device categories. |
| PLI Scheme Participation | CDSCO priority review slashes registration timelines for indigenously manufactured catheters in India. |
| Captive Nitinol Supply | Backward integration into alloy melting insulates producers from spot price volatility and supply concentration. |
| Same-Day PCI Protocol Expansion | Ambulatory surgery centers across South Korea and Taiwan absorb volume from tertiary hospitals. |
| Bioabsorbable Platform Development | Tyrosine-derived polycarbonate scaffolds pilot in Japan and Australia for younger elective PCI patients. |
Research Methodology
Document review covered PMDA GMP audit protocols, CDSCO PLI scheme guidelines, and China's centralized procurement tender documents, complemented by interviews with hospital purchasing committee directors, biomedical engineers at tertiary cardiac care units, GPO contracts managers, and nitinol alloy processors. Secondary validation drew from TGA registration databases, MFDS regulatory filings, hospital procurement platform disclosures, and trade flow records. Bottom-up procedure volume estimates triangulated against top-down device shipment data across the analysis window.
Segmentation outputs reflect product type, end user setting, technology platform, and delivery mode dimensions modeled over the projection horizon. CAGRs were derived from regression analysis against procedure volume drivers and reimbursement trajectory assumptions. Forecast inputs incorporated PMDA audit capacity constraints, China's provincial procurement centralization timelines, and India's domestic manufacturing incentive acceleration.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden PMDA protocol revisions or alloy supply disruptions. Outputs reflect documented assumptions around regulatory pathway durations and procurement centralization penetration rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Medical Oxygen Concentrators Market
Medical Devices
Global Trauma Devices Market
Medical Devices
Radial Head Resection Implant Market
Medical Devices
Europe Insulin Pumps Market
Medical Devices
Asia-Pacific Ultrasound Probe Disinfection Market
Medical Devices
Chest Drainage Devices Market
Medical Devices
Air Compressor Nebulizer Market
Medical Devices
Global Robotic Flight Simulator Surgery Market
Medical Devices
Robotic Biopsy Devices Market
Medical Devices
Asia-Pacific Digital Dentistry Market
Medical Devices
Global Disposable Medical Sensors Market
Medical Devices
Endoscopic Mucosal Resection Device Market
Medical Devices
Global Sphygmomanometer Market
Medical Devices
Electric Massage Equipment Market
Medical Devices
Sentinel Node Biopsy Market
Medical Devices
Russia Massage Equipment Market