
 Acne Treatment Market | 2026-2036
Acne Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Acne Treatment Market Intelligence
Project finance for dermatology clinic networks is tilting competitive dynamics toward scaled operators with capital access. Johnson & Johnson leverages its consumer health infrastructure to sustain shelf presence across retail and clinical channels. Galderma S.A. anchors its position through specialization in dermatology-specific formulations and physician-directed sampling programs.
Acne treatment encompasses pharmacological and procedural interventions targeting sebaceous gland activity, follicular keratinization, and Cutibacterium acnes colonization, delivered through topical, oral, or device-based modalities. The primary purpose spans cosmetic improvement, psychological wellbeing, and prevention of permanent scarring in affected individuals. Retinoids dominate prescription volume due to established efficacy in comedolytic and anti-inflammatory action, while hormonal treatments capture margin pools in adult female cohorts with androgen-driven presentations. E-commerce platforms represent the fastest-growing distribution channel, reflecting patient preference for discreet access and subscription-based replenishment models.
FDA oversees prescription drug approval and labeling standards, while EPA regulates active pharmaceutical ingredient manufacturing discharge under environmental compliance frameworks. HIPAA shapes how telehealth platforms and online retailers handle patient data in acne consultation workflows. Stakeholders must monitor how FDA guidance on fixed-dose combination therapies evolves, as this will determine which development pipelines advance toward commercialization and which reformulation strategies require additional investment.
Market Dynamics
Fixed-dose combination therapies are compressing development timelines and reshaping competitive entry barriers as FDA streamlines approval pathways for multi-mechanism acne formulations.
Growth Catalysts
- Telehealth Expansion:HIPAA-compliant virtual consultation platforms extend prescription-grade access to rural and underserved patient cohorts, reducing geographic friction in dermatology service delivery.
- Retinoid Formulation Advances:Novel encapsulation technologies improve tolerability profiles and expand addressable populations beyond traditional adolescent demographics.
- Subscription Commerce:Direct-to-consumer replenishment models capture recurring revenue streams and reduce patient discontinuation rates through automated adherence programs.
Market Restraints
- API Manufacturing Concentration:Active pharmaceutical ingredient production clusters in China and India create supply vulnerability and quality assurance complexity for Western formulators.
- Isotretinoin REMS Burden:FDA's risk evaluation and mitigation strategy imposes costly compliance infrastructure and limits prescriber pool expansion for oral retinoid therapies.
- Antibiotic Resistance Pressure:Cutibacterium acnes resistance to clindamycin and erythromycin degrades efficacy of legacy topical combination products and triggers formulary restrictions.
Strategic Opportunities
- Hormonal Therapy Underserve:Adult female patients with androgen-driven presentations remain underdiagnosed relative to adolescent cohorts, representing unconverted demand for spironolactone and combined oral contraceptive interventions.
- Device-Drug Convergence:Integration of blue-light phototherapy with topical delivery systems creates novel reimbursement categories and differentiates clinic-based service offerings.
- Environmental Compliance Differentiation:EPA discharge standards for benzoyl peroxide manufacturing reward early adopters with sustainability credentials that resonate with institutional procurement.
Industry Challenges
- Formulation Stability Expertise:Retinoid oxidation sensitivity and benzoyl peroxide degradation kinetics require specialized analytical chemistry capabilities that concentrate among limited contract development partners.
- Clinical Trial Endpoint Standardization:Discordance between FDA's Investigator Global Assessment and patient-reported outcomes complicates label claim strategy and payer negotiation positioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acne Treatment Market |
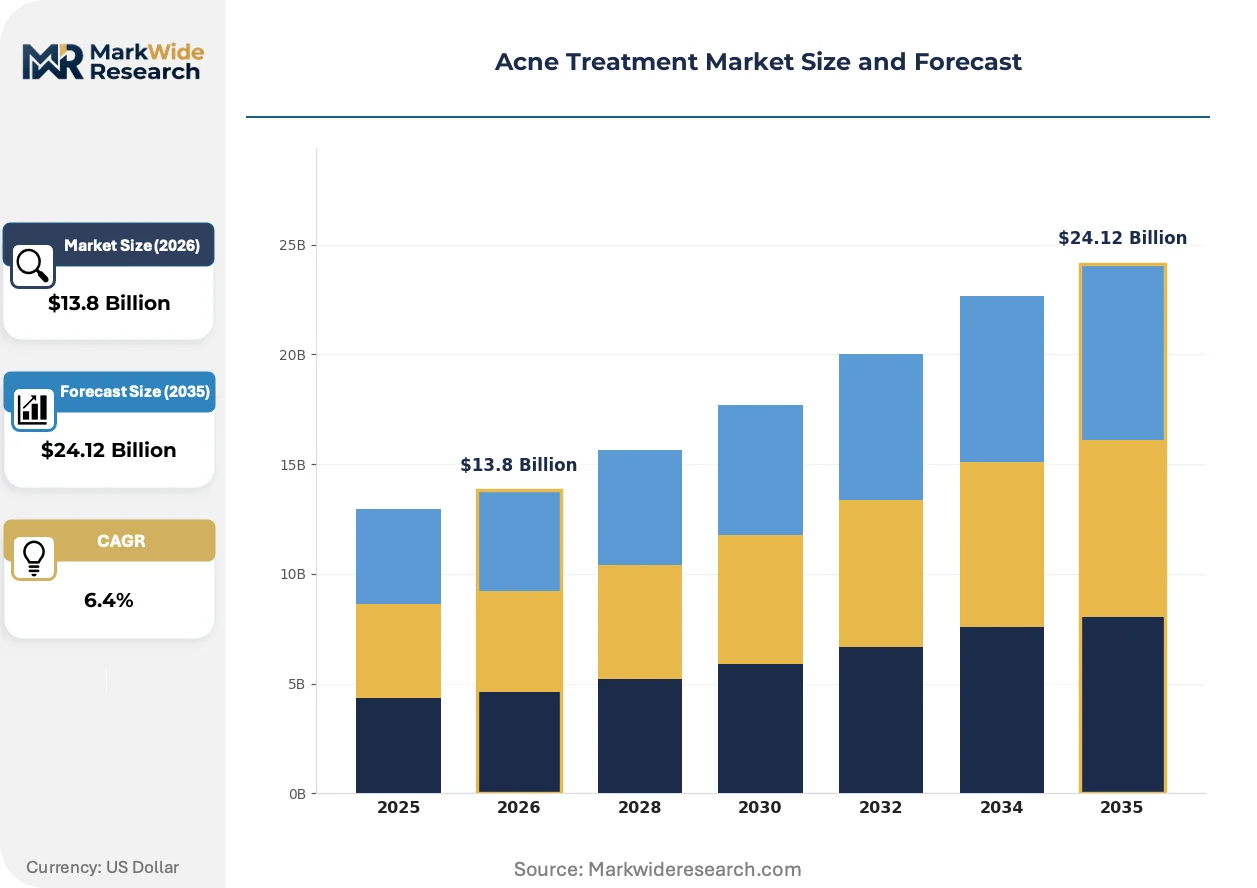
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $24.12 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Creams, Oral Antibiotics, Retinoids, Hormonal Treatments, Salicylic Acid Gels, Others Therapy Area: Mild Acne, Moderate Acne, Severe Acne, Cystic Acne, Nodular Acne End User: Dermatology Clinics, Beauty Salons, Pharmacies, Online Retailers, Hospitals Distribution Channel: Hospital Pharmacies, Drug Stores, E-commerce Platforms, Direct Sales, Specialty Stores |
| Companies Covered | Pfizer Inc., Bayer AG, Johnson & Johnson, GlaxoSmithKline plc, Sanofi S.A., Galderma S.A., AbbVie Inc., Teva Pharmaceutical Industries Ltd., Bausch Health Companies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acne Treatment Market Strategic Shifts & Innovations
Digital diagnostic tools and algorithmic treatment selection are compressing the traditional physician-patient consultation model while expanding precision in therapy matching.
Artificial intelligence-powered skin analysis applications are virtualizing the initial assessment phase of acne care. Dermatology practices and telehealth platforms deploy computer vision algorithms to classify lesion severity and predict treatment response. This capability is compressing time-to-treatment initiation and enabling asynchronous care models that extend provider capacity.
EMA's evolving guidance on fixed-dose combination quality requirements is elevating manufacturing standards for European market entry. Formulators must demonstrate dissolution profile equivalence and stability data across climatic zones. The directive most affects mid-scale generic manufacturers seeking pan-European distribution, driving consolidation in contract manufacturing organization selection.
Patient acquisition through social media influencer partnerships is displacing traditional physician referral channels for cosmetic-grade and over-the-counter segments. Direct-to-consumer brands leverage user-generated content and before-after documentation to build trust without clinical intermediation. This pattern concentrates in United States and United Kingdom markets where regulatory boundaries between cosmetic and drug claims remain contested.
Acne Treatment Market Segmentation
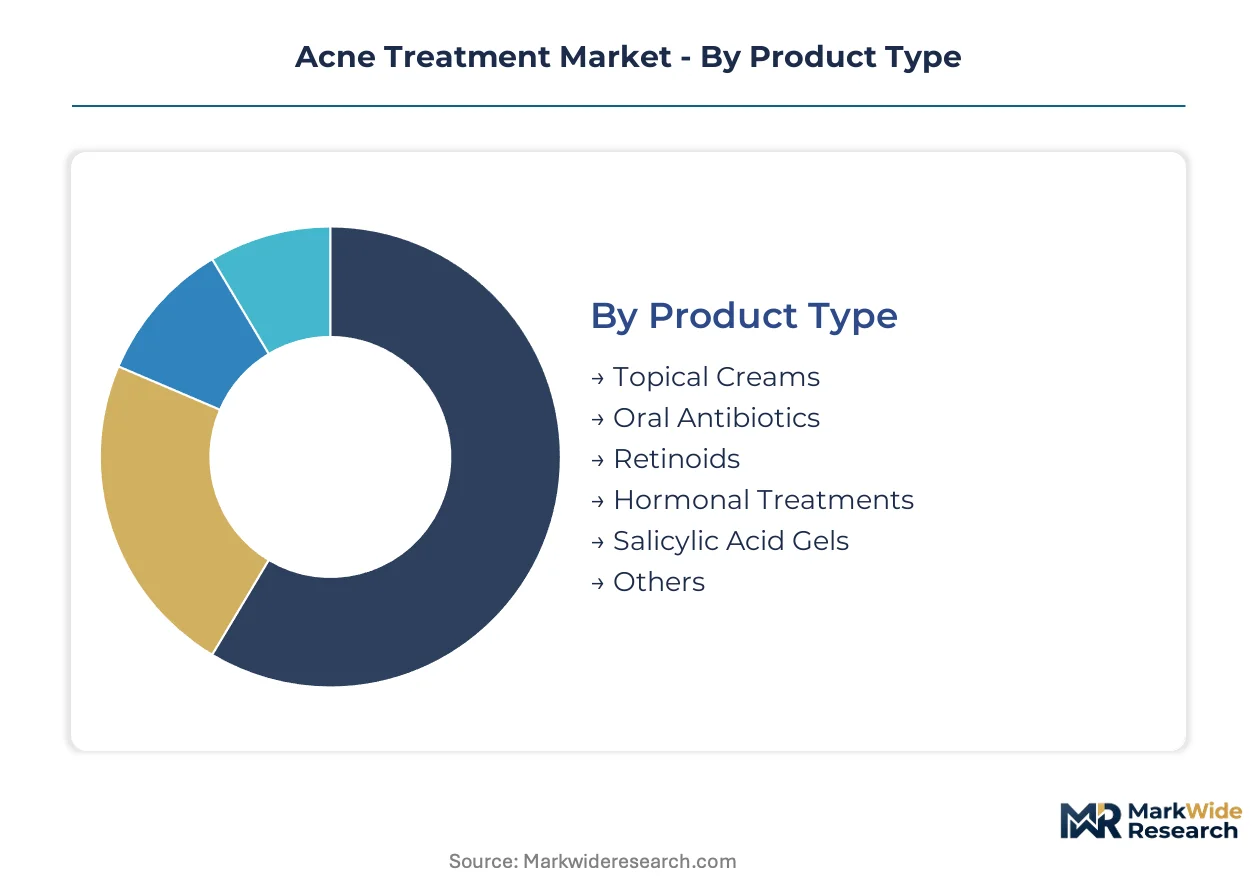
Acne treatment segmentation reveals distinct replenishment cycles across product categories, with topical formulations turning over monthly while oral therapies stretch to quarterly or annual scripts. Understanding these velocity differentials shapes inventory planning and patient adherence program design for manufacturers and channel partners.
Product Type:
Topical creams and gels rotate through patient medicine cabinets fastest, with average treatment cycles of four to eight weeks driving repeat purchase frequency, while oral isotretinoin courses extend six to twelve months with minimal interim buying.
- Topical Creams:Benzoyl peroxide and antibiotic combinations dominate pharmacy shelves with twice-daily application regimens. United States adolescent demand concentrates in mass retail channels where co-pay sensitivity shapes brand switching behavior.
- Retinoids:Tretinoin and adapalene formulations require photostable packaging and nighttime-only protocols. Adult female patients in urban United States markets drive prescription volume through dermatology-directed initiation followed by telehealth maintenance.
- Oral Antibiotics:Doxycycline and minocycline courses typically run three to four months per protocol.
- Hormonal Treatments:Spironolactone and combined oral contraceptives address androgen-driven presentations in adult women.
- Salicylic Acid Gels:Over-the-counter concentrations serve maintenance and mild inflammatory cases.
- Others:Azelaic acid and dapsone fill niche tolerability gaps.
Topical creams anchor the volume base while retinoids gain share at the steepest rate.
Therapy Area:
Severity stratification determines reimbursement tiering and prescriber channel, with mild cases self-treating through retail while severe presentations mandate specialist oversight and prior authorization navigation.
- Mild Acne:Comedonal and occasional papular lesions respond to over-the-counter salicylic acid and benzoyl peroxide without prescription friction.
- Moderate Acne:Inflammatory papules and pustules drive the bulk of dermatology visits and combination therapy prescriptions in United States commercial insurance populations.
- Severe Acne:Extensive nodular involvement triggers oral antibiotic or isotretinoin consideration with mandatory laboratory monitoring.
- Cystic Acne:Deep inflammatory nodules require intralesional corticosteroid injection or isotretinoin referral.
- Nodular Acne:Persistent large lesions carry highest scarring risk and psychological burden.
Moderate acne generates the majority of prescription revenue while severe acne commands the highest per-patient lifetime value through procedural and maintenance attach rates.
End User:
Channel selection tracks severity assessment and insurance status, with cash-pay patients gravitating toward retail and subscription models while insured severe cases concentrate in clinic-based care.
- Dermatology Clinics:Physician-supervised initiation and monitoring capture moderate-to-severe cases with prior authorization requirements.
- Pharmacies:Community and hospital outpatient dispensaries handle the majority of prescription fulfillment with generic substitution driving margin compression.
- Online Retailers:Direct-to-consumer platforms and telehealth-integrated pharmacies serve discreet replenishment demand.
- Beauty Salons:Aesthetic practitioners offer superficial extraction and light therapy adjuncts.
- Hospitals:Inpatient and emergency settings manage acute fulminant presentations and medication complications.
Pharmacies process the highest transaction volume while online retailers expand most quickly.
Distribution Channel:
Channel economics diverge sharply on fulfillment speed versus clinical touch requirements, with acute needs favoring physical retail and maintenance scripts shifting to automated delivery.
- E-commerce Platforms:Subscription models and telehealth integration capture recurring revenue with 90-day auto-refill programs reducing discontinuation.
- Drug Stores:CVS, Walgreens, and independent pharmacies maintain immediate accessibility for acute flare management.
- Hospital Pharmacies:Captive dispensing within dermatology practices and medical centers ensures protocol adherence.
- Direct Sales:Manufacturer-operated portals and physician dispensing programs bypass wholesale markup.
- Specialty Stores:Sephora, Ulta, and dermocosmetic boutiques bridge cosmetic and therapeutic positioning.
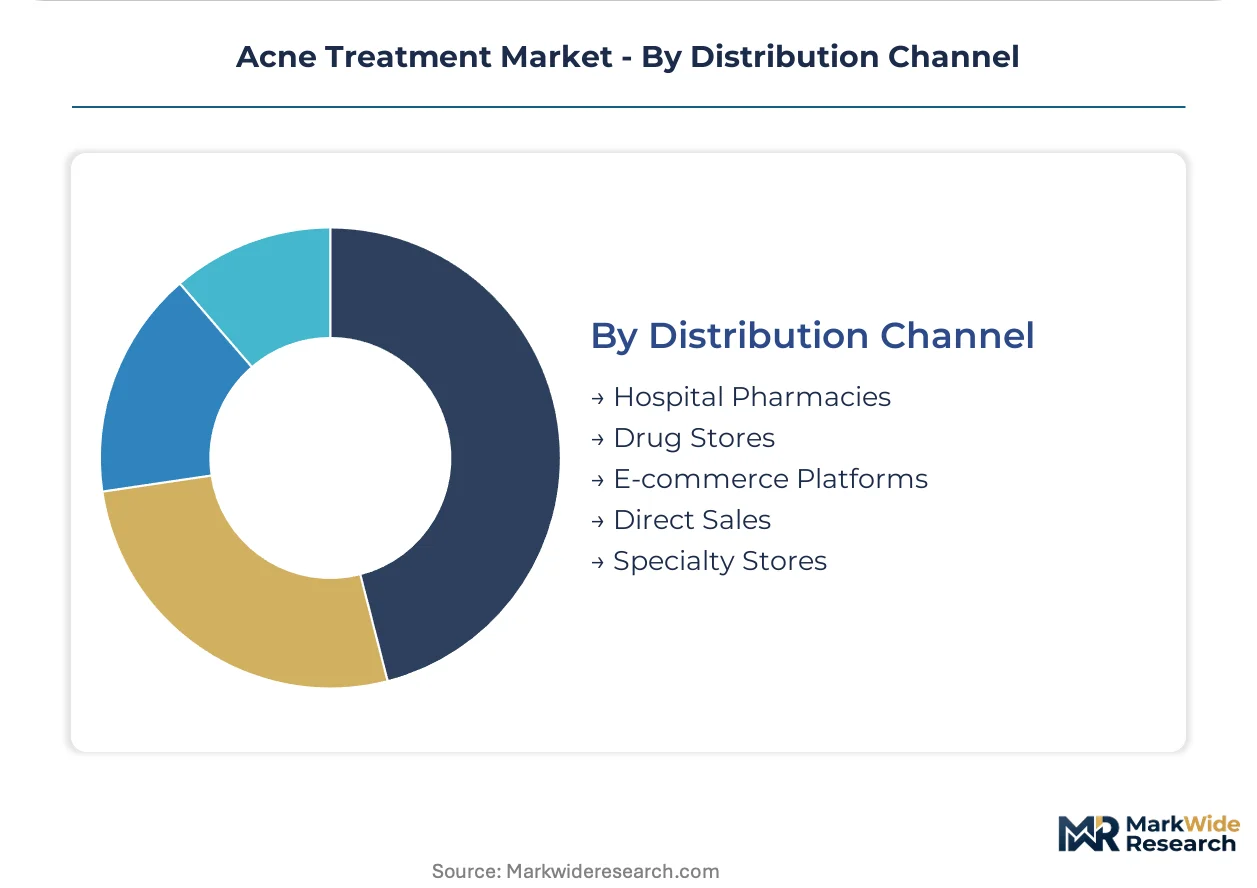
Drug stores retain the largest prescription volume footprint while e-commerce platforms capture the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Acne treatment trade flows reveal a pronounced import dependency in high-value prescription segments, with active pharmaceutical ingredient sourcing concentrated in Asian manufacturing clusters while finished formulation demand clusters in North American and European consumer markets.
United States
FDA's streamlined approval pathways for fixed-dose combination therapies accelerate product entry for adolescent and young adult cohorts seeking prescription-grade interventions. HIPAA-compliant telehealth platforms extend dermatology access to rural populations, reducing geographic friction in service delivery. Boston and San Francisco anchor device-drug convergence innovation, with phototherapy-integrated delivery systems emerging from academic medical center spinouts.
Germany
EMA's evolving guidance on combination quality requirements elevates manufacturing standards for European market entry, particularly affecting mid-scale generic manufacturers. REACH compliance for benzoyl peroxide discharge standards rewards early sustainability adopters with institutional procurement advantages. The Rhine-Ruhr corridor concentrates contract manufacturing organization capacity, with dissolution profile testing facilities serving pan-European distribution networks.
China
NMPA regulatory harmonization initiatives accelerate domestic innovation in retinoid encapsulation technologies targeting tolerability improvements. Dual carbon goals reshape environmental compliance frameworks for API production facilities in Jiangsu and Zhejiang provinces. Shanghai's Pudong district hosts multinational joint ventures specializing in photostable packaging for export markets.
India
CDSCO's abbreviated approval pathways for generic oral antibiotics support cost-competitive supply to African and Southeast Asian markets. PLI scheme incentives attract investment in benzoyl peroxide manufacturing capacity expansion. Hyderabad's Genome Valley clusters analytical chemistry capabilities serving Western formulators seeking formulation stability expertise.
Brazil
ANVISA's alignment with ICH guidelines reduces registration timelines for hormonal therapy imports addressing adult female androgen-driven presentations. Local production incentives under pharmaceutical sector programs stimulate contract manufacturing partnerships. São Paulo's dermatology clinic networks expand service lines for moderate-to-severe case management.
Acne Treatment Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in formulation stability and API supply. The market structures around three tiers: multinational pharmaceutical conglomerates with consumer health infrastructure, dermatology-focused specialists with physician-directed sampling programs, and generic manufacturers competing on cost and regulatory agility. Consolidation pressures concentrate among mid-scale players lacking vertical integration into encapsulation technologies or photostable packaging capabilities. Dominant competitive moves include portfolio diversification into hormonal therapy segments and strategic partnerships with telehealth platforms for patient acquisition.
Among Switzerland-based dermatology specialists, Galderma S.A. exemplifies the physician-directed sampling archetype, while Johnson & Johnson occupies a position bridging consumer health retail presence with clinical channel penetration. Pfizer Inc. represents the scale-driven pharmaceutical conglomerate tier, leveraging existing antibiotic manufacturing infrastructure. These three anchors illustrate divergent strategic postures: specialization versus integration versus scale.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Bayer AG |
| Johnson & Johnson |
| GlaxoSmithKline plc |
| Sanofi S.A. |
| Galderma S.A. |
| AbbVie Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Bausch Health Companies Inc. |
| Others |
Cost & Logistics Intelligence
The Shanghai-to-Los Angeles maritime corridor carries retinoid active pharmaceutical ingredients and benzoyl peroxide precursors at freight rates that directly compress margin pools for Western formulators while enabling three-tier pricing stratification across premium dermatology-directed, standard retail pharmacy, and economy generic tiers.
Pricing Analysis
Industrial OEM buyers anchor subscription-based replenishment models that capture recurring revenue through 90-day auto-refill programs. Pricing stratifies across premium photostable retinoid formulations, standard antibiotic combinations, and economy benzoyl peroxide generics based on encapsulation technology sophistication and FDA approval pathway. Cost compression in the generic tier is intensifying because Indian and Chinese manufacturers exploit abbreviated approval pathways. Cash-pay adolescent patients in United States mass retail channels exhibit highest price sensitivity, while insured adult females in urban dermatology practices show lowest elasticity.
Supply Chain Analysis
Upstream feedstock production of adapalene, tretinoin, and clindamycin concentrates in Jiangsu and Zhejiang provinces of China and Hyderabad's Genome Valley in India. Finished formulation depends on photostable packaging materials from German specialty suppliers and dissolution testing equipment from Swiss analytical firms. Single-source vulnerability in retinoid encapsulation technology creates bottleneck risk for Western formulators seeking tolerability improvements. Distribution runs through wholesale pharmaceutical distributors to retail pharmacies, with direct-to-consumer platforms capturing fastest channel expansion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acne treatment market sits in early-cycle expansion as telehealth platforms penetrate rural United States cohorts previously excluded from dermatology access, compressing time-to-treatment initiation and expanding addressable patient populations.
For Market Incumbents: Pre-empt generic erosion in topical antibiotic combinations by accelerating fixed-dose combination submissions through FDA's streamlined pathways. Secure backward integration into photostable packaging capabilities to defend margin position against supply chain disruption. Counter emerging direct-to-consumer brands through physician-directed sampling programs that reinforce clinical channel loyalty. For New Entrants and Emerging Players: Pursue hormonal therapy white space in adult female androgen-driven presentations, where underdiagnosis relative to adolescent cohorts leaves demand unconverted. Target Brazil's expanding dermatology clinic networks through ANVISA-aligned registration strategies. Deploy influencer partnerships on visual platforms as primary patient acquisition channel, bypassing traditional physician referral infrastructure. For Investors and Strategic Acquirers: Contract development organizations with specialized retinoid stability expertise represent priority acquisition targets as formulation complexity concentrates analytical chemistry capabilities among limited partners. Long-term viability hinges on exposure to device-drug convergence and subscription commerce models. Monitor FDA guidance evolution on fixed-dose combination quality requirements as inflection signal for pipeline advancement versus reformulation investment.| Strategic Initiative | Industry Significance |
|---|---|
| Telehealth Platform Partnership | HIPAA-compliant virtual consultation extends prescription-grade access to rural United States cohorts. |
| Retinoid Encapsulation Scale-Up | Novel tolerability technologies expand addressable populations beyond traditional adolescent demographics. |
| Fixed-Dose Combination Submission | FDA streamlined pathways compress development timelines for multi-mechanism acne formulations. |
| Subscription Commerce Launch | Direct-to-consumer auto-refill models capture recurring revenue and reduce patient discontinuation rates. |
| Sustainability Certification Program | EPA discharge standard compliance rewards early adopters with institutional procurement advantages. |
Research Approach
Initial hypotheses were tested against primary input from dermatology practice administrators, pharmaceutical regulatory affairs leads, formulary directors at United States commercial payers, and telehealth platform operators, then refined through secondary validation against FDA filings, EMA submission databases, ClinicalTrials.gov records, and hospital procurement contract repositories. Bottom-up patient volume estimates and top-down pharmaceutical revenue triangulation anchored segmentation modeling.
Demand-supply-balance framing structured the analytical approach across the projection horizon. Segmentation dimensions included product type, therapy severity stratification, end-user channel, and regional regulatory cluster. CAGRs were derived from modeled prescription volume trajectories and average selling price evolution, incorporating telehealth penetration curves, isotretinoin REMS compliance cost inflation, and antibiotic resistance formulary restriction patterns as industry-specific inputs.
Macroeconomic conditions sit as an overlay; deviation in United States insurance coverage expansion, Chinese environmental enforcement intensity, or Indian PLI scheme continuation would shift the trajectory. Forecasts reflect documented assumptions on patient adherence rates and generic substitution elasticity. Cross-checking against CMS Medicare Part D utilization data and IQVIA prescription audit benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Skincare
Cosmeceutical Ingredients Market
Skincare
Germany Skincare Product Market
Skincare
Europe Functional Cosmetics Market
Skincare
Skincare Serums Market
Skincare
Organic Skincare Products Market
Skincare
Biocellulose Mask Market
Skincare
Tinted Sunscreen Market
Skincare
Facial Mask Market
Skincare
Body Scrub Market
Skincare
ASEAN Sensitive Skin Care Market
Skincare
Facial Skincare Market
Skincare
Skin Resurfacing Market
Skincare
Global Healthcare Wipes Market
Skincare
Vitamin C Serum Market
Skincare
CBD Skincare Products Market
Skincare
Sun-Care Wipes Market