
 Photorejuvenation Devices Market | 2026-2036
Photorejuvenation Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Photorejuvenation Devices Market Analysis
ISO 13485 certification for medical device quality management is bifurcating the competitive landscape into qualified manufacturers and aspirants lacking audit-ready systems. Lumenis leverages decades of laser platform development to sustain installed-base loyalty across dermatology practices. Alma Lasers anchors its position through direct service infrastructure in key European and Middle Eastern markets. Cutera competes by specializing in multi-wavelength platforms that address diverse skin phototypes.
Photorejuvenation devices are systems that deliver controlled optical or radiofrequency energy to dermal and epidermal tissues, typically operating at wavelengths between 500 nm and 1200 nm for selective photothermolysis of chromophores. These systems serve the commercial purpose of non-ablative skin resurfacing, collagen remodeling, and lesion reduction without the recovery periods associated with surgical intervention. Laser devices command the dominant share of product-type revenue due to their precision and established reimbursement coding in medical settings, while radiofrequency devices represent the fastest-expanding category as combination protocols with microneedling gain clinical acceptance. Among end users, dermatology centers capture the highest per-site equipment spend, though beauty salons are emerging as volume outlets for lower-intensity LED and IPL systems.
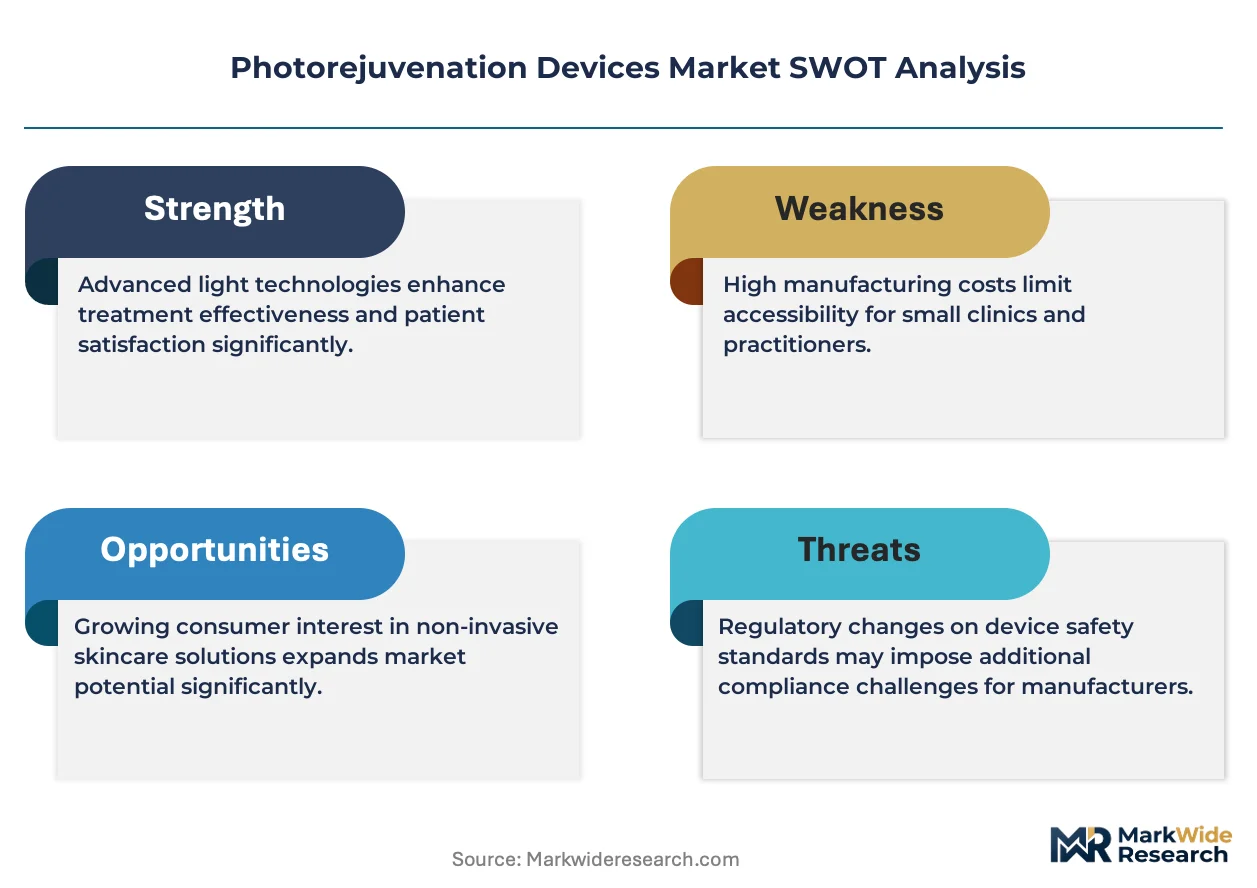
FDA 510(k) premarket notification requirements and the EU MDR's tightened clinical evidence standards for active medical devices are extending development timelines and raising capital barriers for new entrants. The EPA regulates mercury-containing lamps used in some IPL systems, pushing manufacturers toward solid-state and LED-based architectures. South Korea's MFDS maintains stringent electromagnetic compatibility testing that shapes export-ready product configurations for Asia-Pacific distribution. Stakeholders must monitor evolving state-level scope-of-practice regulations that determine whether non-physician operators can deploy energy-based devices, as these rules directly affect addressable clinic and salon populations.
Market Dynamics
Energy-based aesthetic medicine is consolidating around dual-wavelength platforms that merge fractional laser delivery with real-time skin temperature monitoring, compressing treatment protocols while elevating safety thresholds.
Growth Catalysts
- Non-surgical procedure volume:Dermatology centers in the United States, Germany, and South Korea report rising patient throughput for collagen induction therapies without ablative downtime.
- MFDS electromagnetic standards:South Korea's stringent compatibility testing protocols are accelerating export-ready product development for Asia-Pacific distribution.
- LED solid-state architectures:Replacement of mercury-containing IPL lamps under EPA pressure is driving platform refreshes across installed bases.
Market Restraints
- Capital intensity:Multi-wavelength systems require substantial upfront investment, limiting procurement frequency to 5-7 year replacement cycles.
- Clinical evidence burdens:EU MDR tightened standards for active medical devices extend premarket timelines and raise documentation costs for light-based systems.
- Substitute modalities:Topical retinoid and peptide formulations capture budget-conscious segments seeking lower-cost skin rejuvenation alternatives.
Strategic Opportunities
- Beauty salon channel expansion:Lower-intensity LED and IPL systems are penetrating non-medical settings where scope-of-practice regulations permit operator delegation.
- Combination protocol adoption:Radiofrequency-microneedling convergence is opening new treatment indications beyond traditional photorejuvenation applications.
- ISO 13485 certification gap:Qualified manufacturers can capture share from aspirants lacking audit-ready quality management systems.
Industry Challenges
- Service infrastructure scaling:Direct technical support networks must expand to match device deployment velocity across dispersed clinic populations.
- 510(k) pathway navigation:FDA premarket notification requirements for novel wavelength combinations create unpredictable clearance timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Photorejuvenation Devices Market |
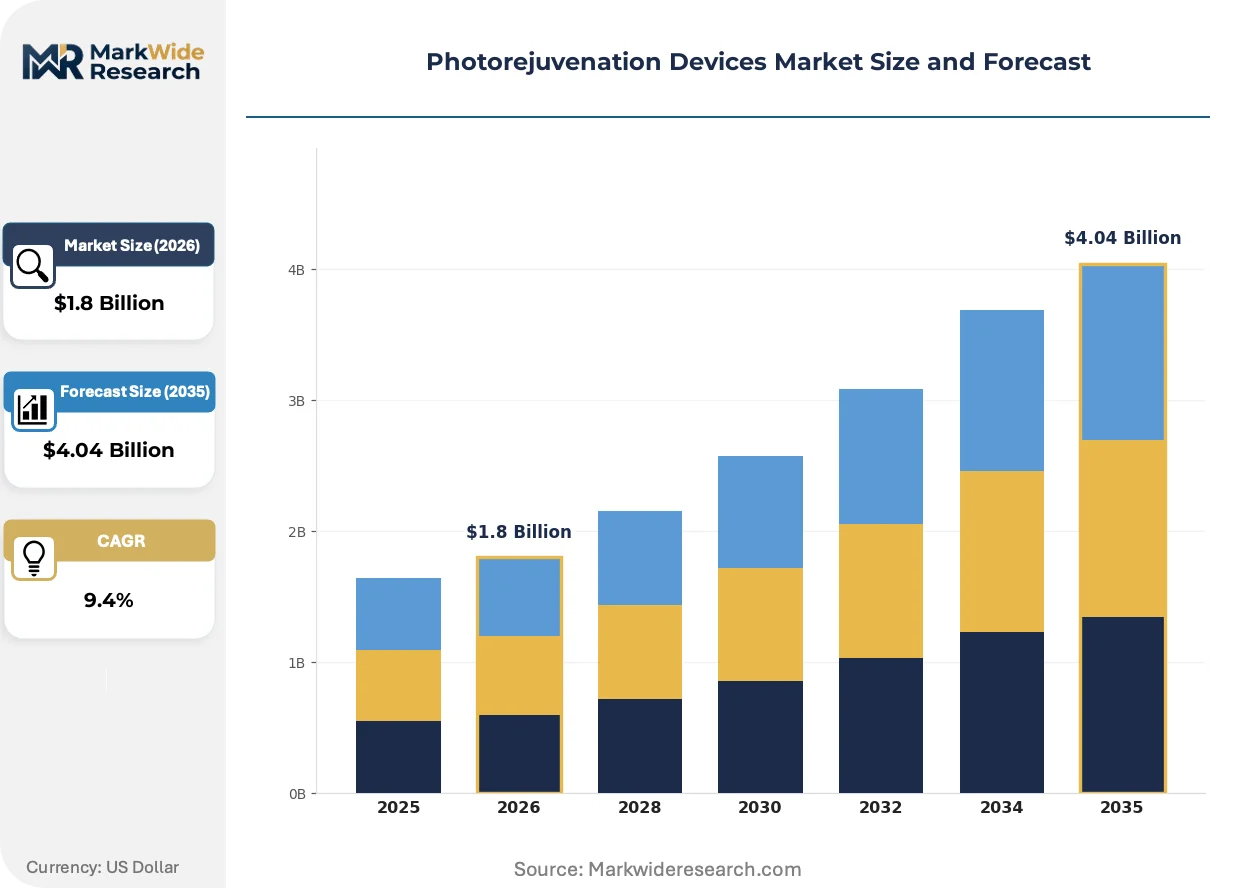
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Devices, Intense Pulsed Light, Radiofrequency Devices, Light Emitting Diodes End User: Clinics, Dermatology Centers, Beauty Salons, Home Users Technology: Non-Ablative, Ablative, Fractional, Hybrid Application: Skin Tightening, Acne Scarring, Pigmentation Removal, Vascular Lesion Treatment |
| Companies Covered | Lumenis, Cynosure, Cutera, Fotona, Candela Corporation, Alma Lasers, Lutronic Corporation, Asclepion, Lynton Lasers Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Photorejuvenation Devices Market Emerging Trajectories
Photorejuvenation platforms are converging with diagnostic imaging and automated parameter adjustment, transforming standalone energy delivery into closed-loop therapeutic systems.
Dual-wavelength laser architectures are bifurcating the equipment landscape into precision medical-grade systems and accessible salon-grade alternatives. Dermatology practices with established reimbursement relationships are consolidating procurement around platforms offering real-time epidermal temperature feedback. This technology compression is enabling shorter treatment intervals while reducing adverse event liability exposure.
EU MDR clinical evidence standards are reshaping development economics for active aesthetic devices. Manufacturers must now compile substantially larger safety datasets before CE marking authorization. Light-based systems with novel chromophore targets face the steepest compliance burden, prompting some developers to prioritize 510(k) clearance sequencing in the United States.
After-sales service unbundling is altering capital deployment patterns among mid-sized dermatology groups. Rather than bundled maintenance contracts, buyers are negotiating component-level service agreements with third-party biomedical technicians. This procurement fragmentation is most pronounced in Germany, where independent service provider networks have achieved critical density.
Photorejuvenation Devices Market Segmentation
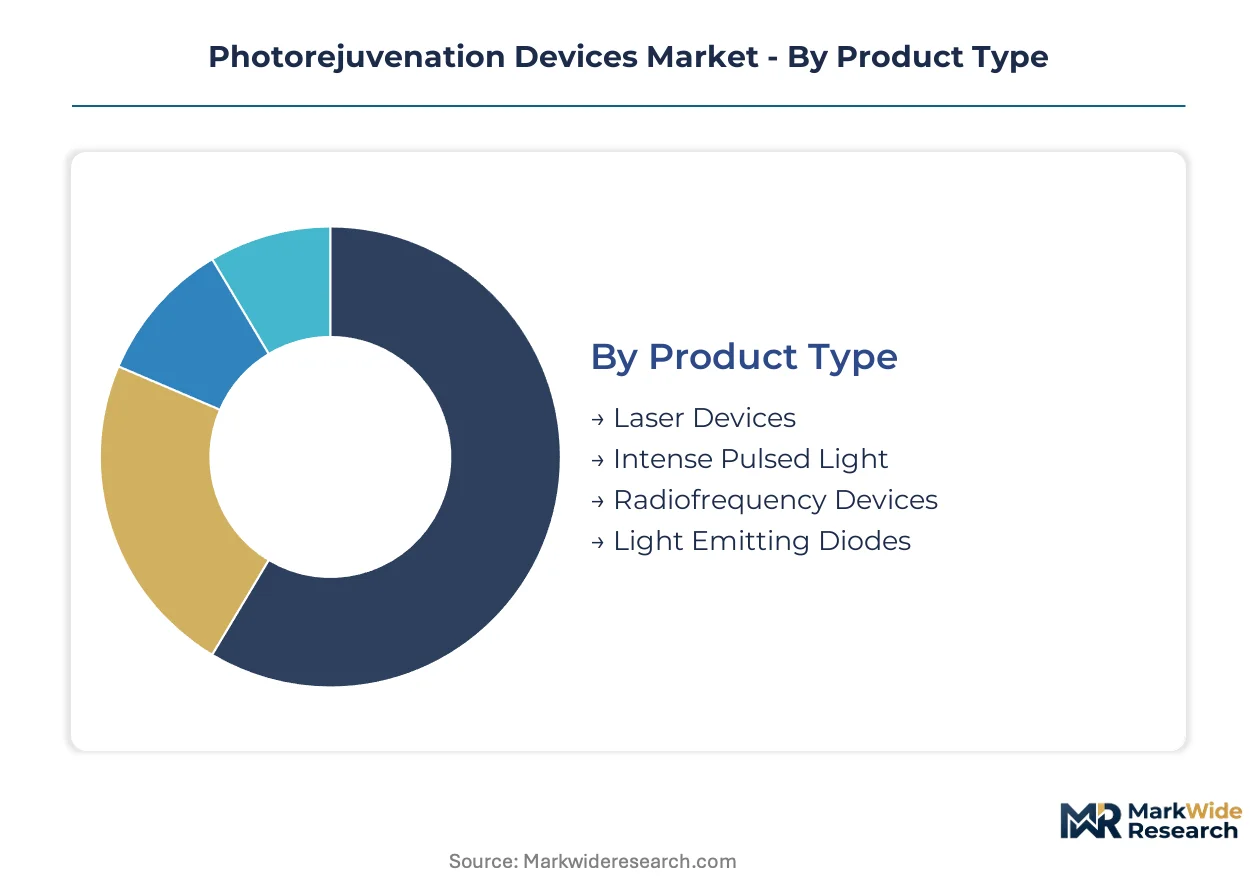
Photorejuvenation device segmentation reveals divergent commercial strategies across medical and consumer channels. Manufacturers configure wavelength architectures, energy delivery modes, and operator interfaces to match distinct regulatory environments and reimbursement conditions.
Product Type:
Laser platforms dominate domestic procurement in the United States and Germany, while radiofrequency and LED systems drive export volume to Asia-Pacific and Middle Eastern markets.
- Laser Devices:Solid-state and diode-pumped configurations deliver precise chromophore targeting through tunable wavelengths between 500 nm and 1200 nm. United States dermatology centers with established reimbursement coding for medical-grade procedures account for concentrated demand, though capital intensity restricts replacement cycles to 5-7 years.
- Radiofrequency Devices:These systems generate dermal heating through electromagnetic energy rather than optical absorption, enabling safer application across diverse skin phototypes. South Korean clinics and export markets across Southeast Asia are absorbing capacity fastest as combination protocols with microneedling gain clinical validation.
- Intense Pulsed Light:Broadband flashlamp systems address multiple chromophores simultaneously through filtered emission spectra.
- Light Emitting Diodes:Solid-state architectures eliminate mercury-containing components under EPA regulatory pressure.
Laser devices hold the largest share; momentum sits with radiofrequency platforms.
End User:
Capital deployment patterns bifurcate between high-intensity medical settings and lower-intensity consumer-accessible channels.
- Dermatology Centers:These facilities command the highest per-site equipment spend, prioritizing multi-wavelength platforms with real-time temperature monitoring and documented clinical efficacy. German and South Korean centers are consolidating procurement around systems with EU MDR and MFDS pre-certification to streamline cross-border service support.
- Clinics:Mid-sized medical practices balance reimbursement eligibility against capital constraints, favoring lease-financed platforms with bundled maintenance.
- Beauty Salons:Scope-of-practice regulations in Texas, Florida, and select German Länder permit non-physician operators to deploy lower-intensity LED and IPL systems.
- Home Users:Consumer-grade devices with simplified interfaces and reduced energy output are penetrating direct-to-consumer channels.
Dermatology centers generate the highest revenue per installation; beauty salons are expanding addressable volume fastest.
Technology:
Clinical evidence requirements under EU MDR and FDA 510(k) pathways are concentrating development investment in hybrid and fractional architectures.
- Fractional:Microthermal zone delivery preserves surrounding tissue for accelerated recovery while maintaining collagen remodeling efficacy. United States-based device developers are prioritizing 510(k) clearance sequencing for fractional platforms given established predicate device pathways.
- Hybrid:Simultaneous or sequential delivery of multiple energy modalities addresses complex presentations like acne scarring with pigmentation. South Korean manufacturers are exporting hybrid configurations with integrated cooling systems to meet MFDS electromagnetic compatibility standards for Asia-Pacific distribution.
- Non-Ablative:Epidermal-sparing energy delivery enables minimal-downtime protocols.
- Ablative:Full-th resurfacing maintains niche positioning for severe photodamage cases.
Fractional technology commands installed-base loyalty; hybrid systems are climbing the fastest.
Application:
Reimbursement coding availability and patient self-pay willingness shape geographic concentration across treatment indications.
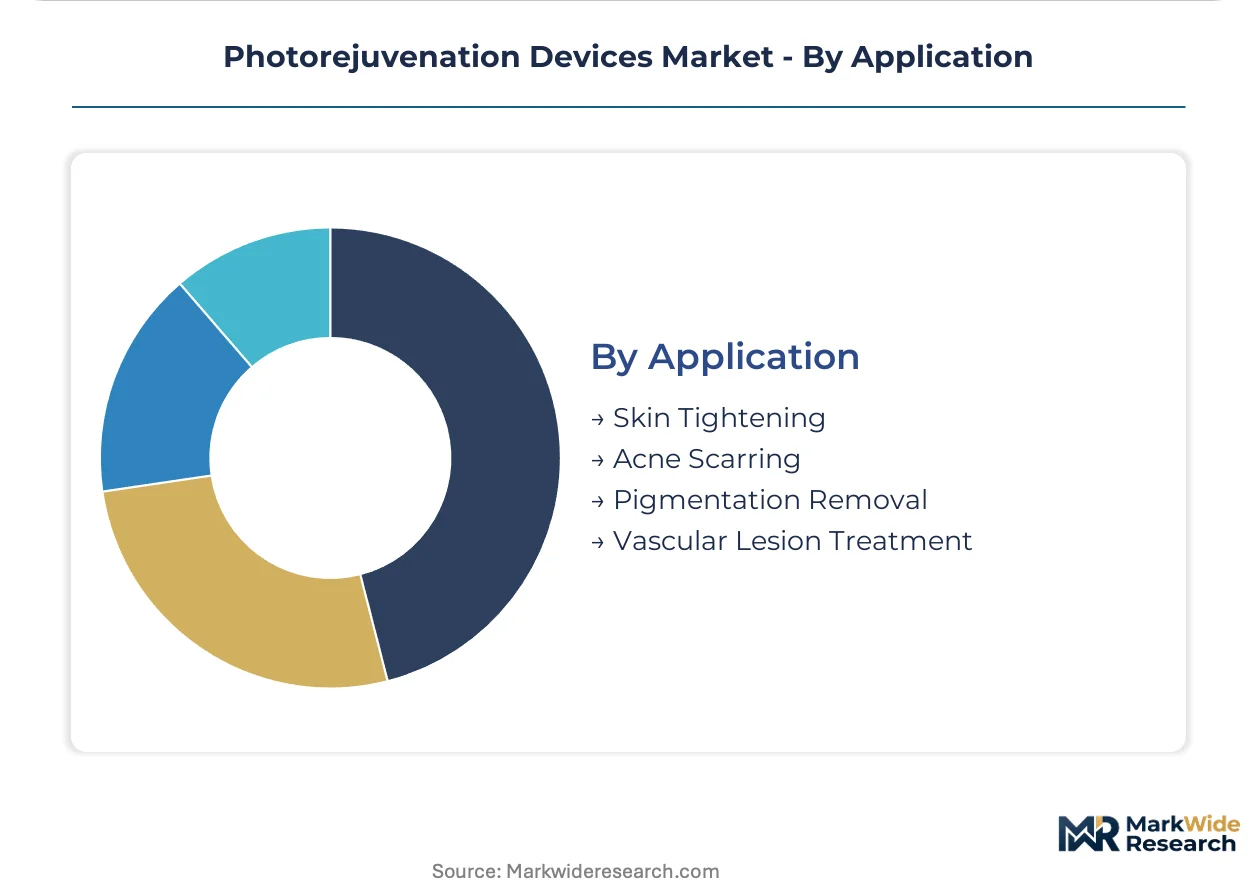
- Skin Tightening:Non-surgical collagen induction for facial and neck laxity represents the highest-volume indication, with demand concentrating in affluent urban markets across the United States, Germany, and South Korea where disposable income supports premium per-session pricing.
- Acne Scarring:Fractional and hybrid modalities address atrophic and hypertrophic scar variants through controlled dermal remodeling. German dermatology centers are adopting combination protocols fastest given favorable statutory health insurance positioning for functional scar revision.
- Pigmentation Removal:Selective photothermolysis of melanin targets solar lentigines and melasma.
- Vascular Lesion Treatment:Hemoglobin-selective wavelengths address telangiectasia and port-wine stains.
Skin tightening holds the largest share; acne scarring applications are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reimbursement coding expansions for non-ablative procedures in the United States are accelerating clinic procurement cycles. Germany's statutory health insurance positioning for functional scar revision is elevating multi-wavelength platform demand. South Korea's MFDS electromagnetic compatibility standards are reshaping export-ready product configurations across Asia-Pacific distribution channels.
United States
Dermatology centers in metropolitan clusters report rising patient throughput for collagen induction therapies without ablative downtime. FDA 510(k) premarket notification requirements for novel wavelength combinations create unpredictable clearance timelines that extend development schedules. The Greater Boston and Pacific Northwest corridors concentrate early adoption of fractional platforms with real-time epidermal temperature feedback systems.
Germany
Independent service provider networks achieving critical density are fragmenting after-sales procurement patterns among mid-sized dermatology groups. EU MDR tightened clinical evidence standards for active medical devices extend premarket timelines and raise documentation costs. The Bavaria and North Rhine-Westphalia regions anchor consolidated procurement around systems with EU MDR pre-certification to streamline cross-border service support.
South Korea
Clinics and export markets across Southeast Asia are absorbing radiofrequency capacity fastest as combination protocols with microneedling gain clinical validation. MFDS electromagnetic compatibility testing protocols are accelerating export-ready product development for Asia-Pacific distribution. The Seoul Capital Area and Busan-Ulsan corridor dominate hybrid configuration manufacturing with integrated cooling systems.
United Kingdom
Beauty salons in England are penetrating non-medical settings where scope-of-practice regulations permit operator delegation for lower-intensity LED and IPL systems. CE marking under the EU MDR tightens premarket requirements for light-based systems despite post-Brexit regulatory divergence. The London/Southeast cluster concentrates premium device uptake driven by clinic density and disposable income thresholds.
Japan
Consumer-grade devices with simplified interfaces and reduced energy output are penetrating direct-to-consumer channels among home users. METI standards for active medical devices shape domestic certification requirements that influence regional export specifications. The Kanto/Tokyo metropolitan area anchors demand concentration for non-surgical aesthetic procedures with minimal recovery protocols.
Photorejuvenation Devices Market Vendor Landscape
Player mix skews toward established laser platform developers with decades of installed-base relationships across dermatology practices. The competitive structure concentrates around manufacturers possessing direct service infrastructure in key European and Middle Eastern markets. Two strategic archetypes dominate: multi-wavelength platform specialists addressing diverse skin phototypes, and quality-management-qualified manufacturers capturing share from aspirants lacking ISO 13485 audit-ready systems. Dominant competitive moves include geographic expansion through direct technical support networks and portfolio diversification into combination radiofrequency-microneedling protocols.
Within the established developer tier, Lumenis leverages installed-base loyalty across dermatology practices, while Alma Lasers anchors positioning through direct service infrastructure. Cutera occupies a specialization position in multi-wavelength configurations. These three exemplify how decades of laser platform development and quality management certification bifurcate competitive positioning between qualified manufacturers and market aspirants.
| Leading Market Players |
|---|
| Lumenis |
| Cynosure |
| Cutera |
| Fotona |
| Candela Corporation |
| Alma Lasers |
| Lutronic Corporation |
| Asclepion |
| Lynton Lasers Ltd |
| Others |
Supply Flow & Price Mechanics
EU MDR clinical evidence standards gate both supply qualification and price differentiation, forcing manufacturers to absorb documentation costs into premium-tier positioning while audit-ready ISO 13485 certification becomes a non-negotiable threshold for procurement eligibility. This regulatory bifurcation concentrates pricing power among qualified manufacturers while aspirants compete on stripped-down configurations.
Pricing Analysis
Cost-plus contracts with semiconductor component indexation dominate procurement between dermatology centers and device manufacturers. Pricing stratifies across premium, standard, and economy tiers based on ISO 13485 certification status and bundled after-sales service depth. Cost compression in the standard tier intensifies as third-party biomedical technicians unbundle maintenance agreements. Price-sensitive beauty salons drive volume at the economy tier, while dermatology centers with established reimbursement coding exhibit lowest sensitivity to per-unit hardware pricing.
Supply Chain Analysis
Inbound logistics costs through the Busan-Ulsan corridor and Rotterdam-Antwerp gateway shape landed cost structures for solid-state laser components. Manufacturing concentrates in South Korea, Germany, and the United States for precision optical assemblies and diode-pumped configurations. Supply chains draw from gallium arsenide wafer foundries, medical-grade aluminum extrusions, and FDA-compliant cooling system components. Single-source vulnerability sits with specialized optical coating suppliers. Distribution runs through direct manufacturer service infrastructure in key markets alongside third-party biomedical equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Photorejuvenation device economics increasingly hinge on recurring service revenue layers expanding faster than hardware replacement cycles, with component-level maintenance agreements and software upgrade subscriptions capturing margin expansion unavailable in capital equipment sales alone.
For Market Incumbents: Consolidate installed-base loyalty through predictive maintenance software integration and exclusive spare parts provisioning that locks out independent service providers. Expand direct technical support density in Germany's fragmented aftermarket where third-party biomedical technicians are unbundling contracts. Deepen backward integration into solid-state laser diode production to offset semiconductor supply volatility. For New Entrants and Emerging Players: After-sales service gaps in Southeast Asia's emerging clinic networks offer white-space entry points where incumbent infrastructure remains thin. Target mid-sized dermatology groups in South Korea's secondary cities seeking MFDS-certified platforms with localized training support. Pursue lease-financed go-to-market structures that lower capital barriers against established competitors. For Investors and Strategic Acquirers: EU MDR implementation timelines reshape the acquisition landscape toward quality-management-qualified manufacturers with audit-ready systems and predicate device portfolios. Long-term viability favors platforms with hybrid energy architectures and software companion development capabilities. Watch FDA 510(k) clearance velocity for novel wavelength combinations as an inflection signal for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Audit-ready quality management systems unlock procurement eligibility at dermatology centers and EU MDR market access. |
| Direct Service Infrastructure Expansion | Technical support networks in Germany and South Korea capture aftermarket revenue and lock out independent competitors. |
| Hybrid Platform Development | Simultaneous radiofrequency-microneedling configurations address acne scarring indications beyond traditional photorejuvenation. |
| Software Companion Integration | Real-time epidermal temperature monitoring and automated parameter adjustment transform hardware into closed-loop therapeutic systems. |
| Beauty Salon Channel Penetration | Lower-intensity LED and IPL systems penetrate non-medical settings where scope-of-practice regulations permit operator delegation. |
Methodological Framework
A spread of perspectives from dermatology center procurement directors, biomedical equipment distributors, regulatory affairs specialists at active medical device manufacturers, and third-party service technicians converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through FDA 510(k) premarket notification databases, EU MDR technical documentation filings, MFDS electromagnetic compatibility test records, and hospital procurement contract registries. Bottom-up equipment shipment analysis triangulated against top-down dermatology practice revenue segmentation.
Segmentation dimensions modeled span product type, end user, technology architecture, and application indication across the projection horizon. CAGRs derive from installed-base replacement cycle analysis, procedure volume elasticity to disposable income, and regulatory approval pathway timelines. Forecast inputs incorporate clinic density thresholds, reimbursement coding expansions for non-ablative procedures, and scope-of-practice regulation shifts affecting non-physician operator eligibility.
Underlying assumptions cover stable regulatory enforcement intensity, intact semiconductor supply chains for solid-state components, and continued patient preference for minimal-downtime protocols, with deviation risk concentrated in EU MDR documentation requirement escalations and state-level scope-of-practice liberalization reversals. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Surgical Tourniquets Market
Medical Devices
Graft Delivery Devices Market
Medical Devices
United Arab Emirates Drug Delivery Devices Market
Medical Devices
Spinal Fusion Market
Medical Devices
Europe Minimally Invasive Surgery Devices Market
Medical Devices
Implantable Medical Devices Market
Medical Devices
Artificial Eye Lenses Market
Medical Devices
Adsorption Apheresis Devices Market
Medical Devices
Ultrasonic Aspirator Market
Medical Devices
Europe Manual Resuscitators Market
Medical Devices
Flexible and Semi-Rigid Ureteroscopy Market
Medical Devices
Global Metal Implants and Medical Alloys Market
Medical Devices
Quadripodal Implants Market
Medical Devices
Global Implantable Loop Recorder Market
Medical Devices
Plethysmograph Market
Medical Devices
Patellar Implant Market