
 China Intrauterine Devices Market | 2026-2036
China Intrauterine Devices Market Size, Share, and Industry Trends Forecast 2026-2036
China Intrauterine Devices Market Insights
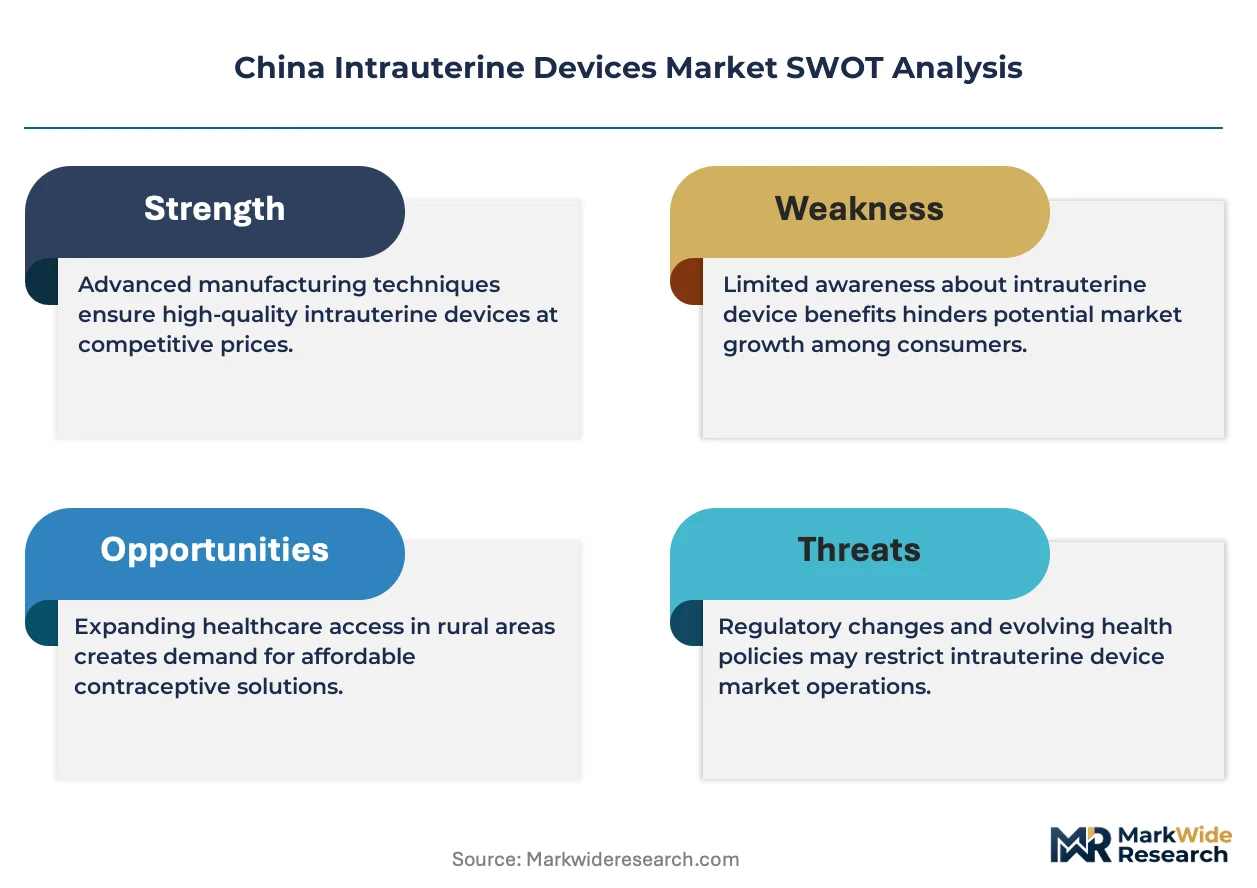
China's medical device registration reforms under NMPA are recalibrating the cost-of-entry calculus for IUD manufacturers seeking domestic market access. Bayer Healthcare leverages its hormonal IUD technology leadership to sustain premium positioning in tier-one hospital networks. Shanghai Dahua Medical Instrument Co. Ltd. anchors its competitive stance through deep manufacturing scale and entrenched distribution across provincial procurement platforms.
An intrauterine device is a small, T-shaped contraceptive implant inserted into the uterus, typically composed of copper wire or hormone-eluting polymers such as levonorgestrel-releasing systems, designed to prevent fertilization through spermicidal or endometrial modification mechanisms. The copper IUD segment dominates procurement volumes under China's national family planning program due to cost efficiency and long-acting reversible contraception utility. Hormonal IUD variants command higher margins in private women's health centers where patient out-of-pocket spending capacity exceeds public reimbursement ceilings.
NMPA device classification rules, GB standards for biocompatibility, and provincial centralized procurement mandates collectively shape product specifications and market access trajectories for domestic and imported IUD suppliers. The national health commission's family planning integration into maternal-child health systems tightens quality benchmarks while expanding institutional channel penetration. Stakeholders must monitor evolving provincial tender rules and reimbursement tier adjustments to anticipate volume shifts between public and private end-user segments.
Market Dynamics
China's three-child policy framework is restructuring demand architecture for long-acting reversible contraception, redirecting procurement volume toward hormonal IUD variants in tier-one hospital networks while copper devices retain dominance in county-level family planning stations.
Growth Catalysts
- NMPA registration reforms:Streamlined Class III medical device approval pathways are compressing time-to-market for domestic manufacturers seeking provincial tender eligibility.
- Eastern coastal infrastructure:Concentrated family planning service networks in Jiangsu, Zhejiang, and Guangdong provinces generate sustained institutional demand for premium IUD insertion services.
- Hormone-eluting polymer advancement:Levonorgestrel-releasing system improvements are expanding clinical indications beyond contraception into therapeutic gynecological applications.
Market Restraints
- Copper commodity volatility:Raw material price fluctuations for copper wire cores directly impact manufacturing cost structures for domestic producers serving mass-market segments.
- Provincial procurement fragmentation:Decentralized tender processes across 31 provincial-level administrative units create compliance complexity and margin compression for multi-regional suppliers.
- Surgical contraception substitution:Tubal ligation procedures in rural health centers compete for family planning budget allocations despite reversibility advantages of IUD technology.
Strategic Opportunities
- Central and western province penetration:Henan, Sichuan, and Shaanxi provinces exhibit underdeveloped private women's health center density relative to eastern benchmarks.
- Telemedicine consultation integration:Digital health platforms are creating novel patient acquisition channels for pre-insertion counseling and post-placement follow-up services.
- GB biocompatibility standard harmonization:Alignment with international ISO 10993 testing protocols positions domestic manufacturers for export market qualification.
Industry Challenges
- Specialized insertion technician scarcity:Certified gynecological practitioners capable of complex hormonal IUD placement remain concentrated in tertiary hospital systems.
- Legacy copper device inventory rationalization:Provincial procurement platforms face working capital strain from obsolete stock rotation amid technology transition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Intrauterine Devices Market |
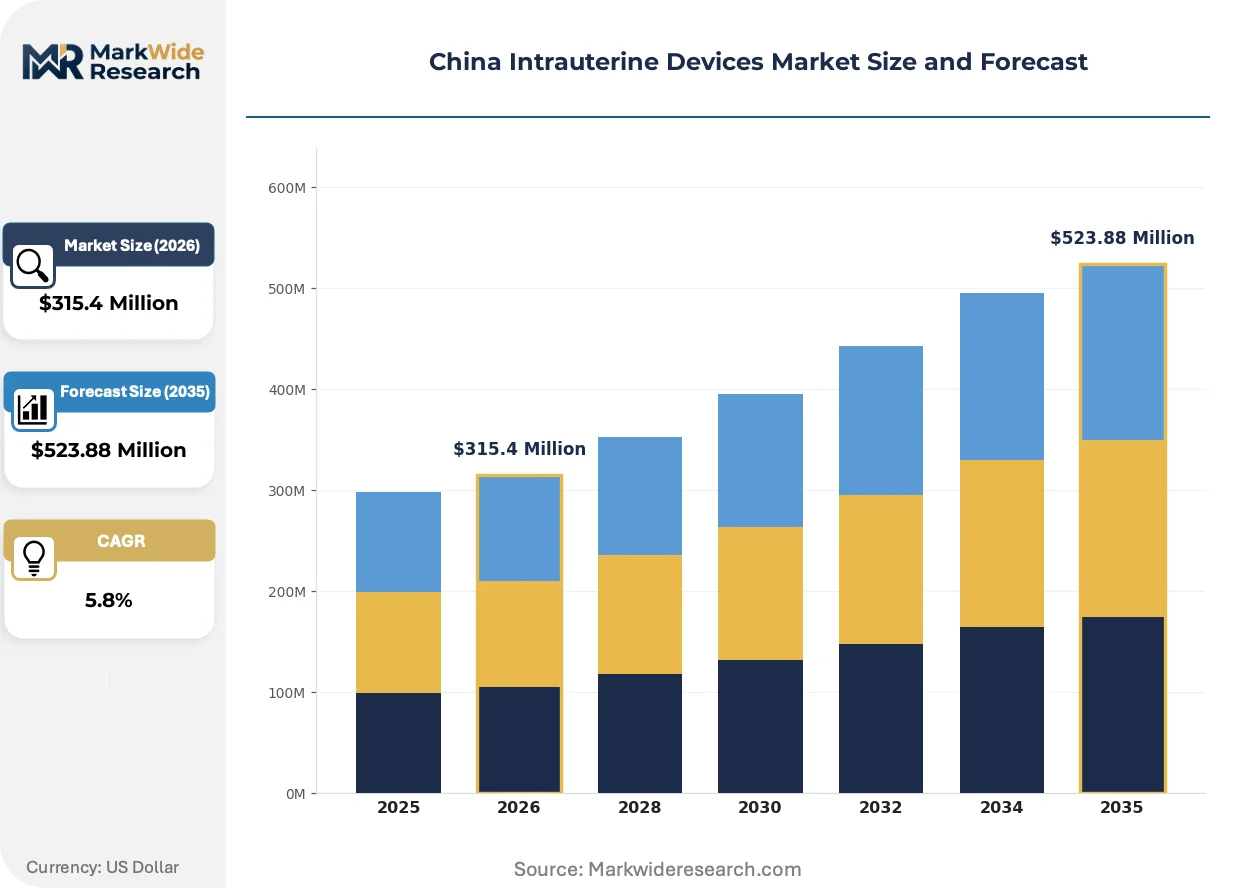
| Market Size in 2026 | $315.4 Million |
| Market Size in 2035 | $523.88 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Copper IUD, Hormonal IUD, Levonorgestrel-releasing IUD, Non-medicated IUD Application: Contraception, Endometriosis Management, Postpartum Birth Control, Abnormal Uterine Bleeding Control End User: Gynecologists, Family Planning Clinics, Women’s Health Centers, Community Health Providers Distribution Channel: Hospitals, Pharmacies, Online Pharmacies, Medical Device Distributors, Clinics |
| Companies Covered | Bayer Healthcare, Cooper Surgical Inc., GUANGZHOU ICLEAR HEALTHCARE LIMITED, DKT International, Shanghai Dahua Medical Instrument Co. Ltd., Merck & Co. Inc., Teva Pharmaceutical Industries Ltd, Reckitt Benckiser, AbbVie Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Intrauterine Devices Market Trends and Innovations
Active pharmaceutical ingredient integration and digital health convergence are redefining product differentiation vectors, shifting competitive emphasis from device mechanics toward sustained-release pharmacology and patient monitoring ecosystems.
Levonorgestrel-eluting intrauterine systems with reduced bleeding profiles are overtaking conventional copper T-shaped devices in municipal hospital procurement catalogs. Tier-one gynecology departments in Beijing and Shanghai are prioritizing hormonal variants for patient retention. This transition is compressing average selling prices for legacy copper manufacturers while expanding service revenue from insertion procedure bundling.
GB standards for biocompatibility testing are tightening substrate qualification requirements for polymer-based IUD frames. NMPA device classification rules now mandate extended cytotoxicity evaluation protocols for new hormonal formulations. Domestic manufacturers with in-house toxicology laboratories are accelerating registration timelines relative to outsourced testing dependencies.
Patient self-referral patterns through private women's health chains are fragmenting traditional public hospital channel concentration. Digital appointment platforms in Shenzhen and Hangzhou are disintermediating provincial family planning station networks for initial consultation capture. This behavioral shift is most pronounced among urban cohorts aged 25-35 seeking reversible contraception with minimal administrative friction.
China Intrauterine Devices Market Segmentation
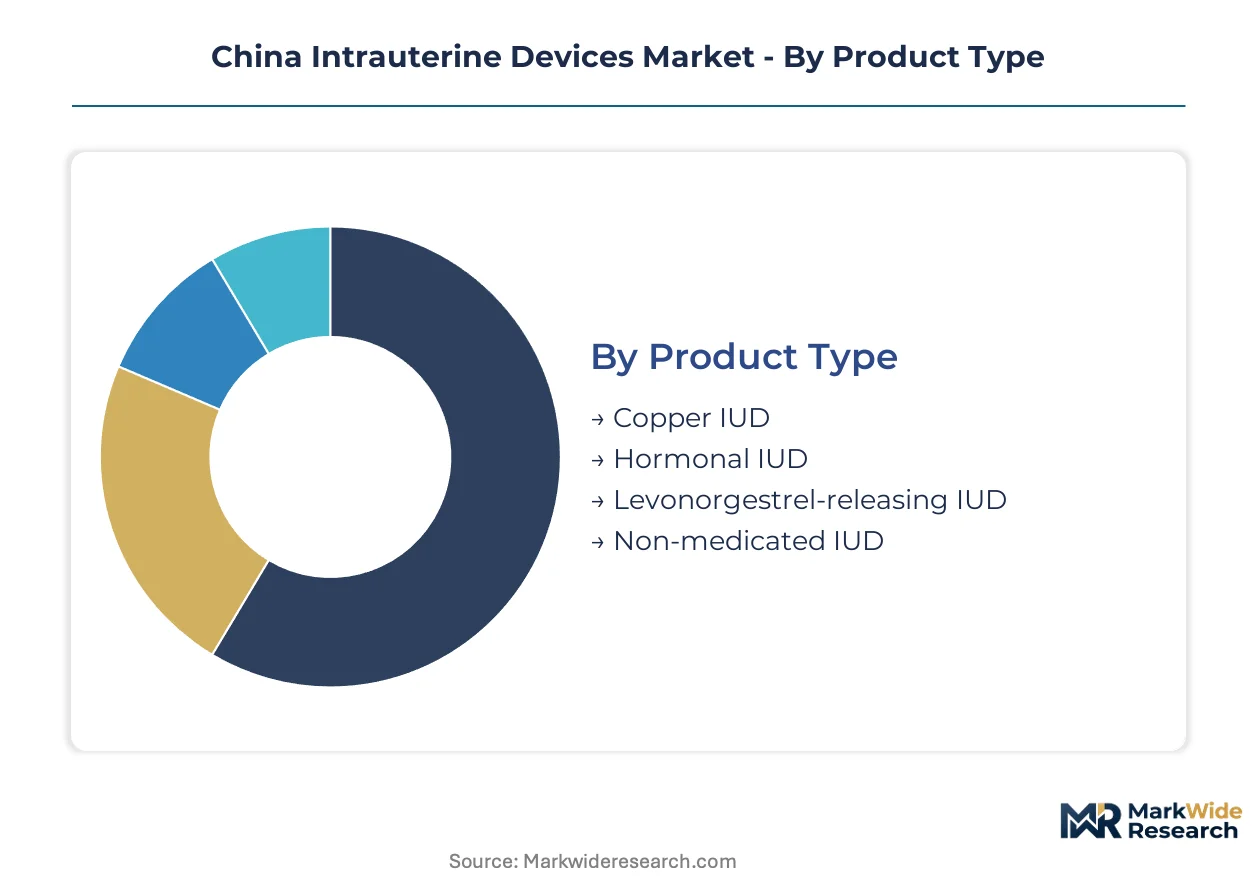
IUD market segmentation in China reflects divergent procurement logics across public health infrastructure and private clinical settings. Product type and end-user channel configurations determine margin structures, regulatory pathways, and competitive positioning for domestic and multinational suppliers.
Product Type:
Cost tier separates mass-market copper devices from premium hormone-eluting systems in provincial tender catalogs.
- Copper IUD:T-shaped polyethylene frames wrapped with copper wire deliver spermicidal ion release over 5-10 year lifespans. County-level family planning stations in Henan and Sichuan provinces drive procurement volumes under national reimbursement ceilings.
- Hormonal IUD:Levonorgestrel-eluting polymer systems modify endometrial lining to prevent implantation while reducing menstrual bleeding. Municipal hospitals in Shanghai and Beijing prioritize these variants for patient retention and procedure bundling revenue.
- Levonorgestrel-releasing IUD:Sustained-release formulations with 52mg reservoir capacity target therapeutic gynecological indications beyond contraception.
- Non-medicated IUD:Inert stainless steel or plastic devices serve cost-sensitive segments in rural western provinces with limited pharmaceutical logistics.
Copper IUD leads volumes today; hormonal IUD is gaining share fastest.
Application:
Clinical indication breadth determines pricing flexibility and specialist referral patterns across hospital tiers.
- Contraception:Primary indication accounting for institutional procurement under family planning program mandates. Public health stations in Jiangsu province distribute copper variants through centralized tender.
- Endometriosis Management:Hormonal IUDs suppress ectopic endometrial tissue growth, expanding addressable market into gynecological therapeutics. Tertiary hospital departments in Guangdong prescribe these for pain management.
- Postpartum Birth Control:Immediate post-delivery insertion protocols in maternity hospitals create captive placement opportunities.
- Abnormal Uterine Bleeding Control:Levonorgestrel systems reduce heavy menstrual bleeding, qualifying for partial reimbursement under maternal-child health integration.
Contraception dominates absolute demand; endometriosis management expands the addressable patient pool most aggressively.
End User:
Credential requirements and reimbursement eligibility fragment channel access for device manufacturers.
- Gynecologists:Certified specialists in tertiary hospitals command premium pricing for complex hormonal IUD placement. Beijing Union Medical College Hospital specialists perform high-margin insertion procedures.
- Family Planning Clinics:Government-operated stations in Zhejiang province distribute copper devices under national program quotas with thin margins.
- Women's Health Centers:Private chains in Shenzhen and Hangzhou attract self-pay patients through digital appointment platforms.
- Community Health Providers:Township-level clinics in rural Shaanxi handle basic copper device insertion with limited specialist oversight.
Family planning clinics move the highest unit volumes; women's health centers deliver the steepest margin expansion.
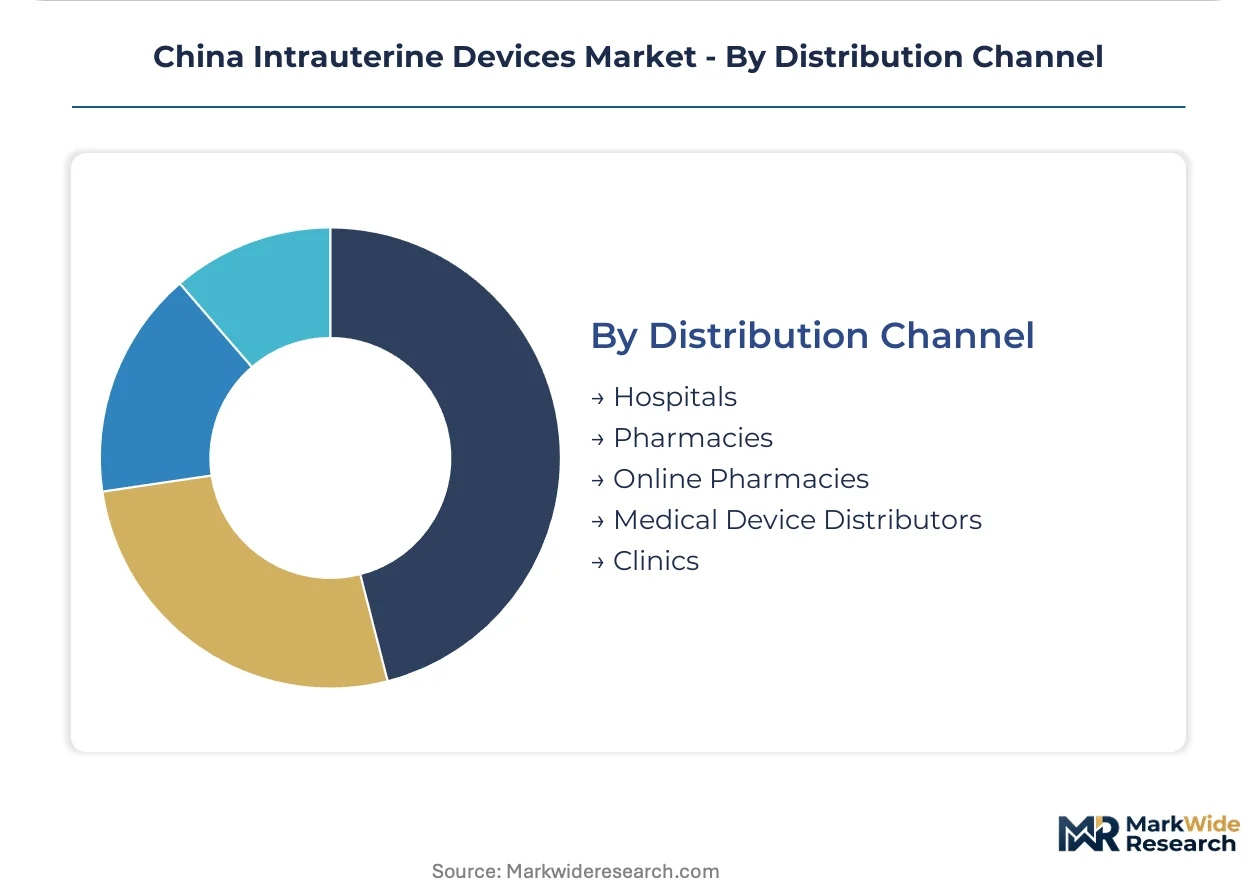
Distribution Channel:
Procurement authority concentration shapes vendor selection criteria and contract duration.
- Hospitals:Provincial centralized procurement platforms in Jiangsu and Guangdong govern tender participation for tier-one and tier-two facilities. NMPA Class III registration is mandatory for catalog inclusion.
- Pharmacies:Retail drugstores in urban centers stock emergency contraception but rarely carry prescription IUDs due to insertion protocol requirements.
- Online Pharmacies:Alibaba Health and JD Health platforms facilitate pre-insertion consultation booking rather than direct device sales.
- Medical Device Distributors:Regional logistics specialists like Shanghai Dahua's affiliate network manage provincial tender fulfillment and inventory rotation.
- Clinics:Private women's health chains in Chengdu and Xi'an source hormonal IUDs through direct manufacturer agreements bypassing public procurement.
Hospitals anchor institutional procurement; medical device distributors mediate the deepest geographic penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified gynecological specialists cluster disproportionately in eastern coastal provinces, concentrating advanced hormonal IUD insertion capacity while county-level family planning stations across central and western regions manage copper device distribution under national program mandates.
Jiangsu Province
Nanjing and Suzhou municipal hospitals generate premium-tier demand for levonorgestrel-releasing systems through procedure bundling models. Provincial centralized procurement platforms under NMPA Class III registration requirements govern tender participation for tier-one facilities. The Yangtze River Delta manufacturing corridor supplies polymer frame components to domestic device assemblers operating under GB biocompatibility standards.
Guangdong Province
Shenzhen's private women's health chains attract self-pay patients through digital appointment platforms, fragmenting traditional public hospital channel concentration. The provincial health commission integrates family planning services into maternal-child health systems, tightening quality benchmarks for insertion protocols. Guangzhou's tertiary hospital networks prioritize hormonal IUD variants for therapeutic gynecological applications beyond contraception.
Zhejiang Province
Hangzhou's municipal procurement catalogs favor hormone-eluting systems with reduced bleeding profiles for patient retention strategies. Government-operated family planning stations distribute copper devices under national program quotas with thin margins. The province's medical device distributor networks mediate inventory rotation between manufacturers and county-level health centers.
Sichuan Province
Chengdu's private clinical chains source hormonal IUDs through direct manufacturer agreements bypassing public procurement platforms. Township-level clinics in rural western counties handle basic copper device insertion with limited specialist oversight. Provincial tender processes exhibit underdeveloped private women's health center density relative to eastern benchmarks.
Shaanxi Province
Xi'an's hospital procurement platforms face working capital strain from legacy copper device inventory rationalization amid technology transition. Community health providers in rural northern counties serve cost-sensitive segments with limited pharmaceutical logistics infrastructure. The province represents an expansion target for manufacturers seeking central province penetration beyond coastal saturation.
China Intrauterine Devices Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across China's IUD market, creating a tiered structure where multinational pharmaceutical-device hybrids anchor premium positioning while domestic manufacturers capture volume through provincial procurement scale. The vendor base separates into three strategic archetypes: hormone-eluting technology leaders, copper device mass-market fabricators, and regional distribution-integrated assemblers. Competitive moves concentrate on NMPA registration timeline acceleration and backward integration into polymer frame production to compress cost structures.
Among multinational hybrids with device-pharma portfolios, Bayer Healthcare and Merck & Co. Inc. occupy positions exemplifying premium-tier hormonal system positioning through sustained-release pharmacology expertise. Shanghai Dahua Medical Instrument Co. Ltd. anchors the domestic fabrication archetype with entrenched provincial distribution scale, while Cooper Surgical Inc. represents the specialized reproductive health device focus. GUANGZHOU ICLEAR HEALTHCARE LIMITED sits within the regional manufacturer tier serving cost-optimized procurement segments.
| Leading Market Players |
|---|
| Bayer Healthcare |
| Cooper Surgical Inc. |
| GUANGZHOU ICLEAR HEALTHCARE LIMITED |
| DKT International |
| Shanghai Dahua Medical Instrument Co. Ltd. |
| Merck & Co. Inc. |
| Teva Pharmaceutical Industries Ltd |
| Reckitt Benckiser |
| AbbVie Inc. |
| Others |
Pricing and Supply Chain Analysis
Levonorgestrel-eluting polymer advancement is compressing manufacturing cost curves for hormonal IUD variants while simultaneously concentrating production capacity among domestic manufacturers with captive pharmaceutical compounding capabilities. This technology transition rewards backward integration into active pharmaceutical ingredient synthesis, reshaping margin distribution between device fabricators and polymer suppliers across China's provincial procurement platforms.
Pricing Analysis
The bundled-vs-unbundled service split separates municipal hospital procurement from county-level family planning station distribution. Three-tier pricing structure across premium hormonal systems, standard copper devices, and economy non-medicated variants reflects NMPA Class III registration tier and insertion protocol complexity. Cost compression in copper IUD segments is intensifying because of raw material volatility and provincial tender price ceilings. County-level family planning stations exhibit highest price sensitivity; tertiary hospital gynecology departments accept premium positioning for therapeutic indications.
Supply Chain Analysis
Freight cost differentials between eastern coastal manufacturing clusters and central-western distribution endpoints shape inventory positioning strategies for provincial tender fulfillment. Domestic production concentrates in Jiangsu, Zhejiang, and Shanghai; polymer frame components and levonorgestrel API draw from specialized chemical manufacturing bases. Single-source vulnerability in pharmaceutical-grade polymer supply creates exposure to GB standard harmonization delays. Distribution runs through regional medical device logistics specialists managing provincial centralized procurement rotation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's IUD market functions as a stable compounder anchored by durable policy support for long-acting reversible contraception under evolving family planning frameworks.
For Market Incumbents: Anticipate margin compression in copper device segments by accelerating NMPA registration timelines for next-generation hormonal formulations. Defensive consolidation through backward integration into polymer frame production offsets raw material cost volatility. Channel control via exclusive distributor agreements in underpenetrated western provinces protects volume position against emerging domestic competitors. For New Entrants and Emerging Players: Private women's health centers in Chengdu and Xi'an represent the most penetrable buyer archetype, bypassing provincial tender complexity through direct manufacturer contracting. White-space targets include telemedicine-integrated pre-insertion counseling platforms and post-placement follow-up service bundling. Go-to-market execution should prioritize digital patient acquisition channels over traditional hospital salesforce deployment. For Investors and Strategic Acquirers: Valuations sit cheapest among regional distribution-integrated assemblers lacking hormonal technology portfolios but possessing entrenched provincial logistics networks. Long-term viability centers on regulatory moat sustainability through NMPA registration acceleration capabilities and GB biocompatibility testing infrastructure. Watch provincial reimbursement tier adjustments for hormonal IUDs as the critical inflection signal for margin expansion timing.| Strategic Initiative | Industry Significance |
|---|---|
| NMPA Class III Registration Acceleration | Compressed approval timelines unlock provincial tender eligibility for domestic hormonal IUD manufacturers. |
| Backward Integration into Polymer Synthesis | In-house pharmaceutical-grade polymer production insulates margin structures from commodity cost volatility. |
| Telemedicine Platform Partnership | Digital health integration captures patient self-referral patterns fragmenting traditional hospital channels. |
| Central Province Distribution Expansion | Henan and Sichuan penetration targets underdeveloped private women's health center density. |
| GB Biocompatibility Standard Harmonization | ISO 10993 alignment positions domestic manufacturers for export market qualification. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with NMPA regulatory consultants, provincial procurement platform managers, hospital gynecology department heads, and medical device distributor operations leads with secondary validation against NMPA registration databases, provincial tender announcement records, and GB standards documentation. Bottom-up device shipment estimates and top-down healthcare expenditure triangulation anchored market sizing.
Comparable-period anchoring linked historical provincial procurement volumes to forward projection assumptions across the analysis window. Segmentation modeling incorporated product type, end-user channel, application indication, and regional reimbursement tier dimensions. CAGRs derived from trend extrapolation of insertion procedure volumes and average selling price trajectories, with NMPA approval pipeline velocity and provincial policy integration timelines as key forecast inputs.
Inputs from NMPA registration filings and provincial health commission procurement announcements were available through the study window; gaps in private women's health center transaction data introduce uncertainty bands around self-pay segment estimates. Forecasts reflect documented assumptions about policy continuity and reimbursement tier evolution. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Medical Bionic Implant Market
Medical Devices
South America Single-Use Medical Device Reprocessing Market
Medical Devices
Australia Contraceptive Devices Market
Medical Devices
Organ Preservation Market
Medical Devices
Infusion Fluid Holder Market
Medical Devices
Electrophysiology Market
Medical Devices
Cast Removal Devices Market
Medical Devices
Mechanical Chest Compression System Market
Medical Devices
Bone Conduction Hearing Aids Market
Medical Devices
Rhinoplasty Implants Market
Medical Devices
Wrist Fixator Procedure Kit Market
Medical Devices
Sleep Apnea Implants Market
Medical Devices
Transcatheter Mitral Valve Market
Medical Devices
Platelet Concentration Systems Market
Medical Devices
Total Artificial Heart Market
Medical Devices
Disposable Needle Guides Market