
 Variable Speed Generator Market | 2026-2036
Variable Speed Generator Market Size, Share, and Industry Trends Forecast 2026-2036
Variable Speed Generator Market Analysis
A shift from single-source to multi-source procurement for permanent magnet components is broadening supplier options for generator manufacturers. ABB leverages its power electronics portfolio to anchor large-scale wind turbine generator contracts across Northern Europe. Siemens AG sustains technology leadership through in-house production of frequency converters that integrate with variable speed architectures. Cummins Inc. competes in the mobile and backup power segment with engine-generator packages that incorporate digital governor controls.
A variable speed generator adjusts rotor speed to match load conditions rather than running at fixed synchronous speed, typically employing power electronics to convert variable-frequency output to grid-compatible electricity. Permanent magnet synchronous machines and doubly-fed induction generators represent the dominant electromechanical architectures, with power ratings spanning from kilowatt-scale residential units to multi-megawatt offshore wind turbines. Stationary generators occupy the largest revenue pool in the type dimension, reflecting baseload industrial and utility-scale installations, while inverter generators command premium pricing in the portable segment due to superior waveform quality for sensitive electronics. Diesel retains the dominant share in fuel type segmentation, though renewable energy–integrated hybrid configurations are expanding fastest in remote and off-grid applications.
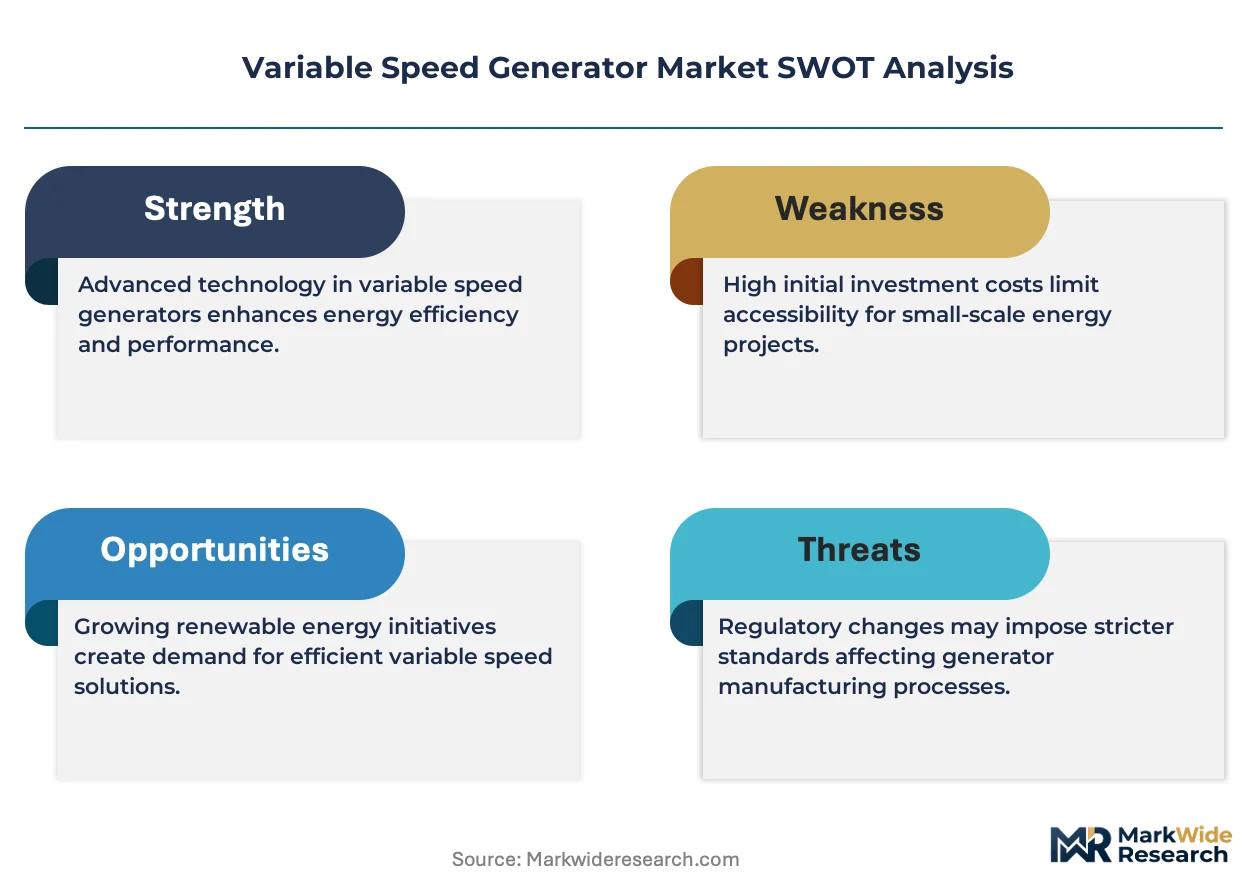
The EU F-Gas Regulation and REACH directives constrain insulation and cooling system material choices for generators sold in Europe, pushing manufacturers toward dry-type transformers and natural ester coolants. EPA Tier 4 Final emissions standards in the United States enforce strict limits on diesel generator nitrogen oxide and particulate output, compelling engine control technology upgrades. IEEE 1547 interconnection standards in North America shape grid-tied variable speed generator inverter requirements. Stakeholders must monitor evolving carbon border adjustment mechanisms and their impact on imported generator component cost structures.
Market Dynamics
The EU F-Gas Regulation is compressing refrigerant options for generator cooling systems while offshore wind developers in the North Sea accelerate procurement of multi-megawatt variable speed units, tightening supply chains for permanent magnet materials.
Growth Catalysts
- Permanent magnet synchronous machines:These architectures deliver superior efficiency at partial loads, making them indispensable for offshore wind turbines where wind speeds fluctuate continuously.
- EPA Tier 4 Final standards:Diesel generator manufacturers must upgrade engine control systems to meet nitrogen oxide limits, creating replacement demand for digitally governed variable speed units.
- Industrial corridor concentration:Germany's Hamburg-Bremen manufacturing belt is absorbing expanded output from generator OEMs serving shipbuilding and port electrification projects.
Market Restraints
- Rare earth supply concentration:Neodymium and dysprosium processing capacity clusters in China, exposing Western generator manufacturers to export restriction risks and price volatility.
- REACH compliance costs:The EU's chemical registration framework limits insulation material choices, forcing costly reformulation of generator winding systems for European market access.
- High-frequency power electronics:IGBT and SiC component thermal management requirements add material cost and engineering complexity to converter designs.
Strategic Opportunities
- Hybrid renewable-diesel configurations:Remote mining and telecom tower operators in Australia are adopting battery-integrated variable speed generators to reduce fuel logistics costs.
- Inverter generator premium segment:Construction contractors and outdoor event operators are paying price premiums for clean sine wave output protecting sensitive electronics.
- Natural ester coolants:The EU Green Deal's decarbonization mandates are accelerating substitution of mineral oil with biodegradable transformer fluids in generator cooling loops.
Industry Challenges
- Power electronics integration:Generator OEMs lack sufficient embedded software engineers to develop grid-forming inverter controls meeting IEEE 1547 interconnection standards.
- Multi-source magnet qualification:Qualifying alternative rare earth suppliers outside China requires 18-24 month validation cycles for magnetic property consistency.
- Frequency converter synchronization:Doubly-fed induction generator rotor-side converter commissioning demands specialized commissioning expertise scarce in emerging markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Variable Speed Generator Market |
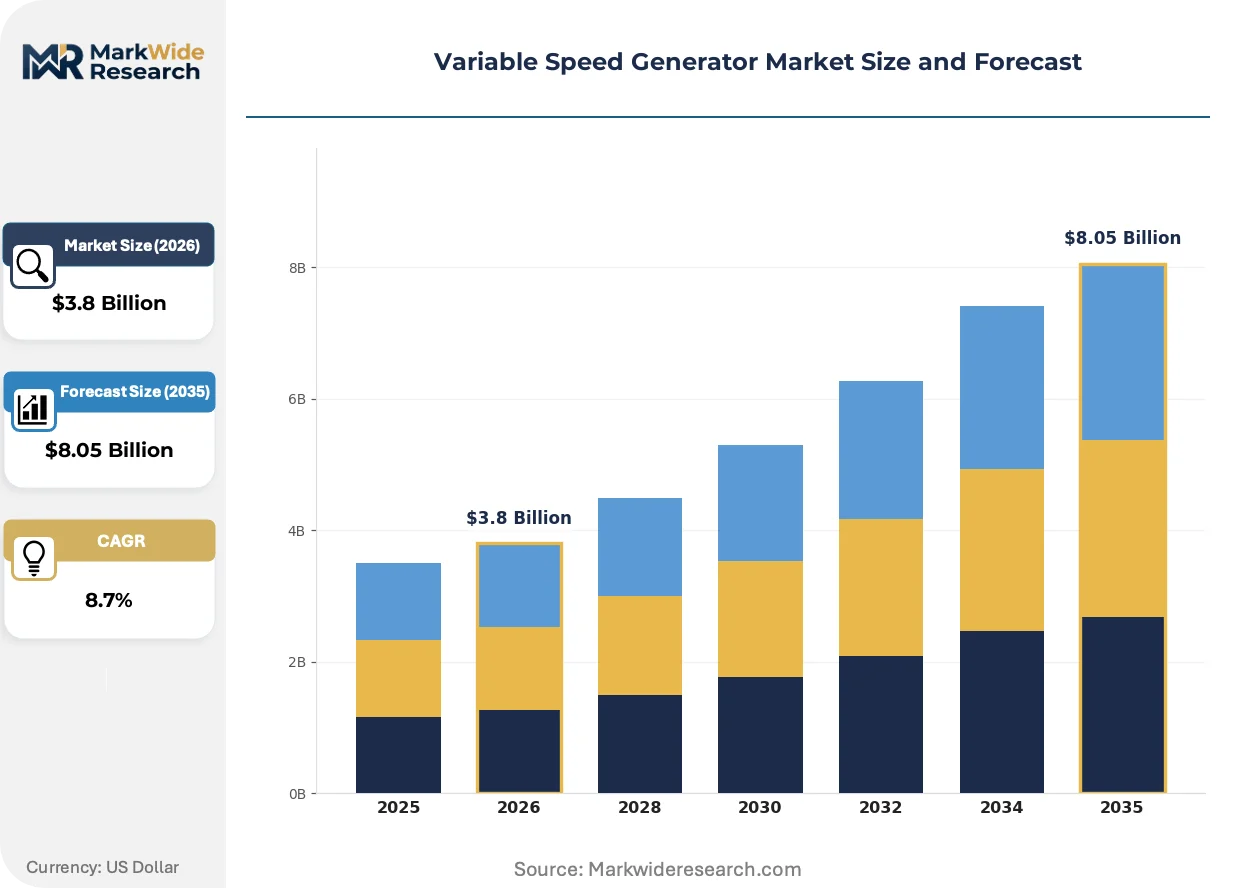
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Portable Generators, Stationary Generators, Hybrid Generators, Inverter Generators Application: Residential Use, Commercial Use, Industrial Use, Emergency Backup Fuel Type: Diesel, Natural Gas, Propane, Renewable Energy Technology: Synchronization Technology, Brushless Technology, Digital Technology, Engine Management |
| Companies Covered | ABB, Siemens AG, General Electric, Cummins Inc., Wärtsilä, Caterpillar Inc., Yanmar Co. Ltd., Vestas Wind Systems, Mitsubishi Heavy Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Variable Speed Generator Market Emerging Trajectories
Silicon carbide power semiconductors are compressing converter footprints while digital twin platforms reshape generator commissioning workflows across utility-scale installations.
Silicon carbide MOSFETs are replacing silicon IGBTs in medium-voltage generator converters, cutting switching losses by half and enabling higher power density in offshore turbine nacelles. Vestas and Siemens Gamesa are specifying SiC-based converters for 15 MW+ platforms entering service in 2026-2027. This transition is electrifying the competitive landscape for frequency converter suppliers, compressing margins for legacy silicon-only vendors while rewarding early SiC adopters with turbine platform design wins.
The EU F-Gas Regulation's phasedown of hydrofluorocarbon refrigerants is banning R-134a and R-410A from generator cooling systems by 2030. Manufacturers are pivoting to CO2 transcritical and propane-based cooling circuits, redesigning heat exchangers and pressure vessels. Offshore wind turbine generators destined for North Sea projects face the steepest compliance burden, with Danish and German developers now requiring F-Gas-free cooling in new procurement specifications.
Long-term service agreements are displacing transactional spare parts purchasing for utility-scale generator fleets. Independent power producers in Texas and California are bundering 15-year maintenance contracts with initial equipment procurement, transferring operational risk to OEM service organizations. This model concentrates aftermarket revenue with vertically integrated manufacturers possessing regional service infrastructure, squeezing third-party maintenance providers from large-scale wind and solar-plus-storage hybrid projects.
Variable Speed Generator Market Segmentation
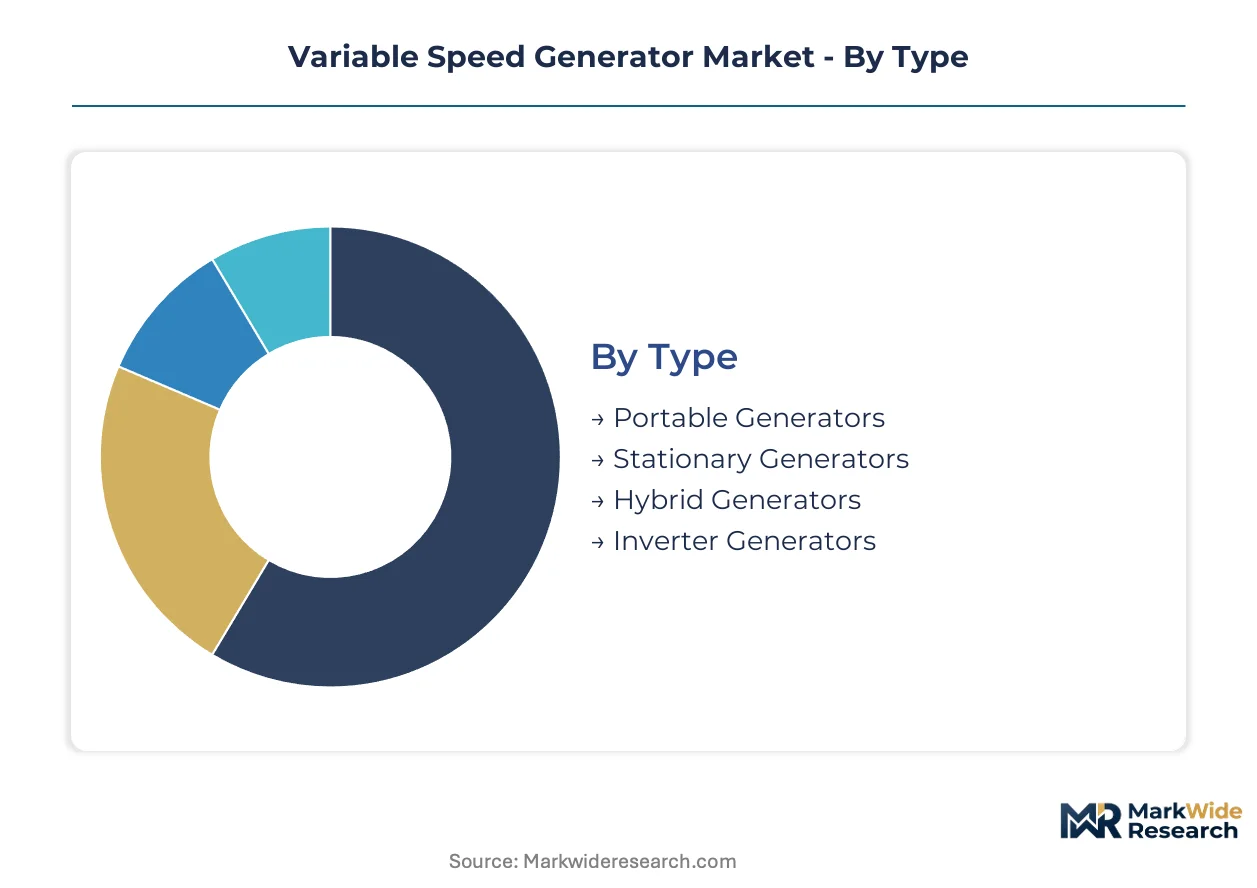
Variable speed generator architectures diverge sharply across deployment contexts, with electromechanical design choices, fuel systems, and control technologies each creating distinct competitive arenas. Procurement specifications in offshore wind, industrial baseload, and portable power segments demand incompatible engineering priorities, fragmenting supplier capabilities across these boundaries.
Type:
Electromechanical configuration and installation permanence define the primary axis of product differentiation.
- Portable Generators:Compact units deployable without fixed infrastructure, typically sub-15 kW output with integrated mobility frames. Demand concentrates with construction contractors and outdoor event operators across Australia and the US Southwest, driven by remote site electrification needs where grid extension is uneconomical.
- Stationary Generators:Permanent installations ranging from 100 kW to multi-megawatt ratings, engineered for continuous or prime power operation. Industrial facilities in Germany's Hamburg-Bremen corridor anchor procurement volumes, absorbing units for shipbuilding yards and port electrification projects where uptime requirements exceed 8,000 annual operating hours.
- Hybrid Generators:Battery-integrated architectures combining diesel or renewable prime movers with energy storage for load-leveling.
- Inverter Generators:Power electronics-based designs producing clean sine wave output through high-frequency conversion and waveform reconstruction.
Mature deployment sits with Stationary Generators. Newer deployment is concentrated in Hybrid Generators.
Application:
End-use intensity and reliability requirements shape specification tiers across customer categories.
- Residential Use:Single-phase units under 20 kW serving household standby and prime power needs in off-grid or unreliable grid contexts. Australian rural properties and Texas exurban developments drive procurement, with homeowners prioritizing automatic transfer switching and quiet enclosure designs for neighborhood compatibility.
- Commercial Use:Three-phase systems from 20-500 kW supporting retail, hospitality, and small manufacturing operations. Data center operators in Northern Virginia and Frankfurt prioritize units with sub-10-second start times and paralleling capability for N+1 redundancy configurations.
- Industrial Use:Heavy-duty architectures engineered for continuous loading in mining, petrochemical, and primary metals processing.
- Emergency Backup:Life safety-grade installations meeting NFPA 110 and EN 50171 standards for healthcare and critical infrastructure.
Volume concentration rests with Industrial Use. Specification intensity peaks in Emergency Backup.
Fuel Type:
Energy density, emissions profile, and supply logistics determine fuel system selection across operating environments.
- Diesel:Dominant fuel for high-power-density applications, leveraging established distribution infrastructure and 35-45% thermal efficiency in modern turbocharged engines. EPA Tier 4 Final compliance costs in the US and EU Stage V standards are compressing supplier margins while accelerating replacement cycles for pre-2015 generator fleets.
- Natural Gas:Pipeline-connected systems preferred for continuous duty in grid-connected industrial facilities with access to utility gas distribution. US shale gas abundance and European LNG infrastructure expansion are extending addressable markets for spark-ignited engines in baseload combined heat and power configurations.
- Propane:Stored fuel option for sites lacking natural gas pipeline access, common in rural residential and commercial standby applications.
- Renewable Energy:Wind, solar, or hydroelectric prime movers integrated with power conditioning electronics for variable speed operation.
Installed base dominance belongs to Diesel. Steepest expansion trajectory characterizes Renewable Energy.
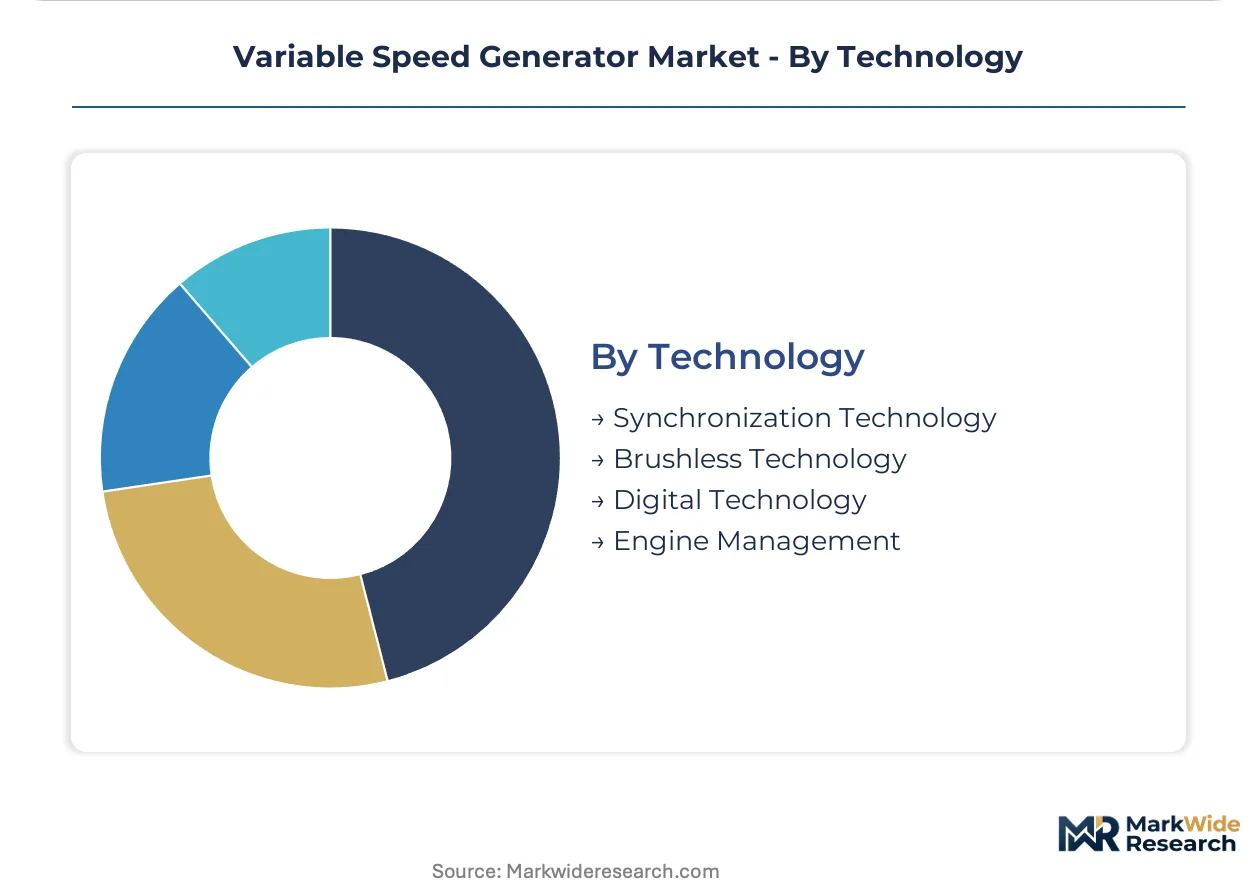
Technology:
Control and conversion architectures differentiate performance capabilities and grid interconnection compliance.
- Synchronization Technology:Phase-locked loop and droop control systems enabling multiple generator paralleling and seamless grid transfer. Microgrid developers in California and Texas specify these capabilities for islanding resilience, with IEEE 1547-2018 compliance mandatory for utility interconnection approval.
- Brushless Technology:Excitation systems eliminating slip rings and commutator maintenance through rotating diode rectification. Offshore wind turbine OEMs in the North Sea mandate brushless excitation for nacelle-mounted generators, where salt corrosion and limited access windows make maintenance intervals exceeding five years essential.
- Digital Technology:Microprocessor-based governor and voltage regulation replacing analog electromechanical controls.
- Engine Management:Integrated electronic control modules optimizing fuel injection, exhaust aftertreatment, and thermal management.
Technology maturity centers on Brushless Technology. Capability investment is concentrating in Digital Technology.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rare earth processing capacity in China anchors upstream material flows for permanent magnet supply chains, while generator assembly and integration concentrate in industrial corridors across Germany, the United States, and Japan.
Germany
Offshore wind procurement in the North Sea and port electrification projects drive multi-megawatt generator demand. The EU F-Gas Regulation mandates CO2-based cooling systems for units installed after 2027. The Hamburg-Bremen industrial corridor absorbs expanded OEM output for shipbuilding and heavy manufacturing applications.
United States
Data center construction in Northern Virginia and Texas creates demand for synchronized backup power systems. EPA Tier 4 Final emissions standards enforce nitrogen oxide limits on diesel generator engines. California microgrid developers specify IEEE 1547-compliant grid-forming inverters for islanding resilience in wildfire-prone regions.
China
Domestic wind turbine installation and export manufacturing sustain demand for doubly-fed induction generator architectures. The Ministry of Ecology and Environment enforces dual carbon goals that constrain coal-integrated generator deployments. Yangtze River Delta manufacturing clusters supply power electronics components for converter systems.
Japan
Industrial combined heat and power installations and disaster-resilient distributed generation shape procurement specifications. METI efficiency standards push generator manufacturers toward permanent magnet synchronous machine adoption. Kansai region engineering firms specialize in high-frequency converter commissioning for offshore wind exports.
Australia
Remote mining operations and telecom tower electrification drive hybrid renewable-diesel generator adoption. The country's national energy regulator enforces grid interconnection standards for distributed energy resources. Western Australian mining camps deploy battery-integrated variable speed units to reduce diesel fuel logistics costs.
Variable Speed Generator Market Vendor Landscape
Capacity expansion dominates the current landscape as manufacturers scale converter production and magnet qualification programs. The market structures around three tiers: vertically integrated European industrial conglomerates with captive power electronics divisions, Asian component specialists supplying magnet and semiconductor materials, and North American engine-generator packagers integrating digital governor controls. Strategic archetypes include turbine OEMs with in-house generator design, independent frequency converter suppliers, and full-service power system integrators. Geographic expansion and technology licensing represent the dominant competitive moves, with players establishing regional service hubs and cross-licensing SiC semiconductor designs.
Among European-based industrial conglomerates, ABB and Siemens AG exemplify the integrated power electronics archetype, anchoring large-scale wind turbine contracts through captive converter technology. Wärtsilä represents the marine and energy sector specialist position, while Cummins Inc. occupies the mobile power tier with engine-generator packaging capabilities. These three named entities illustrate the competitive positioning spectrum without exhaustively cataloging market participation.
| Leading Market Players |
|---|
| ABB |
| Siemens AG |
| General Electric |
| Cummins Inc. |
| Wärtsilä |
| Caterpillar Inc. |
| Yanmar Co. Ltd. |
| Vestas Wind Systems |
| Mitsubishi Heavy Industries |
| Others |
Supply Flow & Price Mechanics
North Sea offshore wind developers' procurement of multi-megawatt permanent magnet generators is forcing supply chain reconfiguration around rare earth qualification programs, compressing margins for converter OEMs unable to absorb magnet price volatility.
Pricing Analysis
Warranty and service bundling separates premium turbine OEM contracts from transactional portable generator sales, with 15-year maintenance agreements now standard for utility-scale installations. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—IEEE 1547-compliant grid-forming inverters command substantial premiums over basic synchronization units. Pricing pressure stems from silicon carbide component shortages constraining converter production. Construction contractors exhibit highest price sensitivity in portable segments, while data center operators prioritize reliability over unit cost.
Supply Chain Analysis
ISO 9001 and specific magnetic property certifications gate entry for rare earth suppliers outside China, extending qualification timelines. Neodymium and dysprosium processing concentrates in China, with Germany and Japan hosting secondary magnet fabrication. Power electronics sourcing draws from Taiwan semiconductor foundries and German IGBT packaging facilities. Single-source vulnerability in rare earth oxide refining exposes Western generator manufacturers to export restriction risks. Distribution runs through turbine OEM direct procurement for offshore wind, with industrial distributors serving stationary generator aftermarket.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Generator manufacturers face a vertical-integration race, with captive power electronics production and in-house magnet qualification emerging as decisive margin levers.
For Market Incumbents: Lock in permanent magnet supply through multi-year offtake agreements with Australian and Canadian rare earth developers, insulating against Chinese export volatility. Expand converter production capacity in Germany's Hamburg-Bremen corridor to capture port electrification and shipbuilding demand. Defend service revenue pools by bundling digital twin commissioning with long-term maintenance contracts. For New Entrants and Emerging Players: Enter via battery-integrated hybrid generator architectures targeting Western Australian mining camps and remote telecom tower operators, segments where fuel logistics costs create willingness to pay premiums for renewable-diesel configurations. Pursue natural ester coolant system specialization for EU F-Gas Regulation compliance, a technical barrier larger OEMs are slow to address. Partner with regional EPC contractors for microgrid project development in California wildfire-prone zones. For Investors and Strategic Acquirers: Re-rating potential sits with independent frequency converter specialists possessing silicon carbide design capabilities given Vestas and Siemens Gamesa platform specifications. Long-term viability favors targets with demonstrated grid-forming inverter software stacks and established service infrastructure in Texas or Northern Virginia data center clusters. Monitor EPA enforcement discretion on Tier 4 Final compliance timelines as an inflection signal for diesel generator replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Converter Scale-Up | Enables 15 MW+ offshore turbine platforms for North Sea developers. |
| Multi-Source Magnet Qualification | Reduces Chinese rare earth dependency for permanent magnet synchronous machines. |
| Natural Ester Coolant Transition | Secures EU market access under F-Gas Regulation phasedown mandates. |
| Grid-Forming Inverter Development | Meets IEEE 1547-2018 requirements for California microgrid islanding resilience. |
| Long-Term Service Agreement Expansion | Captures aftermarket revenue from Texas and California independent power producers. |
Methodological Framework
Document review covered trade customs data, EIA generation statistics, and SEC filings from power equipment manufacturers, complemented by interviews with utility planning officers, offshore wind project developers, EPC contractors, and generator OEM procurement directors. Bottom-up triangulation validated against top-down market sizing from IEA renewable deployment reports and FERC interconnection queue data.
Unit shipment and revenue estimates across the projection horizon reflect segmentation by electromechanical architecture, fuel system, and power rating tier. CAGRs were derived from regression analysis of historical installation data against regulatory milestone schedules and commodity price trajectories. Forecast inputs incorporated silicon carbide semiconductor supply constraints and rare earth oxide spot price volatility.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EPA Tier 5 standards or Chinese rare earth export licensing restrictions. Model outputs reflect assumptions on offshore wind capacity auction timelines and industrial electrification subsidy continuity. A model refresh is warranted upon material change in EU F-Gas Regulation implementation deadlines or IEEE 1547 interconnection standard revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Generation
Global Gas Turbines Market
Power Generation
Philippines Power Generation EPC Market
Power Generation
Gas Turbines in Thermal Power Market
Power Generation
Stirling Engine Market
Power Generation
South America Thermal Power Market
Power Generation
Distributed Generation Market
Power Generation
Industrial Solar Generator Market
Power Generation
Commercial Gensets Market
Power Generation
Iraq Power EPC Market
Power Generation
Global Black Start Generator Market
Power Generation
Marine Power Plant Market
Power Generation
Myanmar Power Generation EPC Market
Power Generation
Power Plant EPC Market
Power Generation
Retail Electricity Market
Power Generation
Canada Power EPC Market
Power Generation
Tunisia Power Market