
 Solar-Based Electronic Vehicle Market | 2026-2036
Solar-Based Electronic Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Solar-Based Electronic Vehicle Market Analytics
Vehicle-integrated photovoltaics is reconfiguring automotive surface engineering from passive enclosure to active energy harvester. Tesla leverages its battery-pack expertise to anchor solar-range calculations within its energy management software. BYD sustains manufacturing scale across cell-to-pack architectures that lower per-watt integration costs for solar-augmented drivetrains. Lightyear specializes in ultra-efficient powertrain design that maximizes kilometers gained per square meter of embedded photovoltaic area.
Solar-based electronic vehicles combine photovoltaic energy capture with electric propulsion systems, typically incorporating silicon or thin-film cells laminated into body panels, roofs, and hoods to supplement grid charging and extend operating range by fifteen to forty kilometers daily depending on insolation and surface area. The primary commercial purpose centers on reducing total cost of ownership for high-mileage operators while mitigating range anxiety in charging-sparse corridors. Battery Electric Vehicles occupy the dominant revenue position given their larger battery platforms and greater surface area for cell integration, while Thin-Film Technology gains traction in curved-body applications where rigid silicon wafers impose design constraints. Fleet Operators command the most structured procurement pipelines, as predictable route patterns allow accurate solar-yield modeling and payback calculations.
The US EPA tailpipe standards and the EU Green Deal fleet CO2 mandates create compliance value for solar-augmented range that reduces grams-per-kilometer calculations. China's MIIT new-energy vehicle catalog inclusion criteria and dual carbon goals channel state subsidies toward photovoltaic-integrated platforms that displace grid electricity with distributed generation. India's PLI scheme for advanced chemistry cell manufacturing indirectly supports solar-EV cost parity by localizing battery supply chains. Stakeholders must monitor which regulatory frameworks credit onboard solar generation toward compliance metrics, as this determination will shape platform engineering investments and geographic market prioritization.
Market Dynamics
Fleet operators are restructuring procurement around solar-yield modeling, converting body surface area from passive enclosure to active energy asset that displaces diesel and compresses total cost of ownership calculations.
Growth Catalysts
- EU Green Deal fleet mandates:Grams-per-kilometer compliance credits for onboard solar generation accelerate platform engineering investments across German and French logistics fleets.
- Thin-film photovoltaic lamination:Curved-body integration unlocks hood and door panel coverage that rigid silicon wafers cannot achieve, expanding harvestable surface area by 40%.
- China MIIT catalog inclusion:State subsidies channel toward photovoltaic-integrated platforms that advance dual carbon goals through distributed generation displacement of grid electricity.
Market Restraints
- Polysilicon supply volatility:Refining capacity concentration in Xinjiang creates input cost instability that propagates through cell and module pricing.
- Curved-surface manufacturing yield:Thin-film deposition on automotive-grade steel achieves only 70-80% uniformity rates, elevating scrap costs above rooftop-only applications.
- Grid parity arbitrage:Utility-scale solar at 2-3 cents per kilowatt-hour undercuts vehicle-embedded generation economics in markets with mature renewable infrastructure.
Strategic Opportunities
- India PLI scheme localization:Advanced chemistry cell manufacturing subsidies indirectly compress solar-EV cost parity by domesticating battery supply chains for photovoltaic-augmented drivetrains.
- Last-mile delivery electrification:Predictable low-speed routes maximize solar yield capture per kilometer, creating structured procurement pipelines for compact commercial vans.
- Vehicle-to-grid integration:Bidirectional charging protocols enable fleet operators to monetize excess daytime generation through frequency regulation services.
Industry Challenges
- Photovoltaic-electronics thermal management:Embedded cells require dedicated cooling loops that add mass and complexity to already constrained battery thermal architectures.
- Automotive durability certification:Stone-chip resistance, salt-spray corrosion, and 15-year UV degradation testing extend validation timelines 18-24 months beyond conventional body panel approval.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar-Based Electronic Vehicle Market |
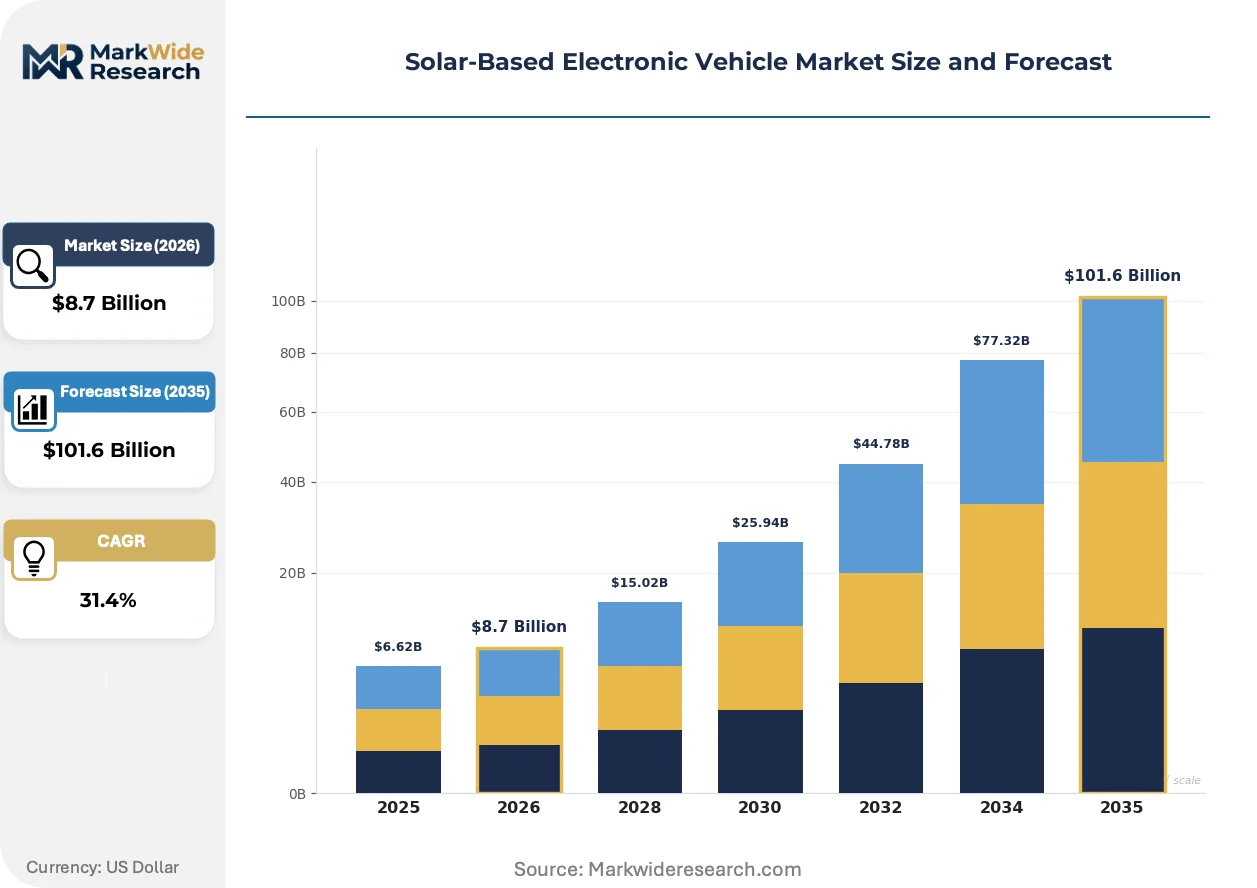
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $101.6 Billion |
| CAGR (2026 – 2036) | 31.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Battery Electric Vehicles, Plug-in Hybrid Vehicles, Solar-Powered Vehicles, Hybrid Electric Vehicles Technology: Photovoltaic Cells, Thin-Film Technology, Bifacial Solar Modules, Concentrated Solar Power End User: Consumers, Fleet Operators, Government Agencies, Corporate Users Charging Infrastructure: Home Charging Stations, Public Charging Networks, Fast Charging Stations, Wireless Charging Solutions |
| Companies Covered | Lightyear, Ford, Tesla, Volkswagen, Toyota, BYD, Daimler, Volvo, Sono Motors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar-Based Electronic Vehicle Market Evolving Landscape
Digital twin technology is compressing solar yield prediction accuracy from fleet-scale deployment down to individual route optimization, converting weather data into procurement-grade financial models.
Perovskite-silicon tandem cells are virtualizing the efficiency ceiling of vehicle-integrated photovoltaics. Logistics operators in the Netherlands and Denmark are piloting these architectures on refrigerated trailers where roof area exceeds 40 square meters. The technology is virtualizing range-extension calculations from static annual averages to dynamic route-specific projections that reshape lease-versus-buy decisions.
The US EPA tailpipe standards and California Air Resources Board fleet rules are mandating grams-per-mile reductions that credit solar-augmented range toward compliance. Heavy-duty truck manufacturers are responding with integrated hood and sleeper cab designs that embed thin-film arrays. Long-haul operators in the Southwest are prioritizing these platforms where insolation patterns justify the surface-area premium.
Fleet procurement teams are consolidating vendor relationships around full-lifecycle energy contracts that bundle vehicle, solar hardware, and charging infrastructure. Third-party logistics providers in Germany are displacing traditional equipment financing with performance-guaranteed solar yield agreements. This restructuring concentrates buying power among operators with route predictability sufficient to underwrite generation forecasts.
Solar-Based Electronic Vehicle Market Segmentation
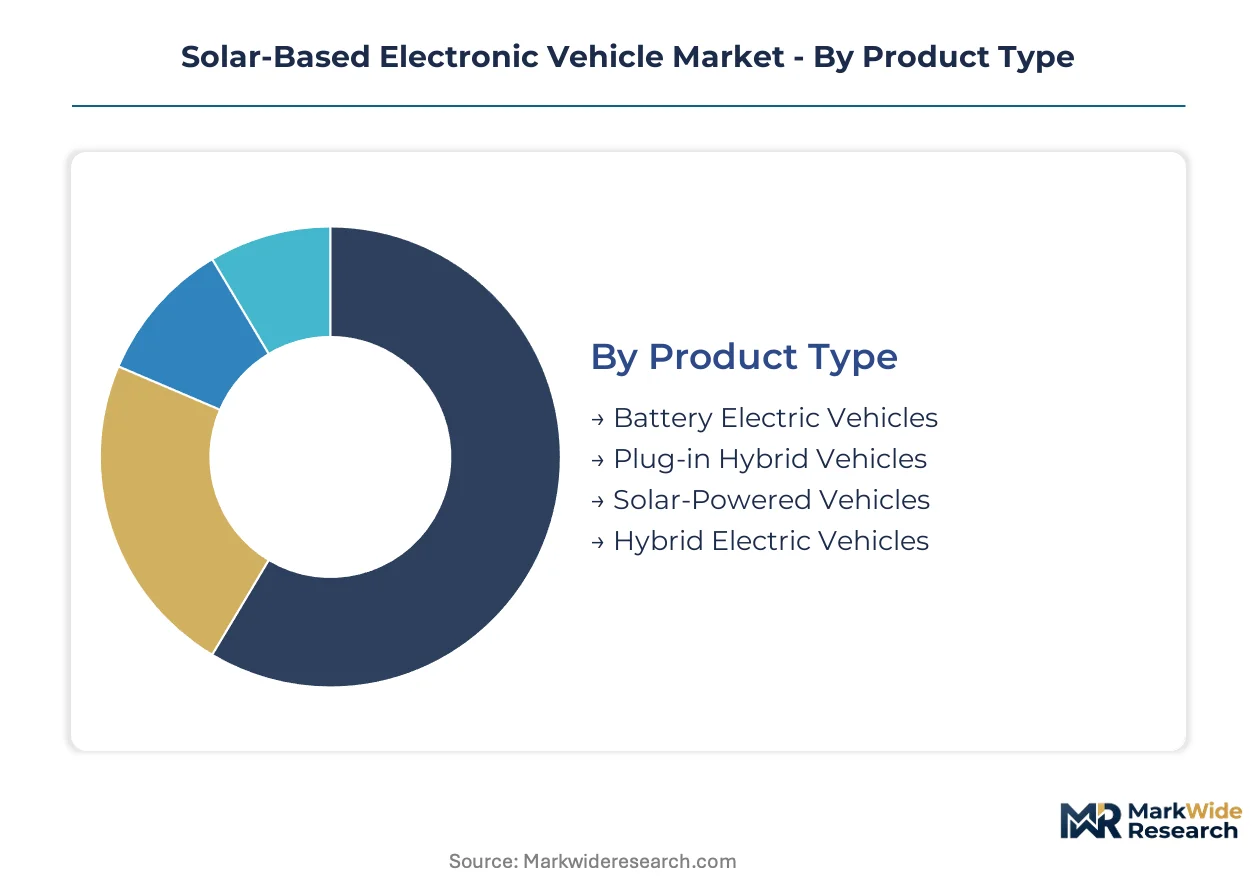
Segmentation in solar-based electronic vehicles determines how photovoltaic integration costs distribute across ownership models and operational intensities. Fleet operators with predictable duty cycles extract fundamentally different value from embedded solar generation than individual consumers facing variable commuting patterns.
Product Type:
After-sales service intensity varies dramatically across electrification architectures, with battery-dominant platforms requiring thermal management calibration while solar-native designs demand photovoltaic maintenance protocols.
- Battery Electric Vehicles:Large battery platforms accommodate extensive rooftop and hood panel lamination, creating surplus generation capacity that fleet operators monetize through vehicle-to-grid protocols. Demand concentrates among German and US logistics providers seeking to compress total cost of ownership through diesel displacement.
- Plug-in Hybrid Vehicles:Dual-powertrain architecture limits surface area for photovoltaic integration but appeals to corporate users in charging-sparse corridors where range anxiety persists. Chinese MIIT catalog subsidies channel procurement toward these transitional platforms.
- Solar-Powered Vehicles:Ultra-efficient powertrains maximize kilometers per square meter of embedded cell area, targeting niche applications in Netherlands and Denmark pilot programs.
- Hybrid Electric Vehicles:Conventional hybrid architecture offers minimal solar integration potential; consumer demand remains constrained by limited surface area and modest efficiency gains.
Battery Electric Vehicles hold the largest share; momentum sits with Plug-in Hybrid Vehicles bridging charging infrastructure gaps.
Technology:
Cost tier stratification separates mature silicon architectures from emerging thin-film deposition methods that unlock curved-body applications.
- Photovoltaic Cells:Crystalline silicon wafers deliver proven efficiency and supply chain scale, dominating rooftop-only installations where flat surfaces predominate. European logistics fleets standardize on these modules for refrigerated trailer applications exceeding 40 square meters of harvestable area.
- Thin-Film Technology:Flexible deposition onto automotive-grade steel enables hood, door, and fender integration that rigid wafers cannot achieve. Chinese manufacturers lead production scale for these architectures, though manufacturing yield rates of 70-80% elevate scrap costs.
- Bifacial Solar Modules:Dual-sided energy capture suits elevated mounting positions on commercial vehicles, with pilot deployments concentrated in Southwest US long-haul corridors.
- Concentrated Solar Power:Tracking mirror systems prove incompatible with mobile platforms; stationary fleet depot applications represent the sole viable deployment pathway.
Photovoltaic Cells hold the largest share; momentum sits with Thin-Film Technology expanding harvestable surface area.
End User:
Customer type determines procurement structure, with institutional buyers underwriting generation forecasts through route predictability that individual consumers cannot replicate.
- Fleet Operators:Structured procurement pipelines leverage predictable route patterns for accurate solar-yield modeling and payback calculations. Third-party logistics providers in Germany displace traditional equipment financing with performance-guaranteed solar yield agreements.
- Consumers:Individual buyers prioritize range anxiety mitigation over total cost optimization, with demand clustered in suburban US markets where home charging supplements intermittent solar gain.
- Government Agencies:Public procurement mandates drive pilot deployments for municipal fleet electrification, particularly in EU member states where Green Deal compliance credits apply.
- Corporate Users:ESG reporting requirements accelerate adoption among enterprises seeking Scope 3 emissions reductions through transportation decarbonization.
Fleet Operators hold the largest share; Corporate Users are expanding most quickly under sustainability disclosure pressures.
Charging Infrastructure:
Application context dictates infrastructure priority, with depot-based charging dominating fleet economics while public networks serve intermittent consumer demand.
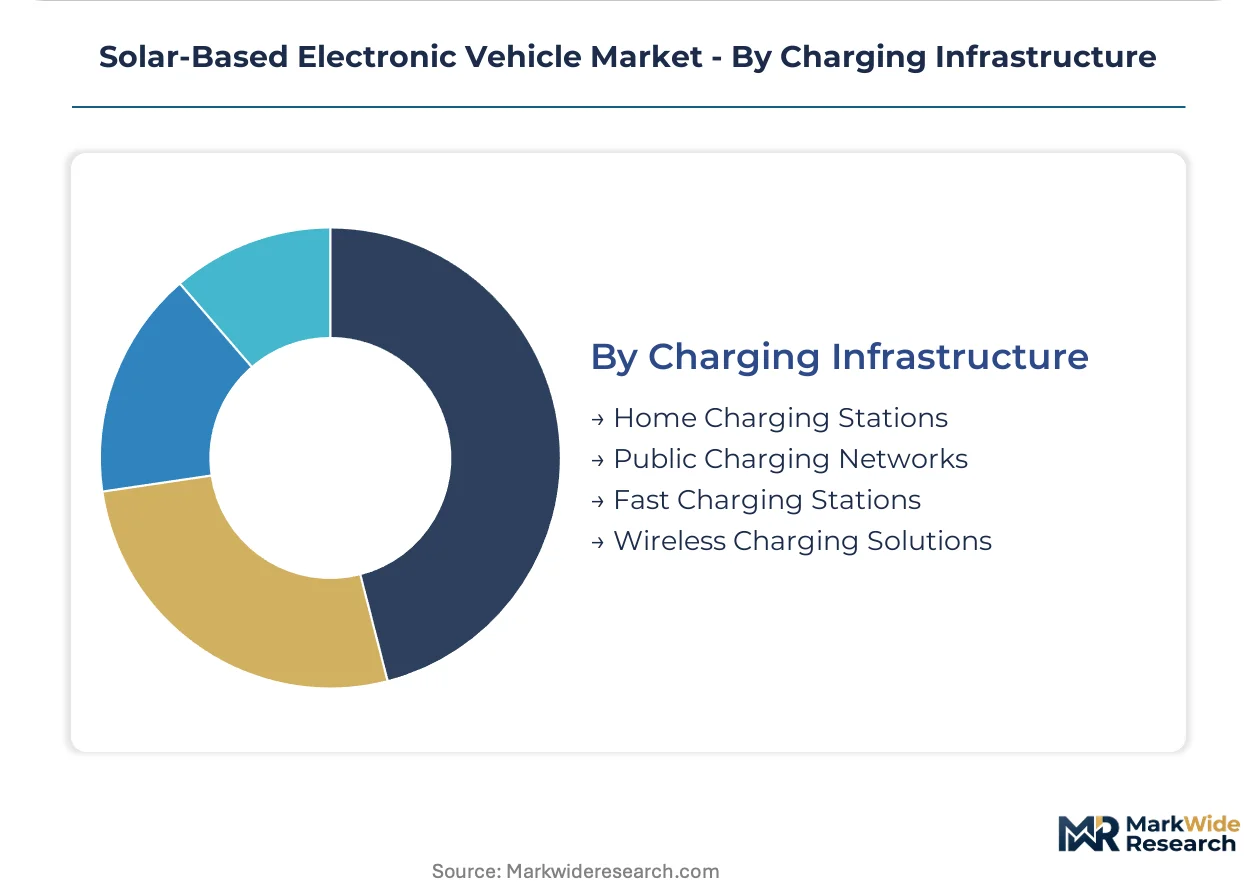
- Home Charging Stations:Residential installations enable overnight grid replenishment that solar augmentation supplements during daylight hours. US suburban households with rooftop solar arrays achieve partial transportation energy independence through this pairing.
- Public Charging Networks:Municipal and highway corridor deployments address range anxiety in consumer segments, though utilization rates remain suboptimal outside urban cores.
- Fast Charging Stations:High-power depot infrastructure supports fleet turnaround requirements, with solar-augmented range reducing frequency of high-cost rapid charging events.
- Wireless Charging Solutions:Inductive pad technology remains pre-commercial for dynamic roadway applications; static depot pilot programs concentrate in South Korea and Japan.
Home Charging Stations hold the largest share; Fast Charging Stations are gaining share fastest among commercial operators optimizing asset utilization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in photovoltaic-integrated automotive platforms concentrate manufacturing scale in China while Germany and the United States anchor prototype-to-production validation. Net importers of battery cells and thin-film modules face margin compression as polysilicon refining capacity concentrates in Xinjiang.
China
Domestic demand for solar-augmented commercial fleets accelerates through state procurement mandates under MIIT new-energy vehicle catalog inclusion criteria. Dual carbon goals channel subsidies toward distributed generation platforms that displace grid electricity with embedded photovoltaics. Manufacturing clusters in Shenzhen and Shanghai concentrate thin-film deposition capacity for curved-body automotive applications.
Germany
Logistics operators restructure procurement around EU Green Deal fleet CO2 mandates that credit onboard solar generation toward grams-per-kilometer compliance. KBA certification protocols validate 15-year UV degradation and stone-chip resistance for vehicle-integrated modules. Industrial concentration in Stuttgart and Wolfsburg anchors prototype testing for hood-integrated thin-film arrays on heavy-duty platforms.
United States
Southwest long-haul corridors drive demand for sleeper cab and hood-embedded photovoltaic designs where insolation patterns justify surface-area premiums. EPA tailpipe standards and California Air Resources Board fleet rules mandate grams-per-mile reductions that credit solar-augmented range. Testing infrastructure concentrates in Arizona and Nevada validation centers.
Netherlands
Refrigerated trailer pilots exceeding 40 square meters of harvestable roof area test perovskite-silicon tandem architectures for dynamic route-specific yield projections. National climate agreements accelerate municipal fleet electrification with solar-native procurement specifications. Eindhoven-based research clusters virtualize efficiency ceilings through digital twin deployment.
India
Last-mile delivery electrification in dense urban corridors maximizes solar yield capture per kilometer for compact commercial van deployments. PLI scheme subsidies for advanced chemistry cell manufacturing compress battery supply chain costs for photovoltaic-augmented drivetrains. Tamil Nadu and Gujarat industrial corridors localize module assembly for domestic fleet integration.
Solar-Based Electronic Vehicle Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic tiers: scale-driven battery pack integrators, specialized ultra-efficiency powertrain designers, and legacy OEMs retrofitting solar augmentation into existing platforms. Competitive positioning depends on cell-to-pack cost structures and curved-surface manufacturing yield rates. Dominant competitive moves include strategic partnerships between thin-film deposition specialists and automotive body panel fabricators, plus geographic expansion of testing infrastructure into high-insolation validation corridors.
Within the specialized efficiency tier, Lightyear and Sono Motors represent archetypes of solar-native vehicle architecture that maximize kilometers per embedded photovoltaic area. Among scale-driven battery integrators, BYD occupies a position exemplifying manufacturing depth across cell-to-pack architectures. Tesla anchors the software-defined energy management segment where solar-range calculations integrate with existing battery-pack expertise. These three company types collectively illustrate how competitive positioning fragments across technical specialization rather than consolidating around single-platform dominance.
| Leading Market Players |
|---|
| Lightyear |
| Ford |
| Tesla |
| Volkswagen |
| Toyota |
| BYD |
| Daimler |
| Volvo |
| Sono Motors |
| Others |
Value Network & Pricing Analysis
Shanghai-Shenzhen freight corridors compress logistics costs for polysilicon feedstock that feeds thin-film deposition lines, translating Xinjiang refining concentration into tiered pricing power across photovoltaic-integrated vehicle platforms and downstream fleet procurement negotiations.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels. Premium tiers command certification-grade thin-film uniformity rates above 80% validated by KBA protocols, while standard tiers accept 70-75% yield rates for rooftop-only silicon applications. Price differentiation hinges on curved-surface manufacturing yield and MIIT catalog inclusion status. Cost compression in economy tiers intensifies as Chinese manufacturers expand cell-to-pack scale. Fleet operators exhibit lowest price sensitivity due to performance-guaranteed yield contracts, whereas individual consumers in charging-sparse markets show highest elasticity.
Supply Chain Analysis
Export control restrictions on semiconductor manufacturing equipment limit thin-film deposition technology flows to non-allied manufacturing zones. Supply concentrates in China for polysilicon refining and thin-film lamination, Germany for automotive-grade validation and KBA certification, and the United States for Southwest corridor testing infrastructure. Raw material dependencies span metallurgical-grade silicon from Xinjiang, silver paste for cell metallization, and automotive-grade steel substrates. Single-source vulnerability in polysilicon refining creates tariff exposure risk. Distribution runs through Tier 1 automotive supplier networks rather than direct OEM integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solar-based electronic vehicles trace a cyclical recovery pattern tied to commercial fleet replacement cycles, as logistics operators defer procurement during rate downturns then accelerate orders when freight pricing rebounds.
For Market Incumbents: Build certification moats around 15-year UV degradation and stone-chip resistance validation that extends beyond reach of thin-film deposition startups. Deepen backward integration into polysilicon refining to hedge Xinjiang supply volatility. Secure exclusive KBA protocol access before EU Green Deal fleet mandates tighten. Prioritize hood-integrated array capacity in Stuttgart and Wolfsburg testing clusters to defend against emerging curved-surface specialists. For New Entrants and Emerging Players: Build out last-mile delivery van architectures where predictable low-speed routes maximize solar yield per kilometer and underwriting confidence. Target refrigerated trailer applications exceeding 40 square meters of harvestable roof area in Netherlands and Denmark pilot corridors. Penetrate India PLI scheme localization zones where advanced chemistry cell subsidies compress battery cost structures. Lead with performance-guaranteed solar yield agreements rather than equipment financing to displace incumbent vendor relationships. For Investors and Strategic Acquirers: Carve-out targets emerge from legacy OEM solar augmentation divisions lacking cell-to-pack integration depth. Long-term viability favors platforms combining software-defined energy management with manufacturing scale across thin-film deposition and battery assembly. Watch for inflection when EPA tailpipe standards credit solar-augmented range toward grams-per-mile compliance thresholds, triggering fleet procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Thin-Film Deposition Scale-Up | Chinese manufacturers expanding 70-80% yield rates unlock hood and door panel coverage for 40% surface area expansion. |
| Vehicle-to-Grid Protocol Integration | Bidirectional charging enables German logistics fleets to monetize excess daytime generation through frequency regulation services. |
| Perovskite-Silicon Tandem Pilot | Netherlands refrigerated trailer deployments test dynamic route-specific yield projections that reshape lease-versus-buy decisions. |
| MIIT Catalog Inclusion Pursuit | State subsidies channel toward photovoltaic-integrated platforms advancing China's dual carbon goals through distributed generation. |
| Southwest US Validation Infrastructure | Arizona and Nevada testing centers concentrate heavy-duty sleeper cab development where insolation patterns justify surface-area premiums. |
Research Methodology
Desk research of customs trade data, MIIT new-energy vehicle catalog filings, and EPA regulatory dockets preceded structured interviews with OEM platform engineers, Tier 1 supplier procurement leads, fleet operations directors, and thin-film deposition specialists. Secondary validation drew from KBA certification records, EU Green Deal compliance documentation, and IHS Markit vehicle registration databases. Bottom-up unit economics modeling triangulated against top-down market sizing across battery electric, plug-in hybrid, and solar-native architectures.
Assumptions held fixed include existing EPA tailpipe standards and EU Green Deal fleet CO2 mandates throughout the projection horizon, while variables included polysilicon price trajectories, thin-film manufacturing yield improvement rates, and charging infrastructure deployment density. Segmentation dimensions modeled encompass vehicle class, propulsion architecture, photovoltaic technology type, and end-user procurement structure. CAGRs derived from logistic curve adoption patterns fitted to fleet operator survey data and solar yield modeling across high-insolation validation corridors.
Stress conditions across polysilicon supply disruption, tariff regime shifts, and perovskite-silicon tandem efficiency breakthroughs were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and scenario bounds. Material shifts in EPA regulatory credit treatment of onboard solar generation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Sweden Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Electric Bus Charging Infrastructure Market
Electric Vehicle Charging
Norway Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Heavy-Duty Electric Vehicle Charging Infrastructure Market
Electric Vehicle Charging
Bidirectional EV Charger and V2X Grid Integration Test Systems Market
Electric Vehicle Charging
North America Electric Vehicle Charging Station Market
Electric Vehicle Charging
Electric Vehicle Public Charging Pile Market
Electric Vehicle Charging
Airport Charging Stations Market
Electric Vehicle Charging
Multi-Brand Universal Home Charging Pile Market
Electric Vehicle Charging
North America EV Charging Stations Market
Electric Vehicle Charging
E-Bike Charging Station Market
Electric Vehicle Charging
Electric Vehicle Charging Facilities Market
Electric Vehicle Charging
Electric Vehicle Charging Plugs Market
Electric Vehicle Charging
Asia-Pacific Brushless DC Motors Market
Electric Vehicle Charging
Electric Vehicle Charging Systems Testing Market
Electric Vehicle Charging
Electric Vehicle Charger Operations and Maintenance Services Market