
 Asia-Pacific Brushless DC Motors Market | 2026-2036
Asia-Pacific Brushless DC Motors Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Brushless DC Motors Market Analytics
Automotive powertrain demand is decoupling from conventional brushed motor supply chains across the Asia-Pacific. Nidec Corporation dominates permanent magnet motor architectures for EV traction systems. Toshiba Corporation anchors industrial servo applications through high-precision inverter integration. Mabuchi Motor specializes in compact brushless designs for thermal management and auxiliary automotive loads.
Brushless DC motors employ electronically commutated stator windings with permanent magnet rotors, achieving efficiency above 90% through precise digital control rather than mechanical brush-arc commutation. Radial flux configurations sustain the largest installed base across industrial equipment and automotive traction, while pancake geometries compete in robotics joints where axial length constraints dominate design envelopes. Sensorless commutation technology leads volume growth by eliminating Hall-effect component costs and wiring complexity in cost-sensitive HVAC and appliance motorization.
Japan's METI enforces Top Runner efficiency standards that progressively tighten permissible loss thresholds for industrial motors sold domestically. China's MIIT mandates GB standard compliance for motor efficiency tiers in domestic manufacturing equipment, directly shaping procurement specifications for Jiangsu and Guangdong factory automation retrofits. India's BIS adoption of IEC efficiency classes for low-voltage motors is expanding addressable market scope for premium brushless substitutes. Stakeholders must monitor how China's dual carbon goals redirect rare earth magnet supply toward domestic motor manufacturers versus export availability.
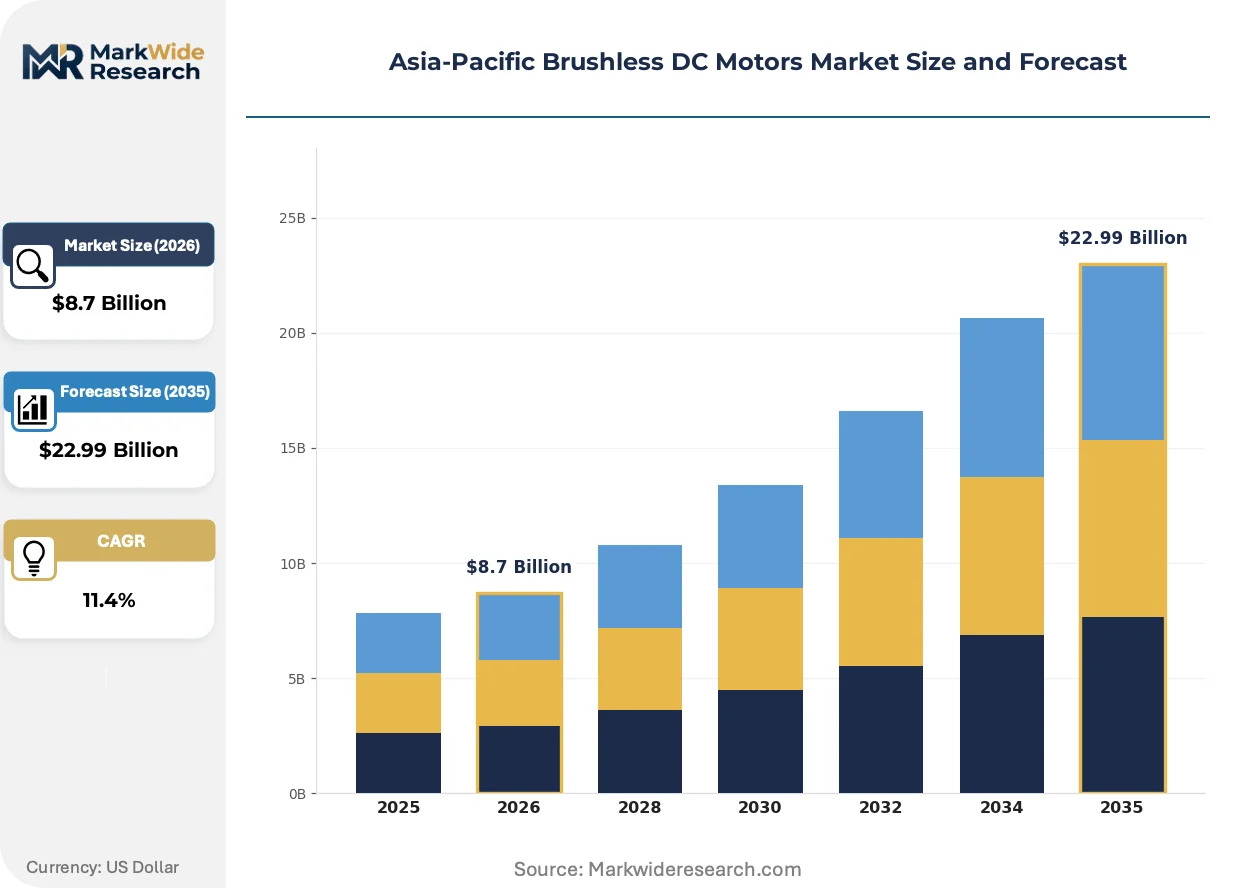
Market Dynamics
China's dual carbon goals are redirecting rare earth magnet supply toward domestic motor manufacturers, compressing export availability and reshaping procurement patterns across the Asia-Pacific.
Growth Catalysts
- Japan's Top Runner program:METI's progressive efficiency mandates for industrial motors tighten permissible loss thresholds, forcing factory automation upgrades across Osaka and Nagoya manufacturing belts.
- EV powertrain electrification:Automotive OEMs in Jiangsu and Zhejiang corridors are decoupling from brushed motor supply chains, sourcing permanent magnet traction systems for battery-electric platforms.
- Sensorless commutation:Elimination of Hall-effect components and wiring complexity is expanding brushless motor penetration in cost-sensitive HVAC and appliance segments across Southeast Asia.
Market Restraints
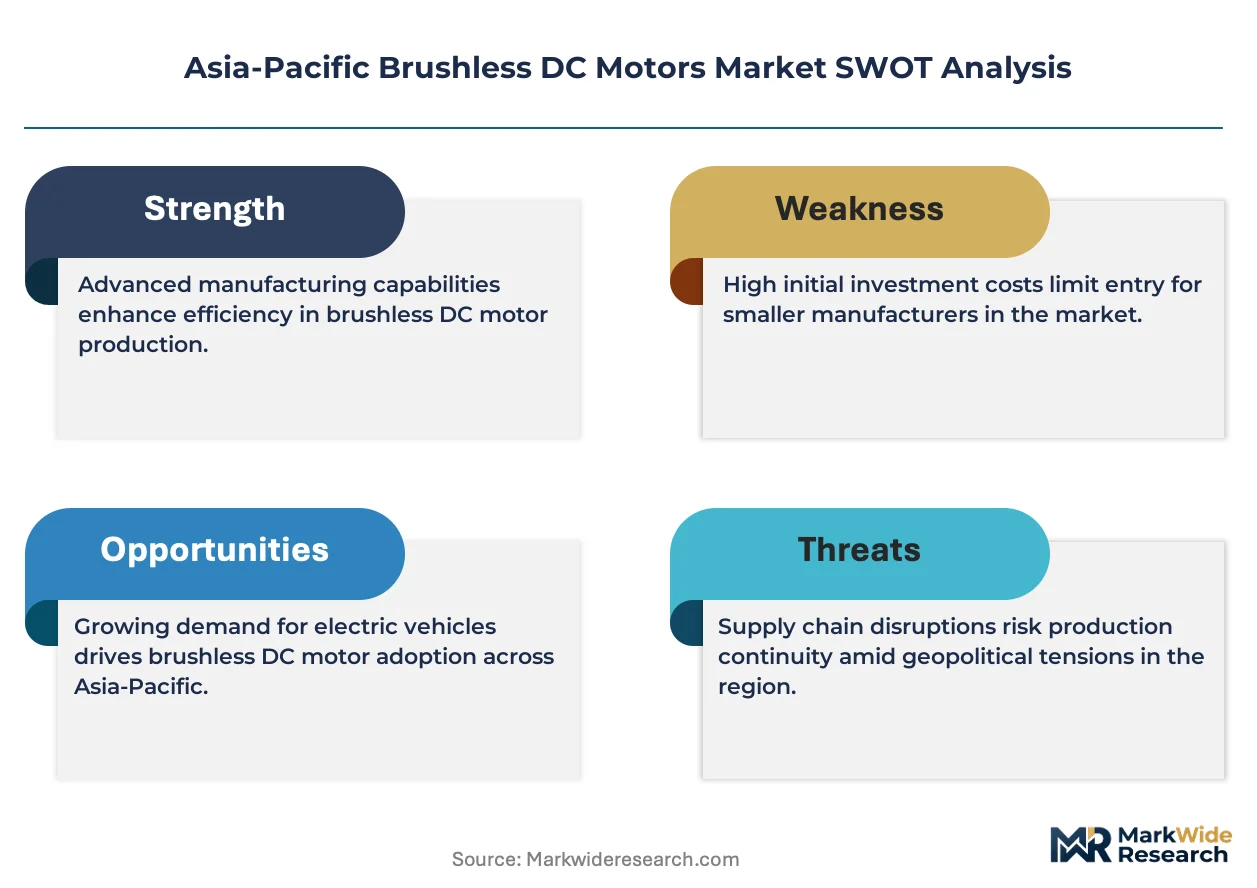
- Neodymium price volatility:Rare earth magnet input costs fluctuate with China's export quota administration, squeezing margin structures for motor assemblers dependent on external magnet sourcing.
- Supply concentration risk:Sintered NdFeB magnet production clusters in Inner Mongolia and Jiangxi, creating single-geography dependency for high-performance rotor assemblies serving Japanese and Korean OEMs.
- Technical thermal limits:Permanent magnet demagnetization thresholds above 150°C constrain traction motor power density for commercial vehicle applications requiring sustained high-torque operation.
Strategic Opportunities
- India's BIS efficiency adoption:IEC class alignment for low-voltage motors opens premium brushless substitution opportunities in Gujarat and Tamil Nadu textile and pump manufacturing.
- Robotics axial flux demand:Pancake motor geometries for collaborative robot joints present white space as Japanese automation integrators redesign arm architectures for compact installations.
- Appliance inverterization:Variable-speed compressor and fan motor mandates across ASEAN markets create channel expansion potential for sensorless drive-integrated motor modules.
Industry Challenges
- Embedded software talent scarcity:Field-oriented control algorithm development and motor-drive firmware integration skills concentrate in Shenzhen and Taipei, constraining expansion for second-tier motor houses.
- Multi-standard certification burden:Simultaneous GB, JIS, and BIS efficiency testing requirements extend product launch timelines for pan-Asia-Pacific motor portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Brushless DC Motors Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radial, Axial, Pancake, Disc Application: Automotive, Robotics, HVAC, Industrial Equipment End User: OEMs, Aftermarket Players, Consumers, Engineers Technology: Sensorless, Hall-Effect, Sinusoidal, Commutation |
| Companies Covered | Toshiba Corporation, Maxon Motor AG, Nidec Corporation, Mabuchi Motor, Oriental Motor Co., Ltd., Johnson Electric Holdings, AMETEK, Inc., Allied Motion Technologies, ABB Group, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Brushless DC Motors Market Evolving Landscape
Digital control architectures and permanent magnet material science are compressing motor footprints while elevating efficiency benchmarks across automotive and industrial applications.
Axial flux brushless motors with toroidal winding configurations are electrifying robotics and aerospace auxiliary systems by delivering torque density exceeding 15 Nm/kg in pancake geometries under 40mm axial length. Japanese collaborative robot manufacturers and Korean drone OEMs are qualifying these topologies for joint actuation and propulsion. The technology is electrifying design envelopes previously dominated by bulky radial flux alternatives with equivalent power output.
China's MIIT GB 18613-2020 efficiency standards mandate IE3 minimum performance for three-phase motors above 0.75kW, eliminating IE2 and IE1 tier sales for domestic manufacturing equipment procurement. Jiangsu and Guangdong factory automation retrofit programs are accelerating brushless servo replacements of induction motors in CNC and injection molding lines. The regulation is compressing brushed motor residual demand in industrial sectors previously tolerant of lower efficiency tiers.
Integrated motor-drive modules combining brushless DC stators with GaN-based inverters are displacing separate component procurement in appliance and HVAC supply chains. Korean whitegoods manufacturers and Chinese heat pump OEMs are specifying these compact assemblies to reduce wiring harness complexity and assembly labor. The shift is most visible in South Korea's residential air conditioning and water heater export manufacturing clustered around Gwangju and Suwon.
Asia-Pacific Brushless DC Motors Market Segmentation
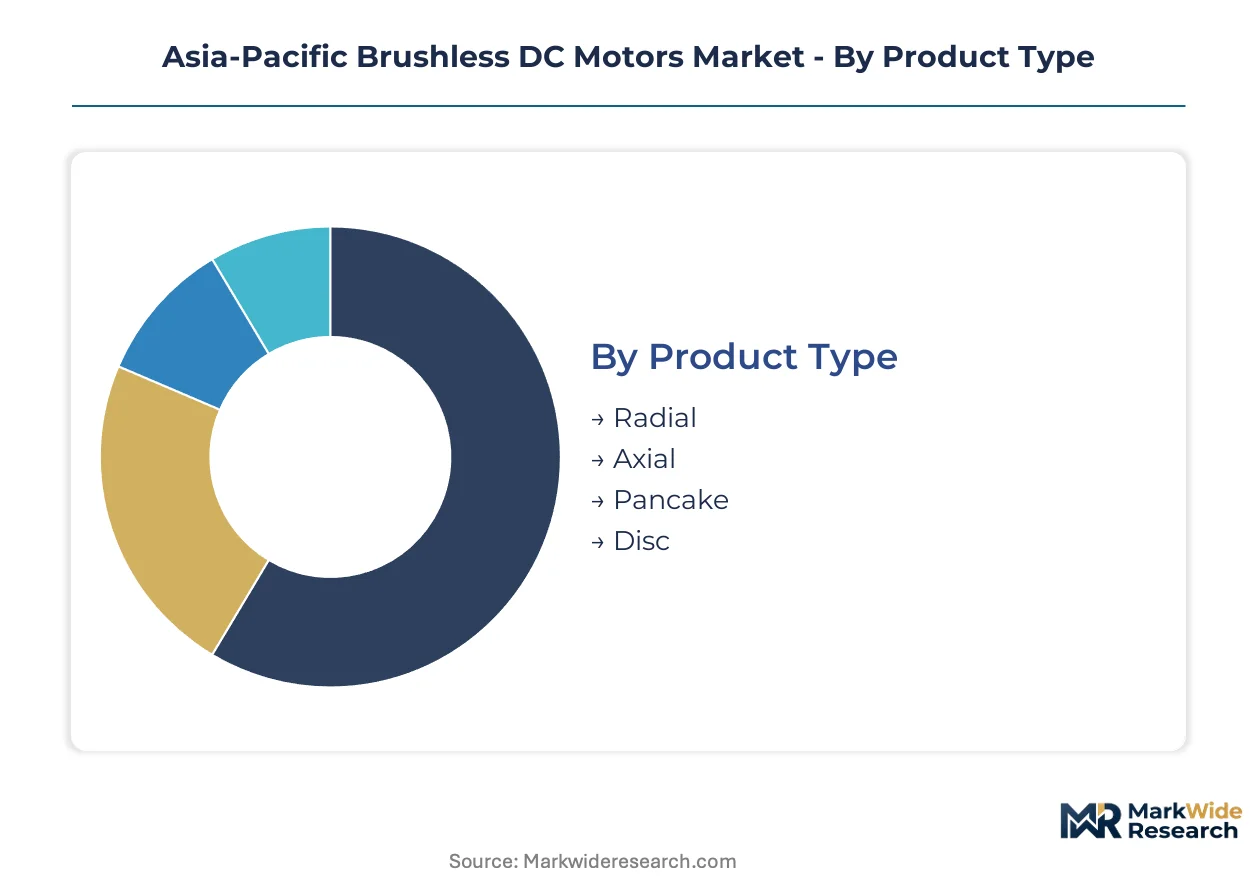
Brushless DC motor architectures diverge sharply across torque density requirements, thermal envelopes, and control precision needs. Understanding these segment boundaries clarifies why automotive traction systems, robotics joints, and HVAC compressors source fundamentally different motor geometries despite sharing core electronically commutated principles.
Product Type:
Buyers in this category prioritize volumetric torque density versus axial length constraints, with automotive powertrains demanding continuous thermal performance and robotics accepting intermittent peak loads.
- Radial:Cylindrical rotor-stator configurations with magnetic flux oriented perpendicular to the shaft axis dominate industrial servo and EV traction applications. Jiangsu automotive OEMs specify these for 150kW-class drive units where sustained high-torque operation and established cooling channel designs outweigh packaging penalties.
- Axial:Toroidal winding geometries with flux parallel to the rotation axis deliver torque density exceeding 15 Nm/kg in sub-40mm axial envelopes. Korean drone manufacturers and Japanese collaborative robot integrators qualify these for joint actuation where arm reach constraints dominate design trade-offs.
- Pancake:Ultra-flat configurations under 25mm axial length serve limited-rotation positioning stages in semiconductor handling equipment.
- Disc:Printed circuit board stator variants with ironless rotors enable sub-gram precision for optical gimbal stabilization in Shenzhen camera module manufacturing.
Radial configurations anchor installed base volumes across the Asia-Pacific; axial flux geometries are climbing fastest as robotics and aerospace auxiliary electrification accelerates.
Application:
End-use differentiation centers on duty cycle severity, with continuous industrial operation demanding thermal management architectures incompatible with intermittent consumer appliance loading.
- Automotive:Traction motor applications spanning 50-300kW peak outputs require rare-earth permanent magnet rotors with 150°C demagnetization margins and liquid cooling circuits. Zhejiang battery-electric vehicle platforms are decoupling from brushed motor supply chains, specifying sensorless field-oriented control to eliminate Hall-effect wiring failures in underhood thermal cycling.
- Robotics:Six-axis collaborative arms and SCARA systems demand high peak torque-to-inertia ratios for dynamic trajectory following. Japanese automation integrators in Osaka and Nagoya corridors specify pancake axial flux motors with integrated harmonic drive gearing to compress joint envelope dimensions.
- HVAC:Variable-speed compressor and fan loads across ASEAN residential markets prioritize cost-optimized sensorless drives over precision positioning bandwidth.
- Industrial Equipment:CNC spindle and injection molding servo retrofits in Guangdong factories substitute brushless systems for induction motors under MIIT efficiency mandates.
Automotive applications command the largest revenue footprint; robotics is expanding most quickly as manufacturing automation density rises across East Asian production corridors.
End User:
Procurement sophistication varies dramatically, with OEMs specifying custom winding configurations and thermal interfaces while aftermarket channels prioritize plug-compatible replacements.
- OEMs:Tier-1 automotive suppliers and industrial automation houses commission application-specific stator laminations, magnet grades, and encoder resolutions. Nidec and Toshiba anchor direct procurement relationships with design-in engineering support.
- Aftermarket Players:Distributors serving industrial maintenance channels stock standardized frame sizes with universal mounting patterns to minimize inventory proliferation.
- Consumers:Hobbyist and maker segments drive demand for low-cost outrunner configurations in personal drone and electric bicycle conversions.
- Engineers:R&D procurement for prototype validation emphasizes rapid sample availability and parametric customization over unit economics.
OEMs dominate premium specification volumes; aftermarket channels are gaining share fastest as installed base maintenance cycles lengthen across aging Japanese and Korean industrial equipment fleets.
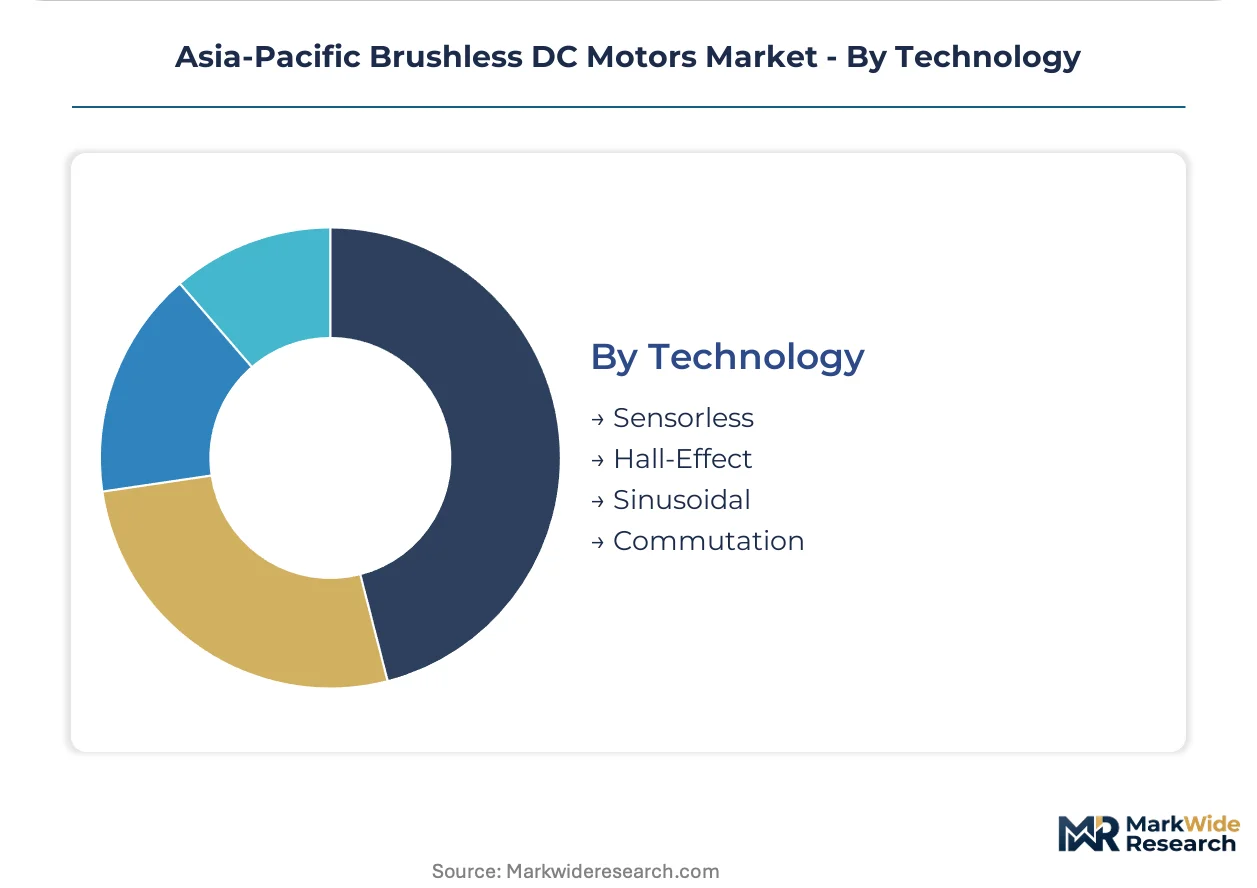
Technology:
Control architecture selection determines BOM cost structure and reliability profile, with sensorless implementations eliminating component count at the expense of low-speed torque precision.
- Sensorless:Back-EMF estimation algorithms and observer-based rotor position detection eliminate Hall-effect sensors and wiring harnesses. Chinese HVAC and appliance OEMs specify these for cost-sensitive compressor motorization where starting torque requirements remain modest.
- Hall-Effect:Discrete magnetic sensors provide absolute position feedback for zero-speed torque production in automotive traction and precision servo applications. Infineon and Allegro Microsystems supply qualified automotive-grade variants for underhood thermal cycling.
- Sinusoidal:Current vector control with space-vector modulation reduces torque ripple and acoustic noise in direct-drive washing machine and precision positioning stages.
- Commutation:Trapezoidal six-step switching remains prevalent in low-cost fan and pump applications where efficiency optimization yields to controller simplicity.
Hall-effect systems retain dominance in safety-critical automotive traction; sensorless architectures are climbing fastest as algorithmic observer performance improves and cost pressure intensifies in appliance and HVAC segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting brushless DC motor production toward jurisdictions with lower compliance costs and concentrated rare earth processing infrastructure. Manufacturers are relocating final assembly to exploit efficiency standard gaps while maintaining magnet sourcing proximity.
China
Domestic EV powertrain demand is absorbing Jiangsu and Zhejiang manufacturing corridor capacity at unprecedented rates. MIIT's GB 18613-2020 efficiency mandates are eliminating IE2-tier motor sales for domestic industrial equipment, forcing Guangdong factory automation retrofits toward brushless servo systems. Inner Mongolia and Jiangxi sintered NdFeB magnet production clusters are prioritizing domestic motor manufacturers under dual carbon goals.
Japan
Top Runner efficiency standards from METI are progressively tightening permissible loss thresholds for industrial motors sold domestically. Osaka and Nagoya manufacturing belts are upgrading factory automation to comply with 2024 loss reduction targets. Nagoya-area automotive suppliers are qualifying axial flux pancake geometries for collaborative robot joint actuation.
South Korea
Residential air conditioning and water heater export manufacturing around Gwangju and Suwon is specifying integrated motor-drive modules with GaN-based inverters. MFDS-aligned efficiency testing is compressing product launch timelines for pan-Asia-Pacific portfolios. Busan-Ulsan industrial zones are retrofitting CNC lines with brushless servo replacements.
India
BIS adoption of IEC efficiency classes for low-voltage motors is expanding addressable market scope for premium brushless substitutes. Gujarat and Tamil Nadu textile and pump manufacturing clusters are specifying IE3-tier brushless systems for new capacity installations. Delhi-NCR industrial automation distributors are building inventory for anticipated efficiency mandate expansion.
Vietnam
ASEAN appliance manufacturing relocation is attracting sensorless brushless motor module suppliers for cost-optimized compressor production. Ho Chi Minh City industrial zones are hosting Korean and Japanese motor houses establishing tariff-advantaged assembly operations. Northern Vietnam electronics corridors are qualifying suppliers for HVAC inverterization mandates across Southeast Asian export markets.
Asia-Pacific Brushless DC Motors Market Competitive Landscape
Strategic partnerships dominate the current landscape as motor houses secure rare earth magnet supply commitments and inverter semiconductor allocation. The vendor base concentrates around three tiers: integrated conglomerates with captive magnet sourcing, specialized motor houses with design-in engineering capabilities, and contract manufacturers serving cost-sensitive appliance segments. Archetypes include magnet-integrated producers, field-oriented control specialists, and sensorless drive module assemblers. M&A activity and backward integration into permanent magnet processing represent the dominant competitive vectors.
Among Japan-based integrated producers, Nidec Corporation and Toshiba Corporation exemplify the magnet-integrated archetype with direct procurement relationships across automotive and industrial channels. Mabuchi Motor occupies a position within the compact brushless specialization tier. These three entities represent distinct strategic postures: Nidec anchors permanent magnet traction system supply, Toshiba exemplifies high-precision inverter integration, and Mabuchi exemplifies auxiliary automotive load specialization.
| Leading Market Players |
|---|
| Toshiba Corporation |
| Maxon Motor AG |
| Nidec Corporation |
| Mabuchi Motor |
| Oriental Motor Co., Ltd. |
| Johnson Electric Holdings |
| AMETEK, Inc. |
| Allied Motion Technologies |
| ABB Group |
| Others |
Value Network & Pricing Analysis
Integrated motor-drive modules combining GaN-based inverters with brushless DC stators are compressing assembly labor costs while concentrating procurement power among Korean whitegoods manufacturers and Chinese heat pump OEMs. This packaging shift simultaneously reduces wiring harness complexity and elevates minimum efficient scale thresholds for motor assemblers competing in ASEAN appliance export manufacturing.
Pricing Analysis
Distributor margins in Jiangsu and Zhejiang manufacturing corridors absorb 12-18 points before OEM direct procurement, with direct-to-automotive-platform contracts commanding steepest volume discounts. Three-tier pricing structure across premium servo systems, standard industrial motors, and economy appliance units tracks magnet grade and thermal interface specifications. Cost compression in sensorless drive modules is intensifying because Chinese HVAC OEMs are consolidating supplier panels. Aftermarket maintenance channels exhibit highest price sensitivity; Tier-1 automotive powertrain procurement shows lowest.
Supply Chain Analysis
Regional distribution centers in Shenzhen, Taipei, and Osaka operate hub-and-spoke patterns feeding Guangdong factory automation retrofits and Nagoya manufacturing belt upgrades. Sintered NdFeB magnet production clusters in Inner Mongolia and Jiangxi; winding copper draws from Chilean and Indonesian concentrate. Single-source vulnerability concentrates in rare earth magnet processing. Distribution runs through captive logistics networks serving Nidec and Toshiba direct procurement relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific brushless DC motor demand functions as a regulatory compounder. China's MIIT GB 18613-2020 efficiency mandates are eliminating IE2-tier motor sales and forcing Guangdong CNC and injection molding line retrofits.
For Market Incumbents: Deploy backward integration into sintered NdFeB magnet processing to secure rotor assembly supply against China's dual carbon export quota compression. Anchor direct procurement relationships with Jiangsu automotive OEMs through design-in engineering support for 150kW-class traction systems. Counter emerging Korean integrated motor-drive module assemblers by accelerating GaN inverter co-development timelines. For New Entrants and Emerging Players: Capture white space in India's Gujarat and Tamil Nadu textile and pump manufacturing clusters where BIS IEC class alignment is expanding addressable market scope for premium brushless substitutes. Target Vietnam's Ho Chi Minh City industrial zones for tariff-advantaged assembly operations serving ASEAN HVAC inverterization mandates. Lead with sensorless drive-integrated motor modules to bypass Hall-effect component sourcing complexity. For Investors and Strategic Acquirers: Valuations sit cheapest among compact brushless specialists with auxiliary automotive load exposure and limited magnet supply captive arrangements. Long-term viability centers on software-defined motor control differentiation and rare earth processing access. Watch China's export quota administration frequency as the inflection signal for input cost volatility.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Magnet Processing | Secures NdFeB rotor supply against China's dual carbon export restrictions. |
| GaN Inverter Co-Development Partnership | Enables integrated motor-drive modules for Korean whitegoods manufacturers. |
| Sensorless Control Algorithm Investment | Eliminates Hall-effect costs for cost-sensitive ASEAN compressor applications. |
| Axial Flux Pancake Motor Qualification | Captures Japanese collaborative robot joint actuation redesign cycles. |
| India BIS Efficiency Certification | Opens Gujarat and Tamil Nadu textile manufacturing procurement channels. |
Research Methodology
Direct dialogue with motor procurement managers at Tier-1 automotive suppliers, plant engineers at Guangdong factory automation facilities, and HVAC OEM technical directors across South Korea and Vietnam grounded qualitative assessment. Secondary validation drew from MIIT GB standard filings, METI Top Runner efficiency disclosures, customs records for NdFeB magnet trade flows, and SEC 10-K segments from Nidec and Toshiba. Bottom-up unit shipment estimates triangulated against top-down industrial equipment investment data.
Segment-level revenue outputs across radial, axial, and pancake motor geometries were modeled over the projection horizon, with automotive traction, robotics, HVAC, and industrial equipment applications as distinct end-use slices. CAGRs emerged from regression against EV powertrain penetration curves and factory automation retrofit program announcements. Rare earth magnet price indices and semiconductor lead time fluctuations fed sensitivity scenarios.
Neodymium price volatility, China's export quota policy shifts, and embedded software talent scarcity in Shenzhen and Taipei are the dominant revision risks for forecast accuracy. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
EV Solar Charging Wallbox Market
Electric Vehicle Charging
Belgium Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Home Charging Piles Market
Electric Vehicle Charging
Europe Airport Electric Vehicle Charging Station Market
Electric Vehicle Charging
Oman EV Charging Station Market
Electric Vehicle Charging
Electric Vehicle Charging System Market
Electric Vehicle Charging
Smart EV Charger Market
Electric Vehicle Charging
Charging As a Service Market
Electric Vehicle Charging
Electric Vehicle Safe Charging Inlet Market
Electric Vehicle Charging
Electric Vehicle (EV) Charging Infrastructure Market
Electric Vehicle Charging
Electric Bus Charging Infrastructure Market
Electric Vehicle Charging
Electric Vehicle Public Charging Pile Market
Electric Vehicle Charging
India Battery Swapping for Electric Two-Wheelers Market
Electric Vehicle Charging
Electric Vehicle Rapid Charger Market
Electric Vehicle Charging
France Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Japan Electric Vehicle Charging Station Market