
 Box Transformer Substation Market | 2026-2036
Box Transformer Substation Market Size, Share, and Industry Trends Forecast 2026-2036
Box Transformer Substation Market Insights
The split between premium and commodity tiers is repositioning competitive dynamics in the box transformer substation sector. ABB Ltd. leverages its integrated power technology portfolio to dominate high-reliability segments for utilities and heavy industry. Schneider Electric SE anchors its position through extensive channel control across European and Asian distribution networks. Siemens AG differentiates via deep R&D intensity in digital substation automation and condition monitoring systems.
A box transformer substation is a prefabricated, enclosure-housed power distribution unit integrating transformers, switchgear, and protection equipment, typically rated from 11 kV to 36 kV for medium-voltage applications and designed for rapid deployment in constrained spaces. Its primary purpose is to step down transmission-level voltages for safe distribution to industrial plants, commercial complexes, and residential clusters while minimizing footprint and installation time. Compact transformer configurations command premium pricing in dense urban deployments where land scarcity and noise restrictions apply most stringently. Medium voltage levels represent the largest installed base, though extra high voltage segments attract disproportionate engineering margins due to custom insulation and cooling requirements.
IEC standards, IEEE C57 guidelines, and national electrical safety codes collectively govern enclosure ratings, oil containment, and arc-flash containment across major markets. China's SAMR enforces GB standards for substation equipment certification, while India's CEA mandates centralized testing protocols for grid-connected installations. Stakeholders must weigh standardization benefits against customization premiums as procurement shifts toward modular, factory-tested systems.
Market Dynamics
Grid modernization mandates across Southeast Asian utilities are compressing deployment timelines for factory-tested substation systems, forcing manufacturers to reconcile modular standardization with site-specific customization requirements.
Growth Catalysts
- Smart City Infrastructure:India's Ministry of Housing and Urban Affairs drives prefabricated substation procurement through its Smart Cities Mission, with municipal corporations specifying compact 11-36 kV units for dense urban corridors.
- IEC 62271-202 Harmonization:The international standard for prefabricated substations is streamlining cross-border certification, reducing retesting costs for equipment suppliers serving multiple ASEAN power markets.
- Copper Winding Substitution:Aluminum-wound transformer designs are gaining traction in cost-sensitive utility segments, enabling manufacturers to offset raw material volatility while maintaining thermal performance specifications.
Market Restraints
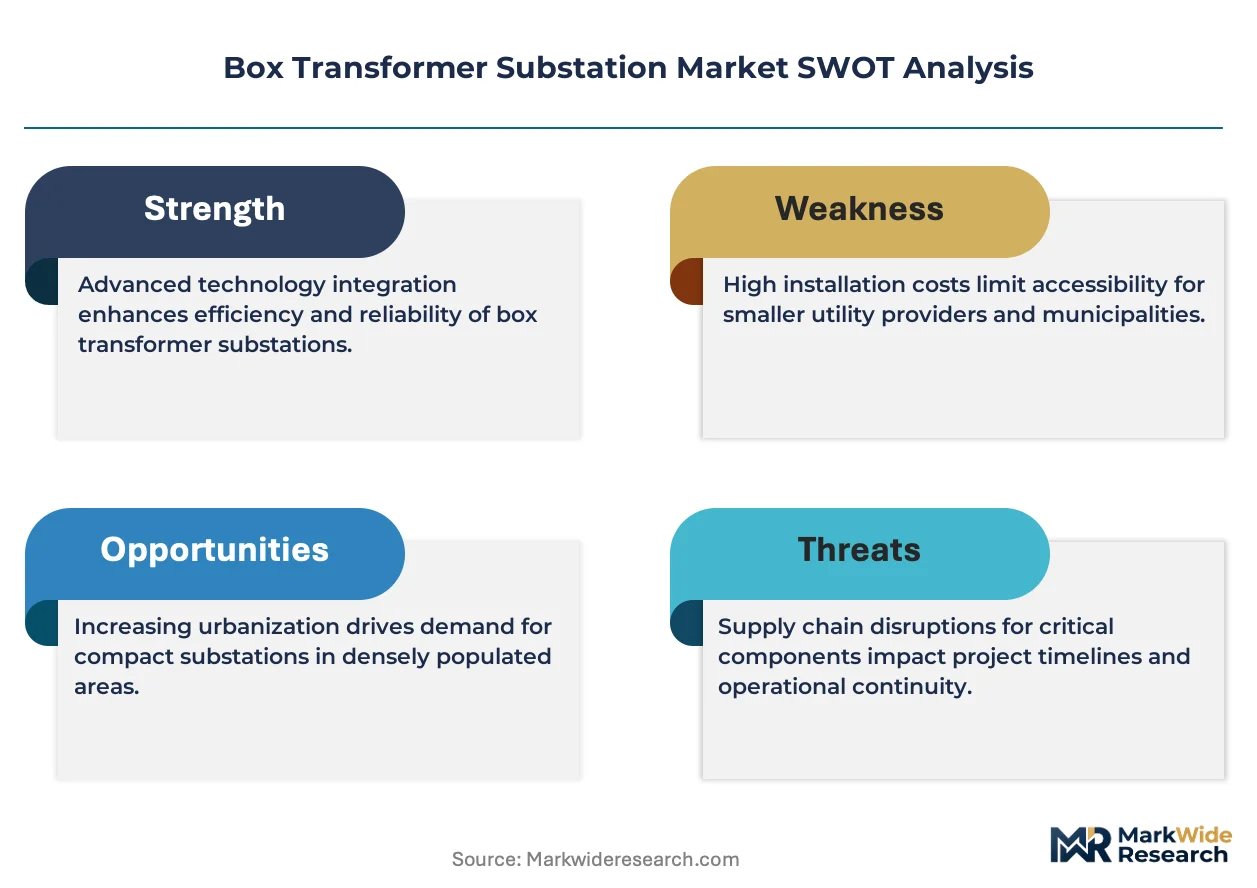
- Silicon Steel Price Volatility:Grain-oriented electrical steel supply concentrates in Chinese and Japanese mills, exposing transformer manufacturers to input cost swings that compress margin buffers on fixed-price utility contracts.
- SF6 Regulatory Friction:The EU F-Gas Regulation is phasing down sulfur hexafluoride use in switchgear insulation, forcing redesign cycles for European-bound substation enclosures before cost-competitive alternatives achieve scale.
- Technical Talent Scarcity:Specialized field technicians capable of integrating digital protection relays with legacy electromechanical systems remain concentrated in mature utility workforces, constraining deployment velocity in emerging markets.
Strategic Opportunities
- Offshore Wind Integration:Vietnam's PDP8 power development plan mandates coastal substation clusters, creating demand for corrosion-resistant enclosure systems rated for salt-laden environments.
- Digital Twin Convergence:Real-time thermal monitoring fused with predictive maintenance algorithms is opening service revenue streams beyond hardware sales for substation OEMs.
- Rural Electrification Channels:India's SAUBHAGYA scheme is channeling compact substations through state distribution companies toward unserved village clusters, bypassing traditional urban-focused distribution networks.
Industry Challenges
- Type Test Certification Timelines:India's Central Electricity Authority mandates witnessed testing at designated laboratories, creating 16-24 week queue delays that misalign with utility procurement schedules.
- Legacy SCADA Integration:Brownfield industrial sites require protocol translation layers between IEC 61850-compliant substation automation and proprietary legacy control systems, inflating commissioning complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Box Transformer Substation Market |
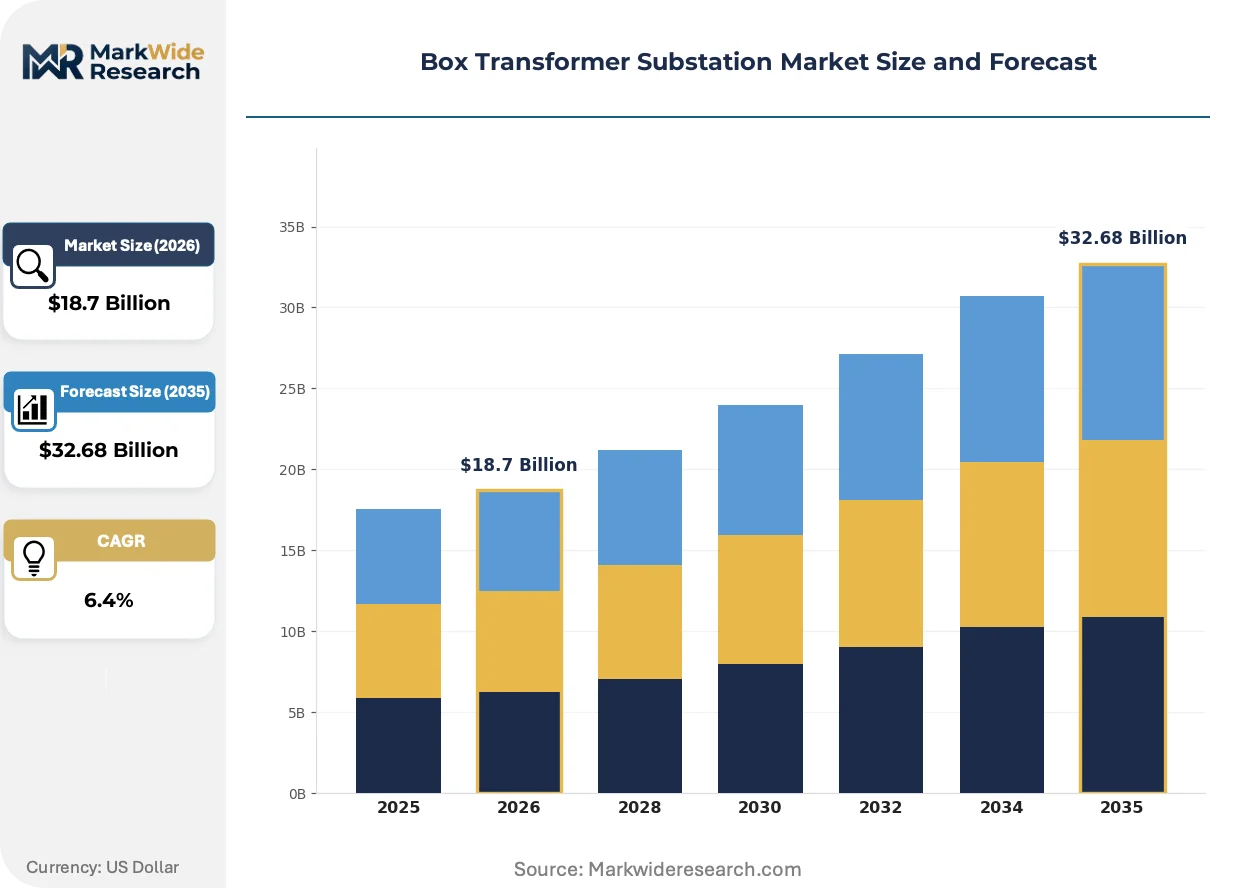
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Outdoor Transformer, Indoor Transformer, Portable Transformer, Compact Transformer Voltage Level: Low Voltage, Medium Voltage, High Voltage, Extra High Voltage End User: Industrial, Commercial, Residential, Utilities Installation Type: Ground Mounted, Pole Mounted, Underground, Integrated |
| Companies Covered | Siemens AG, Schneider Electric SE, ABB Ltd., General Electric, Toshiba, Larsen & Toubro Ltd., Lucy Electric, Eaton Corporation, Hitachi Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Box Transformer Substation Market Trends and Innovations
Digital substation architectures are collapsing traditional hardware hierarchies, with software-defined protection and modular power electronics eroding the boundary between primary equipment and control systems.
Gas-insulated switchgear (GIS) technology is unifying medium-voltage switching functions within hermetically sealed SF6 or fluoronitrile enclosures, slashing footprint by 70% versus air-insulated alternatives. Urban utilities in Singapore and Hong Kong are specifying GIS-integrated box substations for underground substation retrofits where ventilation constraints prohibit conventional designs. This unification is compressing the addressable market for standalone switchgear suppliers while elevating system integrators with in-house GIS capabilities.
The EU F-Gas Regulation is accelerating fluorinated gas phase-down timelines, compelling switchgear manufacturers to validate fluoronitrile or vacuum interrupter alternatives under accelerated aging protocols. Industrial consequence includes premature obsolescence risk for SF6-dependent product lines and capital reallocation toward alternative insulation R&D. Medium-voltage segments serving European utilities face the most acute compliance pressure, with German network operators now requiring g³ gas compatibility in new substation tenders.
Utility procurement departments are consolidating vendor panels and demanding extended warranty terms that bundle equipment, installation, and decade-long maintenance into single-source contracts. Traditional equipment distributors are losing relevance as direct OEM-field service integration becomes the preferred delivery model. This consolidation is most visible in Thailand's Provincial Electricity Authority, which has reduced its approved substation supplier list from 23 to 8 vendors since 2022.
Box Transformer Substation Market Segmentation
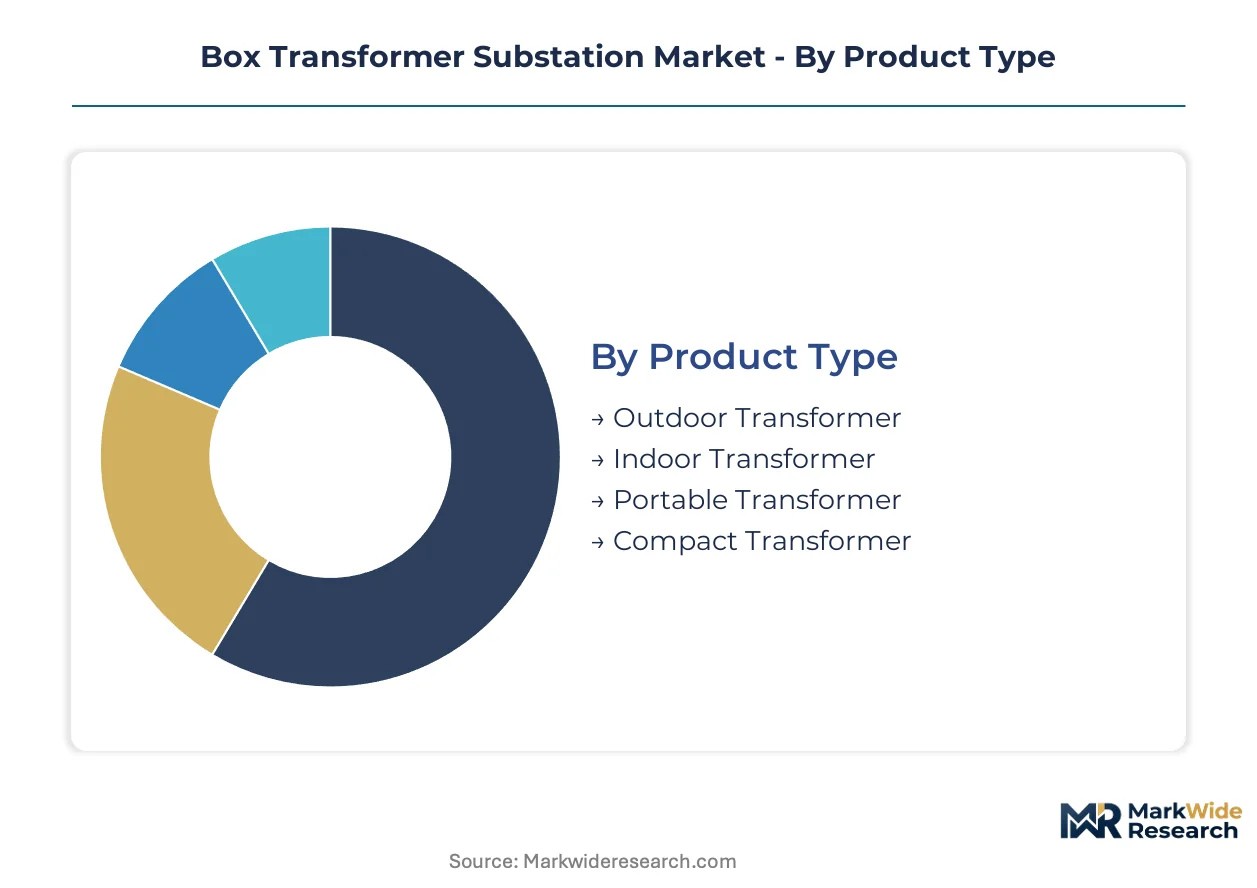
Box transformer substation procurement patterns diverge sharply across voltage tiers and deployment contexts, with manufacturers configuring modular platforms to capture margin pools in premium urban installations while defending volume positions in rural electrification channels.
Product Type:
Supply concentration for enclosure fabrication and transformer integration tilts toward OEMs with captive metalworking capacity and IEC 62271-202 certification infrastructure.
- Outdoor Transformer:Weatherproof steel or aluminum enclosures house oil-immersed or dry-type transformers for exposed utility yard installations. Demand concentrates in India's state distribution companies deploying 11-36 kV units for rural feeder extensions under SAUBHAGYA scheme targets.
- Compact Transformer:Reduced-footprint designs integrate GIS switchgear and forced-air cooling for dense urban corridors where land scarcity and noise restrictions apply most stringently. Singapore's SP Group and Hong Kong's CLP Power specify these for underground substation retrofits with ventilation constraints.
- Indoor Transformer:Ventilated enclosures rated for building-integrated deployment in commercial complexes and data centers.
- Portable Transformer:Skid-mounted or trailer-based configurations for temporary construction power and emergency restoration.
Today's leader: Outdoor Transformer. Tomorrow's challenger: Compact Transformer.
Voltage Level:
Margin structures escalate non-linearly with insulation complexity, creating tiered engineering premiums that reward specialized OEMs with in-house high-voltage testing bays.
- Medium Voltage:11-36 kV ratings constitute the largest installed base across utility distribution networks and industrial plant interconnections. Procurement concentrates in Thailand's Provincial Electricity Authority and Vietnam's EVN as grid modernization accelerates across ASEAN power markets.
- Extra High Voltage:Custom insulation systems and liquid cooling architectures command disproportionate engineering margins for transmission-level interconnections. Demand clusters in Vietnam's PDP8 coastal wind integration zones requiring corrosion-resistant enclosure systems.
- Low Voltage:Final distribution step-down for residential clusters and small commercial loads.
- High Voltage:Sub-transmission interfaces between regional grids and primary distribution substations.
Medium Voltage commands current volume leadership; Extra High Voltage offers the steepest expansion trajectory as offshore wind integration scales.
End User:
Customer concentration patterns split between centralized utility procurement with extended warranty demands and fragmented industrial buyers prioritizing commissioning speed.
- Utilities:Grid operators specify factory-tested modular systems with decade-long service bundling, consolidating vendor panels aggressively. Thailand's PEA reduced approved substation suppliers from 23 to 8 vendors since 2022, favoring OEMs with integrated field service networks.
- Industrial:Manufacturing plants and process facilities demand rapid deployment to minimize production downtime during power infrastructure upgrades. Brownfield sites require protocol translation layers between IEC 61850 automation and legacy SCADA systems.
- Commercial:Shopping complexes, hospitals, and data centers seeking compact urban solutions.
- Residential:Clustered housing developments and gated community distribution requirements.
Utility procurement dominates current contract value; Industrial verticals are gaining share fastest as manufacturing reshoring drives captive power infrastructure investment.
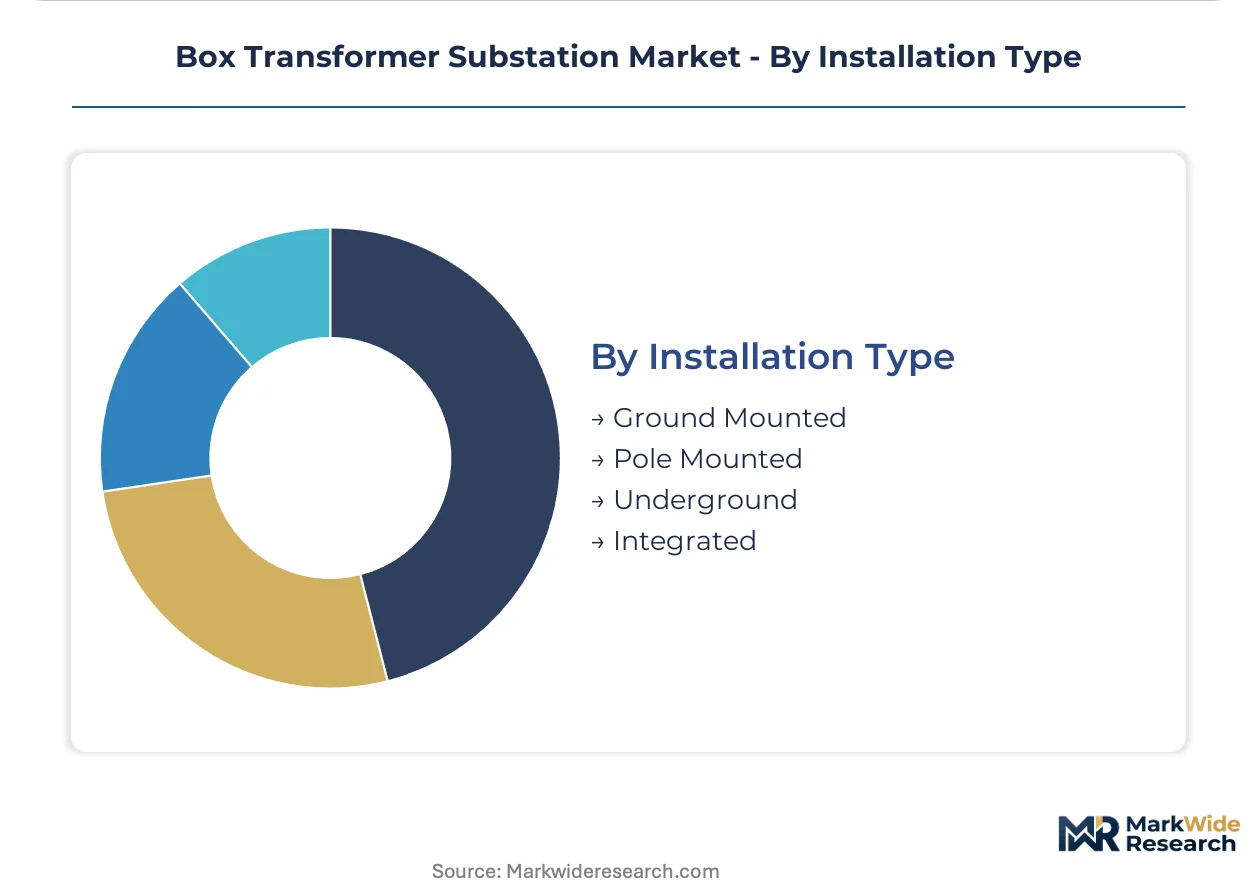
Installation Type:
Site constraints and civil engineering economics determine technology selection, with underground and integrated configurations capturing premium pricing in land-scarce metropolitan zones.
- Ground Mounted:Concrete pad or gravel bed foundations for utility yard and industrial site deployments with available land area. India's smart city municipal corporations specify these for peripheral zone substations where underground civil costs prove prohibitive.
- Underground:Vault-housed or direct-buried configurations eliminating surface footprint for dense urban cores. Singapore and Hong Kong utilities mandate these for central business district retrofits where above-ground space is unavailable.
- Pole Mounted:Elevated single-transformer units for rural radial distribution feeders.
- Integrated:Building-embedded or facade-incorporated designs for architectural constraints.
Ground Mounted retains volume dominance; Underground configurations are expanding most quickly as Asian megacity densification intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized substation engineers cluster in Germany's industrial zones and India's utility corridors, anchoring design-to-deployment capabilities for prefabricated power infrastructure.
India
State distribution companies under the SAUBHAGYA rural electrification scheme drive compact 11-36 kV unit procurement for village feeder extensions. The Central Electricity Authority mandates witnessed type testing at designated laboratories, compressing vendor qualification timelines. Maharashtra and Gujarat host the densest concentrations of domestic enclosure fabricators serving municipal smart city contracts.
Germany
Network operators now require g³ gas compatibility in new substation tenders under accelerated EU F-Gas Regulation phase-down schedules. The country's technical inspection associations enforce enhanced arc-flash containment protocols for urban underground installations. Industrial demand clusters in North Rhine-Westphalia's manufacturing belt and Bavaria's automotive production zones.
China
The State Administration for Market Regulation enforces GB standards for substation equipment certification, streamlining domestic procurement while creating compliance barriers for imported systems. Grid modernization investments concentrate in coastal provinces where offshore wind integration requires corrosion-resistant enclosure architectures. Yangtze River Delta utilities specify factory-tested modular systems for rapid urban deployment.
Vietnam
EVN's distribution network expansion aligns with PDP8 coastal wind development zones, creating demand for salt-resistant enclosure systems. The national power development plan mandates substation clusters within 50 kilometers of planned offshore wind farms. Procurement activity concentrates in Ho Chi Minh City and the central coastal provinces where industrial zone electrification accelerates.
Thailand
The Provincial Electricity Authority consolidated approved substation suppliers from 23 to 8 vendors since 2022, favoring OEMs with integrated field service networks. Board of Investment incentives channel foreign direct investment toward high-voltage equipment manufacturing. Bangkok's underground substation retrofits and eastern seaboard industrial estates anchor current demand concentration.
Box Transformer Substation Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the box transformer substation sector, with integrated OEMs controlling high-reliability segments while regional fabricators capture cost-sensitive utility volume. Market structure tilts toward consolidation as procurement departments demand decade-long service bundling and direct field service integration. Three archetypes dominate: diversified electrical conglomerates with captive transformer manufacturing, specialized GIS-integrated system integrators, and regional enclosure fabricators serving single-country certification requirements. Competitive intensity centers on M&A activity absorbing regional players into global service networks and capacity expansion into Southeast Asian manufacturing hubs.
Among diversified electrical conglomerates, Siemens AG and Schneider Electric SE occupy positions exemplifying the integrated technology-and-service archetype, while ABB Ltd. anchors the premium reliability tier for utility and heavy industrial segments. These European-headquartered entities represent the dominant competitive force as procurement consolidation favors vendors with transnational certification infrastructure and captive field service organizations spanning multiple ASEAN power markets.
| Leading Market Players |
|---|
| Siemens AG |
| Schneider Electric SE |
| ABB Ltd. |
| General Electric |
| Toshiba |
| Larsen & Toubro Ltd. |
| Lucy Electric |
| Eaton Corporation |
| Hitachi Energy |
| Others |
Pricing and Supply Chain Analysis
GIS-integrated compact substation architectures are simultaneously compressing manufacturing cost curves and concentrating supply among OEMs with captive metalworking and hermetic sealing capabilities. This technology shift rewards integrated producers with in-house transformer winding and enclosure fabrication while marginalizing standalone switchgear suppliers.
Pricing Analysis
The bundled-vs-unbundled service split separates OEMs offering decade-long maintenance contracts from equipment-only vendors. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and after-sales bundling intensity. Cost compression in economy tiers is intensifying because aluminum-wound transformer designs are displacing copper in cost-sensitive utility segments. State distribution companies exhibit highest price sensitivity; offshore wind developers show lowest sensitivity due to corrosion-resistance premiums.
Supply Chain Analysis
Direct-to-utility channels handle centralized procurement from Thailand's PEA and India's state discoms, while indirect distribution serves fragmented industrial buyers. Grain-oriented electrical steel supply concentrates in Chinese and Japanese mills, with transformer cores drawing from these sources. Aluminum winding wire and SF6 alternative gases represent critical input dependencies. Single-source vulnerability in electrical steel exposes manufacturers to input cost swings. Distribution runs through OEM-integrated field service networks as procurement consolidates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through aluminum-wound transformer substitution and premium-tier GIS-integrated system demand from Asian megacity underground retrofits.
For Market Incumbents: To counter procurement consolidation by Thailand's PEA and India's state utilities, deepen backward integration into transformer core manufacturing and secure IEC 62271-202 certification infrastructure across multiple ASEAN markets. Prioritize direct field service network expansion to meet bundled warranty demands. For New Entrants and Emerging Players: EU F-Gas Regulation phase-down timelines open a window for fluoronitrile-compatible GIS entrants in European utility tenders. Target Vietnam's PDP8 coastal wind zones with salt-resistant enclosure specialization. Pursue white-label partnerships with established OEMs lacking corrosion-resistant product lines. For Investors and Strategic Acquirers: Valuations sit cheapest among regional enclosure fabricators with single-country certification but transferable technical capabilities. Five-to-ten year viability favors targets with captive GIS integration expertise. Monitor German network operator tender language for g³ gas compatibility mandates as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| GIS Technology Integration | Unifies switching functions within sealed enclosures, slashing footprint for Singapore and Hong Kong underground retrofits. |
| Backward Integration into Core Steel | Captive grain-oriented electrical steel sourcing insulates margins from Chinese and Japanese mill price volatility. |
| Fluoronitrile Validation Investment | Accelerates EU F-Gas Regulation compliance for European-bound substation tenders ahead of SF6 phase-down. |
| Direct Field Service Expansion | Aligns with Thailand PEA vendor consolidation toward OEMs with integrated installation and maintenance networks. |
| Rural Electrification Channel Development | Captures India's SAUBHAGYA scheme volume through state distribution company procurement bypassing urban networks. |
Research Methodology
Bottom-up utility procurement modeling reconciled against top-down transformer manufacturing capacity tracking forms the analytical core. Primary interviews with utility planning officers, EPC contractors, substation OEM product managers, and state distribution company procurement heads combined with secondary validation from IEC certification databases, Central Electricity Authority type test registries, and ASEAN power development plan filings. Triangulation across these sources ensures demand-side and supply-side estimates converge.
Input-output matrices map transformer core steel consumption, GIS switchgear production, and enclosure fabrication capacity against utility capex cycles and smart city infrastructure budgets. Segmentation dimensions span voltage tier, installation type, end-use vertical, and regional regulatory cluster. CAGRs derive from installed base growth rates and replacement demand modeling. Forecast inputs include aluminum-copper price spreads and F-Gas Regulation compliance timelines.
Revisions become necessary when raw material price volatility exceeds historical bands or when regulatory phase-down schedules accelerate. Forecasts reflect assumptions about grid modernization funding continuity and certification laboratory capacity expansion. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transformers
India Distribution Transformer Market
Transformers
Step Up/Down Transformers Market
Transformers
North America Transformer Market
Transformers
United States Dry-Type Transformer Market
Transformers
Three Phase Transformer Market
Transformers
Rail Traction Transformers Market
Transformers
Europe Distribution Transformer Market
Transformers
Global Transformer Market
Transformers
HVDC Converter Transformers Market
Transformers
Liquid-Immersed Transformers Market
Transformers
Asia-Pacific Transformer Market
Transformers
Power Transformer Market
Transformers
Europe Oil Filled Distribution Transformer Market
Transformers
North America Smart Transformers Market
Transformers
North America Oil Filled Transformer Market
Transformers
Cast Resin Transformers Market