
 Marine Power Plant Market | 2026-2036
Marine Power Plant Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Power Plant Market Outlook
The IMO 2023 Carbon Intensity Indicator is shifting compliance burdens onto vessel operators, raising capital requirements for engine upgrades and retrofits. Wärtsilä Corporation leverages its dual-fuel portfolio to anchor contracts across European and Asian shipyards. MAN Energy Solutions SE competes through specialized methanol-ready engine architectures. Rolls-Royce Power Systems AG sustains its position in naval and yacht segments through integrated power and automation systems.
Marine power plants encompass self-contained propulsion and electricity generation systems installed aboard vessels, typically delivering outputs from 1 MW to over 80 MW through diesel, gas turbine, steam, or nuclear configurations. These systems convert thermal or mechanical energy into shaft power for propulsion and electrical power for onboard operations, with thermal efficiency and emissions profiles determining operational economics over vessel lifespans spanning 25–40 years. Diesel generators retain the largest installed base across commercial shipping, though gas turbines occupy the premium segment where power density and rapid load response justify higher fuel consumption. Hybrid technology is recording the fastest order growth as battery integration allows peak shaving and port maneuvering on electric power alone, while thermal desalination-linked plants serve specialized offshore platform demand.
The International Maritime Organization, the US EPA under its marine diesel engine standards, and the EU MRV regulation collectively enforce emissions transparency and fuel sulfur limits that reshape engine procurement criteria. Classification societies including Lloyd's Register and DNV implement type-approval protocols that gate market access for new power plant designs. Stakeholders must monitor fuel infrastructure buildout at major bunkering hubs to validate technology bets on ammonia, methanol, or hydrogen-derived propulsion pathways.
Market Dynamics
Dual-fuel engine architectures are compressing the competitive window for conventional diesel plants as shipowners face IMO 2023 Carbon Intensity Indicator compliance deadlines and bunker fuel infrastructure bifurcates between traditional and alternative pathways.
Growth Catalysts
- IMO Carbon Intensity Regulations:The 2023 CII framework mandates annual efficiency improvements that force vessel operators toward engine retrofits and newbuilds with lower carbon intensity ratings.
- South Korean Shipyard Concentration:Government-backed green shipping corridors at Hyundai Heavy Industries and Samsung Heavy Industries are accelerating procurement of methanol-ready and ammonia-capable propulsion packages.
- NATO Naval Modernization:Fleet recapitalization programs across member states are expanding integrated electric propulsion contracts for surface combatants and auxiliary vessels.
Market Restraints
- Alternative Fuel Infrastructure Gaps:Bunkering availability for methanol and ammonia remains concentrated at Rotterdam, Singapore, and Shanghai, limiting route flexibility for early adopters.
- Stainless Steel and Nickel Alloy Costs:High-performance materials required for corrosive fuel compatibility expose engine manufacturers to commodity price volatility in specialty metallurgy supply chains.
- Classification Society Type-Approval Bottlenecks:Lloyd's Register and DNV protocols for novel fuel systems extend certification timelines by 18–24 months versus conventional diesel architectures.
Strategic Opportunities
- Offshore Platform Electrification:Floating production units are adopting hybrid gas turbine-battery configurations to reduce flaring and meet North Sea environmental discharge permits.
- EU Emissions Trading System Expansion:Maritime inclusion in the EU ETS from 2024 creates compliance-driven demand for monitoring, reporting, and verification-integrated power management systems.
- Battery-Thermal Convergence:Peak shaving architectures combining lithium-ion storage with medium-speed diesel engines enable port maneuvering on electric power alone, cutting harbor emissions.
Industry Challenges
- Marine Engineer Skill Shortages:Operation of multi-fuel injection systems and cryogenic fuel handling requires retraining programs that ship operators struggle to staff at scale.
- Retrofit Capex Recovery:Engine room modification costs for dual-fuel compatibility face payback period skepticism from asset owners with 10–15 year remaining vessel lifespans.
- Legacy Control System Integration:New power plants must interface with existing automation networks, creating commissioning delays and warranty disputes between subsystem suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Power Plant Market |
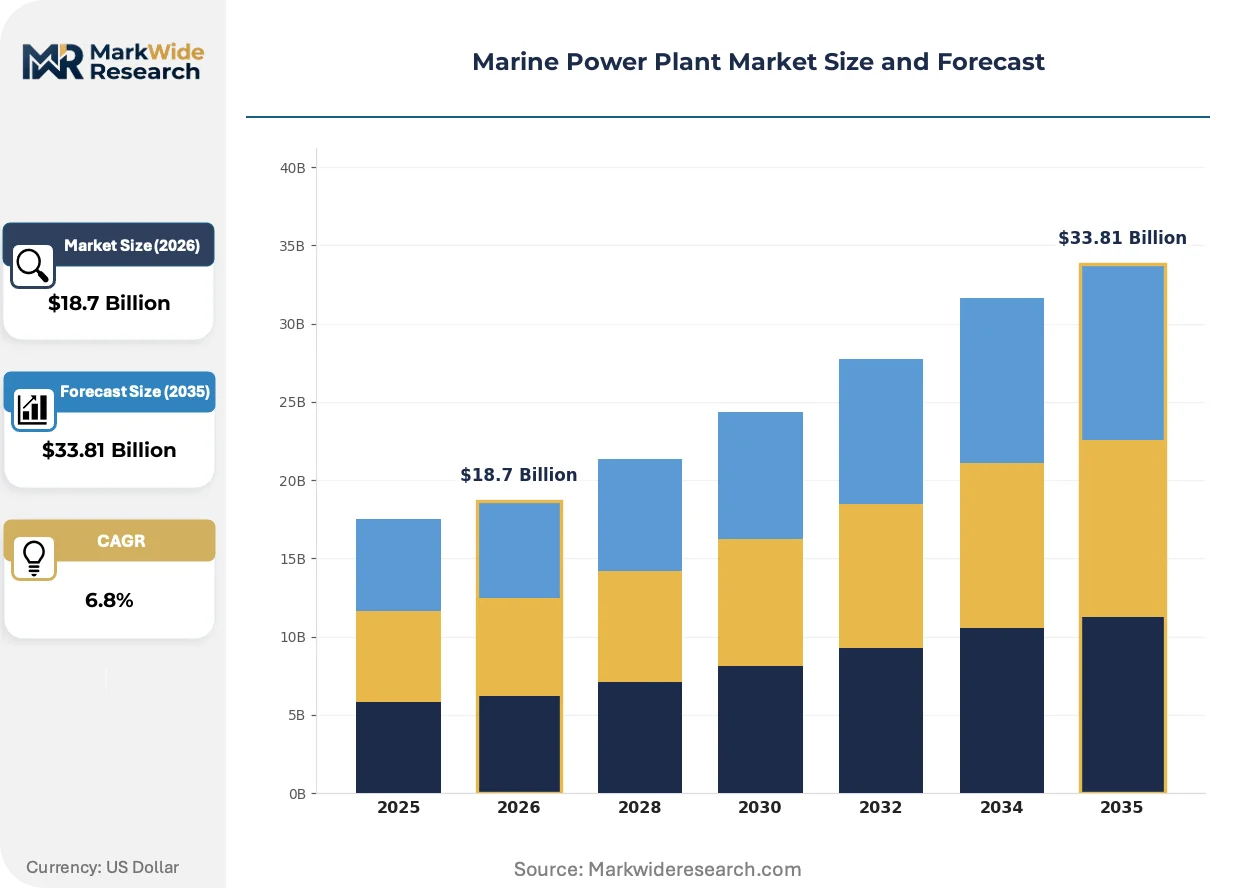
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas Turbines, Steam Turbines, Diesel Generators, Nuclear Reactors Technology: Combustion, Renewable, Hybrid, Thermal Desalination End User: Utilities, Industrial, Government, Private Sector Deployment: Onshore, Offshore, Coastal, Inland |
| Companies Covered | Rolls-Royce Power Systems AG, Mitsubishi Heavy Industries, Ltd., Wärtsilä Corporation, Cummins Inc., ABB Ltd., MAN Energy Solutions SE, General Electric Company, Volvo Penta, Caterpillar Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Power Plant Market Strategic Shifts
Propulsion technology is bifurcating between evolutionary efficiency gains in conventional thermal cycles and disruptive alternative fuel architectures that demand entirely new supply chain and operational competencies.
Hybrid battery-diesel systems are integrating into mainstream commercial shipping as container lines and ferry operators seek to optimize load profiles. Maersk and DFDS vessel categories are adopting these configurations fastest, driven by port authority zero-emission maneuvering mandates. The technology is integrating peak shaving and spinning reserve functions that reduce main engine cycling and extend overhaul intervals.
The EU MRV regulation and its extension into the Emissions Trading System is forcing granular fuel consumption disclosure across all voyages touching European ports. Shipowners now face direct carbon cost exposure that reshapes power plant procurement criteria toward verifiable efficiency guarantees. Deep-sea container shipping is responding with engine performance clauses in charter agreements that penalize excess consumption.
Charter-party contracting is compressing the traditional split between vessel technical management and commercial operation. Shipowners are unbundling power plant maintenance from crew management, creating specialized service contracts with engine OEMs. This shift is most visible in Greek and German-owned fleets operating under third-party technical management agreements.
Marine Power Plant Market Segmentation
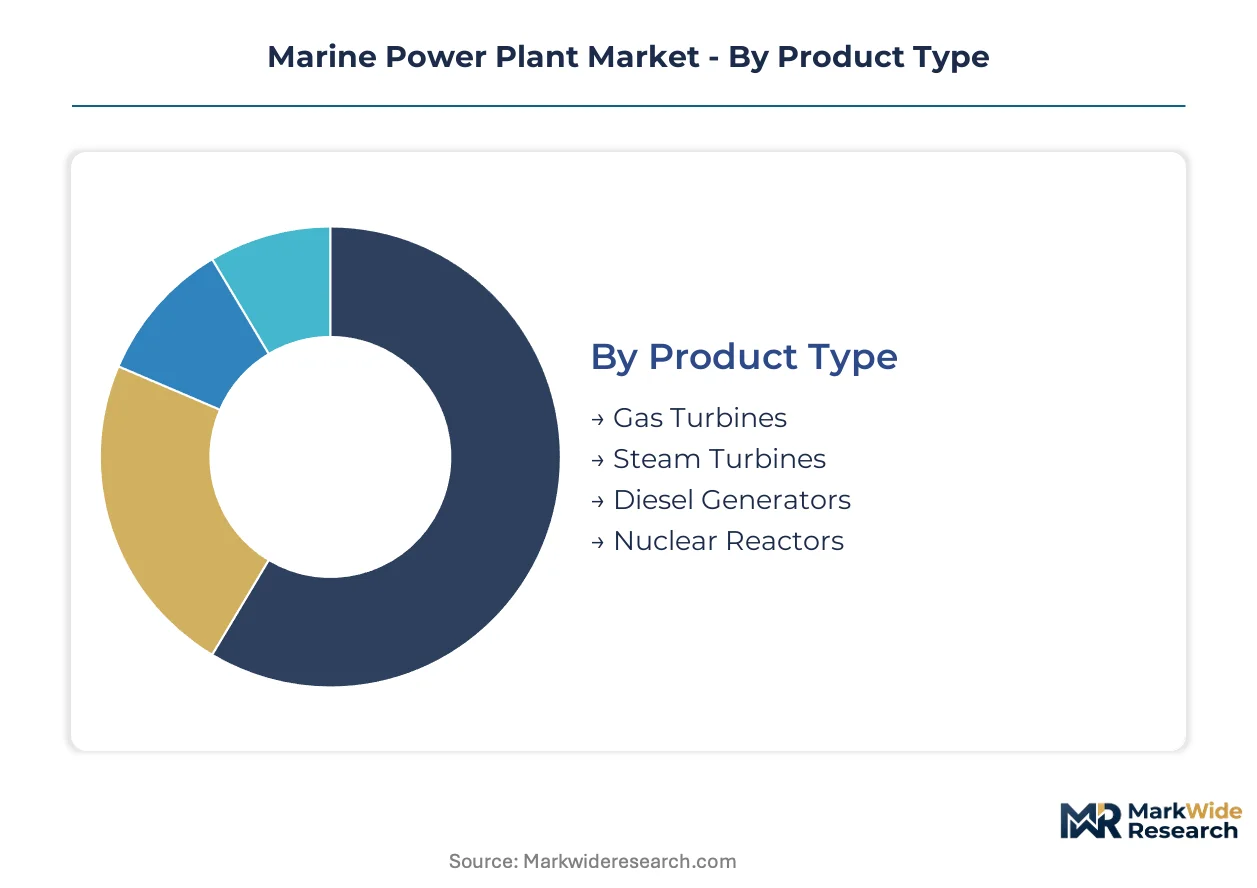
Marine power plant procurement hinges on vessel operating profiles, fuel infrastructure availability, and regulatory compliance timelines. Segmentation reveals how capital allocation diverges between established thermal technologies and emerging hybrid architectures.
Product Type:
Capital intensity varies dramatically across propulsion architectures, with nuclear and dual-fuel gas turbines demanding the highest upfront investment while diesel generators offer the lowest entry threshold.
- Diesel Generators:Medium-speed and slow-speed reciprocating engines dominate commercial shipping fleets, delivering 1–80 MW outputs with established MGO and HFO bunkering infrastructure. Container lines operating Asia-Europe routes favor these units for their fuel flexibility and proven IMO Tier III compliance pathways.
- Gas Turbines:Aeroderivative and industrial gas turbine configurations serve naval combatants and high-speed ferries where power density and rapid load response justify higher specific fuel consumption. South Korean shipyards are integrating these with combined heat and power systems for LNG carriers.
- Steam Turbines:Rankine cycle plants persist in nuclear-powered naval vessels and legacy tankers, though new orders concentrate in specialized applications requiring waste heat recovery integration.
- Nuclear Reactors:Pressurized water reactor plants power aircraft carriers and icebreakers for the US Navy and Russian Federation fleets, constrained by proliferation controls and port access restrictions.
Diesel generators absorb the bulk of installed capacity; gas turbines are expanding most quickly in premium naval and LNG carrier segments.
Technology:
Technology selection tracks fuel pathway maturity, with hybrid systems bridging the gap between conventional combustion and fully renewable propulsion.
- Combustion:Internal combustion engines utilizing diesel, heavy fuel oil, or natural gas retain the largest order book across cargo shipping, with dual-fuel injection systems now standard for newbuilds at major European and Asian yards.
- Hybrid:Battery-diesel and battery-gas turbine configurations enable peak shaving and harbor maneuvering on electric power alone. Norwegian ferry operators and Danish container lines are adopting these systems fastest under port authority zero-emission mandates.
- Renewable:Wind-assisted propulsion and solar-hybrid auxiliary systems serve coastal shipping segments with predictable route profiles and favorable wind conditions.
- Thermal Desalination:Multi-stage flash and multi-effect distillation plants integrated with power generation serve offshore oil platforms in the Persian Gulf and North Sea regions.
Combustion technology retains the dominant revenue share; hybrid architectures are climbing the fastest as battery costs decline and port regulations tighten.
End User:
End-user categories reflect divergent procurement cycles, with government fleets operating on decade-long modernization programs and private operators responding to spot market fuel price signals.
- Utilities:Floating power barges and mobile generation units serve grid stabilization and emergency backup roles in island nations and coastal developing economies.
- Industrial:Offshore oil and gas operators deploy combined power and processing plants on floating production storage and offloading vessels, with North Sea environmental permits driving hybrid gas turbine-battery adoption.
- Government:Naval fleet recapitalization across NATO members and Pacific Rim allies sustains demand for integrated electric propulsion and advanced automation systems.
- Private Sector:Container shipping lines, cruise operators, and ferry companies optimize power plant selection against charter rate volatility and EU Emissions Trading System compliance costs.
Private sector procurement dominates annual order volumes; government programs provide the most stable long-term demand visibility.
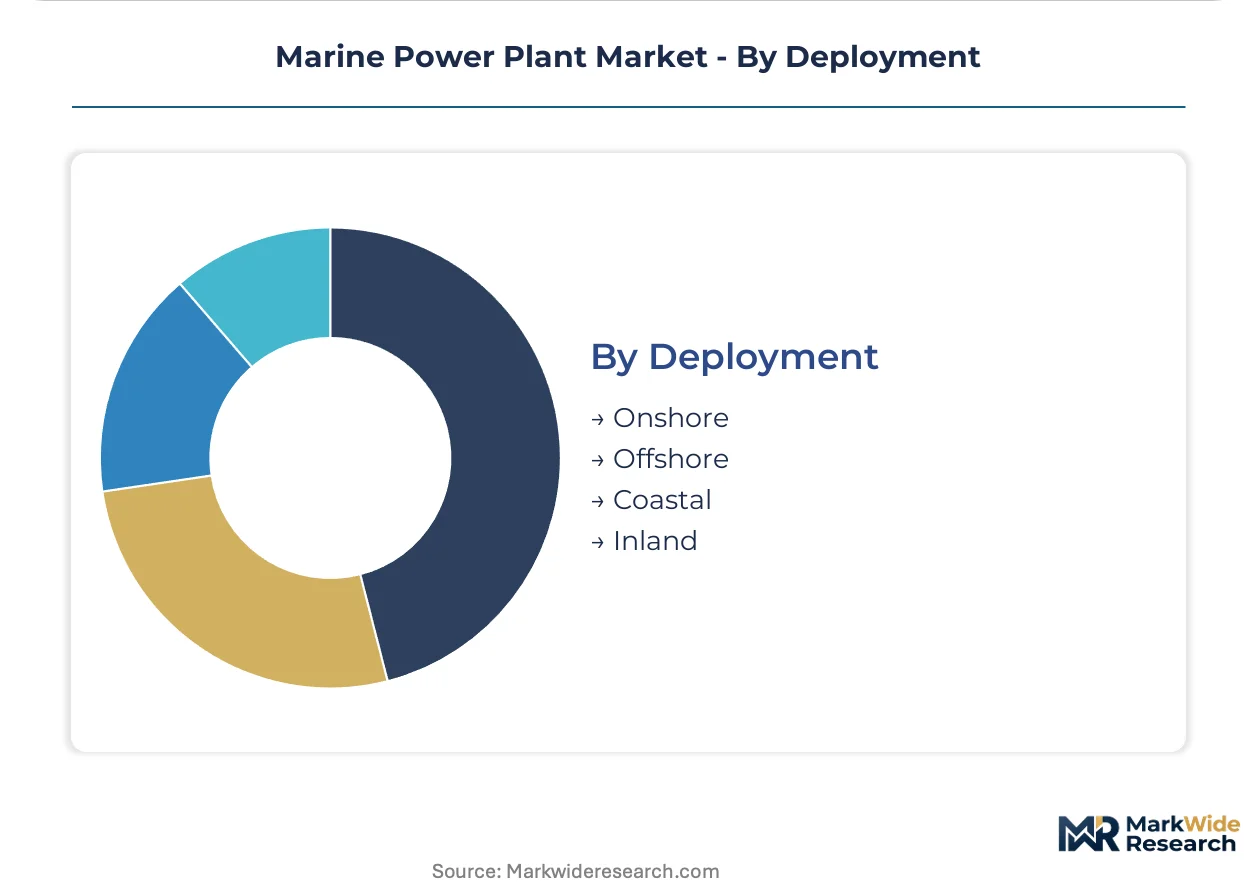
Deployment:
Deployment mode determines environmental exposure, maintenance access, and regulatory jurisdiction, with offshore installations facing the most stringent safety and emissions oversight.
- Offshore:Floating production units, drilling rigs, and accommodation platforms require redundant power architectures capable of withstanding severe weather and supply chain interruptions.
- Coastal:Harbor craft, short-sea shipping, and inland waterway vessels operate under overlapping national and port authority emissions regulations, favoring hybrid and alternative fuel configurations.
- Onshore:Land-based marine engine test facilities and shore power connections support vessel commissioning and cold-ironing operations at major bunkering hubs.
- Inland:River barges and lake freighters face draft and bridge clearance constraints that limit power plant size and fuel storage capacity.
Offshore deployment commands the highest unit values; coastal applications are gaining share fastest under port decarbonization mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korean free economic zones at Ulsan and Geoje anchor the densest concentration of marine power plant manufacturing, with government-backed green shipping corridors funneling procurement toward dual-fuel and ammonia-ready propulsion systems.
South Korea
Hyundai Heavy Industries and Samsung Heavy Industries drive newbuild demand for methanol-capable engine packages under the national K-Shipbuilding Super Gap Vision program. The Ministry of Oceans and Fisheries mandates carbon intensity reductions across coastal shipping lanes by 2030. Busan and Ulsan shipyards now specify dual-fuel architectures as standard for container vessels above 8,000 TEU.
China
State-owned shipbuilders at Shanghai and Dalian expand orders for integrated electric propulsion systems serving Belt and Road container routes. The Ministry of Industry and Information Technology enforces domestic content requirements for critical propulsion components. The Yangtze River Delta cluster concentrates manufacturing of medium-speed diesel generators for coastal bulk carriers.
Germany
Naval fleet modernization across NATO's northern flank sustains demand for combined diesel-electric and gas turbine plants at Thyssenkrupp Marine Systems. The Federal Maritime and Hydrographic Agency implements stringent type-approval protocols for alternative fuel injection systems. Hamburg and Bremen harbor districts mandate shore power connections that accelerate hybrid auxiliary system retrofits.
United States
Navy surface combatant recapitalization programs at Ingalls Shipbuilding and Bath Iron Works anchor integrated power system procurement. The EPA's Tier 4 marine diesel standards drive engine room upgrades across Jones Act-compliant fleets. The Gulf Coast petrochemical corridor sustains demand for offshore platform power modules with waste heat recovery integration.
Norway
Ferry operators on coastal routes adopt battery-hybrid configurations to comply with zero-emission harbor mandates at Bergen and Stavanger. The Norwegian Maritime Authority enforces strict nitrogen oxide limits in designated emission control areas. Kongsberg Maritime anchors automation system integration for electric propulsion architectures serving North Sea offshore vessels.
Marine Power Plant Market Competitive Environment
European producers anchor the premium propulsion tier; East Asian fabricators hold volume manufacturing positions. The market structures around three to five integrated system suppliers with established classification society relationships, tiered by fuel pathway specialization and naval contract access. Strategic archetypes include dual-fuel engine specialists, integrated automation providers, and naval prime contractors. Competitive moves concentrate on technology licensing partnerships and backward integration into fuel injection component manufacturing.
Within the dual-fuel engine tier, Wärtsilä Corporation and MAN Energy Solutions SE occupy positions defined by methanol and ammonia readiness portfolios. Rolls-Royce Power Systems AG anchors the naval and yacht automation segment. These three exemplify divergent strategic postures: Wärtsilä leverages Scandinavian engineering heritage across commercial shipping; MAN Energy Solutions SE maintains German precision manufacturing credentials; Rolls-Royce Power Systems AG sustains British defense-aerospace lineage in integrated power management.
| Leading Market Players |
|---|
| Rolls-Royce Power Systems AG |
| Mitsubishi Heavy Industries, Ltd. |
| Wärtsilä Corporation |
| Cummins Inc. |
| ABB Ltd. |
| MAN Energy Solutions SE |
| General Electric Company |
| Volvo Penta |
| Caterpillar Inc. |
| Others |
Value Chain & Pricing Dynamics
Dual-fuel engine platform transitions at Hyundai Heavy Industries and Samsung Heavy Industries simultaneously compress manufacturing cost curves and concentrate procurement leverage among South Korean shipyard conglomerates. This technological pivot forces tier-two suppliers to absorb stainless steel and nickel alloy volatility while OEMs extract volume discounts through captive fuel injection component sourcing.
Pricing Analysis
Lead-time premiums now dominate contract negotiations, with shipyards paying 15-20 percent markups for methanol-ready engine packages delivered under 18-month windows versus standard 24-month cycles. Three-tier pricing structure across premium, standard, and economy levels reflects classification society certification tier and after-sales service bundling. Pricing pressure stems from South Korean yard consolidation forcing component suppliers into multi-year fixed-price agreements. Charter operators under third-party technical management exhibit highest price sensitivity, while NATO procurement offices prioritize performance guarantees over unit economics.
Supply Chain Analysis
Freight costs for specialty nickel alloy forgings from Germany and precision fuel injection components from Japan now constitute 8-12 percent of landed engine assembly costs, up from historical 4-6 percent baselines. Manufacturing concentrates in South Korea, Germany, and Finland for high-complexity propulsion systems; China dominates medium-speed diesel generator fabrication. Raw material exposure centers on nickel superalloys, high-grade stainless steel, and rare-earth magnets for permanent-magnet generators. Single-source vulnerability persists for cryogenic fuel valve assemblies qualified under Lloyd's Register protocols. Distribution runs through shipyard-integrated procurement consortia rather than independent aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized metallurgy capacity constraints at European forges prop pricing power for incumbent OEMs with captive supply arrangements. This supply-constrained structure favors early-mover consolidation and backward integration investments.
For Market Incumbents: Anticipate margin compression from Chinese state-owned shipbuilders developing indigenous dual-fuel injection capabilities. Defensive moves require securing long-term offtake agreements with Busan and Ulsan yards while deepening backward integration into nickel alloy casting facilities in Germany and Finland. Certification investment in ammonia-ready architectures represents the critical lever for sustaining premium positioning. For New Entrants and Emerging Players: EU Emissions Trading System expansion opens a window for compliance-integrated power management software specialists. White-space targets concentrate in retrofit automation for Greek and German-owned fleets operating under third-party technical management. The most penetrable segment is battery-thermal hybrid auxiliary systems for coastal ferry operators. Go-to-market positioning should emphasize port authority zero-emission mandate compliance as the immediate value proposition. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by defense-aerospace conglomerates seeking naval propulsion capabilities. Long-term viability hinges on fuel pathway optionality across methanol, ammonia, and hydrogen derivatives. Acquisition targets should display established classification society relationships with Lloyd's Register or DNV alongside active contracts at South Korean tier-one yards. The signal to watch is bunker fuel infrastructure buildout velocity at Rotterdam and Singapore as validation of technology bets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fuel Injection Components | Captive supply of cryogenic valves insulates margins from nickel alloy volatility at European forges. |
| Ammonia-Ready Architecture Certification | DNV type-approval for ammonia fuel systems secures early-mover positioning at South Korean green shipping corridors. |
| Hybrid Battery-Thermal System Launch | Peak shaving configurations address Bergen and Stavanger zero-emission harbor mandates for Norwegian ferry operators. |
| Long-Term Service Agreement with Shipyard Consortium | Multi-year maintenance contracts with Hyundai Heavy Industries stabilize revenue visibility across vessel lifecycles. |
| Naval Electric Propulsion Partnership | Integrated power system contracts with Thyssenkrupp Marine Systems access NATO fleet recapitalization programs. |
Study Parameters
IMO regulatory filings, Lloyd's Register type-approval databases, and South Korean Ministry of Oceans and Fisheries procurement records formed the secondary backbone of this analysis. Primary fieldwork involved structured interviews with marine engineering directors at container lines, naval program officers at NATO procurement agencies, and aftermarket service heads at European OEMs. Triangulation across these sources validated bottom-up vessel order book assessments against top-down fleet modernization budget allocations.
Bottom-up modeling tracked individual propulsion system contracts by vessel class and fuel pathway, while top-down analysis anchored on national shipbuilding output projections and defense procurement disclosures. Segmentation dimensions included propulsion architecture, technology type, end-user category, and deployment mode. CAGRs were derived from regression analysis of historical order patterns against regulatory compliance timelines. Industry-specific inputs incorporated bunker fuel infrastructure development trajectories and classification society certification pipeline durations.
The model assumes a particular technology adoption path; alternative pathways for ammonia propulsion would alter the outlook if bunkering infrastructure deployment lags shipyard order cycles. Forecasts reflect assumptions regarding IMO Carbon Intensity Indicator enforcement stringency and NATO fleet recapitalization funding continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Generation
Global Distributed Energy Generation Market
Power Generation
Asia-Pacific Distributed Power Generation Market
Power Generation
Retail Electricity Market
Power Generation
East Africa Power Market
Power Generation
Steam Turbine Market
Power Generation
Oman Power Market
Power Generation
Europe Distributed Power Generation Market
Power Generation
Indonesia Power Market
Power Generation
Global Gensets Market
Power Generation
Algeria Power Market
Power Generation
Global Gas Turbines Market
Power Generation
Europe Thermal Power Market
Power Generation
Peaking Power Plant Market
Power Generation
Gas Turbines in Thermal Power Market
Power Generation
Steam Turbine for Power Generation Market
Power Generation
Thermal Power Market