
 Vacuum Circuit Breaker Market | 2026-2036
Vacuum Circuit Breaker Market Size, Share, and Industry Trends Forecast 2026-2036
Vacuum Circuit Breaker Market Analysis
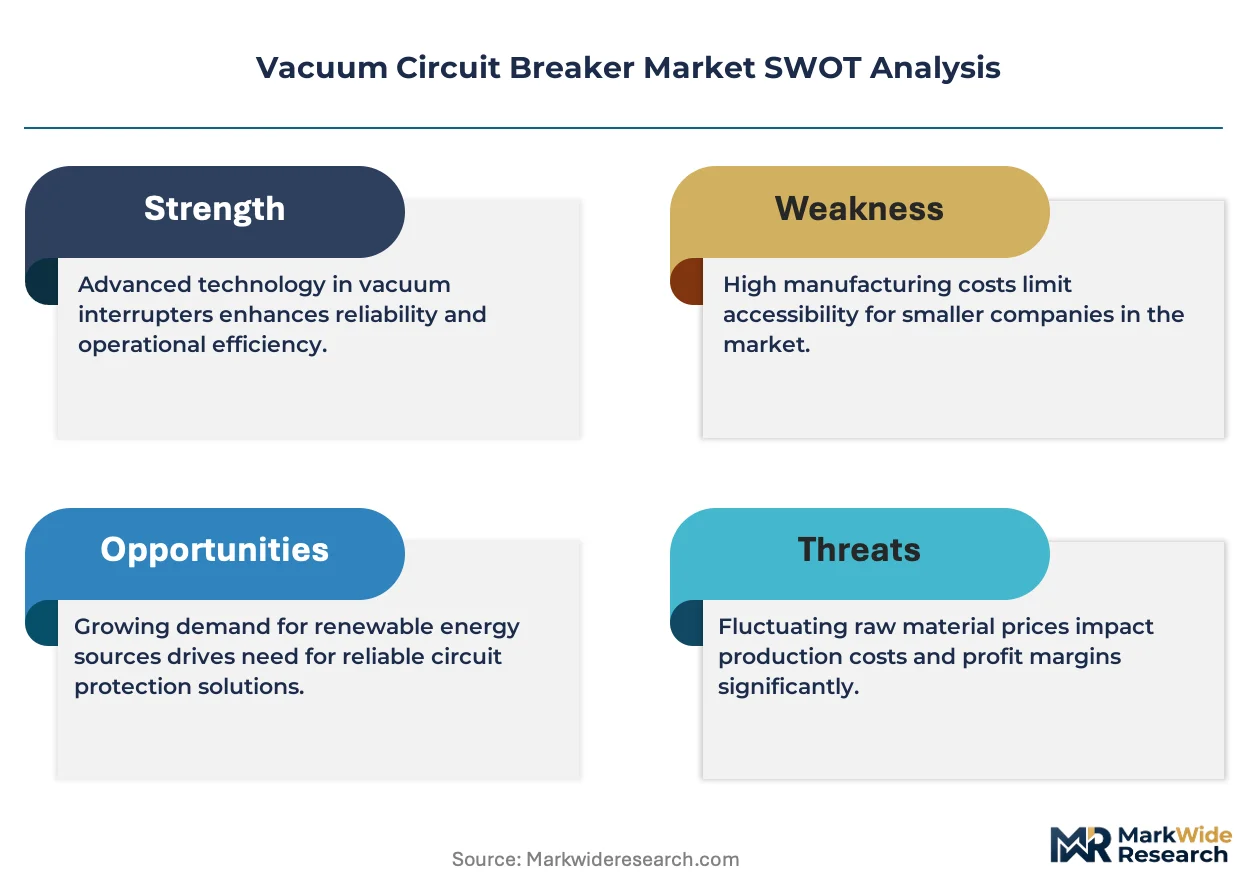
Copper-tungsten contact materials is rebalancing cost-performance trade-offs in medium-voltage interrupter manufacturing. Siemens leverages captive powder-metallurgy capabilities to secure contact supply chains. ABB sustains technology leadership through proprietary vacuum interrupter designs rated above 50 kA breaking capacity. Eaton competes aggressively in North American utility retrofit programs with modular switchgear platforms.
A vacuum circuit breaker employs a sealed vacuum arc chamber where metal vapor plasma extinguishes fault currents within a single half-cycle, achieving dielectric recovery rates exceeding 20 kV/μs. The device protects transformers, generators, and distribution feeders from overload and short-circuit damage. Switchgear configurations dominate installed value due to integrated protection, metering, and remote monitoring requirements in utility substations. Digital technology adoption is accelerating fastest among industrial end users seeking predictive maintenance and arc-flash mitigation. Panel mount variants occupy stable demand niches in OEM electrical equipment and marine applications.
CEA mandates in India enforce type-testing for vacuum circuit breakers at 12 kV and above under centralized grid interconnection rules. IEC 62271-100 and IEEE C37.04 define critical performance benchmarks for short-circuit breaking, mechanical endurance, and temperature rise limits across export markets. EMA-equivalent notified bodies in Europe conduct conformity assessments under the Low Voltage Directive for commercial and residential installations. Stakeholders must monitor evolving F-Gas Regulation implications on competing SF6 breaker phase-outs and assess backward integration into ceramic insulator and bellows manufacturing to protect margin pools.
Market Dynamics
Copper-tungsten powder metallurgy capabilities are concentrating supply leverage among vertically integrated manufacturers, while IEC 62271-100 tightening and India's CEA mandates are accelerating specification divergence between regional procurement pools.
Growth Catalysts
- SF6 phase-out mandates:Europe's F-Gas Regulation and parallel EPA restrictions in the US are forcing utilities to specify vacuum interrupters for new substation builds, eliminating incumbent gas-insulated alternatives from tender eligibility.
- India rural electrification:CEA centralized grid interconnection rules are mandating type-tested vacuum circuit breakers at 12 kV and above across state distribution companies, creating standardized volume demand.
- Copper-tungsten contact advances:Powder-metallurgy improvements in contact erosion resistance are extending mechanical endurance ratings, reducing lifecycle replacement frequency for utility fleet operators.
Market Restraints
- Ceramic insulator supply concentration:High-purity alumina substrate production clusters in China's Shandong province, exposing non-Chinese breaker manufacturers to single-source fragility and logistics cost volatility.
- Breaking capacity ceiling:Vacuum interrupter physics imposes practical limits near 63 kA for single-chamber designs, constraining adoption in ultra-high-voltage transmission applications where SF6 remains technically dominant.
- REACH compliance costs:EU ECHA substance restrictions on tungsten processing byproducts are elevating contact material certification expenses for exporters serving European utilities.
Strategic Opportunities
- Predictive maintenance convergence:Vacuum interrupter embedded sensors and cloud analytics are converging with utility digital transformation programs, enabling condition-based replacement contracts that capture recurring revenue streams.
- Marine electrical retrofits:IEC 62271-100-certified panel mount variants are penetrating offshore platform and vessel switchgear refresh cycles as classification societies tighten arc-flash protection mandates.
- US utility modernization:FERC Order 2222 implementation and state-level renewable portfolio standards are accelerating interconnection switchgear upgrades, opening retrofit channels for modular vacuum breaker platforms.
Industry Challenges
- Vacuum chamber sealing expertise:Thin-walled stainless steel bellows welding and helium leak detection require specialized technician training that outpaces vocational pipeline output in multiple manufacturing regions.
- Legacy electromechanical relay integration:Utilities with aging protection schemes face protocol translation complexity when interfacing digital vacuum breaker controls with existing substation automation architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vacuum Circuit Breaker Market |
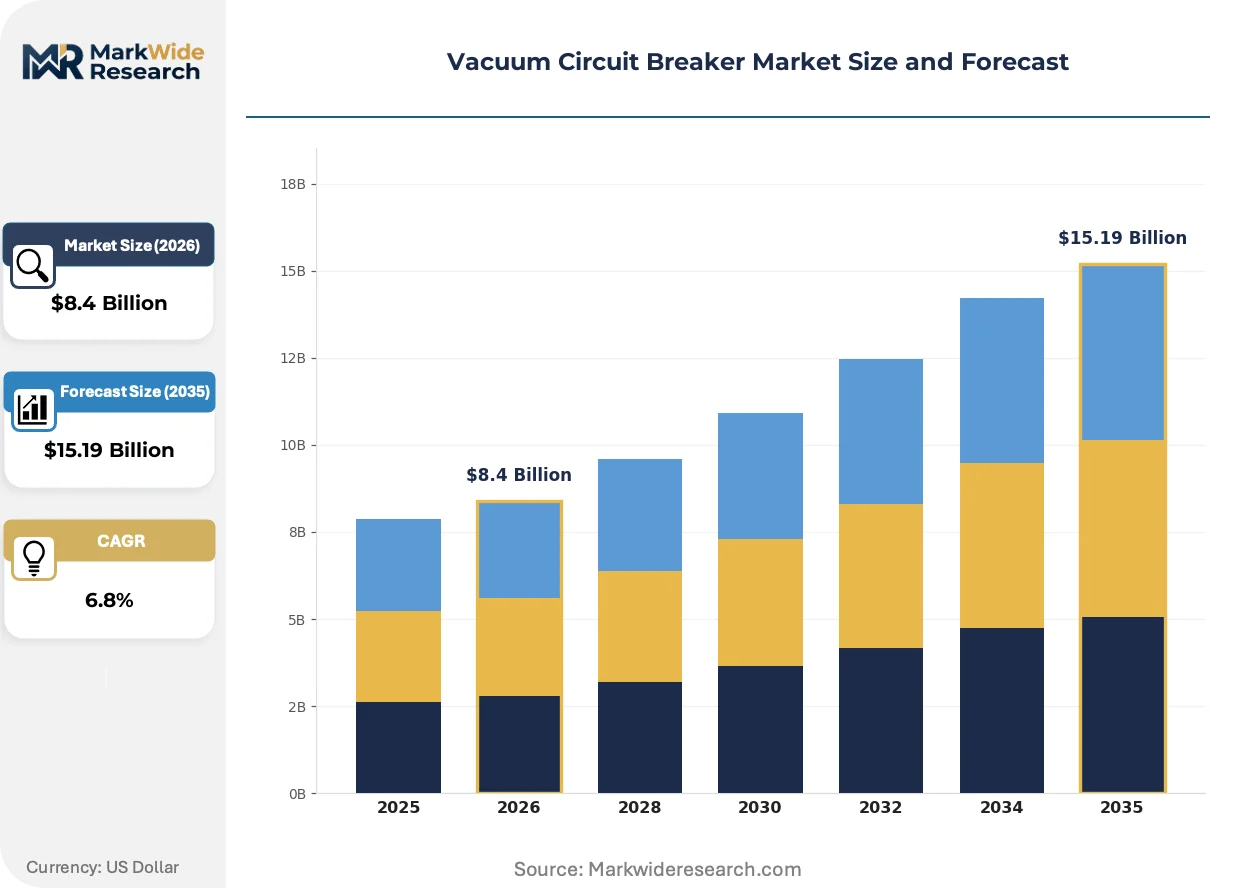
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Panel Mount, Enclosed, Switchgear, Miniature End User: Utilities, Industrial, Commercial, Residential Installation: Indoor, Outdoor, Retrofit, New Technology: Electromechanical, Digital, Hybrid, Others |
| Companies Covered | ABB, Siemens, Schneider Electric, Eaton, Mitsubishi Electric Corporation, Toshiba, Fuji Electric, General Electric, CG Power and Industrial Solutions Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vacuum Circuit Breaker Market Emerging Trajectories
Digital instrumentation and predictive algorithms are embedding directly into vacuum interrupter assemblies, transforming hardware procurement into data-service relationships while regulatory pressure on competing SF6 technology accelerates specification migration.
Copper-chromium contact material formulations are converging with additive manufacturing processes to produce functionally graded electrode structures that optimize arc diffusion and dielectric recovery. Industrial end users in data center and semiconductor fabrication verticals are specifying these next-generation interrupters for mission-critical power distribution. The technology is converging with remote thermal monitoring systems to enable predictive replacement scheduling that minimizes unplanned outage exposure.
India's CEA technical standards division is enforcing centralized type-test protocols for all vacuum circuit breakers at 12 kV and above before grid interconnection approval, creating a de facto certification bottleneck that favors manufacturers with in-country testing partnerships. State electricity boards are consolidating procurement specifications around CEA-compliant product lists, compressing vendor qualification timelines. Distribution utilities in Maharashtra and Gujarat are responding by pre-qualifying breaker platforms through extended trial installations before volume tender participation.
Asset lifecycle contracting is displacing traditional capital purchase models among European utilities facing CSRD disclosure requirements and stranded asset risk scrutiny. Siemens and ABB are restructuring offerings around availability-guaranteed service agreements where breaker hardware is bundled with predictive maintenance analytics and rapid replacement logistics. This shift is most visible in Germany's distribution network operator sector, where TenneT and E.ON have piloted outcome-based contracts for medium-voltage switchgear fleets.
Vacuum Circuit Breaker Market Segmentation
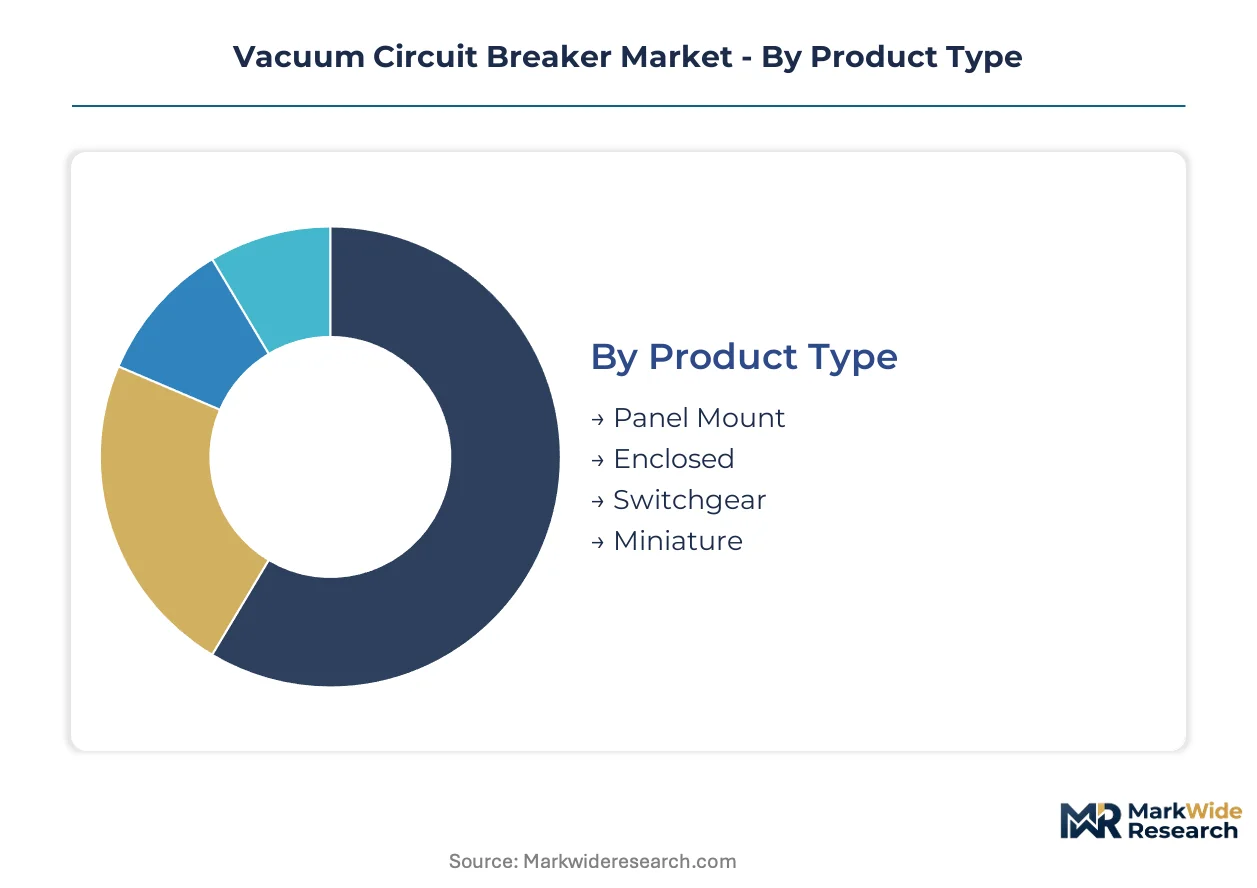
Vacuum circuit breaker procurement patterns diverge sharply across application environments, with utility substations demanding integrated switchgear platforms while industrial buyers prioritize embedded diagnostics. Specification complexity intensifies as IEC 62271-100 compliance requirements fragment by end-use sector and installation context.
Product Type:
Cost tier differentiation separates commodity panel mount units from engineered switchgear systems with integrated protection and metering.
- Switchgear:Factory-integrated assemblies combine vacuum interrupters with busbars, instrument transformers, and remote monitoring interfaces. Demand concentrates in China's State Grid modernization programs and India's CEA-mandated rural electrification drives where centralized procurement specifications favor pre-certified platforms.
- Panel Mount:Compact units designed for OEM integration into electrical enclosures and marine switchboards. Shipbuilders in South Korea and offshore platform operators in the North Sea are specifying IEC 62271-100-certified variants as classification societies tighten arc-flash protection mandates.
- Enclosed:Self-contained breaker modules with factory-installed housing and cable terminations.
- Miniature:Sub-100A rated units for residential distribution boards and light commercial applications.
Volume sits with Switchgear; growth tilts toward Panel Mount.
End User:
Application maturity separates established utility procurement from emerging industrial digitalization requirements.
- Utilities:Grid operators specify vacuum breakers for transmission substations, distribution feeders, and renewable energy interconnection points. Germany's TenneT and E.ON are piloting outcome-based service contracts where breaker hardware bundles with predictive maintenance analytics under CSRD disclosure pressures.
- Industrial:Data center operators and semiconductor fabricators specify copper-chromium contact interrupters with embedded thermal monitoring for mission-critical power distribution. Predictive replacement scheduling minimizes unplanned outage exposure in continuous-process manufacturing.
- Commercial:Building owners and facility managers procure modular platforms for campus distribution upgrades.
- Residential:Developers install miniature breakers in multi-unit housing and smart grid pilot neighborhoods.
Procurement scale favors Utilities; specification innovation concentrates in Industrial.
Installation:
Customer lifecycle stage creates divergent margin profiles between replacement cycles and greenfield construction.
- Retrofit:Existing substation upgrades drive demand for modular breaker platforms compatible with legacy electromechanical relay schemes. US utilities responding to FERC Order 2222 and state renewable portfolio standards are accelerating interconnection switchgear replacements.
- New:Greenfield substation construction specifies fully digital breaker controls with native IEC 61850 protocol support. India's state electricity boards in Maharashtra and Gujarat are pre-qualifying platforms through extended trial installations before volume tender participation.
- Indoor:Climate-controlled substation and industrial facility installations dominate medium-voltage applications.
- Outdoor:Weather-hardened enclosures for transmission switching stations and rural distribution points.
Retrofit commands current volume; New installation offers the steepest expansion trajectory as renewable interconnection accelerates.
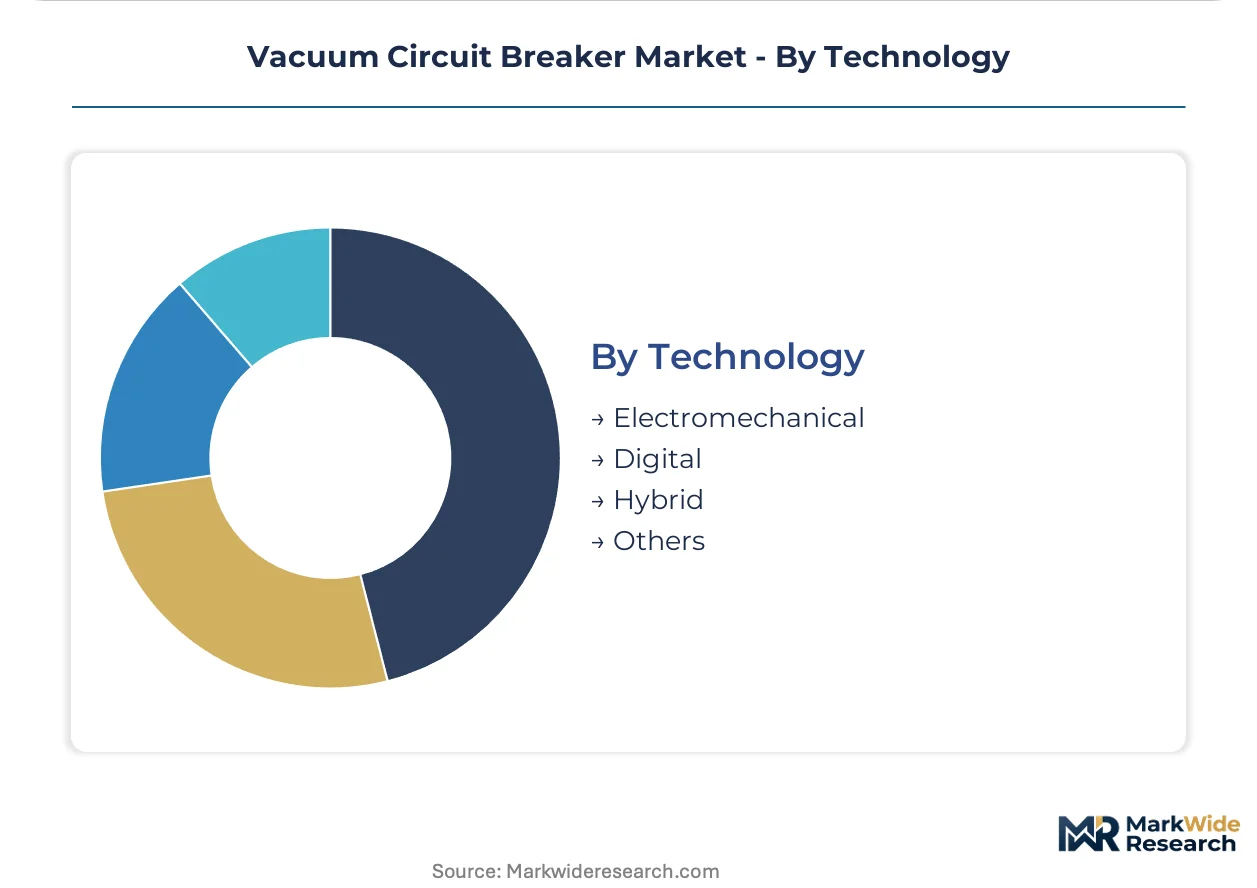
Technology:
Control architecture sophistication separates electromechanical legacy from digitally native platforms with embedded analytics.
- Digital:Microprocessor-based protection relays with cloud-connected condition monitoring and arc-flash mitigation algorithms. European distribution network operators facing stranded asset risk are restructuring procurement around availability-guaranteed service agreements with predictive maintenance bundles.
- Electromechanical:Conventional spring-operated mechanisms with discrete relay protection remain prevalent in developing market utilities with constrained technical training pipelines.
- Hybrid:Platforms combining electromechanical interruption with digital monitoring overlays for transitional upgrade paths.
- Others:Emerging solid-state interruption concepts and superconducting fault current limiter integrations in R&D phase.
Electromechanical retains installed base dominance; Digital is displacing legacy controls fastest among industrial end users.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China and India concentrate procurement volume through state-directed grid modernization programs, while Germany and the United States drive specification innovation around digital controls and service-based contracting models.
China
State Grid Corporation and China Southern Power Grid are expanding ultra-high-voltage transmission corridors to accommodate western renewable generation. MIIT efficiency mandates and dual carbon goals are accelerating SF6-to-vacuum substitution timelines in new substation builds. Shandong province hosts concentrated ceramic insulator manufacturing clusters serving domestic breaker fabricators.
India
Rural electrification drives under CEA centralized interconnection rules are standardizing 12 kV and above vacuum breaker specifications across state distribution companies. Maharashtra and Gujarat electricity boards are pre-qualifying platforms through extended field trials before volume tender participation. Bangalore and Pune industrial corridors are emerging as domestic switchgear assembly hubs.
Germany
TenneT and E.ON distribution network operators are piloting outcome-based service contracts bundling breaker hardware with predictive maintenance analytics. EU F-Gas Regulation phase-out mandates are eliminating SF6 alternatives from tender eligibility for new substation projects. Bavaria and North Rhine-Westphalia host concentrated medium-voltage equipment engineering expertise.
United States
Utilities responding to FERC Order 2222 and state renewable portfolio standards are accelerating interconnection switchgear retrofits. EPA restrictions on SF6 emissions are constraining gas-insulated breaker deployment in new utility infrastructure. Texas and California grid operators are specifying modular vacuum platforms for distributed solar and battery storage integration points.
Japan
Tokyo Electric Power and regional utilities are replacing aging oil circuit breakers with vacuum interrupters in earthquake-resilient substation designs. METI grid stability requirements are tightening short-circuit withstand specifications for renewable interconnection switchgear. Osaka-Kobe industrial zone maintains concentrated vacuum interrupter ceramic processing capabilities.
Vacuum Circuit Breaker Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated electrical conglomerates commanding utility procurement channels while regional fabricators serve retrofit and industrial niches. The structure tilts toward consolidation at the high-voltage extreme and fragmentation in panel-mount and enclosed variants. Three archetypes dominate: vertically integrated power equipment majors, contact material specialists with captive powder-metallurgy capabilities, and modular platform assemblers targeting retrofit velocity. Competitive moves center on backward integration into ceramic insulator supply and predictive maintenance service bundling.
Among European-based integrated majors, ABB and Siemens exemplify the premium-tier archetype through proprietary interrupter designs and availability-guaranteed contracting models. Eaton occupies a distinct position in North American utility retrofit channels with modular switchgear platforms. These three anchors illustrate how geographic footprint and service architecture differentiation separate winners across procurement pools.
| Leading Market Players |
|---|
| ABB |
| Siemens |
| Schneider Electric |
| Eaton |
| Mitsubishi Electric Corporation |
| Toshiba |
| Fuji Electric |
| General Electric |
| CG Power and Industrial Solutions Limited |
| Others |
Supply Flow & Price Mechanics
Copper-tungsten powder metallurgy costs cascade through three distinct pricing tiers, with captive in-house production at Siemens and ABB insulating premium switchgear from Shandong ceramic insulator volatility that squeezes mid-tier panel mount assemblers.
Pricing Analysis
Volume concentrates in commodity switchgear procurement by China's State Grid and India's state electricity boards, while margin pools accrue to predictive maintenance service bundles at TenneT and E.ON. Price differentiation hinges on IEC 62271-100 certification tier and copper-chromium contact material grade, with premium digital platforms commanding availability-guaranteed contracting premiums. Pricing pressure stems from REACH compliance costs elevating tungsten processing certification expenses for European export exposure. Industrial data center buyers exhibit lowest price sensitivity due to mission-critical uptime requirements, whereas rural electrification tenders in India demonstrate acute cost consciousness.
Supply Chain Analysis
Dual-sourcing mandates from European utilities and Japanese grid operators force qualification of secondary ceramic insulator suppliers beyond China's Shandong concentration. Production draws from China, Germany, and Japan for vacuum interrupter assemblies, with high-purity alumina substrates, thin-walled stainless steel bellows, and helium leak detection equipment anchoring critical dependencies. Single-source vulnerability in Shandong ceramic clusters exposes non-Chinese manufacturers to logistics cost volatility and geopolitical disruption. Distribution runs through direct utility procurement channels for switchgear, with OEM integrators and marine shipbuilders sourcing panel mount units through specialized electrical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The vacuum circuit breaker market functions as a cost-of-compliance arena where India's CEA type-test mandates and Europe's F-Gas Regulation erect certification barriers that entrench incumbents with in-country testing partnerships and SF6-to-vacuum transition expertise.
For Market Incumbents: Deploy predictive maintenance service bundling to capture recurring revenue from European utilities facing CSRD disclosure requirements. Backward integration into ceramic insulator supply protects margin pools against Shandong concentration risk. Counter emerging modular platform assemblers in North American retrofit channels by accelerating IEC 61850-native digital control rollouts. For New Entrants and Emerging Players: Enter via marine electrical retrofit niches in South Korean shipbuilding and North Sea offshore platforms where classification society arc-flash mandates create specification openings. Target CEA-compliant 12 kV panel mount variants for India's state electricity board pre-qualification trials. Pursue copper-chromium additive manufacturing partnerships to differentiate on contact erosion performance in semiconductor fabrication verticals. For Investors and Strategic Acquirers: Distressed-cycle entries favor contact material specialists with captive powder-metallurgy capabilities in Germany and Japan during ceramic supply shocks. Long-term viability centers on service-based contracting transition among distribution network operators. Watch F-Gas Regulation enforcement intensity as inflection signal for SF6 phase-out acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Insulator Supply | Shandong concentration risk drives captive alumina substrate production at ABB and Siemens. |
| Predictive Maintenance Service Bundling | TenneT and E.ON pilot availability-guaranteed contracts embedding vacuum interrupter sensor analytics. |
| CEA In-Country Testing Partnership Formation | India's centralized type-test protocols favor manufacturers with Bangalore and Pune laboratory access. |
| Copper-Chromium Additive Manufacturing Scale-Up | Functionally graded electrodes optimize arc diffusion for data center mission-critical specifications. |
| IEC 61850 Native Protocol Development | Greenfield substation digital controls displace legacy electromechanical relay integration complexity. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, with primary interviews conducted among utility planning officers, switchgear procurement leads at state electricity boards, EPC contractors, aftermarket service heads, and vacuum interrupter ceramic processing engineers. IEC 62271-100 certification databases, CEA type-test registries, EU ECHA substance restriction filings, and import-export statistics triangulated against bottom-up segment sizing and top-down macroeconomic validation.
Data-stream reconciliation across shipment volumes, installed base estimates, and replacement cycle assumptions shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end user vertical, installation context, and control technology architecture. CAGRs derived from utility capital expenditure trajectories, renewable interconnection queue data, and industrial automation spending patterns.
Forecast precision tightens around the base case; tail outcomes carry wider variance under ceramic supply disruption or accelerated F-Gas Regulation enforcement timelines. Forecasts reflect documented assumptions regarding SF6 phase-out velocity, CEA mandate expansion scope, and copper-tungsten contact material cost trajectories. Deviation in India's rural electrification disbursement schedules would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Europe High Voltage Switchgear Market
Electrical Equipment
United Kingdom Thermal Protector Market
Electrical Equipment
Magnetic Shielding Device Market
Electrical Equipment
High Voltage Electric Capacitor Market
Electrical Equipment
Europe Electric Drives Market
Electrical Equipment
MCB and MCCB Market
Electrical Equipment
Pad-Mounted Transformer Market
Electrical Equipment
Electric Enclosure Market
Electrical Equipment
Global EMC Filtration Market
Electrical Equipment
Electrical Steel Coatings Market
Electrical Equipment
Electrical Resistor Market
Electrical Equipment
South America High Voltage Switchgear Market
Electrical Equipment
Circuit Breaker and Fuses Market
Electrical Equipment
Electrical Bushings Market
Electrical Equipment
Vacuum Contactor Market
Electrical Equipment
Medium Voltage Fuse Market