
 Electrical Steel Coatings Market | 2026-2036
Electrical Steel Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Electrical Steel Coatings Market Analysis
Aftermarket refurbishment revenue is reshaping margin distribution across the electrical steel coatings value chain, pulling profitability away from virgin material sales toward recoating and performance restoration services. ArcelorMittal SA leverages its integrated steel-coating operations to capture value from both substrate and surface treatment stages. POSCO anchors its position through captive supply relationships with Korean transformer OEMs. Rembrandtin Lack GmbH Nfg. KG specializes in niche insulating varnish formulations for high-frequency applications.
Electrical steel coatings are thin-film surface treatments applied to grain-oriented and non-grain-oriented silicon steel to reduce eddy current losses, typically formulated with inorganic or organic resins achieving thicknesses between 1 and 5 micrometers. Their primary purpose is to maintain electrical insulation between laminated steel sheets in electromagnetic cores while withstanding thermal cycling up to 200°C in service. Epoxy coatings dominate transformer applications due to their thermal endurance and adhesion to grain-oriented substrates, while polyurethane formulations are gaining traction in automotive traction motors where flexibility under mechanical stress matters. CVD technology leads in premium generator segments for its uniformity, though spray coating occupies the volume tier across industrial motor rebuilds.
The EU Green Deal and REACH frameworks in Europe, alongside EPA industrial emissions standards in the United States, are tightening permissible volatile organic compound content in coating formulations and pushing solvent-based systems toward waterborne or powder alternatives. China's GB standards and MIIT efficiency mandates are accelerating domestic coating qualification requirements for grid infrastructure steel. Stakeholders must monitor how regulatory divergence between these jurisdictions affects formulation portability and plant certification costs.
Market Dynamics
Refurbishment economics are restructuring value capture across the electrical steel coatings sector, redirecting margins from virgin substrate sales toward recoating services and performance restoration as transformer fleets age and efficiency mandates tighten.
Growth Catalysts
- EU Green Deal material efficiency mandates:Binding requirements for transformer loss reduction are accelerating coating specification upgrades across European grid infrastructure procurement.
- Electric vehicle traction motor expansion:OEMs pursuing higher efficiency ratings are specifying advanced insulating coatings for laminated steel cores in high-frequency applications.
- Ruhr industrial corridor clustering:Concentrated transformer manufacturing and refurbishment activity in Germany's industrial heartland is generating localized demand density for coating services.
Market Restraints
- Silicon steel substrate concentration:Dependence on a limited number of grain-oriented steel producers creates supply vulnerability for coating applicators without captive metallurgical operations.
- REACH solvent restrictions:ECHA's tightening VOC limits are forcing costly formulation reformulation away from established solvent-based coating systems.
- Ceramic core substitution in high-temperature segments:Emerging soft magnetic composite technologies threaten coating demand in premium generator applications above 200°C service temperatures.
Strategic Opportunities
- India grid modernization under CEA mandates:Central Electricity Authority efficiency regulations are opening qualification pathways for coating suppliers to domestic transformer OEMs.
- Waterborne epoxy convergence with CVD uniformity:Hybrid application technologies combining spray deposition with vapor-phase finishing are enabling mid-tier motor rebuilders to access premium performance tiers.
- Aftermarket channel development:Direct service relationships with industrial motor maintenance shops are bypassing traditional distributor markups in North American refurbishment markets.
Industry Challenges
- Coating-thickness uniformity certification:IEC 60404-8-7 eddy current testing protocols require capital-intensive metrology equipment that smaller applicators struggle to justify.
- High-frequency varnish formulation expertise:Specialized knowledge in polyurethane chemistry for automotive traction motors concentrates among a narrow technical workforce, constraining capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrical Steel Coatings Market |
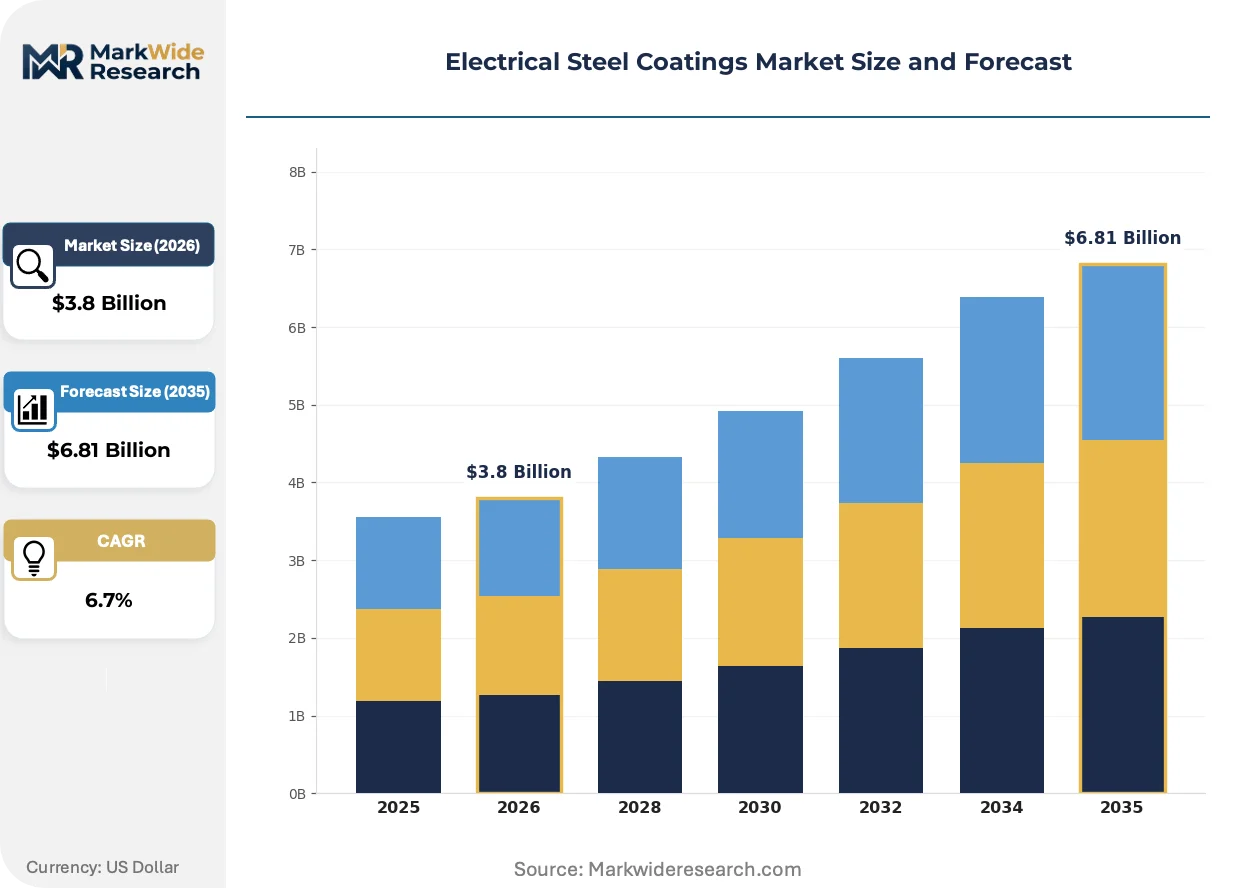
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coating Type: Epoxy, Polyester, Parylene, Polyurethane Application: Transformers, Motors, Generators, Actuators End User: Automotive, Aerospace, Renewable Energy, Industrial Machinery Technology: CVD, PVD, Electroplating, Spray Coating |
| Companies Covered | Axalta Coating Systems Ltd., ArcelorMittal SA, ThyssenKrupp AG, AK Steel Holding Corporation, Nippon Steel & Sumitomo Metal Corporation, POSCO, Baosteel, JFE Steel Corporation, Rembrandtin Lack GmbH Nfg. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrical Steel Coatings Market Emerging Trajectories
Coating application technology is bifurcating between premium uniformity requirements and volume accessibility, while regulatory chemistry constraints and refurbishment service models simultaneously reshape competitive positioning across substrate and surface treatment stages.
Physical vapor deposition is collapsing the performance gap between volume-tier spray coating and premium CVD systems for grain-oriented electrical steel. Japanese generator manufacturers are qualifying PVD-insulated laminations for large hydroelectric units previously reserved for chemical vapor deposition. This convergence is compressing equipment investment thresholds and enabling mid-scale applicators to bid on utility-grade transformer contracts.
REACH Annex XVII restrictions on chromium VI compounds are forcing reformulation of traditional phosphate-based pretreatment systems across European coating operations. The industrial consequence is accelerated qualification of silane-based adhesion promoters and zirconium conversion coatings. Non-grain-oriented steel for automotive traction motors faces the tightest compliance timelines, with Korean OEMs already specifying chrome-free systems for export-bound vehicles.
Service unbundling is fragmenting traditional coating supply relationships in the transformer aftermarket. Industrial rebuilders are separating substrate procurement from surface treatment, awarding recoating contracts to specialized applicators rather than integrated steel mills. This pattern is most visible in Germany's refurbishment sector, where Ruhr-based maintenance shops now source laminations from multiple metallurgical suppliers while captive coating operations handle performance restoration.
Electrical Steel Coatings Market Segmentation
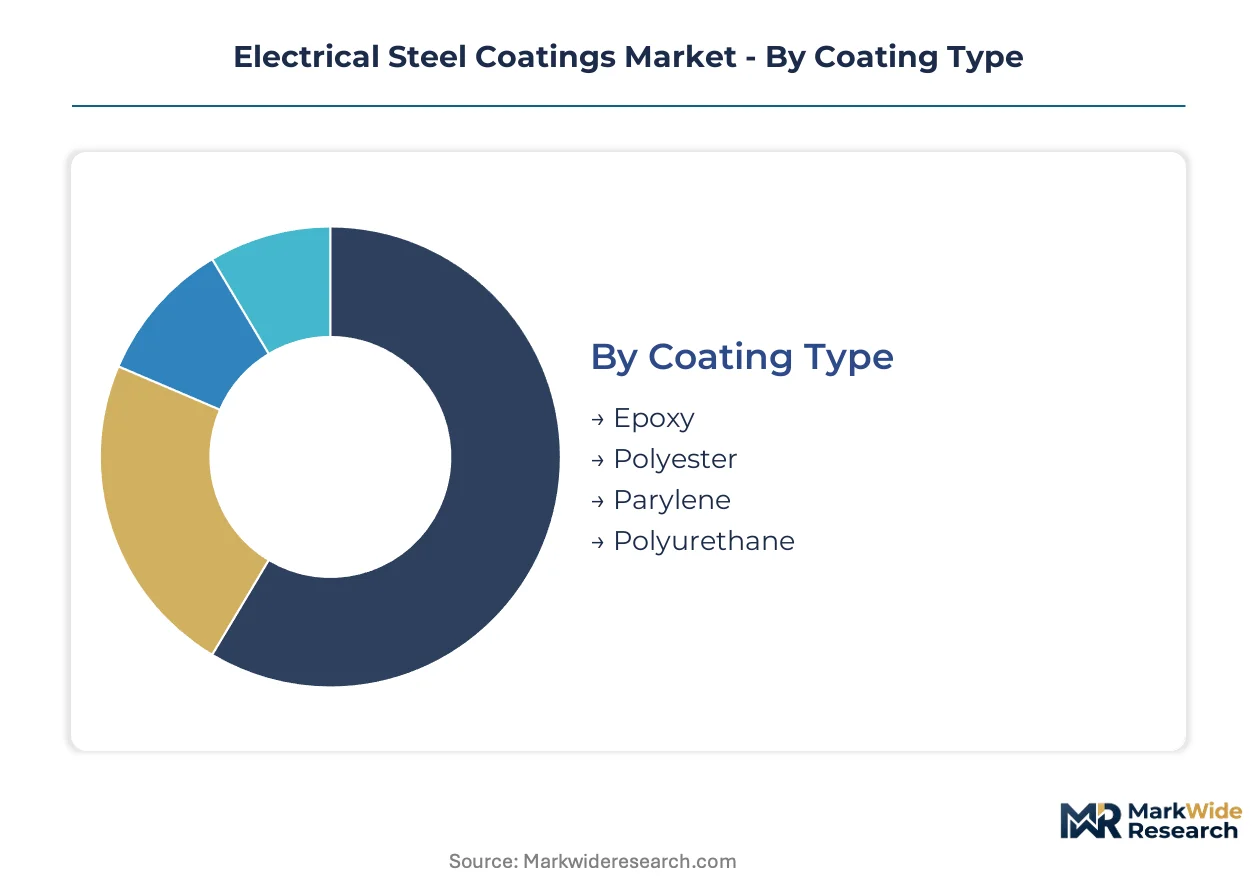
Segmentation in electrical steel coatings reveals how formulation chemistry, deposition physics, and end-use thermal requirements create distinct competitive arenas. Each dimension carries different margin profiles, qualification barriers, and technology substitution risks that reshape supplier positioning.
Coating Type:
Mature epoxy formulations dominate transformer infrastructure, while polyurethane and parylene systems are emerging in high-frequency automotive and aerospace niches demanding mechanical flexibility or hermetic sealing.
- Epoxy:Thermosetting resins formulated with bisphenol-A or novolac backbones achieve dielectric strength above 15 kV/mm and thermal endurance to 180°C. Demand concentrates in Germany's Ruhr corridor where transformer OEMs specify epoxy for grid infrastructure refurbishment under EU Green Deal loss-reduction mandates.
- Polyurethane:Elastomeric coatings based on polyol-isocyanate chemistry tolerate mechanical stress and thermal cycling in high-RPM environments. Korean automotive OEMs are specifying polyurethane for traction motor laminations in export-bound electric vehicles facing REACH chrome-free compliance deadlines.
- Polyester:Saturated or unsaturated resin systems offer cost-positioned insulation for industrial motors with moderate thermal loads.
- Parylene:Vapor-deposited poly-para-xylylene films provide conformal, pinhole-free coverage for aerospace actuator components requiring hermetic environmental protection.
Epoxy handles the majority of throughput; polyurethane is expanding most quickly on share as automotive electrification accelerates coating specification upgrades.
Application:
Application segmentation tracks directly to thermal regime and magnetic flux density requirements, with transformer cores representing established volume and traction motors representing technology-intensive growth.
- Transformers:Grain-oriented steel laminations in power and distribution transformers require interlaminar insulation to limit eddy current losses under 50/60 Hz excitation. India's Central Electricity Authority mandates are opening qualification pathways for coating suppliers to domestic OEMs modernizing aging grid infrastructure.
- Motors:Non-grain-oriented steel in industrial and automotive motors faces higher mechanical stress and, in EV applications, elevated switching frequencies. Japanese manufacturers are qualifying PVD-insulated laminations for large hydroelectric generator units previously reserved for chemical vapor deposition.
- Generators:Utility-scale rotating equipment demands coating uniformity across large lamination surface areas.
- Actuators:Precision electromagnetic components in aerospace and robotics require thin-film insulation without dimensional tolerance compromise.
Transformers absorb the largest coating volumes; motors are gaining share fastest as EV traction applications multiply addressable lamination surface area per vehicle.
End User:
End-user segmentation separates regulated infrastructure procurement from performance-driven mobility and energy transition applications with diverging certification timelines.
- Automotive:OEMs specify advanced insulating coatings for laminated steel cores in battery electric vehicle traction motors, with efficiency ratings directly impacting range certification. Korean and German manufacturers are driving qualification of chrome-free coating systems for export compliance.
- Renewable Energy:Wind turbine generators and solar inverter transformers require coatings tolerant of environmental thermal cycling and humidity exposure.
- Industrial Machinery:Motor rebuilders in North American aftermarket channels are unbundling substrate procurement from surface treatment, awarding recoating contracts to specialized applicators.
- Aerospace:Actuator and generator applications demand hermetic sealing and weight-minimized insulation films.
Automotive commands the steepest technology premium; renewable energy is climbing fastest as wind and solar deployment scales generator and transformer installation.
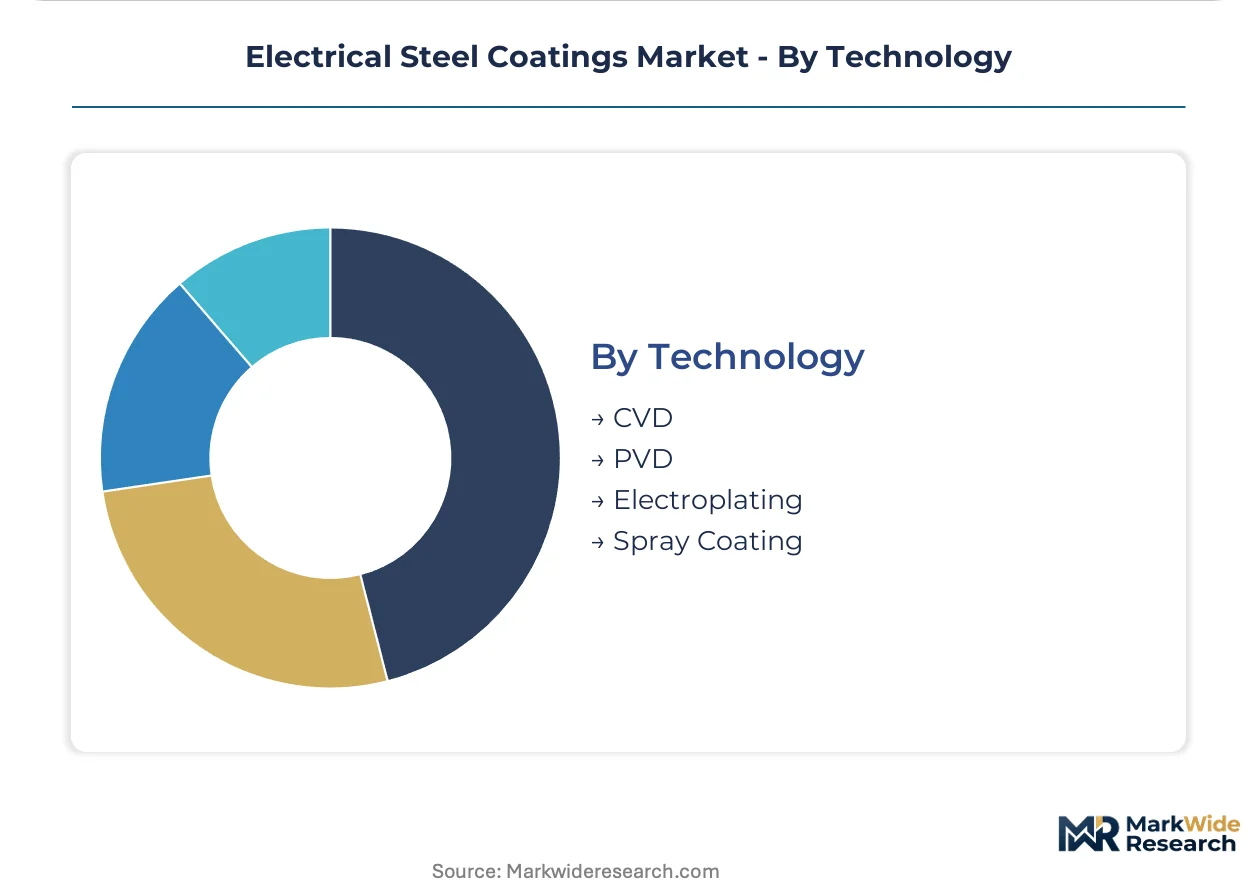
Technology:
Technology segmentation reflects a cost-uniformity tradeoff, with vapor-phase methods capturing premium generator segments and spray coating serving volume industrial motor rebuilds.
- CVD:Chemical vapor deposition achieves sub-micron thickness control and conformal coverage through gas-phase precursor reaction. Japanese generator manufacturers have qualified CVD-insulated laminations for hydroelectric units where eddy current loss minimization justifies capital-intensive coating equipment.
- Spray Coating:Airless and electrostatic spray systems deposit solventborne or waterborne resins with throughput advantages for large lamination batches. German refurbishment shops in the Ruhr industrial corridor rely on spray coating for transformer fleet performance restoration.
- PVD:Physical vapor deposition is collapsing the performance gap between spray coating and premium CVD systems, compressing equipment investment thresholds for mid-scale applicators.
- Electroplating:Aqueous electrolytic deposition of inorganic insulating layers serves niche applications requiring specific surface conductivity control.
Spray coating handles the majority of throughput; PVD is expanding most quickly as equipment costs decline and performance convergence accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. European buyers absorb premium coating costs to meet efficiency mandates, while Indian procurement prioritizes qualification speed over performance tiers. Chinese demand bifurcates between state-grid volume contracts and export-grade precision specifications.
Germany
Ruhr-based transformer OEMs drive coating specification upgrades under EU Green Deal loss-reduction requirements. ECHA REACH Annex XVII restrictions on chromium VI compounds are forcing chrome-free reformulation across phosphate pretreatment systems. Dortmund and Essen maintenance shops now unbundle substrate procurement from recoating services, fragmenting traditional supply relationships.
China
MIIT efficiency mandates and GB standards accelerate domestic coating qualification for grid infrastructure steel. State Grid Corporation procurement concentrates volume demand for grain-oriented substrates. Yangtze River Delta metallurgical clusters are integrating captive coating lines to capture margin from surface treatment stages previously outsourced.
United States
EPA industrial emissions standards tighten permissible VOC content in solvent-based coating formulations. North American motor rebuilders in Ohio and Pennsylvania industrial corridors are developing direct service relationships with specialized applicators. Aftermarket channel unbundling bypasses traditional distributor markups in refurbishment markets.
India
Central Electricity Authority regulations open qualification pathways for coating suppliers to domestic transformer OEMs modernizing aging grid infrastructure. Price-sensitive procurement favors spray coating over CVD systems for distribution transformer applications. Gujarat and Maharashtra industrial zones concentrate new-build manufacturing capacity.
Japan
METI efficiency standards and JIS certification requirements maintain premium performance barriers for coating applicators. Generator manufacturers are qualifying PVD-insulated laminations for hydroelectric units previously reserved for chemical vapor deposition. Nagoya-based industrial motor producers specify high-uniformity coatings for precision electromagnetic components.
Electrical Steel Coatings Market Vendor Landscape
Capability concentration sits with specialized coating formulators; scale advantage sits with integrated steel producers. The market structures around three tiers: metallurgical giants with captive coating operations, independent surface treatment specialists, and regional refurbishment service providers. Strategic moves center on backward integration into substrate supply and forward integration into aftermarket service networks.
Within the integrated steel tier, ArcelorMittal SA exemplifies vertical control across substrate and surface treatment stages. POSCO anchors the Asia-Pacific position through proximity to Korean transformer and automotive OEMs. Rembrandtin Lack GmbH Nfg. KG occupies the specialist tier with focused expertise in insulating varnish formulations.
| Leading Market Players |
|---|
| Axalta Coating Systems Ltd. |
| ArcelorMittal SA |
| ThyssenKrupp AG |
| AK Steel Holding Corporation |
| Nippon Steel & Sumitomo Metal Corporation |
| POSCO |
| Baosteel |
| JFE Steel Corporation |
| Rembrandtin Lack GmbH Nfg. KG |
| Others |
Supply Flow & Price Mechanics
Overcapacity in China's Yangtze River Delta metallurgical clusters is compressing coating margins across export markets, pushing integrated producers toward captive surface treatment lines while independent applicators absorb pricing pressure from excess substrate supply.
Pricing Analysis
Aftermarket refurbishment revenue drives lifetime value capture across the electrical steel coatings value chain. Three-tier pricing structure across premium, standard, and economy levels separates CVD-insulated laminations for hydroelectric generators from spray-coated transformer rebuilds and basic industrial motor recoating. Cost compression in the standard tier is intensifying because REACH Annex XVII compliance is forcing solvent-to-waterborne formulation switches. Industrial motor rebuilders in North America exhibit the highest price sensitivity, while Japanese generator OEMs absorb premium coating costs for JIS-certified uniformity.
Supply Chain Analysis
Silicon steel feedstock concentrates in China, Japan, and South Korea, where Nippon Steel, POSCO, and Baosteel control grain-oriented substrate output. Coating formulation draws from epoxy resin, isocyanate polyols, and phosphate pretreatment chemicals. Single-source vulnerability looms in grain-oriented steel supply for European applicators lacking captive metallurgical operations. Distribution runs through integrated steel mills for virgin laminations and specialized refurbishment shops for aftermarket recoating services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a cyclical recovery phase as transformer fleet age and EU Green Deal efficiency mandates trigger replacement waves across European grid infrastructure.
For Market Incumbents: Harden coating-thickness uniformity certification capabilities to defend against PVD technology convergence eroding CVD premium positioning. Deepen backward integration into silane-based adhesion promoter chemistry ahead of chrome-free REACH deadlines. Lock in direct service relationships with Ruhr-based maintenance shops before substrate unbundling fragments traditional supply relationships further.
For New Entrants and Emerging Players: Pursue qualification pathways with India's Central Electricity Authority for distribution transformer coating contracts, where price-sensitive procurement favors spray application over capital-intensive CVD systems. Target Gujarat and Maharashtra industrial zones for new-build manufacturing partnerships. Lead with waterborne epoxy formulations that satisfy both cost constraints and emerging efficiency mandates.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compression play because tightening VOC limits and material efficiency mandates continuously reshape formulation value toward compliance-capable specialists. Acquisition candidates include regional refurbishment service providers with IEC 60404-8-7 certification infrastructure. Watch for PVD equipment cost curves as the signal indicating when mid-tier applicators can bid utility-grade contracts.
| Strategic Initiative | Industry Significance |
|---|---|
| Chrome-Free Formulation Transition | REACH Annex XVII restrictions force silane-based adhesion promoter qualification across European coating operations. |
| PVD Equipment Investment | Japanese generator manufacturers qualify PVD-insulated laminations for hydroelectric units previously reserved for CVD. |
| Aftermarket Channel Unbundling | German refurbishment shops now separate substrate procurement from recoating contracts, fragmenting integrated mill relationships. |
| CEA Qualification Pathway | Central Electricity Authority efficiency regulations open coating supplier access to India's domestic transformer OEMs. |
| Captive Coating Line Integration | Yangtze River Delta metallurgical clusters integrate surface treatment to capture margin from previously outsourced stages. |
Methodological Framework
A standing panel of transformer OEM procurement directors, coating applicator plant managers, automotive traction motor platform engineers, and aftermarket refurbishment shop owners provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with these stakeholders against secondary validation from IEC standards documentation, ECHA REACH regulatory filings, customs trade data for silicon steel flows, and SEC disclosures from integrated steel producers. Bottom-up lamination demand modeling triangulated against top-down grid infrastructure investment forecasts.
Scenario-bracketing framed volume and value outputs across the projection horizon, with segmentation dimensions spanning coating chemistry type, deposition technology, end-use thermal regime, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to qualified lamination surface area estimates. Industry-specific forecast inputs included EV traction motor penetration rates and transformer fleet age distributions by grid operator.
Macroeconomic conditions sit as an overlay; deviation in electricity demand growth, steel price volatility, or automotive production schedules would shift the trajectory. Forecasts reflect assumptions about regulatory timeline adherence and technology substitution rates. Cross-checking against IEA grid investment benchmarks and automotive OEM electrification targets is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Global Dehumidifier Market
Electrical Equipment
France DC Motors Market
Electrical Equipment
Current Clamps Market
Electrical Equipment
South America High Voltage Switchgear Market
Electrical Equipment
Copper and Copper Alloy Busbars Market
Electrical Equipment
Electric Motors for Conveyor System Market
Electrical Equipment
Capacitor Bank Market
Electrical Equipment
Europe Electrical Bushing Market
Electrical Equipment
Global EMC Filtration Market
Electrical Equipment
Electrical Fuses Market
Electrical Equipment
Busbar Systems Market
Electrical Equipment
Global Medium Voltage Electric Drives Market
Electrical Equipment
MCB and MCCB Market
Electrical Equipment
Circuit Breaker and Fuses Market
Electrical Equipment
Earth Leakage Circuit Breakers Market
Electrical Equipment
Global Sealed DC Contactor Market